
 Ice Cream Cake Market | 2026-2036
Ice Cream Cake Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Cream Cake Market Insights
Premium-tier formulations with higher butterfat content and artisanal inclusions is bifurcating the competitive landscape into craft-oriented and mass-production camps. Rich Products sustains its position through frozen-dough vertical integration and broad foodservice reach. Carvel dominates the branded ice-cream-cake segment with decades of retail presence and seasonal product cycles. De Jong's IJS B.V. anchors European supply through specialized dairy sourcing and regional flavor expertise.
An ice-cream cake combines frozen dairy or non-dairy base layers with cake or cookie substrates, typically stabilized through blast-freezing at minus thirty degrees Celsius to maintain structural integrity during cutting and transport. The product serves celebratory retail occasions and impulse dessert purchase occasions across grocery and foodservice channels. Premium and gluten-free product types command disproportionate margin pools as consumers trade up for dietary accommodation and indulgence positioning. Chocolate and cookies-and-cream flavor profiles lead volume while vegan formulations represent the fastest-expanding segment. Supermarkets and specialty stores remain the dominant distribution channels, though online fulfillment is gaining traction for customized occasion cakes.
FDA oversight of frozen dessert standards, EFSA guidance on novel food ingredients, and state-level cottage-food regulations collectively shape permissible formulations and interstate commerce pathways for ice-cream-cake producers. Compliance with allergen-labeling mandates and clean-label certification requirements directly influences product-development timelines and market-access eligibility for new entrants. Stakeholders must monitor evolving dairy-alternative ingredient classifications and cold-chain integrity standards as determinants of competitive positioning.
Market Dynamics
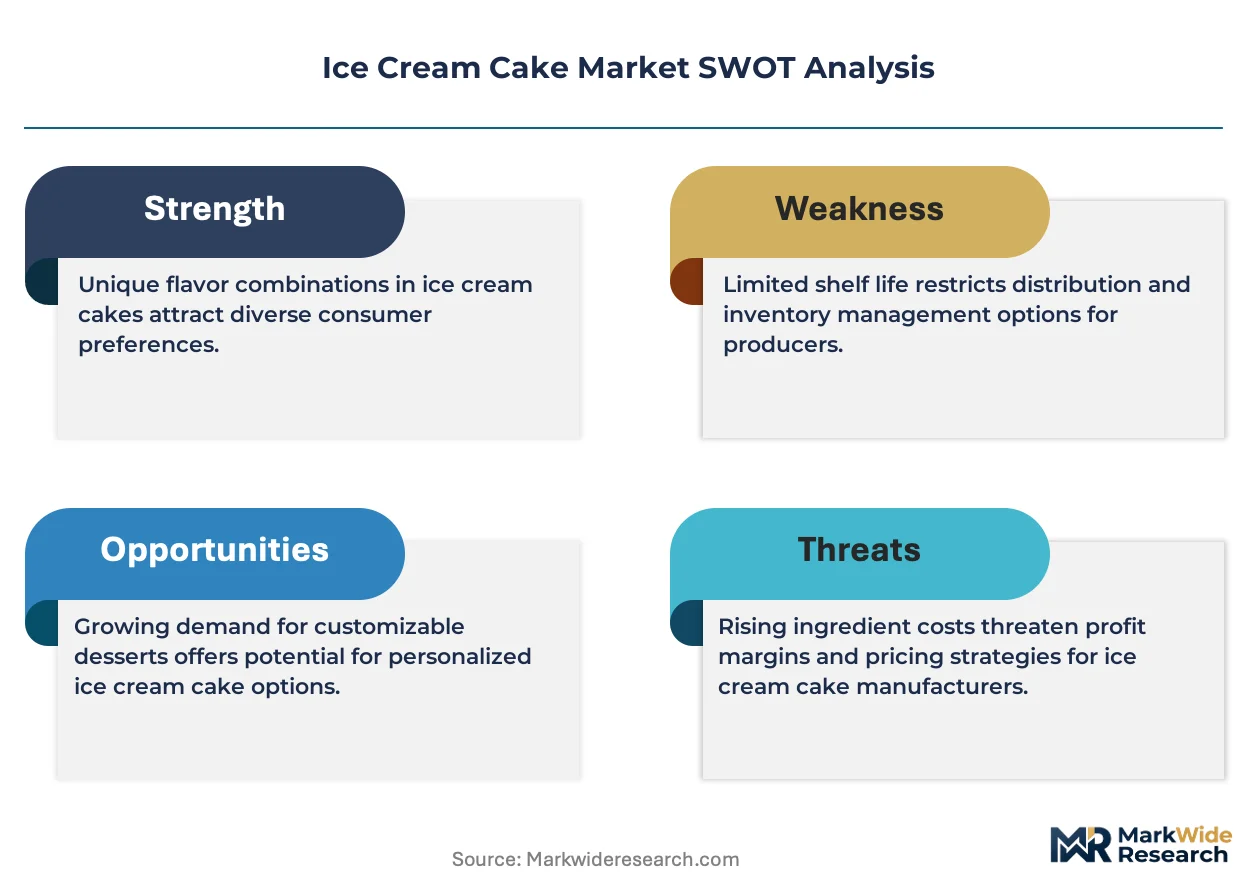
Clean-label ingredient mandates from EFSA and the FDA are forcing reformulation across frozen dessert portfolios, compressing development timelines and elevating R&D spend as the central competitive battleground.
Growth Catalysts
- EFSA Novel Food Guidance:Regulatory clarity on plant-based dairy alternatives accelerates vegan ice-cream-cake commercialization across European retail channels.
- Blast-freezing automation:Continuous tunnel freezers at minus thirty degrees Celsius reduce structural failure rates during transport, enabling e-commerce fulfillment for occasion cakes.
- Metropolitan retail corridor concentration:California, Texas, and New York grocery chains expand dedicated freezer allocations for premium frozen desserts.
Market Restraints
- Butterfat input volatility:Cream and milk powder prices fluctuate with dairy commodity cycles, squeezing margin on premium-tier formulations.
- Cold-chain infrastructure gaps:Last-mile frozen fulfillment remains underdeveloped outside major US urban cores, limiting geographic expansion.
- Substitution by frozen novelties:Single-serve ice-cream bars and mochi bites capture impulse occasions with lower price points and simpler logistics.
Strategic Opportunities
- Specialty retail bakery channel:Dessert shops in Texas and New York seek co-manufactured ice-cream-cake programs to differentiate occasion offerings.
- FDA gluten-free labeling alignment:Certified gluten-free positioning opens premium pricing pools for dietary-accommodation segments.
- Direct-to-consumer customization platforms:Online configurators for birthday and wedding cakes bypass traditional grocery slotting fees.
Industry Challenges
- Allergen cross-contamination protocols:FDA Food Safety Modernization Act compliance requires segregated production lines, elevating capital intensity for multi-SKU facilities.
- Cottage-food regulatory fragmentation:State-level home-kitchen exemptions create uneven competitive terrain between artisanal entrants and licensed manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Cream Cake Market |
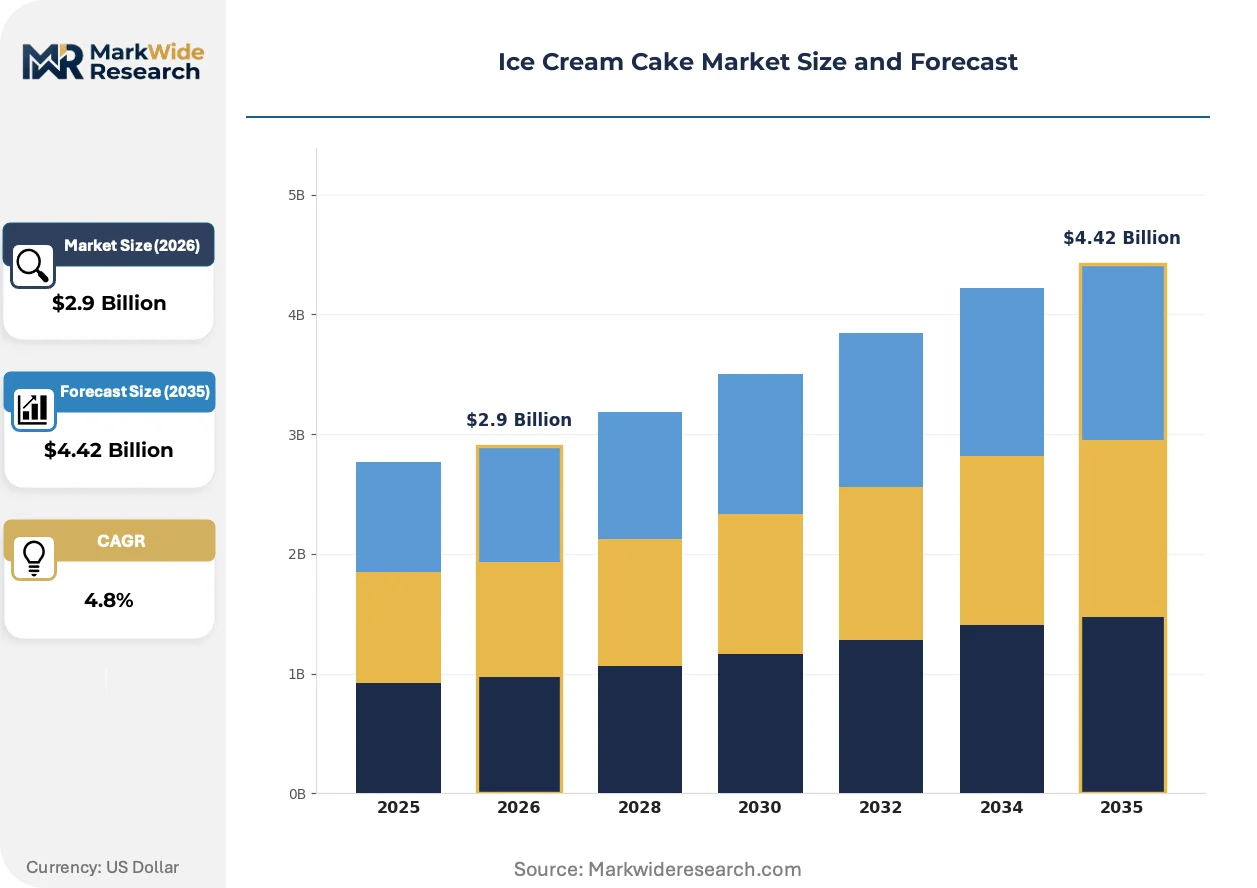
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $4.42 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Vegan, Gluten-Free, Premium Flavor Profile: Chocolate, Vanilla, Strawberry, Cookies & Cream Packaging Type: Box, Tub, Slice, Cup Distribution Channel: Supermarkets, Online, Specialty Stores, Convenience Stores |
| Companies Covered | Cicom SRL, Rich Products, Silver Pail Dairy, Jon Donaire, Friendly's, Moo Moo Isbar, De Jong's IJS B.V., Carvel, Axaiko Entelvais A.V.E.E., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Cream Cake Market Trends and Innovations
Reformulation science and distribution technology are converging to reshape how frozen layered desserts reach celebratory and impulse purchase occasions.
Precision-controlled blast-freezing technology is bifurcating the production landscape. Artisanal producers in California adopt small-batch tunnel systems to preserve structural integrity of cookie-dough inclusions, while mass manufacturers deploy continuous freezers for throughput. This equipment divergence is compressing mid-scale producers between craft credibility and cost efficiency.
EFSA clean-label mandates and FDA frozen dessert standards are tightening ingredient disclosure requirements. Reformulation to eliminate artificial stabilizers extends product-development timelines by eight to fourteen months. Premium and gluten-free SKUs absorb disproportionate compliance burden as certification bodies verify supply-chain integrity.
Occasion-based purchasing is migrating from grocery impulse aisles toward pre-ordered customized fulfillment. Specialty retail bakeries in New York and Texas now allocate freezer capacity to made-to-order ice-cream-cake programs. This channel pivot elevates service complexity but captures margin pools unavailable through standard retail distribution.
Ice Cream Cake Market Segmentation
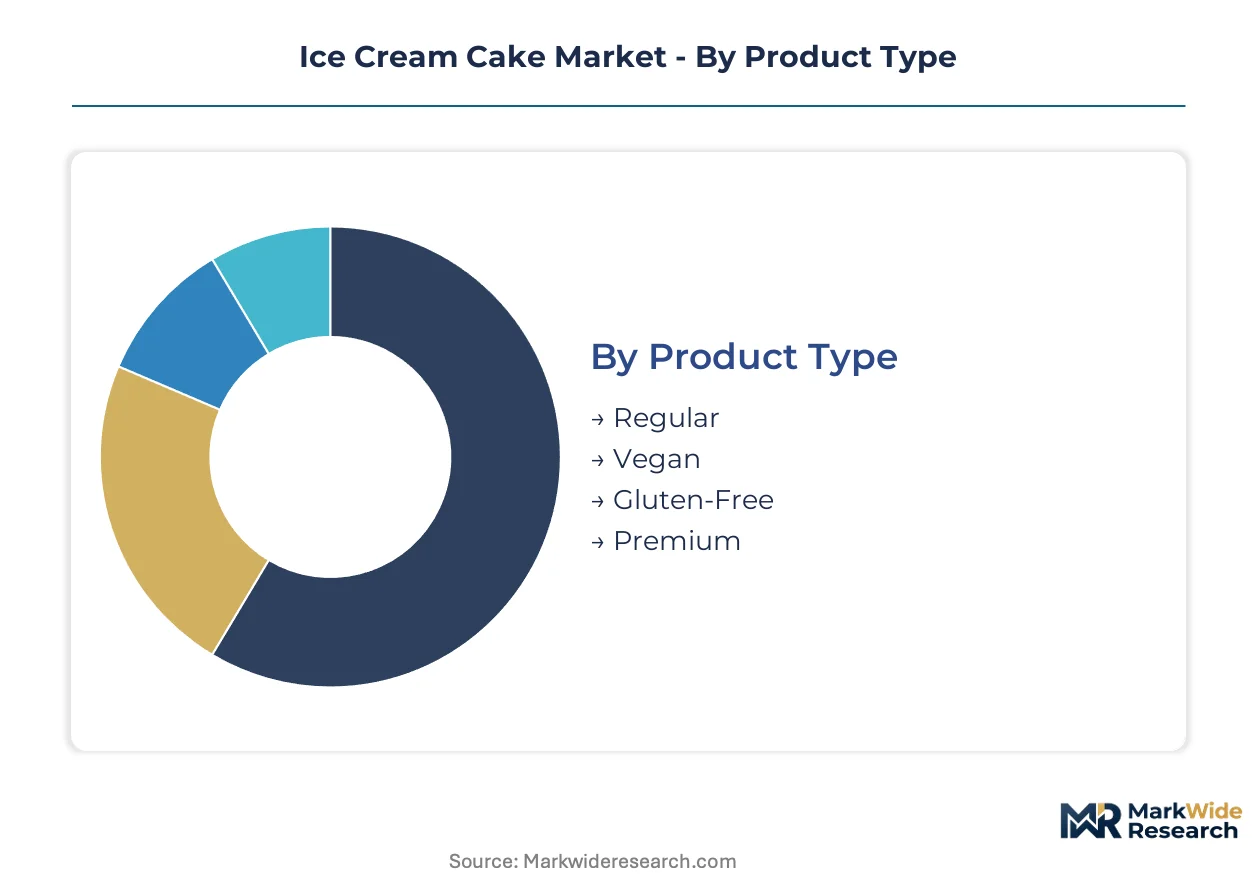
Ice cream cake segmentation reflects divergent compliance burdens and cold-chain requirements across formulation types. FDA frozen dessert standards and EFSA clean-label mandates create tiered regulatory exposure that reshapes portfolio prioritization for manufacturers.
Product Type:
EFSA novel food classifications and FDA dairy standards enforce distinct labeling and stability testing protocols across formulation categories.
- Regular:Conventional dairy-based formulations with butterfat content between 10-16% dominate foodservice and grocery freezer cases. California and Texas metropolitan retail corridors account for the densest concentration of volume, though margin compression from commodity dairy price cycles constrains pricing flexibility.
- Premium:Higher butterfat formulations exceeding 16% with artisanal inclusions command disproportionate margin pools through specialty retail bakery channels. New York dessert shops and Texas occasion-cake specialists drive adoption, trading up for structural integrity during extended display periods.
- Vegan:Plant-based dairy alternatives require EFSA novel food clearance in Europe and FDA ingredient disclosure alignment, extending development timelines. Fastest-expanding segment across direct-to-consumer platforms and metropolitan specialty stores.
- Gluten-Free:Certified formulations eliminate wheat-based cake substrates, requiring segregated production lines under FDA Food Safety Modernization Act protocols. Premium pricing pools open through dietary-accommodation positioning in specialty retail channels.
Regular formulations handle the majority of throughput; Vegan is gaining share fastest on clean-label momentum.
Flavor Profile:
Consumer preference concentration in celebratory purchase occasions drives volume distribution across taste categories.
- Chocolate:Cocoa-based formulations with fudge or ganache layers anchor occasion-cake procurement through supermarkets and online configurators. Structural stability during blast-freezing at minus thirty degrees Celsius favors denser chocolate mousse inclusions over lighter whipped bases.
- Cookies & Cream:Cookie-dough or crushed-cookie inclusions require precision-controlled freezing to prevent textural degradation. California artisanal producers deploy small-batch tunnel systems specifically to preserve inclusion integrity, differentiating against mass-manufactured alternatives.
- Vanilla:Neutral base formulations serve as customizable canvases for decoration and messaging, concentrating in bakery-channel made-to-order programs.
- Strawberry:Fruit-based formulations face shorter shelf-life constraints and stricter cold-chain requirements, limiting distribution radius from production facilities.
Chocolate commands the largest volume position; Cookies & Cream climbs fastest on inclusion-texture innovation.
Packaging Type:
Cold-chain integrity requirements and occasion-based consumption patterns shape format selection across channels.
- Box:Rigid corrugated enclosures with insulated liners protect structural integrity during transport for occasion cakes. E-commerce fulfillment for birthday and wedding custom orders depends on box-format thermal performance through last-mile frozen delivery.
- Slice:Individual portion packaging captures impulse dessert occasions in convenience stores and grab-and-go bakery cases. Lower price points and simpler logistics compete against frozen novelties for unplanned purchase moments.
- Tub:Cylindrical containers accommodate round layer cakes for grocery freezer slotting, optimizing cube utilization in retail display cases.
- Cup:Single-serve formats target portion-controlled consumption, concentrating in convenience store channels and foodservice pre-packaged dessert programs.
Box packaging carries the highest value per unit; Slice formats expand most quickly on impulse-channel penetration.
Distribution Channel:
Channel selection determines margin capture, with direct fulfillment bypassing traditional slotting-fee structures.
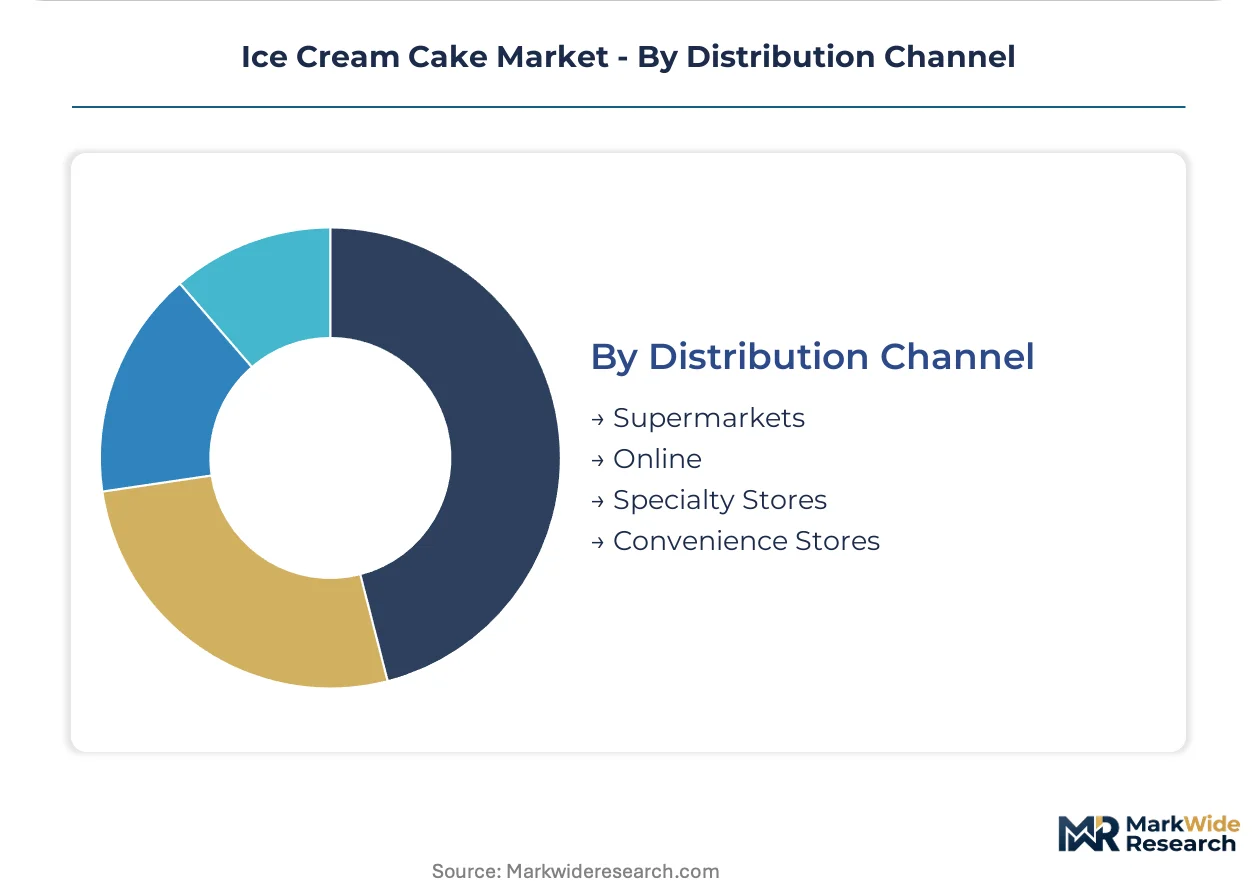
- Supermarkets:Dedicated freezer allocations in California, Texas, and New York grocery chains represent the dominant volume pathway. Slotting fees and promotional spending requirements compress net margins despite high throughput.
- Online:Direct-to-consumer configurators for customized occasion cakes bypass retail intermediaries, capturing margin pools unavailable through standard distribution. Blast-freezing automation and continuous tunnel freezers enable structural integrity through e-commerce fulfillment.
- Specialty Stores:Dessert shops and premium retail bakeries in metropolitan corridors seek co-manufactured ice-cream-cake programs to differentiate occasion offerings, elevating service complexity for higher unit economics.
- Convenience Stores:Impulse-aisle placement for single-serve formats competes with frozen novelties on price and logistics simplicity, constraining premium positioning.
Supermarkets move the bulk of volume; Online channels show the steepest expansion trajectory on customization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European producers ship frozen dessert formulations to North American specialty retailers, establishing transatlantic trade corridors for premium layered products. Dairy commodity arbitrage and regulatory alignment on clean-label standards shape cross-border procurement patterns. Metropolitan retail density in destination markets determines final-mile distribution economics.
United States
California, Texas, and New York metropolitan corridors drive volume concentration through dedicated freezer allocations in grocery chains. FDA frozen dessert standards and Food Safety Modernization Act protocols enforce allergen-labeling and production-line segregation requirements. Los Angeles and Dallas-Fort Worth dessert shops expand co-manufactured ice-cream-cake programs for occasion-based customization.
Germany
Artisanal dairy traditions sustain demand for higher-butterfat premium formulations through specialty retail channels. EFSA clean-label mandates and novel food guidance on plant-based alternatives accelerate vegan SKU development timelines. Bavaria's dairy processing clusters supply stabilized cream bases to frozen dessert manufacturers across Central Europe.
United Kingdom
Metropolitan London and Manchester retail bakeries source imported European formulations for celebration-cake differentiation. EFSA regulatory alignment post-Brexit transition maintains ingredient disclosure requirements for cross-channel trade. Premium positioning in Southeast England grocery chains concentrates on gluten-free and dietary-accommodation segments.
Netherlands
Specialized dairy sourcing networks in North Holland and Friesland anchor European supply for stabilized frozen dessert bases. EFSA guidance on clean-label reformulation extends product-development cycles for export-oriented producers. Rotterdam distribution hubs facilitate cold-chain logistics to UK and German retail channels.
Canada
Ontario and Quebec metropolitan markets exhibit concentrated demand through specialty retail bakery channels. Health Canada frozen dessert regulations align with FDA standards on allergen labeling and production facility inspection protocols. Toronto dessert shops seek co-manufactured programs to compete with US-imported occasion-cake offerings.
Ice Cream Cake Market Competitive Landscape
Listed leaders compete with private specialists across formulation tiers and geographic reach. The vendor base separates into scale-driven mass manufacturers, craft-oriented regional dairies, and co-manufacturing service providers. Three archetypes dominate: vertically integrated frozen-dough conglomerates, heritage-branded retail chains, and specialized European dairy exporters. Competitive moves concentrate on blast-freezing automation investments and direct-to-consumer platform development.
Within the heritage-branded tier, Carvel occupies a position exemplifying decades-long retail presence and seasonal product cycles. De Jong's IJS B.V. represents the specialized European dairy exporter archetype through regional flavor expertise and concentrated supply relationships. Rich Products anchors the vertically integrated conglomerate segment with frozen-dough capabilities and broad foodservice distribution networks.
| Leading Market Players |
|---|
| Cicom SRL |
| Rich Products |
| Silver Pail Dairy |
| Jon Donaire |
| Friendly's |
| Moo Moo Isbar |
| De Jong's IJS B.V. |
| Carvel |
| Axaiko Entelvais A.V.E.E. |
| Others |
Pricing and Supply Chain Analysis
Plant-based dairy alternatives replacing conventional cream bases redraws procurement geography toward EFSA-cleared European suppliers while compressing premium-tier margins through novel-food certification costs. This substitution dynamic simultaneously elevates butterfat input volatility and extends formulation timelines, reshaping how manufacturers balance cost efficiency against clean-label positioning.
Pricing Analysis
Blast-freezing automation gaps separate pricing tiers across production generations, with continuous tunnel systems commanding premium throughput economics against legacy batch operations. Three-tier pricing structure across premium, standard, and economy levels reflects butterfat content gradations and certification status under FDA frozen dessert standards. Cost compression in standard-tier formulations is intensifying because commodity dairy cycles squeeze margin flexibility, while premium buyers exhibit lowest price sensitivity due to occasion-based purchasing patterns.
Supply Chain Analysis
The Netherlands and Germany anchor European supply for stabilized cream bases and specialized dairy ingredients, feeding North American and UK retail channels through Rotterdam distribution hubs. Raw material dependencies center on cream, milk powder, and plant-based fat alternatives, with cold-chain equipment and insulated packaging as critical downstream inputs. Single-source vulnerability concentrates in Bavarian dairy processing clusters, where specialized stabilization expertise limits rapid supplier switching. Distribution runs through dedicated freezer allocations in California, Texas, and New York metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label reformulation mandates from EFSA and FDA constitute a regulatory inflection accelerating SKU rationalization and R&D concentration, positioning this market for high-growth disruption as compliance costs reshape competitive viability.
For Market Incumbents: Fortify blast-freezing automation investments to preserve structural integrity margins against artisanal entrants deploying small-batch tunnel systems. Deepen backward integration into stabilized cream base production to offset butterfat price volatility, while accelerating FDA gluten-free certification to capture dietary-accommodation premium pools before channel saturation. For New Entrants and Emerging Players: Direct-to-consumer customization platforms represent the most penetrable white-space, as incumbents under-serve pre-ordered occasion-cake demand through traditional grocery slotting. Target Texas and New York metropolitan dessert shops seeking co-manufactured programs, leveraging e-commerce fulfillment to bypass slotting-fee barriers and capture margin pools unavailable through standard retail distribution. For Investors and Strategic Acquirers: Capital is best deployed toward specialized European dairy exporters with EFSA novel-food clearance and regional flavor expertise, as these archetypes command scarcity premiums in transatlantic trade corridors. Watch for inflection signals in blast-freezing automation adoption rates among mid-scale producers, indicating consolidation pressure between craft credibility and cost efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Blast-Freezing Automation Investment | Continuous tunnel freezers at minus thirty degrees Celsius reduce structural failure rates during e-commerce fulfillment. |
| Clean-Label Reformulation Program | EFSA and FDA compliance eliminates artificial stabilizers, extending product-development timelines by eight to fourteen months. |
| Direct-to-Consumer Platform Launch | Online configurators for birthday and wedding cakes bypass traditional grocery slotting fees in California and Texas corridors. |
| Co-Manufacturing Partnership Expansion | Specialty retail bakeries in New York and Texas seek differentiated occasion-cake programs to compete with mass brands. |
| Gluten-Free Certification Investment | FDA Food Safety Modernization Act compliance opens premium pricing pools through dietary-accommodation positioning. |
Research Methodology
A spread of perspectives from frozen dessert R&D directors, specialty retail bakery procurement managers, cold-chain logistics operators, and EFSA regulatory affairs specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA frozen dessert standards documentation, EFSA novel food guidance publications, customs trade data on dairy ingredient flows, and SEC filings from vertically integrated frozen-dough conglomerates. Bottom-up SKU-level modeling triangulated against top-down channel volume estimates.
Segmentation dimensions modeled include formulation type across regular, premium, vegan, and gluten-free tiers; flavor profile concentration; packaging format by occasion versus impulse use case; and distribution channel economics across supermarkets, online fulfillment, specialty stores, and convenience retail. CAGRs were derived from trajectory fitting across the projection horizon, with inputs from butterfat commodity cycle patterns, metropolitan retail corridor expansion rates, and blast-freezing automation penetration curves.
Underlying assumptions cover sustained EFSA and FDA clean-label enforcement, stable cold-chain infrastructure investment in major US urban cores, and continued plant-based dairy alternative adoption, with deviation risk concentrated in dairy commodity price spikes and cottage-food regulatory fragmentation. Recalibration cycles align with material shifts in novel food clearance timelines and blast-freezing technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Bahrain Bakery Product Market
Bakery Products
Low-Gluten Emmer and Einkorn Flour Blends Market
Bakery Products
Bakery Conditioner Market
Bakery Products
Par-Baked Bread Market
Bakery Products
Frozen Bakery Additives Market
Bakery Products
India Cake Market
Bakery Products
Premix Bread Flour Market
Bakery Products
Bakery Improvers Market
Bakery Products
Bread Mix Market
Bakery Products
On-The-Go Breakfast Products Market
Bakery Products
Gluten-Free Bread Market
Bakery Products
Pizza Crust Market
Bakery Products
GCC Frozen Bakery Products Market
Bakery Products
Global Baked Food and Cereals Market
Bakery Products
Gluten-Free Pizza Crust Market
Bakery Products
Bake Stable Pastry Fillings Market