
 Low-Calorie Breakfast Muffins Market | 2026-2036
Low-Calorie Breakfast Muffins Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Calorie Breakfast Muffins Market Analytics
Market Context with Strategic Players
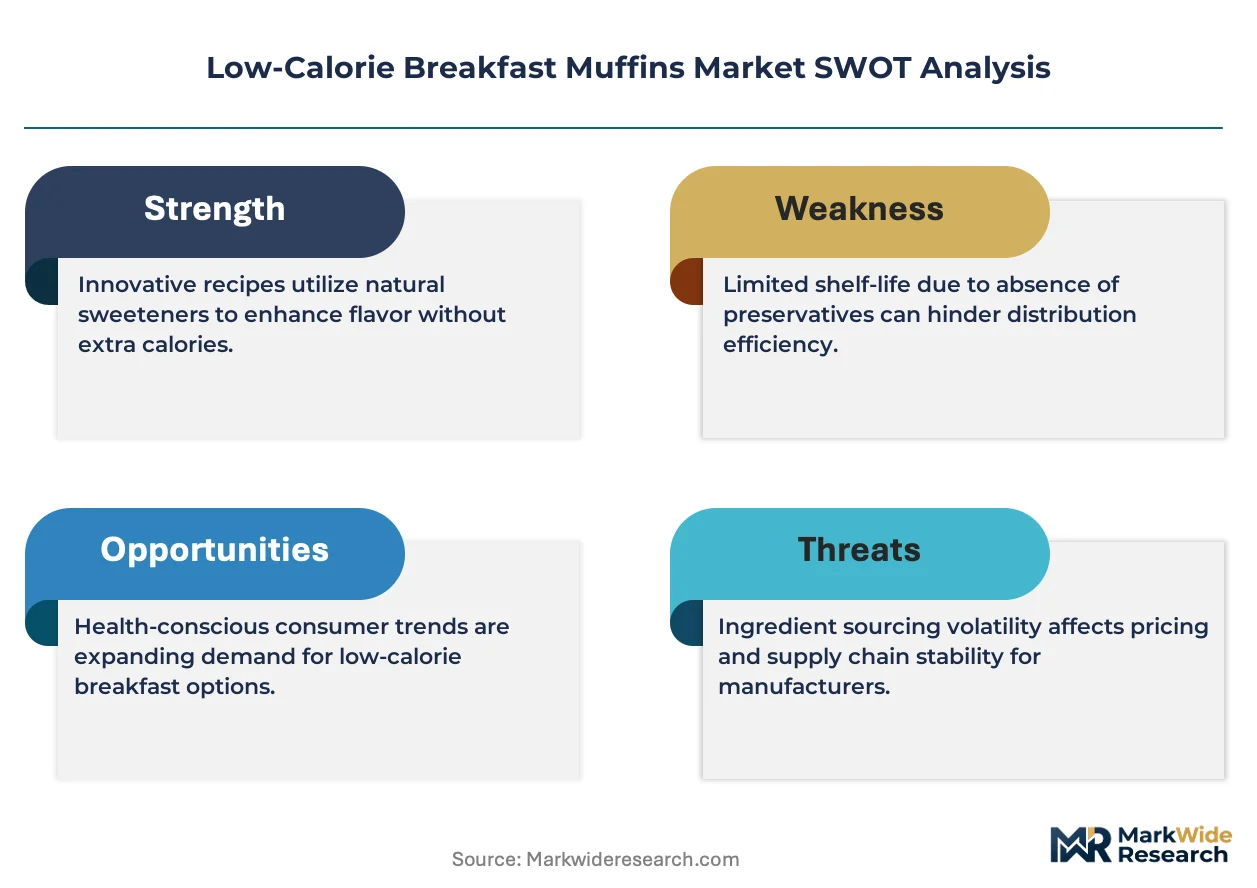
Asset-light co-manufacturing partnerships are reshaping competitive entry barriers in the low-calorie breakfast muffins category, allowing regional brands to scale without capital-intensive bakery investments. Dave's Killer Bread leverages its whole grain expertise and established organic supply chains to dominate shelf-stable distribution in natural grocery channels. Aunt Millie's sustains its position through deep Midwest manufacturing scale and long-standing supermarket relationships that control in-store bakery adjacencies. Food for Life specializes in sprouted grain processes that differentiate its ingredient narrative from conventional reduced-calorie competitors.
Technical Definition and Structural Segments
Low-calorie breakfast muffins are portion-controlled baked goods formulated with reduced caloric density through modified fat content, alternative sweeteners, and fiber enrichment, typically delivering under 200 calories per standard serving while maintaining structural integrity via emulsifier systems and hydrocolloid stabilizers. High-protein formulations now anchor the fastest-growing product type segment as sports nutrition positioning migrates from bars to morning occasions, while gluten-free SKUs retain mature volume but face margin compression from ingredient cost inflation. Online retailers represent the most dynamic distribution channel, though supermarkets still capture the dominant share of purchase occasions and control promotional cadence that determines trial rates for new entrants.
Regulatory Framework and Forward Outlook
The FDA's Nutrition Facts panel mandates and USDA organic certification requirements shape formulation decisions and label claims across the category, with the FTC actively scrutinizing implied health benefit messaging in direct-to-consumer advertising. State-level sugar taxes in jurisdictions like Philadelphia and Berkeley further constrain permissible sweetness levels in products targeting those markets. Stakeholders must monitor evolving FDA guidance on dietary fiber definition and added sugar disclosure thresholds, as these technical determinations will force reformulation investments or disqualify existing products from clean-label positioning.
Market Dynamics
The FDA's updated Nutrition Facts labeling requirements for added sugars and serving sizes are forcing systematic reformulations across the low-calorie breakfast muffins category, compressing permissible sweetness levels and recalibrating portion architecture.
Growth Catalysts
- Fitness enthusiast demand:Protein-forward morning routines are pulling sports nutrition positioning from bars into baked goods, creating new occasion-based consumption.
- Urban health consciousness:United States metropolitan consumers are driving premium positioning and distribution expansion through natural grocery channel growth.
- Organic certification frameworks:USDA organic requirements are incentivizing supply chain transparency and ingredient provenance investments that command shelf price premiums.
Market Restraints
- Alternative sweetener cost volatility:Erythritol and allulose input prices fluctuate with corn and wheat feedstock markets, squeezing margin structures on clean-label formulations.
- Midwest manufacturing concentration:Deep production scale in specific US heartland regions creates geographic vulnerability to weather-driven grain supply disruptions.
- Structural sweetness ceiling:State-level sugar taxes in Philadelphia and Berkeley impose hard formulation constraints that prevent product standardization across jurisdictions.
Strategic Opportunities
- Online retail channel expansion:Direct-to-consumer platforms bypass supermarket promotional gatekeeping and enable subscription-based recurring revenue models.
- Sprouted grain process convergence:Enzymatic activation techniques combined with reduced-calorie density targets create differentiated ingredient narratives.
- Fiber definition clarity:Evolving FDA guidance on dietary fiber thresholds offers first-mover advantage for brands preemptively reformulating to meet stricter disclosure standards.
Industry Challenges
- Emulsifier system expertise scarcity:Hydrocolloid stabilizer formulation requires specialized food science talent that concentrates in legacy bakery R&D centers.
- Clean-label certification timelines:Organic and non-GMO verification processes extend new product development cycles by months.
- Legacy equipment retrofitting:Existing bakery infrastructure requires capital-intensive modification to handle alternative fat systems and reduced moisture formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Calorie Breakfast Muffins Market |
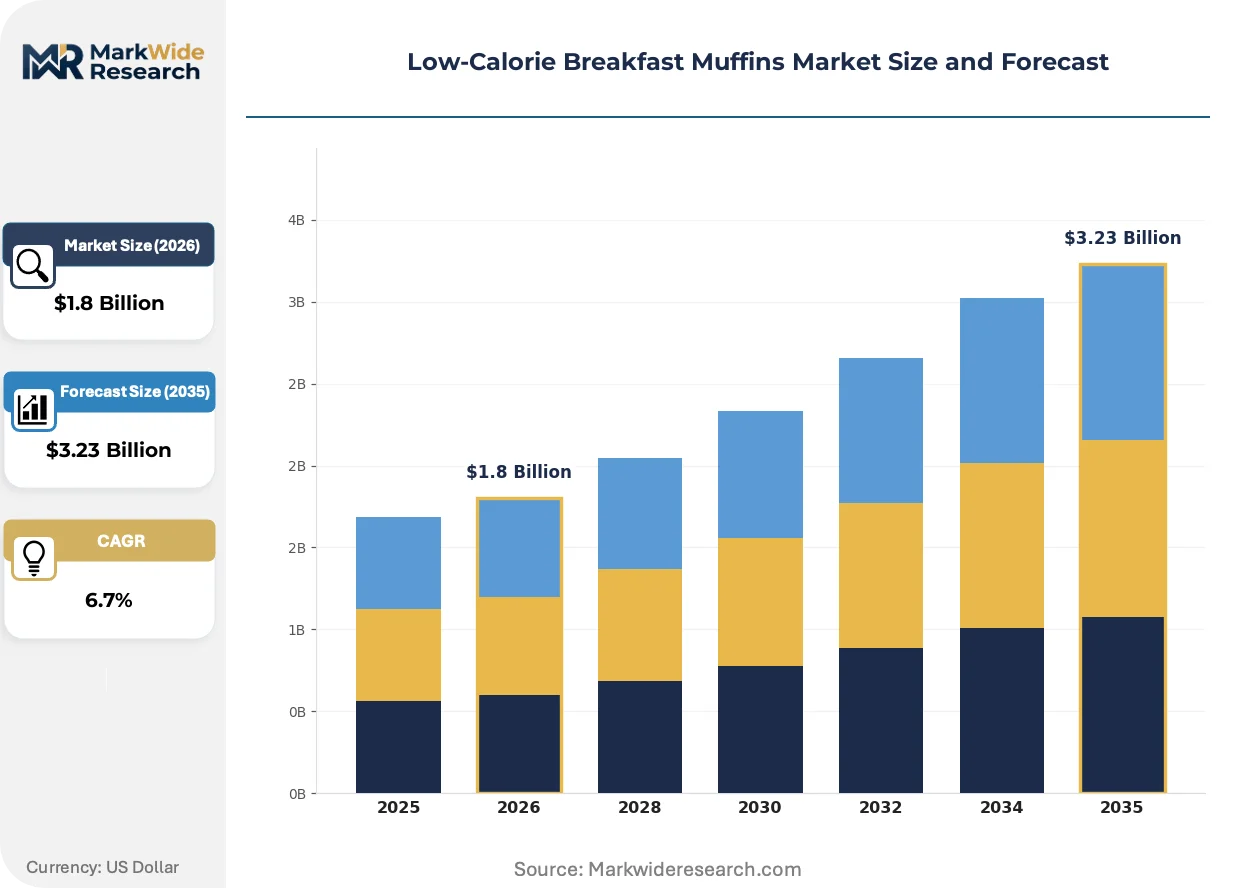
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free, Vegan, High-Protein, Whole Grain Ingredient Type: Oats, Almond Flour, Chia Seeds, Coconut Sugar Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Cafés Customer Type: Fitness Enthusiasts, Weight Watchers, Busy Professionals, Students |
| Companies Covered | Trader Joe’s, Franz Bakery, Food for Life, Dam Good, 365 by Whole Foods Market, Thomas', Aunt Millie’s, Hummus Fit, Dave’s Killer Bread, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Calorie Breakfast Muffins Market Evolving Landscape
Protein enrichment technologies and virtualized production workflows are reconfiguring how low-calorie breakfast muffins are formulated, manufactured, and distributed across fragmented channel landscapes.
Precision fermentation-derived protein isolates are virtualizing traditional dairy and egg binding functions in reduced-calorie formulations. Fitness-oriented consumers are adopting these products at accelerating rates through sports nutrition retail channels. This ingredient shift is compressing reliance on conventional animal-derived emulsifiers and enabling vegan-positioned SKUs to capture shelf space previously reserved for egg-based alternatives.
REACH chemical safety assessments in Europe are tightening scrutiny on hydrocolloid additives and emulsifier systems used in reduced-fat baked goods. Industrial consequence includes accelerated substitution toward naturally derived stabilizers like citrus fiber and oat beta-glucan. Gluten-free SKU producers face disproportionate compliance burden as their formulations depend most heavily on modified additive systems.
Subscription-based replenishment models are displacing traditional supermarket trial-and-repeat purchase cycles among health-conscious urban households. Direct-to-consumer channels capture these buyers through personalized nutrition profiling and automated delivery scheduling. This behavioral shift concentrates most visibly in United States coastal metropolitan markets where time-scarcity and premium willingness intersect.
Low-Calorie Breakfast Muffins Market Segmentation
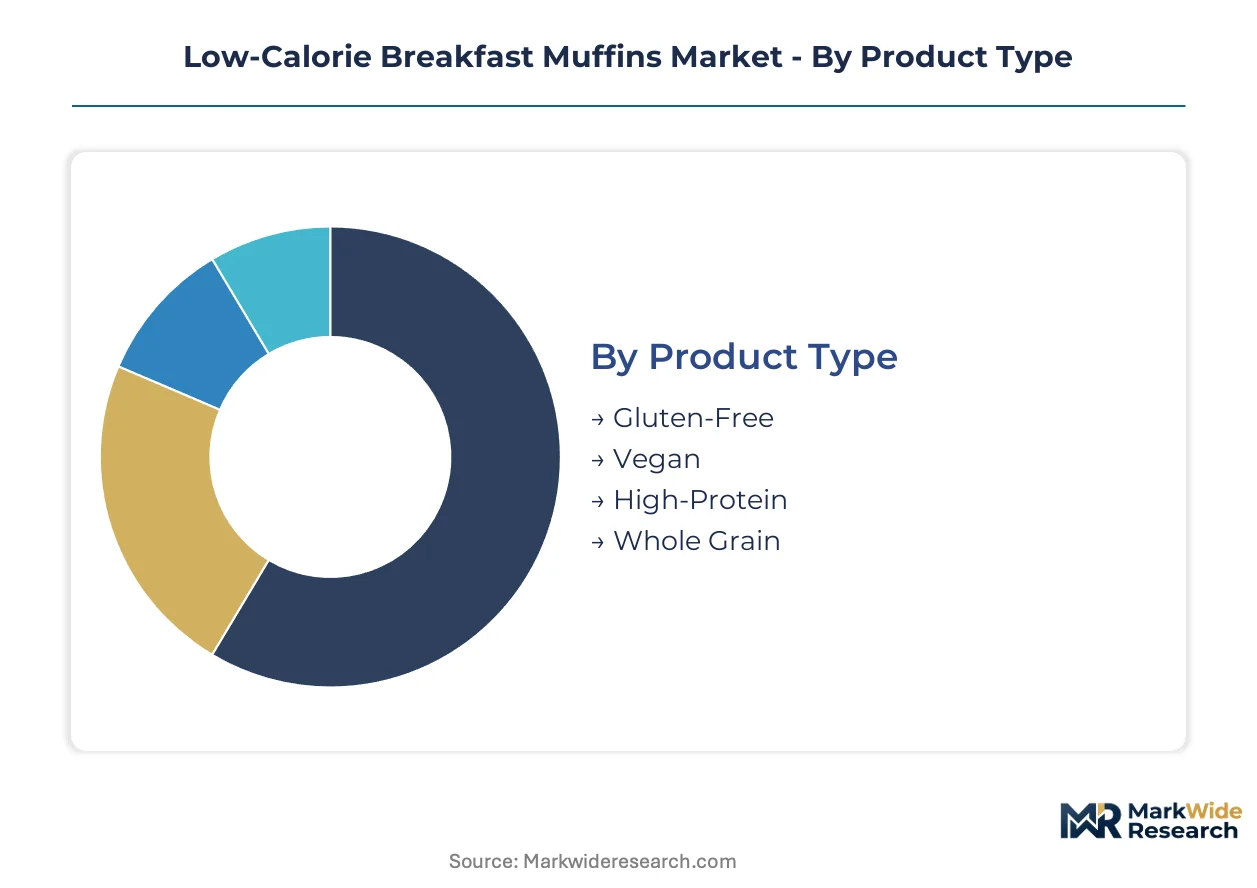
Low-calorie breakfast muffins require precise segmentation to capture divergent formulation requirements across protein-forward fitness consumers and clean-label organic buyers. Each segment demands distinct ingredient sourcing, certification timelines, and channel strategies that reshape margin structures.
Product Type:
After-sales service intensity varies sharply across product types, with high-protein formulations demanding nutritional counseling support and gluten-free SKUs requiring allergen compliance documentation.
- High-Protein:Formulations leverage whey isolates, pea protein concentrates, and precision fermentation-derived binders to deliver 15-20g protein per serving while maintaining moisture retention through hydrocolloid systems. Demand concentrates in United States metropolitan fitness corridors where sports nutrition retail placement drives trial. The FDA's protein content disclosure requirements force third-party testing investments that smaller brands struggle to absorb.
- Gluten-Free:Rice flour, tapioca starch, and xanthan gum systems replace wheat gluten networks, requiring modified baking profiles and extended shelf-life stabilization. Volume concentrates in California and Pacific Northwest markets where celiac awareness and discretionary health spending intersect. Ingredient cost inflation on alternative flours compresses margins versus conventional reduced-calorie alternatives.
- Vegan:Egg replacers from aquafaba, flax gel, or commercial starch-protein blends enable plant-based positioning without dairy derivatives. Clean-label certification timelines extend development cycles.
- Whole Grain:Sprouted wheat, spelt, and ancient grain bases deliver fiber-forward nutrition claims through enzymatic activation processes. USDA organic supply chain transparency commands price premiums in natural grocery channels.
High-Protein holds the largest share; momentum sits with Vegan as precision fermentation technologies mature.
Ingredient Type:
Cost tier stratification separates commodity grain inputs from premium functional ingredients that justify shelf price multiples through provenance storytelling.
- Oats:Rolled and steel-cut oat bases provide soluble beta-glucan fiber for glycemic control claims, with supply chains anchored in Upper Midwest growing regions vulnerable to weather-driven crop variability. Demand concentrates in heartland markets where familiarity reduces education costs and supermarket placement dominates.
- Almond Flour:Blanched almond meal delivers protein density and moisture retention without gluten formation, though California water scarcity and pollination cost volatility create input price instability. Premium positioning in coastal metropolitan natural grocery channels captures health-conscious urban households with discretionary spending capacity.
- Chia Seeds:Omega-3 fatty acid content and hydrophilic gel formation enable egg reduction and moisture binding in reduced-fat formulations. Supply concentrates in Argentina and Australia.
- Coconut Sugar:Low-glycemic index positioning and caramel flavor notes justify premium pricing over conventional sucrose, though Southeast Asian supply chains face climate disruption risks.
Oats holds the largest share; momentum sits with Almond Flour as keto and paleo diet adherence expands.
Distribution Channel:
Customer type concentration determines channel priority, with fitness enthusiasts over-indexing on online replenishment and busy professionals driving convenience-oriented café placement.
- Online Retailers:Direct-to-consumer platforms enable subscription-based recurring revenue, personalized nutrition profiling, and bypass of supermarket promotional gatekeeping. Demand concentrates in United States coastal metropolitan markets where time-scarcity and premium willingness intersect.
- Supermarkets:Dominant purchase occasion capture and promotional cadence control determine trial rates for new entrants, with in-store bakery adjacencies creating impulse purchase opportunities. Volume concentrates in suburban markets where weekly stock-up trips persist.
- Health Food Stores:Natural grocery channel growth in urban corridors supports premium positioning and clean-label certification storytelling. Staff education requirements increase service intensity.
- Cafés:Grab-and-go morning occasion capture targets commuter corridors and central business districts with immediate consumption positioning. Portion-controlled single-serve formats command price premiums over multi-pack retail.
Supermarkets holds the largest share; momentum sits with Online Retailers as subscription models displace traditional trial-and-repeat cycles.
Customer Type:
Application-specific usage occasions separate pre-workout fueling from weight management compliance and convenience-driven meal replacement.
- Fitness Enthusiasts:Protein-forward morning routines and macronutrient tracking discipline drive sports nutrition positioning, with precision fermentation-derived isolates displacing conventional dairy and egg binders. Demand concentrates in United States metropolitan markets with boutique fitness studio density and athletic apparel retail adjacencies.
- Weight Watchers:Caloric density discipline and portion control compliance require precise serving size architecture and transparent macro disclosure. Volume concentrates in suburban markets where structured diet program adherence persists.
- Busy Professionals:Time-scarcity and desk-based consumption favor shelf-stable, individually wrapped formats with minimal preparation requirements. Premium willingness supports convenience pricing.
- Students:Price sensitivity and dormitory storage constraints favor multi-pack value formats and extended shelf-life stability without refrigeration dependency.
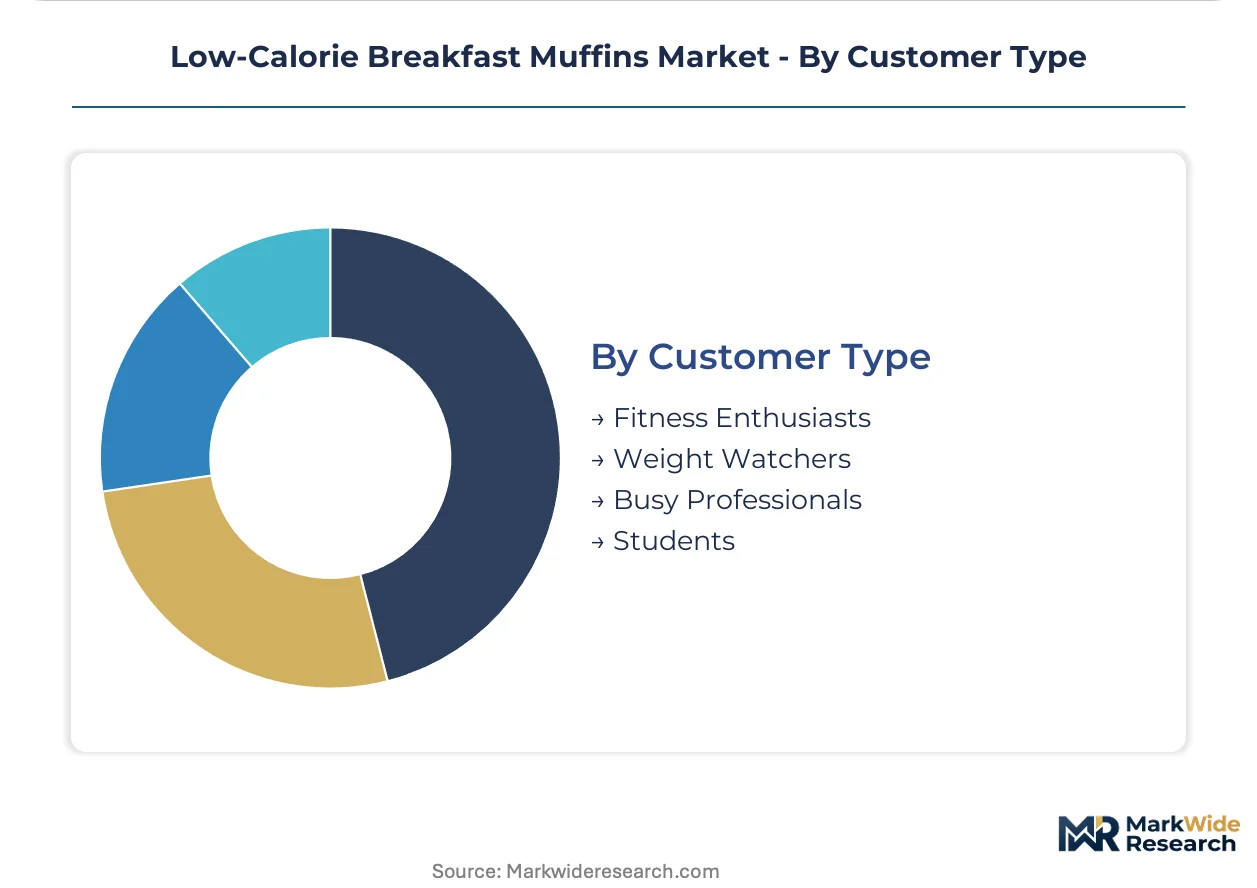
Weight Watchers holds the largest share; momentum sits with Fitness Enthusiasts as sports nutrition positioning migrates from bars to baked goods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium shelf pricing in United States coastal metros commands 40-60% markups over equivalent products in German discount retail channels, creating divergent margin architectures that reshape where innovation capital deploys.
United States
Fitness enthusiast density in Los Angeles, Austin, and New York Metro drives protein-forward SKU proliferation through boutique studio adjacencies and sports nutrition retail placement. The FDA's updated Nutrition Facts labeling requirements for added sugars force systematic reformulation investments that smaller regional brands struggle to absorb. Chicago and Minneapolis manufacturing clusters concentrate Midwest grain supply integration, with Aunt Millie's leveraging deep production scale to control in-store bakery adjacencies across heartland supermarket networks.
Germany
REACH chemical safety assessments tighten scrutiny on hydrocolloid additives and emulsifier systems, accelerating substitution toward naturally derived stabilizers like citrus fiber and oat beta-glucan. Berlin and Hamburg urban corridors support premium organic positioning through EDEKA and REWE natural grocery channel expansion. Bavarian milling traditions supply sprouted grain expertise that Food for Life exemplifies in enzymatic activation process differentiation.
United Kingdom
London and Southeast England health-conscious professionals drive subscription-based replenishment models that displace traditional supermarket trial-and-repeat cycles. The Food Standards Agency's evolving clean-label guidance creates compliance uncertainty that extends new product development timelines. Manchester and Birmingham distribution hubs concentrate direct-to-consumer fulfillment infrastructure for brands bypassing Tesco and Sainsbury's promotional gatekeeping.
Canada
Toronto and Vancouver metropolitan markets concentrate demand for gluten-free formulations where celiac awareness and discretionary health spending intersect. Health Canada's updated nutrition labeling regulations align with FDA disclosure thresholds, enabling cross-border product standardization for US exporters. Quebec's artisan bakery heritage supports small-batch organic positioning that commands price premiums in natural grocery channels.
Australia
Sydney and Melbourne fitness culture drives protein enrichment adoption through sports nutrition retail placement and boutique fitness studio partnerships. The Therapeutic Goods Administration's scrutiny of implied health benefit messaging constrains direct-to-consumer advertising claims. Melbourne's food manufacturing corridor concentrates precision fermentation-derived ingredient processing that enables vegan-positioned SKU expansion.
Low-Calorie Breakfast Muffins Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient and certification layers. The vendor base stratifies between national bakery conglomerates with supermarket distribution lock-in, regional organic specialists with supply chain transparency narratives, and private-label retailers capturing price-sensitive volume. Three archetypes dominate: legacy manufacturers with Midwest production scale, sprouted-grain organic purists with natural grocery channel dominance, and retailer-owned brands with vertical cost control. Competitive moves concentrate on co-manufacturing partnerships that lower capital barriers and subscription platform investments that capture recurring revenue.
Within the organic-specialist tier, Food for Life and Dave's Killer Bread exemplify ingredient-provenance positioning that commands shelf price premiums through USDA organic certification and enzymatic activation storytelling. Aunt Millie's anchors the scale-driven manufacturing archetype with deep Midwest production infrastructure and long-standing supermarket relationships. Among retailer-owned platforms, 365 by Whole Foods Market and Trader Joe's occupy positions that leverage private-label cost structures and controlled distribution to undercut branded alternatives on price while matching clean-label credentials.
| Leading Market Players |
|---|
| Trader Joe's |
| Franz Bakery |
| Food for Life |
| Dam Good |
| 365 by Whole Foods Market |
| Thomas' |
| Aunt Millie's |
| Hummus Fit |
| Dave's Killer Bread |
| Others |
Value Network & Pricing Analysis
Overcapacity in Midwest grain processing facilities compresses supplier margins while concentrating pricing power among co-manufacturing aggregators who bundle regional bakery capacity. This utilization dynamic forces ingredient suppliers toward extended payment terms and volume-commitment contracts that reshape downstream cost structures for branded and private-label muffin producers alike.
Pricing Analysis
The customization-premium spread between configured-to-order organic SKUs and standard reduced-calorie formulations spans certification-grade differentiation and supply chain transparency investments. Pricing stratifies across premium USDA organic tiers, conventional clean-label mid-market positioning, and economy private-label alternatives driven by volume scale and retailer vertical integration. Pricing pressure stems from alternative sweetener cost volatility as erythritol and allulose feedstock prices fluctuate with corn and wheat markets. Weight Watchers segment buyers exhibit highest price sensitivity, while Fitness Enthusiasts demonstrate lowest sensitivity due to sports nutrition premium willingness.
Supply Chain Analysis
Supplier-financing facilities from Upper Midwest grain cooperatives extend payment terms to 90-120 days for certified organic oat and wheat suppliers, easing working capital constraints but embedding interest costs into ingredient pricing. Raw material sourcing draws from United States heartland grain belts, Canadian prairie organic acreage, and Argentinian chia seed harvests. Single-source vulnerability concentrates in California almond flour supply where water scarcity and pollination cost volatility create input instability. Distribution runs through supermarket central warehouses controlling promotional cadence, with direct-to-consumer fulfillment emerging as alternative channel architecture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as protein bars and precision-fermented breakfast alternatives capture morning occasion spending from traditional baked goods. The threat of sports nutrition format migration demands structural response.
For Market Incumbents: Build formulation IP moats around precision fermentation-derived protein integration and enzymatic activation processes that differentiate from commodity reduced-calorie alternatives. Anchor Midwest manufacturing scale through co-manufacturing partnerships that lower capital barriers for capacity expansion. Absorb FDA fiber definition compliance costs ahead of smaller competitors to disqualify rival clean-label claims. For New Entrants and Emerging Players: Pacific Northwest gluten-free white space offers lowest competitive density where celiac awareness and discretionary health spending intersect with limited incumbent shelf presence. Target online subscription replenishment models in coastal metropolitan corridors bypassing supermarket promotional gatekeeping. Deploy personalized nutrition profiling as go-to-market angle capturing Fitness Enthusiast trial through macronutrient customization. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer platforms with subscription infrastructure and proprietary customer data assets. Five-to-ten year viability favors brands with USDA organic certification moats and precision fermentation ingredient partnerships rather than commodity formulation dependencies. Monitor FDA added-sugar disclosure threshold evolution as inflection signal forcing reformulation investment waves that concentrate market share among capitalized players.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Virtualizes dairy and egg binding functions enabling vegan SKU expansion into sports nutrition channels. |
| Subscription Platform Launch | Captures recurring revenue from time-scarce urban households bypassing supermarket promotional dependency. |
| USDA Organic Certification Investment | Commands shelf price premiums through supply chain transparency narratives in natural grocery channels. |
| Co-Manufacturing Network Expansion | Lowers capital barriers for regional brands scaling without bakery infrastructure ownership. |
| Direct-to-Consumer Channel Development | Enables personalized nutrition profiling and automated delivery scheduling in coastal metropolitan markets. |
Research Methodology
Operator-level perspectives from brand managers, category buyers at natural grocery retailers, co-manufacturing facility directors, and supply chain planners anchored the qualitative base for this study. Primary interviews combined with secondary validation from FDA guidance documents, USDA organic certification databases, Nielsen retail audit data, and SEC filings from publicly traded bakery conglomerates. Bottom-up SKU-level volume modeling and top-down category spend analysis provided triangulation across projection methodologies.
Scenario-bracketing framed demand trajectories across the projection horizon with sensitivity testing for regulatory intervention timing and alternative sweetener price volatility. Segmentation dimensions modeled include product type architecture, ingredient provenance tier, distribution channel structure, and customer occasion-based usage patterns. CAGRs derived from historical volume trajectories, penetration rate assumptions, and per-capita consumption elasticity estimates calibrated against protein-forward dietary shift indicators and urban health consciousness indices.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision-fermented alternative protein startups or rapid supermarket private-label expansion would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Pancakes Market
Bakery Products
Laminated Dough Market
Bakery Products
Europe Zwieback Market
Bakery Products
Bread Improver Market
Bakery Products
US Retail Packaged Bread Market
Bakery Products
Bakers Yeast Market
Bakery Products
Shelf-Stable Dough Market
Bakery Products
Baked Foods Market
Bakery Products
Bakery Cases Market
Bakery Products
Instant Cake Emulsifier Market
Bakery Products
Middle East and Africa Fortified Bakery Products Market
Bakery Products
Sourdough Market
Bakery Products
Low Calorie Flour Market
Bakery Products
Low-Calorie Pie Market
Bakery Products
Asia-Pacific Frozen Bakery Market
Bakery Products
Low Fat Bread Market