
 Pastry Dough Market | 2026-2036
Pastry Dough Market Size, Share, and Industry Trends Forecast 2026-2036
Pastry Dough Market Analytics
Portion-controlled and individually wrapped frozen dough configurations is broadening buyer choice across foodservice and retail channels. General Mills Inc. leverages its manufacturing scale to dominate North American frozen dough distribution. Aryzta AG anchors European supply through specialized artisan and industrial bakery formats. Grupo Bimbo extends its reach across Latin America with localized pastry varieties and captive distribution networks.
Pastry dough comprises laminated, shortened, or unleavened flour-based preparations containing specified fat percentages, moisture content, and gluten development parameters, manufactured through sheeting, rolling, or extrusion processes for subsequent baking into structural or decorative food items. Puff pastry and shortcrust categories command the largest volume share due to their versatility across sweet and savory applications, while filo and choux segments attract premium positioning in specialized confectionery and restaurant channels. Bakery Products and Frozen Meals applications concentrate margin pools where cold-chain reliability and extended shelf-life specifications create technical barriers for new entrants.
FDA standards on trans-fat labeling and EFSA thresholds for acrylamide in baked goods constrain formulation choices and drive clean-label R&D investment across manufacturers. The EU F-Gas Regulation and parallel EPA refrigerant rules shape cold-chain infrastructure decisions for frozen dough distribution networks. Stakeholders must monitor evolving sodium-reduction mandates and alternative-fat certification pathways as these regulatory vectors increasingly determine product access and cost structures in key markets.
Market Dynamics
Frozen ready-to-bake formats are compressing traditional scratch-baking workflows across foodservice and retail channels, with cold-chain reliability emerging as the decisive capability separating viable suppliers from marginal operators.
Growth Catalysts
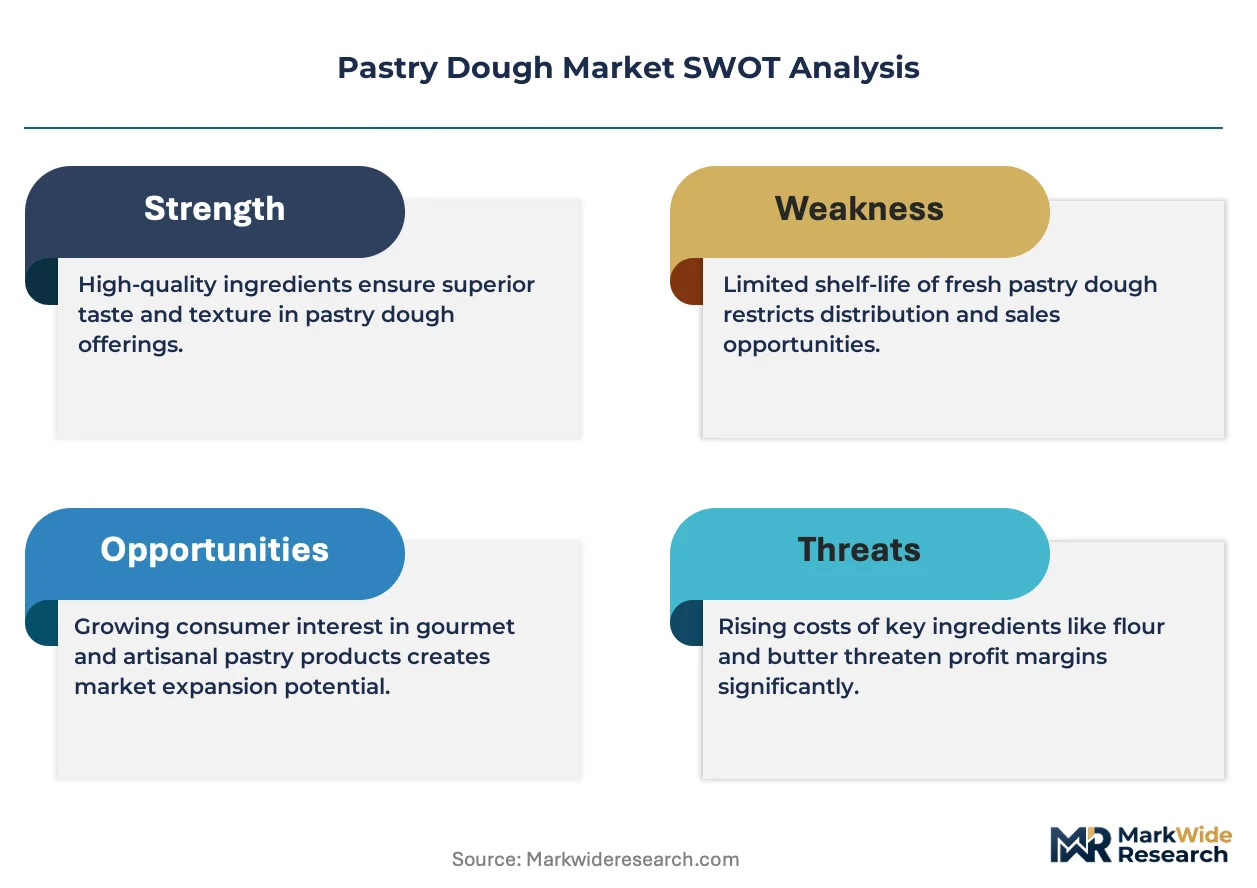
- Clean-label reformulation mandates:FDA trans-fat labeling requirements and EFSA acrylamide thresholds are forcing ingredient transparency upgrades that premium-positioned brands exploit for shelf-space gains.
- Quick-service restaurant automation:Labor-constrained chains in the United States are standardizing frozen dough-to-oven workflows to reduce training overhead and throughput variability.
- Home baking resurgence:Portion-controlled individually wrapped formats are penetrating German and Chinese retail channels where convenience-oriented consumers trade up from commodity flour alternatives.
Market Restraints
- Butter and specialty fat cost volatility:Laminated dough margins compress when European butter futures spike, forcing reformulation trade-offs that degrade texture specifications.
- Cold-chain infrastructure concentration:Frozen dough distribution depends on third-party logistics networks concentrated in coastal United States and Rhine-Ruhr corridors, creating single-point vulnerability.
- Gluten development inconsistency:Industrial sheeting processes struggle to replicate artisanal lamination layers, limiting premium positioning in restaurant channels.
Strategic Opportunities
- Plant-based fat systems:EFSA novel food approval pathways for fermented lipid alternatives open clean-label positioning in European markets where dairy-free claims command price premiums.
- Specialized confectionery channels:Choux and filo segments in Japan and South Korea attract premium pricing from patisserie chains seeking differentiated dessert menus.
- Direct-to-foodservice platforms:Digital ordering portals are bypassing traditional distributor markups for mid-sized bakery operators in urban China.
Industry Challenges
- Skilled lamination technician scarcity:Industrial bakeries struggle to recruit operators capable of calibrating sheeting equipment for consistent layer integrity at scale.
- Refrigerant compliance timelines:EU F-Gas Regulation phase-down schedules force capital-intensive cold-chain retrofits ahead of payback periods.
- Legacy ERP integration:Frozen inventory management systems lack real-time traceability modules required for emerging blockchain-based certification schemes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pastry Dough Market |
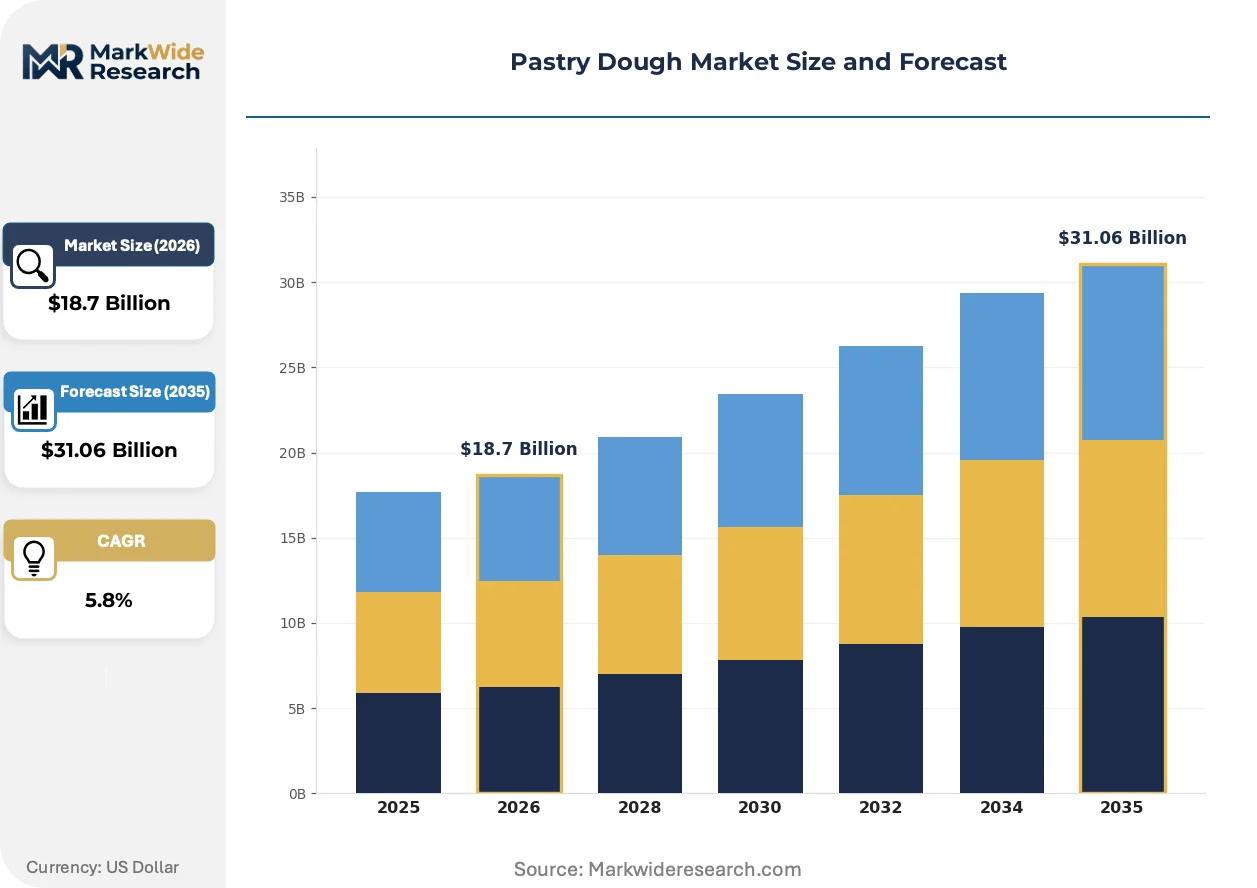
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Puff Pastry, Shortcrust, Filo, Choux Application: Bakery Products, Confectioneries, Frozen Meals, Snacks End User: Restaurants, Catering Services, Retail Bakeries, Home Bakers Packaging Type: Boxes, Bags, Frozen Packs, Tray Packs |
| Companies Covered | Rich Products Corporation, General Mills Inc., Campbell Soup Company, Schwan’s Consumer Brands, Inc, Aryzta AG, Grupo Bimbo, Ardent Mills LLC, Flowers Foods, Inc., Europastry S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pastry Dough Market Evolving Landscape
Automation and ingredient science are converging to redefine production economics and product positioning across frozen and fresh dough categories.
Pressure-fermented laminated dough systems are overtaking conventional retarded-proofing methods in high-volume European facilities. Industrial bakeries in Germany and Poland deploy these systems to compress production cycles from eighteen hours to four without sacrificing layer definition. The technology is overtaking traditional batch processes by enabling just-in-time replenishment for quick-service restaurant networks.
EU F-Gas Regulation refrigerant phase-down mandates are accelerating ammonia-CO2 cascade system adoption in frozen dough cold storage. Facility operators face stranded asset risk from hydrofluorocarbon-dependent infrastructure installed during the 2010s expansion wave. German and Dutch distribution hubs are absorbing the steepest compliance costs as they retrofit multi-temperature zones serving laminated and shortened dough variants.
Subscription-based bakery ingredient kits are disrupting conventional retail purchasing in United States metropolitan markets. Home bakers receive pre-portioned frozen dough components with recipe instructions, displacing impulse purchases of fully finished products. This pattern concentrates in coastal cities where delivery density supports frozen last-mile economics and cooking-as-entertainment consumption patterns dominate weekend meal planning.
Pastry Dough Market Segmentation
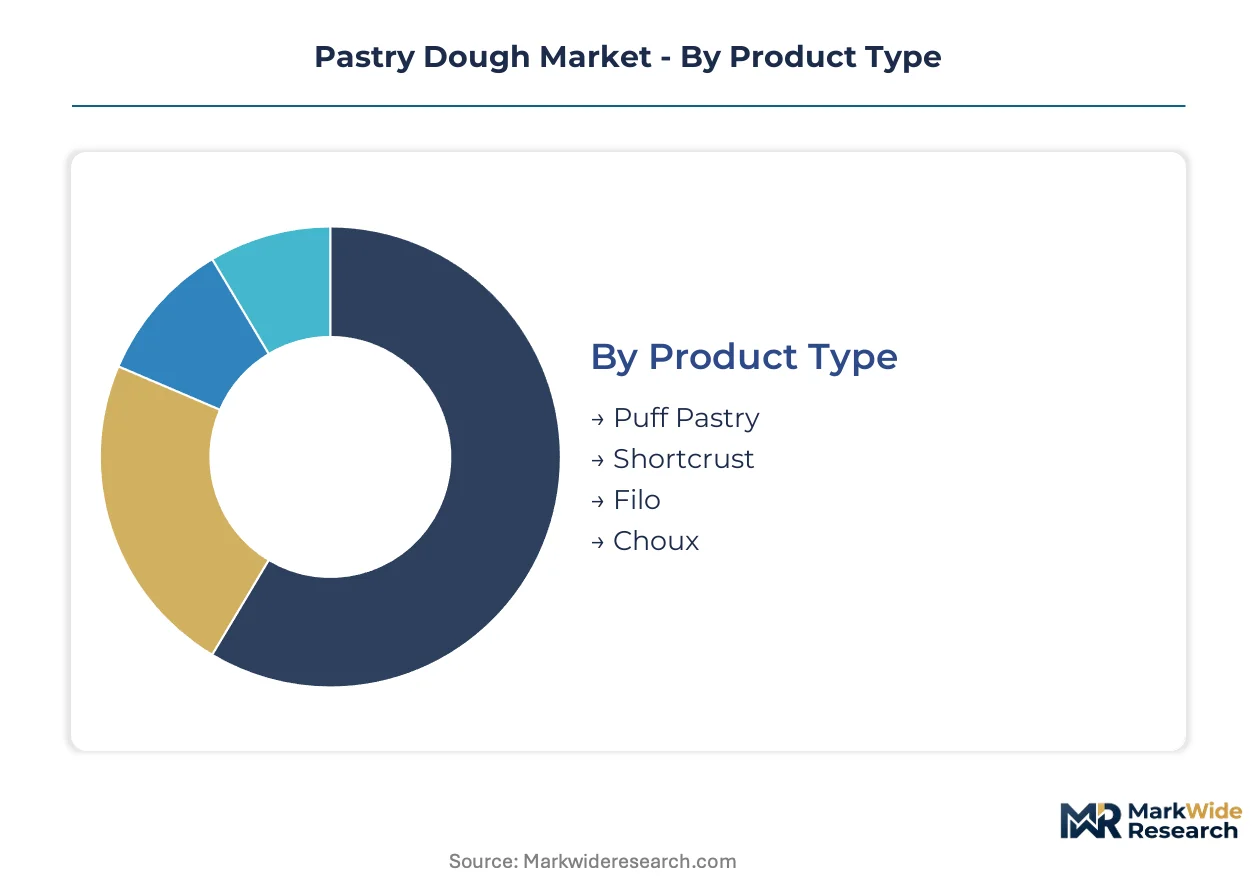
Pastry dough manufacturers configure production lines around specific rheological properties and shelf-life requirements. Segment-specific capital commitments for lamination equipment, cold-chain infrastructure, and packaging automation create divergent margin profiles across the value chain.
Product Type:
Capital intensity peaks in laminated dough categories where precision sheeting equipment and extended retarding capacity dominate facility investment decisions.
- Puff Pastry:Laminated dough with fat content ranging between 50-80% of flour weight, requiring calibrated roll-in and folding sequences to achieve defined layer counts. Quick-service restaurant chains in the United States standardize on frozen puff sheets to eliminate in-house lamination labor. Most installed capacity flows through Puff Pastry. Expansion is steepest in Choux.
- Shortcrust:Fat-in-flour rubbed-in preparation with minimal gluten development, specified for tart shells and pie bases where structural rigidity matters. German retail channels favor pre-formed shortcrust rounds for home baking convenience, driving portion-controlled format innovation.
- Filo:Ultra-thin unleavened sheets demanding specialized stretching equipment and controlled humidity environments during production. Greek and Turkish commercial bakeries maintain captive filo operations due to equipment specificity and skill requirements.
- Choux:High-moisture piped preparation with gelatinized starch structure, requiring precise hydration control and immediate freezing post-extrusion. Japanese patisserie chains source frozen choux puffs for filled dessert applications where volume consistency determines finished product yield.
Equipment utilization rates favor high-volume puff and shortcrust lines. Choux and filo command premium positioning through technical differentiation.
Application:
Margin structures diverge sharply between ambient-stable bakery formats and frozen meal applications where cold-chain reliability creates technical barriers.
- Bakery Products:Bread, viennoiserie, and pastry bases constitute the volume anchor for industrial dough manufacturers. Chinese urban bakery chains source frozen laminated dough for croissant production where consistent layer definition supports premium pricing.
- Confectioneries:Specialized dessert applications including mille-feuille, éclairs, and napoleons demand precise thickness tolerance and fat stability through freeze-thaw cycles. Parisian and Tokyo luxury patisseries specify custom formulations with European butter protection designations.
- Frozen Meals:Savory pie fillings and handheld pastry items require moisture-resistant barriers between dough and filling components. United Kingdom ready-meal manufacturers specify modified starch systems to prevent sogginess during microwave reheating.
- Snacks:Portable pastry items including turnover-style products and stuffed savory pockets target convenience-oriented consumption. South Korean convenience store chains rotate seasonal snack pastry SKUs with compressed development cycles.
Bakery Products absorb the majority of production throughput. Frozen Meals are expanding most quickly as meal-kit platforms aggregate demand.
End User:
Procurement sophistication varies from specification-driven restaurant chains to price-sensitive home baking segments with divergent service requirements.
- Restaurants:Full-service and limited-service operators prioritize consistency and labor reduction over unit cost. Italian and Spanish restaurant groups specify frozen laminated dough for signature desserts where scratch preparation would require dedicated pastry stations.
- Catering Services:Event and institutional foodservice demands volume flexibility with extended holding tolerance. German and Austrian catering cooperatives negotiate seasonal contracts with dough suppliers for wedding and holiday pastry volumes.
- Retail Bakeries:Independent and chain bakeries balance customization requests against production efficiency. French artisan bakeries in Lyon and Bordeaux source frozen croissant blanks for morning rush capacity while maintaining scratch production for signature items.
- Home Bakers:Consumer segments range from convenience-oriented occasional bakers to enthusiast communities seeking professional-grade inputs. Subscription platforms in New York and Los Angeles metropolitan areas deliver pre-portioned frozen dough with recipe integration.
Restaurants concentrate procurement volume. Home Bakers show the steepest demand trajectory through direct-to-consumer channel development.
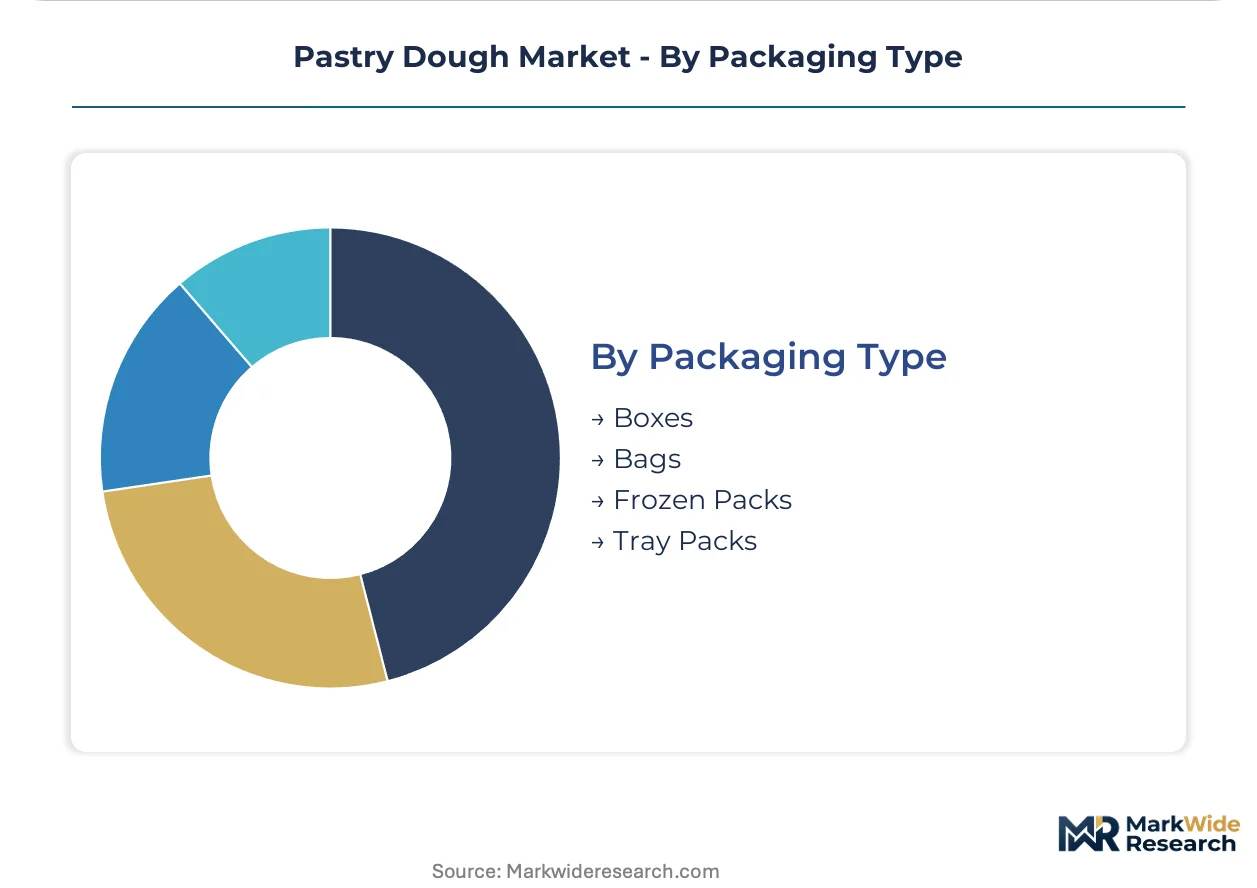
Packaging Type:
Packaging investment priorities align with shelf-life extension requirements and retail display economics across frozen and fresh distribution.
- Boxes:Rigid corrugated or paperboard structures protect fragile laminated products through distribution. Premium positioning in Japanese department store food halls favors windowed boxes showcasing layer definition.
- Bags:Flexible polyethylene or paper laminates suit lower-margin commodity dough formats. French hypermarket private-label shortcrust dominates bagged format volume.
- Frozen Packs:Multi-layer barrier films with modified atmosphere capabilities extend frozen shelf life. EFSA-compliant packaging migration testing requirements constrain film supplier selection for European frozen dough exports.
- Tray Packs:Thermoformed or pressed paperboard trays with lidding film enable portion control and retail-ready presentation. United States club store channels specify tray packs for multi-unit bakery product configurations.
Frozen Packs carry the majority of cold-chain volume. Tray Packs are gaining share fastest in premium retail positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial pastry dough production traces its modern lineage to post-war European bakery mechanization, with laminated dough technologies scaling first in France and Germany before migrating to North American and Asian markets. Frozen dough distribution networks now concentrate capacity in five national markets where cold-chain infrastructure and foodservice density intersect.
United States
Quick-service restaurant chains drive frozen puff pastry consumption as labor constraints eliminate scratch lamination stations. FDA trans-fat labeling requirements and EPA refrigerant rules shape formulation and cold-storage investment decisions. Chicago and Dallas-Fort Worth distribution hubs absorb the majority of frozen dough throughput serving national foodservice networks.
Germany
Retail bakeries and home baking segments sustain demand for portion-controlled shortcrust and croissant blanks. EFSA acrylamide thresholds and EU F-Gas Regulation compliance timelines force clean-label R&D and infrastructure retrofits. The Rhine-Ruhr corridor anchors European frozen dough logistics with multi-temperature zone facilities serving laminated and shortened variants.
China
Urban bakery chains in Shanghai and Beijing source frozen laminated dough for viennoiserie production where consistent layer quality supports premium pricing. SAMR food safety standards and evolving GB standards for frozen bakery products constrain import and domestic manufacturing protocols. Yangtze River Delta manufacturing clusters are expanding retarding and sheeting capacity for regional quick-service restaurant supply.
Japan
Patisserie chains and convenience store networks create specialized demand for frozen choux and precision-thickness filo applications. METI energy efficiency standards and PMDA novel food pathways influence equipment selection and alternative fat ingredient approvals. Tokyo and Osaka metropolitan areas concentrate high-margin confectionery dough procurement through direct supplier relationships.
France
Artisan bakery traditions coexist with industrial frozen croissant blank supply to independent bakers seeking morning rush capacity. ANSM food contact material regulations and EFSA packaging migration testing requirements constrain film supplier selection for frozen exports. Lyon and Bordeaux baking clusters balance scratch production for signature items with frozen inputs for volume consistency.
Pastry Dough Market Competitive Landscape
The competitive structure tilts toward diversified food conglomerates with captive distribution networks and specialized European artisan-industrial hybrids. Three to five multinational operators control the majority of frozen dough volume through manufacturing scale advantages, while mid-tier regional specialists defend positions in premium laminated segments through technical differentiation. Strategic archetypes include scale-driven commodity suppliers, artisan-heritage premium positioners, and vertical bakery-retail integrators. Dominant competitive moves encompass cold-chain infrastructure partnerships and clean-label formulation licensing agreements.
Among North American diversified food manufacturers, General Mills Inc. and Rich Products Corporation exemplify scale-driven archetypes with national frozen distribution footprints. Aryzta AG occupies a position bridging European artisan heritage with industrial throughput capabilities. These three anchors demonstrate how geographic origin and corporate structure map to competitive positioning within frozen and fresh dough segments.
| Leading Market Players |
|---|
| Rich Products Corporation |
| General Mills Inc. |
| Campbell Soup Company |
| Schwan's Consumer Brands, Inc |
| Aryzta AG |
| Grupo Bimbo |
| Ardent Mills LLC |
| Flowers Foods, Inc. |
| Europastry S.A. |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation refrigerant phase-down mandates gate qualified frozen dough supply and premium-tier pricing access by forcing capital-intensive cold-chain retrofits that only scaled operators can absorb. Manufacturers lacking ammonia-CO2 cascade infrastructure face exclusion from European quick-service restaurant procurement panels, while compliant facilities command contract premiums through assured supply continuity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates European butter-designation laminated dough from commodity vegetable-fat formulations and private-label alternatives. Price differentiation rests on clean-label certification status and cold-chain reliability guarantees. Cost compression in the economy tier is intensifying because German and French retailers are consolidating private-label volumes. Quick-service restaurant chains show the least price sensitivity due to labor-cost savings from frozen-to-oven workflows, while independent retail bakeries negotiate aggressively on volume commitments.
Supply Chain Analysis
EFSA packaging migration certification and FDA trans-fat labeling compliance gate supplier qualification before geographic concentration matters. Manufacturing capacity clusters in the United States, Germany, and China where sheeting equipment and retarding infrastructure anchor regional supply. Raw material dependencies center on European butter futures, specialty wheat varieties from Ukraine and Canada, and palm oil alternatives for clean-label reformulation. Single-source vulnerability runs through Rhine-Ruhr cold-chain logistics corridors serving European laminated dough distribution. Distribution runs through captive networks at General Mills and Aryzta AG alongside third-party frozen foodservice distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EFSA novel food approval timelines in Europe lag FDA Generally Recognized As Safe pathways in the United States, creating first-mover windows for plant-based fat innovators.
For Market Incumbents: Cement lamination technician training pipelines and captive cold-chain infrastructure to defend against pressure-fermented automation disruptors. Expand ammonia-CO2 retrofit capacity in German distribution hubs ahead of F-Gas Regulation deadlines. Deepen backward integration into specialty wheat sourcing to buffer against Black Sea supply volatility.
For New Entrants and Emerging Players: Enter via direct-to-foodservice digital platforms in Chinese metropolitan markets where traditional distributor markups remain unchallenged. Target frozen choux and filo segments in Japanese patisserie channels where technical differentiation commands sustainable premiums. Pursue EFSA novel food approval for fermented lipid alternatives as the primary go-to-market credential.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap regional specialists with artisan heritage positioning because buyer consolidation in European retail bakery channels demands scale for procurement access. Five-to-ten-year viability hinges on clean-label R&D amortization across expanded manufacturing footprints. Watch EU F-Gas Regulation enforcement intensity as the inflection signal for stranded asset risk in legacy cold-chain portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Program | EFSA acrylamide threshold compliance opens shelf-space access in German and French retail channels. |
| Cold-Chain Infrastructure Retrofit | Ammonia-CO2 cascade adoption in Rhine-Ruhr hubs secures European frozen dough distribution continuity. |
| Direct-to-Foodservice Platform Launch | Digital ordering portals bypass traditional markups for mid-sized bakery operators in urban China. |
| Artisan-Industrial Capacity Expansion | Pressure-fermented systems in Polish facilities compress production cycles for quick-service restaurant supply. |
| Plant-Based Fat Certification Pathway | EFSA novel food approval unlocks dairy-free premium positioning in European clean-label segments. |
Research Methodology
Multiple input streams — structured interviews with frozen dough plant managers and quick-service restaurant procurement directors, trade data from customs filings and foodservice distribution records, and regulatory documentation from FDA and EFSA dockets — were reconciled through bottom-up manufacturing capacity tallies and top-down demand segmentation validation. Primary fieldwork encompassed technical discussions with sheeting equipment manufacturers and cold-chain logistics operators. Secondary sources included SEC filings from diversified food conglomerates, EU F-Gas Regulation implementation reports, and frozen food industry association statistics.
Historical volume trajectories were cross-referenced against panel input from bakery chain operators to anchor projection assumptions across the analysis window. Segmentation dimensions modeled encompassed product type, application, end-user procurement sophistication, and packaging format alongside regional cold-chain infrastructure maturity. CAGRs were derived from elasticity-adjusted demand curves incorporating clean-label regulatory phase-in schedules and quick-service restaurant automation adoption curves. Forecast inputs centered on European butter price volatility indices and Chinese urban bakery chain expansion rates.
Inputs from EFSA novel food approval databases and SAMR frozen bakery product standard drafts were available through the study window; gaps in real-time cold-chain capacity utilization data introduce uncertainty bands around European distribution growth assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and foodservice labor cost trajectories. A model refresh is warranted upon material change in EU F-Gas Regulation phase-down acceleration or FDA trans-fat labeling enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Personalized Bakery Products Market
Bakery Products
On-The-Go Breakfast Products Market
Bakery Products
Baking Mix, Base and Concentrate Market
Bakery Products
Low Calorie Cake Market
Bakery Products
Global Wafer Biscuits Market
Bakery Products
Organic Frozen Bakery Market
Bakery Products
Low Calorie Flour Market
Bakery Products
Teaseed Cake Market
Bakery Products
Cream Cheese Frosting Market
Bakery Products
Bread Premix Market
Bakery Products
Bakers Yeast Market
Bakery Products
Bakery Fats Market
Bakery Products
Diabetic Bakery Products Market
Bakery Products
Global Bakery Product Market
Bakery Products
Pancakes Market
Bakery Products
Bread and Baked Food Market