
 Middle East and Africa Sweet Biscuits Market | 2026-2036
Middle East and Africa Sweet Biscuits Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Sweet Biscuits Market Insights
Halal certification compliance is bifurcating the competitive landscape into credentialed suppliers and aspirants. Mondelez International Inc leverages its centralized halal audit infrastructure to sustain shelf placement across Gulf retail networks. Britannia Industries Limited anchors its regional position through localized production facilities that navigate import-duty structures effectively.
Sweet biscuits denote flour-based baked products containing added sugars, fats, and leavening agents, typically achieving moisture content below five percent for ambient stability and extended shelf life; these formulations serve as mass-market convenience foods distributed through modern and traditional trade channels. Cookies command the widest manufacturing footprint and deepest consumer recognition, while resealable pouch formats are capturing margin pools through premium positioning and reduced per-gram packaging waste. Health-conscious consumer segmentation is expanding fastest as reformulated recipes with reduced sugar and fortified ingredients gain shelf space in Saudi and UAE supermarkets.
Saudi Food and Drug Authority standards, UAE Ministry of Industry and Advanced Technology technical regulations, and Egypt's National Food Safety Authority protocols collectively govern ingredient sourcing, label claims, and factory inspection cycles across the region. These frameworks elevate compliance costs for new entrants while rewarding established operators with integrated quality systems. Stakeholders must monitor evolving sugar taxation proposals and front-of-pack labeling mandates that could reshape formulation strategies and portfolio prioritization decisions.
Market Dynamics
Halal certification infrastructure is bifurcating competitive access across Gulf retail networks, with credentialed suppliers securing shelf placement while aspirants face audit backlog delays of 8-14 months.
Growth Catalysts
- Modern Retail Penetration:Hypermarket chains in Cairo and Lagos are expanding chilled and ambient biscuit aisles, capturing working-adult traffic seeking grab-and-go breakfast substitutes.
- SFDA Nutritional Disclosure Mandates:Saudi Arabia's front-of-pack labeling requirements are accelerating reformulation investments among established manufacturers, creating first-mover advantages in reduced-sugar segments.
- Localized Production Incentives:Egypt's industrial zones offer duty-drawback schemes for wheat-flour imports, lowering effective input costs for biscuit manufacturers serving North African export corridors.
Market Restraints
- Wheat Price Volatility:Black Sea supply disruptions transmit directly to Egyptian and Nigerian milling costs, compressing gross margins for non-integrated producers.
- Halal Audit Concentration:Only three accredited certification bodies serve the entire GCC, creating bottlenecks for new product launches and line extensions.
- Palm Oil Substitution Pressure:Bakery manufacturers face reformulation complexity as EU deforestation regulations disrupt traditional Malaysian and Indonesian supply channels.
Strategic Opportunities
- Ethiopia Distribution Gap:Underdeveloped modern trade infrastructure in Addis Ababa creates first-mover potential for ambient biscuit brands establishing direct-store-delivery networks.
- Fortification Mandates:Nigeria's national food fortification alliance incentivizes vitamin-A and iron-enriched formulations, opening premium positioning for compliant manufacturers.
- E-Commerce Convergence:Quick-commerce platforms like Talabat and Jumia Food are merging impulse-snack purchasing with delivery logistics, enabling single-serve pouch trials.
Industry Challenges
- Halal Technical Competency Gap:Shortage of auditors trained in enzymatic ingredient verification extends certification timelines and raises compliance consulting fees.
- Legacy Equipment Retrofit Costs:Transitioning to allergen-segregated production lines requires capital outlays that strain mid-tier manufacturers' balance sheets.
- MOHAP Label Harmonization:Divergent UAE emirate-level enforcement of nutritional claim thresholds creates compliance fragmentation for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Sweet Biscuits Market |
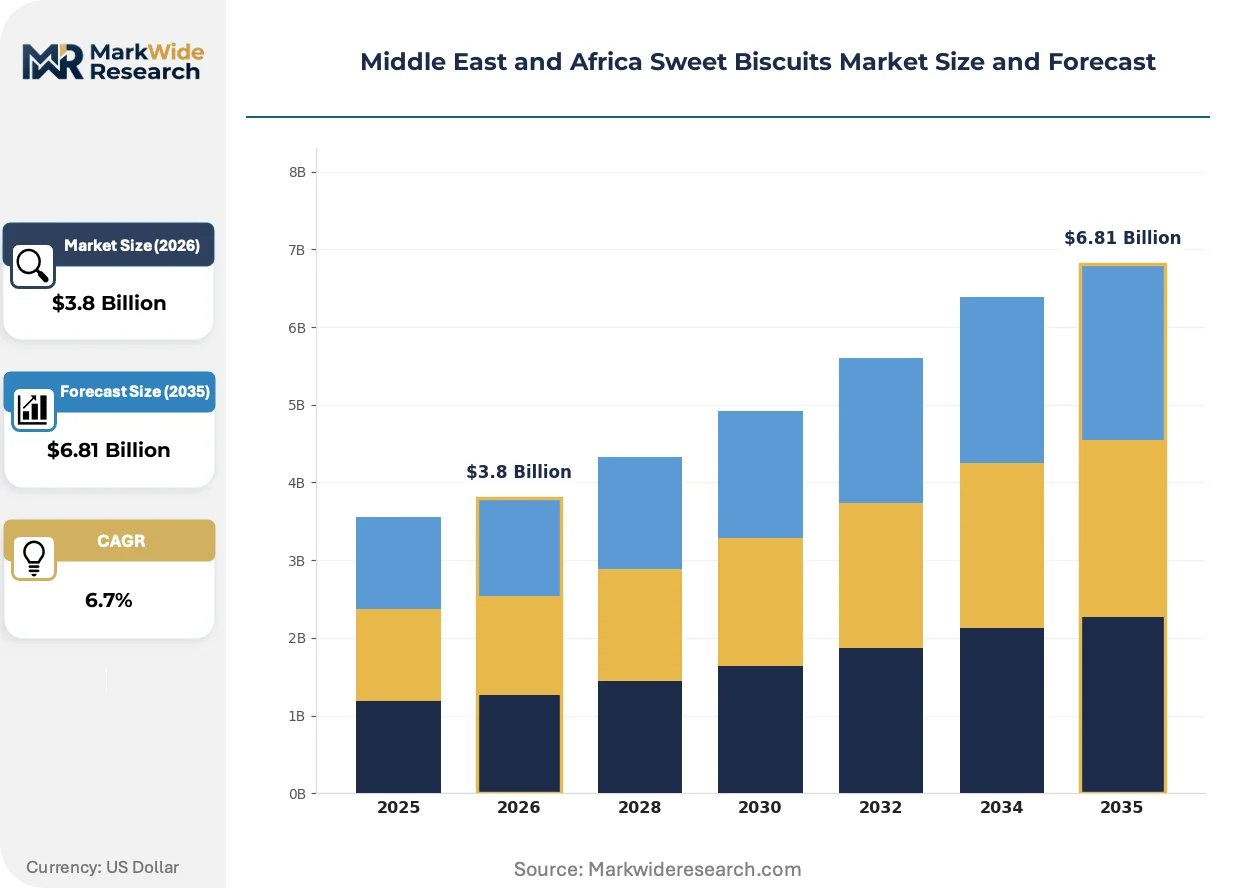
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cookies, Cream Biscuits, Wafer Biscuits, Digestive Biscuits Packaging Type: Box, Plastic Wrap, Bag, Resealable Pouch Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Stores Customer Type: Children, Adults, Health-conscious Consumers, Occasional Buyers |
| Companies Covered | Tiffany Foods Ltd, Mondelez International Inc, Britannia Industries Limited, Al Yanbou, ITC Limited, Gandour, Yildiz Holding Inc, Gulf Confectionery & Biscuit Co LLC, Deemah United Food Industries Corp Ltd, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Sweet Biscuits Market Trends and Innovations
Reformulation science and packaging automation are compressing product development cycles while regulatory disclosure requirements reshape portfolio prioritization across the Middle East and Africa.
Modified starch and soluble fiber blends are displacing traditional sugar-fat structures in premium biscuit formulations. Saudi and UAE health-conscious consumers are adopting these reformulated lines at rates outpacing conventional variants. This ingredient technology is miniaturizing batch-scale testing, allowing regional manufacturers to validate sensory profiles before committing to full production runs.
SFDA's 2024 technical regulations on front-of-pack nutritional labeling are mandating traffic-light color coding for sugar, salt, and fat content. Industrial consequence includes accelerated R&D spending on clean-label recipes that achieve green-tier ratings without sacrificing shelf stability. Premium supermarket chains in Riyadh and Jeddah are responding by dedicating expanded facing to compliant SKUs, marginalizing legacy formulations.
Working adults across Gulf urban centers are consolidating snacking occasions into single convenience purchases rather than planned grocery trips. Quick-commerce and petrol-station convenience formats are displacing traditional grocery stocking patterns as the primary trial channel. This behavioral compression is most visible in Dubai and Abu Dhabi, where 24-hour delivery apps now capture 30-40% of impulse biscuit purchases.
Middle East and Africa Sweet Biscuits Market Segmentation
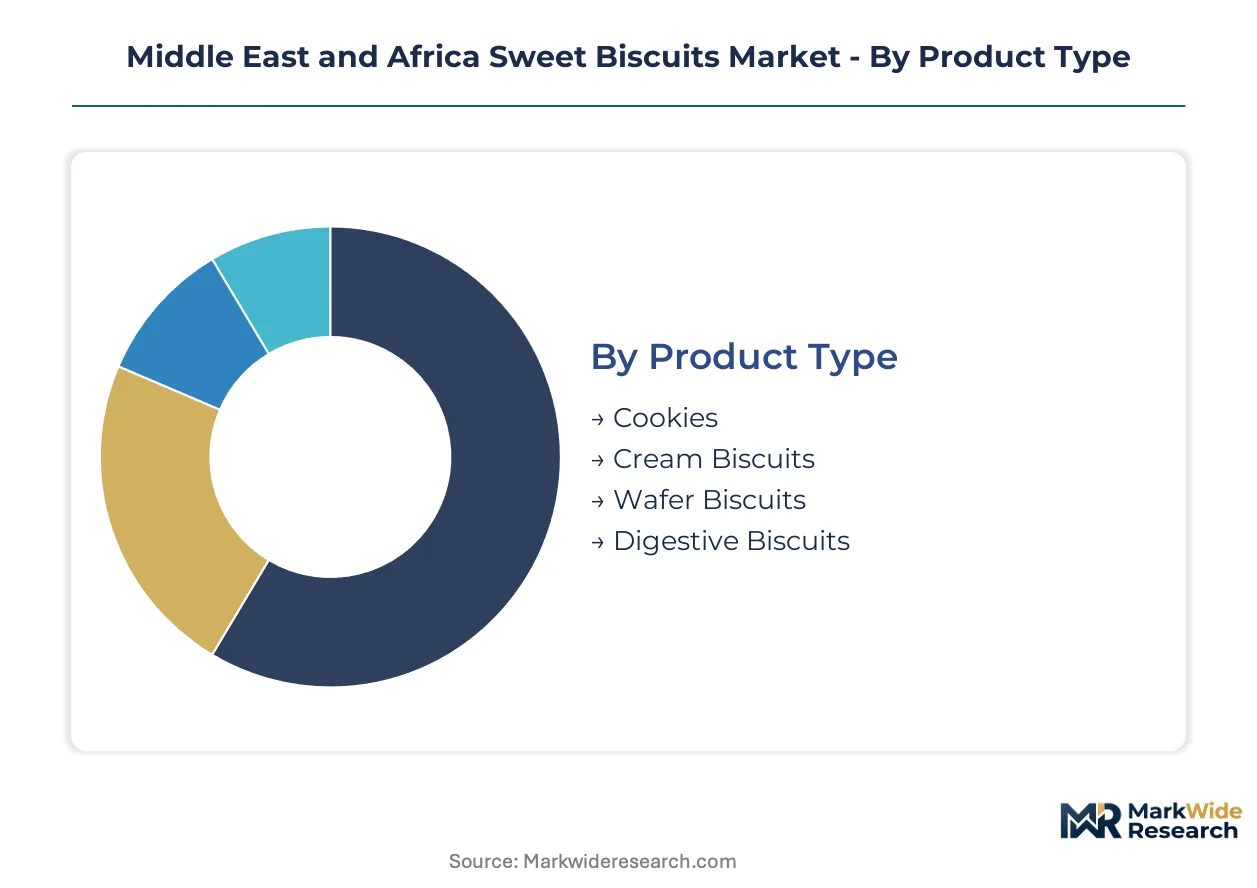
Sweet biscuits fragment across four structural dimensions that determine margin capture and shelf placement. Product type governs manufacturing capital intensity, while packaging and channel choices increasingly separate premium positioning from commodity volume plays.
Product Type:
Substitution pressure from savory snacks and confectionery varies sharply across flour-based formats, with some segments facing acute displacement risk from protein bars and chocolate assortments.
- Cookies:Dense, flour-based formulations with elevated fat and sugar content achieve ambient stability through low moisture baking. Demand concentrates in Saudi Arabia and UAE hypermarkets where grab-and-go breakfast substitution drives repeat purchase frequency.
- Cream Biscuits:Sandwich constructions with fat-based fillings require controlled humidity packaging to prevent moisture migration. Nigerian and Egyptian working adults favor these for midday energy replenishment, though sugar taxation proposals threaten margin structures.
- Wafer Biscuits:Layered, low-density products with crisp texture profile serve gift-giving occasions in Gulf markets. SFDA labeling mandates are accelerating reformulation toward reduced-sugar variants.
- Digestive Biscuits:Whole-grain formulations with higher fiber content target health-positioned snacking. UAE and Saudi health-conscious consumers are migrating toward these as breakfast alternatives.
Cookies retain volume leadership; cream biscuits hold the steepest expansion curve.
Packaging Type:
Cost tier stratification in packaging materials directly maps to retail channel access and per-gram economics across modern and traditional trade.
- Resealable Pouch:Multi-layer barrier films with zipper closures extend shelf life while enabling portion control. Premium supermarket chains in Dubai and Riyadh dedicate expanded facing to these SKUs.
- Box:Rigid paperboard with printed graphics serves gift and seasonal segments. Egyptian and Nigerian urban centers show concentration for family-size formats.
- Plastic Wrap:Single-serve flow-wrapped units dominate petrol-station and convenience store channels. Quick-commerce platforms favor these for impulse-basket economics.
- Bag:Basic polyethylene formats serve price-sensitive traditional trade in Ethiopia and secondary Nigerian cities. Wheat price volatility compresses margins for this tier.
Resealable pouch commands premium positioning; box formats maintain seasonal peak concentration.
Distribution Channel:
Customer type fragmentation—impulse versus planned purchase—determines which channels capture trial versus loyalty economics.
- Supermarkets:Chilled and ambient aisle expansion in Cairo and Lagos captures working-adult traffic seeking breakfast substitutes. SFDA and MOHAP labeling mandates reshape shelf allocation.
- Online Retailers:Quick-commerce platforms like Talabat and Jumia Food merge impulse purchasing with delivery logistics. Single-serve pouch trials dominate this channel.
- Convenience Stores:24-hour petrol-station formats in Dubai and Abu Dhabi capture 30-40% of impulse biscuit purchases. Resealable pouches and flow-wrapped units predominate.
- Specialty Stores:Health-focused retailers in Saudi Arabia and UAE stock fortified and reduced-sugar variants. Clean-label recipes achieve green-tier traffic-light ratings here.
Supermarkets retain volume leadership; online retailers are climbing the fastest.
Customer Type:
Volume concentration and margin potential diverge across demographic segments with distinct occasion patterns and price sensitivity profiles.
- Health-conscious Consumers:Reformulated recipes with reduced sugar and fortified ingredients gain shelf space. Saudi and UAE supermarkets show fastest uptake for clean-label variants.
- Adults:Working professionals in Gulf urban centers consolidate snacking into single convenience purchases. Quick-commerce and petrol-station formats serve this segment.
- Children:Sweetness-forward formulations with character licensing dominate Egyptian and Nigerian family purchases. Price sensitivity constrains premium migration.
- Occasional Buyers:Seasonal and gift-driven demand concentrates in wafer and cookie segments. Box packaging and specialty store placement target this group.
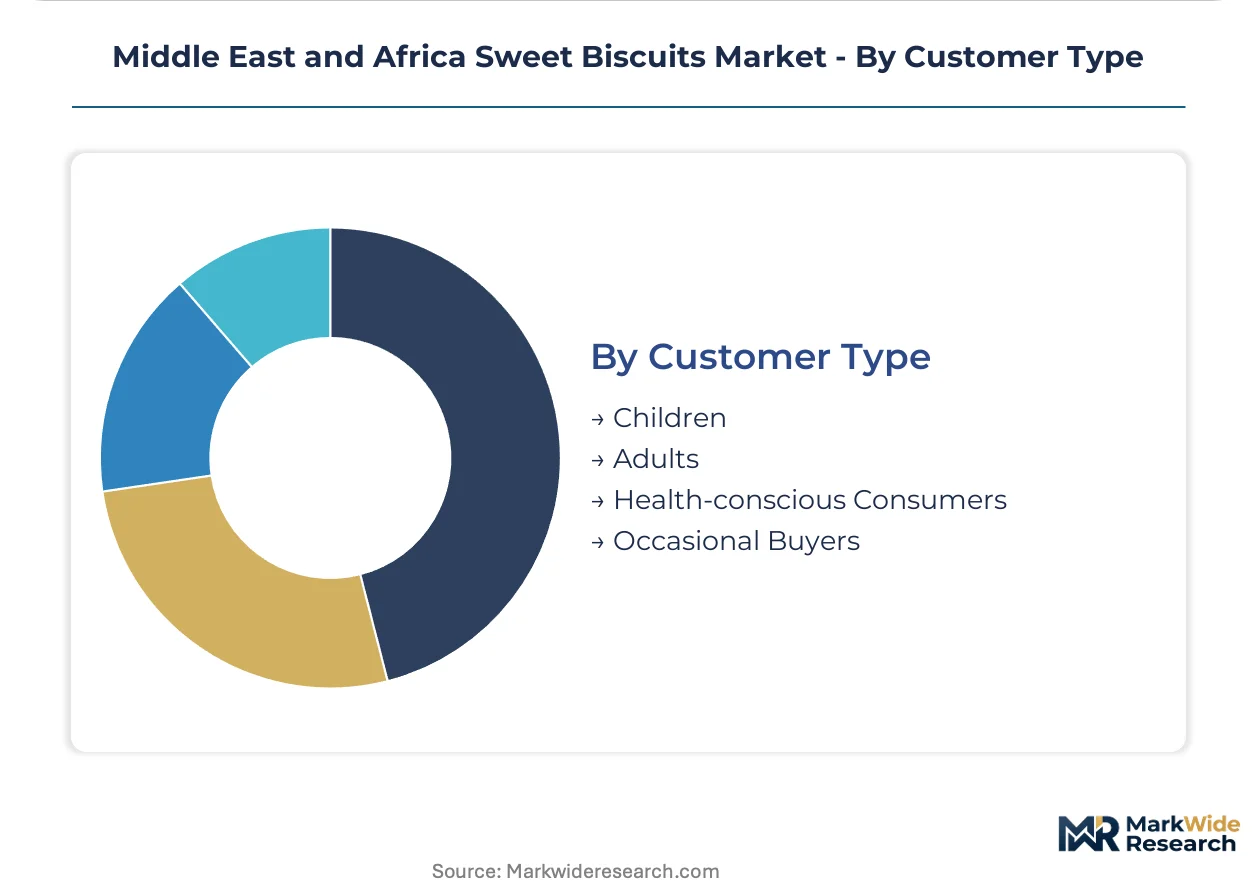
Adults retain volume leadership; health-conscious consumers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Duty-drawback schemes for wheat-flour imports are reshaping manufacturing economics across North African industrial zones. SFDA labeling mandates and MOHAP technical regulations are creating compliance gradients that favor established operators with integrated quality systems.
Saudi Arabia
Hypermarket chains in Riyadh and Jeddah are expanding ambient biscuit aisles to capture working-adult breakfast substitution demand. SFDA front-of-pack labeling requirements mandate traffic-light color coding for sugar, salt, and fat content. Industrial clusters in Jeddah and Dammam host reformulation facilities serving Gulf export corridors.
UAE
Quick-commerce platforms in Dubai and Abu Dhabi now capture 30-40% of impulse biscuit purchases through 24-hour delivery apps. MOHAP label harmonization efforts face divergent emirate-level enforcement of nutritional claim thresholds. Petrol-station convenience formats in Dubai anchor single-serve pouch distribution for grab-and-go snacking.
Egypt
Population density in Cairo and Alexandria supports volume uptake through evolving grocery infrastructure and traditional trade networks. The National Food Safety Authority governs ingredient sourcing and factory inspection cycles with protocols that elevate compliance costs for new entrants. Industrial zones offering wheat import duty drawbacks concentrate manufacturing capacity in Greater Cairo.
Nigeria
The national food fortification alliance incentivizes vitamin-A and iron-enriched formulations, opening premium positioning for compliant manufacturers. Wheat price volatility from Black Sea supply disruptions transmits directly to domestic milling costs. Lagos anchors modern retail penetration with hypermarket chains capturing working-adult traffic seeking convenience foods.
Ethiopia
Underdeveloped modern trade infrastructure in Addis Ababa creates first-mover potential for ambient biscuit brands establishing direct-store-delivery networks. Traditional polyethylene bag formats serve price-sensitive distribution in secondary cities. Addis Ababa's emerging urban retail corridors present untapped shelf space for resealable pouch introductions.
Middle East and Africa Sweet Biscuits Market Competitive Landscape
Listed leaders compete with private specialists across halal certification infrastructure and localized production capacity. The vendor base clusters around three tiers: multinational CPG conglomerates with centralized audit systems, regional manufacturers with duty-optimized production footprints, and domestic specialists serving traditional trade channels. Strategic archetypes include credentialed halal suppliers securing Gulf retail placement, import-duty navigators with Egyptian or Nigerian manufacturing assets, and quick-commerce enablers optimizing single-serve pouch economics. Dominant competitive moves encompass M&A to acquire halal certification capabilities and capacity expansion into industrial zones offering input cost subsidies.
Within the multinational tier, Mondelez International Inc and Britannia Industries Limited exemplify divergent approaches to regional positioning. Mondelez leverages centralized halal audit infrastructure to sustain shelf placement across Gulf retail networks. Britannia anchors its position through localized production facilities that navigate import-duty structures effectively. Among Middle East-based specialists, Gulf Confectionery & Biscuit Co LLC and Deemah United Food Industries Corp Ltd occupy positions shaped by proximity to Saudi and UAE regulatory frameworks. Yildiz Holding Inc represents Turkish-origin manufacturing groups extending distribution into North African corridors.
| Leading Market Players |
|---|
| Tiffany Foods Ltd |
| Mondelez International Inc |
| Britannia Industries Limited |
| Al Yanbou |
| ITC Limited |
| Gandour |
| Yildiz Holding Inc |
| Gulf Confectionery & Biscuit Co LLC |
| Deemah United Food Industries Corp Ltd |
| Others |
Pricing and Supply Chain Analysis
Modified starch and soluble fiber blends displacing traditional sugar-fat structures simultaneously redraw sourcing geography toward Gulf chemical clusters and compress formulation premiums for legacy biscuit recipes. This substitution dynamic funnels pricing power toward suppliers with integrated reformulation capabilities while margin pressure accumulates for commodity flour-based producers.
Pricing Analysis
Certification level (halal audit tier) creates the primary spread between premium resealable pouches and economy polyethylene bags. Three-tier pricing structure across premium, standard, and economy levels anchors on SFDA green-tier traffic-light ratings, brand heritage, and volume scale. Price erosion runs through bag-format segments as wheat price volatility transmits directly from Black Sea disruptions to Egyptian and Nigerian milling costs. Traditional trade buyers in Ethiopia and secondary Nigerian cities exhibit highest price sensitivity; health-conscious consumers in Riyadh and Dubai show lowest.
Supply Chain Analysis
Strait of Hormuz transit underwrites palm oil and modified starch flows to Saudi and UAE reformulation facilities. Supply concentrates in Malaysia and Indonesia for palm derivatives, India for wheat flour when Black Sea routes constrict, and Egypt for duty-optimized North African production. Wheat, palm oil, and dairy powder feedstock dependencies expose manufacturers to EU deforestation regulation compliance costs and Black Sea supply disruptions. Distribution runs through hypermarket chains in Cairo and Lagos, quick-commerce platforms in Dubai, and direct-store-delivery networks in Addis Ababa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reformulation services and halal certification consulting layers expand faster than base biscuit production, creating attach-rate opportunities for technical-service providers. Recurring audit contracts and clean-label recipe development fees outpace commodity volume growth across the Gulf.
For Market Incumbents: Compound shelf placement advantages through accelerated halal certification for line extensions, closing the 8-14 month audit backlog gap that threatens aspirant competitors. Deepen backward integration into Egyptian industrial zones capturing wheat import duty drawbacks. Channel control through quick-commerce exclusivity agreements with Talabat and Jumia Food defends against private-label encroachment in impulse segments.
For New Entrants and Emerging Players: Lead with direct-store-delivery networks in Addis Ababa's underdeveloped modern trade corridors, establishing first-mover shelf space before hypermarket chains consolidate. Target health-conscious segmentation in Saudi and UAE specialty stores where clean-label green-tier SKUs command premium positioning. Single-serve pouch trials through petrol-station convenience formats anchor lowest-friction customer acquisition.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional manufacturers possessing Egyptian duty-optimized production footprints but lacking Gulf halal certification infrastructure. Five-to-ten year viability hinges on reformulation capability depth and regulatory compliance integration rather than commodity scale alone. Monitor SFDA sugar taxation proposals as inflection signal for portfolio prioritization toward reduced-sugar variants.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Acquisition | Mondelez's centralized audit infrastructure sustains shelf placement across Saudi and UAE retail networks. |
| Localized Production Expansion | Britannia's Egyptian facilities navigate import-duty structures that strain non-integrated competitors. |
| Reformulation R&D Investment | Clean-label recipes achieving SFDA green-tier ratings capture expanded facing in Riyadh hypermarkets. |
| Quick-Commerce Partnership | Talabat and Jumia Food integration captures 30-40% of impulse biscuit purchases in Dubai and Abu Dhabi. |
| Fortification Compliance Program | Nigeria's national food fortification alliance opens premium positioning for vitamin-A enriched formulations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SFDA technical regulations, MOHAP labeling mandates, and Egypt's National Food Safety Authority protocols. Interviews with biscuit category managers at Saudi and UAE hypermarket chains, halal certification auditors at GCC-accredited bodies, and supply planners at Egyptian industrial zone manufacturers inform demand and compliance assessments. Secondary sources include customs records tracking wheat flour import flows, Nielsen retail audit data for Cairo and Lagos, and quick-commerce platform transaction disclosures. Bottom-up volume builds triangulate against top-down macroeconomic consumption models.
Segmentation dimensions modeled span product type (cookies, cream biscuits, wafers, digestives), packaging format (resealable pouch, box, plastic wrap, bag), distribution channel (supermarkets, online retailers, convenience stores, specialty stores), and customer archetype (health-conscious, working adults, children, occasional buyers). CAGRs derive from regression analysis of historical consumption patterns against urbanization rates, modern retail penetration curves, and regulatory implementation timelines. Wheat price volatility indices and halal certification queue lengths feed industry-specific forecast adjustments across the projection horizon.
The analysis sits within stated boundaries; outcomes outside sustained Gulf urbanization, stable Egyptian duty-drawback schemes, or unaltered SFDA labeling timelines would require recalibration. Forecasts reflect assumptions around Black Sea wheat supply normalization and GCC halal auditor capacity expansion. Practitioners should keep alternative scenarios live as sugar taxation proposals and EU deforestation regulation enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Frozen Bakery Products Market
Bakery Products
Pastries Market
Bakery Products
GCC Frozen Bakery Products Market
Bakery Products
Premixed Bread Flour Market
Bakery Products
Baking Mixes Market
Bakery Products
North America Fortified Bakery Products Market
Bakery Products
Bread and Baked Food Market
Bakery Products
Asia-Pacific Bakery Products Market
Bakery Products
Bakery Fillings Market
Bakery Products
South America Ice Cream Market
Bakery Products
Oman Frozen Bakery Products Market
Bakery Products
United States Cookies Market
Bakery Products
Instant Cake Gel Market
Bakery Products
North America Bakery Products Market
Bakery Products
Biscuits Market
Bakery Products
Wedding Cakes Market