
 UAE Breakfast Cereals Market | 2026-2036
UAE Breakfast Cereals Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Breakfast Cereals Market Analytics
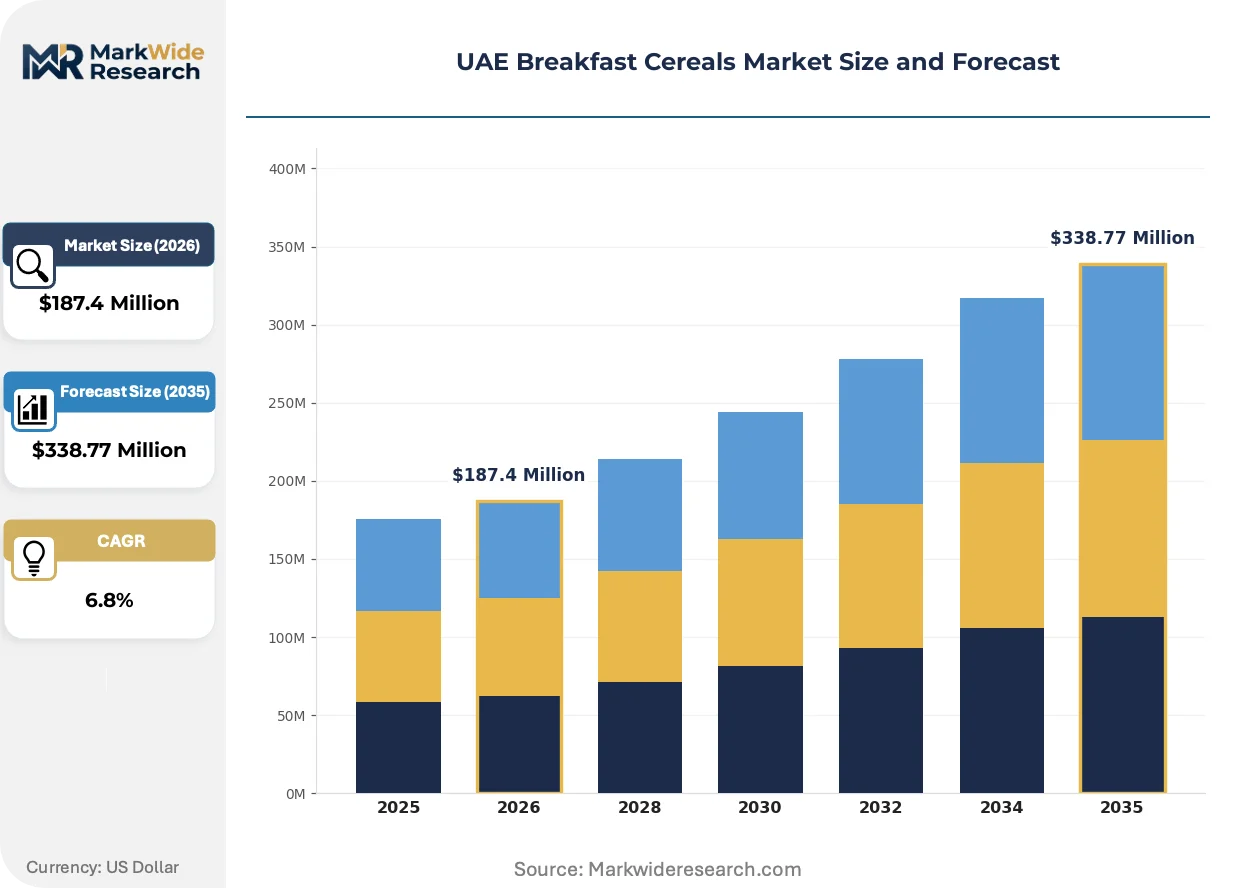
Halal certification compliance is redrawing competitive boundaries in the UAE breakfast cereals sector. Nestlé S.A. leverages its regional manufacturing footprint to secure streamlined Halal approvals across Gulf markets. The Kellogg's Company sustains brand recognition through dedicated Arabic-language packaging and localized flavor development. Associated British Foods PLC competes via its Twinings and Jordans portfolios, emphasizing whole-grain credentials in premium retail placements.
Breakfast cereals comprise processed grain formulations—typically wheat, oats, rice, or corn—flaked, puffed, or extruded into ready-to-eat products, often fortified with vitamins, minerals, and protein isolates to meet nutritional benchmarks. These formulations serve commercial and household consumers seeking shelf-stable, portion-controlled morning meal solutions with minimal preparation time. Flakes and granola lead volume shipments due to established palatability and extended shelf stability in the UAE's climate-controlled retail infrastructure. The health-conscious consumer segment commands premium pricing, while oatmeal gains traction among athletes requiring sustained-release carbohydrate profiles.
MOHAP enforces sugar-content thresholds and front-of-pack labeling mandates that compel manufacturers to reformulate recipes or risk distribution restrictions. The UAE's PLI-aligned food manufacturing incentives and ESMA nutritional standards further tighten compliance requirements for imported and domestically produced cereals. Stakeholders must monitor evolving Halal certification protocols and sugar-reduction timelines to preserve shelf access and consumer trust.
Market Dynamics
MOHAP's sugar disclosure mandates and Halal certification protocols are compressing formulation timelines and redrawing shelf-access rules for breakfast cereal suppliers across Dubai and Abu Dhabi retail networks.
Growth Catalysts
- Protein fortification technology:Extrusion processes now integrate whey and plant isolates at scale, meeting athlete demand for sustained-release carbohydrate profiles in Abu Dhabi's fitness clusters.
- ESMA nutritional standards:The Emirates Authority for Standardization and Metrology enforces micronutrient benchmarks that validate premium positioning for imported and domestic brands alike.
- Dubai's urban professional density:Concentrated white-collar employment in Business Bay and DIFC generates consistent demand for portion-controlled, shelf-stable morning solutions.
Market Restraints
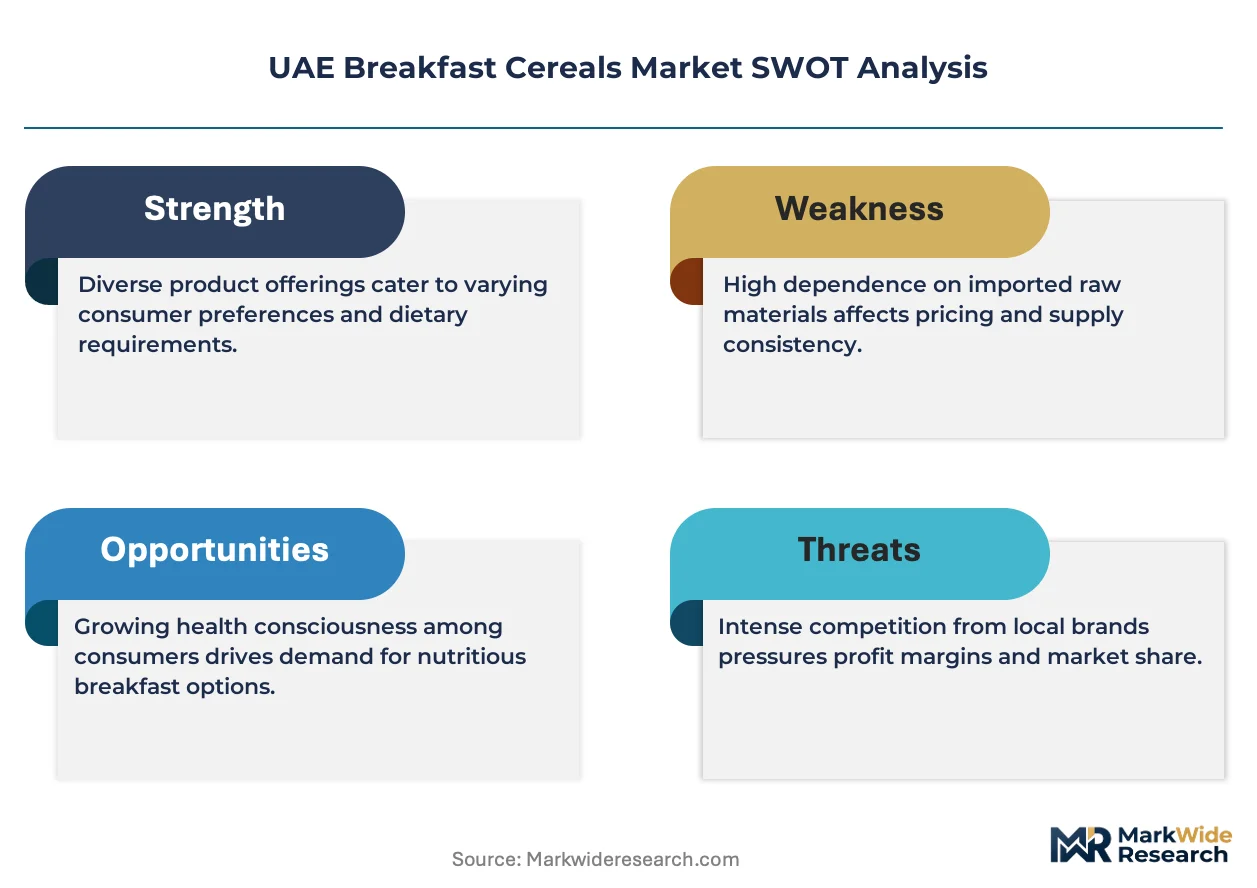
- Wheat import dependency:The UAE sources over 90% of milling wheat from Black Sea and Australian suppliers, exposing margins to freight volatility and currency swings.
- Climate-controlled logistics cost:Extended shelf stability requires refrigerated transport through the Gulf's summer peaks, elevating last-mile expenditure versus European benchmarks.
- Reformulation compliance burden:MOHAP's front-of-pack labeling mandates force recipe overhauls that consume 12-18 month development cycles.
Strategic Opportunities
- Sharjah and Northern Emirates penetration:Retail cereal density in Ajman, Fujairah, and Ras Al Khaimah lags Dubai by 40%, offering whitespace for distribution expansion.
- E-commerce subscription models:Direct-to-consumer platforms bypass hypermarket slotting fees while capturing recurring revenue from expatriate households.
- PLI-aligned manufacturing incentives:The UAE's Production-Linked Incentive scheme subsidizes domestic extrusion and packaging capacity, reducing import reliance.
Industry Challenges
- Halal certification timeline compression:Gulf-standard approvals now require 8-14 months, delaying new product launches and seasonal range refreshes.
- Refrigerated warehousing capex:Ambient storage inadequacy for fortified cereals forces investment in temperature-controlled distribution centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Breakfast Cereals Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flakes, Granola, Muesli, Oatmeal Distribution Channel: Supermarkets, Online Stores, Convenience Stores, Health Shops End User: Children, Adults, Athletes, Health-conscious Consumers Price Tier: Premium, Mid-range, Economical, Organic |
| Companies Covered | General Mills Inc., Associated British Foods PLC, Bobs Red Mill, Bio Familia AG, The Weetabix Food Company, Nestlé S.A., The Kellogg's Company, Ecotone (Whole Earth), PepsiCo Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Breakfast Cereals Market Evolving Landscape
Three forces are restructuring the UAE breakfast cereals sector: precision fortification systems, regulatory transparency mandates, and channel migration toward digital fulfillment.
Extrusion-based micro-encapsulation is miniaturizing vitamin and mineral delivery systems within cereal matrices, enabling heat-stable nutrient retention through Dubai's summer supply chains. Adult professionals seeking convenient nutrition now specify these fortified formats in employer-subsidized cafeteria contracts. The technology compresses the gap between pharmaceutical-grade supplementation and mass-market breakfast pricing.
MOHAP's updated food labeling requirements for sugar content disclosure are forcing reformulation investments across imported and domestic portfolios. Manufacturers must now retest recipes through accredited UAE laboratories before shelf placement approval. High-sugar legacy brands face distribution restrictions in government-affiliated retail channels, accelerating portfolio rationalization.
Digital grocery platforms are capturing an expanding share of UAE cereal purchases, disintermediating traditional hypermarket dominance. Quick-commerce operators promise 30-minute delivery windows that match the convenience positioning of ready-to-eat formats. This channel shift concentrates most visibly in Dubai Marina and Jumeirah Lakes Towers, where dual-income households prioritize time savings over in-store browsing.
UAE Breakfast Cereals Market Segmentation
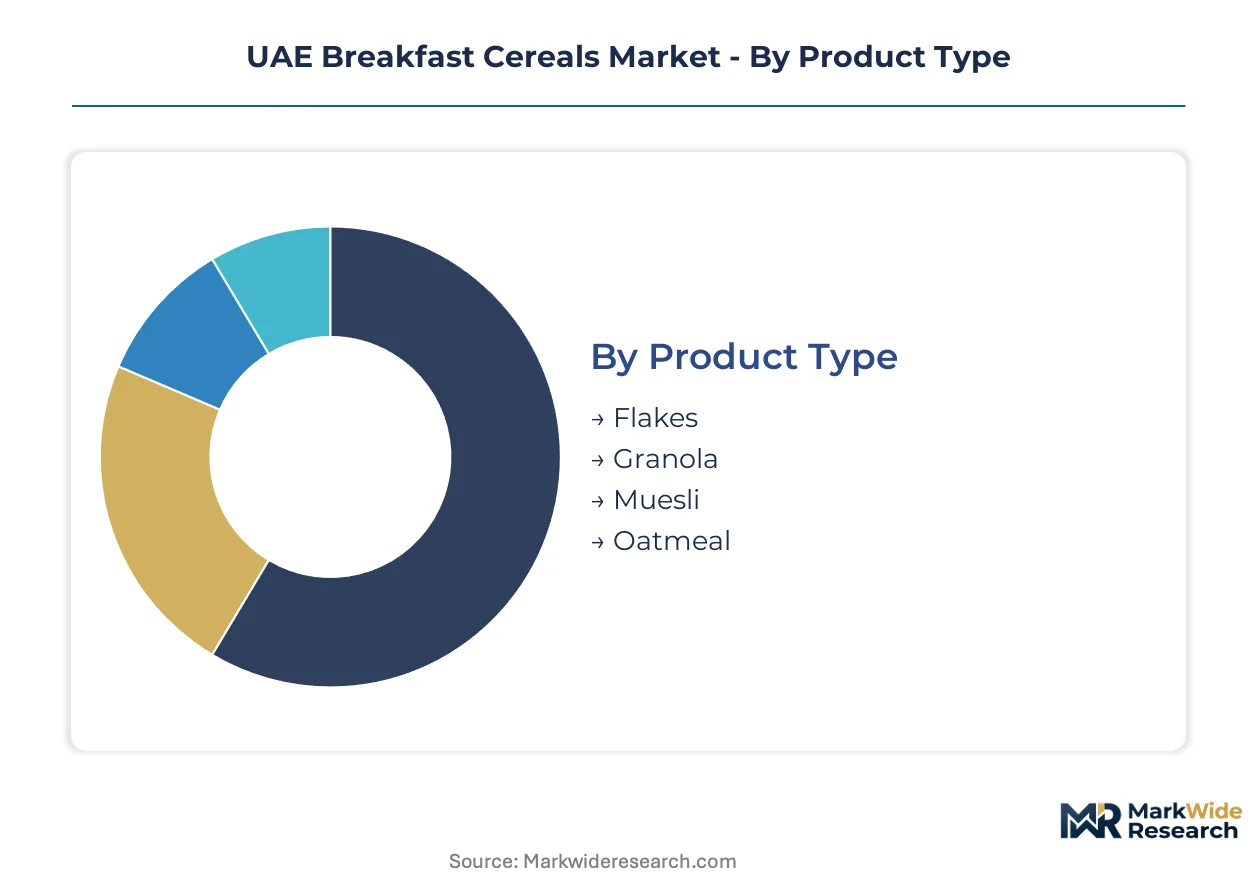
Segmentation in the UAE breakfast cereals market reveals distinct margin architectures across product formats and channel strategies. Understanding where value concentrates helps suppliers align reformulation investments with purchasing power clusters in Dubai and Abu Dhabi.
Product Type:
Margin pools concentrate in formats that withstand Dubai's summer logistics while commanding shelf-space premiums.
- Flakes:Extruded wheat and corn matrices dominate production volumes due to established palatability and heat-stable fortification compatibility. Demand clusters in Business Bay employer-subsidized cafeterias where portion-controlled single-serve packs reduce waste.
- Granola:Baked oat clusters with honey or date syrup binding attract premium positioning through whole-grain credentials and local ingredient sourcing. Abu Dhabi's health-conscious professionals in Al Reem Island drive recurring purchases of low-sugar variants.
- Muesli:Raw oat blends with dried fruit and nut inclusions serve European expatriate preferences in Jumeirah and Arabian Ranches communities.
- Oatmeal:Steel-cut and rolled formats gain traction among athletes requiring sustained-release carbohydrate profiles for training regimens.
The dominant share belongs to Flakes, while Granola is closing the gap fastest.
Distribution Channel:
Channel selection determines compliance burden and working capital intensity for cereal suppliers entering the UAE market.
- Supermarkets:Hypermarket chains in Dubai Mall and Yas Mall anchor volume shipments through promotional slotting fees and seasonal display allocations. Lulu Hypermarket and Carrefour UAE enforce MOHAP labeling audits before listing approval.
- Online Stores:Quick-commerce platforms promise 30-minute delivery windows in Dubai Marina and Jumeirah Lakes Towers, capturing dual-income households prioritizing convenience over in-store browsing.
- Convenience Stores:Smaller format retail in petrol stations and residential lobbies serves impulse purchases and emergency replenishment.
- Health Shops:Specialty retailers in Dubai's Kite Beach district curate protein-fortified and organic SKUs for fitness-oriented consumers.
Supermarkets still capture the largest transaction volumes, though Online Stores are expanding most quickly.
End User:
User-based segmentation exposes divergent price elasticities and nutritional specification requirements across demographic cohorts.
- Children:Sugar-reduced formulations with vitamin fortification face MOHAP distribution restrictions in government-affiliated retail channels, forcing portfolio rationalization.
- Adults:Working professionals in DIFC and Abu Dhabi Global Market generate consistent demand for single-serve, shelf-stable morning solutions with minimal preparation time.
- Athletes:CrossFit and endurance training communities specify whey-isolate-fortified cereals with precise macronutrient ratios.
- Health-conscious Consumers:High-fiber and protein-fortified variants command premium pricing in Dubai's wellness-focused retail environments.
Adults represent the largest addressable base, while Athletes show the steepest expansion trajectory.
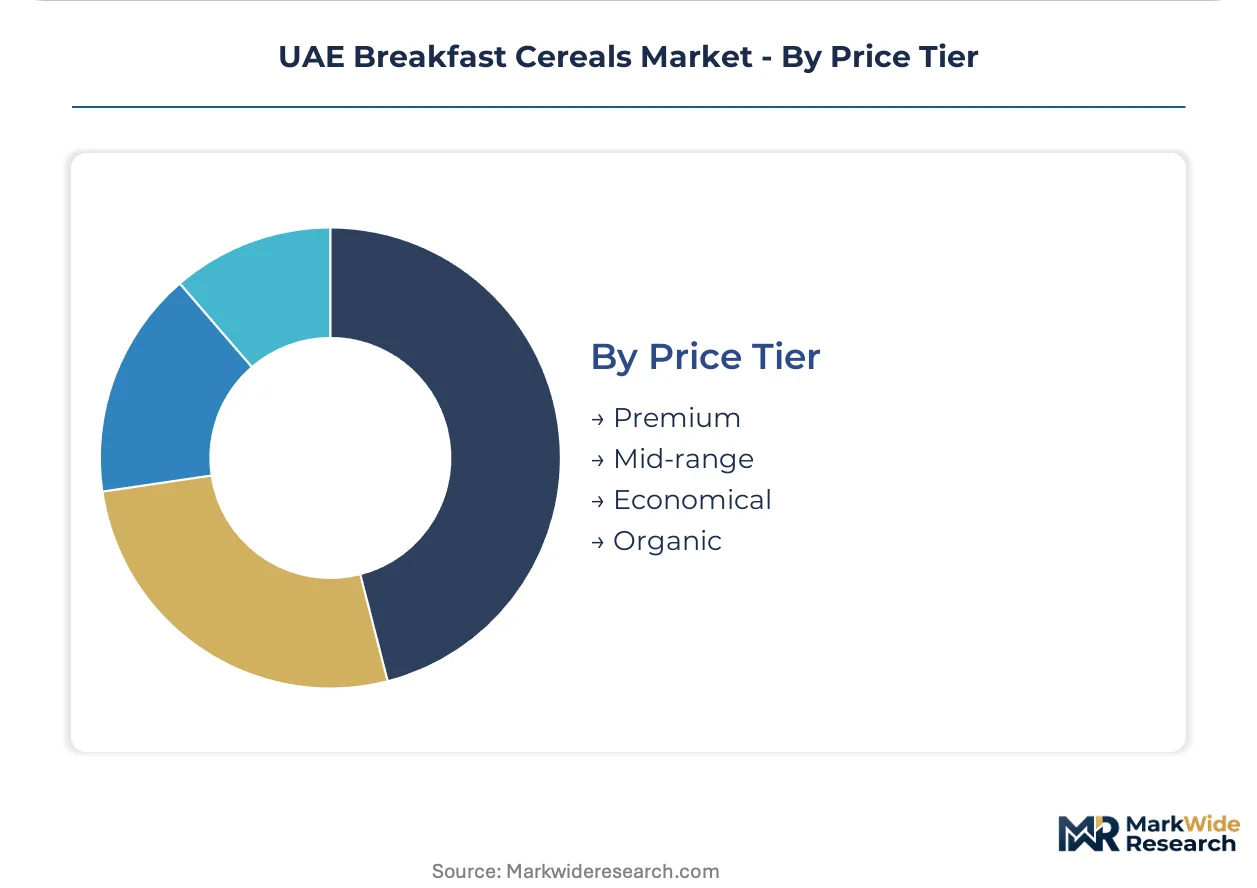
Price Tier:
Pricing architecture reflects certification costs and ingredient sourcing geography rather than manufacturing scale alone.
- Premium:Imported European brands with ESMA-validated micronutrient benchmarks occupy eye-level shelf positions in Waitrose UAE and Spinneys Dubai.
- Mid-range:Regional manufacturers leverage PLI-aligned subsidies to compete on reformulated sugar-reduced recipes.
- Economical:Private-label offerings from supermarket chains capture price-sensitive South Asian expatriate households in Deira and Sharjah.
- Organic:Certified organic oats and ancient grains serve niche demand in Dubai's sustainability-focused consumer segments.
Premium tiers command disproportionate shelf investment, though Mid-range products are gaining share fastest through local production incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MOHAP's sugar disclosure mandates and PLI-aligned manufacturing incentives are redrawing production footprints across the Emirates. The UAE's federal framework concentrates regulatory authority in Abu Dhabi while Dubai drives commercial innovation through its free-zone infrastructure.
Dubai
Business Bay and DIFC's white-collar density sustains demand for single-serve, shelf-stable morning solutions. ESMA nutritional standards enforcement through Dubai Municipality laboratories accelerates reformulation timelines for imported brands. Dubai Industrial City clusters extrusion and packaging capacity benefiting from PLI subsidies.
Abu Dhabi
Al Reem Island's health-conscious professionals command premium pricing for protein-fortified and low-sugar variants. MOHAP headquarters enforces front-of-pack labeling audits that compress product development cycles to 12-18 months. Khalifa Industrial Zone Abu Dhabi anchors domestic manufacturing investments reducing wheat import exposure.
Sharjah
Retail cereal density lags Dubai by 40 percent, creating whitespace for distribution network expansion. Hamriyah Free Zone offers tariff advantages for regional re-export operations serving Gulf Cooperation Council markets. Sharjah's South Asian expatriate households exhibit price elasticity favoring mid-range and economical tier products.
Northern Emirates
Ajman, Fujairah, and Ras Al Khaimah present underpenetrated channels with lower slotting fees than Dubai hypermarkets. Fujairah's port infrastructure supports bulk wheat discharge reducing freight costs for domestic millers. Ras Al Khaimah Economic Zone attracts packaging material suppliers supporting localized cereal production.
UAE Breakfast Cereals Market Competitive Landscape
Player mix skews toward multinational packaged food conglomerates with regional manufacturing footprints. The vendor base concentrates around three to four parent companies controlling multiple brand portfolios through subsidiary structures. Strategic archetypes include Halal-certified regional producers, European premium importers with ESMA validation, and Gulf-based private-label contractors. Competitive moves center on reformulation compliance investments and e-commerce platform partnerships bypassing traditional retail slotting fees.
Within the multinational conglomerate tier, Nestlé S.A. and The Kellogg's Company exemplify divergent Gulf market strategies. Nestlé leverages its regional manufacturing footprint to secure streamlined Halal approvals across Emirates retail networks. Kellogg's sustains brand recognition through Arabic-language packaging investments and localized flavor development. Associated British Foods PLC occupies a position emphasizing whole-grain credentials through its Jordans portfolio in premium retail placements. General Mills Inc. and PepsiCo Inc. sit within the diversified packaged food archetype with cereal representing one vertical among broader snack and convenience portfolios.
| Leading Market Players |
|---|
| General Mills Inc. |
| Associated British Foods PLC |
| Bobs Red Mill |
| Bio Familia AG |
| The Weetabix Food Company |
| Nestlé S.A. |
| The Kellogg's Company |
| Ecotone (Whole Earth) |
| PepsiCo Inc. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts for Black Sea and Australian wheat lock in both raw material access and cost visibility for UAE cereal manufacturers facing freight volatility and currency swings. These arrangements insulate domestic extrusion facilities from spot market spikes while compressing margin buffers for importers lacking equivalent sourcing structures.
Pricing Analysis
Certification level creates the primary spread between premium European imports and mid-range regional production. ESMA-validated micronutrient benchmarks command shelf-space premiums in Waitrose UAE and Spinneys Dubai, while PLI-subsidized domestic manufacturers compete on reformulated sugar-reduced recipes. Pricing pressure stems from MOHAP's front-of-pack labeling mandates forcing 12-18 month reformulation cycles. South Asian expatriate households in Deira and Sharjah exhibit highest price sensitivity, while health-conscious professionals in Al Reem Island accept premium positioning.
Supply Chain Analysis
Inventory cycles stretch through summer peaks as climate-controlled warehousing requirements extend lead times for fortified cereal shipments. The UAE draws over 90% of milling wheat from Black Sea and Australian suppliers, with extrusion equipment and packaging materials sourced from Germany and Italy. Single-source vulnerability concentrates in Black Sea grain corridors exposed to geopolitical disruption. Distribution runs through hypermarket chains in Dubai Mall and Yas Mall anchored by promotional slotting fees, with quick-commerce platforms capturing incremental volume in Dubai Marina.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE breakfast cereals market presents a defensive moat rooted in regulatory entrenchment. MOHAP's Halal certification timelines and sugar disclosure mandates create switching costs that favor established players with accredited laboratory relationships and reformulation expertise.
For Market Incumbents: Secure streamlined Halal approval pathways by leveraging regional manufacturing footprints across Gulf markets. Expand extrusion capacity in Dubai Industrial City to capture PLI subsidies while compressing import exposure. Defend against quick-commerce disintermediation through direct-to-consumer platform partnerships that bypass hypermarket slotting fees.
For New Entrants and Emerging Players: ESMA fast-track validation for micronutrient benchmarks opens shelf access in premium retail channels. Target underpenetrated Northern Emirates distribution networks in Ajman and Ras Al Khaimah where cereal density lags Dubai by 40%. Penetrate through employer-subsidized cafeteria contracts in Business Bay and DIFC specifying portion-controlled single-serve formats.
For Investors and Strategic Acquirers: Capital is best deployed toward regional manufacturers with captive Halal certification infrastructure and PLI-aligned production assets. Long-term viability hinges on reformulation agility under tightening MOHAP sugar thresholds. Watch for inflection in e-commerce subscription penetration rates among expatriate households as signal of channel shift acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Streamlining | Regional manufacturing footprint accelerates Gulf market access for Nestlé and Kellogg's portfolios. |
| Sugar Reformulation Investment | MOHAP compliance preserves shelf placement in government-affiliated Lulu and Carrefour channels. |
| Direct-to-Consumer Platform Launch | Quick-commerce partnerships bypass hypermarket slotting fees while capturing recurring expatriate revenue. |
| Northern Emirates Distribution Expansion | Whitespace in Ajman and Ras Al Khaimah offers 40% lower slotting costs than Dubai hypermarkets. |
| Protein Fortification Scale-Up | Extrusion-based micro-encapsulation serves athlete demand in Abu Dhabi's CrossFit and endurance clusters. |
Research Methodology
The analysis maps flakes, granola, muesli, and oatmeal segments, each validated through category buyers at Lulu Hypermarket and Carrefour UAE, supply planners at regional extrusion facilities, and regulatory affairs leads navigating MOHAP approval pathways. Secondary sources include ESMA nutritional standard filings, Dubai Municipality laboratory audit records, and PLI scheme disclosure documents. Bottom-up shipment data triangulates against top-down retail audit estimates from Nielsen and Circana.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product format, distribution channel, end-user demographic, and price tier. CAGRs derive from trend extrapolation of health-conscious consumer purchasing patterns and athlete segment expansion. Forecast inputs incorporate wheat import dependency ratios and climate-controlled logistics cost trajectories.
Underlying assumptions cover sustained MOHAP enforcement of sugar disclosure mandates and PLI subsidy continuity, with deviation risk concentrated in Black Sea supply disruption and Halal certification timeline compression. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Quinoa Pasta Market
Packaged Foods
Pre-Packaged Sandwich Market
Packaged Foods
Prepared Flour Mixes Market
Packaged Foods
India Instant Noodles Market
Packaged Foods
Japan Packaged Food Products Market
Packaged Foods
Sugar Free Cookies Market
Packaged Foods
Rice Noodles Market
Packaged Foods
Reduced Salt Packaged Foods Market
Packaged Foods
United Kingdom Food Spreads Market
Packaged Foods
Dinner Ready-To-Eat (RTE) Food Market
Packaged Foods
Impulse Ice-Cream Market
Packaged Foods
Australia Food Cans Market
Packaged Foods
Europe Free from Food Market
Packaged Foods
Global Breakfast Cereals Market
Packaged Foods
Asia-Pacific Ready-To-Eat Food Market
Packaged Foods
Cookie Pucks Market