
 Organic Bakery Products Market | 2026-2036
Organic Bakery Products Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Bakery Products Market Analysis
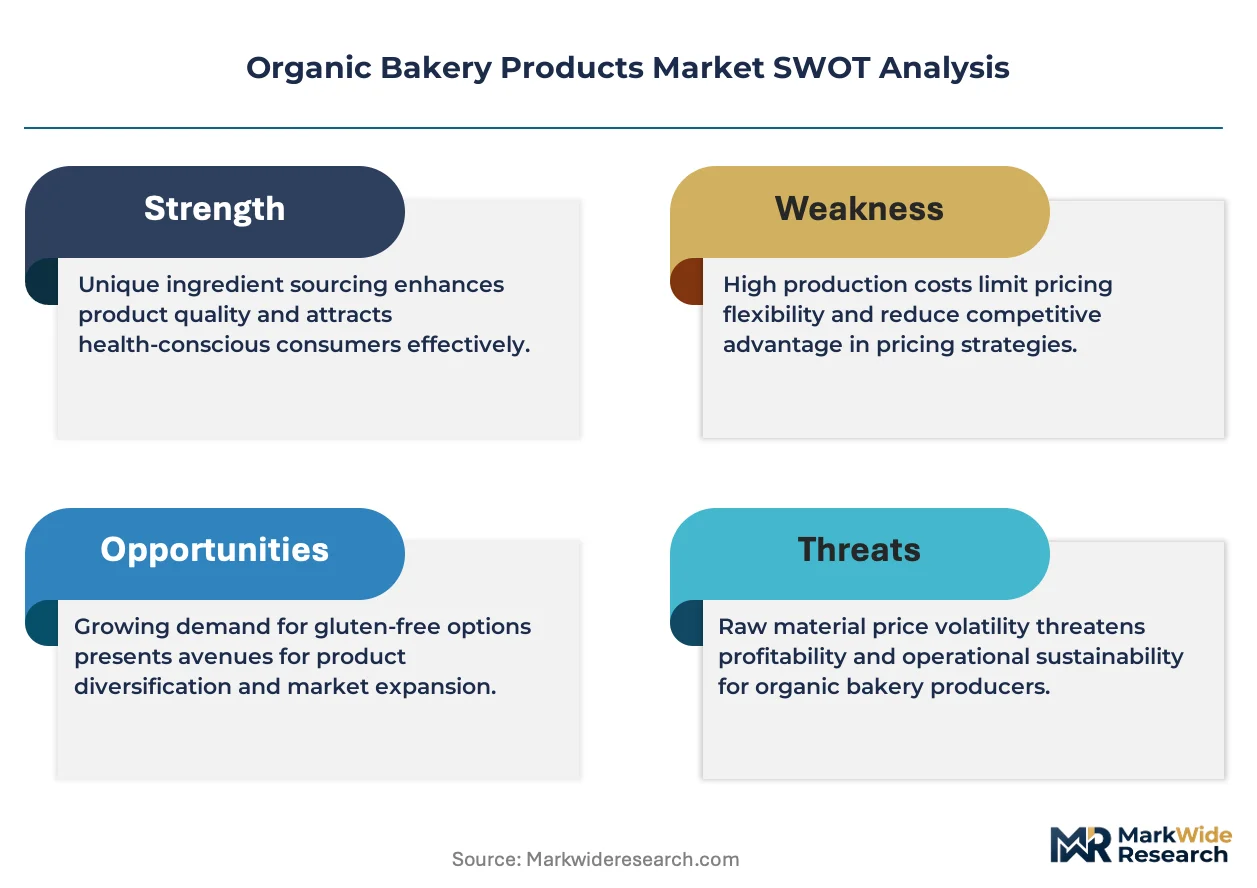
Clean-label certification is redrawing competitive boundaries in organic bakery products. Flowers Foods, Inc. leverages its southeastern distribution network to anchor conventional-to-organic conversions. Dave's Killer Bread specializes in whole-grain organic loaves with visible seed inclusions that command shelf-space premiums. Grupo Bimbo S.A.B. de C.V. extends its North American manufacturing scale into organic line extensions through in-house milling capacity.
Organic bakery products comprise flour-based goods manufactured without synthetic pesticides, genetically modified organisms, or artificial preservatives, with dough conditioning restricted to enzymatic and fermented alternatives. These products serve retail and foodservice channels seeking compliance with third-party organic standards such as USDA Organic or EU Organic certification. Bread and pastries capture the largest volume share within product type segments, though gluten-free ingredient formulations generate disproportionate margin expansion due to ingredient complexity and pricing power. Online retail and specialty stores represent the fastest-growing distribution channels as direct-to-consumer fulfillment reduces conventional supermarket slotting fee burdens.
The USDA National Organic Program governs ingredient sourcing and labeling integrity for products sold in the United States, while the EU Organic Regulation enforces equivalent standards across member states with mandatory annual inspection cycles. FDA food safety requirements intersect with organic claims through allergen disclosure and facility registration mandates. Stakeholders must monitor evolving enzyme approval lists and regional grain origin requirements that determine supply base eligibility.
Market Dynamics
Ingredient traceability mandates from the EU Organic Regulation and USDA National Organic Program are compressing supplier qualification timelines and forcing bakeries to consolidate sourcing relationships around certified grain elevators with full chain-of-custody documentation.
Growth Catalysts
- Clean-label certification:USDA Organic and EU Organic seals command shelf-space premiums in urban retail channels across Germany, France, and the United States, pulling conventional bakeries toward certified reformulation.
- Enzymatic dough conditioning:Transglutaminase and xylanase alternatives to synthetic conditioners enable organic compliance without sacrificing production throughput, accelerating adoption in industrial-scale facilities.
- Direct-to-consumer fulfillment:Online retail channels bypass conventional supermarket slotting fees, improving margin structures for regional organic bakeries serving metropolitan clusters.
Market Restraints
- Organic grain supply concentration:North American certified wheat and rye production concentrates in the Northern Plains, creating weather-dependent input volatility and single-source risk for coastal bakeries.
- Certification timeline friction:USDA National Organic Program mandates three-year transition periods for conventional acreage, constraining supply elasticity when demand spikes.
- Price elasticity ceilings:Premium organic positioning limits addressable market penetration in price-sensitive foodservice channels serving institutional buyers.
Strategic Opportunities
- Gluten-free ingredient convergence:Buckwheat, sorghum, and teff formulations capture dual-certification premiums for organic-gluten-free positioning in specialty retail.
- Urban micro-bakery networks:Underpenetrated secondary cities in the United States and Eastern Europe present whitespace for compact production facilities with localized sourcing.
- EU Green Deal agricultural incentives:Carbon-sequestration payments for organic tillage practices reduce effective grain costs for vertically integrated bakeries with captive milling capacity.
Industry Challenges
- Organic certification audit complexity:Annual third-party inspections across multi-site manufacturing networks strain quality assurance staffing and documentation systems.
- Legacy equipment retrofitting:Conventional mixing and proofing infrastructure requires sanitation protocol overhauls to prevent commingling with non-organic production lines.
- Enzyme approval list navigation:EFSA and FDA maintain divergent permitted-substance catalogs, complicating formulation standardization for multinational product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Bakery Products Market |
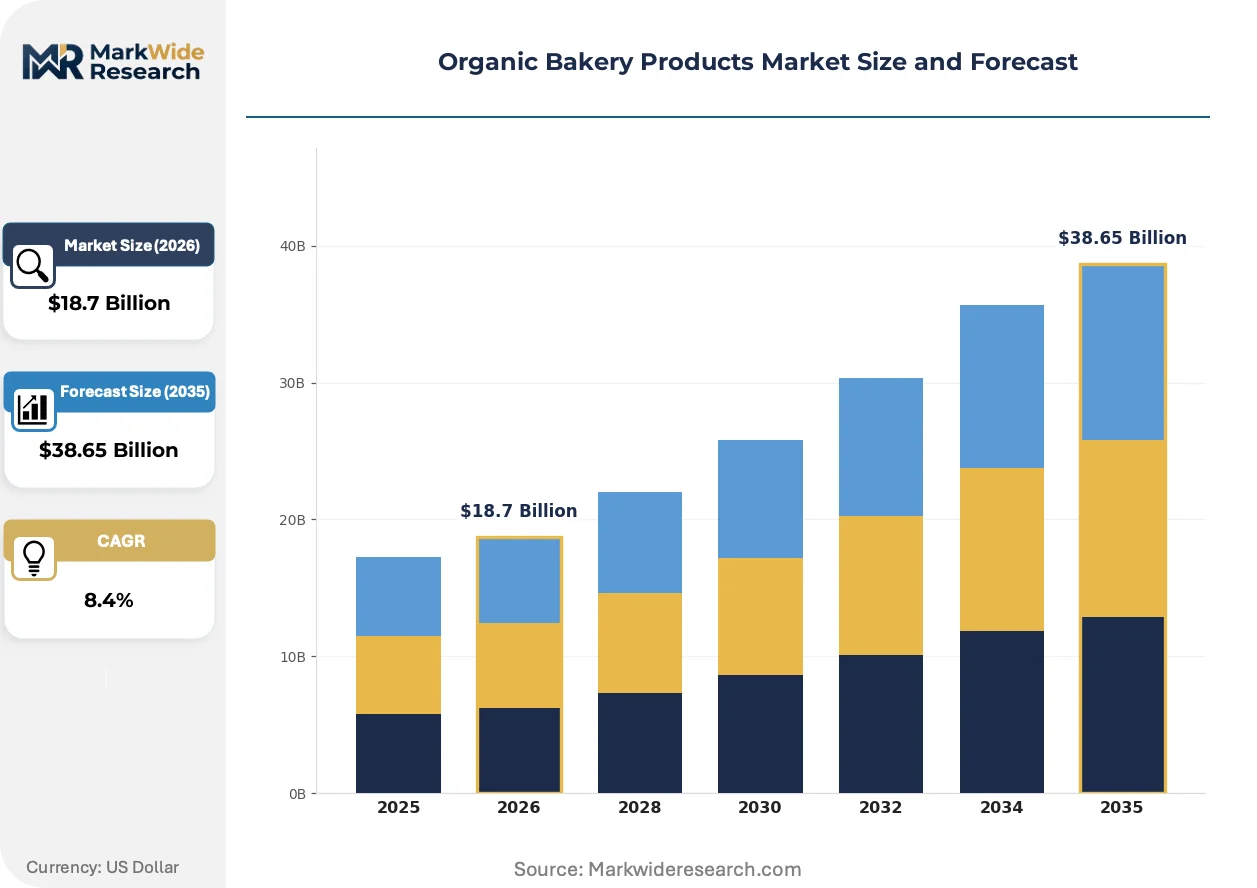
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bread, Pastries, Cookies, Cakes Ingredient Type: Whole Grain, Gluten-Free, Ancient Grains, Sweeteners Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Health Food Stores Consumer Segment: Health-Conscious, Families, Vegetarians, Organic Enthusiasts |
| Companies Covered | Grupo Bimbo S.A.B. de C.V., Flowers Foods, Inc., The Hain Celestial Group, Inc., Alvarado Street Bakery, General Mills, Inc., Dave's Killer Bread, Nature’s Bakery, Finsbury Food Group Plc, Toufayan Bakery, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Bakery Products Market Emerging Trajectories
Reformulation science and supply chain digitization are compressing the gap between artisanal quality claims and industrial production scale, enabling certified organic goods to penetrate mainstream retail channels previously dominated by conventional alternatives.
Fermentation monitoring systems using embedded pH and temperature sensors are miniaturizing quality control infrastructure previously confined to laboratory settings. Mid-size organic bakeries in metropolitan France and Germany deploy these units to maintain batch consistency without dedicated technical staff. The technology is miniaturizing the competitive barrier that separated artisanal credibility from scalable manufacturing, allowing regional players to challenge national brands on consistency metrics.
EU Organic Regulation enforcement harmonization across member states tightens residue testing protocols for imported grains, particularly from Black Sea origin countries. This industrial consequence redirects sourcing volumes toward domestic European cereal production, elevating regional grain premiums. German and French organic bakeries with long-term supply contracts face margin compression unless they pass input cost increases through to retail pricing.
Subscription-based replenishment models displace conventional supermarket purchasing for household bread consumption in urban United States markets. Direct-to-consumer channels capture recurring revenue streams while reducing slotting fee exposure, though fulfillment infrastructure demands capital deployment in cold-chain logistics. This behavioral shift concentrates most visibly in coastal metropolitan areas where delivery density supports route economics.
Organic Bakery Products Market Segmentation
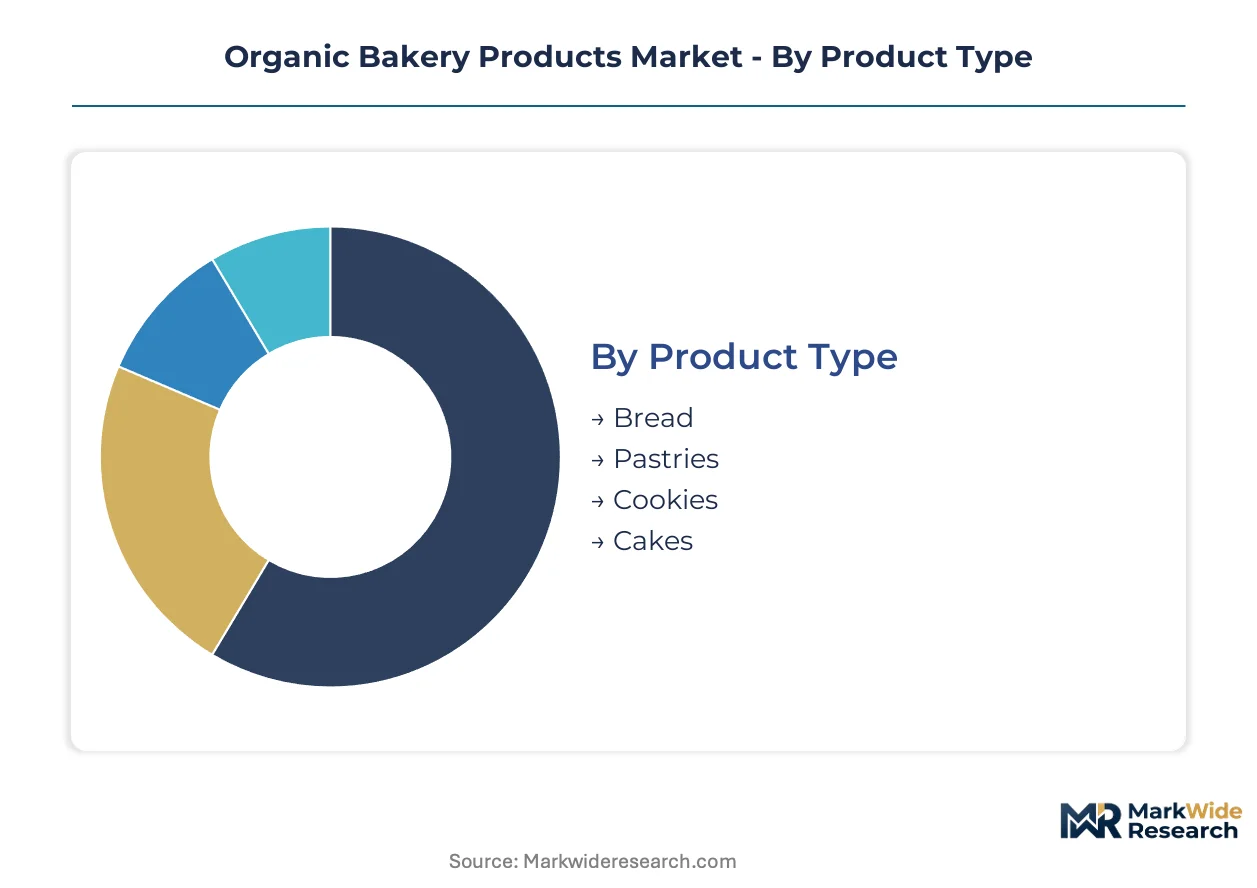
Segmentation in organic bakery products reveals how certification premiums flow through distinct product formats and channel structures. Manufacturers calibrate formulation complexity and distribution investment against margin capture potential in each slice.
Product Type:
Margin pools concentrate in formats where ingredient costs can be passed through via visible quality cues and habitual purchase frequency.
- Bread:Loaves and rolls manufactured from certified organic wheat, rye, or multigrain formulations account for the largest volume throughput. Daily consumption patterns in German and United States households sustain premium pricing power, though slotting fees in conventional retail compress net margins for non-integrated producers.
- Pastries:Croissants, danishes, and laminated dough products require extended fermentation and butterfat layering that differentiates artisanal positioning. French and Belgian urban bakeries command the steepest price premiums here, with butter origin labeling adding a secondary certification layer that supports further markup.
- Cookies:Shelf-stable formats with lower moisture content suit extended distribution radiuses and online retail fulfillment.
- Cakes:Celebration-oriented purchases concentrate in specialty retail channels with higher per-unit ticket values.
The dominant share belongs to Bread, while Pastries is closing the gap fastest.
Ingredient Type:
Cost structures diverge sharply based on grain sourcing geography and processing complexity.
- Whole Grain:Unrefined flour retains bran and germ layers, delivering fiber content claims that satisfy USDA Organic labeling requirements. United States coastal markets show particular density of demand, with Dave's Killer Bread and similar brands anchoring shelf-space allocation in Pacific Northwest retail clusters.
- Gluten-Free:Buckwheat, sorghum, and teff substitutions require segregated milling infrastructure and dedicated production lines to prevent cross-contamination. Dual organic-gluten-free certification captures the steepest premiums in the analysis, though EFSA and FDA maintain divergent approved-ingredient lists that complicate multinational standardization.
- Ancient Grains:Spelt, einkorn, and emmer varieties appeal to heritage-seeking consumers in German and Austrian markets.
- Sweeteners:Honey, maple syrup, and coconut sugar replacements for refined cane sugar support clean-label positioning.
Whole Grain commands the volume base, though Gluten-Free is expanding most quickly.
Distribution Channel:
Channel selection determines working capital intensity and customer acquisition economics.
- Supermarkets:Conventional grocery retail provides the broadest household penetration but demands slotting fees and promotional funding that strain regional bakery margins. Flowers Foods and Grupo Bimbo leverage manufacturing scale to absorb these costs while converting conventional shelf space to organic line extensions.
- Online Retail:Direct-to-consumer fulfillment bypasses intermediary margin extraction and enables subscription-based replenishment models. Cold-chain logistics requirements concentrate this channel in United States coastal metropolitan areas where delivery density supports route economics.
- Specialty Stores:Independent organic retailers in France and Germany provide curated assortment and staff expertise that justifies premium pricing.
- Health Food Stores:Narrower footprints with concentrated organic-loyal shopper bases suit niche brand incubation.
Supermarkets retain the largest throughput, while Online Retail is gaining share fastest.
Consumer Segment:
Purchase motivation clusters around health attribution versus values-based identification.
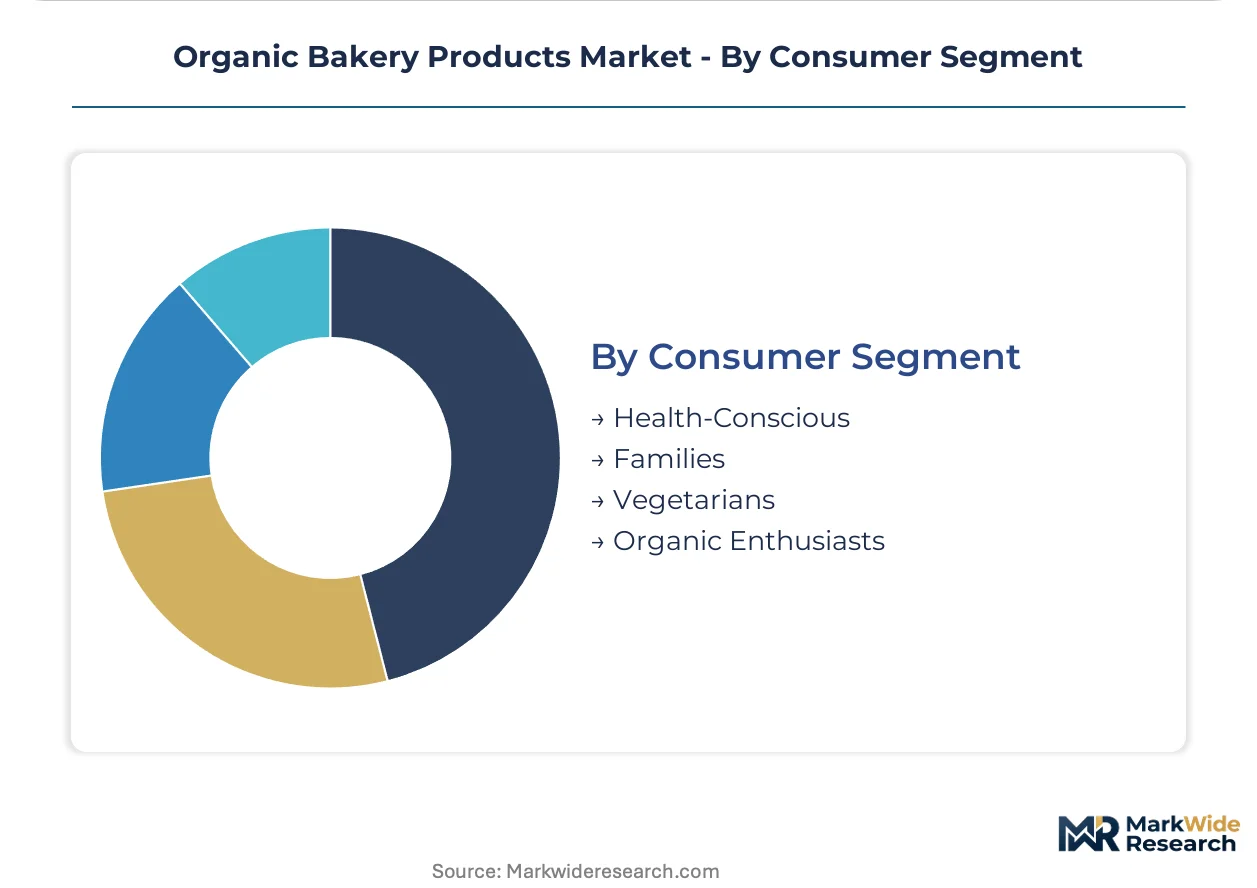
- Health-Conscious:Buyers prioritizing nutritional density and absence of synthetic inputs drive reformulation toward whole-grain and reduced-sugar variants. Urban professional households in France and the United States show the highest per-capita expenditure within this cluster.
- Families:Multi-person households with children under twelve concentrate volume purchasing in conventional retail channels, with price sensitivity moderating as household income rises.
- Vegetarians:Ethical consumption alignment extends to bakery selection, with egg and dairy substitution requirements influencing ingredient sourcing.
- Organic Enthusiasts:Certification-purist buyers who prioritize USDA Organic or EU Organic seals above other product attributes, often accepting significant price premiums.
Health-Conscious consumers anchor the revenue base, while Organic Enthusiasts are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German and French consumers absorb organic premiums with minimal volume attrition, while price-sensitive buyers in Mexico and India constrain premium penetration. Coastal United States markets split the difference, with subscription models insulating against sticker shock.
United States
Health-conscious urban households in Seattle, Portland, and San Francisco sustain double-digit organic bakery premiums. The USDA National Organic Program enforces three-year transition mandates for conventional farmland, tightening supply elasticity. Pacific Northwest micro-bakeries leverage direct-to-consumer channels to bypass supermarket slotting fees.
Germany
EU Organic Regulation compliance has become table stakes for retail shelf access in Berlin and Munich metropolitan clusters. The EU Green Deal agricultural incentives reward carbon-sequestration practices among organic grain growers. Bavarian and Baden-Württemberg bakeries with captive milling capacity capture margin relief from tillage subsidies.
France
Butter-origin labeling叠加 atop EU Organic certification commands steepest price premiums in Paris and Lyon artisanal channels. ANSM residue-testing protocols for imported Black Sea grains redirect sourcing toward domestic cereal production. Île-de-France industrial bakeries face input cost pressure from regional grain premiums.
Canada
Health Canada and PMRA alignment with USDA organic standards facilitates cross-border ingredient flows into Toronto and Vancouver production facilities. Provincial organic certification programs in British Columbia and Quebec add secondary compliance layers. Prairie province organic wheat output concentrates around Manitoba elevators with full chain-of-custody documentation.
United Kingdom
Post-Brexit divergence from EU Organic Regulation complicates certification portability for London-based bakeries exporting to continental Europe. Soil Association standards maintain equivalency recognition with EU Organic in key member states. Southeast England specialty retailers incubate niche organic-gluten-free brands for metropolitan London demand.
Organic Bakery Products Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the organic bakery products landscape. Industrial-scale manufacturers with in-house milling capacity and enzymatic formulation expertise dominate cost efficiency, while artisan-positioned specialists command premium shelf-space through visible seed inclusions and heritage grain storytelling. The competitive terrain splits between consolidation-driven national brands and fragmentation among regional micro-bakeries. Dominant competitive moves include backward integration into certified grain sourcing and geographic expansion through direct-to-consumer fulfillment infrastructure.
Within the multinational conglomerate tier, Grupo Bimbo S.A.B. de C.V. and Flowers Foods, Inc. occupy positions defined by manufacturing scale and distribution network density. Dave's Killer Bread exemplifies the specialist archetype that has achieved national penetration without sacrificing craft positioning. These three anchors illustrate how divergent strategic postures—scale efficiency versus premium differentiation—can coexist within the same certification framework.
| Leading Market Players |
|---|
| Grupo Bimbo S.A.B. de C.V. |
| Flowers Foods, Inc. |
| The Hain Celestial Group, Inc. |
| Alvarado Street Bakery |
| General Mills, Inc. |
| Dave's Killer Bread |
| Nature's Bakery |
| Finsbury Food Group Plc |
| Toufayan Bakery, Inc. |
| Others |
Supply Flow & Price Mechanics
In-house milling capacity at industrial-scale bakeries compresses per-unit flour costs and sets price floors that regional competitors struggle to match. USDA National Organic Program certification timelines and EU Organic Regulation compliance costs further stratify the market, with captive grain sourcing becoming the decisive scale economy separating viable players from margin-squeezed followers.
Pricing Analysis
USDA National Organic Program and EU Organic Regulation dictate the pricing tier structure across the organic bakery products market. Three-tier pricing separates artisanal heritage-grain positioning from standard certified organic and private-label economy tiers. Price differentiation rests on certification grade and visible ingredient quality cues such as seed inclusions and butter origin labeling. Cost compression in the standard tier is intensifying because German and French bakeries face regional grain premiums from EU Green Deal sourcing redirection. Foodservice institutional buyers exhibit the highest price sensitivity, while urban professional households in Seattle and Paris absorb premiums with minimal volume attrition.
Supply Chain Analysis
Northern Plains certified wheat elevators underwrite North American organic bakery supply security, though weather-dependent harvests create input volatility for coastal production facilities. Geographic supply concentration centers on United States Northern Plains, Canadian Prairie provinces, and domestic European cereal production in Germany and France. Raw material dependencies include certified organic wheat, enzymatic dough conditioners such as transglutaminase, and heritage grain varieties like spelt and einkorn. Single-source vulnerability runs through the three-year transition mandate for conventional farmland conversion under USDA rules. Distribution runs through supermarket retail with slotting fee burdens, direct-to-consumer subscription channels, and specialty independent retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment models represent a service-attach opportunity expanding faster than conventional retail throughput, capturing recurring revenue streams while insulating bakeries from slotting fee extraction.
For Market Incumbents: Shield margin position by accelerating backward integration into certified grain elevators with full chain-of-custody documentation. Consolidate sourcing relationships around Northern Plains suppliers before EU Green Deal incentives further elevate regional grain premiums. Invest in enzymatic formulation R&D to maintain production throughput without synthetic conditioner reliance. For New Entrants and Emerging Players: Direct-to-consumer fulfillment infrastructure gaps in secondary United States cities and Eastern European metropolitan clusters present white-space targets. The most penetrable segment is health-conscious urban professional households seeking subscription convenience. Pursue a go-to-market angle anchored on localized micro-bakery production with heritage grain storytelling to differentiate from industrial-scale competitors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated bakeries with captive milling capacity and established certification infrastructure. Long-term viability hinges on supply base control rather than brand equity alone. Target acquisition archetypes include regional organic bakeries with underutilized production capacity and existing USDA or EU Organic certifications. Watch EU Green Deal agricultural incentive adjustments as the inflection indicator for input cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Grain Sourcing | Captive milling capacity insulates margins from EU Green Deal regional grain premiums. |
| Direct-to-Consumer Subscription Launch | Recurring revenue models bypass supermarket slotting fees in coastal metropolitan clusters. |
| Enzymatic Formulation R&D Investment | Transglutaminase alternatives enable organic compliance without sacrificing industrial throughput. |
| Heritage Grain Product Line Extension | Spelt and einkorn positioning commands shelf-space premiums in German and Austrian retail. |
| EU Organic Certification Expansion | Regulatory compliance opens Berlin and Munich metropolitan retail access. |
Methodological Framework
A spread of perspectives from plant managers at industrial bakeries, procurement leads at certified grain elevators, category buyers at supermarket chains, and technical R&D directors at enzyme suppliers converged on the working assumptions. Primary interviews combined with secondary validation from USDA National Organic Program filings, EU Organic Regulation enforcement reports, SEC 10-K disclosures from publicly traded food manufacturers, and Nielsen retail audit data. Bottom-up volume modeling and top-down value triangulation anchored the market sizing.
Segmentation dimensions modeled include product type, ingredient category, distribution channel, and consumer motivation cluster across the projection horizon. CAGRs derived from historical trajectory analysis and forward-looking elasticity assumptions. Industry-specific forecast inputs incorporated three-year organic transition timelines and EU Green Deal agricultural incentive schedules.
Material uncertainties — weather-dependent grain harvests, regulatory enzyme approval list revisions, and subscription model adoption rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification compliance costs and channel migration patterns. Practitioners should keep alternative scenarios live as EU Green Deal implementation and direct-to-consumer logistics economics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Pizza Crust Market
Bakery Products
Bakery Fillings Market
Bakery Products
Pizza Dough Balls Market
Bakery Products
North America Fortified Bakery Products Market
Bakery Products
Latin America Frozen Bakery Market
Bakery Products
Pancake Mixes Market
Bakery Products
Organic Bread Flour Market
Bakery Products
North America Gluten Free Bakery Mixes Market
Bakery Products
Oman Frozen Bakery Products Market
Bakery Products
Fortified Bakery Market
Bakery Products
Organic Frozen Bakery Market
Bakery Products
Bahrain Bakery Product Market
Bakery Products
Bread Improver Market
Bakery Products
Pancakes Market
Bakery Products
Vegan Certified Cake Mixes Market
Bakery Products
Frozen Bakery Additives Market