
 Organic Bread Flour Market | 2026-2036
Organic Bread Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Bread Flour Market Insights
Ingredient sourcing premiums is reconfiguring margin distribution across the organic bread flour value chain. King Arthur Flour Company leverages its farmer-direct wheat partnerships to sustain price stability in volatile grain markets. Bob's Red Mill anchors its competitive position through certified gluten-free and organic co-manufacturing infrastructure. Ardent Mills dominates bulk organic flour supply to national bakery chains, controlling distribution scale that smaller regional mills cannot match.
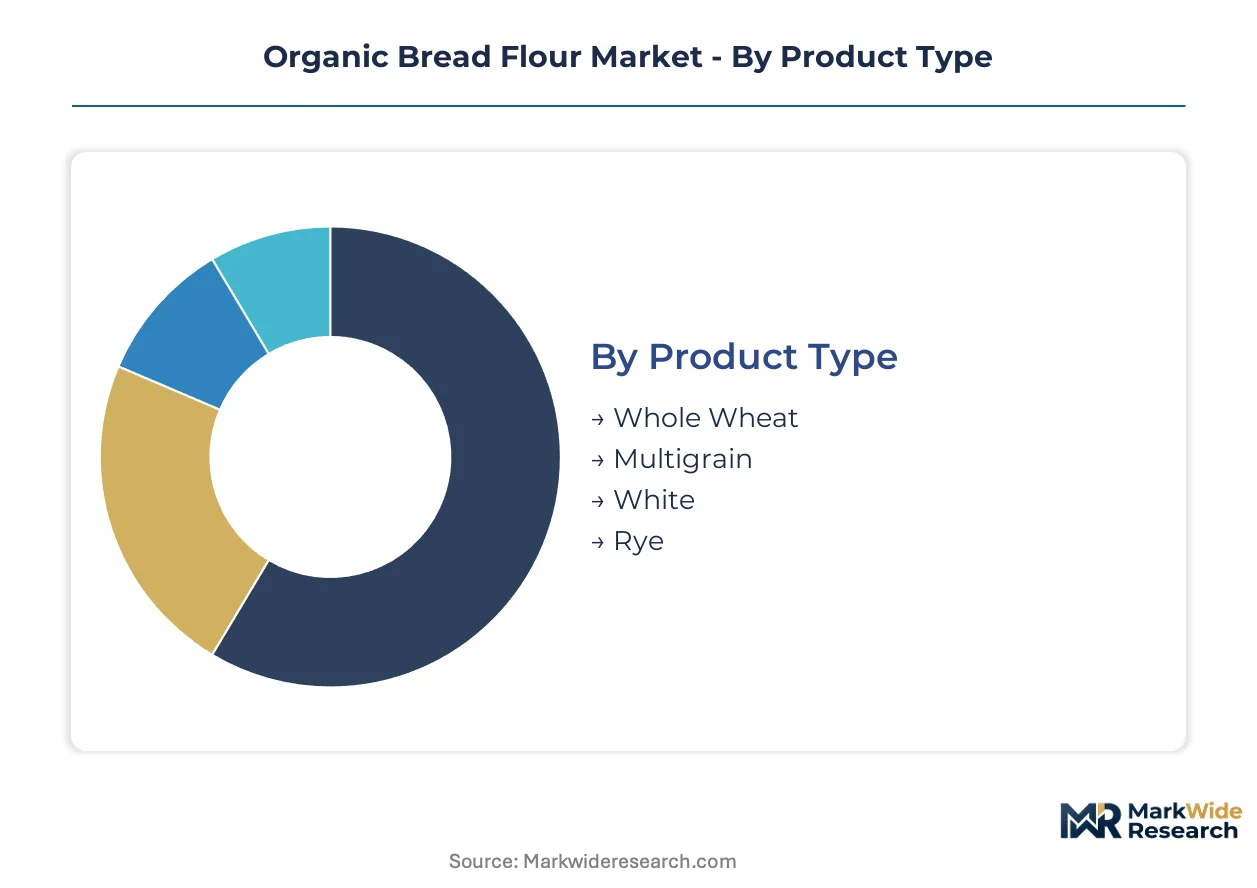
Organic bread flour consists of wheat milled from certified organic grain, processed without synthetic pesticides, herbicides, or chemical fertilizers, with protein content typically ranging from 11% to 14% to achieve proper gluten development in yeast-leavened breads. Its primary commercial purpose is enabling bakeries and food manufacturers to produce bread meeting USDA Organic or equivalent certification standards for premium retail positioning. Whole wheat organic flour leads product type volume due to its alignment with fiber-forward nutrition positioning, while multigrain variants represent the fastest-growing segment as bakeries formulate complex flavor profiles. Commercial bakeries command the largest end-use share through contracted bulk procurement, though foodservice channels are expanding fastest as restaurant chains add artisan bread programs.
USDA organic certification and the EU Organic Regulation shape ingredient traceability requirements, forcing mills to maintain segregated supply chains from farm to finished flour. FDA food safety standards and state-level organic program accreditation further govern processing facility compliance and labeling integrity. Stakeholders must monitor evolving organic integrity rules and climate-driven wheat supply volatility to secure long-term milling capacity and farmer contracts.
Market Dynamics
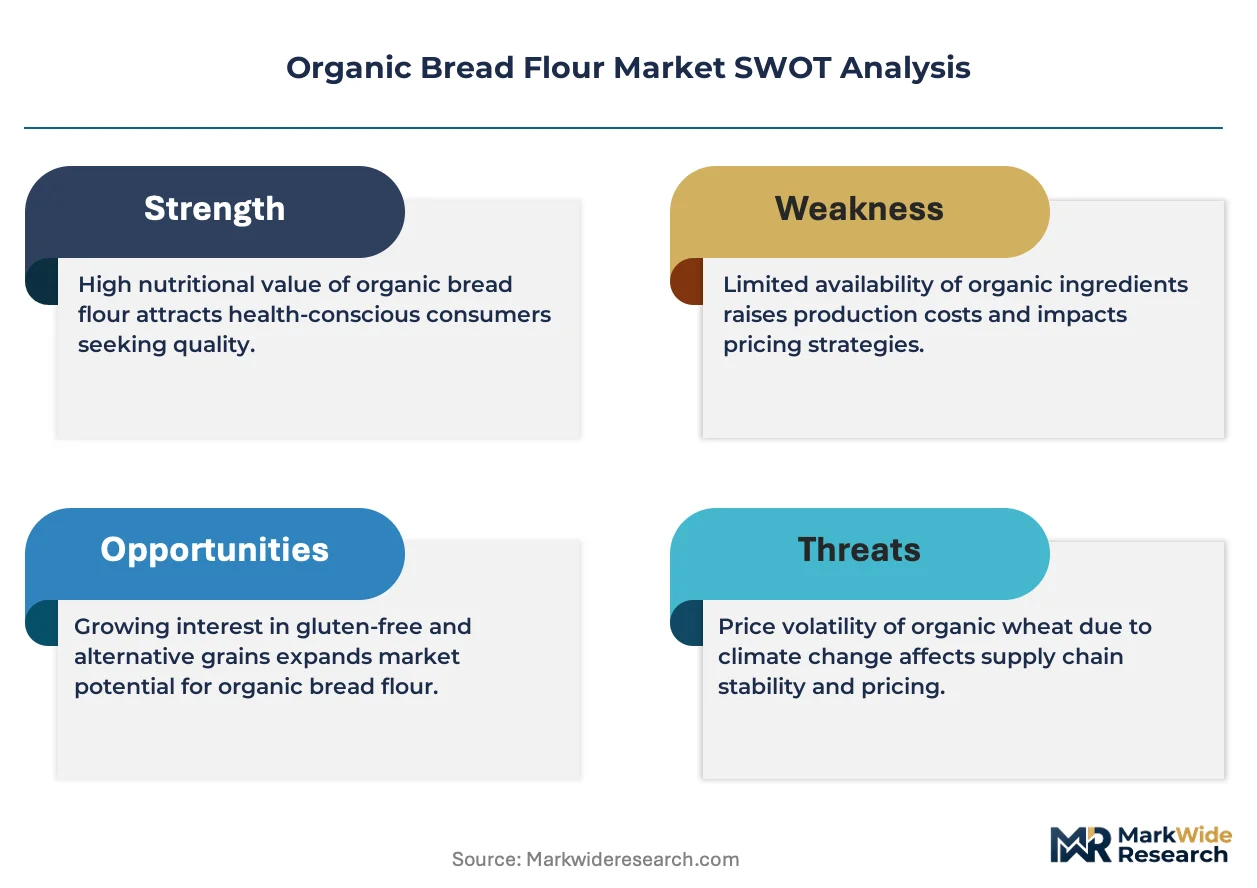
Organic bread flour supply chains face mounting pressure from climate-driven wheat yield volatility and tightening organic integrity enforcement by USDA and EU regulators, forcing mills to rebuild farmer contracting models and segregated handling infrastructure from farm to finished product.
Growth Catalysts
- EU Organic Regulation traceability mandates:Certified mills gain preferential access to German and French retail channels as supermarkets demand documented chain-of-custody from field to bakery.
- Artisan bakery channel expansion:Independent bakers in urban clusters across Italy, Spain, and the Netherlands are converting to certified organic flour to capture premium positioning in specialty retail.
- Stone-milling revival:Traditional low-temperature milling preserves wheat germ integrity and enables nutrient-forward labeling claims that differentiate finished loaves in competitive bakery cases.
Market Restraints
- Organic wheat input cost volatility:Certified grain carries 40-60% premiums over conventional, compressing mill margins when commodity markets spike and long-term bakery contracts fix flour prices.
- Great Plains supply concentration:North American organic hard red winter wheat production clusters in Kansas and Nebraska drought corridors, exposing mills to single-region weather risk without geographic diversification.
- Three-year organic transition barrier:Conventional farmers face revenue loss during mandatory soil-building periods before certification eligibility, constraining new supply entry regardless of price signals.
Strategic Opportunities
- Portuguese and Greek market underpenetration:Mediterranean bakery traditions remain dominated by conventional flour, creating first-mover openings for certified organic positioning in tourist-heavy coastal cities.
- Direct-to-bakery subscription platforms:Specialty mills are bypassing distributors to capture margin and build loyalty through scheduled flour deliveries matched to bakery production cycles.
- USDA Climate-Smart Commodities funding:Federal grants for regenerative organic wheat production reduce farmer transition risk and expand certified acreage available to mill contracting programs.
Industry Challenges
- Certified organic millwright scarcity:Equipment maintenance and calibration for segregated organic lines requires specialized technicians, with training programs lagging behind facility expansion timelines.
- Cross-contamination prevention capex:Dual-use mills must invest in dedicated conveying, sifting, and packaging lines to maintain organic integrity, stretching capital deployment across extended payback periods.
- Multi-jurisdiction label compliance:Simultaneous USDA Organic, EU Organic, and Canada Organic Regime requirements force redundant testing and documentation systems that slow product release.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Bread Flour Market |
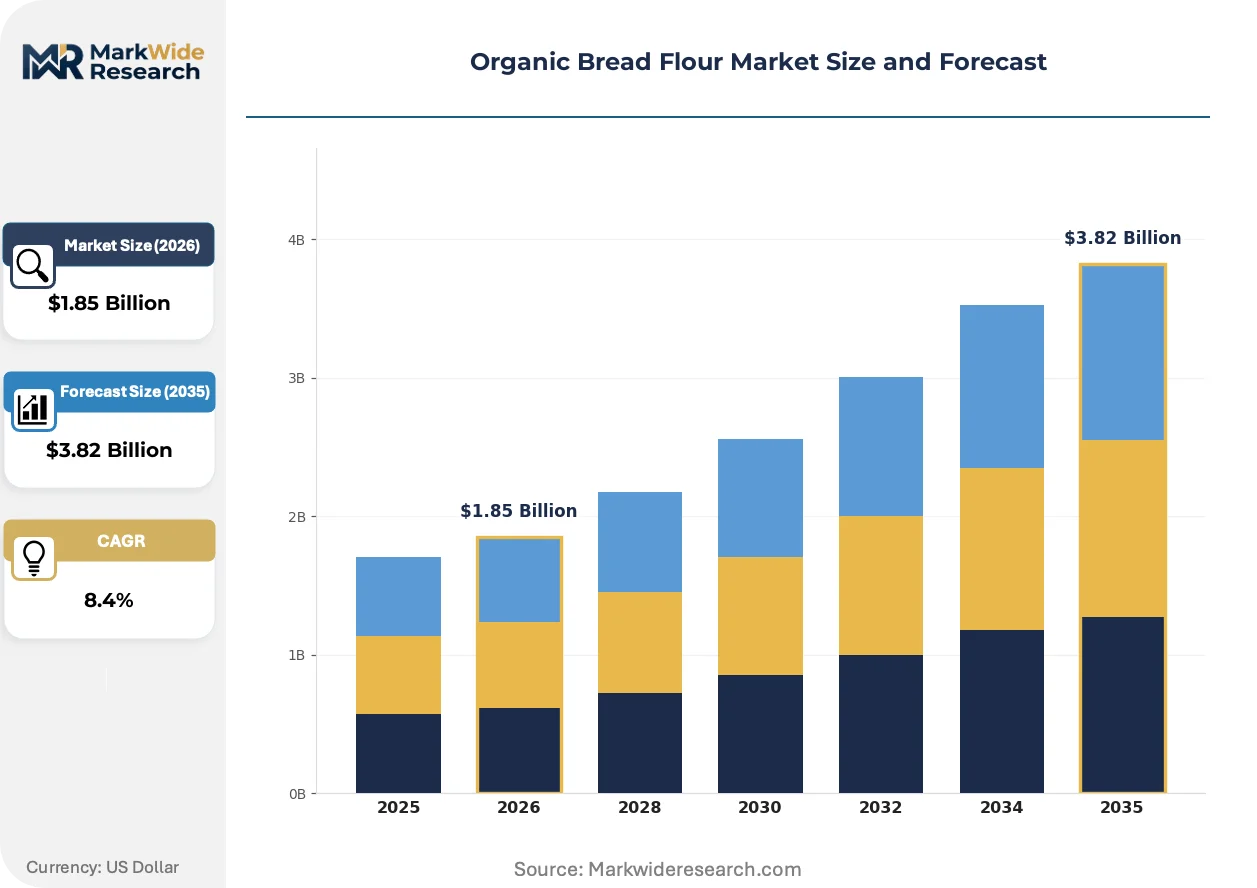
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Wheat, Multigrain, White, Rye End Use: Commercial Bakeries, Retail Consumers, Food Processing, Foodservice Packaging Type: Bulk Bags, Small Bags, Eco-friendly Packaging, Resealable Bags Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | Hodgson Mill, Fairhaven Organic Flour Mill, Bob's Red Mill, Fieldstone Organics, Anita’s Organic Mill, King Arthur Flour Company, Great River Organic Milling, Flourist, Ardent Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Bread Flour Market Trends and Innovations
Digital traceability infrastructure and regenerative agriculture verification are converging to reshape how organic flour mills demonstrate integrity to risk-averse bakery customers and liability-conscious retailers.
Blockchain-enabled grain tracking is digitizing custody documentation from organic farm certification through elevator receipt, mill intake, and bulk bakery delivery. Large commercial bakeries in Germany and France are mandating this transparency layer in supplier contracts, compressing acceptance timelines for mills lacking real-time provenance systems and favoring early adopters with integrated ERP-traceability platforms.
EU Green Deal agricultural transition incentives are channeling subsidy flows toward regenerative organic wheat cultivation, redirecting farmer planting decisions across Poland and Romania. Mills with established regenerative sourcing programs are securing multi-year supply commitments ahead of competitors, while late entrants face contracted organic grain availability through the mid-decade.
Bakery procurement departments are consolidating supplier rosters to reduce audit burden and simplify ingredient qualification. National bread manufacturers in the United States and United Kingdom are shrinking approved organic flour vendor lists from dozens to three-to-five strategic partners, concentrating volume with mills offering integrated technical service and consistent protein specification across harvest years.
Organic Bread Flour Market Segmentation
Organic bread flour procurement cycles vary dramatically across product formats and customer types, with bulk commercial buyers turning inventory weekly while retail packaged goods rotate monthly. Understanding these velocity differentials helps mills align production scheduling, working capital deployment, and certification audit timing with actual demand patterns.
Product Type:
Inventory velocity diverges sharply across flour varieties, with high-turnover white flour demanding continuous mill runs and slower-moving specialty grains requiring campaign-style production batches.
- Whole Wheat:Milled from complete wheat berries retaining bran and germ layers, delivering fiber content that commands premium shelf positioning in German and French retail channels. Commercial bakeries in urban clusters across Italy and Spain specify this grade for dense, rustic loaves that justify higher price points in specialty retail.
- Multigrain:Blends hard red wheat with certified organic rye, spelt, or ancient grains to achieve complex flavor matrices. Bakeries in the Netherlands and Belgium are converting formulations to capture differentiation in competitive artisan markets, though sourcing multiple certified organic grains extends procurement cycles and complicates supplier qualification.
- White:Refined flour with bran and germ removed, offering extended shelf stability and consistent protein performance for high-volume bread production.
- Rye:Dense, low-gluten flour traditional to Northern European baking, requiring specialized fermentation handling and longer proofing protocols.
Whole wheat anchors the volume base while multigrain gains share at the steepest rate.
End Use:
Customer scale determines margin structure and service intensity, with national bakery chains extracting volume discounts that independent operators cannot match.
- Commercial Bakeries:Large-scale bread manufacturers operating continuous production lines demand consistent protein specifications across harvest years. These buyers lock in multi-year contracts with mills offering technical service support and segregated organic handling infrastructure.
- Foodservice:Restaurant chains and hotel groups are expanding artisan bread programs, creating spot-demand volatility that strains mill scheduling flexibility. Operators in tourist-heavy Mediterranean coastal cities are specifying certified organic flour to meet sustainability procurement mandates from corporate headquarters.
- Retail Consumers:Home bakers purchasing through grocery and specialty channels, sensitive to packaging convenience and recipe guidance.
- Food Processing:Industrial manufacturers incorporating organic flour into frozen dough, cracker, and prepared meal applications with exacting moisture and ash specifications.
Commercial bakeries dominate tonnage throughput while foodservice climbs the fastest.
Packaging Type:
Packaging economics split along volume tiers, with bulk formats capturing transportation efficiency and small bags capturing retail markup.
- Bulk Bags:One-ton totes and 50-pound sacks for commercial bakery intake, minimizing per-unit packaging cost but requiring dedicated handling equipment and climate-controlled storage.
- Eco-friendly Packaging:Compostable or recyclable materials addressing sustainability mandates from German and French supermarket chains. Mills serving these retailers must validate packaging claims through third-party certification, extending product development timelines.
- Small Bags:Five-pound retail units for home bakers, carrying highest margin per pound but demanding complex SKU management and frequent changeovers.
- Resealable Bags:Zip-closure formats preserving flour freshness across multiple baking sessions, popular with occasional home users.
Bulk bags carry the volume weight while eco-friendly packaging expands most quickly.
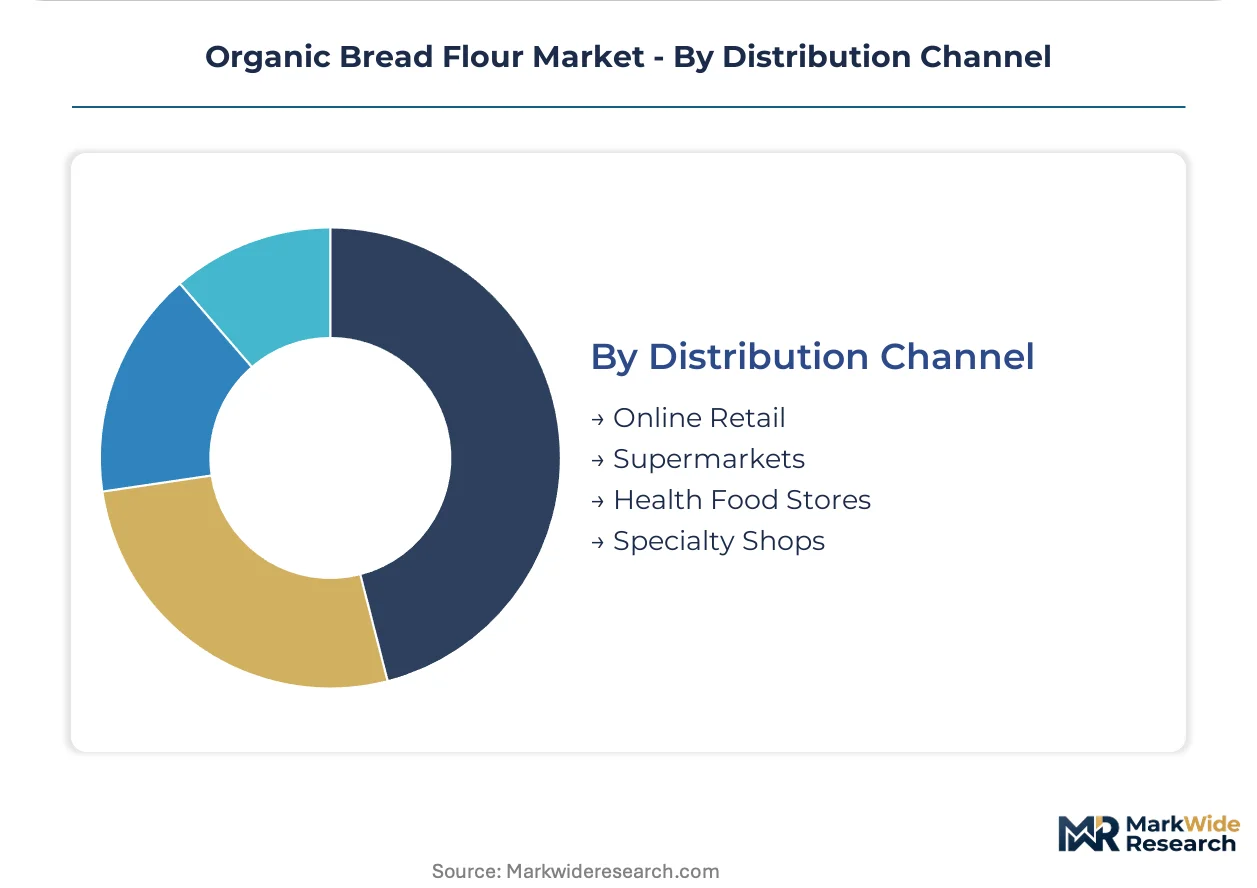
Distribution Channel:
Channel selection determines customer acquisition cost and brand control, with direct digital relationships offering margin recovery that intermediated retail cannot provide.
- Supermarkets:National chains in Germany and France are consolidating organic flour SKUs and demanding documented chain-of-custody from field to shelf. These retailers now mandate blockchain-enabled traceability systems that compress supplier acceptance timelines for mills lacking integrated platforms.
- Online Retail:Direct-to-consumer and marketplace platforms enabling subscription models matched to bakery production cycles. Specialty mills in Portugal and Greece are bypassing traditional distributors to capture margin and build loyalty through scheduled deliveries.
- Health Food Stores:Independent retailers with educated staff capable of explaining protein specifications and organic certification differences to discerning buyers.
- Specialty Shops:Artisan bakery supply stores and restaurant equipment dealers serving professional accounts with technical product knowledge.
Supermarkets command the revenue base while online retail scales fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies, with German and French buyers accepting substantial premiums for certified organic traceability while Mediterranean markets remain acutely sensitive to cost differentials against conventional flour.
United States
Commercial bakeries in the Midwest and Northeast are converting production lines to organic flour to meet retailer clean-label mandates. USDA organic certification requirements and Climate-Smart Commodities grant programs are accelerating farmer transitions in Kansas and Nebraska. Minneapolis-St. Paul anchors North American organic milling capacity, with major facilities processing hard red winter wheat from the Great Plains.
Germany
Artisan bakery density in Berlin and Munich sustains the world's highest per-capita organic flour consumption. EU Organic Regulation traceability mandates and the EU Green Deal agricultural transition incentives are reshaping procurement standards across Baden-Württemberg and Bavaria. The Black Forest region concentrates stone-milling operations supplying premium retail channels with heritage wheat varieties.
France
Boulangeries in Paris and Lyon are expanding organic bread programs to capture sustainability-conscious tourists and affluent urban households. ANSM and DGCCRF enforcement of organic integrity rules is tightening documentation requirements for imported grain. The Île-de-France region hosts specialized distributors serving the concentration of artisan bakeries in the capital corridor.
Italy
Independent bakers in Milan and Rome are converting to certified organic flour to differentiate in competitive specialty retail. EU organic subsidies and regional quality designation protections are supporting farmer transitions in Emilia-Romagna and Tuscany. The Po Valley remains the primary domestic source of organic soft wheat for regional milling operations.
Netherlands
Foodservice operators in Amsterdam and Rotterdam are specifying organic flour for corporate sustainability procurement mandates. EU Organic Regulation compliance and national environmental subsidies are reducing transition barriers for conventional wheat farmers in Flevoland and Gelderland. The Randstad urban cluster concentrates demand from restaurant chains and hotel groups expanding artisan bread programs.
Organic Bread Flour Market Competitive Landscape
Specialty mills and diversified grain processors split the market along service-intensity lines, with artisan-focused operators commanding premium positioning against bulk suppliers serving national bakery chains. Consolidation pressure is mounting as procurement departments shrink approved vendor lists to reduce audit burden. Two strategic archetypes dominate: heritage-branded specialty mills leveraging direct farmer relationships, and scale-driven processors controlling distribution infrastructure. Competitive moves center on backward integration into organic wheat contracting and geographic expansion through regional mill acquisitions.
Among heritage-branded specialty mills, King Arthur Flour Company and Bob's Red Mill exemplify the farmer-direct sourcing archetype that sustains price stability and certification integrity. Ardent Mills occupies a position within the scale-driven tier, supplying bulk organic flour to national bakery chains through controlled distribution networks. Fairhaven Organic Flour Mill represents the regional specialist model, anchoring Pacific Northwest supply relationships that larger processors cannot replicate.
| Leading Market Players |
|---|
| Hodgson Mill |
| Fairhaven Organic Flour Mill |
| Bob's Red Mill |
| Fieldstone Organics |
| Anita's Organic Mill |
| King Arthur Flour Company |
| Great River Organic Milling |
| Flourist |
| Ardent Mills |
| Others |
Pricing and Supply Chain Analysis
Minneapolis-St. Paul milling capacity anchors North American organic flour supply, with Great Plains wheat intake dictating protein premium spreads to commercial bakeries locked into annual contracts. USDA organic certification compliance costs and Climate-Smart Commodities grant flows are reshaping farmer contracting terms that cascade into bakery procurement negotiations.
Pricing Analysis
After-sales technical service and extended quality guarantees drive lifetime value for mill-bakery relationships. Three-tier pricing structure across premium heritage-stone-milled, standard certified-organic, and economy private-label tiers segments buyers by certification depth and protein specification rigor. Cost compression in the economy tier is intensifying because conventional flour price spikes compress organic premiums during commodity rallies. National bakery chains exhibit lowest price sensitivity due to clean-label mandate compliance requirements, while independent foodservice operators in Mediterranean markets resist premiums exceeding conventional flour by more than 25 percent.
Supply Chain Analysis
Ardent Mills, King Arthur Flour Company, and Bob's Red Mill control the majority of certified organic milling capacity across the United States. Kansas, Nebraska, and North Dakota organic hard red winter wheat production draws from drought-exposed Great Plains corridors, creating geographic concentration risk without Canadian or Argentine diversification. Single-region weather vulnerability threatens harvest consistency for mills lacking multi-hemisphere sourcing programs. Distribution runs through bulk tote deliveries to commercial bakeries, supplemented by palletized retail channels serving supermarkets and online subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled traceability infrastructure is transforming organic flour procurement into a platform-economics arena where interoperability between mill ERP systems and retailer compliance portals determines supplier viability.
For Market Incumbents: Pre-empt consolidation pressure from shrinking approved vendor lists at national bakery chains by acquiring regional stone-milling operations in Germany and France. Backward integration into regenerative organic wheat contracting secures multi-year supply commitments ahead of EU Green Deal subsidy competition. Certification investment in simultaneous USDA Organic and EU Organic compliance reduces audit burden for cross-Atlantic bakery customers.
For New Entrants and Emerging Players: Build out direct-to-bakery subscription platforms in Portuguese and Greek coastal cities where conventional flour dominance leaves white-space for certified organic positioning. Mediterranean foodservice procurement mandates from corporate sustainability offices create entry traction unavailable in saturated German markets. Technical service differentiation through scheduled flour deliveries matched to bakery production cycles captures loyalty that commodity distributors cannot replicate.
For Investors and Strategic Acquirers: Long-term, this sits as a regenerative agriculture infrastructure play because EU subsidy flows and USDA Climate-Smart Commodities funding are structurally expanding certified acreage through the mid-decade. Target acquisition profiles center on regional mills with established farmer-direct relationships and segregated organic handling infrastructure. Monitor organic millwright training program graduation rates as inflection signal for capacity expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regenerative Wheat Contracting | USDA Climate-Smart grants reduce farmer transition risk and secure multi-year supply commitments ahead of competitors. |
| Blockchain Traceability Platform Deployment | German and French supermarket chains mandate documented chain-of-custody, compressing acceptance timelines for non-compliant mills. |
| Regional Mill Acquisition in Mediterranean Markets | Portuguese and Greek coastal cities lack certified organic penetration, creating first-mover positioning in tourist-heavy demand clusters. |
| Dual Certification Infrastructure Investment | Simultaneous USDA Organic and EU Organic compliance reduces redundant testing burden for cross-Atlantic bakery procurement departments. |
| Direct-to-Bakery Subscription Channel Launch | Scheduled flour deliveries matched to production cycles capture margin recovery and technical service loyalty unavailable through distributors. |
Research Methodology
A spread of perspectives from mill operations directors, bakery procurement managers, organic certification auditors, and agricultural extension specialists converged on the working assumptions driving supply-demand balances. Primary interviews with farmer cooperative leaders and elevator receipt administrators were cross-referenced against USDA National Agricultural Statistics Service data, EU organic farming subsidy disbursement records, and customs trade documentation. Bottom-up acreage and yield projections were triangulated against top-down bakery capacity expansion announcements across the analysis window.
Demand-supply balance modeling anchored volume forecasts to commercial bakery line conversions, foodservice artisan program expansions, and retail SKU consolidation trends. Segmentation dimensions included product type, end-use customer scale, packaging format, and distribution channel velocity. CAGRs were derived from harvest-year protein specification consistency and contract pricing durability across volatile commodity cycles. Climate-driven yield volatility and organic integrity enforcement intensity served as scenario-weighting inputs.
Stress conditions across drought frequency in Kansas-Nebraska corridors, EU organic regulation amendment timelines, and bakery procurement department vendor consolidation rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding subsidy program continuity and certification standard harmonization. Quarterly review of organic millwright training program enrollment and blockchain traceability platform adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Vegan Donuts Market
Bakery Products
Global Wafer Biscuits Market
Bakery Products
Personalized Bakery Products Market
Bakery Products
Bakers Yeast Market
Bakery Products
Sourdough Market
Bakery Products
Muffins Market
Bakery Products
Vegan Baking Mix Market
Bakery Products
Gluten-Free Bakery Products Market
Bakery Products
Bakery Cases Market
Bakery Products
Premixed Bread Flour Market
Bakery Products
Fondant Market
Bakery Products
Bakery Conditioner Market
Bakery Products
Low-Calorie Pie Market
Bakery Products
Banana Bread Market
Bakery Products
Gluten-Free Bakery Market
Bakery Products
Baking Mix, Base and Concentrate Market