
 Yeastless Dough Market | 2026-2036
Yeastless Dough Market Size, Share, and Industry Trends Forecast 2026-2036
Yeastless Dough Market Analytics
The gap between artisanal yeastless dough and mass-market alternatives is pivoting on ingredient transparency and production scale. General Mills leverages its milling infrastructure to supply consistent wheat flour bases at volume. Bob's Red Mill differentiates through stone-ground specialty flours that command shelf space in premium retail channels.
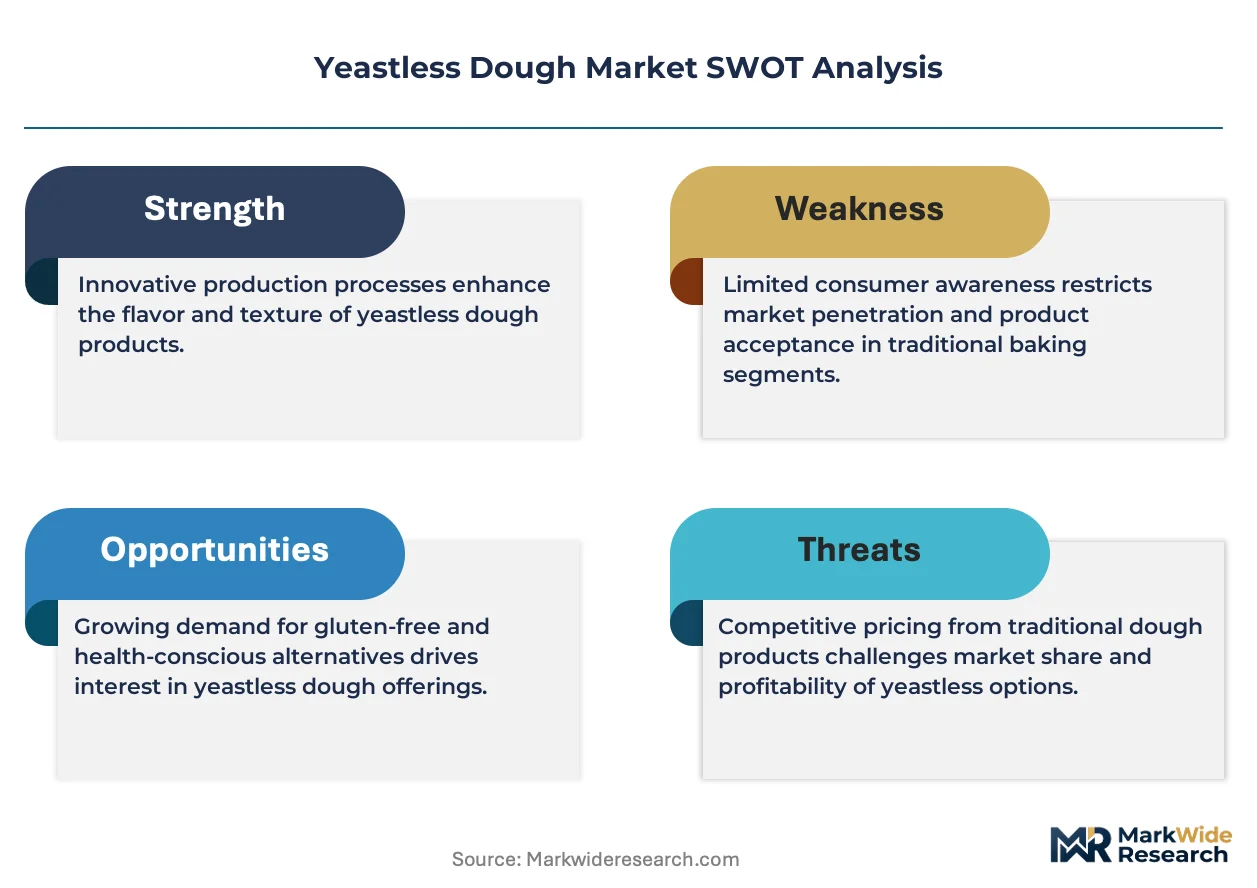
Yeastless dough refers to leavened or unleavened flour-based preparations manufactured without Saccharomyces cerevisiae, typically relying on chemical leavening agents such as sodium bicarbonate or mechanical aeration to achieve texture. The formulation serves commercial bakeries and home cooks seeking alternatives for gluten-free, low-FODMAP, or rapid-preparation applications. Flatbreads and pizzas anchor current volume due to their structural tolerance for denser, non-yeast matrices, while almond flour and coconut flour formulations capture expanding margin pools in allergen-free segments. Ready-to-bake and frozen forms dominate food service procurement, though home cooking mixes sustain higher per-unit profitability through direct-to-consumer channels.
The FDA enforces allergen labeling under FALCPA, compelling manufacturers to declare coconut, almond, and wheat cross-contact risks on yeastless dough packaging. The EU Green Deal's farm-to-fork targets pressure ingredient sourcing toward lower-carbon grain cultivation, reshaping supplier qualification for European market entry. Stakeholders must monitor evolving EFSA guidance on novel protein additives and positioning between clean-label commodity supply and functional premium formulations.
Market Dynamics
The yeastless dough market pivots on the collision between EU Green Deal carbon-accounting requirements and FDA allergen-labeling mandates, forcing manufacturers to requalify suppliers while maintaining clean-label positioning.
Growth Catalysts
- FALCPA Enforcement:The FDA's allergen declaration rules compel reformulation transparency, accelerating adoption of certified gluten-free production lines in US commercial bakeries.
- Low-FODMAP Certification:Registered dietitian protocols for irritable bowel syndrome management now specify yeastless bases, pulling volume through hospital food service and specialty retail channels.
- Mechanical Aeration Systems:Continuous mixing technology reduces batch-to-batch density variation, enabling pizza chains to standardize crust texture across franchise networks.
Market Restraints
- Almond Flour Input Volatility:California drought cycles and pollinator colony collapse disorder create price instability for allergen-free formulations.
- European Milling Concentration:Six cooperative grain processors control 70% of certified low-carbon wheat supply in Germany and France, creating qualification bottlenecks for new market entrants.
- Structural Density Limitation:Chemical leavening produces less extensible protein networks than yeast fermentation, restricting yeastless dough to flatbread and cracker categories in high-volume applications.
Strategic Opportunities
- India Urban Premium Retail:Modern trade expansion in Mumbai and Bangalore creates shelf space for imported gluten-free mixes targeting diagnosed celiac populations.
- EU Farm-to-Fork Incentives:Carbon-sequestering grain cultivation subsidies reduce input costs for manufacturers sourcing within 300-kilometer radii of processing facilities.
- Direct-to-Consumer Subscription:Monthly delivery models for frozen pizza bases bypass traditional distributor markups while capturing recurring revenue from home cooks with dietary restrictions.
Industry Challenges
- Clean-Label Formulation Expertise:Shortage of food chemists skilled in phosphate-free leavening systems delays product development timelines for mid-tier manufacturers.
- Cross-Contamination Certification:Third-party gluten-free facility audits require 18-24 month validation cycles, freezing capital in redundant production lines during qualification.
- Legacy Equipment Retrofit:Existing yeast-optimized proofing chambers and humidity controls demand capital replacement for chemical-leavening process parameters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yeastless Dough Market |
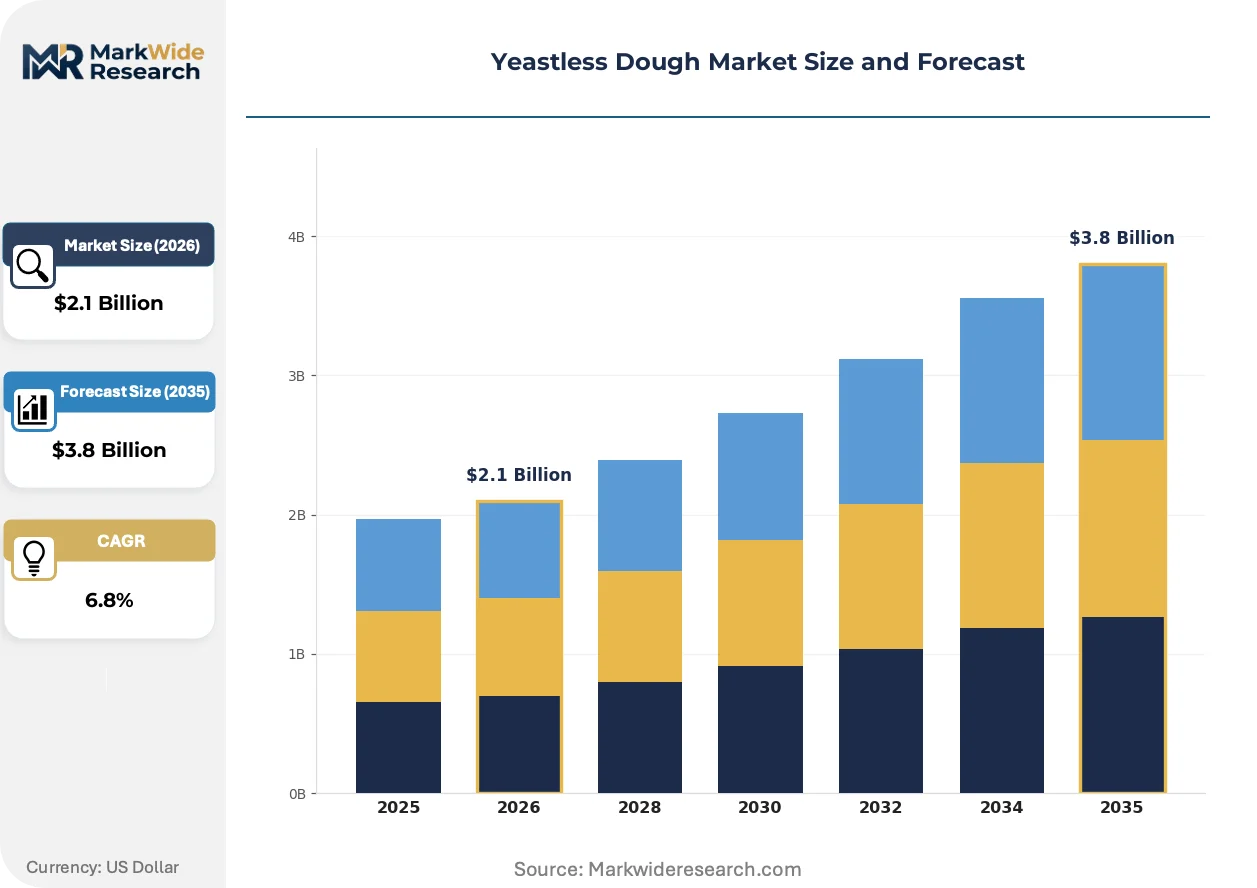
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbreads, Pizzas, Pancakes, Muffins Ingredient Type: Wheat Flour, Cornmeal, Almond Flour, Coconut Flour Application: Bakery, Food Service, Retail, Home Cooking Form: Mixes, Ready-to-Bake, Frozen, Packaged |
| Companies Covered | Hungryroot, Taste of Nature, Inc., Midland Cookie Dough, Neighbors Cookie Dough, General Mills, Bob's Red Mill, King Arthur, Bread Haus, Pillsbury, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yeastless Dough Market Evolving Landscape
Active dry yeast alternatives are fragmenting into function-specific categories as manufacturers engineer leavening systems for distinct texture outcomes rather than generic substitution.
High-pressure processing of alternative flours is overtaking conventional heat treatment for enzyme deactivation. Almond and coconut flour processors adopt cold-pasteurization to preserve lipid integrity and extend frozen dough shelf life. Commercial bakeries in Italy and Spain now specify HPP-treated bases for premium pizza export lines, compressing the viability window for untreated commodity supply.
REACH authorization requirements for sodium aluminum phosphate are forcing European manufacturers toward potassium bicarbonate and monocalcium phosphate blends. The ECHA evaluation timeline creates formulation uncertainty through 2027, pushing R&D investment into uncharacterized leavening acid combinations. Frozen pizza producers in Germany accelerate dual-formula development to maintain continental distribution regardless of authorization outcomes.
Home cooking mix buyers now prioritize single-ingredient transparency over convenience positioning. Direct-to-consumer channels displace supermarket placement for premium stone-ground wheat and heritage grain formulations. This pattern concentrates in France and Italy, where regional flour provenance carries brand equity independent of organic certification status.
Yeastless Dough Market Segmentation
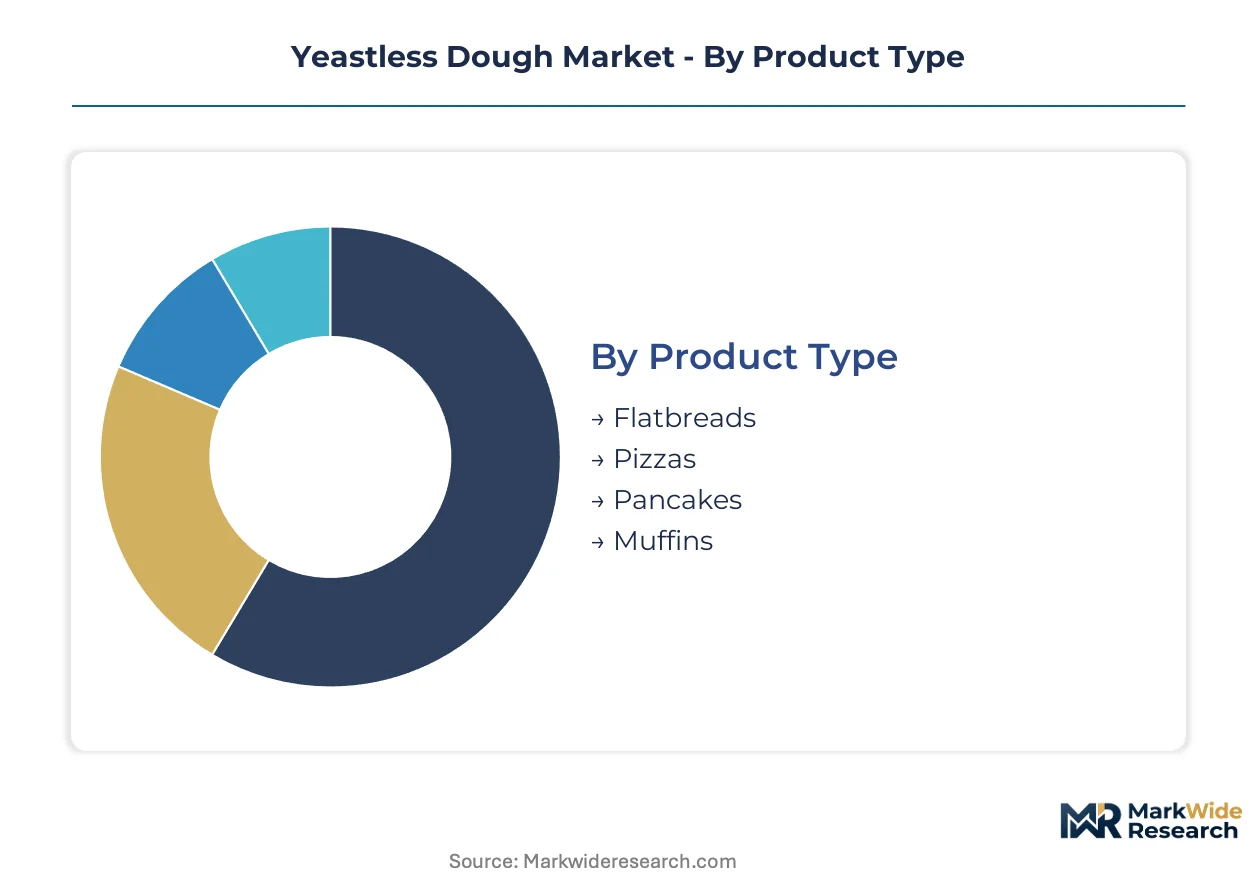
Segmentation in yeastless dough reflects divergent certification burdens across product categories. Bakery chains demand gluten-free facility audits for retail-facing lines, while food service procurement prioritizes mechanical aeration consistency over third-party certifications.
Product Type:
Certification requirements vary sharply by product geometry and moisture content. Flatbreads and pizzas face lower validation thresholds due to single-step baking, while chemically leavened muffins trigger extended shelf-stability testing under FDA acidified food regulations.
- Flatbreads:Dense, non-extensible matrices tolerate minimal protein development. Demand clusters in Mediterranean food service channels across Italy, Spain, and Greece, driven by EU Green Deal carbon-accounting pressure on imported wheat substitutes.
- Pizzas:Frozen pizza bases require precise density control for conveyor oven compatibility. German and French bakery chains specify HPP-treated almond flour formulations to extend frozen shelf life without chemical preservatives.
- Pancakes:Home cooking mix formats dominate; FALCPA allergen declarations mandatory for coconut and almond variants.
- Muffins:Chemical leavening acid selection constrained by pending ECHA REACH authorization timelines.
Leading the category by volume: Flatbreads. Growing fastest: Pizzas.
Ingredient Type:
Input cost tiers separate commodity wheat from specialty allergen-free alternatives, with carbon intensity now qualifying European supply contracts.
- Wheat Flour:Stone-ground heritage varieties command provenance premiums in French and Italian direct-to-consumer channels. Six cooperative processors in Germany and France control certified low-carbon supply, creating qualification bottlenecks for new entrants.
- Almond Flour:California drought cycles and pollinator colony collapse disorder generate price volatility. EFSA novel protein guidance monitors emerging applications.
- Cornmeal:Structural density limitations restrict use to flatbread and cracker categories.
- Coconut Flour:High-fiber matrices require modified hydration protocols; Low-FODMAP certification pulls volume through hospital food service.
Wheat flour anchors volume. Almond flour climbs the fastest on allergen-free positioning.
Application:
Customer procurement patterns split between centralized food service specifications and fragmented retail channel requirements.
- Food Service:Hospital and institutional accounts specify Low-FODMAP certified bases for irritable bowel syndrome protocols. Mechanical aeration systems enable pizza chains to standardize crust texture across franchise networks.
- Retail:Supermarket placement competes with direct-to-consumer subscription models for frozen pizza bases.
- Bakery:Commercial operations face 18-24 month gluten-free facility audit cycles.
- Home Cooking:Single-ingredient transparency priorities displace convenience positioning in premium channels.
Food service leads by volume. Home cooking gains share fastest on subscription recurring revenue models.
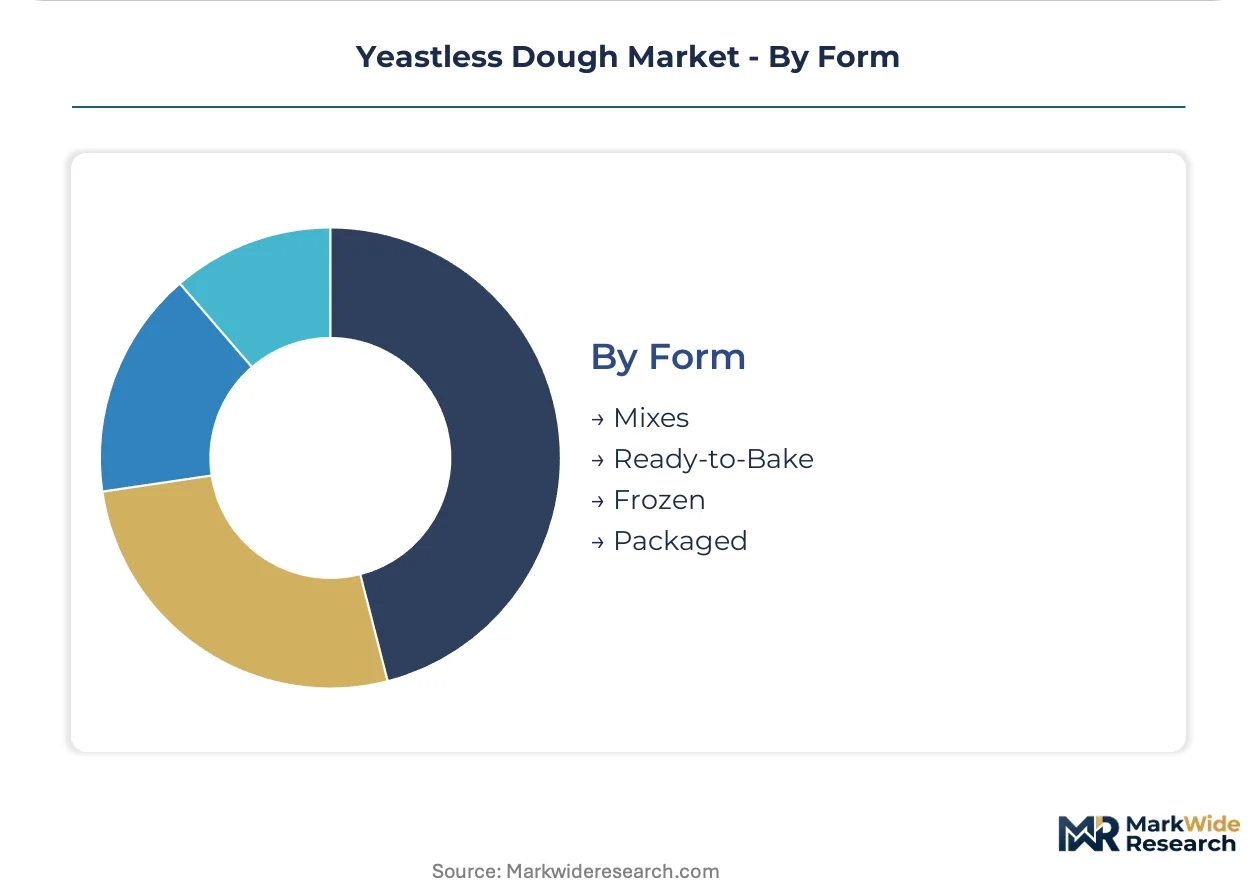
Form:
Processing intensity and capital requirements scale from dry mix packaging to frozen dough blast freezing infrastructure.
- Frozen:Blast freezing capacity constraints limit new entrants; Italian and Spanish exporters specify HPP-treated bases for premium pizza lines.
- Mixes:Direct-to-consumer channels sustain higher per-unit profitability through subscription delivery.
- Ready-to-Bake:Refrigerated logistics networks favor regional production within 300-kilometer radii.
- Packaged:Shelf-stable formats face EFSA guidance uncertainty on novel protein additives.
Frozen dominates volume. Mixes expand most quickly on e-commerce penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Milan anchors European yeastless dough innovation through its concentration of gluten-free pizza exporters and heritage wheat millers responding to EU Green Deal carbon-accounting mandates.
Germany
Bakery chains in Berlin and Munich specify HPP-treated almond flour bases for frozen pizza lines. The EU Green Deal's farm-to-fork subsidies reduce input costs for manufacturers sourcing within 300-kilometer radii of processing facilities. Six cooperative grain processors in Bavaria and Baden-Württemberg control certified low-carbon wheat supply, creating qualification bottlenecks for new entrants seeking shelf space in REWE and Edeka networks.
France
Regional flour provenance carries brand equity independent of organic certification in Paris and Lyon direct-to-consumer channels. EFSA guidance on novel protein additives shapes formulation decisions for manufacturers targeting hospital food service accounts. The Île-de-France cluster houses stone-ground heritage wheat specialists supplying premium retail placements in Monoprix and Naturalia chains.
Italy
Mediterranean flatbread demand concentrates in Rome and Naples food service channels driven by EU Green Deal pressure on imported wheat substitutes. Italian exporters specify HPP-treated bases for premium pizza lines bound for Northern Europe. The Emilia-Romagna corridor hosts mechanical aeration system manufacturers serving franchise networks standardizing crust texture across locations.
United States
FALCPA enforcement accelerates adoption of certified gluten-free production lines in Chicago and New York commercial bakeries. California almond flour processors face drought cycle volatility and pollinator colony collapse disorder price shocks. The Pacific Northwest cluster of stone-ground specialty millers commands shelf space in Whole Foods and Sprouts premium retail channels.
India
Modern trade expansion in Mumbai and Bangalore creates shelf space for imported gluten-free mixes targeting diagnosed celiac populations. FSSAI labeling requirements for allergen declarations reshape packaging decisions for multinational entrants. The Maharashtra industrial corridor hosts contract manufacturers producing Low-FODMAP certified bases for hospital food service procurement.
Yeastless Dough Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity and ingredient transparency dimensions. The vendor base stratifies between stone-ground heritage wheat specialists, chemical-leavening technology licensors, and frozen dough blast freezing operators. Three archetypes dominate: provenance-driven millers with direct-to-consumer subscription models, scale-oriented suppliers to bakery chains, and allergen-free formulation specialists. Competitive moves concentrate on gluten-free facility audit completion and HPP-treated base specification for export lines.
Within the scale-oriented tier, General Mills and Pillsbury occupy positions leveraging milling infrastructure for consistent wheat flour supply at volume. Bob's Red Mill exemplifies the provenance-driven archetype through stone-ground specialty flours commanding premium retail placement. Among heritage grain specialists, King Arthur represents clean-label positioning targeting home cooking mix buyers prioritizing single-ingredient transparency.
| Leading Market Players |
|---|
| Hungryroot |
| Taste of Nature, Inc. |
| Midland Cookie Dough |
| Neighbors Cookie Dough |
| General Mills |
| Bob's Red Mill |
| King Arthur |
| Bread Haus |
| Pillsbury |
| Others |
Value Network & Pricing Analysis
Captive milling infrastructure anchors supply position and pricing power for scale-oriented suppliers, while outsourced specialty flour sourcing fragments margin capture among provenance-driven millers responding to EU Green Deal carbon-accounting mandates.
Pricing Analysis
Yield-based pricing anchors contract negotiations between bakery chains and frozen dough suppliers, with conveyor oven compatibility and density consistency commanding premiums over commodity flatbread bases. Certification grade separates gluten-free facility-audited production from standard lines, while volume scale drives tiered arrangements across REWE, Edeka, and Monoprix procurement desks. Cost compression in almond flour formulations intensifies as California drought cycles and pollinator colony collapse disorder tighten input availability. Home cooking mix buyers through direct-to-consumer channels show least price sensitivity, prioritizing single-ingredient transparency over per-unit cost.
Supply Chain Analysis
Refrigerated freight costs from Emilia-Romagna mechanical aeration manufacturers to German bakery chains concentrate margin pressure on cross-border frozen pizza base shipments. Input sourcing draws from German and French cooperative grain processors for certified low-carbon wheat, California almond flour processors, and Italian heritage wheat millers. Single-source vulnerability sits with six Bavarian and Baden-Württemberg cooperatives controlling certified supply. Distribution runs through REWE and Edeka centralized procurement for retail, with direct-to-consumer subscription models bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is reshaping competitive positioning as players pursue upstream control over certified low-carbon grain supply to defend margin pools against EU Green Deal qualification bottlenecks.
For Market Incumbents: Anticipate REACH authorization timelines for sodium aluminum phosphate by accelerating dual-formula development with potassium bicarbonate alternatives. Secure gluten-free facility audit completion ahead of 18-24 month validation cycles to freeze out mid-tier competitors. Backward integration into stone-ground heritage wheat milling protects provenance premiums in French and Italian direct-to-consumer channels against emerging specialty millers.
For New Entrants and Emerging Players: Capture shelf space in Mumbai and Bangalore modern trade before multinational gluten-free mix suppliers establish FSSAI-compliant labeling infrastructure. Target Low-FODMAP certified hospital food service procurement in Maharashtra industrial corridor where dietitian protocol specifications pull volume through institutional accounts. Lead with subscription delivery models for frozen pizza bases to bypass entrenched distributor relationships.
For Investors and Strategic Acquirers: Exit pathways concentrate in provenance-driven millers with direct-to-consumer subscription infrastructure and completed gluten-free facility audits. Long-term viability hinges on positioning between clean-label commodity supply and functional premium formulations as EFSA guidance crystallizes on novel protein additives. Watch ECHA REACH authorization outcomes as inflection indicator for leavening acid portfolio valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Gluten-Free Facility Certification | 18-24 month audit completion locks out mid-tier competitors from REWE and Edeka shelf space. |
| Backward Integration into Heritage Wheat Milling | Stone-ground provenance capture defends margin pools against commodity flour price volatility. |
| HPP-Treated Base Specification | Cold-pasteurization adoption by Italian exporters compresses viability window for untreated commodity supply. |
| Direct-to-Consumer Subscription Launch | Monthly delivery models bypass traditional distributor markups while capturing recurring revenue from dietary-restricted home cooks. |
| Dual-Formula Leavening Development | Potassium bicarbonate alternatives hedge against ECHA REACH authorization uncertainty for sodium aluminum phosphate. |
Research Methodology
Multi-period observation of EU Green Deal carbon-accounting compliance rates, FALCPA enforcement patterns, and HPP-treated base specification trends anchored the trend analysis, supplemented by interviews with commercial bakery procurement directors, stone-ground miller operations managers, food service dietitians, frozen dough logistics coordinators, and EFSA regulatory affairs specialists. Secondary validation drew from FDA allergen labeling guidance documents, ECHA REACH authorization timelines, EU farm-to-fork subsidy disbursement records, and Italian frozen pizza export statistics. Bottom-up volume modeling across flatbread, pizza, pancake, and muffin categories triangulated against top-down wheat flour and almond flour input cost indices.
Input-output matrices mapped ingredient type, product geometry, and application channel against mechanical aeration system penetration and certification intensity over the projection horizon. Segmentation dimensions modeled included product type, ingredient tier, customer procurement pattern, and processing form. CAGRs were derived from slope analysis of normalized volume trajectories, with almond flour allergen-free positioning and home cooking subscription revenue weighted as category-specific growth amplifiers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA novel protein guidance crystallization, California almond harvest volatility, and EU cooperative grain processor consolidation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Global Bakery Product Market
Bakery Products
Instant Cake Gel Market
Bakery Products
Ready-To-Finish Bakery Products Market
Bakery Products
Gluten-Free Baking Mixes Market
Bakery Products
Europe Zwieback Market
Bakery Products
Dough Whitener Market
Bakery Products
Toasted Flour Market
Bakery Products
North America Gluten Free Bakery Mixes Market
Bakery Products
Gluten-Free Bakery Market
Bakery Products
On-The-Go Breakfast Products Market
Bakery Products
Low Calorie Muffins Market
Bakery Products
Vegan Certified Cake Mixes Market
Bakery Products
Ice Cream Cake Market
Bakery Products
Low-Carb Low-Fat Bread Market
Bakery Products
GCC Bakery Products Market
Bakery Products
Frosting, Toppings, and Decorations Market