
 Cakes and Pastries Market | 2026-2036
Cakes and Pastries Market Size, Share, and Industry Trends Forecast 2026-2036
Cakes and Pastries Market Intelligence
The artisanal retail channel is narrowing as supermarkets and convenience stores expand their in-store bakery footprints. Grupo Bimbo leverages its vertically integrated flour-to-shelf network to dominate mass-market distribution across Latin America and the United States. Yamazaki Baking Co., Ltd. anchors its position through dense convenience-store penetration in Japan, while Mondelez International competes in premium gifting segments with controlled-origin chocolate sourcing.
Cakes and pastries comprise wheat-flour-based baked goods incorporating fats, sugars, eggs, and leavening agents, with moisture content typically ranging from 15% to 35% depending on formulation and shelf-life target; these products serve as dessert, snack, or celebratory items across commercial and household consumption settings. Layer cakes and cupcakes capture the strongest margin pools in premium gifting and occasion-based purchasing, while puff pastries sustain volume leadership in foodservice breakfast and all-day snacking applications. Retail bakeries and cafes represent the fastest-growing end-user channel as experiential consumption displaces purely functional purchasing.
The FDA governs ingredient labeling and allergen declarations in the United States, while the EU Green Deal and F-Gas Regulation constrain industrial refrigeration energy profiles across European production facilities. EFSA and national food safety agencies enforce additive limits and clean-label standards that directly reformulate product development pipelines. Stakeholders must monitor evolving trans-fat restrictions and carbon-footprint disclosure requirements as these frameworks increasingly determine market access and consumer preference alignment.
Market Dynamics
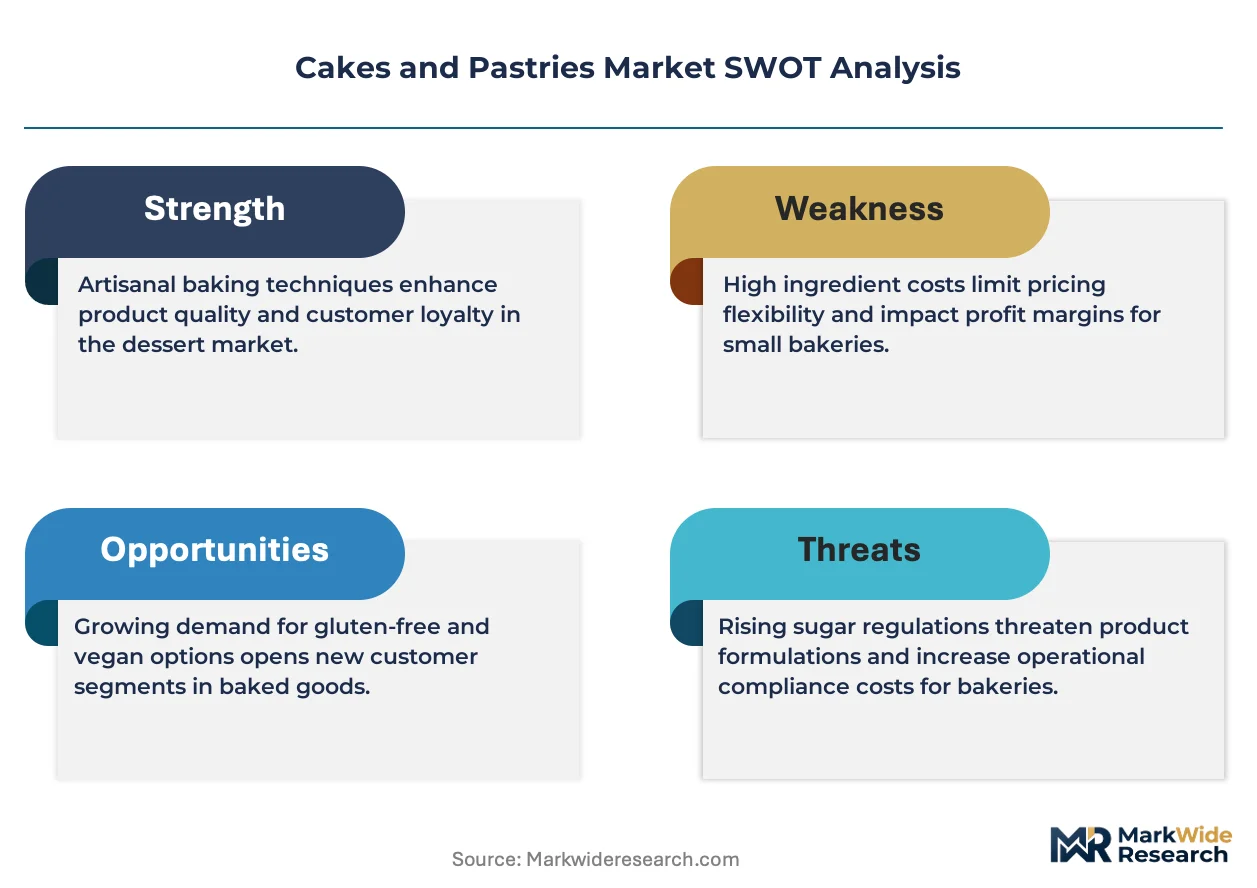
The cakes and pastries market is undergoing structural compression as clean-label mandates from the EU Green Deal force reformulation of legacy recipes while artisanal retail channels face displacement from supermarket in-store bakery expansion.
Growth Catalysts
- Cafe Channel Expansion:Coffee chains in France, Germany, and Italy are converting pastry counters into premium snacking destinations, driving experiential consumption patterns that command margin premiums over functional purchasing.
- EFSA Clean-Label Standards:Additive limits and reduced-sugar frameworks are accelerating R&D investment in natural preservation systems and alternative sweeteners across European production facilities.
- Convenience-Store Density:Japan's urban retail infrastructure sustains daily fresh pastry turnover through high-frequency, small-format distribution that minimizes waste and maximizes product rotation velocity.
Market Restraints
- Wheat Price Volatility:Input cost swings for flour and butter compress margin predictability for mid-scale producers lacking long-term commodity hedging capabilities.
- Refrigeration Energy Constraints:The EU F-Gas Regulation limits industrial cooling equipment options, extending capex timelines for facility upgrades across Italian and Spanish manufacturing bases.
- Plant-Based Substitution:Egg and dairy alternatives in vegan baking are capturing occasion-based purchasing from traditional formulations among urban consumers under 35.
Strategic Opportunities
- Gifting Segment Premiumization:Controlled-origin chocolate sourcing and limited-edition seasonal releases are opening margin pools in celebration-based purchasing occasions.
- Foodservice Breakfast Expansion:Puff pastry applications in all-day snacking menus are penetrating hotel and airline catering contracts previously dominated by standardized baked goods.
- Carbon-Footprint Disclosure:Early compliance with emerging EU environmental reporting requirements positions suppliers for preferred vendor status with sustainability-mandated retail buyers.
Industry Challenges
- Artisan Skill Scarcity:Traditional laminated dough techniques and decorative finishing capabilities are concentrating in aging workforce cohorts without adequate apprenticeship pipeline replacement.
- Legacy Equipment Integration:Automated portioning and packaging lines require retrofitting of existing bakery footprints, creating production downtime risks during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cakes and Pastries Market |
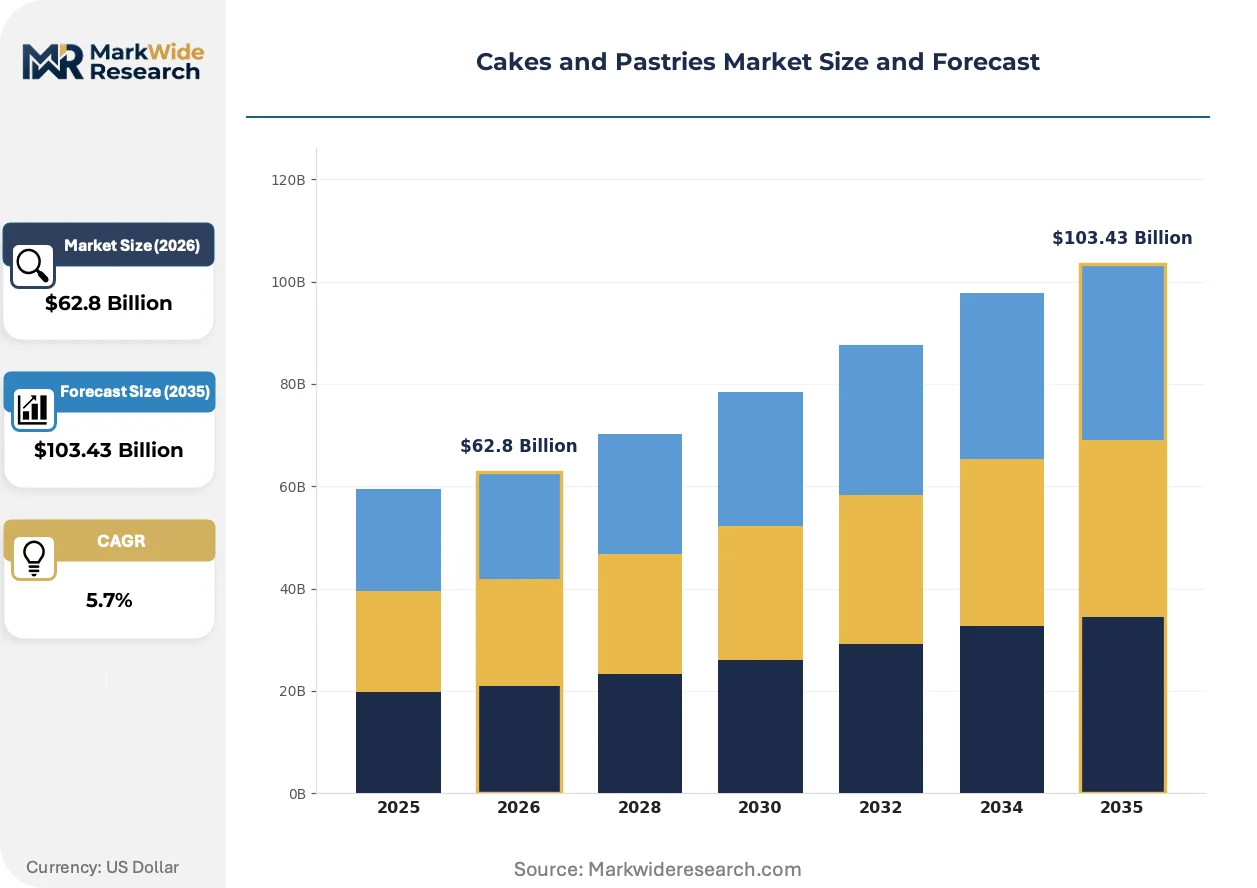
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $103.43 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Layer Cakes, Cheesecakes, Puff Pastries, Cupcakes End User: Retail Bakeries, Cafes, Restaurants, Catering Services Flavor Profile: Chocolate, Vanilla, Red Velvet, Fruit Packaging Type: Boxes, Trays, Clamshells, Custom Packaging |
| Companies Covered | McKee Foods, Finsbury Food Group, Grupo Bimbo, Kellogg Company, Associated British Foods Plc, Mondelez International, Yamazaki Baking Co., Ltd., Campbell Soup Company, Hostess Brands (J.M. Smucker Company), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cakes and Pastries Market Strategic Shifts & Innovations
Reformulation technologies and distribution infrastructure are converging to compress product development cycles while regulatory pressure accelerates the retirement of conventional preservation and labeling practices across commercial baking operations.
High-pressure processing (HPP) for extended shelf-life without chemical preservatives is rendering obsolete traditional thermal pasteurization methods for chilled cream-filled pastries. Premium retail bakeries in France and Germany are piloting HPP lines to maintain 21-day distribution windows while eliminating benzoate additives. This technology is compressing the competitive gap between artisanal freshness claims and supermarket distribution scale.
The EU F-Gas Regulation is mandating industrial refrigeration retrofits that disqualify conventional hydrofluorocarbon cooling systems from new facility approvals. European production plants must absorb 15-25% equipment cost premiums for approved natural refrigerant alternatives. Cold-chain-dependent layered cake manufacturers in Italy and Spain are consolidating production into fewer, larger facilities to amortize compliance costs across higher throughput volumes.
Experiential retail formats are displacing purely transactional bakery purchasing as destination consumption migrates from product acquisition to social occasion. Cafe-bakery hybrids in Tokyo, Paris, and New York are redesigning floor plans around Instagram-optimized display cases and open-kitchen theater. This behavioral shift is most visible in urban districts where foot traffic patterns now prioritize dwell time over convenience proximity in site selection algorithms.
Cakes and Pastries Market Segmentation
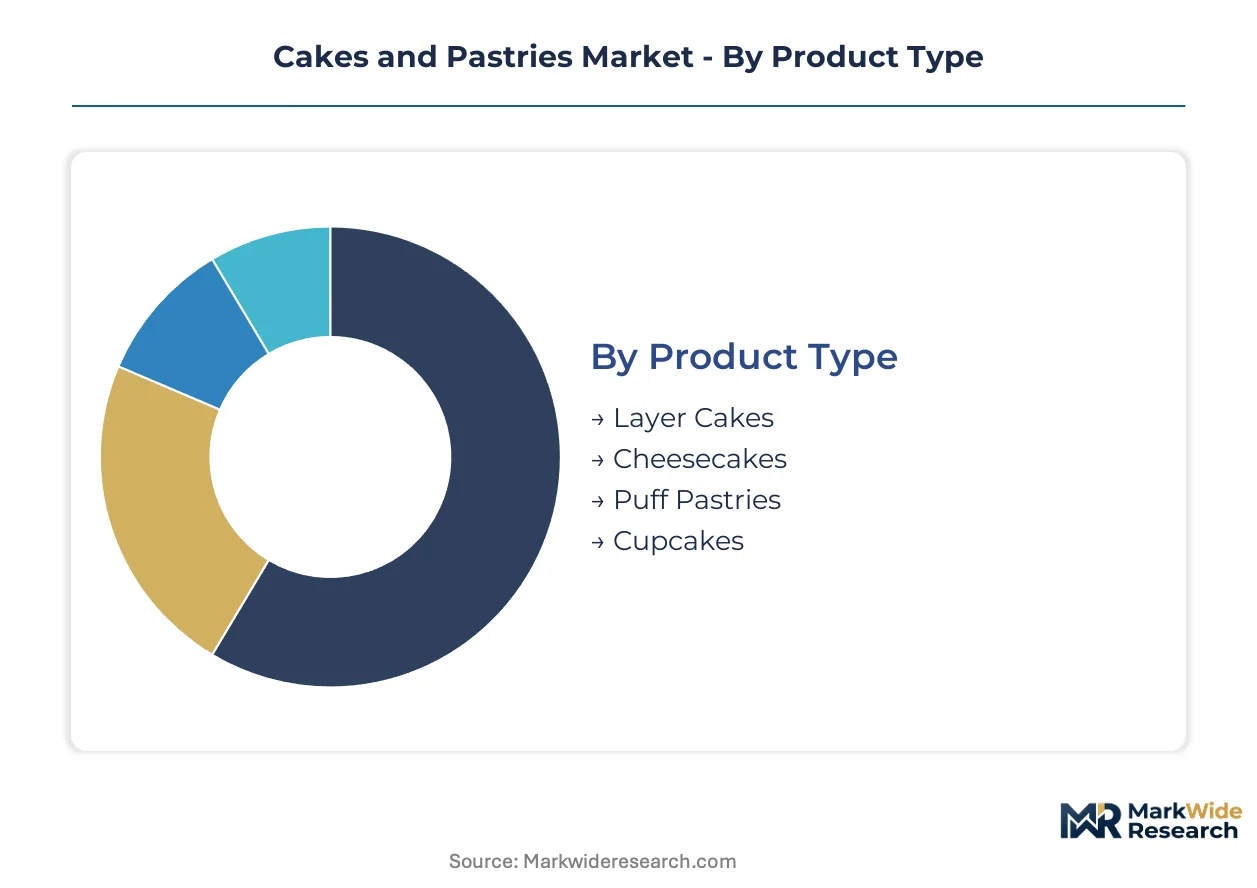
Cakes and pastries segmentation reveals how production complexity and consumption occasion intersect to determine channel strategy. Manufacturers must align formulation durability, packaging investment, and distribution frequency to match each segment's spoilage sensitivity and margin profile.
Product Type:
After-sales intensity varies sharply across product types, with cream-filled and laminated items demanding cold-chain monitoring and shorter rotation cycles than ambient-stable formats.
- Layer Cakes:Multi-tiered constructions with buttercream or fondant exteriors require precise humidity control during transport and display. Demand concentrates in celebration occasions across France and Germany, where premium gifting commands margin premiums through controlled-origin chocolate sourcing and seasonal limited editions.
- Puff Pastries:Laminated dough products achieve 27% butterfat content through precise fold-and-rest cycles, creating flaky texture profiles that degrade within hours of exposure. Foodservice breakfast applications in Tokyo and Paris drive volume, with all-day snacking menus expanding hotel and airline catering contracts previously dominated by standardized baked goods.
- Cheesecakes:Dense cream-cheese-based formulations with refrigerated shelf-life requirements.
- Cupcakes:Individual portion formats optimized for impulse purchasing and social-media-optimized presentation.
By volume, puff pastries lead through foodservice penetration. By growth pace, layer cakes are ahead through premium gifting expansion.
End User:
Channel economics diverge based on production scale versus experiential positioning, with capital requirements and labor intensity determining viable operator profiles.
- Retail Bakeries:Artisanal operators in Italy and Spain combine open-kitchen theater with Instagram-optimized display cases to extend dwell time. EFSA clean-label standards and reduced-sugar frameworks accelerate R&D investment in natural preservation systems, compressing the competitive gap between freshness claims and supermarket distribution scale.
- Cafes:Coffee chains across France, Germany, and Italy convert pastry counters into premium snacking destinations. Experiential consumption patterns command margin premiums over functional purchasing as floor-plan redesigns prioritize social occasion over transaction speed.
- Restaurants:Dessert-menu integration with plated presentation requirements.
- Catering Services:Event-based volume with logistics complexity for off-premise execution.
Retail bakeries dominate value capture through premium positioning. Cafes are climbing the fastest as experiential formats displace transactional purchasing.
Flavor Profile:
Formulation stability and ingredient sourcing transparency create tiered margin structures across taste categories.
- Chocolate:Cocoa butter and controlled-origin sourcing command price premiums in gifting segments.
- Vanilla:Madagascar and Tahitian extract grades differentiate mass-market from premium positioning.
- Red Velvet:Cream cheese frosting requirements elevate per-unit production costs.
- Fruit:Seasonal availability and HPP compatibility for extended distribution windows.
Chocolate maintains volume leadership. Red velvet is gaining share fastest through occasion-based premiumization.
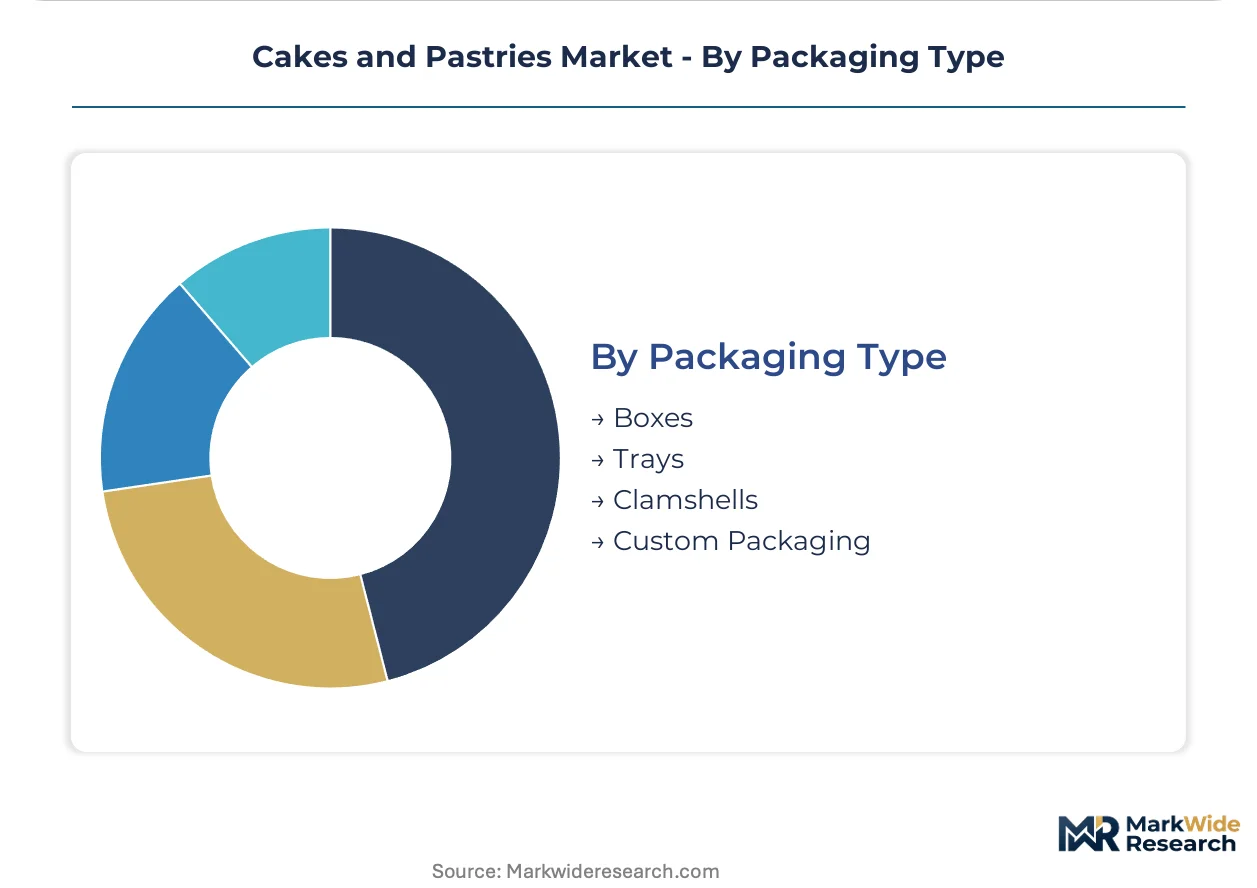
Packaging Type:
Material specifications and customization depth determine protection level and brand communication capacity.
- Boxes:Rigid board constructions for gifting presentation with tamper-evident closures.
- Trays:Corrugated or molded fiber platforms for foodservice display and transport stability.
- Clamshells:Thermoformed PET or PLA for visibility and portion protection in convenience retail.
- Custom Packaging:Seasonal and limited-edition graphics with sustainability credentialing for ESG-mandated buyers.
Clamshells lead by unit volume through supermarket in-store bakery expansion. Custom packaging shows steepest expansion trajectory through carbon-footprint disclosure requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites Europe's role as the primary distribution hub for cream-filled and laminated products requiring precise temperature management across multimodal transport networks.
United States
Convenience-store density and cafe channel expansion drive demand for individually portioned formats. FDA allergen labeling mandates and trans-fat restrictions reshape formulation standards. Chicago and New York City host dense clusters of artisanal retail bakeries converting pastry counters into experiential destinations.
Germany
EFSA clean-label standards and reduced-sugar frameworks accelerate R&D spending on natural preservation systems. The EU F-Gas Regulation forces industrial refrigeration retrofits across Bavarian and North Rhine-Westphalian production facilities. Munich anchors premium gifting segment concentration through controlled-origin chocolate sourcing.
Japan
Urban convenience-store networks sustain daily fresh pastry turnover through high-frequency, small-format distribution. METI energy-efficiency standards govern commercial baking equipment specifications. Tokyo's Shibuya and Shinjuku districts concentrate cafe-bakery hybrids redesigning floor plans around Instagram-optimized display cases.
France
Artisanal retail bakeries in Paris and Lyon combine open-kitchen theater with experiential consumption patterns commanding margin premiums. EU Green Deal carbon-footprint disclosure requirements position early-compliant suppliers for preferred vendor status. Île-de-France maintains leadership in layer cake premiumization through seasonal limited editions.
Italy
Traditional laminated dough techniques concentrate in aging workforce cohorts across Emilia-Romagna and Lombardy without adequate apprenticeship pipeline replacement. EFSA additive limits reformulate product development pipelines for puff pastry applications. Milan's foodservice sector expands all-day snacking menus into hotel and airline catering contracts.
Cakes and Pastries Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in ingredient and equipment supply. The market structures around consolidated mass-market distribution networks and fragmented artisanal retail channels. Three archetypes dominate: vertically integrated flour-to-shelf operators, dense convenience-store penetrators, and premium gifting segment specialists. Competitive moves concentrate on backward integration into captive flour milling and strategic partnerships with controlled-origin chocolate suppliers.
Among North American packaged goods operators, McKee Foods and Hostess Brands occupy positions within the mass-market snack cake tier. Grupo Bimbo exemplifies the vertically integrated archetype through Latin American and United States distribution dominance. Yamazaki Baking Co., Ltd. anchors the convenience-store density model. Mondelez International sits within the premium gifting segment through controlled-origin sourcing strategies.
| Leading Market Players |
|---|
| McKee Foods |
| Finsbury Food Group |
| Grupo Bimbo |
| Kellogg Company |
| Associated British Foods Plc |
| Mondelez International |
| Yamazaki Baking Co., Ltd. |
| Campbell Soup Company |
| Hostess Brands (J.M. Smucker Company) |
| Others |
Cost & Logistics Intelligence
The Port of Rotterdam's cold-chain corridors impose freight cost differentials that stratify European cream-filled pastry pricing from ambient-stable formats, concentrating margin power among producers with captive distribution infrastructure while forcing mid-scale competitors into contract-manufacturing arrangements that surrender pricing autonomy.
Pricing Analysis
Volume-discount tiering separates artisanal retail bakeries from mass-market in-store bakery suppliers, with premium gifting segments commanding spreads through controlled-origin chocolate sourcing and seasonal limited editions. Price differentiation rests on certification grade—EFSA clean-label compliance versus conventional additive formulations—and geographic delivery cost premiums for refrigerated last-mile service. Cost compression in mid-tier puff pastry applications is intensifying because wheat and butter commodity hedging capabilities concentrate among vertically integrated operators. Supermarket private-label buyers exhibit highest price sensitivity, while cafe channel operators prioritize product rotation velocity over unit cost.
Supply Chain Analysis
Upstream feedstock flows for wheat flour and dairy inputs concentrate in France, Germany, and the United States, with butterfat supply tethered to seasonal dairy production cycles in Normandy and Bavaria. Raw material dependencies center on specialty grains for laminated dough performance, cocoa butter for premium chocolate applications, and natural refrigerants for EU F-Gas Regulation compliance. Single-source vulnerability runs through aged artisan workforce cohorts in Italy's Emilia-Romagna region where traditional laminated techniques concentrate without apprenticeship pipeline replacement. Distribution runs through dense convenience-store networks in Japan's urban corridors and supermarket in-store bakery expansions across Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cakes and pastries market sits at a platform-economics inflection where cafe-bakery hybrid formats are redefining customer acquisition through Instagram-optimized experiential design rather than product-centric value propositions.
For Market Incumbents: Harden cold-chain infrastructure ownership against refrigeration energy cost escalation driven by EU F-Gas Regulation mandates, while securing captive flour milling capacity to buffer wheat price volatility. Consolidate artisan skill concentration through apprenticeship pipeline investments in Italy and Spain, where aging workforce cohorts threaten laminated dough quality consistency. Prioritize backward integration into controlled-origin chocolate sourcing to defend premium gifting segment margins from specialty couverture suppliers. For New Entrants and Emerging Players: Germany's reduced-sugar reformulation gap offers white-space entry through natural preservation system partnerships with Bavarian R&D facilities. Target carbon-footprint disclosure compliance as a differentiated procurement credential for ESG-mandated retail buyers in France and the Netherlands. Deploy direct-to-cafe distribution models that bypass supermarket slotting fee barriers, leveraging high-frequency small-batch production for daily fresh turnover in urban convenience-store networks. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate parent portfolios where bakery divisions lack strategic fit yet retain dense regional distribution infrastructure. Long-term viability favors operators with demonstrated clean-label reformulation capabilities and refrigerated logistics integration. Monitor EFSA additive limit enforcement timelines as the signal to watch for accelerated industry consolidation among conventional formulation-dependent producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flour Milling | Captive wheat supply buffers Grupo Bimbo's Latin American and US operations against commodity volatility. |
| High-Pressure Processing Line Deployment | HPP technology adoption by French premium bakeries compresses the freshness-versus-scale competitive gap. |
| Natural Refrigerant Retrofit Compliance | EU F-Gas Regulation adherence qualifies Italian and Spanish facilities for preferred vendor status with sustainability-mandated buyers. |
| Controlled-Origin Chocolate Sourcing Partnership | Mondelez International's premium gifting positioning rests on traceable cocoa supply chain credentials. |
| Cafe-Bakery Hybrid Format Expansion | Tokyo's Shibuya district exemplifies experiential retail redesign around dwell-time optimization and social-media visibility. |
Research Approach
A spread of perspectives from artisan bakery operators, industrial production facility managers, cafe chain procurement directors, and refrigerated logistics specialists converged on the working assumptions underlying demand projections. Primary interviews with these stakeholders combined with secondary validation against customs records, EU EFSA additive regulation filings, and trade association production statistics. Bottom-up segment sizing triangulated against top-down macroeconomic consumption indicators to establish forecast boundaries.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeled across product type, end-user channel, flavor profile, and packaging format dimensions. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points including EU Green Deal implementation timelines and F-Gas Regulation enforcement phases. Wheat commodity futures curves and refrigerated freight cost indices informed input cost assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity consolidation moves by vertically integrated mass-market operators would shift outcomes beyond modeled ranges. Cross-checking against retail scanner data from France, Germany, and Japan is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
North America Gluten Free Bakery Mixes Market
Bakery Products
Bread Crumbs Market
Bakery Products
Bread Improver Market
Bakery Products
No-Fat Cake Market
Bakery Products
Middle East and Africa Fortified Bakery Products Market
Bakery Products
Ice Cream Cake Market
Bakery Products
Biscuit Mixes Market
Bakery Products
Personalized Bakery Products Market
Bakery Products
Organic Bread Flour Market
Bakery Products
Layer Cake Mixes Market
Bakery Products
Gluten-Free Bread Market
Bakery Products
Pizza Crust Market
Bakery Products
Baking Mixes Market
Bakery Products
Asia-Pacific Baked Food and Cereals Market
Bakery Products
Pastries Market
Bakery Products
Qatar Bakery Product Market