
 Corn Gluten Meal Market | 2026-2036
Corn Gluten Meal Market Size, Share, and Industry Trends Forecast 2026-2036
Corn Gluten Meal Market Analysis
The EU Green Deal is restructuring feed ingredient procurement across European livestock operations, tightening sustainability criteria for imported proteins. Cargill Incorporated leverages its integrated wet-milling network to secure consistent CGM supply for regional feed formulators. Archer Daniels Midland Company anchors North American production capacity through its Decatur, Illinois processing complex. Bunge Limited competes on export logistics, moving Gulf Coast volumes into Asian and Middle Eastern feed markets.
Corn gluten meal is the protein-rich byproduct of corn wet-milling, typically containing 60% crude protein and 3% crude fiber, recovered after starch extraction and sold as a dried feed ingredient or organic fertilizer. Its primary commercial purpose centers on delivering cost-competitive protein and phosphorus to livestock rations while diverting waste from ethanol and sweetener production. Animal Feed dominates volume consumption among product types, reflecting entrenched demand from poultry and aquaculture sectors where CGM displaces fishmeal and soybean meal. Organic Fertilizer applications are expanding fastest, as granular formulations gain traction among agronomists responding to soil health mandates and synthetic nitrogen restrictions. The Herbicide segment occupies a narrower niche, where CGM's pre-emergent weed suppression properties serve organic and transitional farming systems.
The United States Department of Agriculture and the Environmental Protection Agency jointly shape CGM market access through biofuel mandates that expand wet-milling output and nutrient management rules that constrain manure-based alternatives. The European Commission's REACH framework and F-Gas Regulation indirectly elevate CGM fertilizer appeal by raising compliance costs for synthetic nitrogen production. China's Ministry of Agriculture and Rural Affairs and its national feed safety standards influence import acceptance criteria for foreign-origin protein meals. Stakeholders must monitor how carbon border adjustments and feed carbon intensity scoring reshape competitive positioning between corn-derived and oilseed proteins.
Market Dynamics
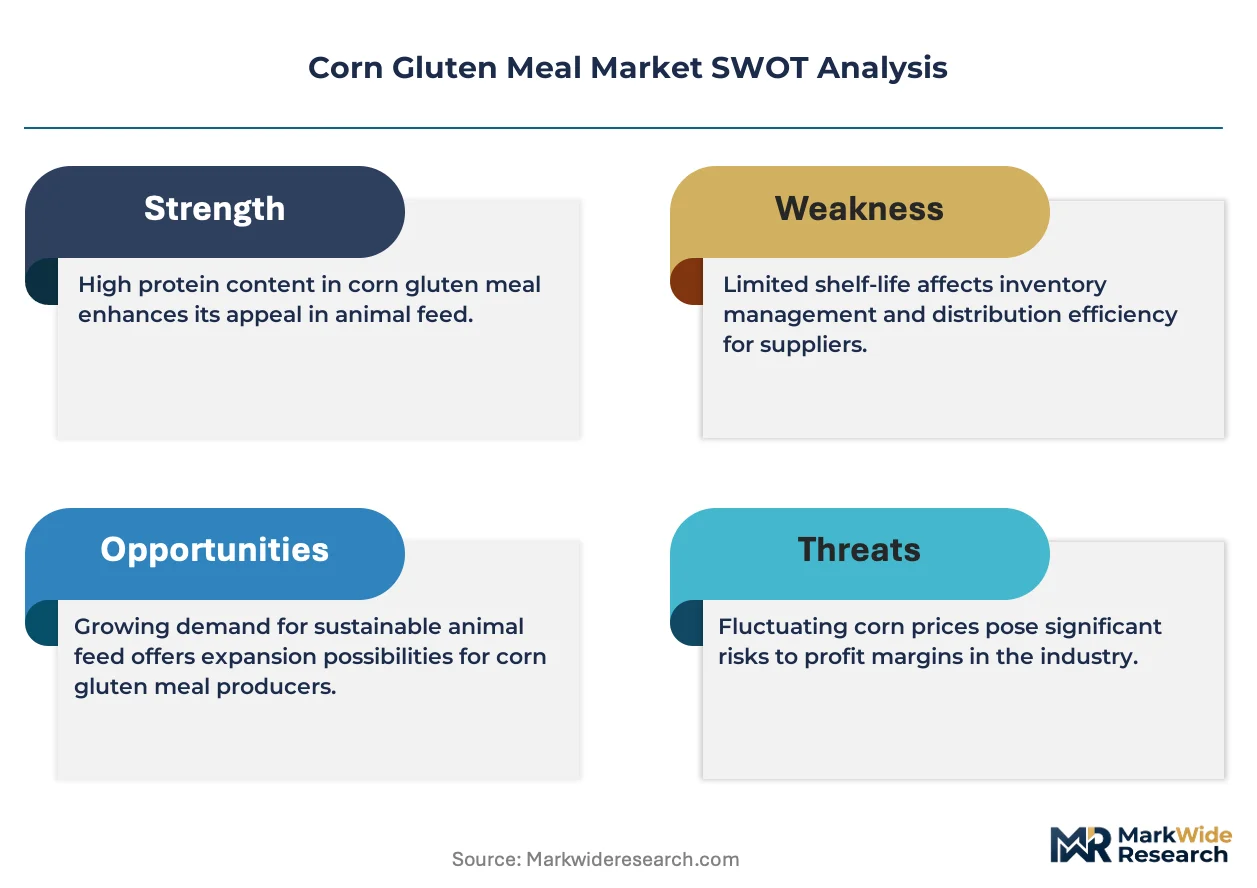
Ethanol policy mandates in the United States are expanding wet-milling capacity faster than feed demand growth, creating persistent supply surpluses that compress protein meal pricing and redirect corn gluten meal toward fertilizer and specialty applications.
Growth Catalysts
- USDA Biofuel Mandates:Renewable Fuel Standard requirements sustain ethanol production volumes, ensuring steady corn wet-milling output and abundant CGM co-product availability for protein markets.
- Aquaculture Formulation:Salmon and shrimp producers in Southeast Asia are substituting fishmeal with corn gluten meal to reduce feed costs and improve phosphorus digestibility in intensive pond systems.
- Soil Health Mandates:The EU Green Deal's Farm to Fork strategy restricts synthetic nitrogen application rates, elevating organic fertilizer demand for corn-derived soil amendments.
Market Restraints
- Input Cost Volatility:Corn price swings driven by drought cycles in the US Corn Belt transmit directly to CGM production economics, eroding margin stability for toll processors.
- Supply Concentration Risk:Wet-milling infrastructure clusters in Illinois, Iowa, and Indiana create geographic vulnerability to regional weather shocks and logistics disruptions.
- Protein Substitution Threat:Fermented single-cell proteins from precision fermentation startups are targeting poultry feed applications where CGM currently dominates cost-sensitive rations.
Strategic Opportunities
- Brazilian Feed Market Penetration:Poultry integrators in São Paulo state are seeking non-soy protein alternatives to diversify ration formulations and reduce dependence on domestic soybean meal.
- Controlled-Release Fertilizer Blends:Granular CGM formulations with polymer coatings are capturing turf management contracts from municipal golf courses and sports field operators.
- Carbon Intensity Scoring:California's Low Carbon Fuel Standard and pending EU carbon border adjustments reward lower-emission feed ingredients, favoring domestically sourced corn proteins over imported oilseeds.
Industry Challenges
- Quality Certification Timelines:Organic certification bodies require 18-24 month transition periods for wet-milling facilities converting to non-GMO corn streams, delaying premium market access.
- Legacy Equipment Integration:Drying and milling systems designed for 60% protein output struggle to achieve the 65%+ protein specifications demanded by marine feed formulators without capital retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn Gluten Meal Market |
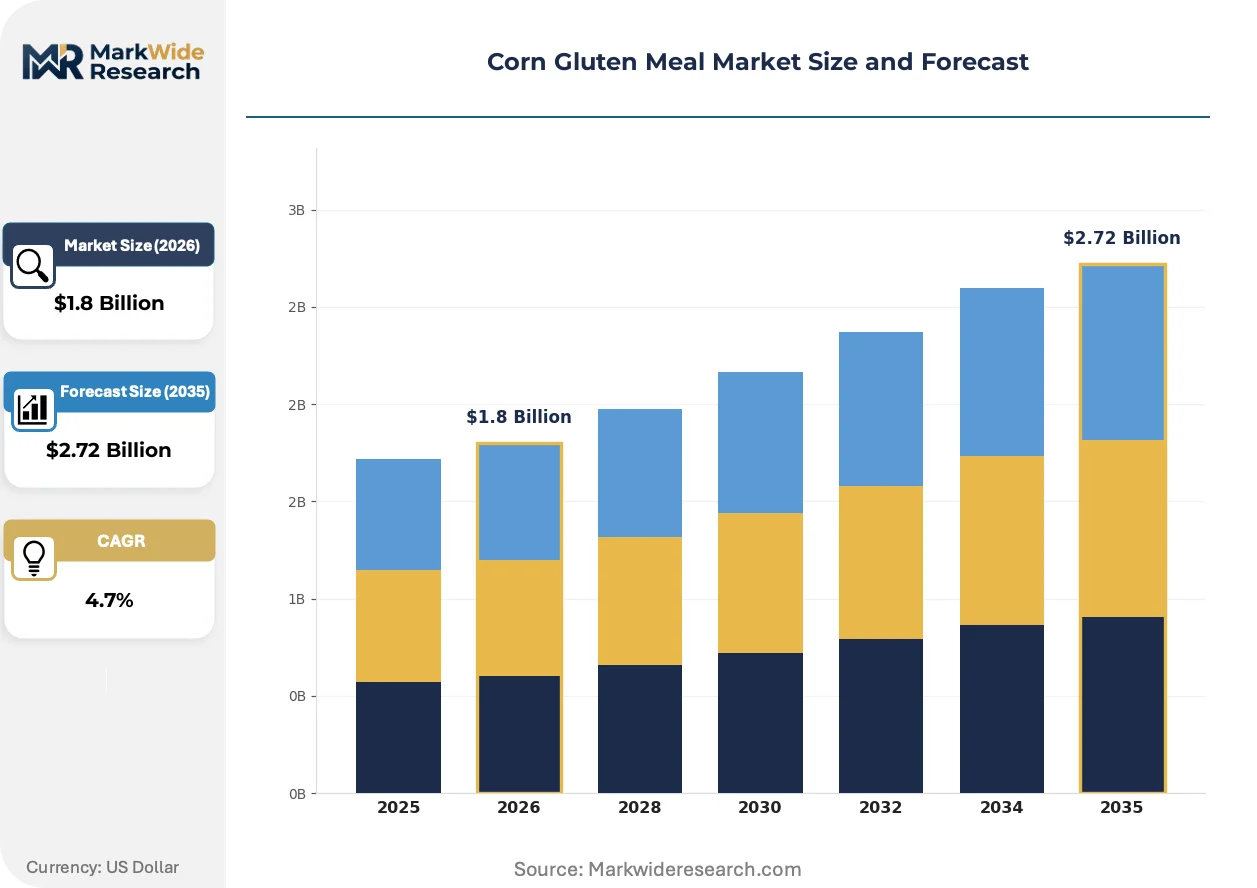
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Animal Feed, Organic Fertilizer, Herbicide, Dietary Supplement Application: Agriculture, Food Processing, Pharmaceuticals, Personal Care Form: Granular, Powdered, Liquid, Organic End User: Agronomists, Livestock Farmers, Food Manufacturers, Research Laboratories |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Bunge Limited, Ingredion Incorporated, Grain Processing Corporation, Tate & Lyle PLC, Roquette Frères, Tereos Group, AGRANA Beteiligungs-AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn Gluten Meal Market Emerging Trajectories
Processing technology and regulatory frameworks are converging to transform corn gluten meal from a commodity co-product into a precision-formulated input for specialized nutrition and crop management applications.
Enzymatic protein concentration systems are expanding into high-value feed segments. These membrane filtration and protease treatments boost crude protein content from 60% to 70% while reducing fiber carryover. Aquafeed compounders in Norway and Chile are adopting these upgraded meals for Atlantic salmon smolt diets. The technology is expanding into premium rations where protein digestibility coefficients determine formulation economics.
REACH framework amendments in the European Union are tightening contaminant thresholds for heavy metals and mycotoxins in imported feed materials. This regulatory compression is forcing third-country suppliers to implement pre-shipment testing protocols and certified storage chains. Spanish and Dutch feed compounders are responding by consolidating procurement through approved vendor lists with documented traceability systems.
Integrated crop-livestock operations are internalizing protein sourcing decisions. Large Midwestern grain handlers are constructing on-site feed mills that consume wet-milling co-products directly, bypassing traditional merchant distribution channels. This vertical absorption is most visible in Iowa and Nebraska, where ethanol-plant-adjacent finishing operations capture CGM at moisture levels that eliminate drying costs.
Corn Gluten Meal Market Segmentation
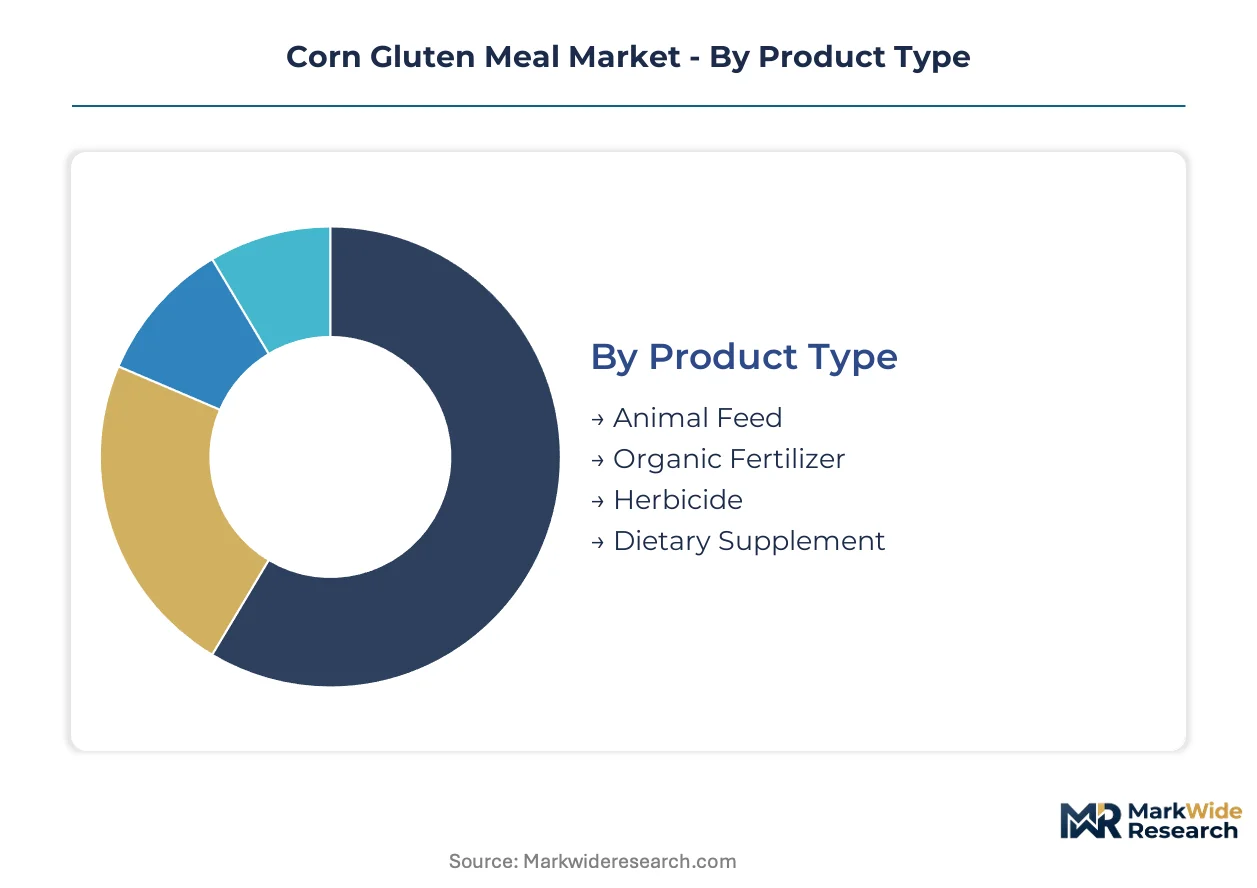
Corn gluten meal's commercial trajectory hinges on how protein concentration, organic certification status, and application-specific formulation requirements partition value across buyer segments. Wet-milling processors calibrate drying protocols and particle sizing to match divergent end-use specifications, creating tiered margin structures within what appears as a homogeneous co-product stream.
Product Type:
Animal Feed formulations demand FDA and AAFCO nutritional adequacy verification, while Organic Fertilizer grades require OMRI listing and state-level fertilizer registration. Herbicide applications fall under EPA biopesticide exemption protocols, and Dietary Supplement segments trigger FDA cGMP facility audits and NDI notification requirements for novel protein concentrates.
- Animal Feed:Standard 60% protein meal serves as the workhorse specification for poultry and aquaculture compounders. Demand concentrates in Iowa and Nebraska feed mills adjacent to ethanol plants, where wet-milling output bypasses drying stages and captures moisture-premium economics. USDA biofuel mandates sustain supply volumes that outpace domestic feed absorption, pressuring pricing into fertilizer displacement.
- Organic Fertilizer:Granular formulations with enhanced nitrogen release profiles command premium placement against synthetic urea. EU Green Deal nitrogen restrictions are redirecting procurement toward corn-derived soil amendments in Dutch and Spanish horticulture operations. State fertilizer regulators in California and Florida impose heavy metal testing burdens that filter supplier eligibility.
- Herbicide:Pre-emergent weed suppression properties serve organic and transitional farming systems under EPA biopesticide exemption frameworks.
- Dietary Supplement:Protein isolate fractions require FDA cGMP compliance and novel food consultations under EFSA guidance for European market access.
Leading the category by volume: Animal Feed. Growing fastest: Organic Fertilizer.
Application:
Cost tier stratification separates commodity agriculture inputs from pharmaceutical-grade protein isolates requiring multi-stage purification.
- Agriculture:Soil amendment and crop protection applications dominate tonnage throughput. Midwestern grain handlers in Illinois and Indiana integrate CGM into precision fertility programs, leveraging local wet-milling proximity to undercut imported organic nitrogen sources. State nutrient management plans in Chesapeake Bay watershed states restrict manure applications, opening substitution opportunities for corn-derived fertilizers.
- Food Processing:Protein fortification in baked goods and meat alternatives demands allergen-free handling protocols and kosher/halal certification. FDA food facility registration and preventive controls rule compliance add fixed cost burdens that favor larger wet-milling operations with dedicated food-grade production lines.
- Pharmaceuticals:Excipient and culture media applications require USP-grade material characterization and endotoxin testing.
- Personal Care:Hydrolyzed protein fractions for cosmetic formulations trigger REACH registration obligations in European markets.
Volume concentration: Agriculture. Steepest expansion trajectory: Food Processing.
Form:
Particle morphology determines handling economics and dissolution kinetics across broadcast fertilizer versus precision feed weighing applications.
- Granular:Sized for mechanical spreader compatibility in turf management and row-crop fertility. Municipal golf courses in Arizona and Florida specify sieve-grade consistency for uniform application. Polymer coating technologies are extending nitrogen release windows to match crop uptake curves, capturing premium positioning against uncoated alternatives.
- Powdered:Fine milling enables homogeneous incorporation into pelleted aquafeed and extruded pet food matrices. Dust control regulations in OSHA and state workplace safety frameworks elevate capital requirements for powder handling infrastructure.
- Liquid:Suspension concentrates for foliar feeding and hydroponic systems require stabilizing agents and pH buffering.
- Organic:Certified non-GMO and synthetic-additive-free grades carry OMRI and state organic program approvals for premium horticulture channels.
Granular commands the largest share. Organic certification tier is climbing the fastest.
End User:
Customer sophistication and procurement scale create divergent specification tolerances and contract structures.
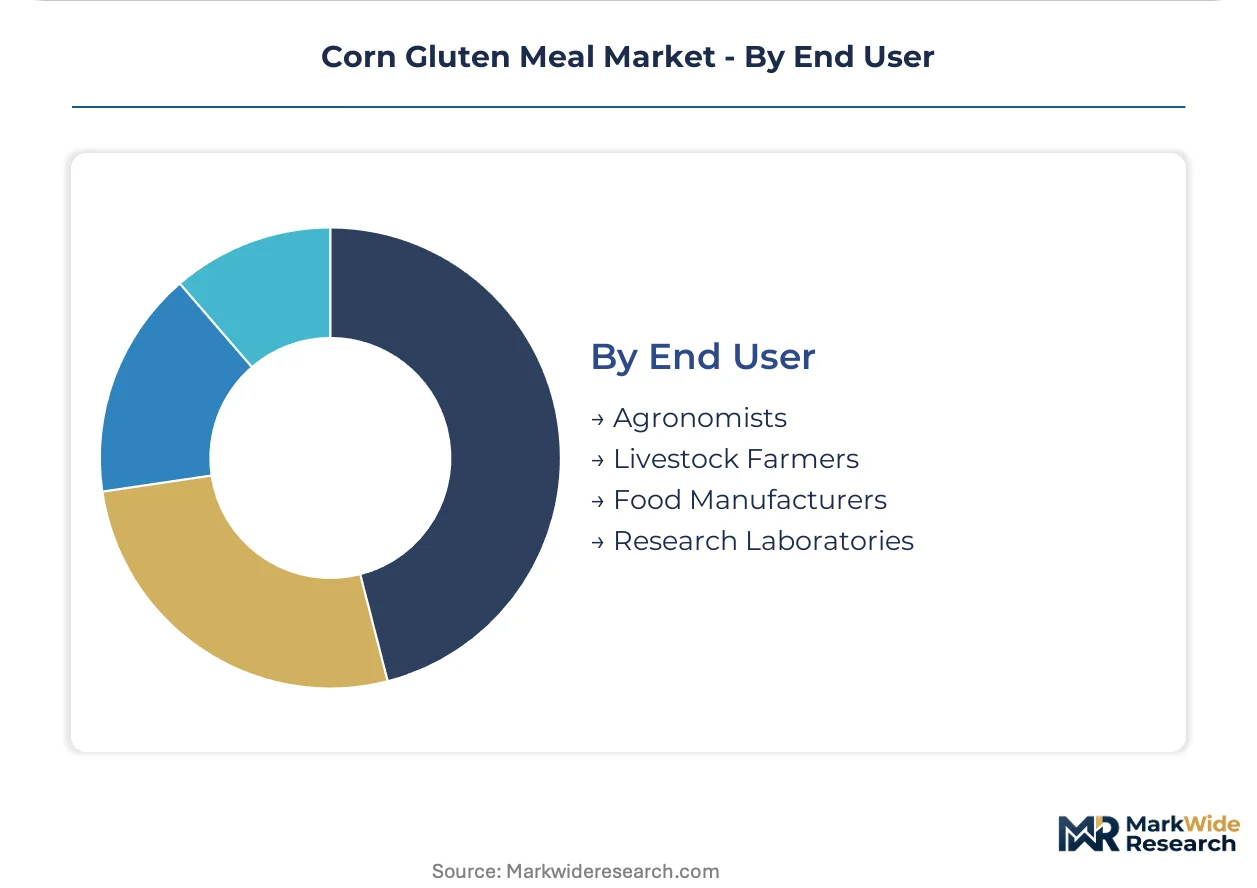
- Livestock Farmers:Integrated poultry and swine operations in the US Corn Belt negotiate direct offtake agreements with wet-milling facilities, locking in protein supply at moisture levels that eliminate merchant drying margins. Farm-level feed milling investments in Iowa and Nebraska are absorbing CGM volumes that previously flowed through regional distributors.
- Agronomists:Independent crop consultants and cooperative extension specialists specify soil amendment programs for commercial growers. Certification requirements vary by state fertilizer licensing boards, with Florida and California imposing continuing education mandates for recommendation authority.
- Food Manufacturers:R&D-scale buyers test protein functionality in novel applications before committing to supply agreements.
- Research Laboratories:Academic and government institutions purchase analytical-grade material for nutritional and agricultural science protocols.
Livestock Farmers represent the dominant demand source. Agronomists are gaining share fastest as soil health advisory services expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Decatur, Illinois anchors wet-milling capacity for corn gluten meal, with Archer Daniels Midland's processing complex supplying protein meal across North American feed markets. Corn Belt ethanol policy and starch extraction infrastructure create supply density that shapes trade flows into Asia and Europe.
United States
Integrated poultry operations in Iowa and Nebraska negotiate direct offtake agreements with ethanol-adjacent wet-milling facilities. USDA Renewable Fuel Standard mandates sustain corn processing volumes that generate abundant CGM co-product. The Decatur, Illinois processing corridor supplies standard 60% protein meal to regional feed compounders.
Brazil
Poultry integrators in São Paulo state seek non-soy protein alternatives to diversify ration formulations beyond domestic soybean meal dependence. The country's national agricultural regulator enforces feed safety standards that govern import acceptance for foreign-origin protein meals. Southern grain handlers evaluate corn wet-milling investments to capture ethanol policy tailwinds.
China
Aquaculture formulators in coastal provinces substitute fishmeal with corn gluten meal to reduce phosphorus loading in intensive shrimp pond systems. The Ministry of Agriculture and Rural Affairs sets national feed safety standards that influence protein meal procurement criteria. Yangtze River Delta feed mills source imported CGM through port terminals in Shanghai and Ningbo.
Netherlands
Dutch horticulture operations redirect procurement toward corn-derived soil amendments under EU Green Deal nitrogen application restrictions. REACH framework amendments tighten contaminant thresholds for heavy metals in imported feed materials. Rotterdam port terminals distribute CGM fertilizer grades into German and Belgian agricultural markets.
Norway
Atlantic salmon smolt producers adopt enzymatically concentrated CGM with 70% protein content for premium aquafeed formulations. EFSA guidance shapes novel food consultations for protein isolate market access. Bergen-area aquafeed compounders test membrane-filtered meal fractions in marine hatchery trials.
Corn Gluten Meal Market Vendor Landscape
Premium-margin players sit above commodity-margin players across protein concentration tiers, with enzymatic filtration specialists capturing aquafeed premiums against standard 60% protein merchants. The market structure concentrates around integrated agribusiness conglomerates with captive wet-milling networks and independent toll processors serving regional feed markets. Three archetypes dominate: ethanol-integrated starch extractors, merchant protein refiners, and specialty fertilizer formulators. Competitive moves center on backward integration into corn origination and geographic expansion into Southeast Asian aquafeed channels.
Within the integrated agribusiness tier, Cargill Incorporated and Archer Daniels Midland Company exemplify ethanol-integrated starch extractors with Corn Belt processing density. Bunge Limited occupies a position among merchant protein refiners leveraging Gulf Coast export logistics for Middle Eastern and Asian feed markets. These three companies represent the scale-driven end of wet-milling capacity, anchoring supply availability that shapes pricing dynamics across standard and premium protein grades.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Bunge Limited |
| Ingredion Incorporated |
| Grain Processing Corporation |
| Tate & Lyle PLC |
| Roquette Frères |
| Tereos Group |
| AGRANA Beteiligungs-AG |
| Others |
Supply Flow & Price Mechanics
Protein concentration divergence between standard 60% and enzymatically upgraded 70% grades creates parallel pricing regimes that reshape procurement patterns across feed compounders and fertilizer distributors. This bifurcation manifests in contract structures: aquafeed formulators in Norway pay yield-linked premiums for membrane-filtered isolates, while Midwestern livestock operations capture moisture-adjusted spot pricing from ethanol-adjacent wet-milling facilities.
Pricing Analysis
Yield-based pricing anchors contract negotiations, with aquafeed compounders indexing payments to protein digestibility coefficients in Atlantic salmon smolt trials. Price differentiation separates certified organic grades carrying OMRI listing from commodity 60% protein meal sold on spot markets. Pricing pressure stems from precision fermentation startups targeting poultry rations with single-cell protein substitutes. Contract-based long-term offtake agreements dominate integrated livestock operations, while spot trading concentrates among regional distributors serving price-sensitive agronomists.
Supply Chain Analysis
Skilled technician availability in Illinois, Iowa, and Indiana constrains wet-milling capacity expansion despite abundant corn feedstock. Supply concentrates in the United States Corn Belt, with secondary nodes emerging in Brazil and China as ethanol policy spreads. Raw material dependencies center on No. 2 yellow corn, natural gas for drying operations, and polymer inputs for controlled-release fertilizer coatings. Single-source vulnerability runs through Decatur-area processing clusters exposed to regional drought cycles. Distribution runs through merchant refiners for export markets and direct offtake agreements for integrated livestock operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic protein concentration technology is displacing legacy drying-milling systems, forcing wet-milling operators to choose between capital retrofit for premium grades or margin compression in commoditized feed markets.
For Market Incumbents: Anchor defensible positioning through backward integration into non-GMO corn origination networks and captive supply of polymer-coated fertilizer formulations. Precision fermentation entrants threaten poultry feed market share; counter through exclusive multi-year offtake contracts with salmon aquafeed compounders in Norway and Chile. Certification investment in OMRI and state organic program approvals creates switching costs against merchant competitors. For New Entrants and Emerging Players: E-commerce procurement platforms for specialty organic fertilizer grades offer the lowest customer acquisition friction in this market. White-space targets include Brazilian poultry integrators seeking soy diversification and municipal turf management contractors in Arizona and Florida requiring sieve-grade granular consistency. Direct-to-grower digital channels bypass established distributor networks in fragmented agronomist segments. For Investors and Strategic Acquirers: Re-rating potential sits with enzymatic filtration specialists given aquafeed premium capture and EFSA novel food consultation progress. Long-term viability favors operators with integrated wet-milling networks rather than toll-dependent merchant processors. Watch California Low Carbon Fuel Standard implementation and pending EU carbon border adjustment mechanisms as demand inflection signals for domestically sourced corn proteins.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Protein Concentration Capacity | Membrane filtration upgrades capture 70% protein premiums from Norwegian salmon feed compounders. |
| Non-GMO Corn Origination Integration | Backward control over grain supply secures 18-24 month organic certification timelines. |
| Controlled-Release Fertilizer Formulation | Polymer coating technology extends nitrogen release windows for California and Florida horticulture. |
| Direct Offtake Agreements with Livestock Integrators | Moisture-premium contracts with Iowa and Nebraska poultry operations eliminate merchant drying margins. |
| EFSA Novel Food Consultation Pathway | Regulatory approval unlocks protein isolate access to European dietary supplement channels. |
Methodological Framework
Independent corroboration across wet-milling plant managers, aquafeed formulation scientists, and state fertilizer regulators underwrites the qualitative findings in this study. Primary interviews with procurement leads at integrated poultry operations, distribution channel partners in Rotterdam and Shanghai, and technical R&D directors at enzymatic filtration specialists were combined with secondary validation. Secondary sources include USDA biofuel production statistics, EFSA novel food consultation registers, EU REACH framework amendment texts, and customs trade data for corn gluten meal shipments. Bottom-up volume modeling and top-down value triangulation were applied across the analysis window.
Rate-of-change decomposition separated volume growth from price realization across protein concentration tiers, organic certification status, and application-specific formulation requirements. The analytical framework modeled demand by product type, end-use industry, geographic production hub, and regulatory compliance tier. CAGRs were derived from segment-level trajectory aggregation. Industry-specific forecast inputs include USDA Renewable Fuel Standard volume mandates and EU Green Deal nitrogen restriction implementation timelines.
The model holds under sustained biofuel policy support and stable corn supply conditions; deviation in drought severity across the US Corn Belt or accelerated precision fermentation cost reduction would shift protein substitution dynamics. Forecasts reflect documented assumptions regarding wet-milling capacity utilization and aquafeed formulation adoption rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cocoa Bean Extract Market
Ingredients
Konjac Flour Market
Ingredients
Canada Soy Protein Market
Ingredients
US Plant-Based Oils Market
Ingredients
United States Protein Market
Ingredients
Sodium Reduction Ingredients Market
Ingredients
Dry Molasses Products Market
Ingredients
Bean Flour Market
Ingredients
Homecare Ingredients Market
Ingredients
Tomato Concentrate Market
Ingredients
Biotech Ingredients Market
Ingredients
Omega 9 Market
Ingredients
Liquid Malt Extract Products Market
Ingredients
North America Plant Protein Ingredients Market
Ingredients
Protein Hydrolysate Market
Ingredients
Specialty Starch Market