
 Spandex Market | 2026-2036
Spandex Market Size, Share, and Industry Trends Forecast 2026-2036
Spandex Market Intelligence
Chinese capacity expansion is fragmenting the supply base for commodity-grade spandex fibers. This shift allows specialized producers to focus on higher-margin segments. South Korea's HYOSUNG leverages its global manufacturing footprint across several continents. Indorama Corporation sustains a diversified portfolio including both spandex and related raw materials, while The LYCRA Company differentiates through strong brand recognition and patented fiber technologies.
Spandex, or elastane, is a synthetic polyurethane-polyurea copolymer known for its exceptional elasticity, capable of stretching over 500% without breaking. It is typically produced via a dry spinning process and blended with other fibers like cotton or polyester to impart stretch. While activewear and stretch fabrics for apparel constitute the largest volume segments, medical textiles offer a consistent high-margin niche. Performance attire applications represent the fastest-growing category, driven by consumer wellness trends.
Regulations like the EU's REACH directive govern the chemical inputs for spandex production, while EPA rules in the United States manage solvent emissions from manufacturing facilities. In parallel, China's national GB standards set stringent quality and performance benchmarks for finished textiles. Navigating these divergent regional standards for chemical safety, recycled content, and product circularity is becoming a central strategic challenge for producers.
Market Dynamics
The central dynamic in the spandex market is the tension between the commoditization of standard-grade fibers, driven by Chinese capacity expansion, and a simultaneous flight-to-quality towards high-margin, sustainable, and specialized elastanes demanded by global apparel brands.
Growth Catalysts
- Performance Activewear Demand:A persistent consumer focus on health and wellness sustains high volume demand for stretch fabrics in athletic apparel, athleisure, and sportswear, which are the largest end-use segments for spandex blends.
- Bio-Based Material Innovation:Development of spandex fibers derived from renewable feedstocks offers a key differentiator, appealing to brands and consumers seeking sustainable alternatives to petroleum-based synthetics and aligning with circular economy goals.
- Textile Hub Investment:Concentrated capital flows from global brands into textile manufacturing centers in Vietnam, Bangladesh, and Turkey are creating localized, high-volume demand for spandex as a critical input for export-oriented apparel production.
Market Restraints
- Raw Material Price Volatility:Spandex production costs are directly tied to the fluctuating prices of petrochemical precursors like polytetramethylene ether glycol (PTMEG) and methylene diphenyl diisocyanate (MDI), creating margin pressure for fiber manufacturers.
- Divergent Chemical Regulations:Producers face significant compliance costs and complexities navigating differing regional chemical safety standards, such as the EU's REACH directive for substance registration and the US EPA's rules on solvent emissions.
- Substitution from Mechanical Stretch:Advances in knitting and weaving techniques are enabling the creation of "mechanical stretch" textiles from fibers like polyester, offering a lower-cost alternative to spandex blends in some mid-range apparel applications.
Strategic Opportunities
- Smart Textile Integration:Incorporating spandex with conductive yarns presents an opportunity to develop next-generation smart apparel for health monitoring and athletic performance tracking, creating a new, high-value application category.
- Closed-Loop Recycling Technologies:Developing commercially viable chemical or enzymatic processes to separate and recover spandex from post-consumer textile blends would meet significant unmet demand for circular materials from major apparel brands.
- Medical Textile Penetration:Expanding the use of high-performance, medical-grade elastane in applications like compression hosiery, wound care dressings, and orthopedic braces offers a stable, high-margin niche outside the fashion cycle.
Industry Challenges
- Multi-Standard Compliance Burden:Manufacturers face a significant operational challenge in certifying products against a growing matrix of standards, including China's GB quality benchmarks and the EU's Corporate Sustainability Reporting Directive (CSRD) traceability requirements.
- High Capital Investment:Modernizing or constructing dry spinning facilities to accommodate more environmentally benign solvents or new bio-based polymers requires substantial capital expenditure, creating a barrier to entry and slowing material innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spandex Market |
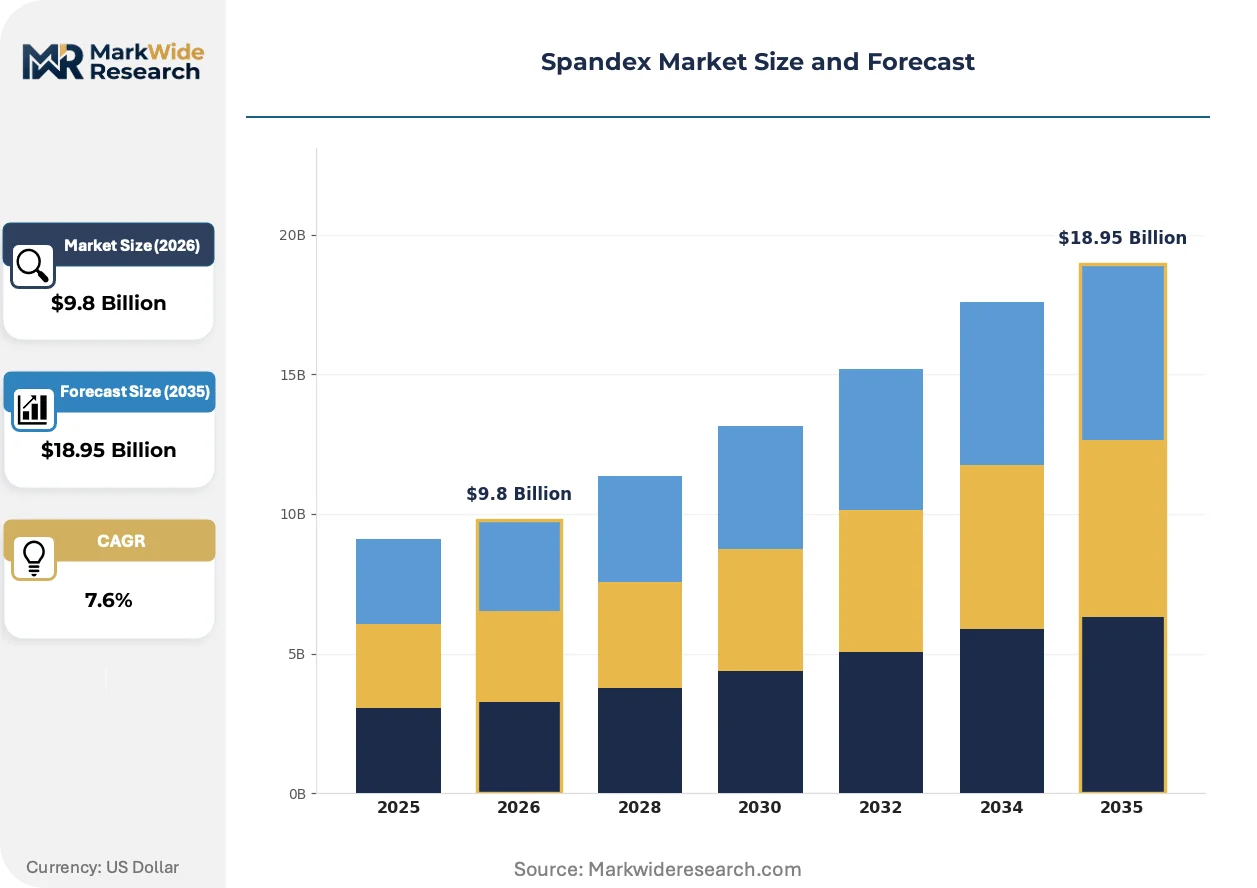
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $18.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Fabrics, Swimwear, Activewear, Under Garments End User: Manufacturers, Retailers, Distributors, Fashion Designers Application: Sportswear, Casual Wear, Performance Attire, Medical Textiles Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Asahi Kasei Corporation, Yantai Tayho Advanced Materials Co., Ltd., HYOSUNG, TK Chemical Corporation, Indorama Corporation, Huafon Chemical Co., Ltd., TAEKWANG INDUSTRIAL CO., LTD, Toray Industries, Inc., The LYCRA Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spandex Market Strategic Shifts & Innovations
Material science advancements are steering the spandex industry toward greater circularity and bio-based origins. Concurrently, digitalization is transforming the textile design and development process, compressing timelines from concept to production for apparel brands incorporating stretch fabrics.
Digital material libraries, which contain precise data on the physical properties of different spandex blends, are a key enabling technology. Apparel designers and sourcing teams are the primary adopters, using this data in 3D design software to simulate drape, fit, and stretch performance. This trend is virtualizing the physical sampling stage, significantly reducing material waste and accelerating the development cycle for new garments.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is a pivotal regulatory driver. Its implementation compels large companies to provide audited disclosures on their supply chain's environmental and social impact, including material circularity. Global apparel brands and their primary textile mill partners are most affected, prompting investment in digital traceability systems to validate claims of recycled spandex content.
A notable behavioral change is the shift toward on-demand manufacturing models adopted by direct-to-consumer and fast-fashion brands. This pattern disrupts the traditional, large-volume seasonal purchasing of fabrics, creating an advantage for agile spandex suppliers capable of fulfilling smaller, more frequent, and customized orders. This trend is most visible within the North American and European e-commerce apparel sectors, where speed is a paramount competitive advantage.
Spandex Market Segmentation
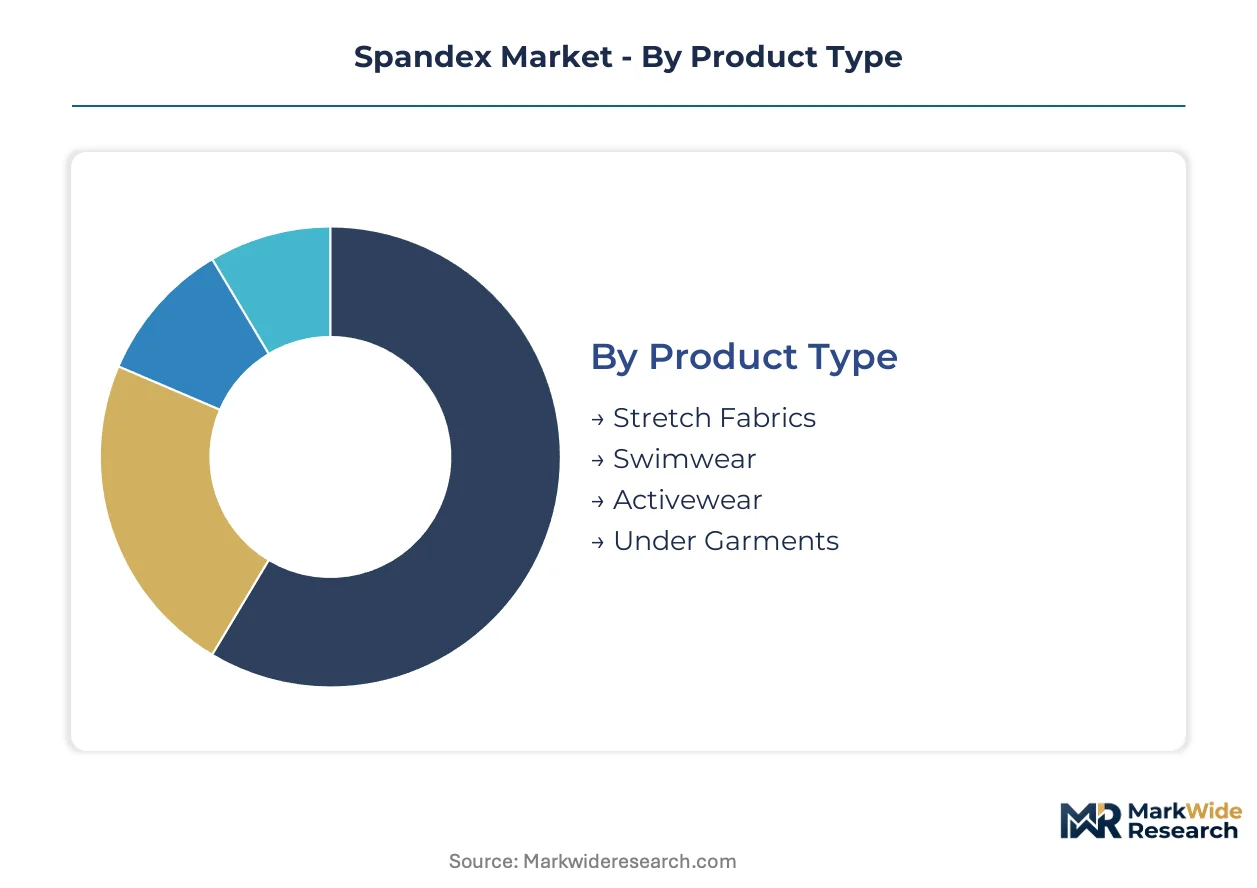
Market segmentation for spandex highlights the diverse product forms, end-user groups, and application areas driving demand for elastic fibers. This delineation helps producers align material innovation with specific commercial requirements across the textile value chain.
Product Type:
The functional characteristics of spandex-blended textiles define product type segmentation within the market.
- Activewear:These garments incorporate spandex for flexibility, moisture-wicking properties, and shape retention, essential for athletic performance and comfort. Demand concentrates in North America and Europe, driven by persistent consumer wellness trends.
- Stretch Fabrics:Spandex is blended with natural or synthetic fibers to impart elasticity, drape, and comfort in a wide range of woven and knitted textiles. Apparel brands utilize these fabrics for everyday clothing, enhancing fit and movement.
- Swimwear:Spandex provides the necessary stretch and recovery for swimwear, ensuring a comfortable fit and resistance to chlorine and UV degradation. Global fashion brands integrate spandex for both performance and aesthetic appeal.
- Under Garments:This segment uses spandex for comfortable fit, support, and shape retention in items like hosiery, lingerie, and shapewear. Material science advancements enhance breathability in these intimate apparel applications.
Stretch Fabrics commands the established base. The steepest expansion runs through Activewear.
End User:
Customer type delineation clarifies the primary purchasing entities for spandex materials.
- Manufacturers:Textile mills and garment factories are primary purchasers, integrating raw spandex fibers into yarns and fabrics for subsequent apparel production. Investment in textile hubs like Vietnam and Bangladesh drives their demand.
- Retailers:Apparel retailers, including major global brands, influence spandex specifications and sourcing decisions through their supply chain requirements. The EU's CSRD impacts retailer demands for traceable, sustainable spandex content.
- Distributors:These entities manage the supply chain logistics, connecting spandex producers with smaller textile manufacturers and specialized garment makers. They facilitate access to diverse regional markets.
- Fashion Designers:Designers specify spandex-blended fabrics for their collections, influencing material innovation and aesthetic trends in the apparel industry. They prioritize both performance and visual appeal.
Manufacturers drive foundational demand for spandex. Retailers increasingly influence material specifications.
Application:
The end-use application segments highlight the diverse functional requirements for spandex.
- Performance Attire:This category includes highly technical garments for professional athletes and specialized outdoor activities, demanding superior stretch, recovery, and durability from spandex fibers. Consumer wellness trends fuel this segment's expansion.
- Medical Textiles:High-performance elastane is critical for compression hosiery, wound dressings, and orthopedic supports, requiring consistent elasticity and biocompatibility. This niche offers a stable, high-margin market for specialized spandex.
- Sportswear:Spandex is integral to athletic apparel for its ability to provide comfort, flexibility, and shape retention during physical activity. This segment aligns with broad consumer interest in health and fitness.
- Casual Wear:Everyday clothing like jeans, t-shirts, and dresses incorporate spandex to enhance comfort, fit, and freedom of movement. This application represents a significant volume segment for standard-grade spandex.
Sportswear applications maintain significant volume. Medical Textiles are expanding most quickly.
Distribution Channel:
Volume and reach considerations shape the distribution channel for spandex products.
- Online Retail:E-commerce platforms facilitate direct-to-consumer sales of spandex-containing garments, supporting agile, on-demand manufacturing models. This channel is prominent in North American and European apparel sectors.
- Wholesale:Large-volume transactions between spandex producers, textile mills, and major apparel manufacturers characterize the wholesale channel. This traditional route handles significant quantities of commodity-grade fibers.
- Specialty Stores:These retailers focus on niche markets like outdoor gear, lingerie, or athletic equipment, often stocking premium spandex-blended products. They cater to specific consumer performance requirements.
- Supermarkets:Mass-market apparel, including basic activewear and undergarments, is distributed through supermarket chains, offering convenience and affordability to a broad consumer base. This channel emphasizes cost-effectiveness.
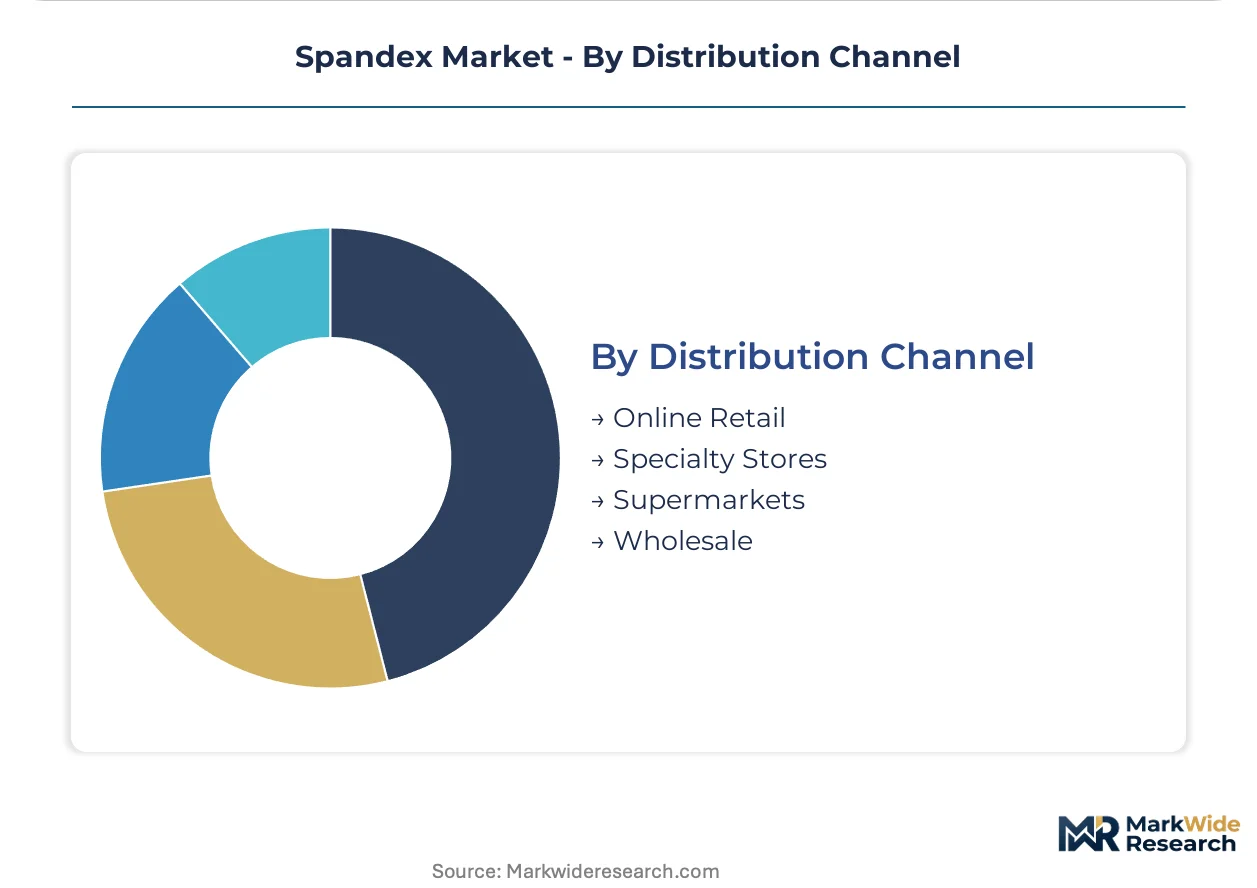
Wholesale channels move the largest volumes. Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU's Corporate Sustainability Reporting Directive (CSRD) is reshaping material sourcing decisions for global apparel brands. This regulation compels companies to disclose environmental and social impacts, including material circularity, directly influencing demand for sustainable spandex. Producers must now align their supply chains with stringent European sustainability benchmarks.
China
Chinese capacity expansion drives the commoditization of standard-grade spandex fibers for its vast domestic apparel market. China's national GB standards enforce strict quality and performance benchmarks for finished textiles. Manufacturing hubs in Zhejiang and Guangdong provinces concentrate spandex production for global supply chains.
United States
Consumer wellness trends sustain high demand for stretch fabrics in performance activewear across the United States. EPA rules in the country manage solvent emissions from spandex production facilities. Apparel brands in New York and California drive innovation in specialized elastanes for premium garments.
Vietnam
Global apparel brands invest heavily in Vietnam's textile manufacturing centers, creating localized demand for spandex as a critical input. The country's trade agreements influence sourcing patterns for textile inputs. Concentrated capital flows into textile hubs near Ho Chi Minh City support high-volume export-oriented apparel production.
Germany
Germany exhibits strong demand for high-performance and sustainable textiles, particularly in medical and technical applications. The EU's REACH directive governs the chemical inputs used in German spandex production. Technical textile clusters in Bavaria focus on specialized, high-margin elastane for industrial and medical uses.
South Korea
South Korean producers drive innovation in specialized elastanes, leveraging global manufacturing footprints. The country's environmental regulations influence the development of sustainable fiber technologies. Major players like HYOSUNG maintain significant R&D and production facilities near Seoul and Ulsan.
Spandex Market Key Industry Players
Capability concentration sits with specialized producers focusing on high-margin, performance-oriented elastanes; scale advantage sits with large-volume manufacturers of commodity-grade fibers. The market fragments into distinct archetypes: integrated chemical giants, specialized fiber innovators, and high-volume commodity suppliers. Companies pursue strategic capacity expansion in emerging textile hubs while simultaneously investing in technological differentiation, brand recognition, and sustainable material development.
Among diversified producers, Indorama Corporation exemplifies a strategy of sustaining a broad portfolio, encompassing both spandex and related raw materials, which provides inherent supply chain stability. South Korean-headquartered HYOSUNG leverages its extensive global manufacturing footprint across several continents, anchoring its position as a major fiber supplier for various end-use applications. The LYCRA Company differentiates its offerings through strong brand recognition and patented fiber technologies, occupying a premium segment by focusing on performance and specialized applications within the global market.
| Leading Market Players |
|---|
| Asahi Kasei Corporation |
| Yantai Tayho Advanced Materials Co., Ltd. |
| HYOSUNG |
| TK Chemical Corporation |
| Indorama Corporation |
| Huafon Chemical Co., Ltd. |
| TAEKWANG INDUSTRIAL CO., LTD |
| Toray Industries, Inc. |
| The LYCRA Company |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping costs influence spandex pricing, reflecting the concentrated manufacturing base in Asia and its impact on global apparel brand procurement strategies. This dynamic creates a cost-driven tension between commodity volumes and high-performance specialized fibers.
Pricing Analysis
Significant price spreads exist between commodity-grade spandex from Chinese producers and specialized elastanes from European and South Korean suppliers. The market primarily uses a contract-based long-term offtake model for large volumes, supplemented by spot purchases for niche requirements. Price differentiation stems from quality grade, adherence to certifications like EU's REACH, and brand premium for patented technologies. Pricing pressure intensifies in the commodity segment due to Chinese capacity expansion. Manufacturers of casual wear exhibit higher price sensitivity compared to performance attire and medical textile producers.
Supply Chain Analysis
Textile manufacturing hubs in Vietnam, Bangladesh, and Turkey consolidate significant capacity for apparel production, driving localized demand for spandex. The supply chain draws heavily from petrochemical precursors like polytetramethylene ether glycol (PTMEG) and methylene diphenyl diisocyanate (MDI, primarily produced in China and Europe. Raw material price volatility represents a key structural risk for fiber manufacturers. Distribution runs through wholesale channels for bulk commodity fibers, with online retail gaining share for specialized or on-demand garment production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spandex market requires a robust substitution defense strategy, particularly against the rising threat of mechanical stretch textiles in mid-range apparel applications.
For Market Incumbents: Build a technological differentiation moat through continuous R&D in specialized elastanes and sustainable fiber technologies. Invest in closed-loop recycling processes to meet Corporate Sustainability Reporting Directive (CSRD) requirements and counter commoditization from Chinese capacity expansion. Strategic partnerships with apparel brands can secure long-term demand for high-performance spandex. Focus on developing bio-based alternatives to petroleum-derived fibers.
For New Entrants and Emerging Players: Underpenetrated medical textile markets offer a strategic entry point for specialized spandex producers. Target niche applications like compression hosiery or wound care, which demand consistent elasticity and biocompatibility. A go-to-market angle focusing on advanced material science and stringent quality certifications provides a competitive advantage. Explore smart textile integration for health monitoring apparel as a high-value white space.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical giants and integrated textile conglomerates seeking to divest non-core spandex assets. Spandex remains critical for performance apparel and technical textiles over the long term, making specialized fiber innovators attractive acquisition targets. Prioritize companies with patented fiber technologies or proven closed-loop recycling capabilities. Commercial viability of chemical recycling solutions is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Closed-Loop Recycling | This meets increasing brand demand for circular materials and enhances supply chain sustainability for global apparel companies. |
| Develop Bio-Based Spandex | This offers a key differentiator, appealing to brands and consumers seeking sustainable alternatives to petroleum-based synthetics. |
| Form Smart Textile Partnerships | This integrates spandex with conductive yarns to create next-generation health monitoring and athletic performance apparel. |
| Expand Capacity in Emerging Hubs | This aligns production with concentrated capital flows into textile manufacturing centers like Vietnam and Bangladesh. |
| Integrate Digital Material Libraries | This accelerates apparel development cycles by enabling 3D design software to simulate drape, fit, and stretch performance. |
Research Approach
A spread of perspectives from apparel brand sourcing managers, textile mill procurement leads, spandex R&D directors, and regulatory compliance specialists converged on the working assumptions for this analysis. Primary interviews were validated against secondary data from EU CSRD guidelines, EPA regulatory documents, China GB standards, and corporate sustainability reports. Bottom-up and top-down triangulation ensured comprehensive market sizing.
Demand-supply balance modeling informed the market projections across the analysis window, integrating segmented insights from the value chain. Segmentation dimensions included product type, end-user, application, distribution channel, and material innovation tier. Compound Annual Growth Rates were calculated considering historical performance and projected shifts in end-use demand, with petrochemical precursor prices and global apparel production volumes as key inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by specialized fiber innovators or large chemical producers would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and consumer wellness trends. Quarterly review of petrochemical prices and textile manufacturing investment flows is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Nylon Tire Cord Fabrics Market
Synthetic Fibers
Performance Fabric Market
Synthetic Fibers
Global Lyocell Fibers Market
Synthetic Fibers
Asia-Pacific Spandex Market
Synthetic Fibers
Europe Nanofiber Market
Synthetic Fibers
Staple Fibers Market
Synthetic Fibers
Regenerated Fibers Market
Synthetic Fibers
Middle-East and Africa Aramid Fiber Market
Synthetic Fibers
Monofilament Market
Synthetic Fibers
Parachute Fabric Market
Synthetic Fibers
Clothing Fibers Market
Synthetic Fibers
Modacrylic Fiber Market
Synthetic Fibers
Synthetic Fabric Market
Synthetic Fibers
Short Cut Polyester Fiber Market
Synthetic Fibers
Polyolefin Fiber Market
Synthetic Fibers
Spandex Fiber Market