
 Clothing Fibers Market | 2026-2036
Clothing Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Clothing Fibers Market Intelligence
Athleisure brands and outdoor apparel makers are redrawing fiber procurement priorities away from commodity synthetics toward traceable and low-impact alternatives. Toray Industries leverages its Japan-based polymer science expertise to supply differentiated nylon and polyester to performance-wear labels. Grasim Industries anchors India's viscose staple fiber output with integrated pulp-to-fiber operations in Madhya Pradesh and Karnataka. Reliance Industries dominates petrochemical-derived fiber production through its Jamnagar complex, competing on scale while navigating sustainability scrutiny.
Clothing fibers are filamentous or staple materials—natural, synthetic, or regenerated—engineered to specified denier, tenacity, and moisture-regeneration parameters for yarn production and fabric construction. Their primary commercial purpose is to deliver tactile, thermal, and durability performance across garment and textile applications. Polyester leads fiber type volume globally due to cost efficiency and blend compatibility, while cotton retains margin concentration in premium apparel segments demanding breathability and natural provenance. Non-woven production methods are expanding fastest in industrial fabrics and disposable hygiene applications where thermal-bonded or spun-laid structures replace traditional woven substrates.
The EU ECHA REACH framework restricts hazardous chemical inputs in fiber finishing, while the EU Green Deal's textile strategy mandates design-for-recycling standards that reshape virgin fiber demand in European markets. India's BIS certification requirements for textile quality and the country's PLI scheme for man-made fibers and technical textiles are accelerating domestic capacity modernization and export compliance investments. Stakeholders must monitor regulatory divergence between European chemical restrictions and Asian production incentives to align capital allocation with emerging compliance-driven sourcing corridors.
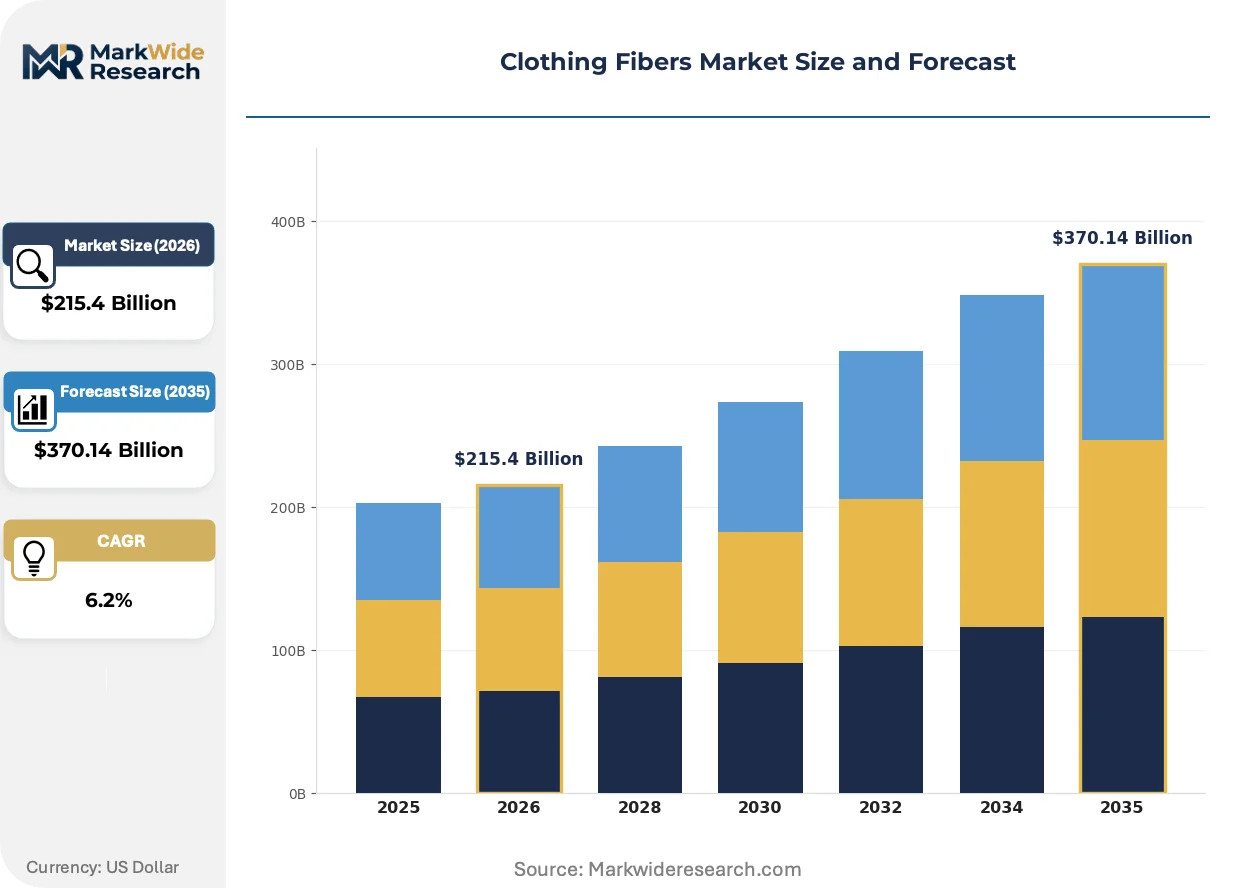
Market Dynamics
EU ECHA REACH microplastic restrictions and the EU Green Deal textile strategy are forcing European mills to abandon conventional polyester in favor of certified bio-based and recycled alternatives, redirecting procurement flows toward traceable feedstock corridors.
Growth Catalysts
- EU Green Deal textile mandates:Design-for-recycling standards compel garment brands to specify mechanically recycled or bio-based fibers, expanding addressable demand for certified sustainable yarn suppliers.
- Athleisure performance requirements:Moisture-wicking and thermal-regeneration specifications in yoga and outdoor apparel pull regenerated cellulosic and advanced synthetic blends into premium product lines.
- India PLI scheme for man-made fibers:Domestic capacity modernization incentives accelerate viscose and polyester technical textile investments, positioning Indian mills for export compliance with European sustainability protocols.
Market Restraints
- Crude oil price volatility:Petrochemical-derived polyester feedstock costs fluctuate with naphtha and paraxylene spot markets, compressing margin predictability for commodity fiber producers.
- Single-country pulp dependence:Dissolving wood pulp for viscose production concentrates in Indonesian and Brazilian supplier networks, exposing regenerated cellulosic fiber makers to shipping disruption and currency risk.
- Mechanical recycling quality ceiling:Post-consumer polyester depolymerization yields shorter polymer chains than virgin resin, limiting recycled fiber adoption in high-tenacity industrial applications.
Strategic Opportunities
- Bio-based synthetic feedstocks:Agricultural waste-derived polyester precursors and algae-based nylon polymers open premium positioning for fiber makers targeting carbon-neutral apparel claims.
- Technical textile non-wovens:Spun-laid and thermal-bonded industrial fabrics for geotextiles and filtration media expand fiber demand outside traditional garment channels.
- Blockchain traceability integration:Farm-to-garment digital certification platforms enable European brands to verify recycled content claims for EU Green Deal compliance documentation.
Industry Challenges
- Polymer science talent scarcity:Bio-based fiber R&D requires specialized biochemistry and materials engineering expertise that outpaces current European and Asian technical university output.
- Multi-certification timeline compression:Simultaneous pursuit of OEKO-TEX, GRS, and EU Ecolabel approvals extends product launch cycles by 12-18 months for sustainable fiber introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clothing Fibers Market |
| Market Size in 2026 | $215.4 Billion |
| Market Size in 2035 | $370.14 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fiber Type: Cotton, Polyester, Wool, Nylon Production Method: Spinning, Weaving, Knitting, Non-woven End Use: Apparel, Home Textiles, Industrial Fabrics, Accessories Maintenance Type: Machine Washable, Dry Clean Only, Hand Wash, Stain Resistant |
| Companies Covered | Asahi Kasei Corporation, Arvind Limited, Eastman Chemical Company, Unifi Inc., Grasim Industries, Toray Industries, Reliance Industries Limited, The Bombay Dyeing and Manufacturing Co. Ltd., Teijin Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clothing Fibers Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory disclosure mandates are converging to reshape how fiber producers compete on provenance, performance, and circularity credentials.
Lyocell solvent-spinning technology is displacing conventional viscose production in European and East Asian mill investments. Outdoor apparel brands specify Tencel-branded lyocell for its closed-loop solvent recovery and superior wet strength versus modal. This shift is compressing demand for traditional sulfite-pulp viscose in premium garment segments.
ECHA REACH restrictions on intentionally added microplastics now cover synthetic fiber shedding from textile washing. The regulation forces polyester and nylon suppliers to develop low-shedding yarn constructions or biodegradable alternatives. Sportswear brands serving Nordic and German markets accelerate procurement of solution-dyed fibers that reduce surface microfiber release.
Direct-to-mill procurement platforms are bypassing traditional yarn trading houses for large-volume garment contracts. Tier-one apparel manufacturers in Bangladesh and Vietnam now source certified recycled polyester through blockchain-verified supplier networks rather than commodity brokers. This channel compression is most advanced in European brand supply chains where ESG audit requirements demand supplier transparency.
Clothing Fibers Market Segmentation
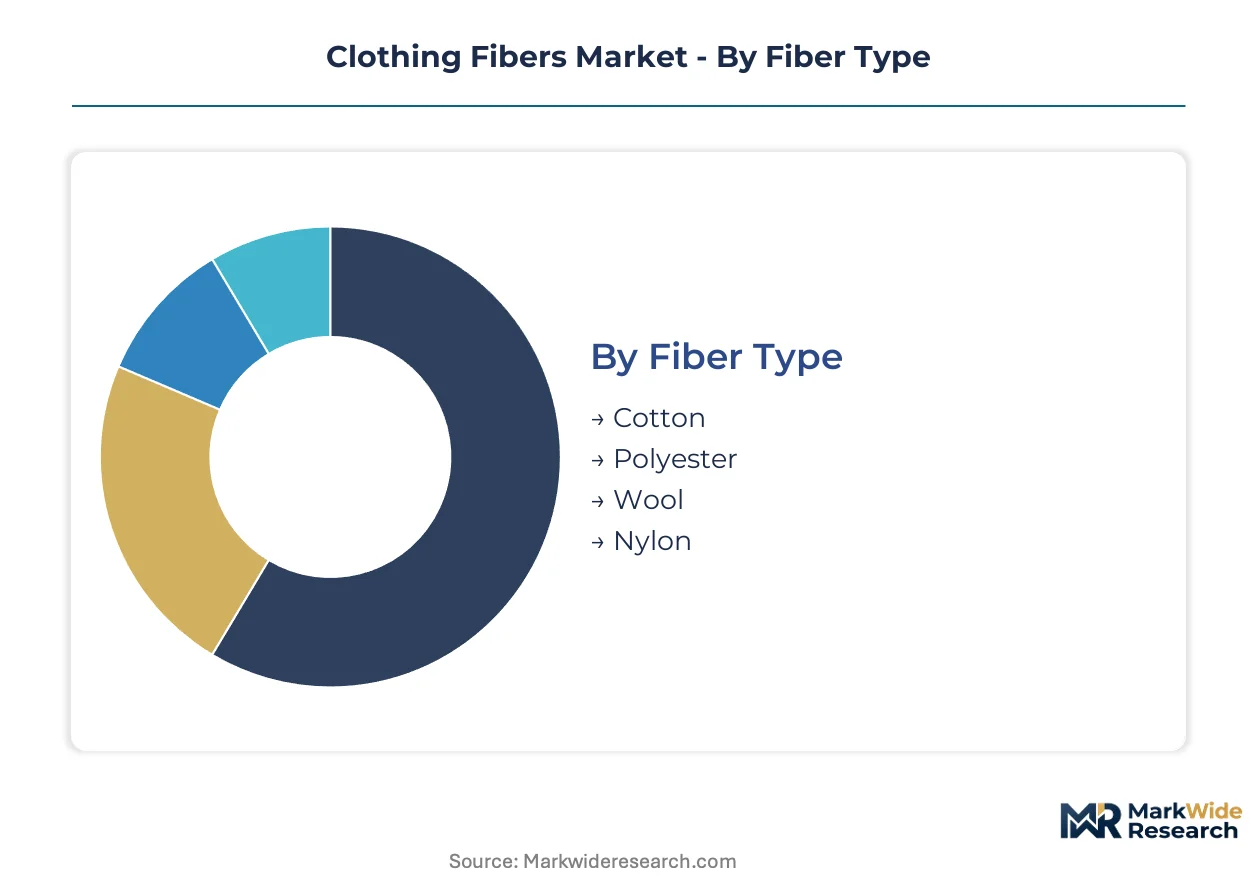
Clothing fiber segmentation determines procurement corridors, compliance obligations, and margin structures for mills and brands. Regulatory frameworks like EU REACH and India's BIS standards create divergent specification requirements across fiber categories, forcing suppliers to maintain parallel certification tracks for export market access.
Fiber Type:
ECHA REACH chemical restrictions and EU Green Deal textile mandates differentiate compliance burdens across natural and synthetic categories, redirecting European mill procurement toward certified alternatives while Asian producers optimize for scale and blend compatibility.
- Polyester:Petrochemical-derived polymer engineered to specified denier and tenacity parameters for blend compatibility with cotton and elastane. European athleisure brands now specify mechanically recycled or bio-based polyester grades to satisfy EU Green Deal design-for-recycling standards, compressing virgin resin demand in premium garment segments.
- Cotton:Natural cellulose staple fiber valued for breathability and moisture absorption in premium apparel applications. Indian ginning and spinning clusters in Gujarat and Maharashtra supply global garment manufacturers, though water-intensive cultivation faces sustainability scrutiny from European procurement teams.
- Wool:Protein-based animal fiber with natural thermal regulation and odor-resistance properties. Australian and New Zealand merino grades dominate performance outdoor apparel specifications.
- Nylon:Polyamide polymer delivering superior abrasion resistance and elastic recovery for hosiery and technical applications. Toray Industries and domestic Chinese producers compete on polymer science differentiation.
Polyester handles the majority of throughput; bio-based and recycled alternatives within this category are gaining share fastest as compliance requirements tighten.
Production Method:
Capital intensity and energy consumption vary dramatically across mechanical and chemical transformation processes, with non-woven technologies offering the steepest unit cost reduction for industrial applications.
- Spinning:Drafting and twisting staple fibers into continuous yarn for downstream weaving or knitting operations. India's PLI scheme for man-made fibers accelerates ring and open-end spinning capacity modernization in Tiruppur and Surat clusters.
- Non-woven:Spun-laid, melt-blown, or thermal-bonded fiber assembly bypassing traditional yarn formation. Geotextile and filtration media manufacturers in Germany and the United States specify non-woven polypropylene and polyester for civil engineering and liquid filtration applications.
- Weaving:Interlacing warp and weft yarns at right angles to create structured fabric with dimensional stability. Bangladeshi and Vietnamese mills dominate apparel fabric weaving for European and North American garment brands.
- Knitting:Loop-forming construction delivering stretch and drape for intimate apparel and casual wear. Seamless knitting technology compresses labor content in sportswear production.
Non-woven methods are expanding most quickly on share as industrial fabric applications displace traditional woven substrates; spinning retains the largest installed base.
End Use:
Application-specific performance requirements dictate fiber specification, with technical textiles commanding premium pricing for engineered functionality versus commodity apparel volumes.
- Apparel:Garment applications spanning fast fashion through luxury segments, with fiber selection driven by tactile properties, dye affinity, and care label requirements. Athleisure brands specify regenerated cellulosic and advanced synthetic blends for moisture-wicking performance.
- Industrial Fabrics:Engineered textiles for automotive, aerospace, construction, and filtration applications demanding specified tensile strength and chemical resistance. European automotive suppliers source aramid and glass fiber composites for tire reinforcement and interior panel substrates.
- Home Textiles:Bedding, upholstery, and decorative applications prioritizing durability and aesthetic finish. Indian exporters supply cotton and polyester bedding sets to North American and European retail chains.
- Accessories:Belts, bags, and footwear components requiring abrasion resistance and colorfastness. Italian leather goods houses specify nylon and cotton webbing for luxury bag straps and trim.
Apparel commands the dominant volume position; industrial fabrics show the steepest expansion trajectory as technical specifications proliferate across transportation and infrastructure sectors.
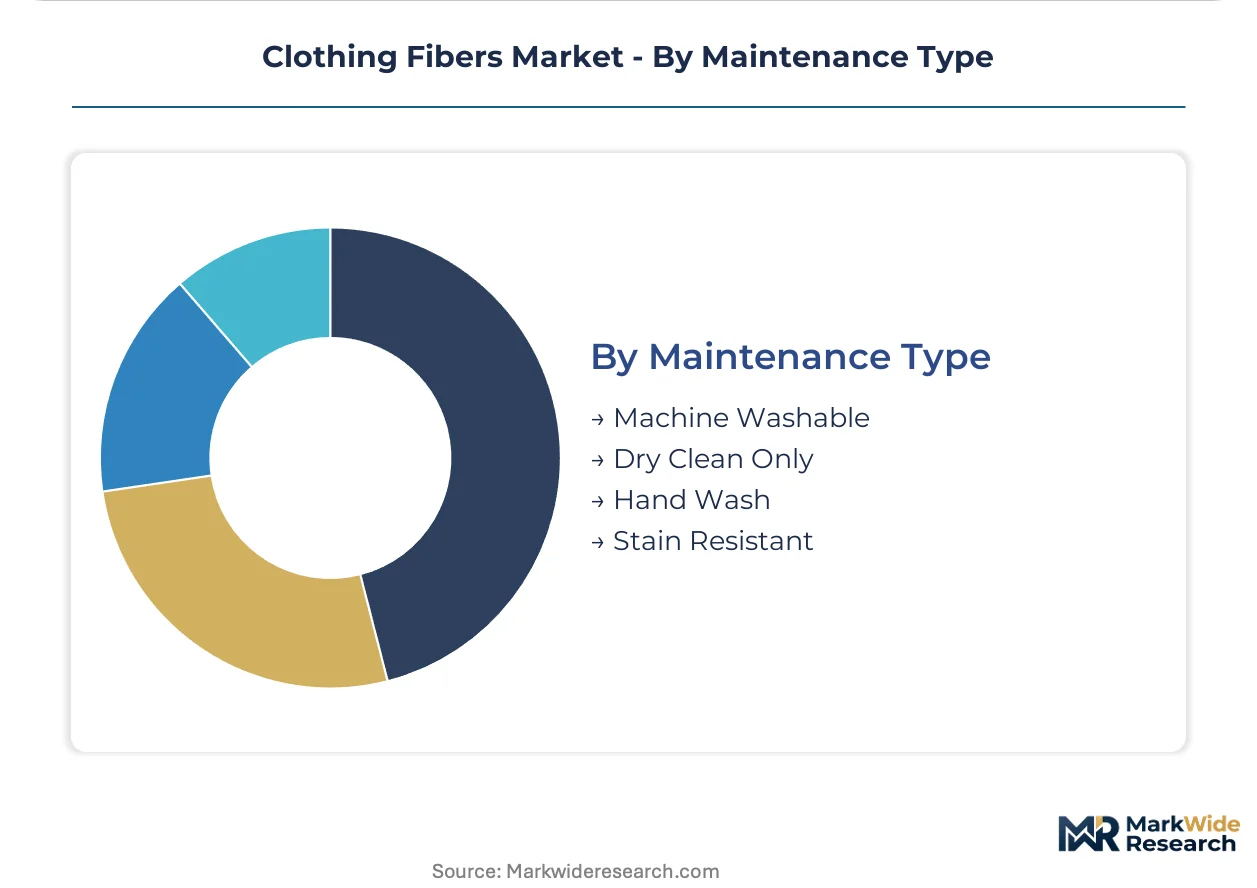
Maintenance Type:
Care label classification determines fiber finishing chemistry and retail positioning, with machine-washable specifications now standard for mass-market penetration.
- Machine Washable:Fiber and finish combinations engineered to withstand agitation, temperature cycling, and detergent exposure without dimensional distortion or color loss. This specification is mandatory for fast fashion and children's wear distribution through mass retail channels.
- Stain Resistant:Fluoropolymer or silicone-based surface treatments repelling liquid and particulate soiling. ECHA REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation toward bio-based repellency chemistry.
- Dry Clean Only:Delicate protein fibers and structured garments requiring solvent-based cleaning to preserve hand and construction. Wool suiting and silk evening wear retain this classification for premium positioning.
- Hand Wash:Cellulosic and protein fibers with limited wet strength or dimensional stability. Viscose and modal knits require gentle handling to prevent felting and shrinkage.
Machine washable grades dominate unit volume; stain resistant treatments are climbing fastest as performance apparel brands integrate functional finishing into core product lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian polyester and viscose producers supply garment manufacturers across Bangladesh and Vietnam, while European mills source certified sustainable fibers to meet EU Green Deal compliance requirements.
India
Domestic garment exporters and South Asian textile hubs drive demand for polyester and viscose staple fiber. The PLI scheme for man-made fibers and technical textiles accelerates capacity modernization investments. Jamnagar, Madhya Pradesh, and Karnataka clusters anchor integrated pulp-to-fiber and petrochemical-derived production operations serving both export and domestic markets.
China
Massive spinning and weaving capacity supports global fast fashion supply chains with cost-optimized synthetic fiber output. The country's dual carbon goals and GB standards for textile sustainability reshape virgin polyester investments. Zhejiang and Jiangsu province mill clusters dominate regenerated cellulosic and conventional synthetic fiber production for international brand procurement.
Germany
Automotive and technical textile manufacturers specify high-tenacity industrial fibers for tire reinforcement and filtration media. ECHA REACH microplastic restrictions and EU Green Deal textile strategy mandates redirect procurement toward certified recycled and bio-based alternatives. North Rhine-Westphalia and Baden-Württemberg host specialized non-woven and engineered fabric producers serving European industrial demand.
United States
Outdoor apparel brands and athletic wear labels drive specification of traceable recycled polyester and solution-dyed nylon. EPA oversight of chemical inputs and state-level extended producer responsibility proposals reshape fiber sourcing transparency requirements. North Carolina and Georgia textile corridors concentrate spinning and non-woven operations for domestic garment and industrial fabric applications.
Japan
Performance-wear brands source advanced polymer science differentiation in nylon and polyester for moisture-wicking and thermal-regulation applications. METI industrial policy supports materials science R&D for next-generation bio-based synthetic feedstocks. Osaka and Nagoya metropolitan areas anchor Toray Industries and Teijin Ltd. polymer research and differentiated fiber production for global athletic apparel supply chains.
Clothing Fibers Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and sustainability certification dimensions. The market structure tiers between scale-driven petrochemical giants, integrated pulp-to-fiber operators, and specialized polymer science innovators. Three archetypes dominate: commodity polyester producers competing on volume cost, regenerated cellulosic specialists leveraging integrated forestry assets, and advanced materials developers targeting performance-wear specifications. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure feedstock access and compliance certification.
Among Japan-based polymer science developers, Toray Industries and Teijin Ltd. exemplify the advanced materials archetype through differentiated synthetic fiber positioning. Grasim Industries and Reliance Industries Limited represent the scale-integrated tier, with the former anchoring viscose staple fiber output and the latter dominating petrochemical-derived polyester production. Asahi Kasei Corporation occupies a position within the diversified chemical conglomerate segment, spanning fiber portfolios alongside broader materials science applications.
| Leading Market Players |
|---|
| Asahi Kasei Corporation |
| Arvind Limited |
| Eastman Chemical Company |
| Unifi Inc. |
| Grasim Industries |
| Toray Industries |
| Reliance Industries Limited |
| The Bombay Dyeing and Manufacturing Co. Ltd. |
| Teijin Ltd. |
| Others |
Cost & Logistics Intelligence
Jamnagar-scale petrochemical integration and Karnataka pulp-to-fiber operations compress unit economics for polyester and viscose producers, concentrating supply-side pricing power among Indian integrated giants while forcing smaller European mills toward premium certified grades to escape commodity price floors.
Pricing Analysis
Conventional sulfite-pulp viscose, closed-loop lyocell, and next-generation algae-based nylon polymers stratify across three distinct price bands. Three-tier pricing structure across premium, standard, and economy levels separates EU Ecolabel-certified bio-based grades from commodity virgin polyester and mechanical recycled intermediates. Price differentiation hinges on certification tier and volume scale, with GRS-certified recycled polyester commanding modest premiums over virgin resin. Cost compression in standard-grade polyester is intensifying because Reliance Industries' Jamnagar complex optimizes naphtha cracking at unmatched scale. Fast fashion garment manufacturers exhibit highest price sensitivity; performance outdoor brands show lowest.
Supply Chain Analysis
Strategic stockpiling of dissolving wood pulp dominates regenerated cellulosic fiber procurement, while just-in-time resin delivery suffices for commodity polyester spinners with reliable petrochemical feedstock contracts. Supply concentrates in India, China, and Indonesia, with Jamnagar, Zhejiang province, and Sumatran pulp mills anchoring upstream capacity. Raw material dependencies span naphtha and paraxylene for polyester, dissolving pulp for viscose, and caprolactam for nylon. Single-country pulp concentration in Indonesia and Brazil creates tariff exposure and currency risk for European lyocell producers. Distribution runs through direct-to-mill platforms for large garment contracts and traditional yarn trading houses for spot purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent fiber producers face substitution pressure from bio-based synthetic feedstocks and closed-loop regenerated cellulosic technologies that threaten to displace conventional petrochemical-derived volume.
For Market Incumbents: Consolidate backward integration into dissolving pulp assets or captive bio-based feedstock cultivation to defend against Indonesian pulp supply disruption and emerging algae-polymer competitors. Expand lyocell solvent-spinning capacity in Madhya Pradesh to capture EU Green Deal-driven demand shifts away from conventional viscose. Certification investment in OEKO-TEX and GRS tiers remains essential for European market access. For New Entrants and Emerging Players: Lead with blockchain-verified recycled content platforms targeting Bangladeshi and Vietnamese garment manufacturers supplying EU athleisure brands. Technical textile non-wovens for geotextile and filtration applications represent the most penetrable white-space segment, given lower incumbent concentration versus apparel spinning. Direct mill partnerships bypassing commodity brokers offer the clearest go-to-market angle for traceability-focused procurement teams. For Investors and Strategic Acquirers: Integrated pulp-to-fiber operators with certified forestry assets and captive renewable energy supply offer the strongest long-term viability framing across the analysis window. Watch EU ECHA REACH enforcement intensity against microplastic shedding as the critical inflection signal; acceleration in Nordic and German market penalties would compress conventional polyester valuations and expand certified alternative addressable markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dissolving Pulp | Captive pulp supply from Indonesian or Brazilian forestry assets insulates Grasim Industries from shipping disruption and currency volatility. |
| Lyocell Capacity Expansion | Closed-loop solvent recovery investments in Madhya Pradesh position Indian mills to capture EU Green Deal design-for-recycling specifications. |
| Blockchain Traceability Platform Deployment | Farm-to-garment digital certification enables Toray Industries and Teijin Ltd. to verify recycled content claims for ECHA REACH compliance documentation. |
| Bio-Based Synthetic Feedstock R&D | Agricultural waste-derived polyester precursors open premium positioning for fiber makers targeting carbon-neutral apparel claims in German and Nordic markets. |
| Technical Textile Non-Woven Joint Venture | Spun-laid capacity partnerships with German automotive suppliers expand fiber demand outside traditional garment channels into tire reinforcement applications. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with fiber procurement managers at European athleisure brands, technical textile engineers at German automotive suppliers, and sustainability officers at Indian integrated producers; and secondary validation through customs trade databases, BIS certification registries, EU ECHA REACH restriction filings, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up capacity modeling across Jamnagar, Zhejiang, and Madhya Pradesh clusters triangulated against top-down demand segmentation by fiber type and end-use application.
Across the projection horizon, the analytical framework modeled volume and value trajectories across fiber type, production method, end-use application, and regional regulatory cluster dimensions. CAGRs derived from weighted average of historical capacity utilization trends, announced expansion pipelines, and elasticity-adjusted demand response to EU Green Deal compliance deadlines. Industry-specific forecast inputs incorporated PLI scheme disbursement timelines for Indian man-made fiber investments and ECHA REACH microplastic restriction implementation phasing.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement intensity, stable Indonesian pulp supply flows, and continued Indian PLI scheme funding would require recalibration. Forecasts reflect documented assumptions regarding polymer science R&D timelines and brand procurement shift velocities. Revision becomes warranted when EU Ecolabel certification adoption rates among mid-tier European mills cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Latin America Textile Market
Synthetic Fibers
Global Acrylic Fibers Market
Synthetic Fibers
Polyester Filament Market
Synthetic Fibers
Fiberglass Roving Market
Synthetic Fibers
Nylon Tire Cord Fabrics Market
Synthetic Fibers
IMO Fiber Market
Synthetic Fibers
North America High Performance Fibers Market
Synthetic Fibers
Middle-East and Africa Aramid Fiber Market
Synthetic Fibers
Sic Fibers Market
Synthetic Fibers
Synthetic Sewing Thread Market
Synthetic Fibers
South Korea Textile Market
Synthetic Fibers
Polyester Staple Fiber Market
Synthetic Fibers
Carbon Fiber Strands Market
Synthetic Fibers
Para-Aramid Fibers Market
Synthetic Fibers
Fiber Blends Market
Synthetic Fibers
Europe Nanofiber Market