
 Flat Knitting Machine Market | 2026-2036
Flat Knitting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Flat Knitting Machine Market Foresight
Modular machine configurations that separate software licenses from hardware acquisition is hardening buyer choice across the flat knitting machine landscape. Shima Seiki Mfg., Ltd. leverages its integrated design-to-production software ecosystem to anchor premium positioning in fashion knitwear. H. Stoll GmbH & Co. KG sustains engineering intensity in multi-gauge systems for technical textile applications. Cixing Textile Machinery Co., Ltd. dominates volume tiers through manufacturing scale in China's Yangtze River Delta cluster.
A flat knitting machine forms fabric by moving yarn through opposing needle beds arranged in a flat frame, typically achieving gauges from 1.5 to 18 needles per inch depending on end-use precision requirements. The equipment produces shaped panels without cutting or sewing, serving apparel manufacturing and technical textiles where seam elimination improves structural integrity. Computerized flat knitting machines command the highest margin pools as software integration enables pattern-on-demand and zero-waste production workflows. Electronic flat knitting machines represent the fastest-expanding installed base among mid-scale garment manufacturers upgrading from mechanical systems. Automatic flat knitting machines retain relevance in high-volume commodity knitwear where cycle speed outweighs pattern complexity.
EU F-Gas Regulation and REACH compliance in Europe shape refrigerant and lubricant specifications for climate-controlled knitting floors, while China's MIIT enforces GB energy-efficiency standards on textile machinery imports. Japan's METI promotes JIS-certified smart manufacturing integration that affects software protocol requirements for exported equipment. Stakeholders must monitor divergence between European CE-marked safety protocols and China's SAMR certification timelines when planning multi-region product rollouts.
Market Dynamics
Modular software licensing is decoupling from hardware acquisition across the flat knitting machine market, forcing manufacturers to defend margin pools through recurring revenue streams rather than upfront equipment sales. This structural shift compresses capital barriers for mid-scale garment producers while elevating switching costs through pattern ecosystem lock-in.
Growth Catalysts
- EU F-Gas Regulation:REACH-compliant refrigerant specifications for climate-controlled knitting floors are accelerating replacement cycles in Germany and Italy. Technical textile producers retrofit facilities to maintain automotive supplier certifications.
- Seamless panel production:Zero-waste knitting protocols eliminate cutting room waste for export-oriented apparel clusters in China's Zhejiang province. Brands specify computerized machines to meet circularity pledges.
- Medical fabric specifications:Compression garment and implantable mesh standards in Japan are pulling multi-gauge systems into healthcare supply chains. METI-certified smart manufacturing integration enables traceability protocols.
Market Restraints
- Needle bed precision tooling:Hardened steel gauge components face supply concentration in German and Swiss specialty metallurgy suppliers. Input cost volatility ripples through 18-gauge and finer system pricing.
- REACH compliance friction:ECHA substance restrictions on lubricant formulations create procurement complexity for equipment operating across EU and non-EU facilities. Dual inventory requirements inflate working capital.
- Mechanical system substitution:Refurbished electronic flat knitting machines from Yangtze River Delta secondary markets displace new equipment demand in Southeast Asian garment hubs.
Strategic Opportunities
- India technical textile expansion:PLI scheme incentives for automotive and geotextile manufacturing are creating first-mover advantage for multi-gauge system vendors establishing service networks in Tamil Nadu and Gujarat.
- Software-hardware convergence:Cloud-based pattern libraries integrated with 3D body scanning are converging with on-demand production models. Fashion knitwear brands pilot subscription-based design access.
- CE marking acceleration:Streamlined EU conformity assessment timelines for textile machinery are compressing market entry barriers for Chinese manufacturers upgrading from SAMR-only certification.
Industry Challenges
- Mechatronics technician scarcity:Servo motor calibration and needle bed alignment expertise concentrates in aging workforces across European machine builder hubs. Training pipeline gaps extend commissioning timelines.
- Legacy mechanical integration:Computerized control retrofits onto existing flat frames face protocol incompatibility with 1990s-era drive systems. Brownfield installations require custom interface engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flat Knitting Machine Market |
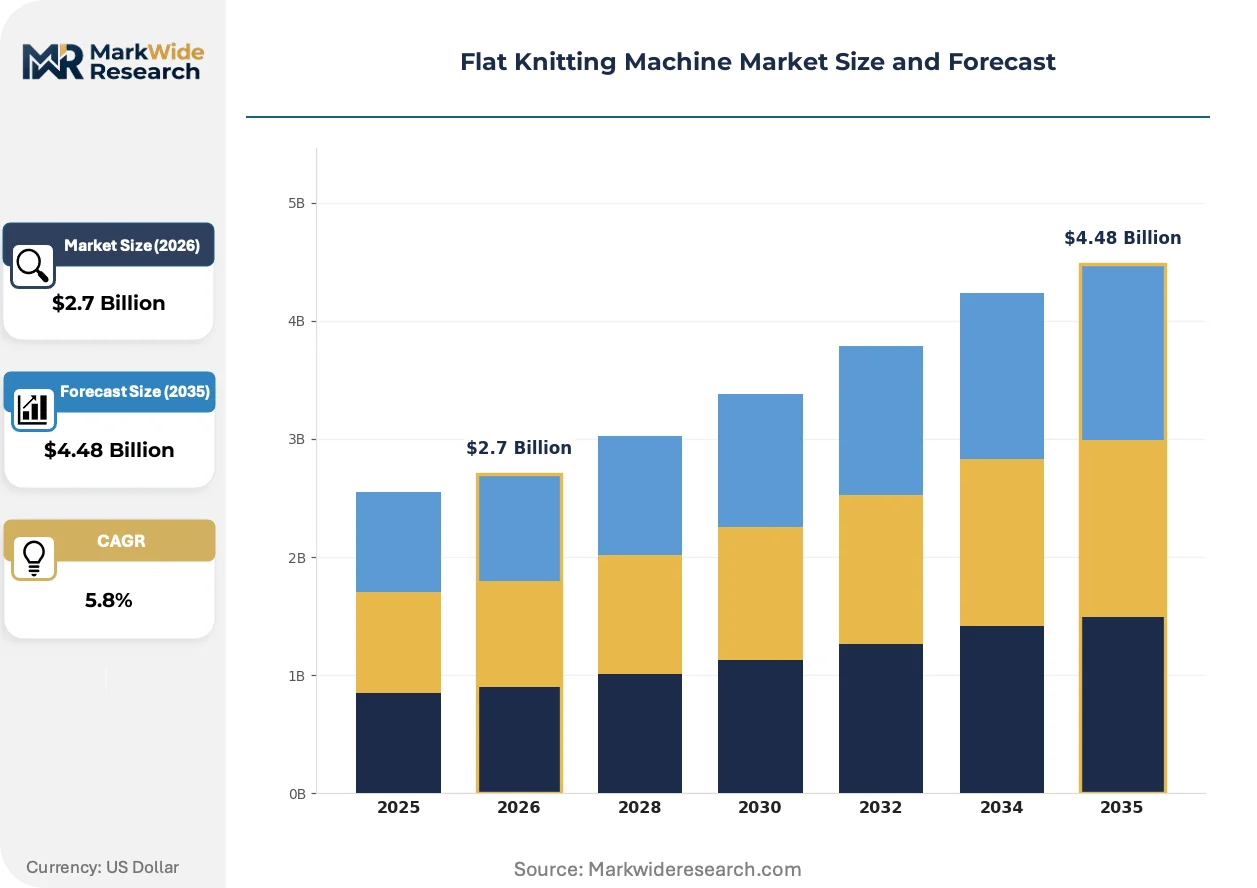
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $4.48 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Flat Knitting Machines, Electronic Flat Knitting Machines, Mechanical Flat Knitting Machines, Computerized Flat Knitting Machines Application: Apparel Manufacturing, Home Textiles, Technical Textiles, Sportswear Production, Fashion Knitwear End User: Garment Manufacturers, Textile Mills, Design Studios, Knitting Workshops, Fashion Brands Technology: Needle Bed Technology, Stitch Formation Technology, Yarn Feeding Technology, Motion Control Systems, Software Integration |
| Companies Covered | Mayer & Cie., Fukuhara Corp., Ltd., Shima Seiki Mfg., Ltd., Protti S.r.l., Changshu Changhua Smart Manufacturing Technology Co., Ltd., H. Stoll GmbH & Co. KG, Terrot GmbH, Cixing Textile Machinery Co., Ltd., Brother Industries, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flat Knitting Machine Market Shifts & Advancements
Digital thread technologies are compressing design-to-production cycles across fashion and technical textile applications. Three convergent developments are restructuring competitive advantage in equipment specification and operator capability requirements.
Artificial intelligence-driven pattern optimization is converging with real-time tension monitoring to eliminate manual adjustment interventions during complex jacquard sequences. High-mix, low-volume producers in Italy's Como silk district deploy these systems to reduce sample lead times from weeks to days. The technology is converging with predictive maintenance algorithms that schedule needle replacements before quality deviation occurs.
China's MIIT enforcement of GB energy-efficiency standards on imported textile machinery is mandating variable-frequency drive retrofits and heat recovery systems. Equipment failing to meet Grade 2 efficiency thresholds faces import clearance delays at Shanghai and Ningbo ports. Japanese and German manufacturers are accelerating localized assembly to bypass certification bottlenecks while maintaining technical control.
After-sales service unbundling is separating software updates, spare parts logistics, and field technician dispatch into discrete purchase decisions. Mid-scale garment manufacturers in Bangladesh and Vietnam now comparison-shop maintenance contracts independently from original equipment procurement. This fragmentation is most visible in export-oriented knitting clusters where margin pressure forces operational cost visibility at the line-item level.
Flat Knitting Machine Market Segmentation
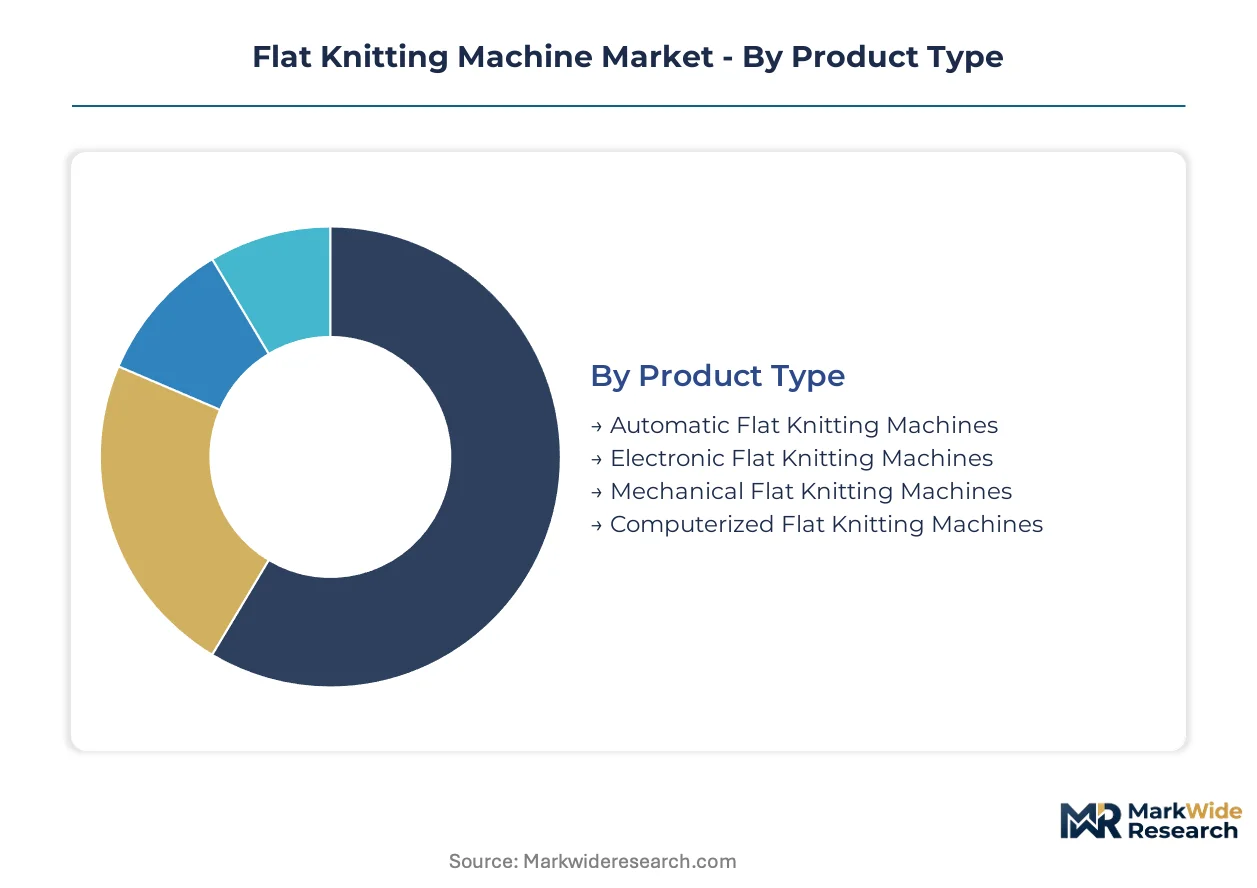
Segmentation in flat knitting machines reveals how certification requirements, software licensing models, and end-use precision demands split procurement behavior across equipment tiers. Buyers select configurations based on gauge flexibility needs, regulatory compliance burdens, and integration depth with design-to-production workflows.
Product Type:
CE marking and China's SAMR certification timelines create divergent approval pathways across equipment generations, with computerized systems facing the most complex multi-jurisdiction validation.
- Computerized Flat Knitting Machines:Software-integrated systems enable pattern-on-demand execution and zero-waste production protocols through direct CAD linkage. Demand concentrates in China's Zhejiang and Jiangsu provinces where export-oriented apparel clusters source equipment to meet circularity pledges from European fashion brands. SAMR certification delays for imported control modules push some buyers toward localized assembly options.
- Electronic Flat Knitting Machines:Microprocessor-controlled stitch formation bridges mechanical reliability with programmable flexibility, achieving gauges from 3 to 12 needles per inch. Mid-scale garment manufacturers in Bangladesh and Vietnam upgrade from mechanical systems to capture higher-value contract knitwear, though variable-frequency drive compliance with China's GB energy-efficiency standards adds procurement friction.
- Automatic Flat Knitting Machines:Cycle-optimized systems retain dominance in high-volume commodity knitwear where pattern complexity remains limited.
- Mechanical Flat Knitting Machines:Cam-driven operation persists in budget-constrained workshops and secondary market refurbishment chains.
Leading the category by volume: Electronic Flat Knitting Machines. Growing fastest: Computerized Flat Knitting Machines.
Application:
End-use specifications determine gauge range requirements and software integration depth, with technical textile applications commanding the highest precision tolerances.
- Technical Textiles:Automotive airbag fabrics, medical compression garments, and implantable mesh structures require multi-gauge capability from 1.5 to 18 needles per inch. Producers in Germany and Japan retrofit facilities to maintain automotive supplier certifications under EU F-Gas Regulation and METI traceability protocols.
- Fashion Knitwear:Complex jacquard and intarsia patterns drive demand for software-ecosystem lock-in, with Italy's Como silk district deploying AI-driven pattern optimization to compress sample lead times.
- Apparel Manufacturing:Seamless panel production eliminates cutting room waste for circularity-compliant supply chains.
- Sportswear Production:Engineered knit structures with zoned compression properties integrate moisture-wicking yarn feeds.
- Home Textiles:Blanket and upholstery applications prioritize throughput over pattern complexity.
Widest margin pool: Technical Textiles. Steepest expansion trajectory: Fashion Knitwear.
End User:
Customer scale determines whether procurement favors capital purchase with bundled service or modular software licensing with unbundled maintenance.
- Garment Manufacturers:High-volume producers in Vietnam and Bangladesh comparison-shop maintenance contracts independently from equipment acquisition, fragmenting supplier relationships.
- Textile Mills:Integrated spinning-to-fabric operations in China's Yangtze River Delta cluster source computerized systems for captive apparel and technical textile output.
- Fashion Brands:Direct equipment investment enables on-demand production pilots with 3D body scanning integration.
- Design Studios:Pattern development workflows prioritize software license flexibility over hardware ownership.
- Knitting Workshops:Small-batch operators in secondary markets favor refurbished electronic machines from Yangtze River Delta resale channels.
Highest equipment turnover: Garment Manufacturers. Fastest software subscription adoption: Fashion Brands.
Technology:
Component-level specification determines compatibility with predictive maintenance platforms and energy-efficiency mandates.
- Software Integration:Cloud-based pattern libraries and CAD-to-machine data pipelines enable subscription revenue models that decouple from hardware sales. REACH-compliant lubricant formulations and ECHA substance restrictions create dual inventory requirements for equipment operating across EU and non-EU facilities.
- Motion Control Systems:Servo motor calibration expertise concentrates in aging European workforces, extending commissioning timelines for high-precision installations.
- Needle Bed Technology:Hardened steel gauge components face supply concentration in German and Swiss specialty metallurgy suppliers.
- Stitch Formation Technology:Loop transfer mechanisms determine fabric structure versatility for technical applications.
- Yarn Feeding Technology:Tension monitoring integration with real-time adjustment eliminates manual intervention during complex sequences.
Deepest margin capture: Software Integration. Fastest capability convergence: Motion Control Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in East Asian manufacturing belts while consumption distributes across European technical textile hubs and South Asian garment export zones. This geographic split shapes divergent equipment specifications and certification requirements.
China
Zhejiang and Jiangsu province textile clusters source computerized flat knitting machines for circularity-compliant apparel exports to European fashion brands. MIIT enforces GB energy-efficiency Grade 2 thresholds on imported equipment, creating clearance delays at Ningbo and Shanghai ports. Yangtze River Delta integrated mills deploy multi-gauge systems for captive technical textile output.
Germany
Automotive airbag fabric producers in Baden-Württemberg retrofit climate-controlled knitting floors to maintain supplier certifications under EU F-Gas Regulation. ECHA REACH compliance reshapes lubricant procurement for equipment operating across EU and non-EU facilities. Stuttgart-region technical textile specialists source 18-gauge precision systems from Swiss and domestic metallurgy suppliers.
Japan
Medical compression garment manufacturers in Osaka prefecture deploy multi-gauge systems meeting implantable mesh standards. METI promotes JIS-certified smart manufacturing integration affecting software protocol requirements for exported equipment. METI traceability protocols enable healthcare supply chain verification for Kansai-region producers.
India
PLI scheme incentives for automotive and geotextile manufacturing attract multi-gauge system vendors establishing service networks in Tamil Nadu and Gujarat. BIS certification timelines compress for textile machinery imports under streamlined procedures. Surat and Tiruppur knitting clusters upgrade from refurbished electronic machines to capture higher-value contract knitwear.
Vietnam
Garment manufacturers in Ho Chi Minh City and Dong Nai province comparison-shop maintenance contracts independently from equipment acquisition. Secondary market electronic machines from Yangtze River Delta resale channels displace new equipment demand. Binh Duong industrial zones host mid-scale producers upgrading from mechanical systems for complex jacquard sequences.
Flat Knitting Machine Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three discernible tiers. Integrated textile machinery groups leverage cross-product service networks while dedicated knitting equipment builders defend margin pools through software ecosystem lock-in. Strategic archetypes include: design-to-production software integrators, multi-gauge engineering specialists, and scale-driven volume manufacturers. Geographic expansion and technology licensing dominate competitive moves as vendors navigate divergent certification timelines between CE marking and SAMR protocols.
Among Japanese precision equipment builders, Shima Seiki Mfg., Ltd. and Fukuhara Corp., Ltd. occupy positions within the software-integrated tier. German engineering-focused specialists include H. Stoll GmbH & Co. KG and Terrot GmbH, representing the multi-gauge systems archetype. At the scale-driven end, Cixing Textile Machinery Co., Ltd. exemplifies volume-tier positioning through Yangtze River Delta manufacturing concentration. Mayer & Cie. and Brother Industries, Ltd. sit within diversified conglomerate structures where knitting equipment represents one vertical among broader textile or industrial machinery portfolios.
| Leading Market Players |
|---|
| Mayer & Cie. |
| Fukuhara Corp., Ltd. |
| Shima Seiki Mfg., Ltd. |
| Protti S.r.l. |
| Changshu Changhua Smart Manufacturing Technology Co., Ltd. |
| H. Stoll GmbH & Co. KG |
| Terrot GmbH |
| Cixing Textile Machinery Co., Ltd. |
| Brother Industries, Ltd. |
| Others |
Supply & Pricing Matrix
REACH-compliant lubricant procurement mandates from European automotive textile buyers are forcing equipment vendors to dual-source formulations, fragmenting supplier relationships and compressing margin pools across computerized system tiers.
Pricing Analysis
Margin tightening in premium computerized tiers reflects software licensing unbundling from hardware sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Cost-down pressure on mid-scale electronic machines accelerates because refurbished Yangtze River Delta secondary market units displace new equipment demand in Vietnam and Bangladesh. Garment manufacturers in Southeast Asian export zones exhibit highest price sensitivity, while Japanese medical textile producers show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale integrated mill demand in China's Yangtze River Delta, while distributor networks serve fragmented garment workshop procurement in Vietnam and India. Hardened steel gauge components draw from German and Swiss specialty metallurgy suppliers. Servo motor systems and variable-frequency drives rest on East Asian electronics manufacturing. Single-source vulnerability concentrates in 18-gauge and finer precision tooling. Distribution runs through authorized service networks for software-integrated systems and gray-market refurbishment chains for mechanical legacy units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computerized flat knitting machines are displacing mechanical and electronic systems across fashion and technical textile applications, creating asymmetric opportunity windows for positioned players.
For Market Incumbents: To counter software-hardware decoupling threats, anchor premium positioning through pattern ecosystem lock-in with CAD-to-machine data pipelines. Secure backward integration into hardened steel gauge component supply through partnerships with Stuttgart-region metallurgy specialists. Defend service revenue pools by unbundling maintenance contracts only for high-volume commodity segments. For New Entrants and Emerging Players: Launch via cloud-based pattern library subscriptions targeting design studios and fashion brands piloting on-demand production. India's Tamil Nadu and Gujarat technical textile corridors offer most penetrable geography given PLI scheme incentives and nascent multi-gauge system penetration. Lead with AI-driven pattern optimization to compress sample lead times for Como silk district producers. For Investors and Strategic Acquirers: The window for entry favors software-integrated specialists with JIS or CE certification depth over undifferentiated volume manufacturers. Long-term viability hinges on recurring revenue share from pattern ecosystems rather than equipment sales cyclicality. Monitor MIIT enforcement velocity on GB energy-efficiency Grade 2 thresholds as inflection indicator for Chinese market access costs.| Strategic Initiative | Industry Significance |
|---|---|
| Software Licensing Unbundling | Recurring revenue streams from pattern ecosystems reduce capital barrier sensitivity for mid-scale garment producers in Bangladesh. |
| Multi-Gauge System Localization | Indian assembly operations bypass BIS certification delays while capturing PLI scheme automotive textile incentives. |
| Predictive Maintenance Platform Launch | AI-driven needle replacement scheduling reduces quality deviation for high-mix Como silk district jacquard producers. |
| REACH-Compliant Lubricant Dual-Sourcing | ECHA substance restriction compliance maintains EU automotive supplier certifications for Baden-Württemberg airbag fabric mills. |
| Secondary Market Refurbishment Network | Yangtze River Delta resale channels capture displaced demand from Vietnamese garment manufacturers facing margin pressure. |
Research Methodology
Trade association filings, customs import records, and machinery registration databases formed the secondary backbone, cross-referenced with primary interviews across plant engineers at integrated textile mills, procurement leads at garment export houses, aftermarket service heads at European machine builders, and regulatory affairs specialists navigating CE-SAMR divergence. Bottom-up equipment shipment tracking triangulated against top-down textile production capacity estimates.
Bottom-up modeling aggregated segment-level demand across product type, application, and technology dimensions over the projection horizon. CAGRs derived from regression analysis against textile output growth, regulatory replacement cycle triggers, and software adoption curves. Industry-specific inputs included MIIT enforcement schedules on GB energy-efficiency standards and ECHA REACH substance restriction timelines.
Regulatory enforcement delays, commodity steel price volatility, and technician training pipeline gaps are the dominant revision risks to installed base forecasts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Outdoor Fabric Market
Yarn and Fabric Manufacturing
Fancy Yarn Market
Yarn and Fabric Manufacturing
E-Glass Fiber Yarn and Roving Market
Yarn and Fabric Manufacturing
Mercerized Cotton Market
Yarn and Fabric Manufacturing
Canvas and Muslin Bags Market
Yarn and Fabric Manufacturing
Cotton Bags Market
Yarn and Fabric Manufacturing
Polypropylene Yarn Market
Yarn and Fabric Manufacturing
Europe Textile Market
Yarn and Fabric Manufacturing
Textile Fabrics Market
Yarn and Fabric Manufacturing
Global Tire Cord Fabrics Market
Yarn and Fabric Manufacturing
Spun Yarn Paper Cone Market
Yarn and Fabric Manufacturing
Knitting Cam Market
Yarn and Fabric Manufacturing
Printed Tissue Paper Market
Yarn and Fabric Manufacturing
Fiberglass Fabric Market
Yarn and Fabric Manufacturing
Knitted Fabric Market
Yarn and Fabric Manufacturing
Global Arab Thobe Fabric Market