
 Spandex Fiber Market | 2026-2036
Spandex Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Spandex Fiber Market Intelligence
Direct procurement from bulk distributors is tilting toward specialty chemical platforms serving mid-sized textile mills. Hyosung Corporation leverages captive production of precursor chemicals to sustain margin control across its spandex operations. INVISTA anchors North American supply through integrated polymerization facilities in the United States. Huafon Chemical dominates domestic filament volumes while competing on cost-engineered covered yarn variants.
Spandex fiber is a segmented polyurethane elastomer typically produced via solution dry-spinning or melt-spinning processes, yielding filaments with elongation capacities exceeding 500 percent for stretch-recovery applications in form-fitting garments. Continuous filament leads industrial throughput due to its compatibility with high-speed circular knitting machines, while medical textiles represent the fastest-growing application segment as hospitals demand compression-grade elasticity for post-surgical garments and wound-care supports. Covered yarn occupies a mature margin pool where established textile manufacturers bundle spandex with hard yarns to protect against price volatility in raw polymer feedstock.
REACH restricts diisocyanate monomer handling across European manufacturing sites, forcing reformulation investments that elevate compliance costs for exporters. OEKO-TEX Standard 100 certification shapes brand procurement rules as retailers mandate toxin-free fiber inputs for skin-contact apparel. China's GB standards and evolving MEE emissions protocols tighten solvent-recovery thresholds at domestic dry-spinning facilities. Stakeholders must monitor polymer precursor availability and regulatory divergence between Asian production hubs and European import markets when siting capacity or qualifying suppliers.
Market Dynamics
Spandex fiber production is consolidating around captive precursor supply chains as diisocyanate cost volatility and REACH compliance costs squeeze merchant producers without backward integration into polymer feedstock.
Growth Catalysts
- Activewear specification tightening:Performance brands now mandate minimum 500% elongation recovery in base-layer fabrics, pulling filament volumes from commodity apparel into technical sportswear.
- REACH chemical safety mandates:European formulators must certify diisocyanate-free handling protocols, accelerating replacement demand for pre-certified fiber imports from integrated Asian producers.
- Medical compression garments:Post-surgical recovery protocols in hospital systems are standardizing gradient-compression hosiery, opening a high-margin filament channel distinct from apparel cyclicality.
Market Restraints
- PTMEG feedstock concentration:Polytetramethylene ether glycol supply clusters in Chinese and Korean petrochemical corridors, exposing non-integrated spinners to input cost spikes during cracker maintenance cycles.
- Dry-spinning solvent recovery:MEE emissions thresholds at Chinese manufacturing sites require capital-intensive thermal oxidizer installations that raise breakeven volumes for mid-scale producers.
- Polyester elastomer substitution:Thermoplastic polyester elastomers from compounders are capturing lower-stretch intimates and swimwear segments where 200-300% elongation suffices.
Strategic Opportunities
- India technical textiles corridor:PLI scheme incentives for man-made fiber production are drawing spandex filament investment toward Surat and Tiruppur knitting clusters.
- Recycled-content spandex:Chemical recycling of post-industrial elastomer waste into repolymerized PTMEG precursors is opening circular sourcing claims for OEKO-TEX-certified brands.
- Digital textile printing compatibility:Low-temperature dye-sublimation adhesives are converging with high-heat-resistant spandex copolymers, enabling on-demand printed activewear with retained stretch performance.
Industry Challenges
- Dry-spinning operator expertise:Solution concentration control and filament denier consistency require tacit knowledge that is aging out of European and North American workforces without structured apprenticeship pipelines.
- Multi-certification stacking:Simultaneous OEKO-TEX Standard 100, ZDHC MRSL, and brand-specific RSL compliance creates documentation burdens that extend qualification timelines for new supplier onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spandex Fiber Market |
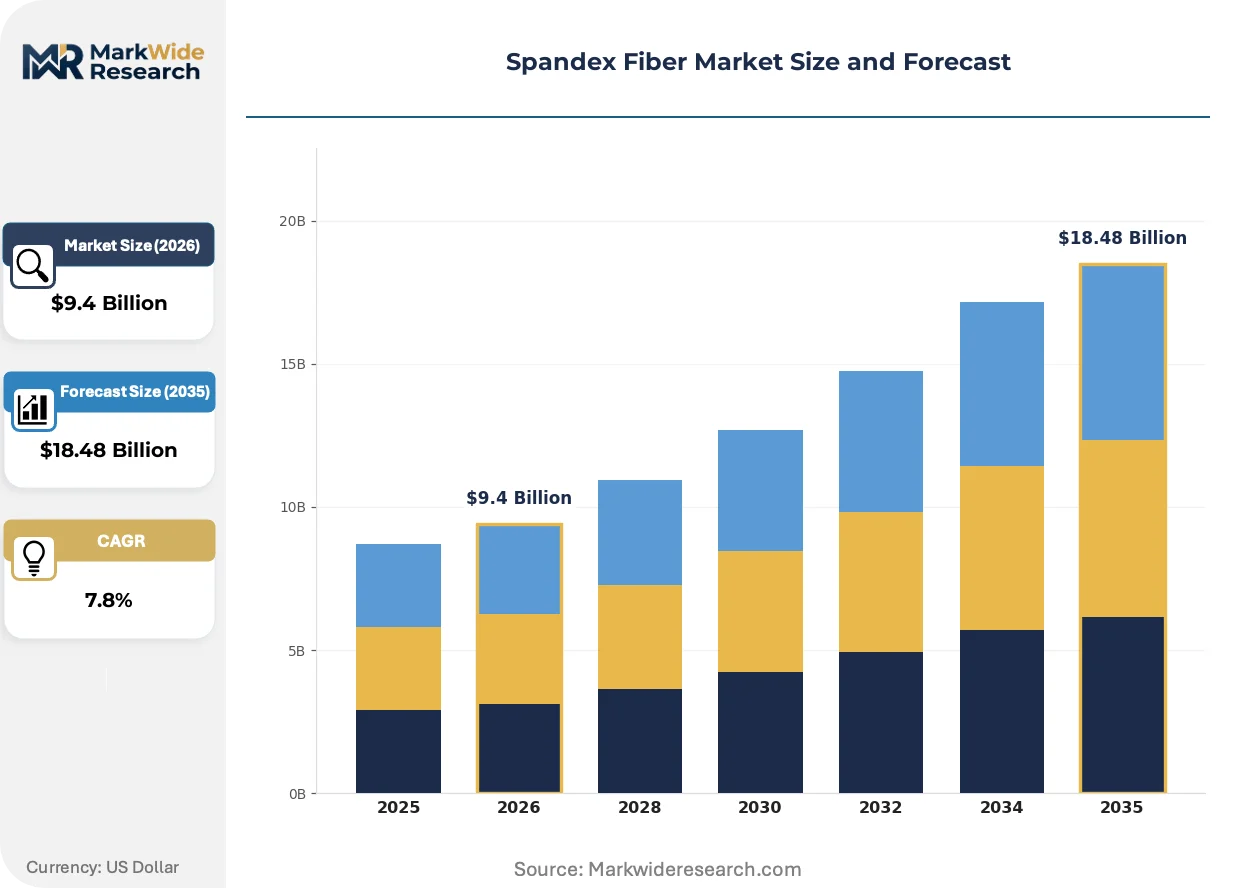
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $18.48 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Filament, Crimped Yarn, Textured Yarn, Covered Yarn Application: Activewear, Swimwear, Medical Textiles, Hosiery End User: Textile Manufacturers, Retailers, Hospitals, Fitness Brands Distribution Channel: Online Retail, Specialty Stores, Bulk Distributors, Direct Sales |
| Companies Covered | Hyosung Corporation, INVISTA, Toray Industries, Asahi Kasei Corporation, Huafon Chemical Co., Ltd., Indorama Corporation, Teijin Limited, TK Chemical Corporation, Taekwang Industrial Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spandex Fiber Market Strategic Shifts & Innovations
Spandex manufacturing is pivoting from commodity filament supply toward co-engineered stretch solutions where fiber properties are tuned to specific end-use mechanical requirements and regulatory constraints.
Bio-based PTMEG feedstocks derived from renewable butanediol are hybridizing with conventional petroleum-derived polymer streams, allowing fiber producers to offer mass-balance certified products without sacrificing tensile performance. Sportswear brands with science-based targets are adopting these hybrid formulations fastest, compressing price premiums for sustainable elastomers toward parity with standard grades within three qualification cycles.
REACH diisocyanate restrictions are forcing European compounders to reformulate prepolymer systems or relocate finishing stages to non-EU jurisdictions, fragmenting supply chain geography for brands maintaining EU manufacturing claims. Medical device manufacturers are responding by dual-qualifying Asian filament sources to ensure uninterrupted access for compression garment production.
Direct mill procurement through specialty chemical platforms is displacing traditional distributor networks for mid-volume textile operations seeking lot-traceable fiber with embedded compliance documentation. This channel shift is most visible in Portugal and Italy where knitwear SMEs are consolidating purchases through pooled procurement consortia to meet minimum order quantities for certified filament.
Spandex Fiber Market Segmentation
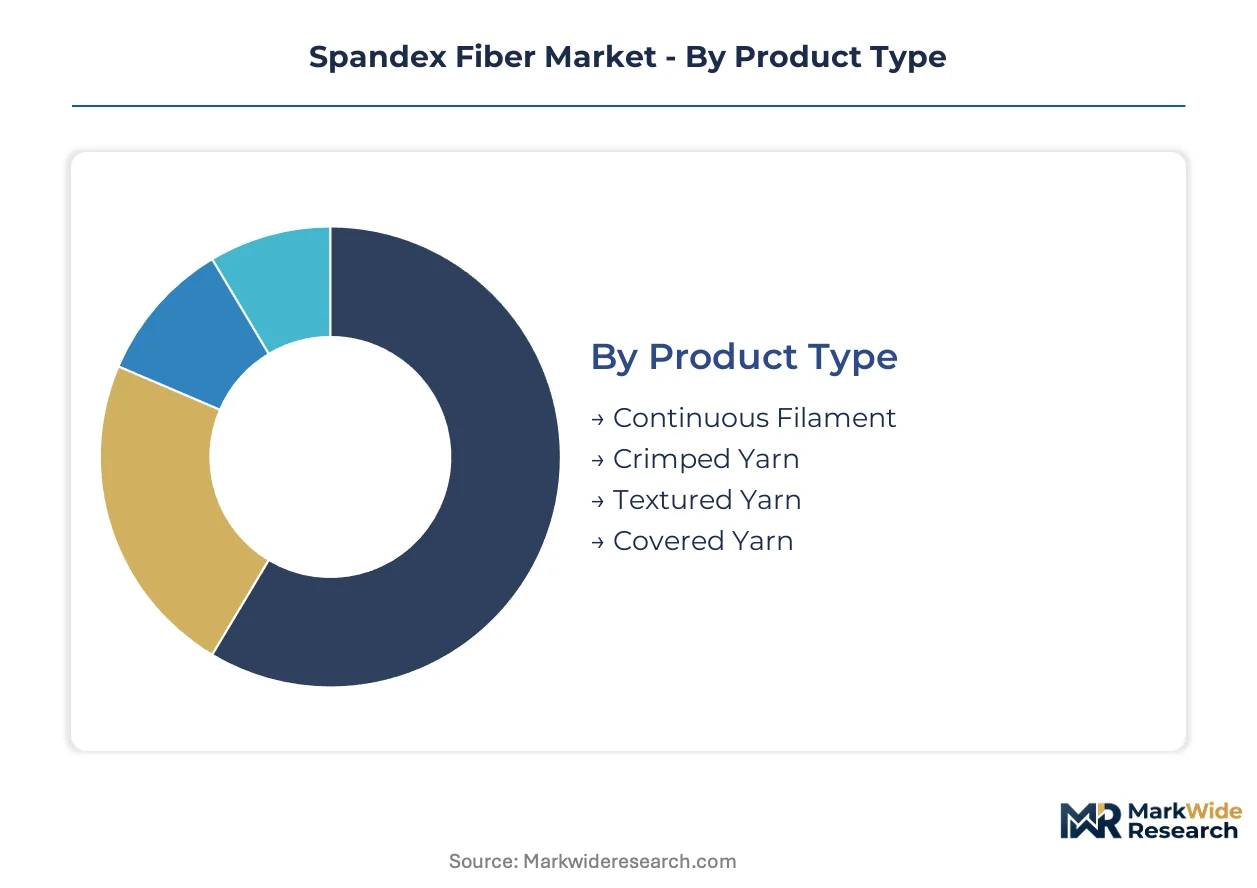
Spandex fiber segmentation reflects divergent technical requirements across apparel performance tiers and regulatory compliance thresholds. Manufacturers tune polymer formulations and spinning methods to match end-use elasticity specifications while navigating certification demands from OEKO-TEX and REACH.
Product Type:
Cost tier differentiation separates commodity filament from engineered yarn constructions serving premium elasticity specifications.
- Continuous Filament:Solution dry-spun polyurethane elastomer delivered as bare fiber with elongation exceeding 500 percent. Demand concentrates in high-speed circular knitting operations serving activewear brands in China and Vietnam, where throughput velocity justifies the capital intensity of dedicated spinning lines.
- Covered Yarn:Spandex core wrapped with nylon or polyester hard yarns to buffer against raw polymer price volatility. European textile mills in Portugal and Italy favor this construction for mid-market intimates, trading some elasticity range for supply chain stability during PTMEG feedstock disruptions.
- Crimped Yarn:Mechanical texturing creates bulk and stretch through fiber geometry rather than polymer chemistry.
- Textured Yarn:Air-jet or false-twist processing imparts surface character and modified hand-feel for fashion applications.
Continuous filament commands the established base. The steepest expansion runs through covered yarn as mills seek price-hedged alternatives.
Application:
Application segmentation tracks performance requirements from recreational stretch to medical-grade compression engineering.
- Activewear:Base-layer and compression sportswear demanding 500 percent minimum elongation recovery with moisture-wicking compatibility. North American and European brands now specify OEKO-TEX Standard 100 certification as table stakes, pulling volume toward pre-qualified Asian filament sources.
- Medical Textiles:Post-surgical compression garments and wound-care supports requiring gradient elasticity calibrated in millimeters of mercury. Hospital systems in Germany and the United States are standardizing procurement protocols for these devices, opening a channel with pricing power distinct from apparel cyclicality.
- Swimwear:Chlorine-resistant formulations for recreational and competitive aquatic apparel.
- Hosiery:Traditional pantyhose and socks where moderate stretch and cost efficiency dominate purchasing decisions.
Hosiery retains the volume base. Medical textiles are climbing the fastest as healthcare systems formalize compression therapy protocols.
End User:
Customer type determines procurement scale, certification burden, and technical service intensity from fiber suppliers.
- Textile Manufacturers:Mid-to-large scale knitting and weaving operations purchasing filament in tonnage lots with embedded compliance documentation. Mills in Surat and Tiruppur are consolidating through pooled procurement consortia to meet minimum order thresholds for certified grades.
- Fitness Brands:Direct material specification by performance apparel labels with science-based sustainability targets. These buyers are accelerating adoption of bio-based PTMEG hybrid formulations, compressing price premiums toward parity with conventional grades.
- Retailers:Private-label apparel programs with standardized fiber specifications across supplier bases.
- Hospitals:Institutional procurement of compression garments with device-class regulatory requirements.
Textile manufacturers anchor established demand. Fitness brands are gaining share fastest as direct specification authority shifts downstream.
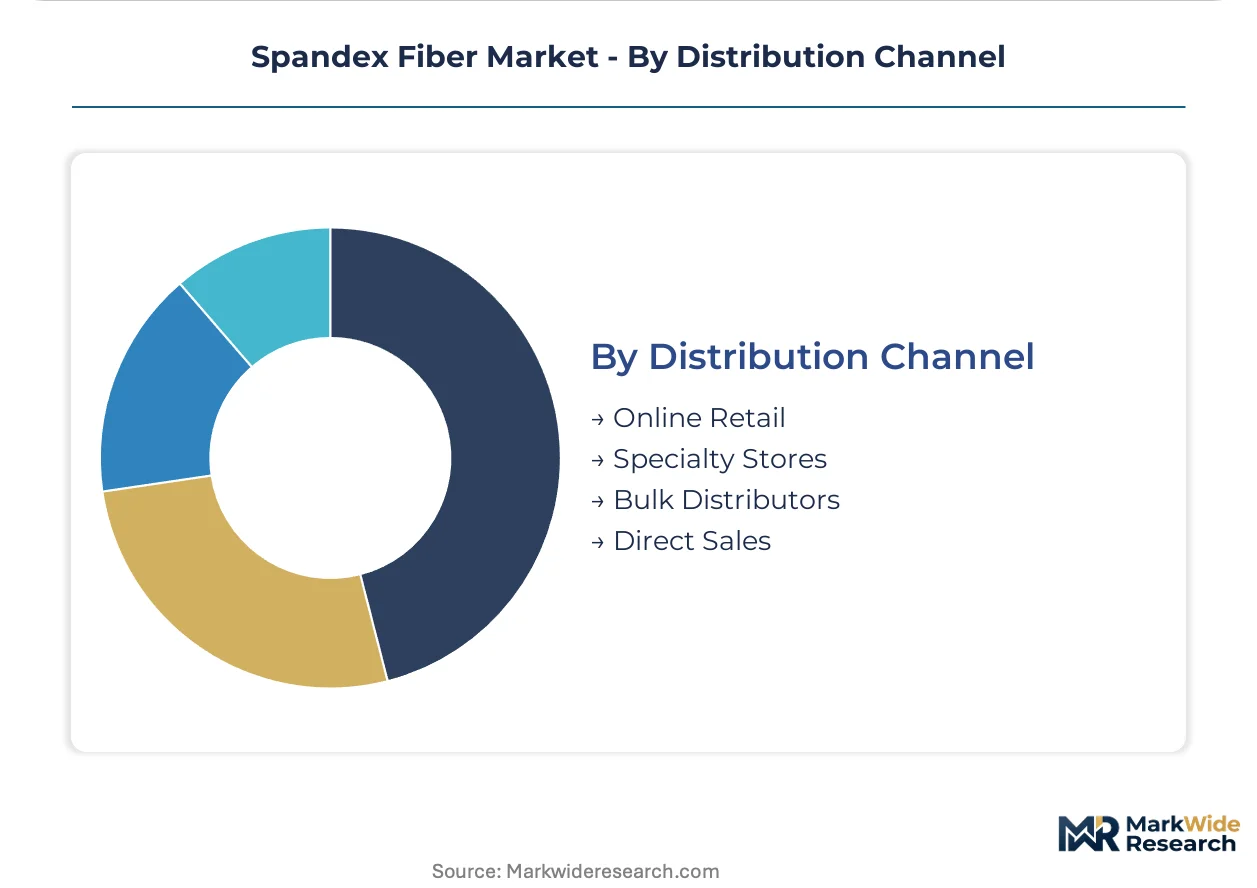
Distribution Channel:
Channel structure reflects lot-traceability requirements and order-size economics across customer segments.
- Bulk Distributors:Traditional intermediaries holding inventory for spot purchases by smaller mills. Portuguese and Italian knitwear SMEs are migrating away from this channel toward specialty chemical platforms offering embedded compliance documentation and pooled procurement structures.
- Direct Sales:Mill-direct relationships for volume accounts with customized denier and finish specifications. Hyosung Corporation and INVISTA anchor this channel through integrated polymerization and spinning operations that guarantee feedstock traceability.
- Online Retail:E-commerce platforms serving small-batch designers and prototyping operations.
- Specialty Stores:Regional distributors with technical service capabilities for niche applications.
Bulk distributors retain the incumbent position. Direct sales are expanding most quickly as certification stacking demands supplier intimacy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao and Shanghai port complexes anchor Asia-Pacific spandex logistics, handling bulk PTMEG feedstock imports and finished filament exports for circular knitting mills across the region.
China
Activewear brands in Fujian and Zhejiang provinces pull continuous filament volumes toward technical sportswear specifications. MEE emissions protocols tighten solvent-recovery thresholds at dry-spinning facilities in Shaoxing and Shengze. The Yangtze River Delta clustering concentrates Hyosung Corporation and Huafon Chemical operations alongside downstream textile mills in Suzhou and Nantong.
United States
Hospital systems in Texas and Florida standardize procurement protocols for post-surgical compression garments. FDA device-class regulations shape qualification timelines for medical-grade filament imports. INVISTA anchors North American polymerization capacity at integrated facilities in the Southeast, supplying domestic knitting operations in North Carolina.
Germany
REACH diisocyanate restrictions force reformulation investments at compounders serving medical textile OEMs in Baden-Württemberg. ECHA certification mandates accelerate replacement demand for pre-certified fiber imports. The Stuttgart industrial corridor hosts compression garment manufacturers dual-qualifying Asian filament sources to ensure supply continuity.
India
PLI scheme incentives for man-made fiber production draw spandex investment toward Surat and Tiruppur knitting clusters. BIS quality standards tighten lot-traceability requirements for imported filament. Maharashtra-based textile mills consolidate purchases through pooled procurement consortia to meet minimum order thresholds for OEKO-TEX-certified grades.
Vietnam
Garment export factories in Ho Chi Minh City and Binh Duong province absorb filament volumes for activewear cut-and-sew operations serving North American brands. The country's national chemical safety regulator enforces handling protocols for diisocyanate-containing inputs at bonded warehouse facilities. Da Nang port infrastructure supports just-in-time feedstock delivery from Korean petrochemical suppliers.
Spandex Fiber Market Key Industry Players
On the supply side, the industry is consolidating around captive precursor supply chains as feedstock cost volatility squeezes merchant producers without backward integration. Two strategic archetypes dominate: integrated petrochemical-spinning hybrids with in-house PTMEG production, and regional filament specialists serving mid-scale textile mills through distributor networks. Dominant competitive moves include capacity expansion in low-cost manufacturing jurisdictions and technology licensing agreements to bypass REACH compliance barriers in European markets.
Among Asia-Pacific integrated producers, Hyosung Corporation exemplifies the captive-precursor archetype through its Korean petrochemical base, while Huafon Chemical Co., Ltd. occupies a position within China's cost-engineered filament tier. INVISTA anchors the North American supply structure through United States-based polymerization operations. These three entities collectively represent the geographic and structural diversity of upstream spandex manufacturing, spanning Korean chaebol, Chinese private-sector chemical groups, and American multinational fiber operations.
| Leading Market Players |
|---|
| Hyosung Corporation |
| INVISTA |
| Toray Industries |
| Asahi Kasei Corporation |
| Huafon Chemical Co., Ltd. |
| Indorama Corporation |
| Teijin Limited |
| TK Chemical Corporation |
| Taekwang Industrial Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Overcapacity warnings from Shaoxing dry-spinning facilities signal margin compression across Asian filament exports, forcing suppliers into volume-discount negotiations while buyers consolidate procurement through pooled consortia to extract pricing leverage.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEKO-TEX-certified medical grades from commodity activewear filament and unbranded hosiery inputs. Price differentiation hinges on certification stacking burden and volume scale, with multi-certification tiers commanding premiums against spot-market commodity grades. Pricing pressure stems from PTMEG feedstock volatility during Korean petcracker maintenance cycles. Small Portuguese knitwear SMEs exhibit highest price sensitivity, while hospital procurement committees prioritize compliance documentation over unit cost.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk calculus for North American activewear brands qualifying alternative filament sources. Manufacturing concentrates in China, South Korea, and Vietnam, with PTMEG, MDI, and spinning solvent feedstock dependencies anchored in Korean and Chinese petrochemical corridors. Single-source vulnerability concentrates at Korean PTMEG producers supplying Asian spinning operations. Distribution runs through specialty chemical platforms displacing traditional bulk distributors for mid-volume textile mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Activewear specification tightening fragments demand into performance-tier niches, creating entry points for specialized filament producers against commodity incumbents.
For Market Incumbents: Entrench captive precursor control through backward integration into PTMEG production or long-term offtake agreements with Korean petrochemical suppliers. Accelerate OEKO-TEX Standard 100 and ZDHC MRSL certification stacking to defend against Asian integrated producers pre-qualified for European medical textile procurement. Prioritize capacity utilization management at Shaoxing and Shengze facilities to prevent margin-eroding overcapacity signals. For New Entrants and Emerging Players: Build out recycled-content spandex capabilities targeting fitness brands with science-based sustainability targets, where chemical recycling of post-industrial elastomer waste opens circular sourcing claims. Focus initial penetration on India's Surat and Tiruppur knitting clusters, where PLI scheme incentives and pooled procurement consortia reduce minimum order threshold barriers. Pursue digital textile printing compatibility as a technical differentiation angle for on-demand activewear segments. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because captive precursor integration determines margin sustainability as feedstock volatility intensifies. Target regional filament specialists with established distributor relationships in Portugal and Italy's knitwear corridors but lacking backward integration. Monitor MEE emissions compliance investments at Chinese dry-spinning facilities as an inflection signal for cost-competitive capacity rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PTMEG | Captive precursor supply insulates margin from Korean petrochemical price spikes. |
| Multi-Certification Investment | Simultaneous OEKO-TEX and ZDHC MRSL qualification accelerates hospital procurement access. |
| Recycled-Content Scale-Up | Chemical recycling infrastructure enables circular sourcing claims for fitness brand compliance. |
| India Manufacturing Footprint | PLI scheme incentives in Surat and Tiruppur reduce landed cost for European knitwear mills. |
| Specialty Chemical Platform Partnership | Lot-traceable procurement consortia meet Portuguese and Italian SME compliance documentation demands. |
Research Approach
Initial hypotheses were tested against primary input from spinning plant managers, textile procurement leads at Portuguese and Italian knitwear mills, distribution channel partners, and technical R&D directors at fiber producers, and refined through secondary validation against customs and trade data, chemical industry association reports, SEC 10-K filings, and regulatory agency certification databases. Bottom-up filament volume estimates from individual facility capacities were triangulated against top-down demand projections derived from end-use consumption patterns.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling continuous filament, covered yarn, and crimped yarn product tiers alongside activewear, medical textile, swimwear, and hosiery applications. CAGRs were derived from elasticity-adjusted consumption coefficients applied to regional knitting and weaving capacity expansion trajectories, with feedstock cost pass-through assumptions and certification adoption curves as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-backed chemical groups or sudden REACH enforcement escalations would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
High End Synthetic Suede Market
Synthetic Fibers
Polybenzoxazole Fibers Market
Synthetic Fibers
Carbon Fiber Strands Market
Synthetic Fibers
Performance Fabric Market
Synthetic Fibers
Polyimide Fiber Market
Synthetic Fibers
Polyester Strap for Manual Grade Market
Synthetic Fibers
Sic Fibers Market
Synthetic Fibers
US Textile Market
Synthetic Fibers
Polyethylene Terephthalate (PET) Fiber Market
Synthetic Fibers
Polyester Tire Cord Fabrics Market
Synthetic Fibers
High-Strength Polyester Thread Market
Synthetic Fibers
Designer Fiber Market
Synthetic Fibers
Polyester Fibers Market
Synthetic Fibers
North America Aramid Fiber Market
Synthetic Fibers
Synthetic Sewing Thread Market
Synthetic Fibers
Textile Fibers Market