
 Europe Nanofiber Market | 2026-2036
Europe Nanofiber Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Nanofiber Market Foresight
REACH is hardening the cost-of-entry calculus for nanofiber producers seeking European market access. DuPont leverages its polymer science heritage to sustain differentiated electrospun product lines. Elmarco s.r.o. anchors the regional equipment supply base with specialized needle-free electrospinning systems. TORAY INDUSTRIES, INC. competes through controlled membrane architectures serving high-specification filtration buyers.
Nanofibers are synthetic or natural polymer fibers with diameters below 100 nanometers, typically produced via electrospinning, melt blowing, or solution blow spinning processes that draw molten or dissolved polymers through electric fields or high-velocity gas streams to create non-woven mats with exceptional surface-area-to-volume ratios. These structures function primarily as precision barriers, scaffolds, or conductive substrates across filtration, biomedical, textile, and energy storage applications. Electrospun nanofibers dominate current manufacturing output due to mature equipment ecosystems and versatile polymer compatibility, while melt blown variants command premium positioning in automotive cabin air filtration where thermal resilience matters. Biomedical applications represent the fastest-expanding demand pool, with nanolithography-enabled patterning creating specialized niches for cell-culture substrates and drug-delivery matrices.
EMA medical device regulations and ECHA substance restrictions shape product development timelines and material selection protocols for nanofiber developers. The EU Green Deal's chemical sustainability mandates are redirecting R&D investment toward bio-based polymer feedstocks and closed-loop solvent recovery systems. CE marking requirements under the MDR framework add compliance layers for implantable nanofiber devices entering clinical supply chains. Stakeholders must monitor how the EU AI Act intersects with automated quality-control systems in nanofiber manufacturing lines.
Market Dynamics
REACH compliance deadlines and the EU Green Deal's chemical sustainability mandates are compressing product development timelines while redirecting capital toward bio-based feedstocks and closed-loop solvent recovery systems across European nanofiber manufacturing.
Growth Catalysts
- Automotive filtration demand:German and French OEMs are integrating nanofiber cabin air filters to meet stringent interior air quality standards, creating pull-through for electrospun membrane suppliers.
- EMA medical device pathways:Accelerated CE marking procedures under the MDR framework are shortening time-to-market for implantable nanofiber scaffolds in Nordic biomedical corridors.
- Electrospinning equipment maturation:Specialized needle-free systems from Czech manufacturing clusters are reducing barrier-to-entry for mid-scale producers serving regional filtration buyers.
Market Restraints
- Acrylonitrile and fluoropolymer input volatility:Petrochemical feedstock price swings compress margin predictability for producers reliant on synthetic polymer precursors.
- Equipment supply concentration:Needle-free electrospinning system availability depends heavily on Central European specialized machinery vendors, creating single-source vulnerability.
- ECHA substance restriction scope creep:Expanding SVHC candidate list uncertainty delays material qualification timelines and freezes R&D portfolio decisions.
Strategic Opportunities
- Spanish and Italian textile modernization:Underpenetrated southern European markets present whitespace for nanofiber-enabled functional fabric integration in technical textile segments.
- EU AI Act alignment:Automated quality-control system vendors can capture premium positioning by certifying machine-vision inspection platforms for nanofiber manufacturing lines.
- Closed-loop solvent recovery:Chemical recycling infrastructure partnerships in German industrial clusters enable circular economy claims that differentiate against import competition.
Industry Challenges
- Electrospinning process engineering talent scarcity:European universities produce insufficient graduates with combined polymer science and high-voltage systems expertise to staff expanding production facilities.
- CE marking timeline compression:MDR technical documentation requirements for implantable devices extend certification cycles beyond traditional product development budgets.
- Legacy filtration incumbent adaptation:Established melt-blown producers face technical retooling costs and workforce retraining burdens to compete with electrospun performance specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Nanofiber Market |
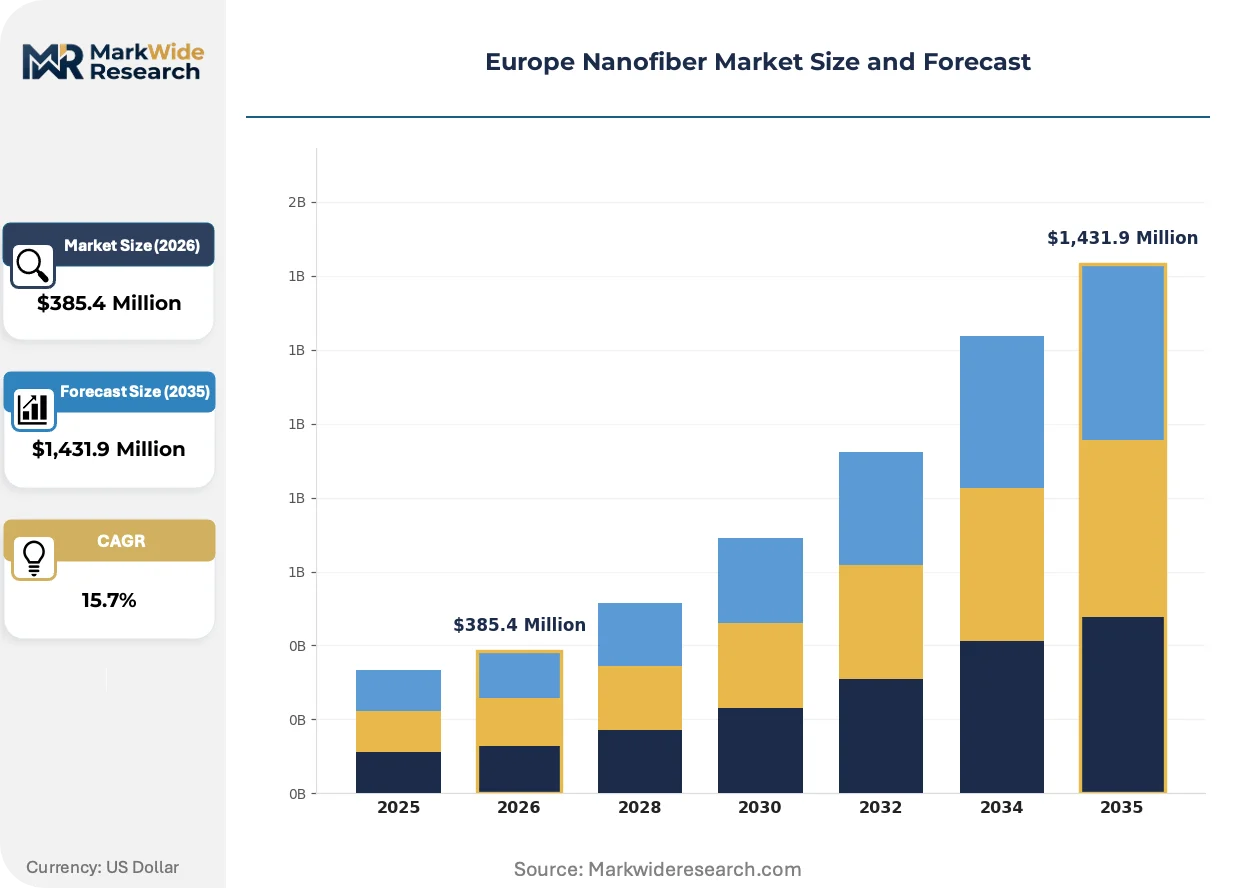
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,431.9 Million |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrospun Nanofibers, Melt Blown Nanofibers, Solution Blow Spinning Nanofibers, Others Application: Filtration, Biomedical, Textile, Energy Storage End User: Healthcare, Automotive, Consumer Electronics, Defense Technology: Nanofluidic Technology, Nanolithography, Biocompatible Techniques, Others |
| Companies Covered | Mitsubishi Chemical Corporation, Hollingsworth & Vose, TORAY INDUSTRIES, INC., Ahlstrom-Munksjo, Asahi Kasei Corporation, Donaldson Company, Inc., DuPont, Elmarco s.r.o., eSpin Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Nanofiber Market Shifts & Advancements
European nanofiber production is pivoting from commodity filtration toward high-specification biomedical and energy storage applications, driven by regulatory pressure on material provenance and end-of-life handling.
Cellulose nanofiber substrates derived from agricultural waste streams are overtaking petroleum-based alternatives in wound-care and drug-delivery applications. Scandinavian pulp processors and Dutch biotech formulators are scaling pilot lines to serve pharmaceutical contract manufacturers seeking REACH-compliant sourcing. This feedstock transition is compressing synthetic polymer incumbent margins while opening valorization partnerships with food processing waste generators.
The EU Green Deal's chemical sustainability mandates are forcing solvent selection revisions across electrospinning operations. Dimethylformamide recovery system investments now dominate capex planning for German and French production facilities, with ECHA guidance on worker exposure limits accelerating substitution toward aqueous and supercritical CO2-based processes. Biomedical-grade producers face the steepest compliance curves due to residual solvent validation requirements under MDR Annex I.
Automotive OEMs are consolidating nanofiber filter procurement under long-term framework agreements with tier-one suppliers, displacing spot-market purchasing for cabin air and battery ventilation applications. German premium vehicle manufacturers now specify electrospun membrane performance thresholds in supplier quality handbooks, compressing qualification cycles for second-source entrants. This concentration is most visible in Baden-Württemberg supplier clusters serving Stuttgart-based powertrain engineering centers.
Europe Nanofiber Market Segmentation
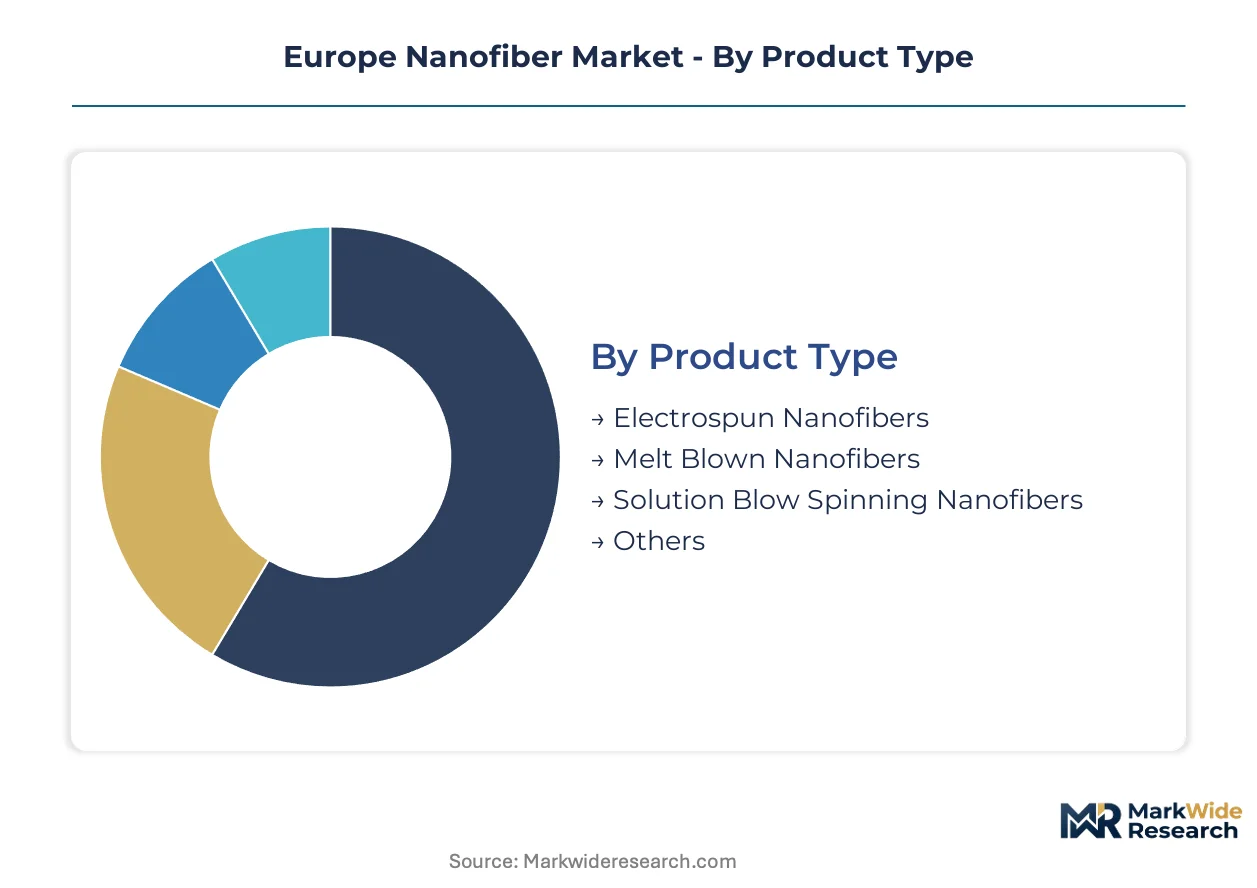
Segmentation in the Europe nanofiber market reveals how manufacturing methods, application requirements, and end-use specifications create distinct competitive arenas. Each dimension carries different regulatory burdens and margin structures that shape supplier positioning across German industrial clusters and Nordic biomedical corridors.
Product Type:
Integration depth varies sharply: electrospun variants function as standalone membrane products sold directly to filter assemblers, while melt blown grades embed within multi-layer composite structures where thermal bonding demands dictate specification.
- Electrospun Nanofibers:Produced via high-voltage polymer jet drawing onto grounded collectors, these fibers achieve sub-100 nanometer diameters with exceptional surface-area-to-volume ratios. German automotive OEMs in Baden-Württemberg specify electrospun cabin air filters to meet interior air quality standards under REACH substance restrictions.
- Melt Blown Nanofibers:Thermoplastic polymers extrude through heated dies with high-velocity air attenuation, yielding fibers optimized for thermal resilience rather than minimum diameter. French battery ventilation system manufacturers favor melt blown constructions for their tolerance of powertrain thermal cycling.
- Solution Blow Spinning Nanofibers:Compressed gas drives polymer solution through specialized nozzles without electric fields, enabling faster throughput for commodity filtration applications.
- Others:Centrifugal spinning and template synthesis methods serve niche biomedical scaffold requirements where fiber alignment control outweighs production speed.
Volume placements concentrate in Electrospun Nanofibers; the faster expansion belongs to Solution Blow Spinning Nanofibers as mid-scale producers seek throughput advantages.
Application:
Cost tier separation dominates this dimension: filtration commands economy-scale pricing with automotive volume contracts, while biomedical applications sustain premium positioning through MDR compliance costs and validation timelines.
- Filtration:Cabin air, HVAC, and liquid filtration membranes represent the established revenue base. Czech equipment suppliers anchor regional production capacity for this segment.
- Biomedical:Wound dressings, drug delivery matrices, and tissue engineering scaffolds require EMA pathway navigation and residual solvent validation under MDR Annex I. Nordic research corridors in Sweden and Denmark drive fastest adoption.
- Textile:Functional fabric integration in protective apparel and sportswear leverages nanofiber surface properties for moisture management and barrier performance.
- Energy Storage:Battery separator membranes and fuel cell electrodes demand controlled porosity architectures that electrospinning delivers with precision.
Revenue gravity sits with Filtration; Biomedical climbs the fastest as pharmaceutical contract manufacturers seek REACH-compliant sourcing alternatives.
End User:
Customer type fragmentation creates distinct procurement patterns: healthcare buyers prioritize regulatory documentation depth, while automotive purchasers emphasize supplier quality handbook conformance and long-term framework agreements.
- Healthcare:Hospitals, clinics, and pharmaceutical manufacturers drive demand for implantable scaffolds and sterile wound care products. CE marking under MDR compresses viable supplier pools to established European manufacturers.
- Automotive:German and French OEMs integrate nanofiber filters across cabin air, battery ventilation, and powertrain applications. Stuttgart-based engineering centers specify performance thresholds that tier-one suppliers must meet.
- Consumer Electronics:Acoustic membranes and display protection films utilize nanofiber thinness for device miniaturization.
- Defense:CBRN protection and ballistic applications require specialized fiber architectures with restricted supplier access.
Procurement volume clusters in Automotive; Healthcare demonstrates the steepest expansion trajectory as EMA accelerated pathways shorten time-to-market.
Technology:
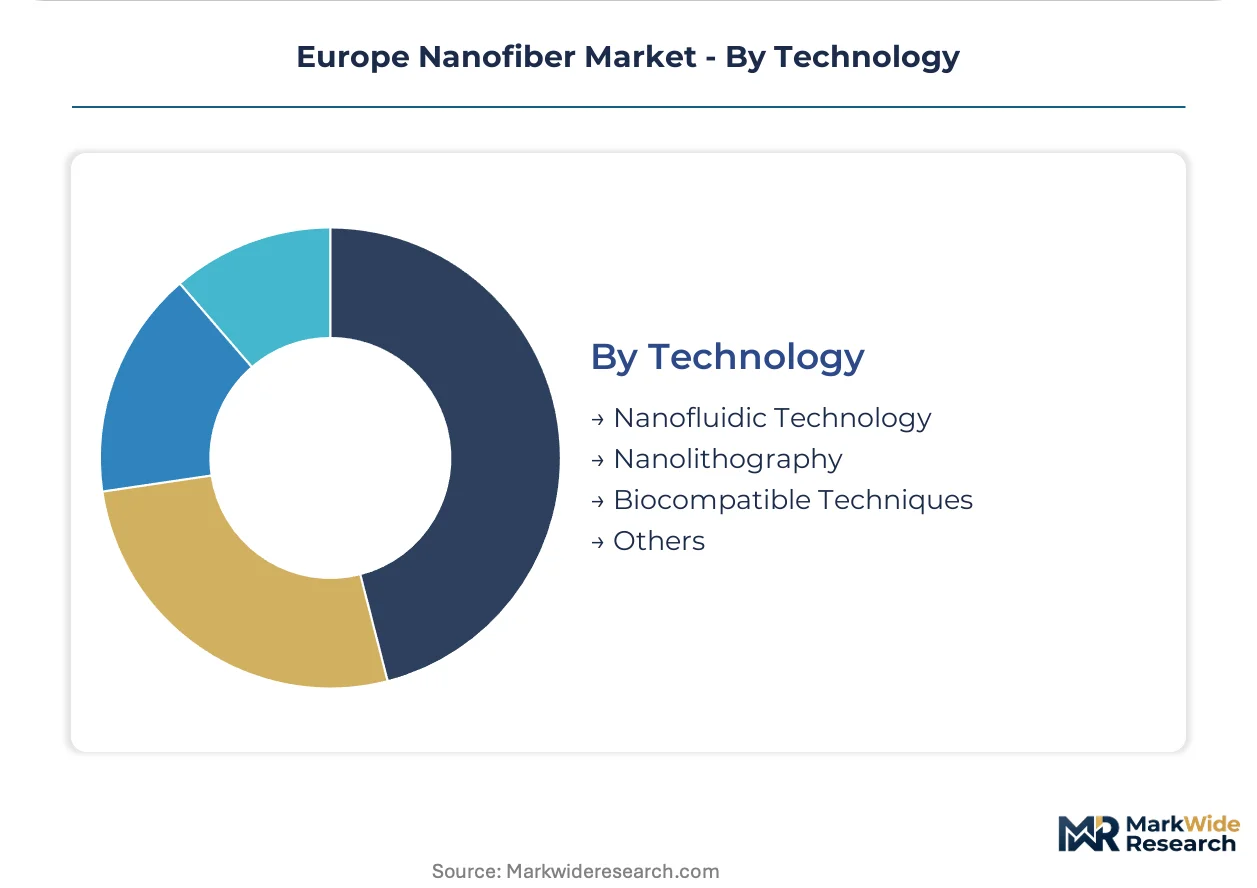
Maturity gradients separate this dimension: nanofluidic and nanolithography methods remain development-stage with limited commercial deployment, while biocompatible techniques scale for regulatory-validated production.
- Nanofluidic Technology:Fluid confinement in nanochannels enables precise fiber diameter control and surface functionalization. Research-stage applications dominate current deployment.
- Nanolithography:Patterning techniques create specialized cell-culture substrates with defined topographical cues. Dutch biotech formulators pilot these methods for pharmaceutical contract manufacturing partnerships.
- Biocompatible Techniques:Aqueous solvent systems and bio-based polymer feedstocks align with EU Green Deal mandates. Scandinavian pulp processors scale cellulose nanofiber production from agricultural waste streams.
- Others:Self-assembly and phase separation methods serve niche applications where conventional electrospinning proves incompatible with sensitive active ingredients.
Production scale concentrates in Biocompatible Techniques; Nanolithography gains share fastest as cell-culture substrate specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European nanofiber demand concentrates in German automotive clusters and Nordic biomedical research corridors, with regulatory pressure from REACH and the EU Green Deal redirecting investment toward bio-based feedstocks and closed-loop solvent recovery systems.
Germany
Baden-Württemberg automotive OEMs specify electrospun cabin air filters for interior air quality compliance, while Stuttgart-based engineering centers consolidate procurement under long-term framework agreements. REACH substance restrictions harden material qualification timelines for tier-one suppliers. Bavarian chemical recycling infrastructure enables circular economy claims that differentiate domestic producers against import competition.
France
Battery ventilation system manufacturers favor melt blown nanofiber constructions for powertrain thermal cycling tolerance. ECHA guidance on worker exposure limits accelerates solvent substitution toward aqueous processes in electrospinning operations. Paris-Saclay research clusters pilot cellulose nanofiber substrates from agricultural waste streams for pharmaceutical contract manufacturing.
Sweden
Scandinavian pulp processors scale pilot lines serving wound-care and drug-delivery applications with REACH-compliant sourcing. EMA accelerated CE marking pathways under MDR shorten time-to-market for implantable nanofiber scaffolds. Stockholm-Uppsala biomedical corridors drive fastest adoption of nanolithography-enabled cell-culture substrates.
Czech Republic
Elmarco s.r.o. anchors the regional equipment supply base with specialized needle-free electrospinning systems that reduce barrier-to-entry for mid-scale filtration producers. EU Green Deal chemical sustainability mandates redirect R&D investment toward bio-based polymer feedstocks. Brno manufacturing clusters supply machinery to German and French automotive filter assemblers.
Netherlands
Dutch biotech formulators partner with Scandinavian pulp processors to scale cellulose nanofiber production for pharmaceutical applications. ECHA substance restriction scope creep delays material qualification timelines and freezes R&D portfolio decisions. Eindhoven technical textile clusters explore functional fabric integration for protective apparel and sportswear moisture management.
Europe Nanofiber Market Competitive Landscape
German and French producers anchor one tier of filtration-focused supply; Czech and Nordic specialists hold equipment and biomedical positioning respectively. The vendor base stratifies across polymer science heritage players, electrospinning machinery fabricators, and membrane architecture specialists. Three archetypes dominate: integrated material-equipment providers, pure-play membrane suppliers, and research-stage technology licensors. Competitive moves concentrate on strategic partnerships for closed-loop solvent recovery and geographic expansion into underpenetrated southern European markets.
Within the integrated material tier, DuPont leverages polymer science heritage to sustain differentiated positioning, while TORAY INDUSTRIES, INC. competes through controlled membrane architectures. Among equipment specialists, Elmarco s.r.o. occupies the needle-free electrospinning niche that reduces capital barriers for regional producers. These three exemplify how European nanofiber competition splits between material science depth, manufacturing system control, and high-specification filtration performance thresholds.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| Hollingsworth & Vose |
| TORAY INDUSTRIES, INC. |
| Ahlstrom-Munksjo |
| Asahi Kasei Corporation |
| Donaldson Company, Inc. |
| DuPont |
| Elmarco s.r.o. |
| eSpin Technologies |
| Others |
Supply & Pricing Matrix
EU Green Deal chemical sustainability mandates gate qualified supply and premium-tier pricing access for nanofiber producers, compressing margin structures for synthetic polymer incumbents while rewarding bio-based feedstock investments with contract pricing premiums. REACH-compliant solvent recovery infrastructure and MDR-validated production lines function as pricing tier separators that tier-one automotive and healthcare buyers will not cross without documented certification.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with German automotive OEMs paying 15-25% above baseline for qualified electrospun membrane delivery inside compressed product development cycles. Pricing stratifies across MDR-certified biomedical grades, REACH-compliant filtration tiers, and commodity spot volumes, with cellulose nanofiber substrates commanding sustainable sourcing premiums. Cost compression in synthetic polymer feedstocks intensifies margin pressure as petrochemical volatility transfers unpredictability to contract structures. Healthcare buyers demonstrate lowest price sensitivity due to validation switching costs, while mid-scale filtration assemblers squeeze suppliers on volume scale.
Supply Chain Analysis
CE marking and REACH substance qualification gate supply chain participation, filtering viable producers to established European manufacturers with documented MDR technical files. Production concentrates in Germany, France, and the Czech Republic, with Scandinavian pulp processors scaling cellulose feedstock alternatives. Raw material dependencies center on acrylonitrile and fluoropolymer precursors, bio-based polymer formulations, and specialized electrospinning equipment from Central European machinery vendors. Single-source vulnerability in needle-free system supply creates structural risk for mid-scale producers. Distribution runs through tier-one automotive supplier clusters and pharmaceutical contract manufacturing partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European nanofiber supply remains capacity-constrained by electrospinning process engineering talent scarcity and extended MDR certification timelines, propping pricing power for qualified incumbents while extending backlog visibility into multi-year framework agreements.
For Market Incumbents: Extend backward integration into bio-based polymer feedstocks to secure REACH-compliant supply chains against ECHA substance restriction scope creep. Add captive solvent recovery capacity in Bavarian chemical recycling clusters to differentiate circular economy claims. Defend margin position by locking tier-one automotive buyers into long-term procurement frameworks before Czech equipment suppliers enable second-source competition.
For New Entrants and Emerging Players: Enter via Spanish and Italian technical textile corridors where nanofiber functional fabric integration remains underpenetrated relative to German automotive saturation. Target wound-care applications in Nordic biomedical research corridors where EMA accelerated pathways shorten time-to-market for REACH-compliant cellulose substrates. Lead with aqueous solvent electrospinning systems that bypass dimethylformamide recovery capital requirements.
For Investors and Strategic Acquirers: EMA accelerated CE marking approvals for implantable nanofiber scaffolds is the leading indicator that biomedical revenue pools are reaching commercial inflection. Frame long-term viability around 5-10 year regulatory compliance moats rather than commodity filtration scale. Target acquisition profiles combining nanolithography patterning capabilities with pharmaceutical contract manufacturing relationships. Watch for EU AI Act certification of automated quality-control systems as the signal that manufacturing efficiency gaps are widening between automated and manual production lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | REACH-compliant sourcing from Scandinavian pulp processors locks premium pricing tiers against petrochemical volatility. |
| Closed-Loop Solvent Recovery Deployment | German chemical recycling infrastructure partnerships enable circular economy claims that differentiate against import competition. |
| MDR Accelerated Pathway Navigation | EMA fast-track CE marking shortens time-to-market for implantable scaffolds in Nordic biomedical corridors. |
| Needle-Free Electrospinning Equipment Scale-Up | Czech machinery supply expansion reduces capital barriers for mid-scale producers entering southern European markets. |
| EU AI Act Quality Control Certification | Machine-vision inspection platform validation captures premium positioning in automated nanofiber manufacturing lines. |
Research Methodology
Document review covered ECHA substance restriction guidance, EMA MDR technical documentation requirements, EU Green Deal chemical sustainability mandates, and automotive OEM supplier quality handbooks, complemented by interviews with electrospinning equipment engineers, polymer science R&D directors, pharmaceutical contract manufacturing procurement leads, and tier-one automotive filter assemblers. Secondary validation drew from customs trade data, SEC filings of listed materials companies, and industry association capacity surveys. Bottom-up production capacity estimates triangulated against top-down demand segmentation across filtration, biomedical, and energy storage applications.
Historical capacity utilization and pricing patterns cross-referenced against expert panel input on regulatory timeline compression and feedstock transition economics shaped the analytical framework across the analysis window. Segmentation dimensions modeled include manufacturing method, application specification, end-use industry, and technology maturity tier. CAGRs derived from installed base growth rates, replacement demand cycles, and penetration assumptions for emerging applications. Industry-specific inputs incorporated REACH substance restriction expansion schedules and MDR Annex I validation timeline benchmarks.
Revisions become necessary when ECHA expands SVHC candidate list scope beyond current guidance, EU AI Act enforcement timelines accelerate quality-control system mandates, or bio-based polymer feedstock cost curves intersect synthetic incumbent pricing. Forecasts reflect assumptions on regulatory compliance cost pass-through and automotive OEM procurement consolidation trajectories. A model refresh is warranted upon material change in electrospinning equipment lead times or cellulose nanofiber production scale economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Textile Fibers Market
Synthetic Fibers
Global Lyocell Fibers Market
Synthetic Fibers
Polyimide Fiber Market
Synthetic Fibers
Long Fiber Thermoplastics Market
Synthetic Fibers
Global High Performance Fibers Market
Synthetic Fibers
Bio-Based Elastic Core-Spun Yarn for Denim Stretch Market
Synthetic Fibers
Polyester Staple Fiber Market
Synthetic Fibers
Staple Fibers Market
Synthetic Fibers
Extruded PLA Fiber Market
Synthetic Fibers
Asia-Pacific Spandex Market
Synthetic Fibers
Polyester Filament Market
Synthetic Fibers
Polyester Strap for Manual Grade Market
Synthetic Fibers
Synthetic Sewing Thread Market
Synthetic Fibers
Polymer Nanofiber Market
Synthetic Fibers
Latin America Textile Market
Synthetic Fibers
Global Acrylic Fibers Market