
 Staple Fibers Market | 2026-2036
Staple Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Staple Fibers Market Outlook
The gulf between premium specialty staple fibers and commodity-grade polyester is expanding as automakers and technical textile producers demand certified recycled content and enhanced performance metrics while apparel markets absorb undifferentiated volume. Indorama Ventures leverages its integrated PET resin-to-fiber chain to control feedstock costs across Southeast Asian production bases. Toray Industries differentiates through advanced polymer modification for high-tenacity industrial applications. Lenzing AG specializes in wood-based cellulosic fibers with closed-loop manufacturing credentials that command price premiums in European home furnishings channels.
Staple fibers are discrete, short-length textile fibers—typically 25–150 millimeters in cut length—that are spun into yarn through carding, combing, or open-end rotor processes, serving as the foundational raw material for woven fabrics, nonwovens, and filled products across industrial and consumer applications. Synthetic fibers dominate volume throughput, yet specialty fibers capture disproportionate margin pools in medical nonwovens and filtration media where technical specifications override price sensitivity. Blended fibers are gaining structural share as mills engineer cotton-polyester and wool-synthetic combinations to balance cost, durability, and sustainability credentials for mid-tier apparel brands.
The EU REACH regulation and ECHA chemical restrictions govern azo dyes and restricted substances in fiber processing, while the EU Green Deal's textile strategy mandates recycled content thresholds that reshape raw material procurement for European end users. India's BIS certification requirements and the country's PLI scheme for man-made fibers create dual pressure on exporters to meet quality benchmarks while scaling capacity for domestic textile integration. Stakeholders must monitor how regulatory divergence between European chemical compliance and Asian production incentive structures will fragment sourcing strategies and certification costs across the value chain.
Market Dynamics
Automotive interior specifications and EU chemical compliance mandates are bifurcating the staple fibers value chain, forcing suppliers to choose between certified recycled-content specialty grades for technical textiles and undifferentiated volume production for apparel.
Growth Catalysts
- EU Green Deal textile strategy:Mandated recycled content thresholds in European end-use markets pull certified fiber grades through the supply chain.
- Automotive lightweighting:Interior panel and seating applications demand higher-tenacity polyester and polypropylene staple fibers with defined flame-retardant properties.
- India PLI scheme for man-made fibers:Domestic capacity expansion incentives concentrate polyester and viscose staple fiber output for export-oriented textile clusters.
Market Restraints
- PET resin price volatility:Crude oil-linked feedstock costs compress margins for polyester staple fiber producers without backward integration into purified terephthalic acid.
- ECHA chemical restrictions:REACH-regulated azo dyes and restricted substances in fiber processing add compliance layers for European market access.
- Mechanical recycling yield limits:Contamination sensitivity in post-consumer polyester feedstock constrains certified recycled fiber output at scale.
Strategic Opportunities
- Medical nonwoven penetration:Surgical gown and filtration media applications absorb specialty fiber grades with defined biocompatibility and barrier properties.
- Wood-based cellulosic expansion:Closed-loop manufacturing credentials for viscose and lyocell variants command price premiums in European home furnishings channels.
- BIS certification arbitrage:Quality benchmark compliance for Indian export markets creates differentiation against non-certified regional competitors.
Industry Challenges
- Polymer modification expertise scarcity:High-tenacity industrial fiber production requires specialized melt-spinning and drawing capabilities concentrated among limited technical staff pools.
- Multi-jurisdiction certification timelines:Simultaneous EU REACH, BIS, and OEKO-TEX compliance documentation extends product launch cycles for blended fiber introductions.
- Legacy carding equipment retrofit costs:Open-end rotor spinning lines require capital-intensive upgrades to process recycled-content feedstocks with variable staple length distributions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Staple Fibers Market |
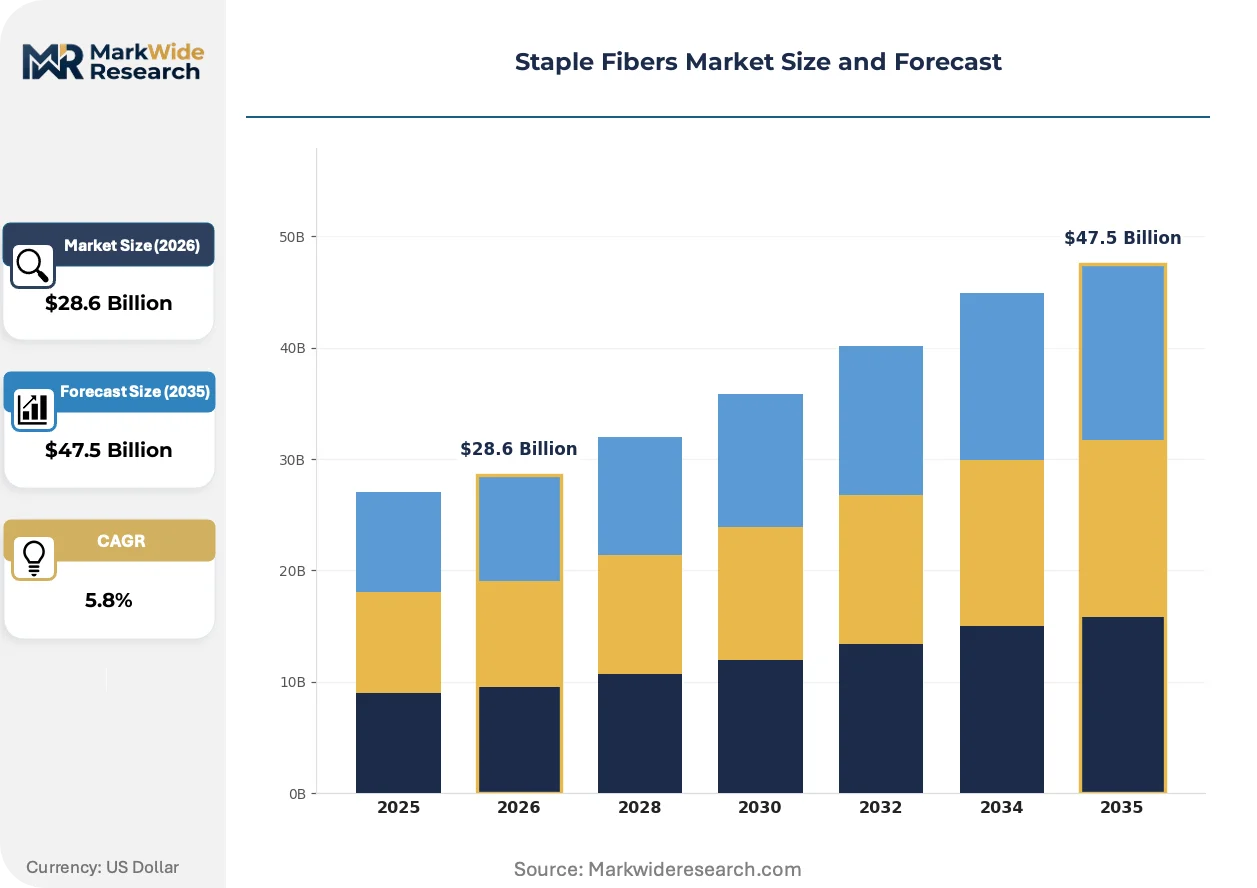
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Fibers, Synthetic Fibers, Blended Fibers, Specialty Fibers Grade: High Grade, Medium Grade, Low Grade, Industrial Grade Form: Carded, Combed, Spun, Open-End End Use Industry: Textiles, Automotive, Home Furnishings, Construction |
| Companies Covered | Indorama Ventures, Toray Industries, Sinopec Group, Reliance Industries, Aditya Birla Group, Lenzing AG, Alpek, Tongkun Group, Barnet GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Staple Fibers Market Strategic Shifts
Polymer science advances and chemical compliance automation are compressing development cycles for certified fiber grades while procurement patterns favor suppliers with integrated sustainability documentation.
Bi-component sheath-core staple fiber technology is expanding into thermal-bonded nonwoven applications where controlled melting points enable binder-free web consolidation. Hygiene product manufacturers adopt these fibers for diaper and wipe substrates to eliminate chemical adhesive residues. The technology is expanding into automotive insulation and filtration media where uniform bond strength and loft retention override pure cost minimization.
EU REACH regulation enforcement through ECHA is tightening restricted substance lists for fiber processing chemicals including certain flame retardants and antimicrobial treatments. Textile finishers serving European automotive and home furnishing markets reformulate chemical portfolios to maintain market access. Downstream brands accelerate supplier qualification audits to document compliance across multi-tier supply chains before mandatory disclosure deadlines.
Certificate-based fiber procurement is displacing spot-market purchasing for mid-tier apparel brands seeking OEKO-TEX and GRS chain-of-custody documentation. Sourcing teams now require mill-level transparency on recycled-content percentages and chemical inputs rather than accepting trader-level assurances. This shift concentrates contract volumes with integrated resin-to-fiber producers capable of batch-level traceability, particularly visible in European and North American brand supply chains.
Staple Fibers Market Segmentation
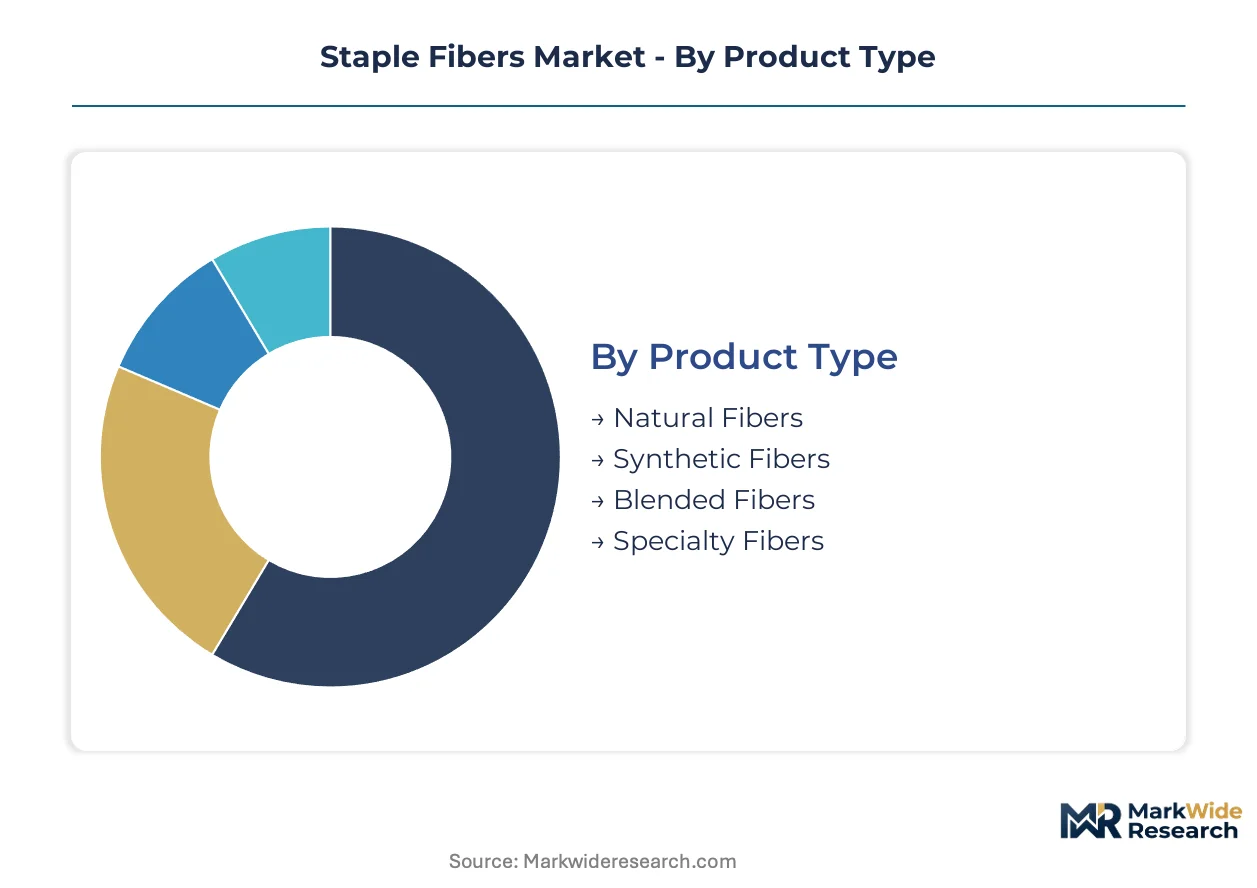
Staple fiber segmentation reveals divergent capital requirements and margin profiles across the value chain. Synthetic fiber production demands integrated petrochemical infrastructure while specialty grades require polymer modification expertise that concentrates among limited technical suppliers.
Product Type:
Capital intensity peaks with synthetic fiber production due to purified terephthalic acid integration and continuous polymerization assets, while natural fiber processing requires lower upfront equipment investment.
- Synthetic Fibers:Polyester and polypropylene grades dominate volume throughput through melt-spinning and staple cutting operations. Automotive interior specifications in Germany and Japan pull higher-tenacity variants with defined flame-retardant properties under ECHA and METI chemical compliance frameworks.
- Specialty Fibers:High-performance aramid, carbon, and modified cross-section polymers serve filtration media and industrial reinforcement applications. Medical nonwoven penetration in the US and EU absorbs grades with certified biocompatibility documentation under FDA and MDR requirements.
- Natural Fibers:Cotton, wool, and bast fibers processed through conventional ginning and scouring equipment serve apparel and home textile channels.
- Blended Fibers:Cotton-polyester and wool-synthetic combinations engineered for cost-durability balance in mid-tier apparel brands.
Synthetic fibers absorb the bulk of installed capacity; specialty fibers are expanding most quickly.
Grade:
Margin stratification across grade tiers reflects certification burden and performance specification density rather than pure production scale.
- High Grade:Certified recycled-content and OEKO-TEX documented fibers command procurement preference from European and North American brands. EU Green Deal textile strategy mandates pull these grades through automotive and home furnishing supply chains.
- Industrial Grade:High-tenacity polyester and polypropylene variants with defined tensile strength and thermal stability specifications serve geotextile and composite reinforcement applications. Construction sector demand in India and China absorbs volume for infrastructure membrane and soil stabilization uses.
- Medium Grade:Standard performance specifications for general apparel and textile applications without premium certification requirements.
- Low Grade:Undifferentiated commodity grades for filler, padding, and cost-sensitive disposable applications.
Industrial grade captures the steepest expansion trajectory as infrastructure investment concentrates in Asian markets; high grade maintains the widest margin premium.
Form:
Processing technology selection determines fiber alignment quality and downstream yarn uniformity for specific end-use performance requirements.
- Combed:Parallel fiber alignment through additional refining stages produces superior yarn strength and surface finish for premium apparel. European and Japanese textile mills specify combed cotton and synthetic blends for fine-count woven fabrics.
- Carded:Mechanical opening and cleaning without combing refinement offers lower-cost processing for bulk applications. Home furnishing and industrial nonwoven producers in India and Turkey absorb volume for mid-tier bedding and upholstery substrates.
- Spun:Ring-spun yarn construction from drafted fiber slivers delivers balanced strength and hand-feel characteristics.
- Open-End:Rotor spinning technology processes shorter staple lengths at higher speeds for cost-optimized yarn production.
Carded form retains the largest production base; combed form is climbing the fastest as quality specifications tighten in export-oriented textile clusters.
End Use Industry:
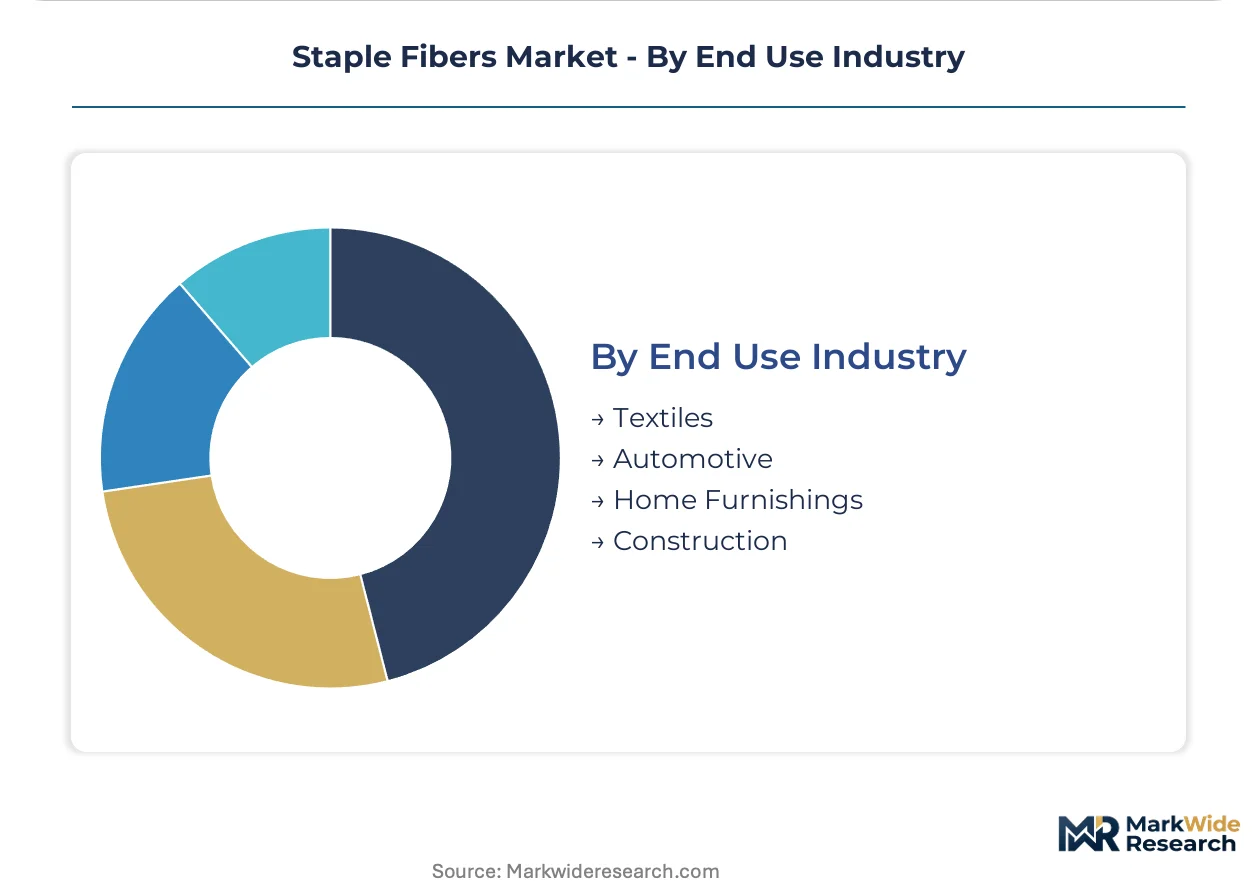
Application-driven demand fragmentation requires fiber suppliers to maintain distinct technical service capabilities across divergent specification regimes.
- Automotive:Interior panel, seating, and insulation applications demand flame-retardant polyester and polypropylene grades with defined fogging and emissions characteristics. ECHA REACH restrictions on processing chemicals reshape supplier qualification protocols for European vehicle programs.
- Textiles:Apparel and fabric production absorbs the widest grade range from commodity polyester to certified organic cotton and recycled-content synthetic blends. India's PLI scheme for man-made fibers concentrates export-oriented polyester and viscose staple capacity for global garment supply chains.
- Home Furnishings:Upholstery, bedding, and decorative textile channels in Europe and North America prioritize wood-based cellulosic fibers with closed-loop manufacturing credentials.
- Construction:Geotextile, concrete reinforcement, and insulation applications absorb high-tenacity industrial grades with defined creep resistance and UV stability specifications.
Textiles command the dominant share of fiber offtake; automotive is gaining share fastest as lightweighting specifications proliferate across vehicle platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surat anchors global staple fiber processing as India's synthetic textile corridor concentrates polyester and viscose staple capacity for export-oriented garment manufacturing. The city's integrated dyeing, weaving, and finishing clusters absorb feedstock from domestic polymer producers and international resin suppliers alike.
China
Shaoxing's chemical fiber belt drives polyester staple output for technical textile applications including automotive interiors and geotextiles. MIIT industrial standards govern polymer purity specifications for high-tenacity grades serving infrastructure reinforcement. Tongkun Group and Sinopec affiliates operate continuous polymerization assets across Zhejiang province to supply both domestic mills and Southeast Asian fabricators.
India
Reliance Industries scales purified terephthalic acid-to-fiber integration at Jamnagar and Hazira to capture PLI scheme incentives for man-made fiber expansion. BIS certification requirements for export markets pressure smaller regional spinners to upgrade quality systems. Tiruppur's knitwear cluster absorbs viscose staple for European fast-fashion supply chains requiring OEKO-TEX documentation.
Germany
ECHA REACH enforcement tightens restricted substance lists for azo dyes and flame retardants in automotive interior applications. Baden-Württemberg's technical textile producers reformulate chemical portfolios to maintain supply contracts with BMW and Mercedes-Benz vehicle programs. Stuttgart-region suppliers invest in batch-level traceability systems to document recycled-content percentages for EU Green Deal compliance.
United States
North Carolina's nonwoven belt absorbs specialty fiber grades for medical gown and filtration media production under FDA biocompatibility requirements. EPA industrial discharge regulations constrain chemical finishing operations at legacy mill sites. Charlotte-area logistics hubs distribute imported polyester staple from Asian producers to regional carding and air-laid operations serving hygiene product manufacturers.
Japan
METI chemical compliance frameworks govern fogging and emissions specifications for automotive interior fibers supplied to Toyota and Honda production networks. Nagoya-region technical textile producers engineer high-tenacity polyester variants for tire cord and industrial reinforcement applications. Toray Industries maintains polymer modification expertise for cross-section engineered fibers serving premium filtration markets.
Staple Fibers Market Competitive Environment
Capital-heavy producers compete with asset-light designers as integrated petrochemical groups battle specialized fiber engineering firms for margin pools. The market structure concentrates among Asian resin-to-fiber conglomerates with backward integration into purified terephthalic acid, while European and Japanese players occupy specialty niches requiring polymer science expertise. Three archetypes dominate: integrated chemical-fiber conglomerates controlling feedstock costs, specialty cellulose producers with closed-loop manufacturing credentials, and regional scale players serving domestic textile clusters. Competitive moves center on capacity expansion in India under PLI incentives and certification investments for EU Green Deal compliance.
Within the integrated conglomerate tier, Indorama Ventures and Reliance Industries exemplify capital-intensive positioning through captive resin supply chains spanning Southeast Asian and Indian production bases. Lenzing AG occupies the specialty cellulose archetype with wood-based fiber credentials commanding European home furnishings premiums. Toray Industries anchors the advanced polymer modification segment for high-tenacity industrial applications requiring defined tensile specifications.
| Leading Market Players |
|---|
| Indorama Ventures |
| Toray Industries |
| Sinopec Group |
| Reliance Industries |
| Aditya Birla Group |
| Lenzing AG |
| Alpek |
| Tongkun Group |
| Barnet GmbH & Co. KG |
| Others |
Value Chain & Pricing Dynamics
Backward integration into purified terephthalic acid production anchors supply position and pricing power for polyester staple fiber leaders, while non-integrated mills absorb feedstock volatility that compresses margins during crude oil price spikes. This structural divide between captive resin producers and merchant market buyers stratifies pricing tiers across automotive, apparel, and industrial applications.
Pricing Analysis
Certification-based pricing anchors value capture for specialty staple fiber grades, with OEKO-TEX and GRS chain-of-custody documentation commanding procurement preference from European and North American brands. Three-tier pricing structure across premium, standard, and economy levels separates certified recycled-content fibers from industrial-grade high-tenacity variants and undifferentiated commodity polyester. Pricing pressure stems from PET resin cost volatility linked to crude oil movements, squeezing non-integrated producers. Apparel brands exhibit highest price sensitivity, while automotive and medical nonwoven buyers prioritize performance specifications over unit cost.
Supply Chain Analysis
Post-consumer polyester collection and mechanical recycling flows feed certified recycled-content fiber production, though contamination sensitivity constrains yield at scale. Raw material sourcing concentrates in China, India, and Saudi Arabia for purified terephthalic acid and petrochemical feedstocks. Melt-spinning and staple cutting operations draw from continuous polymerization assets clustered in Zhejiang province and Gujarat state. Single-source vulnerability runs through concentrated PTA supply from integrated petrochemical complexes. Distribution runs through regional textile clusters—Surat, Tiruppur, Shaoxing—where dyeing and weaving operations absorb fiber offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The staple fibers market functions as a vertical-integration race where control over purified terephthalic acid feedstock separates margin leaders from price-takers. Players are pursuing backward integration into resin production as the decisive upstream lever for cost position and supply security.
For Market Incumbents: Deepen captive PTA integration at existing Southeast Asian and Indian production bases to defend against feedstock cost volatility eroding polyester staple margins. Expand certified recycled-content capacity ahead of EU Green Deal textile strategy enforcement timelines. Prioritize BIS certification investments for Indian export market access.
For New Entrants and Emerging Players: Technical textile distributors and regional nonwoven converters offer partnership pathways to bypass capital-intensive polymerization assets. Target medical nonwoven and filtration media segments where biocompatibility specifications limit commodity competition. Pursue specialty cellulose fiber production with closed-loop manufacturing credentials for European home furnishings channels.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty fiber engineering firms with polymer modification expertise and established automotive qualification protocols. Long-term viability favors producers with demonstrated ECHA REACH compliance and batch-level traceability systems. Monitor EU recycled-content mandate enforcement as inflection indicator for certified fiber grade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PTA | Captive purified terephthalic acid supply insulates Reliance and Indorama from crude-linked feedstock volatility. |
| Certified Recycled Capacity Expansion | GRS and OEKO-TEX documented output captures EU Green Deal procurement preference from automotive tier suppliers. |
| Medical Nonwoven Qualification | FDA and MDR biocompatibility certification opens surgical gown and filtration media segments with premium pricing. |
| Closed-Loop Cellulosic Manufacturing | Lenzing's wood-based fiber credentials command price premiums in European home furnishings channels. |
| Regional Textile Cluster Partnerships | Direct mill relationships in Surat and Tiruppur secure offtake volumes for export-oriented garment supply chains. |
Study Parameters
Document review covered customs and trade data, SEC and BSE filings from listed fiber producers, ECHA regulatory guidance documents, and MIIT industrial standards, complemented by interviews with plant managers at continuous polymerization facilities, procurement leads at automotive Tier 1 suppliers, technical directors at nonwoven converters, and regulatory affairs specialists navigating REACH compliance. Secondary validation drew from textile industry association reports and fiber production databases. Bottom-up capacity modeling and top-down demand segmentation were triangulated against trade flow analysis.
Segmented outputs across product type, grade tier, processing form, and end-use industry were generated through the analytical framework, with projections developed across the analysis window. CAGRs were derived from elasticity-adjusted demand modeling incorporating automotive lightweighting penetration rates and EU recycled-content threshold implementation schedules. Forecast inputs included polymer modification capacity expansion timelines and BIS certification adoption curves among Indian exporters.
Several conditions sit outside the modeled scope, including abrupt crude oil price dislocations, unilateral tariff impositions on polyester staple imports, and breakthroughs in chemical recycling yield rates that could displace mechanical recycling infrastructure. Practitioners should monitor ECHA restricted substance list updates and PLI scheme disbursement pacing for early signals of supply chain reconfiguration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
High-Strength Polyester Thread Market
Synthetic Fibers
Nylon Tire Cord Fabrics Market
Synthetic Fibers
Asia-Pacific Aramid Fiber Market
Synthetic Fibers
Synthetic Fiber Market
Synthetic Fibers
Polypropylene Fiber Market
Synthetic Fibers
Global Synthetic Spider Silk Market
Synthetic Fibers
Polyester Strap for Manual Grade Market
Synthetic Fibers
Aramid Fiber Market
Synthetic Fibers
Polyethylene Terephthalate (PET) Fiber Market
Synthetic Fibers
Global Acrylic Fibers Market
Synthetic Fibers
Americas Spandex Market
Synthetic Fibers
Performance Fabric Market
Synthetic Fibers
Synthetic Fabric Market
Synthetic Fibers
Microfiber Leather Market
Synthetic Fibers
Nylon Fibers Market
Synthetic Fibers
Synthetic Sewing Thread Market