
 Global Lyocell Fibers Market | 2026-2036
Global Lyocell Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lyocell Fibers Market Foresight
Multi-source lyocell procurement is shifting from European-centric supply chains toward integrated Asian producers. Lenzing AG leverages its Austrian-T Indonesian manufacturing footprint to sustain premium fiber output across apparel and home textile channels. Aditya Birla Group anchors South Asian supply through its pulp-to-fiber integration, while Sateri competes on scale from its Chinese dissolving wood pulp base.
Lyocell fibers are regenerated cellulosic filaments produced via direct dissolution of wood pulp in N-methylmorpholine-N-oxide (NMMO), yielding tenacity values of 36–42 cN/tex and biodegradability exceeding 95% in soil environments. Staple fiber dominates current volume as denim and knitwear mills substitute cotton-polyester blends, while filament fiber occupies the fastest-expanding margin pool in luxury woven apparel. Solvent spinning technology leads manufacturing deployment, though continuous dry jet wet spinning differentiates emerging producers seeking energy recovery efficiencies.
The EU Green Deal and REACH chemical registration frameworks restrict conventional viscose emissions, redirecting European textile demand toward NMMO-based closed-loop processes. China's GB standards and dual carbon goals enforce wastewater recovery thresholds that favor lyocell over older regenerated cellulosic methods. Stakeholders must monitor pulp certification divergence between FSC-tracked European supply and plantation-sourced Southeast Asian feedstock as sustainability claims harden into procurement requirements.
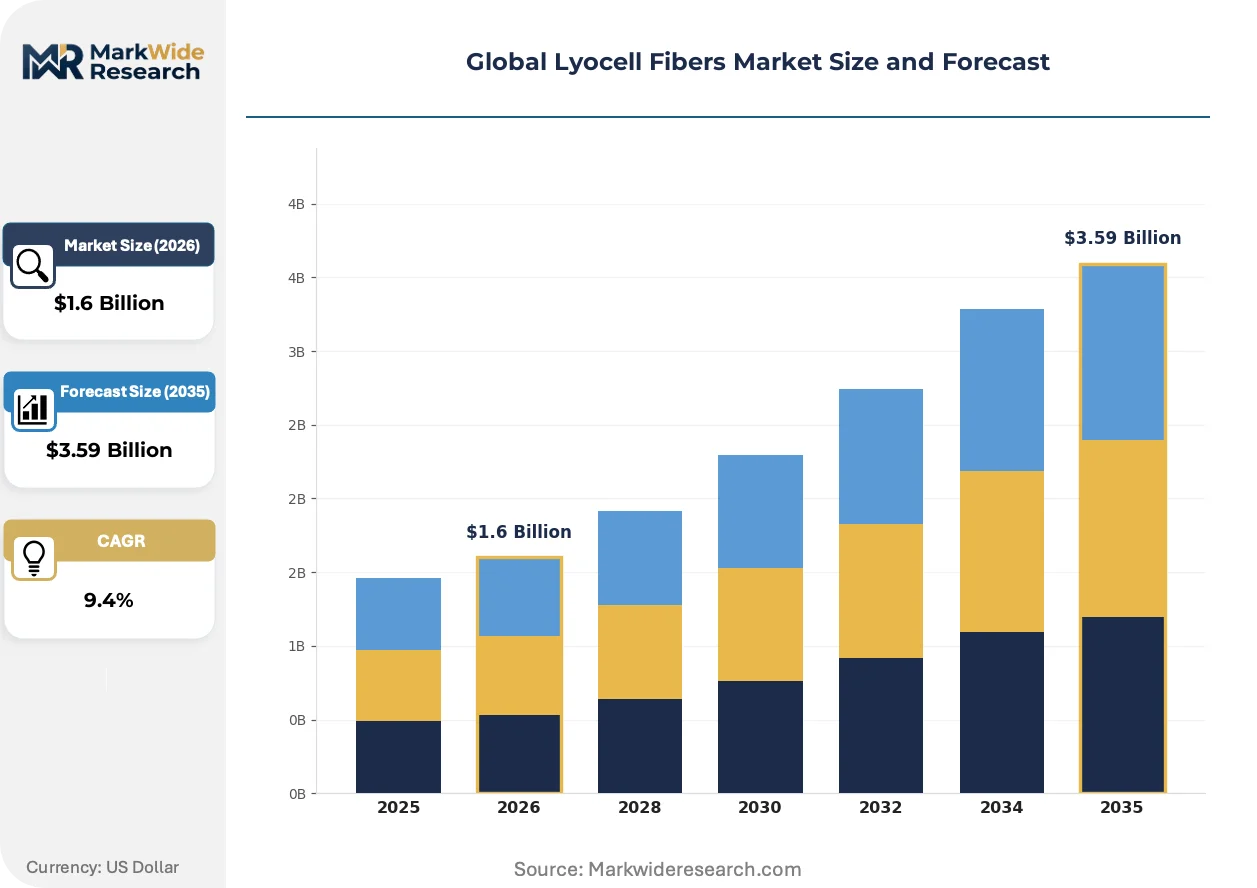
Market Dynamics
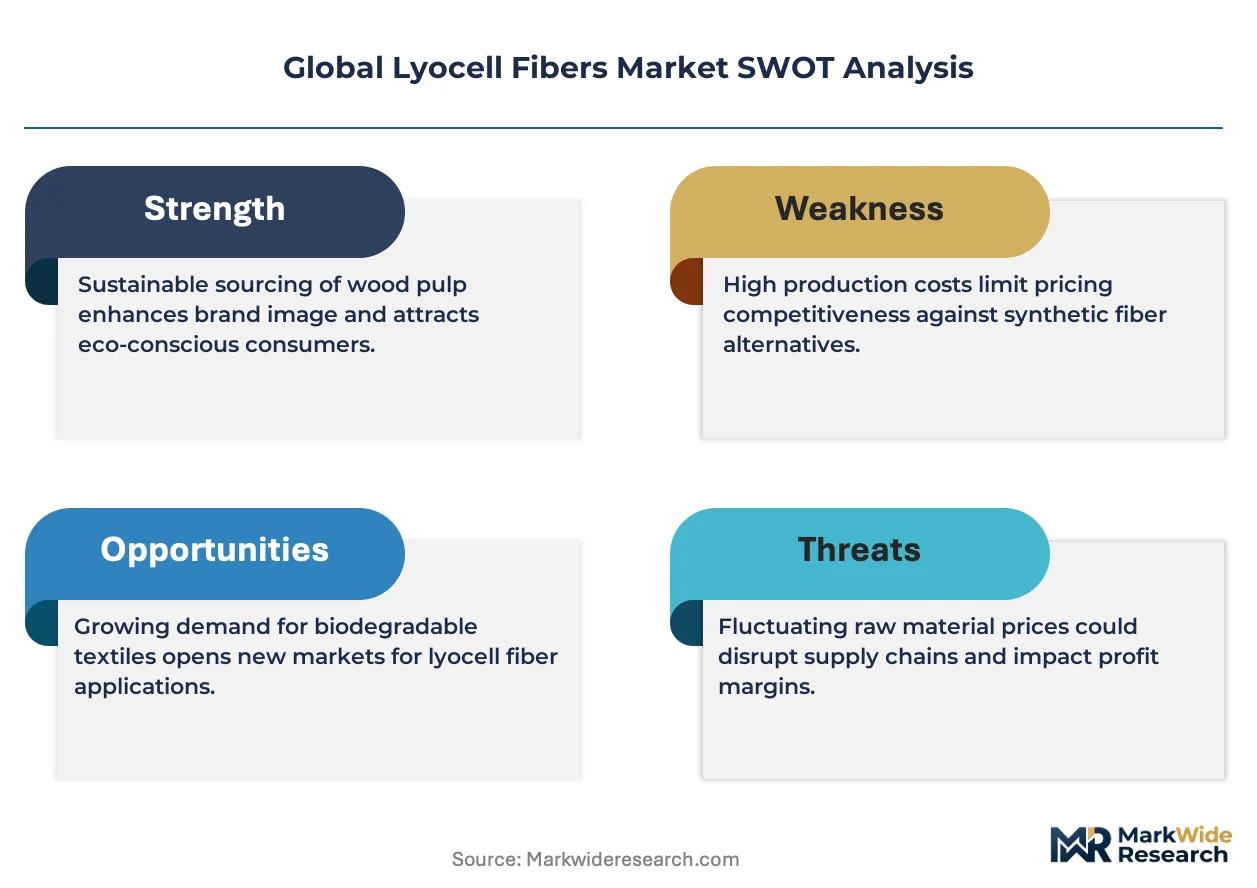
EU Green Deal textile sustainability mandates and China's dual carbon enforcement are compressing demand toward NMMO-based closed-loop fiber production, while Asian integrated producers capture volume from fragmented European supply chains.
Growth Catalysts
- EU Green Deal textile requirements:REACH chemical registration frameworks restrict conventional viscose emissions, redirecting European mill procurement toward solvent-spun cellulosic alternatives with verified biodegradability.
- Denim and activewear substitution:Apparel brands reformulate cotton-polyester blends with lyocell staple to meet tenacity specifications of 36–42 cN/tex while satisfying soil biodegradability thresholds exceeding 95 percent.
- China's GB wastewater standards:Dual carbon goals enforce recovery thresholds that favor lyocell manufacturing over older regenerated cellulosic methods, accelerating domestic pulp-to-fiber capacity expansion.
Market Restraints
- Dissolving wood pulp concentration:Southeast Asian plantation-sourced feedstock creates certification divergence risk against FSC-tracked European supply, complicating sustainability claims for premium fiber tiers.
- NMMO solvent cost volatility:N-methylmorpholine-N-oxide pricing fluctuates with petrochemical feedstock markets, squeezing margin structures for producers without captive chemical synthesis.
- Viscose price competition:Conventional regenerated cellulosic fibers maintain cost advantages in price-sensitive home textile segments, limiting lyocell penetration in mass-market bedding and furnishing channels.
Strategic Opportunities
- India's technical textile expansion:Industrial nonwoven applications for filtration and medical textiles remain underpenetrated by lyocell, offering white space for staple fiber producers targeting BIS-certified performance specifications.
- Luxury woven apparel filament demand:Filament fiber commands premium positioning in high-end fashion, with Italian and French couture houses accelerating sourcing for fluid drape characteristics unavailable in cotton or synthetic alternatives.
- Closed-loop chemical recovery mandates:China's MEE enforcement of solvent recycling thresholds creates competitive moats for producers with integrated NMMO recovery systems versus legacy viscose operators facing retrofit costs.
Industry Challenges
- Dry jet wet spinning engineering scarcity:Continuous solvent spinning expertise concentrates among Austrian and Chinese engineering firms, creating talent bottlenecks for emerging producers in Southeast Asia seeking energy recovery efficiencies.
- FSC-PEFC certification timeline compression:European retail procurement policies now require chain-of-custody documentation within 18-month windows, straining plantation-sourced suppliers with fragmented smallholder feedstock bases.
- Legacy viscose asset stranding:Mills with sunk capital in carbon disulfide-based production face complex reconfiguration costs when retrofitting for NMMO solvent systems, delaying capacity transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lyocell Fibers Market |
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $3.59 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Staple Fiber, Filament Fiber, Microfiber, Blend Fiber Application: Apparel, Home Textiles, Nonwoven, Industrial Fabrics, Personal Care Manufacturing Technology: Solvent Spinning, Dry Jet Wet Spinning, Continuous Dry Jet Wet Spinning, Batch Spinning End User: Textile Mills, Garment Manufacturers, Automotive Upholstery Makers, Medical Supply Producers |
| Companies Covered | Lenzing AG, Aditya Birla Group, Sateri, Baoding Swan Fiber Co., Ltd., Smartfiber AG, Weiqiao Textile Company Limited, Acegreen Eco-Material Technology Co., Ltd., Chonbang Co., Ltd., Qingdao Textiles Group Fiber Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lyocell Fibers Market Shifts & Advancements
Technology convergence between solvent recovery engineering and pulp pretreatment chemistry is compressing production costs while regulatory frameworks harden biodegradability verification requirements across major textile importing regions.
Continuous dry jet wet spinning systems are expanding into commercial deployment among second-tier Asian producers seeking to differentiate from Lenzing AG's established Austrian-Indonesian footprint. Turkish and Pakistani denim mills are adopting these systems at pilot scale to reduce specific energy consumption per kilogram of fiber output. The technology is expanding into margin capture from conventional batch-process viscose operators unable to justify comparable capital intensity.
REACH authorization requirements for NMMO handling and the EU Green Deal's textile sustainability disclosure mandates are tightening traceability obligations across European import channels. Industrial downstream users must now document closed-loop solvent recovery rates exceeding 99 percent to maintain preferential tariff treatment. Italian luxury knitwear manufacturers face the steepest compliance ramps, with several mid-tier mills consolidating procurement toward vertically integrated suppliers with certified recovery infrastructure.
Brand-led fiber preference certification is displacing traditional commodity purchasing in North American and Western European apparel supply chains. Denim brands now specify lyocell content minimums in supplier contracts, replacing volume-based cotton-polyester tenders. This pattern concentrates in California-based sustainable fashion labels and German outdoor apparel manufacturers, where consumer-facing transparency requirements have compressed switching cycles to 12-month contract windows.
Global Lyocell Fibers Market Segmentation
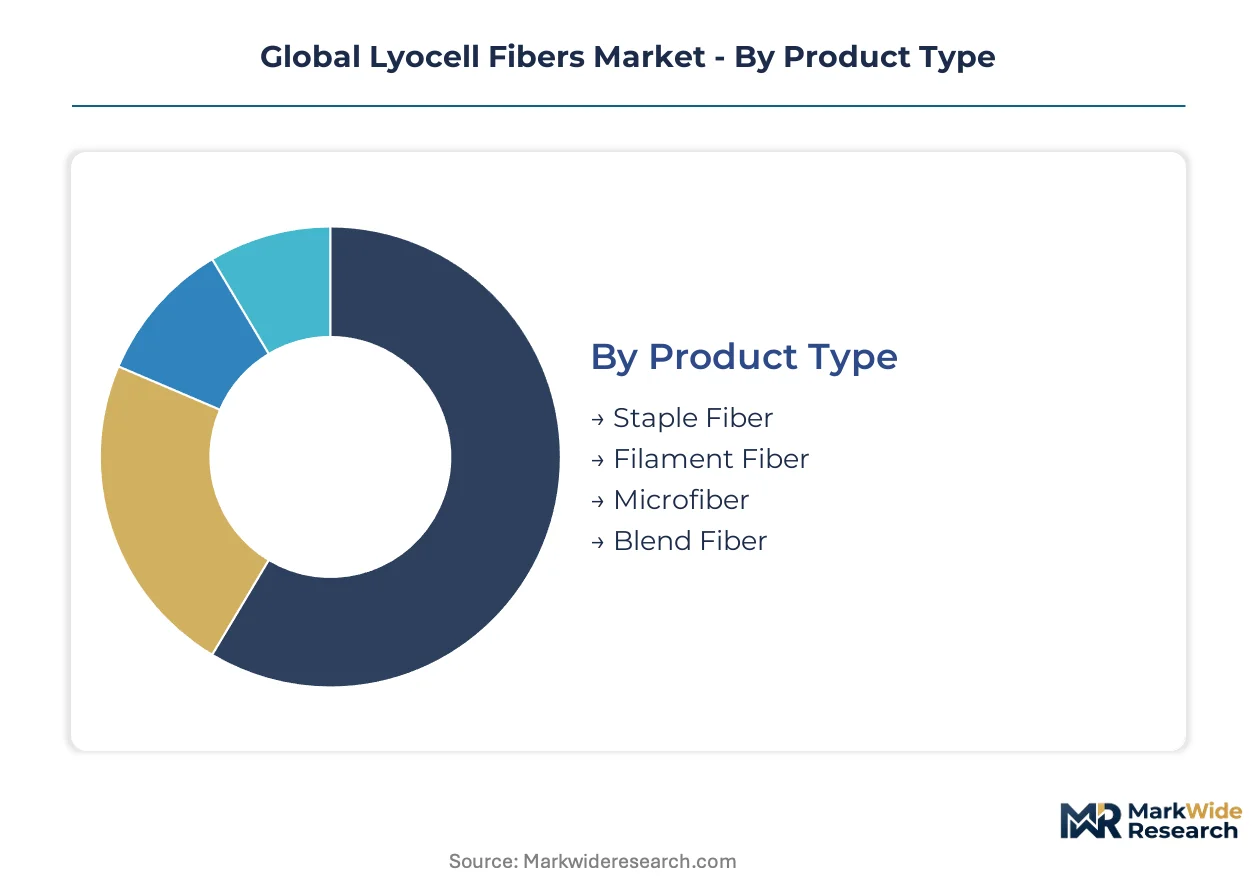
Lyocell fiber purchasing decisions track replacement cycles across denim reformulation, technical textile upgrades, and closed-loop manufacturing retrofits. Segmentation reveals where solvent-spun cellulosic fibers displace incumbent materials through performance specifications and regulatory compliance rather than commodity pricing.
Product Type:
Replacement cycles vary by fiber form, with staple formats penetrating mature apparel channels while filament and microfiber grades capture upgrade demand from synthetic alternatives.
- Staple Fiber:Short-cut filaments spun from NMMO-dissolved pulp deliver tenacity values of 36–42 cN/tex for denim and knitwear applications. Mills in Turkey and Pakistan substitute cotton-polyester blends with lyocell staple to meet EU Green Deal biodegradability thresholds exceeding 95 percent in soil environments.
- Filament Fiber:Continuous extruded filaments provide fluid drape characteristics for luxury woven apparel. Italian and French couture houses source filament lyocell for silk replacement in fluid eveningwear, with demand concentrating in Milan and Paris garment districts.
- Microfiber:Sub-denier filaments engineered for filtration and medical nonwovens. BIS-certified technical textile producers in India pilot microfiber adoption for surgical gown applications.
- Blend Fiber:Pre-compounded lyocell-cotton or lyocell-wool mixtures for downstream spinning efficiency. German outdoor apparel brands specify blend ratios in supplier contracts to reduce finishing-stage fiber preparation.
Staple fiber sits at the top of the volume ranking, with filament fiber climbing the fastest.
Application:
Cost tier differentiation separates premium positioning in fashion apparel from economy penetration in home textiles, with technical applications commanding mid-tier pricing through certification requirements.
- Apparel:Denim and activewear lines drive bulk consumption as California-based sustainable fashion labels mandate lyocell minimums. Reformulated cotton-polyester blends target tenacity specifications while satisfying soil biodegradability claims.
- Home Textiles:Bedding and furnishing channels face viscose price competition, limiting lyocell penetration in mass-market segments. European retail procurement policies now require chain-of-custody documentation within compressed windows.
- Nonwoven:Industrial filtration and medical textiles remain underpenetrated, offering white space for staple fiber producers. India's technical textile expansion targets BIS-certified performance specifications for surgical and hygiene applications.
- Industrial Fabrics:Technical textiles for automotive and aerospace composites utilize lyocell precursor carbon fibers. Japanese engineering firms evaluate lyocell-based carbon fiber for lightweight structural applications.
- Personal Care:Wet wipe substrates and cosmetic applicators leverage biodegradability certification. EU REACH authorization requirements for NMMO handling tighten traceability obligations across European import channels.
Apparel captures the dominant revenue share, with nonwoven applications expanding most quickly.
Manufacturing Technology:
Technology maturity curves separate established solvent spinning from emerging continuous systems, with capital intensity determining competitive moats.
- Solvent Spinning:Conventional NMMO-based direct dissolution dominates commercial deployment. Austrian and Indonesian integrated producers maintain output scale through captive chemical synthesis and recovery infrastructure.
- Dry Jet Wet Spinning:Air-gap coagulation reduces specific energy consumption per kilogram of fiber output. Turkish denim mills adopt pilot-scale systems to differentiate from batch-process viscose operators.
- Continuous Dry Jet Wet Spinning:Uninterrupted production lines enable energy recovery efficiencies and margin capture from conventional operators. Chinese second-tier producers commercialize these systems to compete with established Austrian-Indonesian footprints.
- Batch Spinning:Intermittent processing retains presence in specialty and small-lot production. Legacy viscose asset stranding complicates retrofit decisions for mills with sunk capital in carbon disulfide-based systems.
Solvent spinning retains the volume lead, with continuous dry jet wet spinning gaining share fastest.
End User:
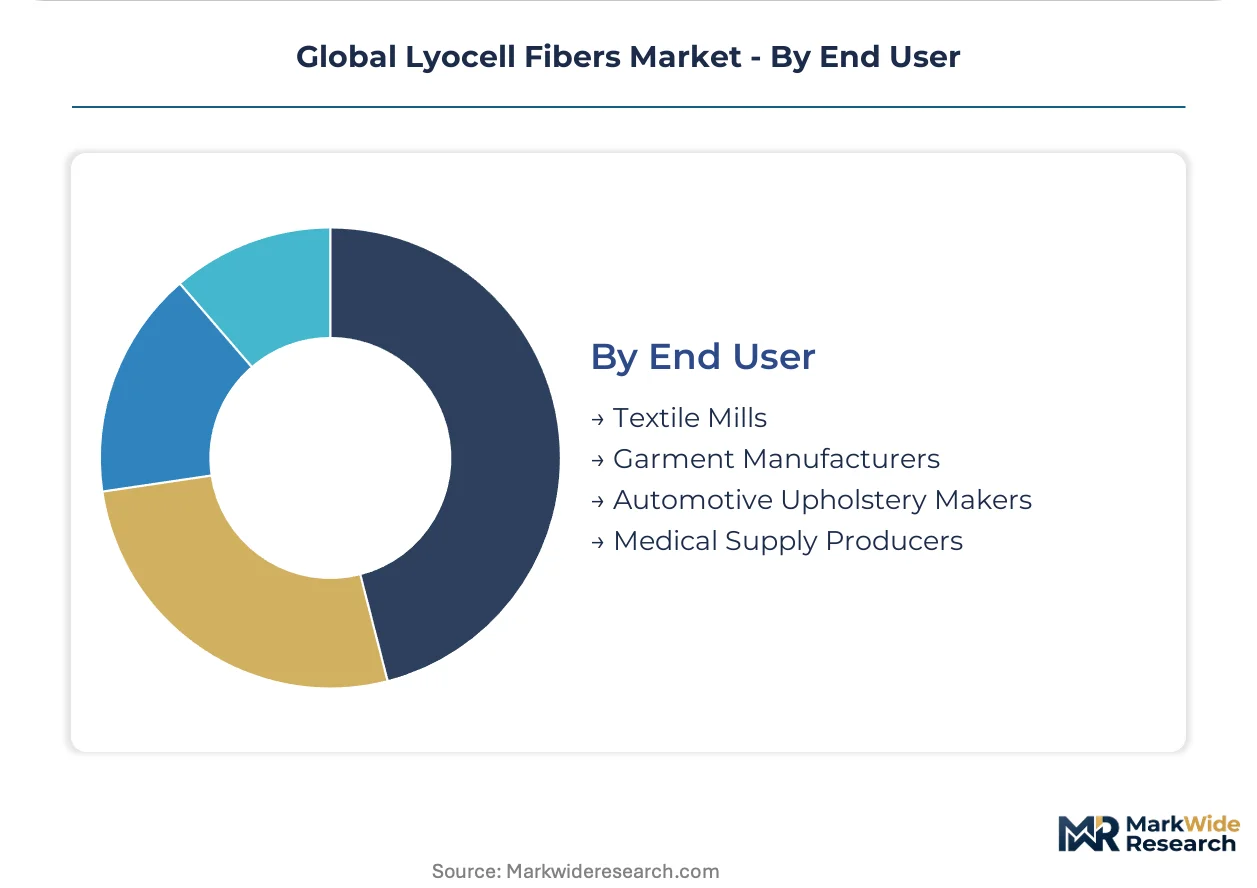
Customer concentration patterns align with geographic clustering of textile manufacturing and regulatory enforcement intensity.
- Textile Mills:Integrated pulp-to-fiber operations in China scale solvent-spun cellulosic capacity under GB wastewater standards and dual carbon enforcement. Domestic mills substitute imported viscose with captive lyocell production.
- Garment Manufacturers:Cut-and-sew operations in Bangladesh and Vietnam source certified lyocell for EU export compliance. Brand-led fiber preference certification displaces traditional commodity purchasing in North American and Western European supply chains.
- Automotive Upholstery Makers:Seat fabric and interior trim suppliers evaluate lyocell for biodegradability claims in European vehicle markets. German OEMs specify recycled and bio-based content minimums in tier-one supplier contracts.
- Medical Supply Producers:Surgical textile and wound dressing manufacturers require sterile-grade fiber with documented solvent recovery rates. Italian luxury knitwear manufacturers face steep compliance ramps, consolidating procurement toward vertically integrated suppliers.
Textile mills command the highest procurement volumes, with medical supply producers showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta hosts the densest concentration of lyocell fiber capacity, with integrated pulp-to-fiber operations scaling under national dual carbon enforcement. European demand redirects toward NMMO-based closed-loop alternatives as REACH frameworks restrict conventional viscose emissions. Turkish and Pakistani denim clusters pilot energy-efficient spinning systems to capture margin from batch-process competitors.
China
Domestic textile mills in Jiangsu and Zhejiang provinces expand solvent-spun cellulosic capacity to substitute imported viscose. The Ministry of Ecology and Environment enforces wastewater recovery thresholds that favor lyocell over older regenerated cellulosic methods. Sateri anchors production in Fujian province with plantation-sourced dissolving wood pulp integration.
Germany
Automotive upholstery suppliers in Baden-Württemberg evaluate lyocell for biodegradability claims in European vehicle markets. The EU Green Deal's textile sustainability disclosure mandates tighten traceability obligations across import channels. Munich-based technical textile developers pilot lyocell precursor carbon fibers for lightweight structural applications.
United States
California-based sustainable fashion labels mandate lyocell content minimums in supplier contracts, replacing volume-based cotton-polyester tenders. EPA industrial chemical regulations intersect with state-level extended producer responsibility frameworks. Los Angeles garment district procurement concentrates toward vertically integrated suppliers with certified solvent recovery infrastructure.
India
Technical textile producers in Maharashtra and Gujarat target BIS-certified performance specifications for surgical and hygiene applications. The country's national textile regulator enforces quality benchmarks that favor closed-loop fiber alternatives in medical nonwovens. Tiruppur knitwear clusters source certified lyocell staple for EU export compliance.
Turkey
Denim mills in Izmir and Istanbul adopt pilot-scale dry jet wet spinning systems to reduce specific energy consumption per kilogram of fiber output. The country's environmental ministry aligns industrial wastewater standards with EU candidate country obligations. Bursa textile engineering firms develop localized solvent recovery equipment for captive lyocell production.
Global Lyocell Fibers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue continuous spinning technology and regional pulp integration. The market structure consolidates around Austrian-Indonesian manufacturing footprints and Chinese dissolving wood pulp bases. Three archetypes dominate: integrated pulp-to-fiber operators, technology licensors with captive chemical synthesis, and regional scale players with plantation feedstock control. Competitive moves center on solvent recovery infrastructure deployment and FSC-PEFC certification acceleration.
Among Austrian-anchored producers, Lenzing AG occupies the premium-tier position exemplifying integrated NMMO recovery systems. Aditya Birla Group represents the South Asian pulp-to-fiber archetype with backward integration into plantation-sourced feedstock. Sateri anchors the Chinese scale-driven segment with dissolving wood pulp base integration. These three entities collectively illustrate how geographic feedstock access and solvent spinning technology concentration shape competitive positioning across apparel and technical textile channels.
| Leading Market Players |
|---|
| Lenzing AG |
| Aditya Birla Group |
| Sateri |
| Baoding Swan Fiber Co., Ltd. |
| Smartfiber AG |
| Weiqiao Textile Company Limited |
| Acegreen Eco-Material Technology Co., Ltd. |
| Chonbang Co., Ltd. |
| Qingdao Textiles Group Fiber Technology Co., Ltd. |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers in China's Yangtze River Delta and family-owned mid-caps in Austria anchor supply discipline through captive NMMO synthesis and FSC-certified pulp integration, translating feedstock control into pricing power across premium fiber tiers.
Pricing Analysis
NMMO solvent cost pass-through from petrochemical feedstock markets compresses margins for producers without captive chemical synthesis. Three-tier pricing structure across premium, standard, and economy levels separates Lenzing AG's certified recovery infrastructure from second-tier Chinese operators and conventional viscose substitutes. Pricing pressure stems from Southeast Asian plantation-sourced pulp competing against FSC-tracked European supply. Mass-market home textile buyers exhibit highest price sensitivity, while Italian luxury couture houses absorb premiums for filament fiber drape characteristics.
Supply Chain Analysis
FSC-PEFC certification gating now requires chain-of-custody documentation within compressed windows, straining plantation-sourced suppliers with fragmented smallholder feedstock bases. Supply concentrates in China, Austria, and Indonesia, with dissolving wood pulp dependencies resting on Southeast Asian plantation operations and European FSC-tracked forests. Single-source vulnerability runs through NMMO solvent supply concentrated among Austrian and Chinese chemical producers. Distribution runs through vertically integrated textile mills in Jiangsu and Zhejiang provinces, with garment manufacturers in Bangladesh and Vietnam sourcing for EU export compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in lyocell fibers hinges on solvent recovery infrastructure deployment and premium-tier filament fiber penetration into luxury apparel, with continuous dry jet wet spinning technology compressing energy costs per kilogram of output.
For Market Incumbents: Lock in pulp-to-fiber integration through backward control over dissolving wood pulp supply in Southeast Asia, while accelerating FSC-PEFC certification timelines to preempt European retail procurement policy shifts. Defend against emerging Chinese second-tier producers by commercializing continuous dry jet wet spinning systems at scale, capturing energy recovery efficiencies that batch-process competitors cannot replicate. For New Entrants and Emerging Players: The gap between premium filament fiber pricing and economy staple tiers offers entry points for Turkish and Pakistani denim mills piloting dry jet wet spinning systems. Target India's technical textile expansion for surgical and hygiene nonwovens, where BIS certification requirements favor closed-loop fiber alternatives. Pursue joint development agreements with European automotive upholstery suppliers seeking biodegradability claims for seat fabric applications. For Investors and Strategic Acquirers: Valuations sit cheapest among regional scale players with plantation feedstock control but lacking solvent recovery infrastructure. Long-term viability over the next decade centers on regulatory enforcement intensity in EU Green Deal textile sustainability mandates and China's dual carbon goals. Watch for inflection signals in NMMO solvent pricing volatility and FSC certification timeline compression affecting Southeast Asian pulp suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dissolving Wood Pulp | Captive pulp supply from Southeast Asian plantations insulates against FSC-PEFC certification divergence and raw material cost volatility. |
| Continuous Dry Jet Wet Spinning Deployment | Turkish denim mills reduce specific energy consumption while differentiating from batch-process viscose operators in Izmir and Istanbul clusters. |
| FSC-PEFC Certification Acceleration | European retail procurement policies now mandate chain-of-custody documentation, favoring suppliers with verified sustainable feedstock traceability. |
| NMMO Solvent Recovery Infrastructure | China's MEE enforcement of recycling thresholds creates competitive moats for producers with integrated closed-loop chemical systems. |
| Luxury Woven Apparel Filament Expansion | Italian and French couture houses source continuous extruded filaments for silk replacement in fluid eveningwear applications. |
Research Methodology
Coverage spans China, Austria, Indonesia, Turkey, and India, with primary inputs from each market combining executive interviews with textile mill procurement directors, garment manufacturer sustainability officers, and chemical engineering specialists with secondary validation. Sources include customs and trade data from Chinese textile export registries, EU REACH authorization filings, SEC 10-K disclosures from listed fiber producers, and BIS technical textile certification records. Bottom-up fiber volume estimates triangulate against top-down apparel industry consumption models.
Rate-of-change decomposition separates volume growth from price-mix effects across staple, filament, microfiber, and blend fiber categories. Segmentation dimensions span product form, application channel, manufacturing technology maturity, and end-user concentration patterns. CAGRs derive from trend-line extrapolation of solvent-spun cellulosic capacity additions, adjusted for regulatory enforcement intensity in EU Green Deal textile mandates and China's GB wastewater standards. Industry-specific inputs include NMMO solvent pricing volatility indices and FSC-certified pulp availability forecasts.
Caveats apply where NMMO petrochemical feedstock cost spikes, FSC-PEFC certification timeline delays, or viscose price competition in home textiles could materially shift the outlook. Forecasts reflect assumptions regarding sustained EU import channel preference for closed-loop fiber alternatives and continued Chinese domestic capacity expansion under dual carbon enforcement. A model refresh is warranted upon material change in REACH authorization requirements or Ministry of Ecology and Environment solvent recycling threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Polypropylene Fiber Market
Synthetic Fibers
Short Cut Polyester Fiber Market
Synthetic Fibers
Polyolefin Fiber Market
Synthetic Fibers
Polyester Staple Fiber Market
Synthetic Fibers
Latin America Textile Market
Synthetic Fibers
Modacrylic Fiber Market
Synthetic Fibers
Synthetic Sewing Thread Market
Synthetic Fibers
Para-Aramid Fibers Market
Synthetic Fibers
Blended Fibers Market
Synthetic Fibers
IMO Fiber Market
Synthetic Fibers
Polyimide Fiber Market
Synthetic Fibers
Asia-Pacific Aramid Fiber Market
Synthetic Fibers
Nanofibers Market
Synthetic Fibers
High End Synthetic Suede Market
Synthetic Fibers
Nylon Fibers Market
Synthetic Fibers
Neoprene Fabric Market