
 Polyolefin Fiber Market | 2026-2036
Polyolefin Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Polyolefin Fiber Market Outlook
ISO 9001 certification cycles for automotive-grade polyolefin fiber suppliers is collapsing from thirty-six months to eighteen months, tightening qualification windows for new entrants. SABIC leverages its upstream petrochemical integration to secure feedstock cost advantages across Middle Eastern production hubs. LyondellBasell Industries Holdings B.V. anchors its position through proprietary Hostalen catalyst technology that yields controlled molecular weight distributions. Indorama Venture Public Company Limited dominates Southeast Asian filament supply by controlling regional recycling streams for post-consumer polypropylene feedstock.
Polyolefin fiber comprises thermoplastic polymer filaments manufactured from polypropylene or polyethylene resins through melt-spinning or gel-spinning processes, typically exhibiting densities below 0.96 g/cm³ and tenacity values ranging from 3.0 to 9.0 g/denier depending on draw ratios and thermal treatment. These fibers serve primarily as lightweight, chemically resistant reinforcement materials in geotextiles, automotive interiors, and liquid filtration media where moisture absorption must remain negligible. Polypropylene fiber leads volume throughput due to its cost-efficiency in staple and filament forms for bulk textile and geosynthetic applications, while polyethylene fiber captures premium positioning in ballistic protection and marine ropes where ultra-high molecular weight grades command substantial margin pools. The filtration application segment is expanding fastest as membrane bioreactor systems in municipal water treatment adopt pleated polypropylene media with defined micron ratings.
FDA regulations governing indirect food contact materials under 21 CFR 177.1520 constrain resin additive packages for polyolefin fibers destined for food packaging and processing applications, while EPA stormwater management mandates under the Clean Water Act accelerate specification of polypropylene geotextiles in erosion control installations. REACH compliance in European markets requires full substance disclosure for imported fiber products containing stabilizers or colorants, elevating documentation burdens for non-EU suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks in multiple jurisdictions, as these mechanisms will determine whether post-industrial and post-consumer polyolefin fiber collection infrastructure achieves the scale needed to support circular manufacturing claims.
Market Dynamics
EU Green Deal mandates for recyclable single-material textiles are redirecting R&D spending toward pure polyolefin constructions, compressing development cycles and forcing suppliers to accelerate qualification timelines for automotive-grade fiber certification.
Growth Catalysts
- Geotextile Infrastructure:Asia-Pacific megaprojects are absorbing larger volumes of high-tenacity polypropylene fiber for soil stabilization and erosion control applications.
- REACH Compliance:Full substance disclosure requirements for imported fiber products containing stabilizers or colorants are elevating documentation standards and favoring prepared suppliers.
- Melt-Spun Capacity Scaling:Domestic producers in China are expanding output for automotive interior applications, creating localized supply advantages.
Market Restraints
- Propylene Feedstock Volatility:Crude oil price swings directly compress margins for non-integrated polyolefin fiber manufacturers lacking captive petrochemical supply.
- ISO 9001 Qualification Compression:Automotive-grade certification cycles collapsing from thirty-six months to eighteen months create barrier-to-entry effects for new suppliers.
- Aramid Substitution in Ballistics:Ultra-high molecular weight polyethylene fiber faces displacement threat from aramid alternatives in premium protective applications.
Strategic Opportunities
- Membrane Bioreactor Filtration:Municipal water treatment systems are adopting pleated polypropylene media with defined micron ratings, opening new specification channels.
- Extended Producer Responsibility Frameworks:Evolving collection infrastructure mandates in multiple jurisdictions will determine circular manufacturing claims scalability.
- Post-Consumer Recycling Streams:Control over regional polypropylene feedstock recovery creates captive raw material positions for forward-integrated filament producers.
Industry Challenges
- Hostalen Catalyst Licensing:Proprietary molecular weight distribution technology remains concentrated among established players, creating IP access barriers for new entrants.
- Stormwater Compliance Documentation:EPA Clean Water Act mandates for erosion control installations require extensive geotextile performance verification, extending sales cycles.
- Gel-Spinning Technical Talent:Ultra-high molecular weight polyethylene fiber production requires scarce polymer processing expertise concentrated in limited geographic clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyolefin Fiber Market |
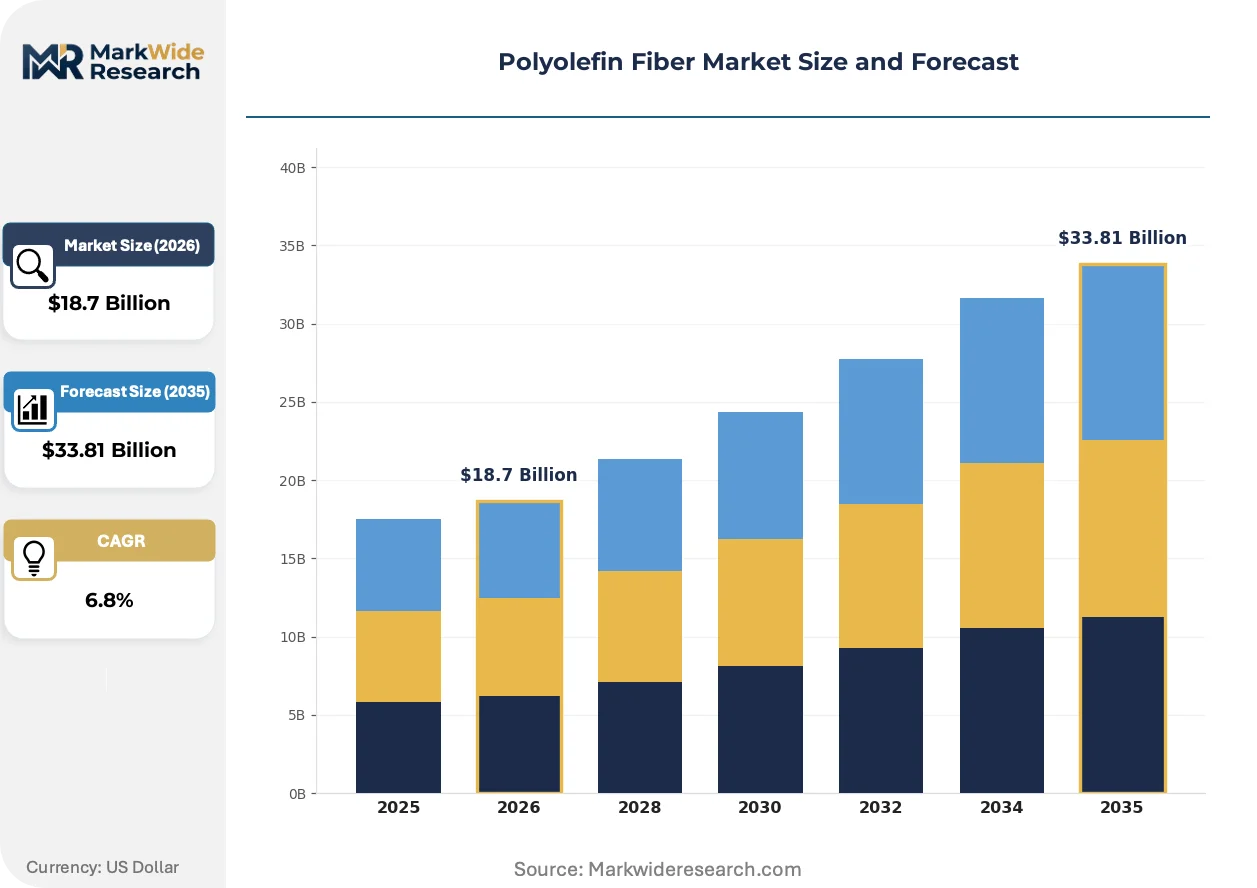
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyethylene, Blends, Others Application: Textiles, Automotive, Foam, Filtration End User: Consumer Goods, Industrial, Healthcare, Packaging Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | SABIC, LyondellBasell Industries Holdings B.V., ExxonMobil Corporation, Dow Inc., Sinopec Group, Borealis AG, Honeywell International, Indorama Venture Public Company Limited, Reliance Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyolefin Fiber Market Strategic Shifts
Active R&D investment is bifurcating the market between commodity melt-spun output for bulk applications and precision-engineered gel-spun fiber for performance-critical end-uses, with regulatory pressure accelerating both tracks simultaneously.
Multi-filament polypropylene yarn with controlled denier variability is supplanting staple fiber in automotive interior applications. Tier 1 seating suppliers are specifying continuous filament constructions for improved abrasion resistance and reduced particulate shedding. This substitution is compressing demand for traditional staple spinning capacity while rewarding producers with draw-texturing capabilities.
REACH substance disclosure requirements are forcing reformulation of antioxidant and UV stabilizer packages across European-bound polyolefin fiber shipments. ECHA registration deadlines are compressing formulation decision windows for compounders serving technical textile markets. Suppliers are responding by qualifying additive systems with full Article 33 transparency ahead of enforcement phases.
Automotive OEMs are consolidating qualified supplier lists around dual-certified producers capable of serving both interior trim and underbody geotextile specifications. Tier 2 converters are losing direct OEM access as procurement functions centralize material approval authority at platform engineering level. This concentration is most visible in German and Japanese automotive supply chains where vertical integration preferences favor captive fiber operations.
Polyolefin Fiber Market Segmentation
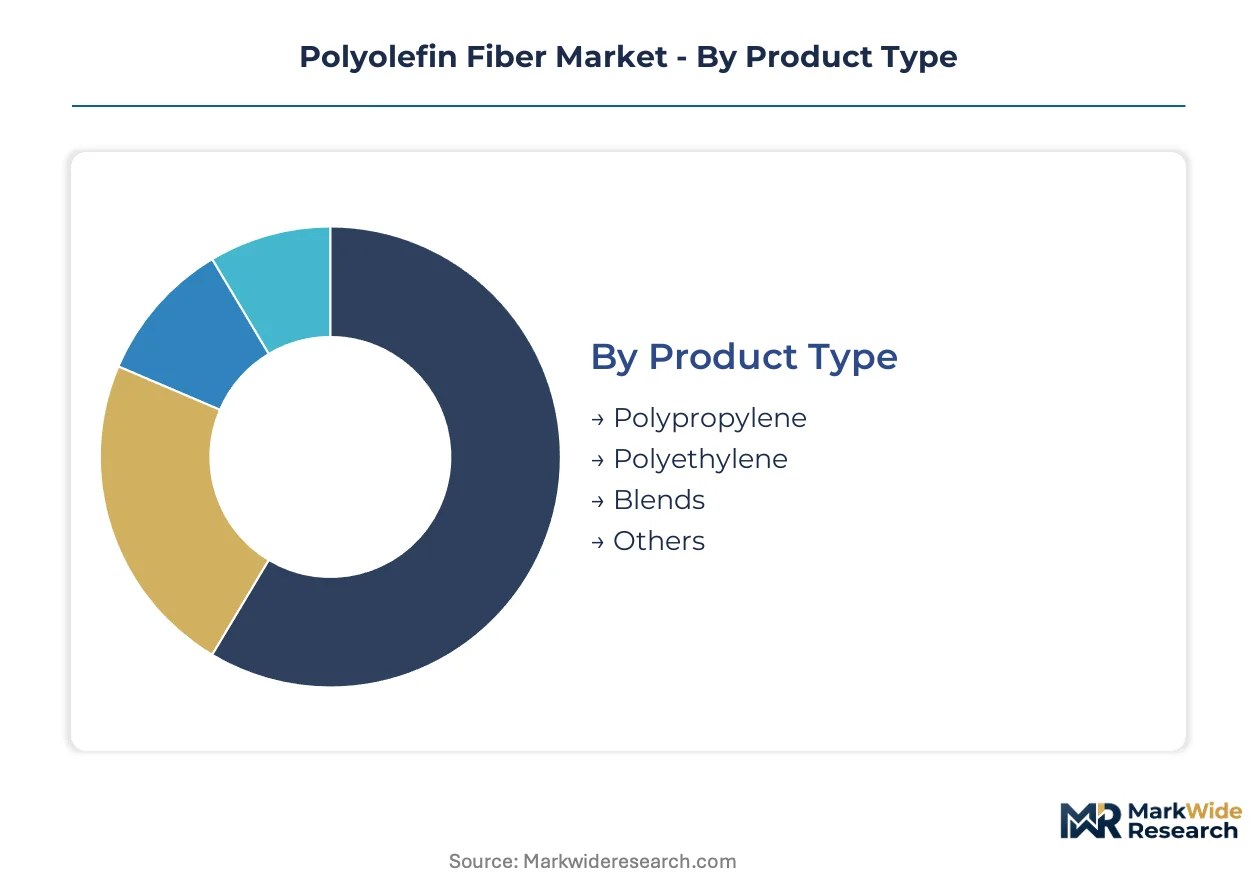
Polyolefin fiber markets fragment along material chemistry, application performance requirements, and channel access structures. Each segmentation axis carries distinct margin profiles and competitive dynamics that determine supplier positioning strategies.
Product Type:
Substitution pressure from bio-based alternatives and engineered polymers varies sharply by base resin chemistry, with commodity grades facing the most severe price-based displacement.
- Polypropylene:Dominates staple and filament production through melt-spinning platforms, achieving densities near 0.90 g/cm³. Demand concentrates in Chinese automotive interior programs and Asia-Pacific geotextile megaprojects where cost-efficiency outweighs performance premiums. Domestic producers are scaling melt-spun capacity aggressively to capture localized supply advantages.
- Polyethylene:Ultra-high molecular weight grades command substantial margin pools in ballistic protection and marine rope applications through gel-spinning processes. Aramid alternatives threaten displacement in premium protective segments where weight reduction targets favor aromatic polymer chemistry.
- Blends:Hybrid constructions combining polyolefin with polyester or polyamide address intermediate performance requirements in technical textiles.
- Others:Specialty copolymers and modified olefinics serve niche medical and filtration specifications requiring defined surface energy characteristics.
Polypropylene retains volume leadership; Polyethylene holds the steepest expansion curve in value terms.
Application:
Customer procurement patterns diverge between specification-driven industrial buyers and price-sensitive commodity converters, reshaping channel economics across each application cluster.
- Textiles:Multi-filament yarn with controlled denier variability is supplanting staple fiber in automotive seating applications. Tier 1 suppliers specify continuous filament constructions for improved abrasion resistance and reduced particulate shedding.
- Automotive:OEMs consolidate qualified supplier lists around dual-certified producers capable of serving both interior trim and underbody geotextile specifications. Procurement centralization at platform engineering level is eliminating Tier 2 converter direct access in German and Japanese supply chains.
- Foam:Lightweight cushioning and insulation applications in furniture and construction absorb commodity-grade staple fiber volumes.
- Filtration:Municipal water treatment systems adopt pleated polypropylene media with defined micron ratings for membrane bioreactor installations.
Automotive commands the highest certification barriers; Filtration is expanding most quickly as infrastructure investment accelerates.
End User:
Regulatory exposure and circular economy readiness separate end-user segments with diverging documentation burdens and collection infrastructure requirements.
- Consumer Goods:Apparel and home textile applications face EU Green Deal pressure for recyclable single-material constructions, redirecting R&D spending toward pure polyolefin formulations.
- Industrial:Geotextile and construction reinforcement buyers prioritize tenacity specifications and UV stability over sustainability credentials in near-term procurement decisions.
- Healthcare:FDA regulations under 21 CFR 177.1520 constrain resin additive packages for medical-grade fiber destined for indirect patient contact applications.
- Packaging:Food contact compliance requirements and extended producer responsibility frameworks determine supplier qualification status in European markets.
Industrial maintains the largest absolute consumption base; Healthcare carries the steepest regulatory compliance cost escalation.
Distribution Channel:
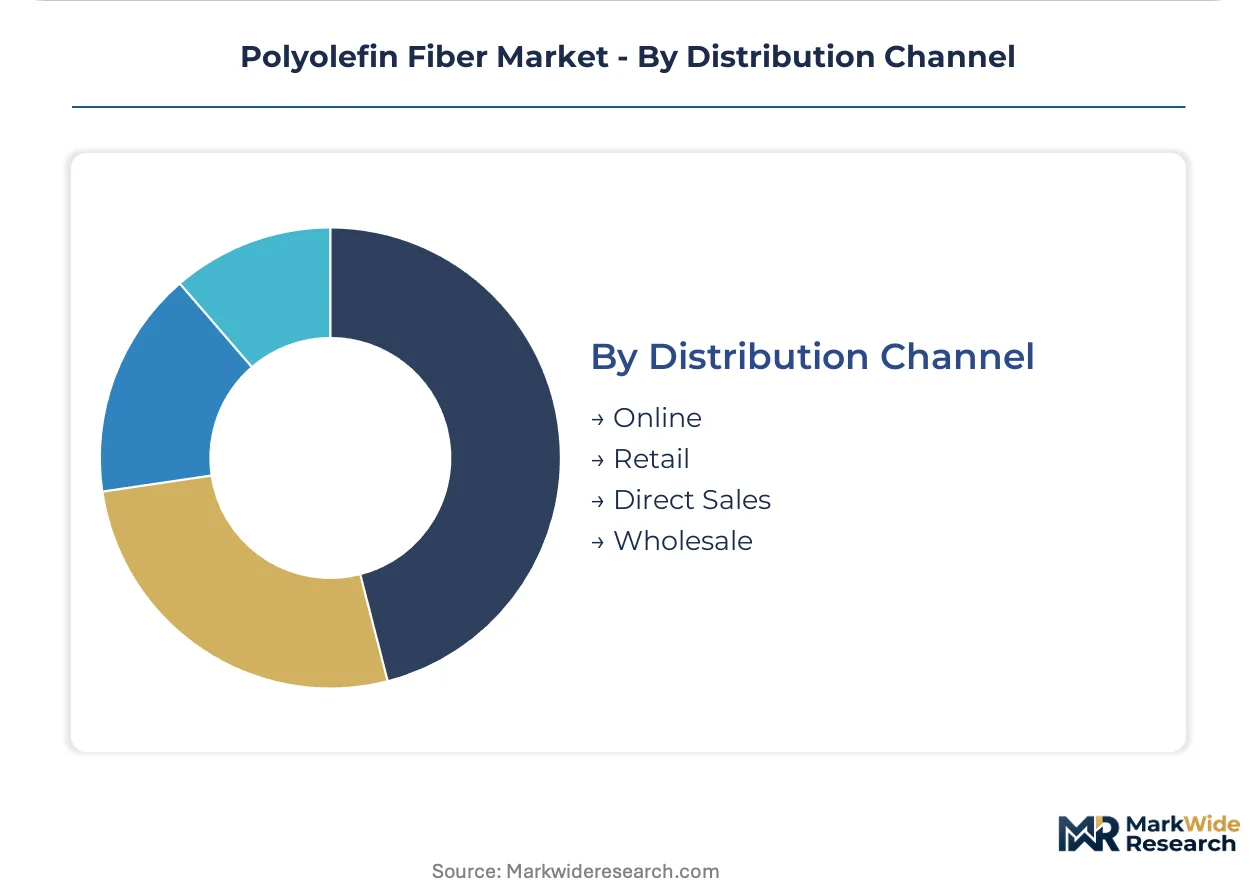
Channel selection reflects order scale, technical service requirements, and geographic proximity to conversion operations, with direct relationships dominating specification-intensive segments.
- Direct Sales:Automotive OEMs and Tier 1 seating suppliers require technical collaboration on fiber denier, draw ratio, and thermal treatment parameters. ISO 9001 certification cycles collapsing from thirty-six to eighteen months compresses qualification windows for new direct channel entrants.
- Wholesale:Geotextile contractors and construction distributors purchase high-tenacity staple fiber in bulk volumes with standardized specifications.
- Retail:Small-lot specialty yarn sales to textile artisans and craft producers carry elevated per-unit margins but limited volume contribution.
- Online:Digital platforms serve prototype development and sample procurement for product designers evaluating fiber candidates.
Direct Sales captures the highest value per ton; Wholesale moves the largest physical volumes across the network.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government infrastructure stimulus packages and circular economy mandates are redirecting polyolefin fiber procurement patterns across major manufacturing economies. National regulators are tightening substance disclosure requirements while industrial clusters concentrate capacity expansion in automotive and geotextile corridors.
China
Domestic melt-spun capacity expansion for automotive interior applications absorbs the largest regional volume increments. MIIT dual carbon goals pressure producers toward energy-efficient spinning technologies. Yangtze River Delta clusters around Shanghai and Ningbo anchor filament yarn output for Tier 1 seating suppliers.
Germany
Automotive OEM procurement centralization at platform engineering level eliminates Tier 2 converter direct access. REACH Article 33 substance disclosure mandates force reformulation of stabilizer packages for European-bound shipments. Baden-Württemberg engineering corridors concentrate qualified supplier certification for interior trim and underbody geotextile specifications.
United States
EPA Clean Water Act stormwater compliance accelerates polypropylene geotextile specification in erosion control installations. FDA 21 CFR 177.1520 constrains resin additive packages for food contact fiber applications. Gulf Coast petrochemical integration secures feedstock cost positions for non-automotive grade staple production.
Saudi Arabia
Upstream petrochemical integration secures propylene feedstock cost advantages across regional production hubs. SAMR-equivalent standards alignment facilitates export qualification for Chinese automotive programs. Jubail Industrial City clusters concentrate high-tenacity fiber output for Middle Eastern geotextile contractors.
Japan
JIS standards and METI circular economy roadmaps elevate documentation burdens for imported fiber products. Automotive supply chain vertical integration preferences favor captive fiber operations over external procurement. Kansai region engineering networks maintain gel-spinning technical expertise for ultra-high molecular weight grades.
Polyolefin Fiber Market Competitive Environment
Player mix skews toward petrochemical-integrated conglomerates with captive feedstock supply, compressing margins for non-integrated specialists. Market structure concentrates around three strategic archetypes: upstream-integrated resin producers controlling molecular weight distribution technology, regional filament specialists dominating post-consumer recycling streams, and diversified chemical conglomerates leveraging catalyst licensing positions. Dominant competitive moves include capacity scaling in Chinese automotive corridors and strategic partnerships securing ECHA-compliant additive formulations ahead of enforcement phases.
Within the upstream-integrated tier, SABIC and LyondellBasell Industries Holdings B.V. exemplify archetypes combining petrochemical feedstock control with proprietary catalyst positions. Indorama Venture Public Company Limited anchors the regional recycling-stream specialist archetype through Southeast Asian filament supply concentration. These three entities occupy positions that reflect the market's bifurcation between commodity melt-spun output and precision-engineered performance grades.
| Leading Market Players |
|---|
| SABIC |
| LyondellBasell Industries Holdings B.V. |
| ExxonMobil Corporation |
| Dow Inc. |
| Sinopec Group |
| Borealis AG |
| Honeywell International |
| Indorama Venture Public Company Limited |
| Reliance Industries Limited |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Chinese automotive Tier 1 seating suppliers and Yangtze River Delta filament producers lock in both propylene feedstock access and eighteen-month price visibility, insulating integrated players from spot resin volatility while exposing non-integrated specialists to margin compression.
Pricing Analysis
Certification level creates the primary spread across automotive-grade, geotextile-specification, and commodity staple tiers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 9001 qualification status, REACH Article 33 compliance documentation, and volume scale commitments. Pricing pressure stems from propylene feedstock volatility and collapsing eighteen-month qualification windows that favor incumbents. Geotextile contractors exhibit highest price sensitivity due to project-based procurement, while automotive OEMs prioritize specification certainty over unit cost.
Supply Chain Analysis
China and Saudi Arabia anchor propylene monomer and high-tenacity filament production through integrated petrochemical corridors. Downstream operations draw from polypropylene resin, Hostalen catalyst systems, and ECHA-compliant additive packages. Single-source vulnerability concentrates in gel-spinning technical talent clusters located in Japan and Germany. Distribution runs through direct sales channels for automotive qualification and wholesale networks for geotextile bulk procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aramid substitution in ballistic protection applications threatens ultra-high molecular weight polyethylene fiber margins, forcing incumbents to defend performance-grade positioning while new entrants exploit certification bottlenecks.
For Market Incumbents: Shield automotive-grade revenue streams by accelerating dual-certification for interior trim and underbody geotextile specifications before procurement centralization eliminates Tier 2 converter access. Deepen backward integration into propylene feedstock through Gulf Coast or Jubail Industrial City production corridors to offset resin price volatility. Lock in Hostalen catalyst licensing positions to maintain molecular weight distribution control against emerging Chinese melt-spun capacity. For New Entrants and Emerging Players: ISO 9001 fast-track programs for automotive-grade fiber open qualification pathways compressed from thirty-six to eighteen months. Target membrane bioreactor filtration media specifications where municipal water treatment infrastructure investment outpaces established supplier capacity. Lead with REACH Article 33 pre-compliant additive packages to bypass documentation barriers blocking non-EU competitors from European technical textile markets. For Investors and Strategic Acquirers: Regional recycling-stream specialists controlling Southeast Asian post-consumer polypropylene feedstock recovery represent the highest-conviction acquisition archetype. Long-term viability hinges on extended producer responsibility framework scalability across European and Asia-Pacific jurisdictions. Monitor ECHA enforcement phase timing as the inflection signal determining circular manufacturing claim legitimacy and feedstock cost advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Chinese domestic melt-spun scaling captures localized automotive interior supply advantages. |
| Backward Integration | Upstream propylene control insulates margins from crude oil price volatility swings. |
| Green Manufacturing Transition | EU Green Deal recyclable single-material mandates redirect R&D toward pure polyolefin constructions. |
| Long-term Supply Agreement | Automotive Tier 1 offtake contracts lock in eighteen-month price visibility and qualification status. |
| Joint Venture | Gel-spinning technical partnerships concentrate scarce polymer processing expertise in limited geographic clusters. |
Study Parameters
A spread of perspectives from filament plant managers, automotive Tier 1 procurement leads, geotextile distribution channel partners, and technical R&D directors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings from petrochemical-integrated conglomerates. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across the projection horizon.
Segmentation dimensions modeled include base resin chemistry, application performance tier, end-use regulatory exposure, and channel access structure throughout the forecast period. CAGRs were derived from production capacity buildout trajectories, OEM platform engineering procurement patterns, and infrastructure stimulus package allocation flows. Industry-specific inputs incorporated MIIT dual carbon goal compliance timelines and EPA Clean Water Act stormwater mandate enforcement schedules.
Decision-makers should treat outputs as directional under assumptions of sustained automotive interior specification consolidation and REACH Article 33 enforcement phasing; material deviation in propylene feedstock pricing or aramid substitution rates would warrant model refresh. Recalibration cycles align with material shifts in extended producer responsibility framework implementation and gel-spinning technical talent migration patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Global High Performance Fibers Market
Synthetic Fibers
North America High Performance Fibers Market
Synthetic Fibers
Polyester Fibers Market
Synthetic Fibers
Americas Spandex Market
Synthetic Fibers
High Temperature Fiber Market
Synthetic Fibers
Long Fiber Thermoplastics Market
Synthetic Fibers
Synthetic Sewing Thread Market
Synthetic Fibers
Asia-Pacific Spandex Market
Synthetic Fibers
Sic Fibers Market
Synthetic Fibers
Blended Fibers Market
Synthetic Fibers
Global Acrylic Fibers Market
Synthetic Fibers
Nanofibers Market
Synthetic Fibers
Polyester Straps Market
Synthetic Fibers
Para-Aramid Fibers Market
Synthetic Fibers
Staple Fibers Market
Synthetic Fibers
Monofilament Market