
 Nylon Fibers Market | 2026-2036
Nylon Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Nylon Fibers Market Outlook
Automotive component buyers are unwinding long-standing polyester commitments in favor of heat-resistant nylon formulations for engine-bay applications. INVISTA leverages its integrated adipic acid supply chain to control raw material flows across North American automotive tiers. BASF SE anchors European demand through specialized high-tenacity grades engineered for airbag fabric and tire cord reinforcement. Shenma Industrial Co., Ltd. dominates captive consumption within China's domestic textile and industrial yarn sectors.
Nylon fibers are synthetic polyamide filaments or staple fibers produced through ring-opening polymerization of caprolactam or condensation of hexamethylenediamine with adipic acid, with melt-spinning temperatures typically ranging from 260°C to 290°C depending on polymer grade. These fibers deliver exceptional abrasion resistance, elastic recovery, and tensile strength for applications spanning tire reinforcement, technical textiles, and engineered plastics. Industrial-grade filaments lead volume consumption across tire cord and conveyor belt applications where fatigue resistance commands premium positioning. High-tenacity grades capture concentrated margin pools in aerospace safety equipment and military ballistic fabrics. Specialty nylon variants including Nylon 11 and Nylon 12 are expanding fastest in medical catheter and fuel line segments where chemical inertness outweighs cost premiums.
REACH registration requirements in Europe and EPA emissions controls in the United States impose stringent caprolactam discharge limits that elevate compliance costs for integrated producers. China's MEE enforcement of dual carbon goals is pressuring coal-based adipic acid routes toward process redesign or capacity rationalization. ISO 14001 environmental management certification increasingly gates supplier qualification for automotive OEM fiber procurement programs. Stakeholders must monitor regulatory divergence between European chemical safety frameworks and emerging Asian carbon intensity benchmarks when situating new polymerization capacity.
Market Dynamics
Automotive OEMs are dismantling metal-intensive engine architectures and substituting heat-stabilized nylon fiber composites, a materials pivot that reconfigures polymer demand curves and supplier qualification protocols across tiered manufacturing networks.
Growth Catalysts
- EPA emissions controls:Tightening caprolactam discharge limits in the United States are accelerating closed-loop polymerization investments that yield higher-grade fiber outputs for technical textile applications.
- Airbag fabric engineering:High-tenacity nylon grades are capturing expanded specification share in automotive safety systems where dimensional stability under rapid inflation stress commands premium positioning.
- China's dual carbon goals:MEE enforcement is redirecting adipic acid investment toward cleaner process routes, consolidating regional capacity and concentrating procurement leverage for domestic textile mills.
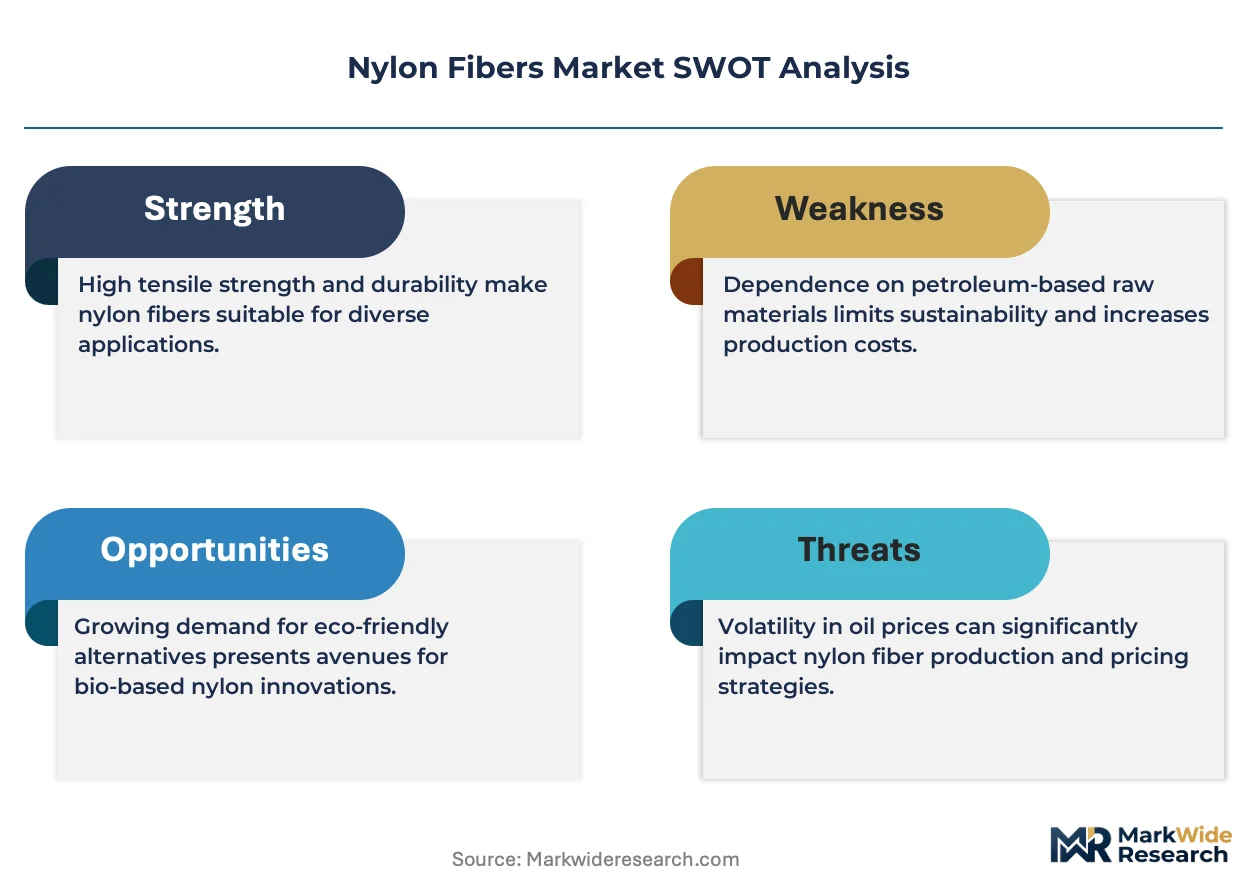
Market Restraints
- Adipic acid price volatility:Benzene feedstock fluctuations transmit directly into nylon 6,6 cost structures, compressing margin predictability for non-integrated spinners.
- REACH registration burdens:ECHA compliance timelines and dossier costs create asymmetric barriers for mid-scale European compounders versus integrated multinational producers.
- Polyester substitution in apparel:Recycled PET fiber economics are undercutting nylon staple in non-technical textile segments where abrasion resistance specifications are relaxed.
Strategic Opportunities
- Medical catheter expansion:Nylon 11 and Nylon 12 biocompatibility profiles are opening specification windows in interventional cardiology devices where chemical inertness outweighs material cost premiums.
- ISO 14001 procurement gating:Automotive OEM fiber qualification programs are creating first-mover advantage for certified producers in underpenetrated Central European supply bases.
- Conveyor belt fatigue resistance:Industrial-grade filament specifications are migrating from mining applications into automated logistics infrastructure where extended duty cycles reduce total cost of ownership.
Industry Challenges
- Melt-spinning technician scarcity:Specialized polymer rheology expertise required for high-tenacity grade production is concentrating within aging workforces in Germany and Japan.
- Polymerization reactor capex intensity:Continuous polymerization line investments demand 8-figure capital commitments that fragment competitive structure between integrated majors and toll-spinning specialists.
- REACH-SVHC compliance documentation:Supply chain traceability requirements for adipic acid derivatives are extending certification timelines and elevating working capital requirements for compound distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nylon Fibers Market |
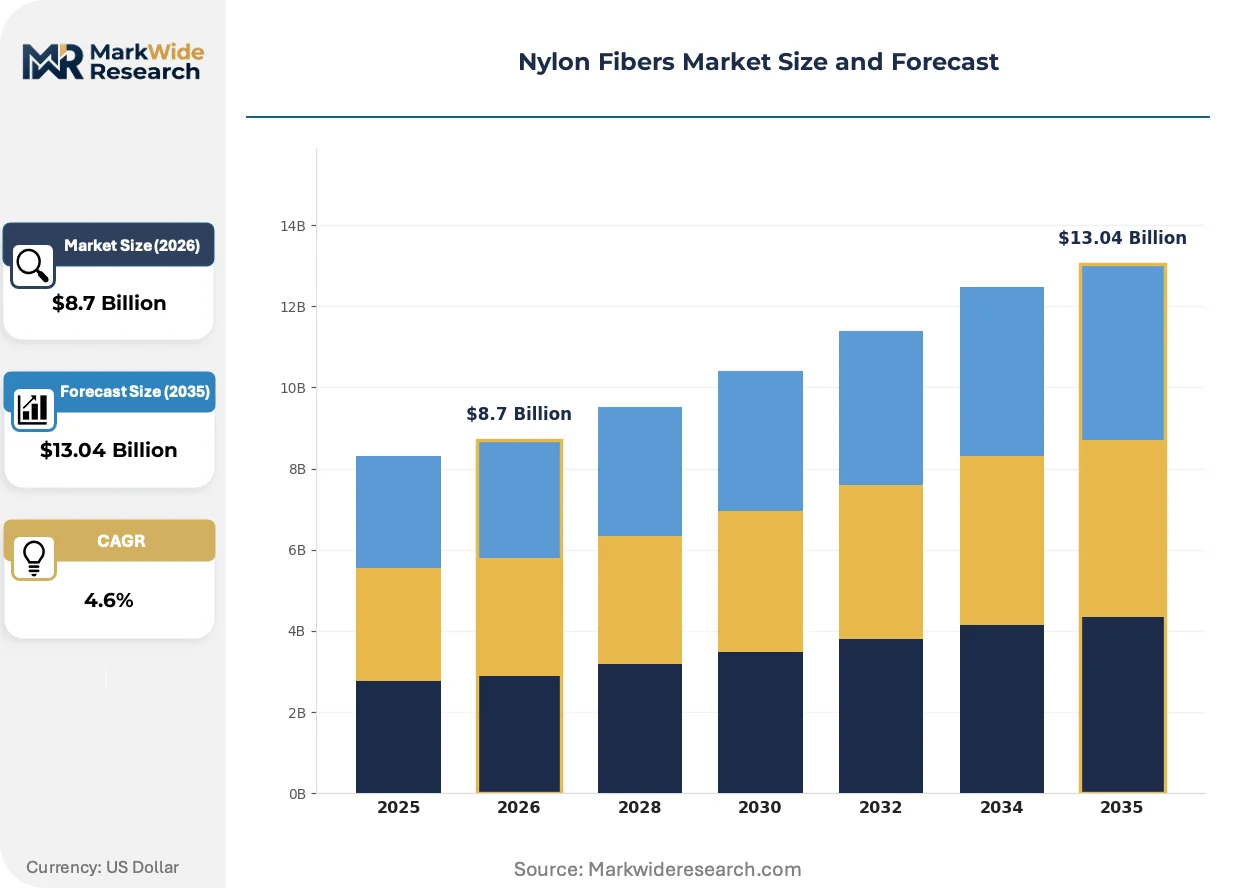
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nylon 6, Nylon 66, Nylon 11, Nylon 12 End Use Industry: Textiles, Automotive, Aerospace, Consumer Goods Form: Filaments, Staple Fiber, Chips, Films Grade: Industrial, High Tenacity, Low Tenacity, Specialty |
| Companies Covered | Asahi Kasei Corporation, Ascend Performance Materials, INVISTA, Radici Partecipazioni SpA, DuPont de Nemours, BASF SE, Solvay, Shenma Industrial Co., Ltd., Toray Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nylon Fibers Market Strategic Shifts
Process intensification and materials science advances are compressing the performance-cost frontier for engineered polyamide fibers, while regulatory chemistry is rewriting supplier qualification protocols across automotive and medical value chains.
Bio-based caprolactam derived from renewable feedstocks is displacing petroleum-sourced monomer in European premium textile applications. Brands with science-based targets are mandating mass-balance certified inputs in performance apparel lines. This displacement is compressing the cost premium between conventional and renewable-grade nylon fibers from double-digit to mid-single-digit percentages.
REACH authorization requirements for hexamethylenediamine intermediates are forcing reformulation investments across European tire cord supply chains. Compounders are accelerating alternative adipic acid route development to preempt SVHC listing impacts. German automotive tier suppliers are most exposed, with several qualifying Asian-sourced polymer to diversify regulatory risk.
Automotive OEMs are consolidating fiber procurement under single-source technical partnerships with integrated polymerization-to-yarn producers. Tier 2 spinners without backward chemical integration are losing specification access in under-the-hood component programs. This concentration is most visible in Detroit and Stuttgart manufacturing clusters where thermal performance guarantees carry liability implications.
Nylon Fibers Market Segmentation
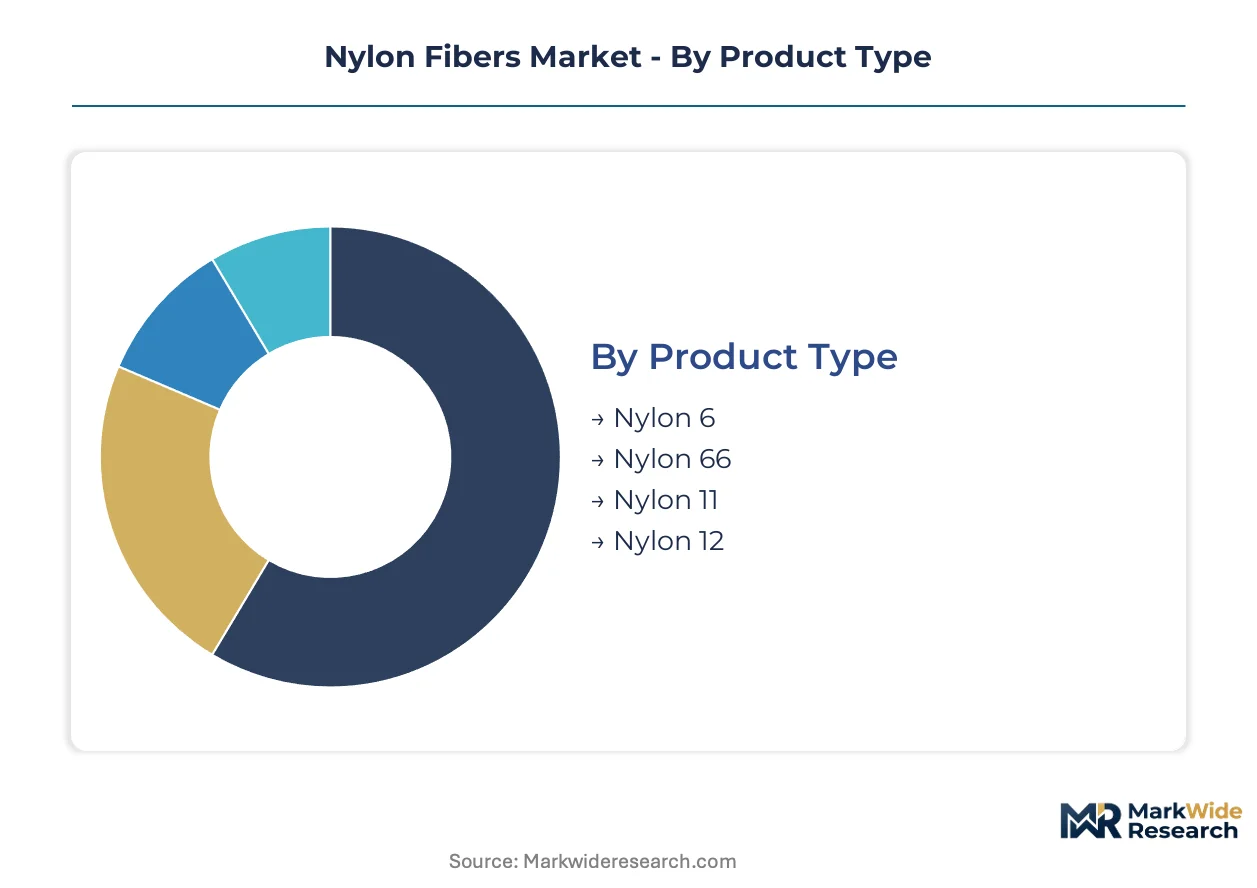
Nylon fiber specifications diverge sharply across end-use requirements, with polymer chemistry and physical form determining channel access and margin capture. Technical buyers in automotive and aerospace sectors impose qualification protocols that filter supply bases by grade and certification tier.
Product Type:
Channel mix varies by polymer backbone: Nylon 6 flows predominantly through textile distributors and compounders, while Nylon 66 concentrates in direct automotive OEM supply chains. Nylon 11 and 12 bypass commodity channels entirely, moving through medical device and specialty chemical distributors.
- Nylon 6:Caprolactam-based polyamide with lower melting point and faster moisture absorption than Nylon 66. Textile mills in China dominate volume consumption, with Shenma Industrial anchoring regional procurement. REACH caprolactam discharge limits are elevating compliance costs for European producers.
- Nylon 66:Hexamethylenediamine-adipic acid condensation polymer delivering superior thermal stability and mechanical strength. Automotive under-the-hood applications in Detroit and Stuttgart manufacturing clusters drive specification demand. EPA emissions controls on adipic acid production are compressing margin structures for non-integrated compounders.
- Nylon 11:Bio-based polyamide derived from castor oil with exceptional chemical resistance and low moisture uptake.
- Nylon 12:Polyamide with lowest moisture absorption and superior dimensional stability for precision medical applications.
Nylon 6 dominates installed base. Nylon 66 is where expansion concentrates.
End Use Industry:
Cost tier stratification separates commodity textile applications from premium technical specifications. Automotive and aerospace segments command 3-5x material premiums over apparel-grade consumption.
- Textiles:Conventional apparel and home furnishing applications consuming staple fiber and textured filament yarns. China's domestic mills process the majority of global volume, with recycled PET economics eroding nylon's share in non-technical segments.
- Automotive:Airbag fabric, tire cord reinforcement, and under-the-hood composite matrices requiring heat-stabilized grades. INVISTA and BASF SE anchor supply through integrated polymerization-to-yarn operations. OEMs are consolidating procurement under single-source technical partnerships.
- Aerospace:Safety equipment and ballistic protection systems demanding certified high-tenacity specifications.
- Consumer Goods:Sports equipment, luggage, and performance apparel where abrasion resistance commands modest premiums.
Textiles anchor volume throughput. Automotive is where margin expansion concentrates.
Form:
Volume concentration favors continuous filament for industrial applications, while staple fiber serves fragmented textile processing. Chips and films occupy specialized compounder and packaging channels with distinct logistics requirements.
- Filaments:Continuous extruded fibers for tire cord, conveyor belts, and technical textiles. Mining and automated logistics infrastructure drive fatigue-resistance specifications. Melt-spinning technician scarcity in Germany and Japan is constraining high-tenacity grade output.
- Staple Fiber:Cut-length fibers for blending with cotton, wool, or synthetic fibers in textile spinning operations.
- Chips:Polymer pellets for downstream compounding and injection molding of engineered plastic components.
- Films:Cast or oriented polyamide films for flexible packaging and industrial barrier applications.
Filaments dominate technical value capture. Staple fiber is where polyester substitution pressure concentrates.
Grade:
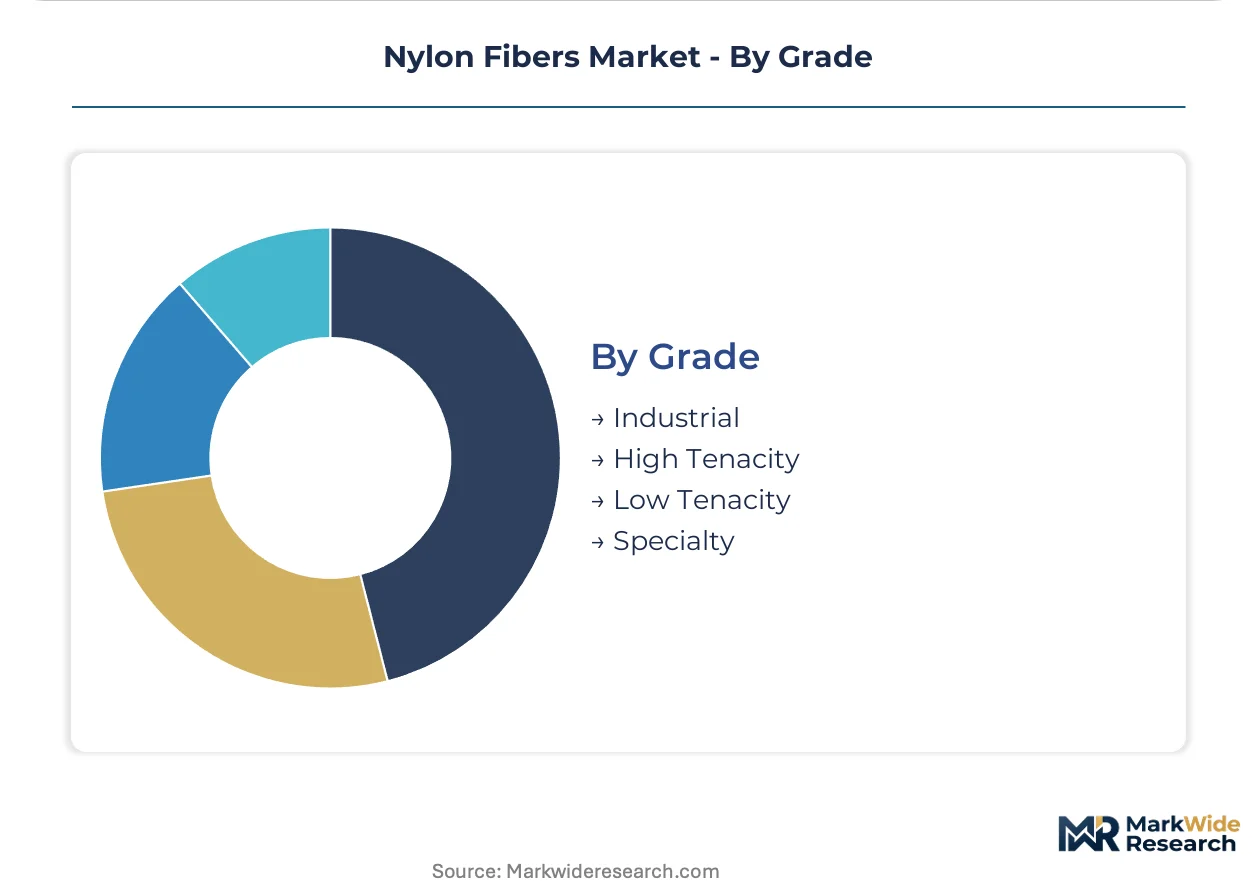
Supply concentration intensifies ascending the performance ladder. Industrial and high-tenacity grades flow through qualified automotive and aerospace channels, while low-tenacity material serves price-sensitive textile markets.
- Industrial:Standard-performance filaments for tire cord, conveyor belts, and rope applications. Mining sector procurement in Australia and Brazil drives fatigue-resistance specifications. ISO 14001 certification increasingly gates supplier qualification.
- High Tenacity:Ultra-high molecular weight grades for airbag fabric, tire reinforcement, and ballistic protection. Aerospace safety equipment manufacturers in the United States and France command premium positioning. REACH-SVHC documentation requirements extend certification timelines.
- Low Tenacity:Apparel and non-technical textile grades competing with polyester on cost.
- Specialty:Custom-formulated grades for medical catheters, fuel lines, and extreme environment applications.
Industrial grade dominates volume throughput. Specialty grade is where steepest expansion trajectory concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports processed nylon fiber intermediates to automotive manufacturing clusters in Germany and the United States, while Japan ships high-tenacity grades to aerospace fabricators in France. This three-corridor trade pattern shapes regional capacity investment and regulatory compliance priorities across polymerization hubs.
China
Shenma Industrial anchors domestic consumption through captive textile and industrial yarn operations. MEE enforcement of dual carbon goals is pressuring coal-based adipic acid producers toward process redesign or capacity rationalization. Shandong Peninsula chemical parks are consolidating regional polymerization capacity to meet stricter emissions benchmarks.
United States
Automotive OEMs in Detroit are expanding under-the-hood nylon fiber content to replace metal engine components. EPA emissions controls on caprolactam discharge are accelerating closed-loop polymerization investments. Gulf Coast petrochemical corridors supply benzene feedstock to integrated adipic acid producers serving tire cord manufacturers.
Germany
REACH registration requirements for hexamethylenediamine intermediates are forcing reformulation investments across tire cord supply chains. ECHA compliance timelines create asymmetric barriers for mid-scale compounders versus integrated multinationals. Stuttgart manufacturing clusters are consolidating fiber procurement under single-source technical partnerships with backward-integrated producers.
Japan
Specialized melt-spinning expertise for high-tenacity grades concentrates within aging technical workforces in Nagoya and Osaka. METI industrial standards govern quality certification for aerospace safety equipment exports. Kanto region producers are qualifying alternative polymer sources to diversify REACH-SVHC regulatory exposure.
India
Domestic textile mills are expanding nylon 6 staple fiber consumption for blending operations with cotton and recycled PET. BIS quality standards increasingly govern supplier qualification for automotive tier procurement. Gujarat chemical corridors are attracting adipic acid investment to reduce import dependence on Chinese intermediates.
Nylon Fibers Market Competitive Environment
Player mix skews toward integrated chemical majors with captive polymerization capacity, creating tiered access to automotive and aerospace qualification programs. Structure concentrates around three strategic archetypes: backward-integrated petrochemical giants controlling feedstock through finished fiber, specialized high-tenacity grade producers serving safety-critical applications, and regional toll-spinning operators dependent on merchant caprolactam supply. Dominant competitive moves include capacity consolidation through asset acquisitions and strategic partnerships locking in automotive OEM technical specifications.
Within the integrated chemical major tier, BASF SE and INVISTA exemplify archetypes with upstream control over adipic acid and caprolactam supply chains. Shenma Industrial Co., Ltd. occupies a position representing regional captive consumption models where polymerization capacity serves domestic textile and industrial yarn demand. Toray Industries sits within the specialty high-tenacity segment, anchoring aerospace and ballistic protection qualification protocols.
| Leading Market Players |
|---|
| Asahi Kasei Corporation |
| Ascend Performance Materials |
| INVISTA |
| Radici Partecipazioni SpA |
| DuPont de Nemours |
| BASF SE |
| Solvay |
| Shenma Industrial Co., Ltd. |
| Toray Industries |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between integrated polymerization majors and automotive OEMs lock in adipic acid supply access while insulating high-tenacity grade producers from benzene feedstock volatility. These arrangements concentrate procurement leverage among backward-integrated players in Germany and China while fragmenting margin capture for toll-spinning specialists dependent on merchant caprolactam.
Pricing Analysis
Current-generation bio-based caprolactam commands mid-single-digit premiums over petroleum-sourced monomer, while next-generation mass-balance certified grades are compressing that gap further. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified high-tenacity filament from automotive industrial grades and apparel staple fiber. Cost compression in textile-grade Nylon 6 is intensifying because recycled PET economics erode specification share where abrasion resistance mandates relax. Tier 2 spinners without chemical integration exhibit highest price sensitivity; integrated majors serving airbag fabric programs demonstrate lowest.
Supply Chain Analysis
China and Germany anchor polymerization capacity, with China processing the majority of global Nylon 6 textile volume and Germany concentrating high-tenacity grades for automotive safety systems. The supply chain draws from benzene feedstock streams in the US Gulf Coast, coal-based adipic acid routes in Shandong Province, and castor oil derivatives for Nylon 11 biopolymer. Single-source vulnerability concentrates in specialized melt-spinning technician pools aging across Nagoya and Osaka. Distribution runs through direct OEM technical partnerships for automotive grades and textile distributor networks for commodity staple fiber.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive OEM consolidation of fiber procurement under single-source partnerships signals platform-economics inflection, where backward-integrated polymerization-to-yarn producers capture specification access and tier 2 spinners face interoperability exclusion.
For Market Incumbents: Secure captive adipic acid supply through capacity rationalization in coal-dependent Shandong corridors or acquisition of distressed European compounders facing REACH-SVHC documentation burdens. Deepen ISO 14001 certification penetration across Central European supply bases to gate competitor qualification access in Stuttgart manufacturing clusters. Prioritize closed-loop polymerization investments that yield higher-grade outputs while preempting EPA emissions enforcement.
For New Entrants and Emerging Players: Lead with medical catheter specifications in interventional cardiology devices, where Nylon 11 and Nylon 12 biocompatibility profiles command cost premiums that outweigh commodity scale disadvantages. Target toll-spinning arrangements for aerospace safety equipment manufacturers in France seeking alternative polymer sources to diversify REACH regulatory exposure. Deploy direct technical sales teams qualified to navigate ECHA compliance timelines.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale European compounders with established automotive tier relationships but stranded without backward chemical integration, as these assets face asymmetric REACH barriers that integrated multinationals can absorb. The acquisition archetype combines qualified high-tenacity production lines with aging technical workforces in Germany or Japan. Monitor MEE enforcement intensity in Shandong Province as inflection indicator for Chinese capacity consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adipic Acid | INSIGHTA's integrated supply chain locks in benzene feedstock access against volatility. |
| Green Manufacturing Transition | Bio-based caprolactam routes displace petroleum monomer for mass-balance certified textile grades. |
| Long-term Supply Agreement | Automotive OEM technical partnerships concentrate procurement under single-source qualification protocols. |
| Joint Venture | Regional toll-spinning operators partner with Chinese polymerization majors to access MEE-compliant capacity. |
| Capacity Expansion | Gujarat chemical corridors attract adipic acid investment to reduce Indian import dependence. |
Study Parameters
A spread of perspectives from polymerization plant managers, automotive Tier 1 procurement leads, textile distribution channel partners, and technical R&D directors converged on the working assumptions driving this analysis. Primary interview insights triangulated against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated chemical majors, and MEE emissions disclosure records. Bottom-up grade-by-grade volume builds reconciled with top-down end-use industry consumption estimates across automotive, aerospace, and textile segments.
Segmentation dimensions modeled include polymer chemistry backbone, physical form, performance grade tier, end-use industry application, and regional production hub classification across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory enforcement intensity and automotive materials substitution velocity. Industry-specific forecast inputs incorporated REACH authorization timelines for hexamethylenediamine intermediates and EPA caprolactam discharge limit implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained MEE enforcement, stable benzene feedstock pricing, or continued automotive metal-to-polymer substitution would require recalibration. Forecasts reflect assumptions regarding technician workforce availability and ECHA compliance cost trajectories. Recalibration cycles align with material shifts in dual carbon policy implementation and airbag fabric specification revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Americas Spandex Market
Synthetic Fibers
Blended Fibers Market
Synthetic Fibers
Polyolefin Fiber Market
Synthetic Fibers
Global Acrylic Fibers Market
Synthetic Fibers
Anti-Static Fibers Market
Synthetic Fibers
Latin America Textile Market
Synthetic Fibers
Modacrylic Fiber Market
Synthetic Fibers
Short Cut Polyester Fiber Market
Synthetic Fibers
Synthetic Fabric Market
Synthetic Fibers
South Korea Textile Market
Synthetic Fibers
Fiberglass Roving Market
Synthetic Fibers
Carbon Fiber Strands Market
Synthetic Fibers
Spandex Fiber Market
Synthetic Fibers
Asia-Pacific Spandex Market
Synthetic Fibers
Polymer Nanofiber Market
Synthetic Fibers
Designer Fiber Market