
 Global Western Wear Market | 2026-2036
Global Western Wear Market Size, Share, and Industry Trends Forecast 2026-2036
Global Western Wear Market Intelligence
Modular product configuration is decoupling traditional western wear sets into mix-and-match components that buyers assemble independently. Levi Strauss & Co. leverages its denim heritage to anchor premium jean collections that function as standalone fashion statements outside ranch contexts. Ariat International specializes in technical footwear and performance apparel that competes across both western and outdoor lifestyle segments. Wrangler sustains volume leadership through workwear distribution channels that dominate rural and industrial markets.
Western wear encompasses apparel and accessories rooted in North American ranching heritage, typically constructed from durable materials such as heavyweight cotton denim, full-grain leather, and wool felt with functional specifications including reinforced stitching, oil-resistant soles, and weatherproof treatments designed for outdoor labor and cultural expression. Denim jeans and cowboy boots represent the most mature product categories where margin pools have compressed, while festival clothing and stage apparel segments are expanding fastest as music tourism and heritage fashion drive non-traditional adoption. E-commerce platforms are displacing department stores as the primary sales channel for younger demographics, though exclusive brand stores retain pricing power among collectors and serious enthusiasts.
FDA oversight of textile chemical treatments, EPA guidelines on leather tanning effluents, and California's Proposition 65 disclosure mandates collectively raise compliance costs for suppliers serving the United States market. REACH regulations in Europe restrict certain chromium compounds in leather processing, forcing manufacturers to reformulate finishing protocols or abandon that geography. Stakeholders must monitor how sustainability certification schemes and supply chain traceability requirements reshape sourcing economics and brand positioning across their distribution footprints.
Market Dynamics
Modular product architecture is fragmenting traditional western wear ensembles into independently purchased components, forcing brands to recalibrate inventory planning and margin allocation across mix-and-match ecosystems rather than bundled set sales.
Growth Catalysts
- REACH compliance migration:European leather tanning reformulation is accelerating vegetable-tanned alternatives that command premium positioning in heritage-conscious consumer segments.
- Music festival economies:Stage apparel demand from Coachella, Stagecoach, and comparable events is pulling non-ranch buyers into western aesthetic adoption.
- Technical fabric innovation:Moisture-wicking wool blends and temperature-regulating denim finishes are expanding western wear into outdoor lifestyle crossover use.
Market Restraints
- Chromium compound restrictions:ECHA limitations on hexavalent chromium in leather processing are raising finishing costs for suppliers serving EU distribution.
- Cotton price volatility:Input cost swings for heavyweight denim fabric are compressing margin predictability across mid-tier product lines.
- Substitution from athleisure:Performance-oriented casual wear is capturing younger demographic spending that previously flowed to western heritage brands.
Strategic Opportunities
- Underpenetrated German market:Heritage fashion adoption in Bavaria and Berlin offers expansion runway for premium boot and accessory lines.
- Resale platform integration:Depop and Poshmark channels are creating circular economy touchpoints for vintage western collectible segments.
- Japanese aesthetic convergence:Amekaji workwear culture in Tokyo and Osaka is importing American ranch heritage with localized styling adaptations.
Industry Challenges
- Artisan skill scarcity:Master leather tooling and hand-stitched bootmaking expertise is concentrating among aging craftspeople in Texas and New Mexico.
- California Proposition 65 compliance:Chemical disclosure mandates for textile treatments are extending product development timelines and testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Western Wear Market |
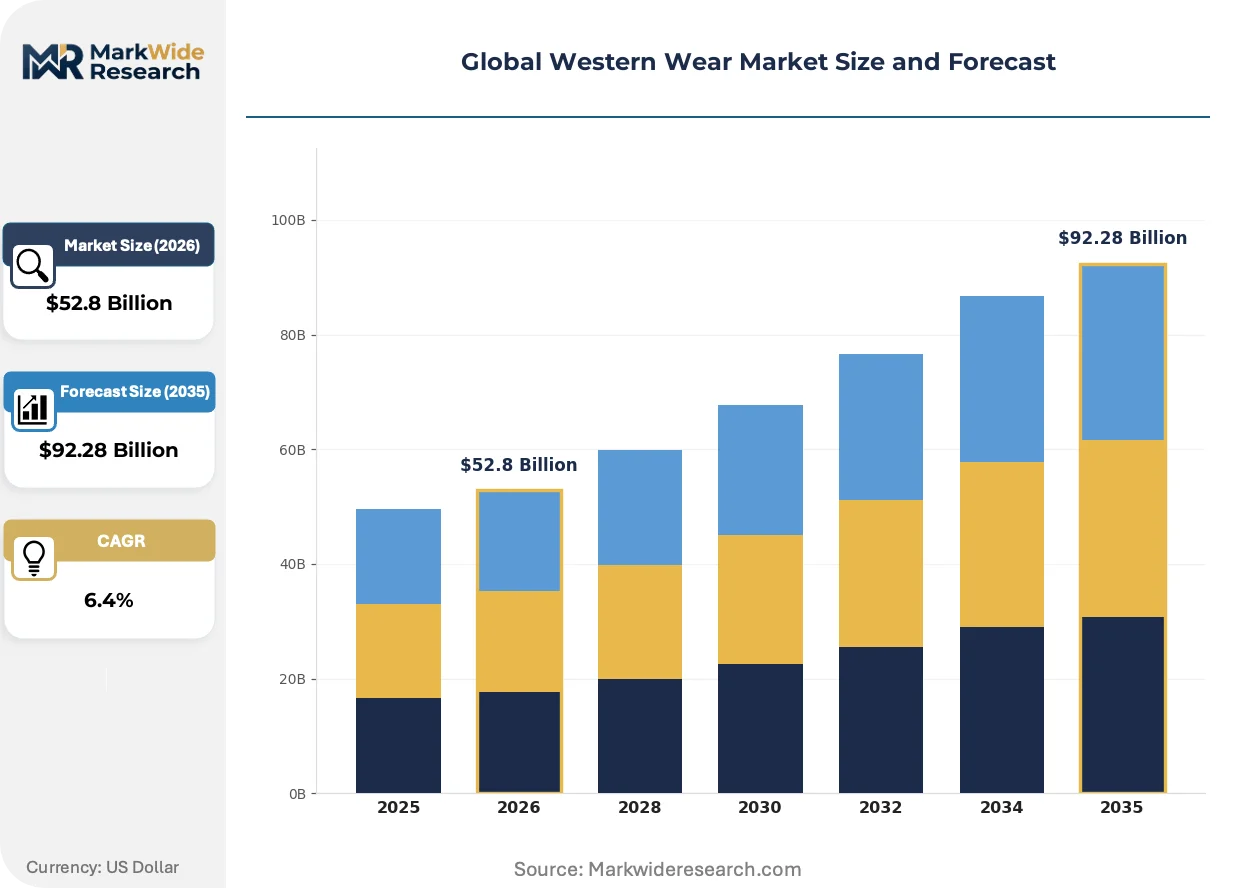
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Denim Jeans, Leather Jackets, Cowboy Boots, Flannel Shirts, Western Hats, Bandanas End User: Men's Apparel, Women's Apparel, Children’s Clothing, Specialty Retail, Online Shoppers, Boutique Customers Sales Channel: Exclusive Brand Stores, Department Stores, E-commerce Platforms, Independent Retailers, Pop-up Shops, Catalog Sales Application: Causal Wear, Workwear, Rodeo Outfits, Festival Clothing, Stage Apparel, Heritage Fashion |
| Companies Covered | Wrangler, PVH Corp., Levi Strauss & Co., Lucchese Brand, Aditya Birla Fashion and Retail Ltd., Ariat International, Diesel, Resistol, Kontoor Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Western Wear Market Strategic Shifts & Innovations
Digital customization tools and on-demand manufacturing are collapsing the traditional seasonal collection cycle, enabling micro-batch production that responds to viral aesthetic moments rather than calendar-driven wholesale schedules.
Blockchain-enabled supply chain verification is decentralizing authenticity claims for leather sourcing and artisan provenance. Heritage brands are adopting distributed ledger systems to document ranch-of-origin for hides and workshop credentials for hand-finished goods. This transparency infrastructure is compressing trust-building timelines with skeptical younger buyers.
REACH chemical restrictions and California's Proposition 65 are forcing reformulation of denim finishing and leather tanning protocols across export-oriented suppliers. Manufacturers serving both European and North American distribution are converging on vegetable-tanned alternatives and laser-based distressing techniques that eliminate potassium permanganate treatments. Small-batch heritage workshops in Italy and Spain are capturing margin from this regulatory-driven quality segmentation.
Festival-driven consumption is rotating demand toward statement pieces with photographic visibility rather than durable workwear functionality. Buyers at Coachella, Stagecoach, and comparable events prioritize visual impact and comfort over traditional oil-resistant soles or reinforced stitching. This behavioral pivot is pulling design resources toward embellishment and away from technical performance specifications that defined ranch-oriented product development.
Global Western Wear Market Segmentation
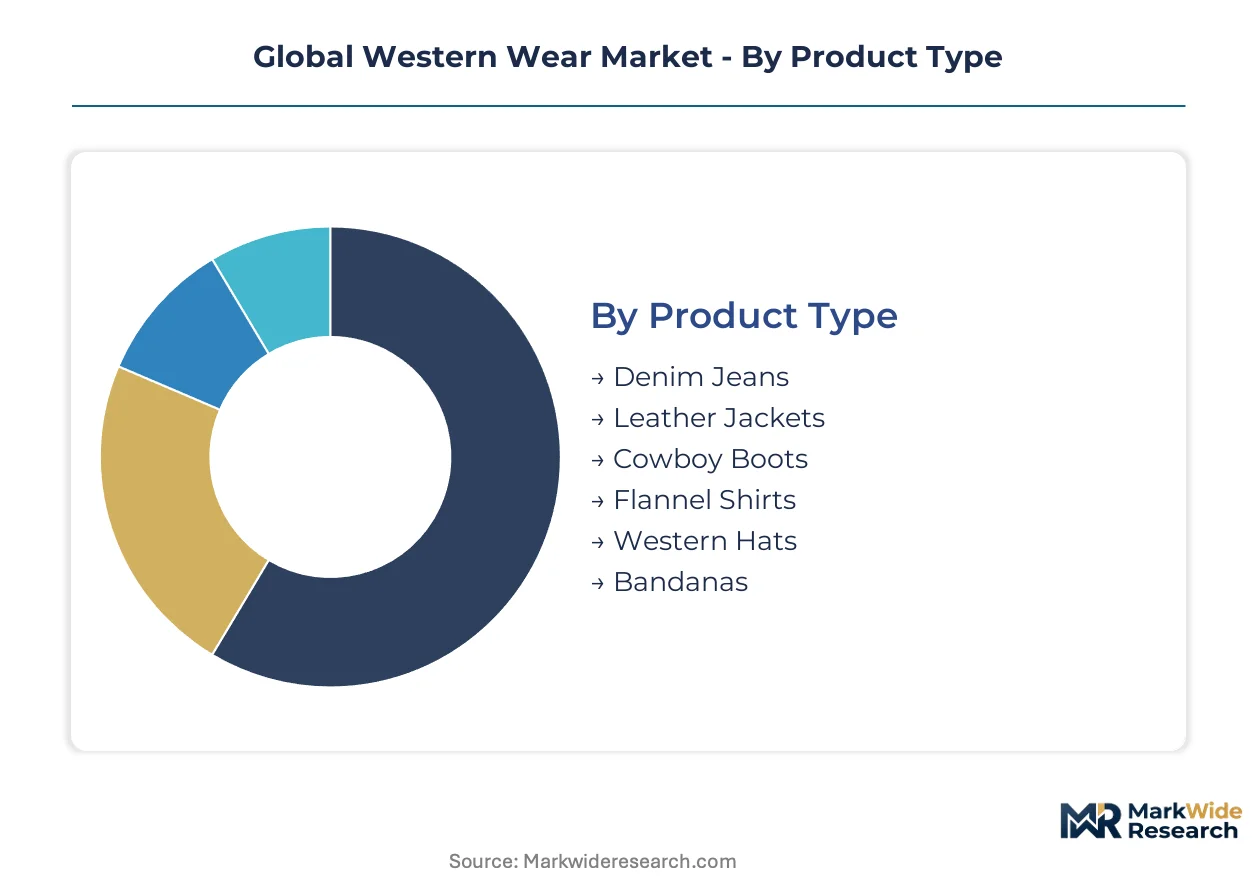
Western wear segmentation reveals how heritage functionality fragments across modern consumption contexts. Product architecture, user identity, purchase venue, and use case each reshape margin structures and inventory velocity differently.
Product Type:
Standalone statement pieces anchor brand recognition while embedded components complete ensemble economics.
- Denim Jeans:Constructed from heavyweight selvedge or stretch cotton with reinforced belt loops and riveted stress points. Volume concentrates in Texas and California where heritage authenticity intersects with music festival styling; cotton price volatility compresses mid-tier margins unpredictably.
- Cowboy Boots:Full-grain leather uppers with leather or synthetic soles, featuring traditional stitching patterns and toe shapes from round to snip. Master bootmakers in El Paso and Leon, Mexico command premium positioning as vegetable-tanned alternatives displace chrome-tanned production under ECHA restrictions.
- Leather Jackets:Heritage silhouettes with shearling or quilted linings, weatherproofed for ranch labor or styled for urban wear. Bespoke workshops in Florence and Madrid capture regulatory-driven quality premiums.
- Flannel Shirts:Brushed cotton or wool-blend weaves in plaid patterns, functioning as layering staples across casual and work contexts. Moisture-wicking technical variants expand into outdoor crossover segments.
- Western Hats:Wool felt or straw constructions with creased crowns and shaped brims, ranging from functional sun protection to collectible artisan pieces. Resale platforms amplify vintage collectible demand.
- Bandanas:Cotton or silk squares with paisley or geometric prints, serving as neckwear, headwear, or accessory accents. Micro-batch production responds to viral aesthetic moments via on-demand manufacturing.
Volume placements concentrate in Denim Jeans; the faster expansion belongs to Cowboy Boots.
End User:
Customer identity shapes price tolerance and purchase frequency across gender, age, and retail sophistication tiers.
- Men's Apparel:Workwear-dominant purchasing with higher per-transaction values and lower return rates. Technical performance specifications drive loyalty in ranch and industrial segments.
- Women's Apparel:Festival and heritage fashion adoption with greater style experimentation and social media influence sensitivity. Stagecoach and Coachella economies pull non-traditional buyers into western aesthetics.
- Children's Clothing:Seasonal replacement cycles tied to growth spurts, with durability demands from rural family households. Rodeo youth circuits in Texas and Oklahoma sustain regional concentration.
- Specialty Retail:Curated assortments targeting collectors and serious enthusiasts, commanding margin premiums through exclusivity and provenance documentation.
- Online Shoppers:Digital-native discovery via Instagram and TikTok, prioritizing visual presentation and peer validation over tactile evaluation.
- Boutique Customers:Personalized service expectations with willingness to wait for made-to-order or limited-release pieces.
Transaction frequency peaks with Online Shoppers; margin retention belongs to Specialty Retail.
Sales Channel:
Channel selection determines pricing power, inventory risk allocation, and customer data access.
- Exclusive Brand Stores:Flagship locations in Dallas, Nashville, and Denver anchor brand mythology while capturing full retail margin. Levi Strauss & Co. and Ariat International leverage these venues for premium positioning.
- E-commerce Platforms:Direct-to-consumer sites and third-party marketplaces displace traditional wholesale for younger demographics. Blockchain-enabled supply chain verification compresses trust-building timelines.
- Department Stores:Declining relevance as assortments narrow to entry-level price points with reduced service differentiation.
- Independent Retailers:Regional western wear specialists in Mountain West states sustaining rodeo culture distribution.
- Pop-up Shops:Festival-adjacent temporary retail capturing impulse demand at Coachella, Stagecoach, and comparable events.
- Catalog Sales:Legacy direct-mail operations retaining rural customer relationships with limited digital engagement.
Customer acquisition concentrates in E-commerce Platforms; pricing power resides with Exclusive Brand Stores.
Application:
Use case segmentation separates durable functionality from ephemeral fashion expression.
- Workwear:Reinforced construction meeting OSHA-relevant durability standards for ranch, oilfield, and agricultural labor. Wrangler sustains volume leadership through industrial distribution channels.
- Festival Clothing:Statement pieces prioritizing photographic visibility and comfort over traditional performance specifications. Design resources shift toward embellishment and away from oil-resistant soles.
- Casual Wear:Everyday adoption of western aesthetics outside occupational or event contexts, driving modular mix-and-match purchasing patterns.
- Rodeo Outfits:Competition-specific garments with regulatory compliance for professional circuits, concentrated in Texas and Oklahoma.
- Stage Apparel:Performance costumes for musicians and entertainers, blending heritage references with theatrical exaggeration.
- Heritage Fashion:Collectible and archival pieces emphasizing artisan provenance and limited production runs.
Unit volume concentrates in Casual Wear; margin expansion belongs to Heritage Fashion.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in Mexico and the southern United States, while consumption disperses across heritage fashion markets in Germany and Japan. Manufacturing gravity pulls toward Leon in Mexico and El Paso in Texas for leather goods, with finishing workshops in Italy and Spain capturing regulatory-driven premium segments.
United States
Texas and the Mountain West anchor domestic demand through rodeo culture and music festival economies. California's Proposition 65 mandates chemical disclosure for textile treatments, extending product development timelines. Artisan bootmakers in El Paso concentrate hand-tooled expertise as vegetable-tanned alternatives displace chrome-tanned production.
Germany
Bavaria and Berlin drive heritage fashion adoption with localized styling preferences for premium boots and accessories. ECHA restrictions on hexavalent chromium in leather processing force reformulation of finishing protocols. Small-batch workshops in Munich capture margin from REACH-compliant quality segmentation.
Mexico
Leon hosts the densest concentration of cowboy boot manufacturing for export markets. Domestic regulators align with U.S. EPA guidelines for leather tanning effluents to maintain cross-border supply relationships. Master craftspeople in Guanajuato sustain hand-stitched production expertise for heritage positioning.
Japan
Tokyo and Osaka import American ranch heritage through Amekaji workwear culture with localized adaptations. METI standards on textile chemical treatments shape import requirements for denim finishing. Specialty retailers in Shibuya curate archival pieces emphasizing artisan provenance documentation.
Italy
Florence and Tuscany host bespoke leather workshops capturing regulatory-driven quality premiums from EU REACH compliance. Vegetable-tanned alternatives command positioning in heritage-conscious consumer segments. Artisan clusters in Santa Croce sustain traditional finishing expertise as chrome-tanned production migrates.
Global Western Wear Market Key Industry Players
The competitive structure tilts toward heritage denim specialists and technical performance brands. Consolidation pressure concentrates around volume leaders with workwear distribution dominance, while fragmentation persists among artisan bootmakers and festival-oriented apparel labels. Two archetypes define positioning: vertically integrated heritage houses controlling full-grain leather supply chains, and modular specialists decoupling components for mix-and-match ecosystems. Dominant moves include geographic expansion into underpenetrated European markets and strategic partnerships with resale platforms for circular economy touchpoints.
Among heritage denim houses, Levi Strauss & Co. and Wrangler occupy positions that exemplify divergent volume-versus-premium strategies. Ariat International represents the technical performance archetype bridging western and outdoor lifestyle segments. These three anchors demonstrate how brand mythology and distribution channel control separate pricing power from commodity positioning.
| Leading Market Players |
|---|
| Wrangler |
| PVH Corp. |
| Levi Strauss & Co. |
| Lucchese Brand |
| Aditya Birla Fashion and Retail Ltd. |
| Ariat International |
| Diesel |
| Resistol |
| Kontoor Brands |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap bootmakers in Texas and New Mexico anchor premium pricing through artisan scarcity, while private-equity-rolled denim specialists compress mid-tier margins through volume scale. This ownership bifurcation concentrates pricing power in hand-tooled heritage segments and erodes it in commodity workwear, reshaping supplier investment priorities across vegetable-tanned leather and laser-finished denim lines.
Pricing Analysis
Margin tightening in mid-tier denim reflects cotton price volatility and athleisure substitution. Three-tier pricing structure across premium, standard, and economy levels separates selvedge heritage lines from stretch basics, with REACH-compliant vegetable-tanned boots commanding quality premiums. Cost-down pressure on festival apparel accelerates because buyers prioritize single-use visual impact over durability. Online shoppers exhibit highest price sensitivity; boutique customers and collectors demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Dallas and Denver anchor hub-and-spoke patterns for domestic fulfillment. Manufacturing concentrates in Mexico, Italy, and Spain, with Leon hosting densest boot production and Tuscan workshops capturing regulatory-driven premiums. Raw material flows draw from full-grain hides, heavyweight cotton denim, and wool felt. Single-source vulnerability concentrates in aging master craftspeople. Distribution runs through exclusive brand stores and direct-to-consumer platforms.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled provenance tracking is displacing legacy authentication methods. This technology transition compresses trust-building timelines with younger buyers and restructures margin allocation toward transparency-verified heritage segments.
For Market Incumbents: Deploy certification investment in REACH-compliant vegetable-tanning capabilities to defend against ECHA regulatory shifts. Anchor channel control through exclusive brand stores in Dallas, Nashville, and Denver. Counter athleisure substitution by accelerating technical fabric innovation in moisture-wicking wool blends. For New Entrants and Emerging Players: Festival-first buyers in Coachella and Stagecoach economies represent the most penetrable archetype. Capture white-space through micro-batch bandana production responding to viral aesthetic moments via on-demand manufacturing. Enter through Depop and Poshmark resale platform partnerships for circular economy positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor distressed heritage denim houses with dormant brand equity in underpenetrated German markets. Long-term viability hinges on regulatory compliance infrastructure and artisan network control. Watch ECHA enforcement intensity in Bavaria as inflection indicator for quality-premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Integration | Decentralized ledger systems document ranch-of-origin for hides, compressing trust timelines with skeptical Gen Z buyers. |
| Vegetable-Tanning Capacity Expansion | REACH-compliant workshops in Tuscany and Leon capture regulatory-driven quality premiums from EU heritage segments. |
| Festival-Adjacent Pop-Up Retail | Temporary venues at Coachella and Stagecoach convert impulse demand into first-party customer data capture. |
| Resale Platform Partnership | Depop and Poshmark integration creates circular economy touchpoints for vintage western collectible segments. |
| Technical Fabric R&D Investment | Moisture-wicking wool blends and temperature-regulating denim finishes expand western wear into outdoor lifestyle crossover. |
Research Approach
Document review covered customs records, SEC filings from Kontoor Brands and Levi Strauss & Co., and ECHA regulatory databases, complemented by interviews with brand managers at heritage denim houses, category buyers at specialty retailers, supply planners for leather tanning operations, and channel sales heads for workwear distribution. Secondary validation drew from Nielsen retail audit data, textile trade associations, and FDA textile treatment guidelines. Bottom-up product-line builds triangulated against top-down macroeconomic consumption models.
Segmentation outputs reflect product type, end-user identity, sales channel configuration, and application use-case across the modeling period. CAGRs derived from historical trajectory analysis adjusted for regulatory phase-in schedules and technology adoption S-curves. Forecast inputs incorporated cotton futures volatility patterns and music festival attendance projections.
Revisions become necessary when ECHA enforcement intensity shifts, California Proposition 65 chemical disclosure mandates expand, or artisan craftsperson attrition accelerates beyond replacement rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Middle East and Africa Footwear Sole Material Market
Apparel Textiles
Global Maternity Innerwear Market
Apparel Textiles
Global Textile Garment Market
Apparel Textiles
Middle East and Africa Textile Garment Market
Apparel Textiles
Rolle Market
Apparel Textiles
North America Footwear Sole Material Market
Apparel Textiles
Head Scarves Market
Apparel Textiles
Braille Clothing Tags Market
Apparel Textiles
Dye Sublimated Apparel Market
Apparel Textiles
TIC for Apparel Market
Apparel Textiles
School Uniform Market
Apparel Textiles
Bridal Wear Market
Apparel Textiles
Uniform Market
Apparel Textiles
Denim Market
Apparel Textiles
China Flame Retardant Apparel Market
Apparel Textiles
Organic Baby Clothes Market