
 Polypropylene Fiber Market | 2026-2036
Polypropylene Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Polypropylene Fiber Market Analysis
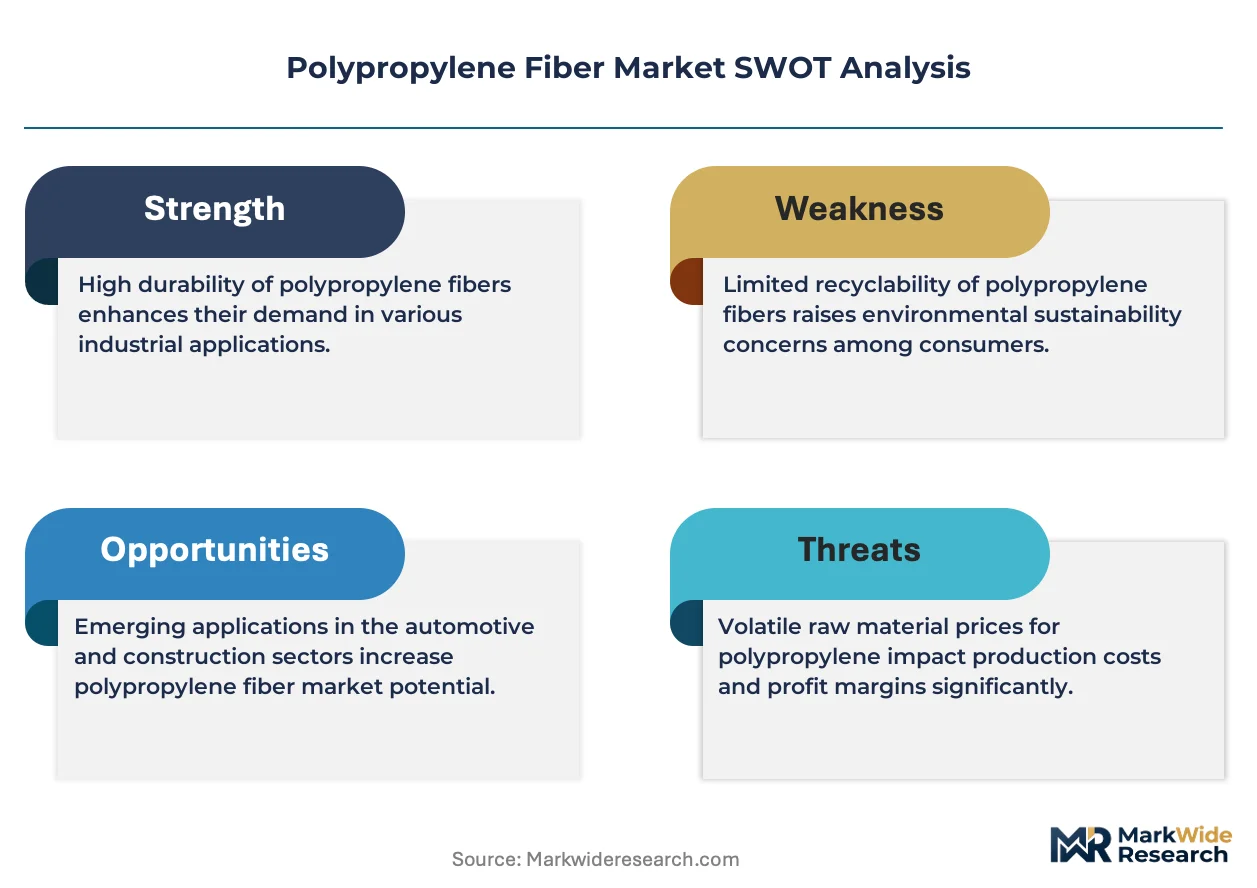
Construction and geotextiles is realigning the demand profile for polypropylene fiber as infrastructure resilience spending redirects volume away from traditional textile applications. Freudenberg Group leverages its filtration specialization to anchor European industrial demand. Indorama Ventures sustains feedstock cost advantages through integrated petrochemical operations in Southeast Asia. Beaulieu Fibres International dominates carpet staple supply to North American flooring manufacturers.
Polypropylene fiber consists of synthetic filaments spun from isotactic polypropylene resin, typically exhibiting tenacities of 4.5–8.0 grams per denier and melting points near 165°C, engineered for moisture resistance, chemical inertness, and dimensional stability in load-bearing applications. Staple fiber occupies the mature, high-volume carpet and upholstery tier where margin compression is structural. Composite fiber is gaining share in automotive underbody shields and construction reinforcement where hybrid performance commands premium positioning. Continuous filament leads filtration and rope applications where tensile consistency determines specification adherence.
EPA industrial emissions standards and REACH substance restrictions are elevating compliance costs for virgin resin producers while accelerating mechanical recycling pathway investments. China's GB standards and MEE enforcement actions are tightening melt-flow index tolerances and volatile organic compound thresholds at extrusion facilities. Stakeholders must monitor regulatory divergence between EU Green Deal circularity mandates and state-level environmental enforcement in the United States to anticipate specification fragmentation and sourcing recalibration needs.
Market Dynamics
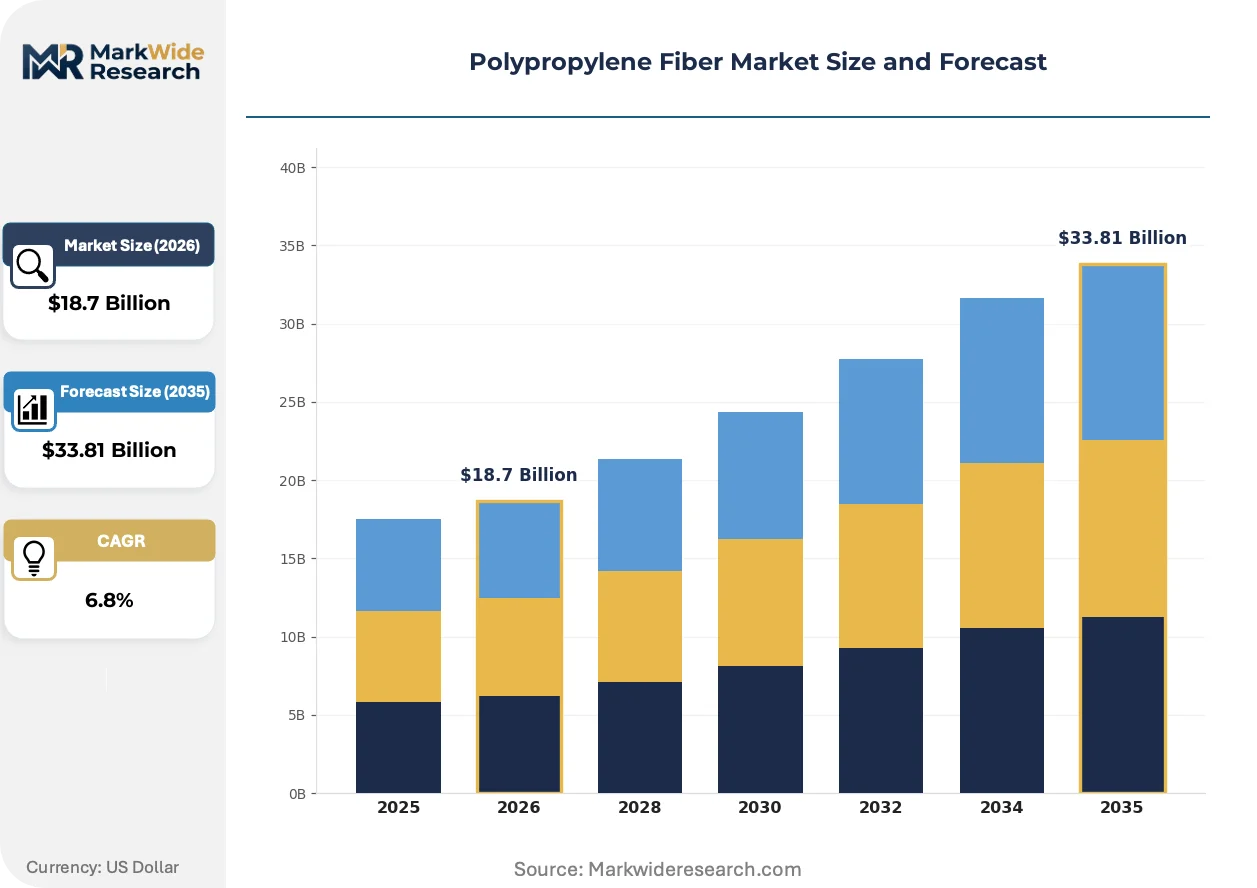
Infrastructure resilience spending is redirecting polypropylene fiber volume from textile applications toward construction-grade geotextiles, while REACH and EPA compliance costs compress margins for virgin resin producers.
Growth Catalysts
- Construction-grade geotextiles:Infrastructure projects in China, India, and the United States are specifying high-tenacity staple fiber for soil stabilization and erosion control. MEE enforcement of GB standards is accelerating qualification of domestic suppliers for these civil engineering contracts.
- REACH substance restrictions:ECHA's tightening limits on additive chemistries are forcing formulation upgrades that improve recyclability credentials. European automotive and filtration buyers now specify mechanically recycled feedstock as a procurement condition.
- Melt-blown filtration media:Industrial air filtration and liquid separation applications are absorbing increasing volumes of fine-denier continuous filament. EPA industrial emissions standards are mandating upgraded particulate capture systems across US manufacturing facilities.
Market Restraints
- Propylene feedstock volatility:Naphtha and propane dehydrogenation economics expose fiber producers to raw material cost swings. Integrated petrochemical operators capture margin that independent spinners cannot access.
- Yangtze River Delta concentration:Export-oriented production clusters in Jiangsu and Zhejiang provinces create single-point vulnerability for global supply. Logistics disruptions at Shanghai Port propagate through downstream carpet and geotextile supply chains.
- Mechanical recycling yield limits:Thermal degradation during re-extrusion reduces molecular weight and tenacity. High-performance applications reject post-consumer feedstock due to inconsistent melt-flow index.
Strategic Opportunities
- Automotive underbody composites:Hybrid fiber-reinforced thermoplastic shields are displacing metal splash guards in electric vehicle platforms. OEM lightweighting mandates favor polypropylene-glass hybrid structures over traditional stamped steel.
- India BIS certification pathways:Bureau of Indian Standards harmonization with ISO test methods is reducing technical barriers for imported specialty fiber. Domestic technical textile capacity gaps create import substitution openings for certified suppliers.
- Chemical recycling scale-up:Pyrolysis and dissolution technologies are approaching commercial viability for contaminated post-industrial waste. Pyrolysis oil yields promise virgin-equivalent resin properties without feedstock quality constraints.
Industry Challenges
- Polymer rheology expertise:Controlling melt-flow index and draw ratios for specialty applications requires process engineering talent that commodity producers lack. Technical textile specifications demand tighter coefficient of variation than carpet-grade operations can deliver.
- Multi-jurisdictional compliance:Simultaneous adherence to REACH SVHC lists, EPA TSCA Section 6 restrictions, and China's MEE volatile organic compound thresholds fragments quality management systems. Testing and documentation burdens scale with export market diversification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polypropylene Fiber Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Fiber, Staple Fiber, Composite Fiber, Specialty Fiber End Use Industry: Textiles, Automotive, Construction, Geotextiles Form: Monofilament, Multifilament, Non-woven, Woven Application: Ropes, Carpets, Upholstery, Filtration |
| Companies Covered | Mitsubishi Chemical Corporation, ABC Polymer Industries LLC, Beaulieu Fibres International, China National Petroleum Corporation, Belgian Fibers, Chemosvit Fibrochem SRO, Radici Partecipazioni SpA, Freudenberg Group, Indorama Ventures, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polypropylene Fiber Market Emerging Trajectories
Polypropylene fiber manufacturing is bifurcating between commodity scale and specialty precision, with process control technologies and regulatory chemistry requirements driving capital deployment decisions.
Multi-component spinning technology is consolidating technical capabilities across previously separate product categories. Bicomponent sheath-core structures now enable thermal bonding in geotextiles while maintaining tensile performance in load-bearing applications. Construction and automotive buyers are consolidating supplier bases toward processors with in-house conjugate spinning capability.
EPA industrial emissions standards and ECHA REACH authorization requirements are elevating capital intensity for virgin resin production. New extrusion lines must incorporate volatile organic compound capture and closed-loop cooling to secure operating permits. Filtration and medical textile segments are responding by qualifying mechanically recycled feedstock to bypass virgin resin compliance costs.
Buyers in European industrial filtration are consolidating annual volume commitments toward processors with demonstrated batch-to-batch consistency. Long-term supply agreements now specify maximum coefficient of variation for tenacity and elongation, replacing spot-market purchasing. German and Benelux automotive suppliers are most advanced in this specification-driven procurement consolidation.
Polypropylene Fiber Market Segmentation
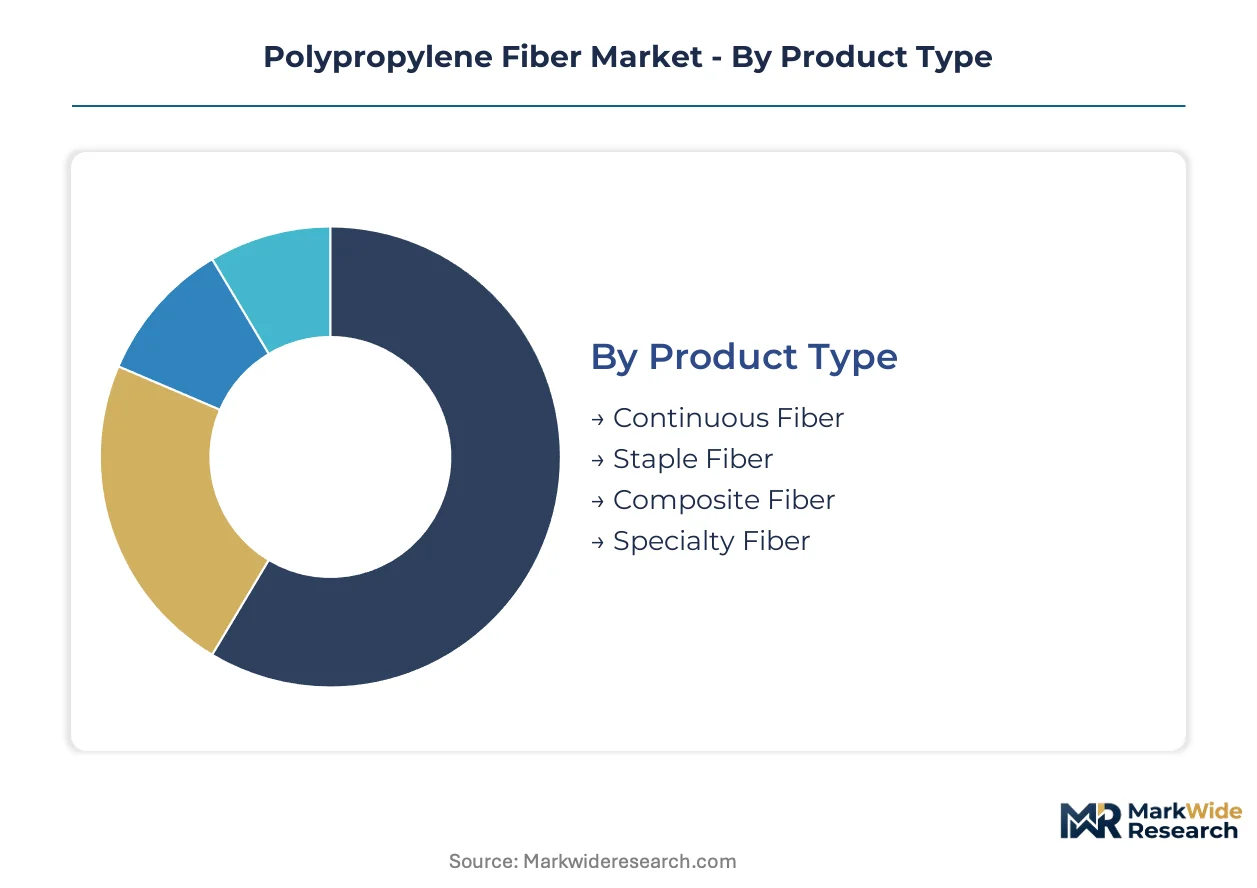
Polypropylene fiber manufacturers configure production lines around specific technical specifications that lock in customer relationships for multi-year contracts. Segmentation reveals how supply-side capabilities map onto end-use requirements, with melt-flow index tolerances and draw ratio controls determining which processors can serve filtration versus carpet markets.
Product Type:
Supply concentration clusters around processors with conjugate spinning capability, where capital intensity creates tiered competitive positions.
- Continuous Fiber:Extruded as unbroken filaments with tenacities of 6.0–8.0 grams per denier, continuous fiber dominates filtration media and industrial rope manufacturing where batch-to-batch consistency determines specification adherence. German and Benelux automotive suppliers now mandate maximum coefficient of variation for tenacity in annual volume commitments.
- Staple Fiber:Cut to discrete lengths of 38–150mm, staple fiber supplies carpet backing and upholstery filling where high-volume throughput outweighs precision requirements. China's Yangtze River Delta manufacturing cluster hosts integrated resin-to-fiber operations that lower logistics costs for export-oriented producers serving North American flooring manufacturers.
- Composite Fiber:Hybrid structures combining polypropylene with glass or mineral fillers enable automotive underbody shields and construction reinforcement applications.
- Specialty Fiber:Modified additive packages and controlled rheology serve medical textiles and high-temperature filtration niches.
Staple fiber absorbs the bulk of installed capacity; composite fiber is expanding most quickly.
End Use Industry:
Customer procurement patterns diverge sharply between spot-market textile buyers and specification-driven automotive and construction contractors.
- Construction:Geotextile specifications for soil stabilization and erosion control demand high-tenacity fiber with UV stabilization packages. Infrastructure resilience spending across China, India, and the United States redirects volume from traditional textile applications toward civil engineering contracts.
- Geotextiles:Load-bearing applications require engineered fabrics meeting ISO 10319 tensile test protocols. MEE enforcement of GB standards accelerates qualification of domestic Chinese suppliers for state-funded infrastructure projects.
- Textiles:Carpet and upholstery manufacturers prioritize cost position over technical performance in mature, margin-compressed segments.
- Automotive:OEM lightweighting mandates favor polypropylene-glass hybrid structures for underbody shields in electric vehicle platforms.
Construction and geotextiles together command premium positioning; automotive applications are climbing the fastest as electrification accelerates material substitution.
Form:
Process technology investments determine which form factors processors can manufacture profitably, with multi-component spinning lines enabling portfolio breadth.
- Non-woven:Melt-blown and spunbond processes produce filtration media and disposable medical textiles where fine denier control determines particulate capture efficiency. EPA industrial emissions standards mandate upgraded air filtration systems across US manufacturing facilities.
- Multifilament:Bundled fine filaments serve rope and industrial sewing thread applications requiring balanced strength and flexibility.
- Monofilament:Single-strand extrusions supply synthetic turf and fishing line markets.
- Woven:Interlaced yarn structures provide dimensional stability for geotextile and industrial fabric applications.
Non-woven forms dominate capital deployment; woven structures are gaining share fastest in infrastructure applications.
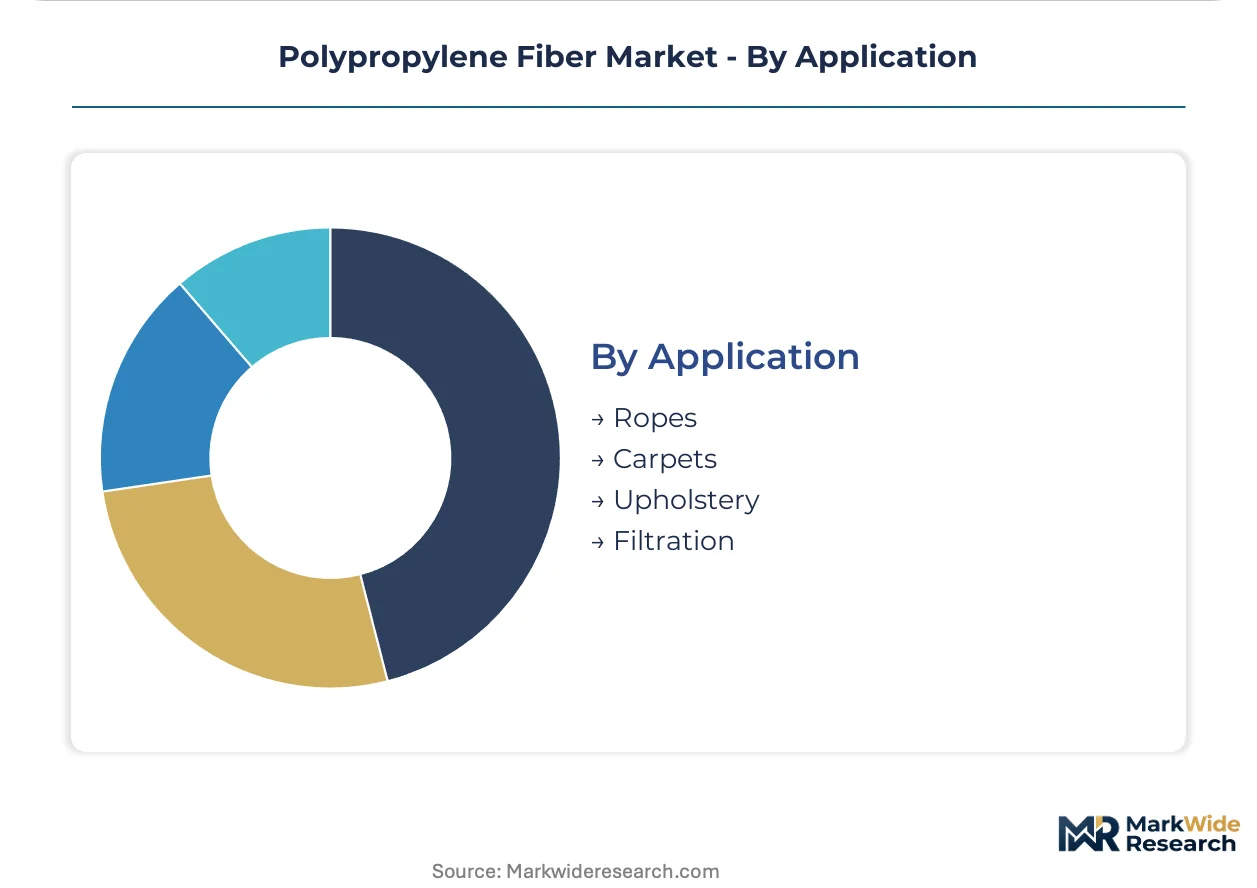
Application:
Application-specific certification requirements fragment the supplier base, with filtration and medical segments demanding documentation that commodity processors cannot provide.
- Filtration:Industrial air and liquid separation systems require fine-denier continuous filament with controlled pore size distribution. REACH substance restrictions and ECHA authorization requirements elevate compliance costs for virgin resin, pushing buyers toward mechanically recycled feedstock procurement.
- Carpets:Bulked continuous filament and staple fiber supply residential and commercial flooring markets where price competition is structural.
- Ropes:Marine and industrial cordage applications specify high-tenacity multifilament with abrasion-resistant coatings.
- Upholstery:Furniture and automotive seating fillers prioritize loft recovery and flame retardancy over tensile performance.
Carpets consume the greatest volume; filtration applications show the steepest expansion trajectory as environmental regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of polypropylene fiber feedstock, while the United States, Germany, and India absorb disproportionate shares of construction-grade and filtration demand. This production-consumption divide shapes freight economics, tariff exposure, and qualification timelines for specification-driven buyers.
United States
Infrastructure resilience spending and electric vehicle manufacturing are redirecting polypropylene fiber volume toward geotextiles and automotive composites. EPA industrial emissions standards mandate upgraded air filtration systems that absorb fine-denier continuous filament. The Gulf Coast petrochemical corridor supplies captive propylene feedstock to integrated fiber spinners serving domestic carpet and construction markets.
China
State-funded infrastructure projects across high-speed rail and coastal erosion control are specifying high-tenacity staple fiber for soil stabilization applications. MEE enforcement of GB standards accelerates qualification of domestic suppliers for civil engineering contracts. The Yangtze River Delta manufacturing cluster hosts integrated resin-to-fiber operations that lower logistics costs for export-oriented producers.
Germany
Automotive OEM lightweighting mandates favor polypropylene-glass hybrid structures for underbody shields in electric vehicle platforms. ECHA REACH authorization requirements elevate compliance costs for virgin resin, pushing industrial filtration buyers toward mechanically recycled feedstock procurement. The Benelux-German corridor concentrates technical textile processors with demonstrated batch-to-batch consistency.
India
Bureau of Indian Standards harmonization with ISO test methods is reducing technical barriers for imported specialty fiber in technical textile applications. Domestic technical textile capacity gaps create import substitution openings for certified suppliers. The Gujarat-Maharashtra industrial belt hosts emerging non-woven filtration media capacity serving pharmaceutical and food processing demand.
Japan
Automotive and industrial filtration applications specify fine-denier continuous filament with controlled coefficient of variation for tenacity. METI circular economy guidelines accelerate mechanical recycling pathway investments for post-industrial fiber waste. The Chubu-Nagoya manufacturing region concentrates precision spinning operations serving medical textile and high-temperature filtration niches.
Polypropylene Fiber Market Vendor Landscape
Top-tier vendors anchor integrated petrochemical-to-fiber operations, while mid-tier independent spinners compete on cost position in commoditized segments. The vendor base stratifies across three archetypes: chemical conglomerates with captive resin supply, specialized fiber processors with conjugate spinning capability, and regional commodity producers serving carpet and upholstery markets. Dominant competitive moves include backward integration into propylene feedstock and technology licensing for multi-component spinning lines.
Within the chemical conglomerate tier, Mitsubishi Chemical Corporation and China National Petroleum Corporation exemplify upstream-controlled positioning that captures margin unavailable to independent processors. Among specialized fiber processors, Freudenberg Group and Beaulieu Fibres International occupy positions defined by technical specification adherence in filtration and carpet staple supply respectively. These named entities represent strategic archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| ABC Polymer Industries LLC |
| Beaulieu Fibres International |
| China National Petroleum Corporation |
| Belgian Fibers |
| Chemosvit Fibrochem SRO |
| Radici Partecipazioni SpA |
| Freudenberg Group |
| Indorama Ventures |
| Others |
Supply Flow & Price Mechanics
Automotive OEM lightweighting mandates for electric vehicle platforms are forcing fiber processors to qualify hybrid composite structures, compressing margins on conventional staple grades while commanding premiums for certified continuous filament. This specification divergence rewards integrated producers with captive resin supply and multi-component spinning capability.
Pricing Analysis
Short lead-time premiums now separate qualified suppliers from spot-market commodity sellers in the polypropylene fiber trade. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume commitment scale, with REACH-compliant virgin resin commanding sustained premiums over mechanically recycled alternatives. Price differentiation stems from melt-flow index precision and batch-to-batch consistency guarantees. Cost compression in carpet-grade staple is intensifying because China's Yangtze River Delta exporters compete on volume throughput. Construction contractors show least price sensitivity due to specification-driven procurement, while upholstery manufacturers absorb greatest margin pressure.
Supply Chain Analysis
India's BIS certification harmonization with ISO test methods is redirecting specialty fiber sourcing toward certified importers and away from undocumented traders. Manufacturing gravity centers on China, the United States, and Germany, with propylene feedstock drawing from Gulf Coast petrochemical corridors, naphtha crackers in East Asia, and propane dehydusion units in the Middle East. Single-source vulnerability concentrates in Shanghai Port logistics for export-oriented Yangtze River Delta spinners. Distribution runs through direct mill relationships for specification-driven automotive and filtration buyers, with commodity carpet staple flowing through distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-component spinning technology is displacing legacy single-extrusion lines as bicomponent sheath-core structures enable thermal bonding without sacrificing tensile performance. This transition favors capital-rich processors with process engineering depth over commodity spinners.
For Market Incumbents: Anchor qualification pipelines for automotive underbody composite specifications before OEM platform finalization locks in supplier bases. Deepen backward integration into propylene feedstock to capture margin unavailable to independent spinners facing naphtha cost volatility. Prioritize conjugate spinning capacity additions in the Benelux-German corridor to serve filtration buyers consolidating toward batch-to-batch consistency guarantees.
For New Entrants and Emerging Players: Technical textile distributors in India represent the most penetrable channel partner type for specialty fiber market entry. Target BIS-certified import substitution openings in Gujarat-Maharashtra pharmaceutical and food processing filtration media. Pursue joint qualification programs with domestic geotextile fabricators serving state-funded infrastructure projects to bypass entrenched Yangtze River Delta supply relationships.
For Investors and Strategic Acquirers: The window for entry favors specialized fiber processors with demonstrated regulatory compliance documentation across REACH, EPA, and GB standards. Five-to-ten-year viability hinges on chemical recycling technology maturation for contaminated post-industrial waste streams. Monitor pyrolysis oil yield consistency as the inflection signal for virgin-equivalent resin property achievement without feedstock quality constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Feedstock | Captures margin compression from naphtha volatility that independent spinners cannot access. |
| Multi-Component Spinning Line Installation | Enables bicomponent thermal bonding for geotextiles while maintaining load-bearing tensile performance. |
| REACH-Compliant Virgin Resin Certification | Secures automotive and filtration procurement conditions mandating mechanically recycled feedstock alternatives. |
| India BIS Harmonization Pathway | Reduces technical barriers for imported specialty fiber in technical textile applications with domestic capacity gaps. |
| Chemical Recycling Scale-Up Partnership | Approaches commercial viability for pyrolysis oil yields promising virgin-equivalent resin properties. |
Methodological Framework
Multi-period observation of melt-flow index tolerance standards, MEE enforcement actions, and OEM lightweighting procurement patterns anchored the trend analysis, supplemented by interviews with plant managers at integrated petrochemical operations, procurement leads at North American flooring manufacturers, technical R&D directors at filtration media processors, and distribution channel partners in the Benelux corridor. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of listed chemical conglomerates, and GB standard publication records. Bottom-up fiber production capacity modeling and top-down end-use demand estimation provided triangulation checks.
Input-output matrices mapped propylene feedstock availability through extrusion capacity to end-use consumption across construction geotextiles, automotive composites, filtration media, and carpet backing. Segmentation dimensions included product type tier, end-use industry, form factor, and regional production hub clustering. CAGRs were derived from elasticity-adjusted demand projections and capacity utilization trends. Forecast inputs incorporated EPA industrial emissions standard implementation timelines and ECHA REACH authorization requirement phase-ins.
Caveats apply where propylene feedstock price volatility, logistics disruptions at Shanghai Port, or mechanical recycling yield breakthroughs could materially shift the outlook. Forecasts reflect documented assumptions about regulatory enforcement intensity and OEM platform material substitution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Short Cut Polyester Fiber Market
Synthetic Fibers
Polyester Staple Fiber Market
Synthetic Fibers
Neoprene Fabric Market
Synthetic Fibers
Nylon Fibers Market
Synthetic Fibers
North America High Performance Fibers Market
Synthetic Fibers
Synthetic Textile Fiber Market
Synthetic Fibers
Glass Fiber Yarn Market
Synthetic Fibers
Europe Nanofiber Market
Synthetic Fibers
Performance Fabric Market
Synthetic Fibers
Synthetic Fabric Market
Synthetic Fibers
Polymer Nanofiber Market
Synthetic Fibers
Middle-East and Africa Aramid Fiber Market
Synthetic Fibers
Polyimide Fiber Market
Synthetic Fibers
US Textile Market
Synthetic Fibers
IMO Fiber Market
Synthetic Fibers
Sic Fibers Market