
 North America High Performance Fibers Market | 2026-2036
North America High Performance Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
North America High Performance Fibers Market Insights
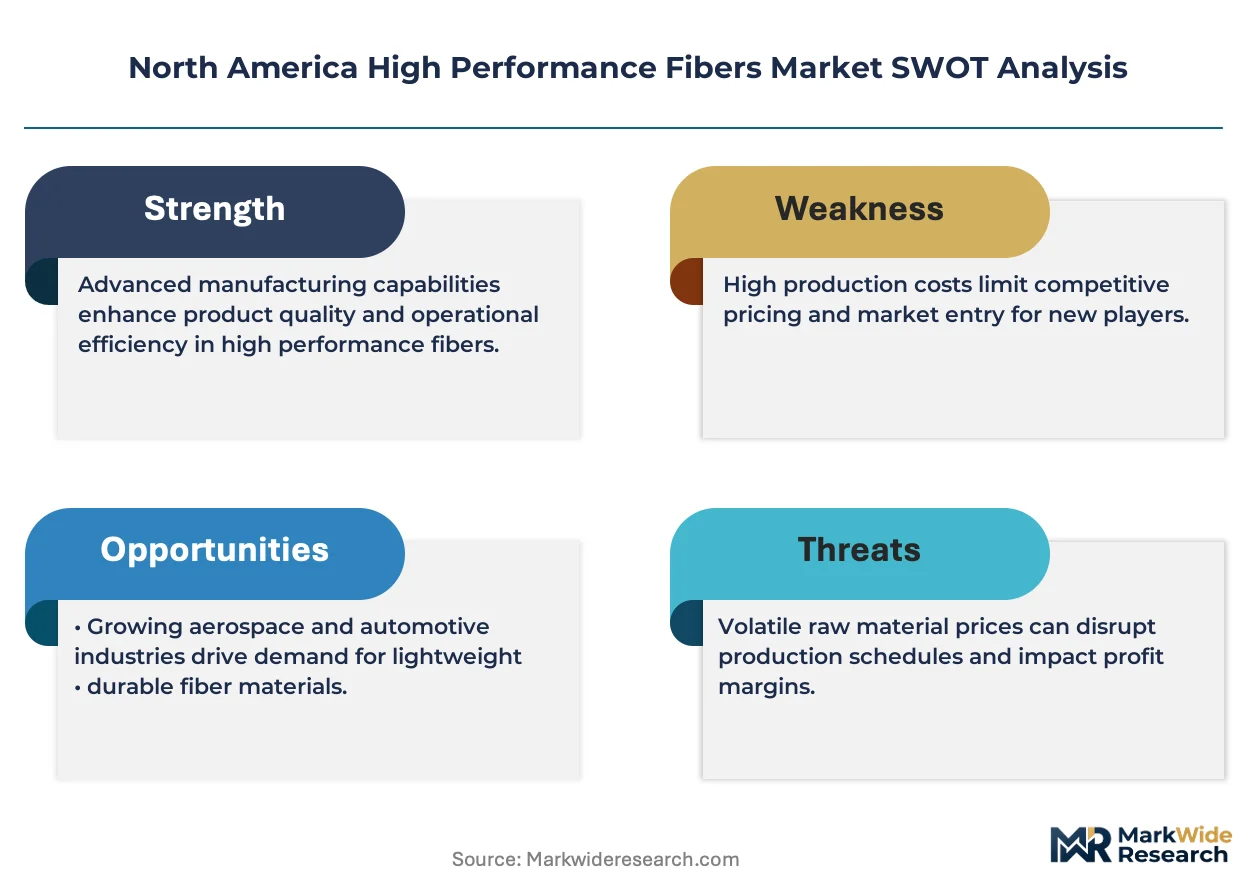
Multi-source precursor procurement is pivoting toward captive supply arrangements as resin and fiber producers seek supply security. DuPont de Nemours Inc anchors aramid fiber production through integrated polymer-to-yarn manufacturing in Virginia and South Carolina. Hexcel Corporation dominates carbon fiber prepreg supply for aerospace tier suppliers, leveraging Salt Lake City and Decatur production assets. Toray Industries Inc competes through its Spartanburg, South Carolina facility, sustaining North American capacity for polyacrylonitrile-based carbon fiber output.
North America High Performance Fibers encompass synthetic filaments engineered to withstand extreme mechanical stress, thermal degradation, and chemical exposure, typically exceeding tenacity thresholds of 15 grams per denier and operating temperatures above 200 degrees Celsius. These fibers serve critical load-bearing, protective, and reinforcement functions across transportation, energy, and industrial infrastructure systems. Carbon fiber leads value generation due to aerospace qualification cycles and automotive lightweighting mandates, while aramid maintains defensive applications in ballistic protection and friction materials. Polyethylene fiber represents the fastest-expanding structural category, displacing conventional materials in marine cables and medical sutures where strength-to-weight ratios determine performance.
The FAA and EPA jointly shape market access through airworthiness certification requirements and emissions controls on precursor chemical production. NHTSA fuel economy standards indirectly accelerate automotive composite adoption by mandating mass reduction in light-duty vehicle platforms. OSHA workplace exposure limits for acrylonitrile and other feedstock chemicals constrain manufacturing scale-up and site selection. Stakeholders must monitor evolving Department of Defense procurement specifications for domestic sourcing requirements that could redirect supply chain investments toward Mexico and Canada.
Market Dynamics
The North America High Performance Fibers Market is undergoing fundamental restructuring as captive precursor supply chains displace multi-source procurement models across carbon fiber and aramid value chains.
Growth Catalysts
- FAA Airworthiness Certification:Accelerated qualification timelines for advanced composite formulations are compressing aerospace fiber adoption cycles in the United States.
- NHTSA Fuel Economy Mandates:Mass reduction requirements for light-duty vehicles are pulling carbon fiber reinforced polymers into automotive structural applications.
- Southeastern Manufacturing Clustering:Co-location of automotive and defense OEMs near precursor supply infrastructure in South Carolina and Virginia is reducing logistics friction.
Market Restraints
- Acrylonitrile Feedstock Concentration:Reliance on petroleum-derived precursor chemicals exposes carbon fiber producers to petrochemical price volatility.
- OSHA Workplace Exposure Limits:Stringent acrylonitrile handling restrictions constrain manufacturing scale-up and site selection flexibility.
- Steel and Aluminum Substitution:Conventional metals retain cost advantages in non-critical structural applications, limiting fiber penetration in price-sensitive segments.
Strategic Opportunities
- Mexico Defense Supply Chain Reconfiguration:Department of Defense domestic sourcing requirements are redirecting precursor investments toward Mexican manufacturing zones.
- Polyethylene Fiber Medical Applications:Ultra-high molecular weight polyethylene is displacing conventional suture materials where strength-to-weight ratios determine surgical outcomes.
- Canada Energy Infrastructure:Carbon fiber reinforcement demand for pipeline rehabilitation and offshore platforms represents underpenetrated territory.
Industry Challenges
- Specialized Polymer Chemistry Talent:Shortages of acrylonitrile polymerization and carbonization process engineers constrain production ramp rates.
- Aerospace Qualification Timelines:FAA certification cycles for new fiber formulations extend 18-36 months, delaying revenue realization for novel products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America High Performance Fibers Market |
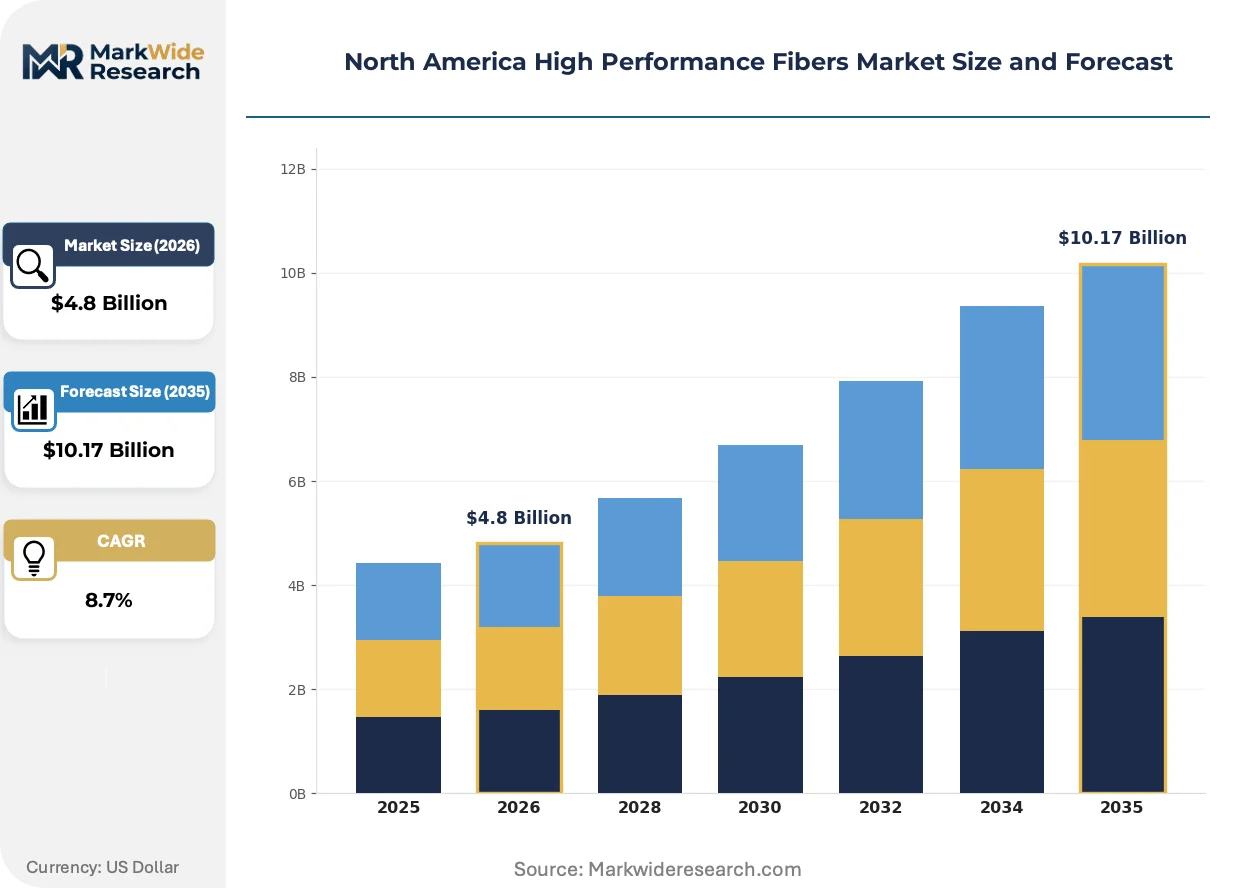
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aramid, Carbon, Glass, Polyethylene End User: Aerospace, Automotive, Construction, Healthcare Application: Composite Materials, Protective Clothing, Filtration, Cables Technology: Spinning, Weaving, Coating, Extrusion |
| Companies Covered | Hexcel Corporation, Toray Industries Inc, DuPont de Nemours Inc, Teijin Ltd, SGL Carbon, Honeywell International Inc, Owens Corning, Solvay, W. L. Gore & Associates, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America High Performance Fibers Market Trends and Innovations
Electrification of transportation platforms is fundamentally altering fiber specification requirements across North American supply chains. Material qualification protocols are compressing as end-users demand faster validation cycles.
Recycled carbon fiber reclamation is electrifying secondary material markets across the region. Automotive tier suppliers in Michigan and Ohio are integrating reclaimed fiber fractions into non-structural components at accelerating rates. This technology is electrifying cost structures for interior and underbody applications previously reserved for virgin material.
EPA emissions controls on acrylonitrile production are tightening precursor chemical manufacturing standards. Facilities in Texas and Louisiana face retrofitted scrubber requirements that add capital intensity to carbon fiber feedstock operations. Polyacrylonitrile-based fiber categories bear the highest compliance burden, pushing producers toward alternative precursor research.
Specification-driven procurement is consolidating buyer power among aerospace OEMs and Tier 1 automotive suppliers. Long-term offtake agreements with volume commitments are replacing spot market purchases for carbon fiber prepreg. This shift concentrates most visibly in Boeing and Airbus supply chains, where qualification status trumps price in supplier selection.
North America High Performance Fibers Market Segmentation
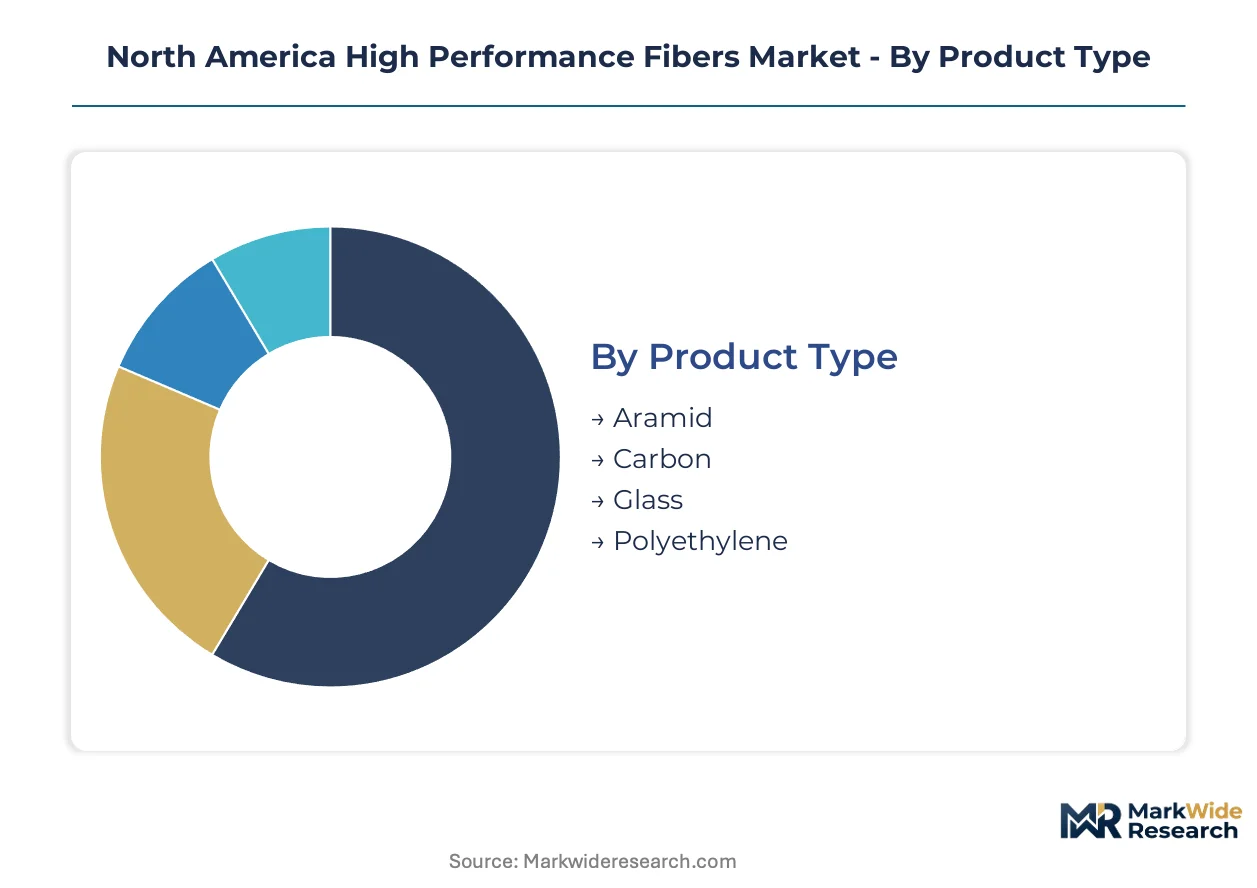
Segmentation in North American high performance fibers reveals how material specifications, regulatory requirements, and end-use performance thresholds fragment demand across distinct procurement channels. Each axis—product chemistry, customer vertical, functional application, and manufacturing process—carries unique qualification barriers and margin structures.
Product Type:
Material chemistry defines thermal tolerance, tensile strength, and cost position across defense, aerospace, and industrial procurement specifications.
- Carbon:Polyacrylonitrile-based filaments deliver the highest stiffness-to-weight ratios in commercial fiber production. Boeing and Airbus supply chains in Washington State and South Carolina specify carbon prepreg for primary aircraft structures, with FAA qualification cycles compressing from 36 to 18 months for qualified formulations.
- Aramid:Aromatic polyamide chains resist thermal degradation above 400 degrees Celsius while maintaining flexibility. DuPont's Richmond, Virginia and Charleston, South Carolina facilities supply ballistic protection contracts for the Department of Defense and law enforcement agencies where fragment resistance standards mandate aramid composites.
- Glass:Silica-based fibers offer cost-effective reinforcement for construction and marine applications where modulus requirements permit heavier composite sections.
- Polyethylene:Ultra-high molecular weight filaments achieve strength-to-weight ratios exceeding aramid at lower density, displacing conventional materials in medical sutures and marine mooring lines.
Carbon leads on scale; polyethylene leads on momentum.
End User:
Customer procurement power concentrates among specification-setting OEMs with captive qualification protocols.
- Aerospace:Tier 1 suppliers and airframers dominate carbon fiber offtake through multi-year volume commitments. Boeing's Everett and Charleston facilities anchor North American demand for qualified prepreg materials.
- Automotive:NHTSA Corporate Average Fuel Economy mandates pull carbon fiber into structural battery enclosures and body-in-white components for electric vehicle platforms. Michigan and Ohio assembly plants specify recycled fiber fractions for non-structural interior panels.
- Construction:Infrastructure rehabilitation projects in Texas and California specify carbon fiber reinforced polymer wraps for seismic retrofit of concrete columns and bridge decks.
- Healthcare:Surgical device manufacturers in Minnesota and Massachusetts specify ultra-high molecular weight polyethylene for orthopedic sutures and cardiovascular implants where biocompatibility and tensile strength determine clinical outcomes.
Aerospace commands pricing power; automotive commands volume expansion.
Application:
Functional use cases separate structural load-bearing from protective and filtration specifications.
- Composite Materials:Fiber-reinforced polymers integrate resin matrices for primary and secondary structural applications. Aerospace tier suppliers in Kansas and Connecticut mold carbon-epoxy prepreg into flight control surfaces and fuselage sections.
- Protective Clothing:Aramid and polyethylene fabrics meet National Institute of Justice ballistic resistance standards for law enforcement and military personnel. South Carolina textile converters laminate multi-ply aramid panels for vest manufacturers.
- Filtration:High-temperature resistant fibers separate particulates in industrial exhaust streams and liquid filtration systems.
- Cables:Synthetic fiber ropes and tethers replace steel wire in offshore mooring and deep-sea lifting operations where corrosion resistance and weight reduction improve vessel economics.
Composite materials anchor revenue; cables are climbing the fastest.
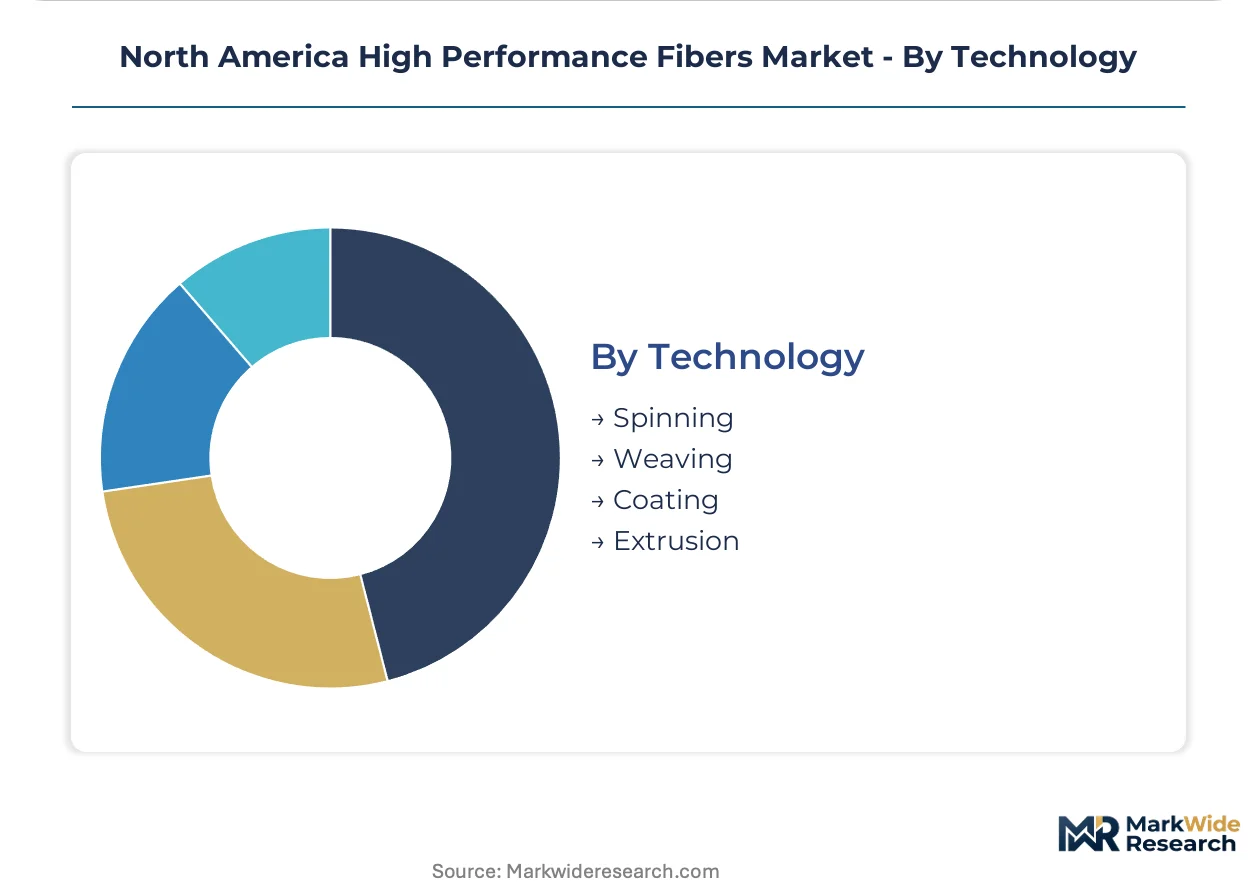
Technology:
Manufacturing process selection determines capital intensity, throughput rates, and fiber property profiles.
- Spinning:Wet and dry-jet spinning extrudes polymer solutions into precursor filaments for carbonization or coagulation into aramid yarn. Toray's Spartanburg facility employs proprietary spinning chemistry for polyacrylonitrile precursor production.
- Weaving:Multi-axial and 3D weaving architectures orient fibers for biaxial and through-thickness load distribution in composite preforms.
- Coating:Sizing chemistry and surface treatments optimize fiber-matrix adhesion in subsequent composite processing steps.
- Extrusion:Melt and gel-spinning processes produce ultra-high molecular weight polyethylene fibers with extended chain crystallinity for maximum tensile properties.
Spinning commands the steepest expansion trajectory; coating maintains margin stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The southeastern United States manufacturing corridor anchors North American high performance fiber demand, with automotive and defense OEMs clustering near precursor supply infrastructure in South Carolina and Virginia.
United States
Boeing's Charleston and Everett facilities drive aerospace carbon fiber offtake through multi-year prepreg contracts. FAA airworthiness certification timelines for advanced composite formulations have compressed from 36 to 18 months, accelerating qualification cycles. The South Carolina Upstate region concentrates Toray Industries' Spartanburg polyacrylonitrile precursor production alongside BMW and Volvo automotive assembly plants.
Canada
Energy infrastructure rehabilitation projects in Alberta and British Columbia specify carbon fiber reinforced polymer wraps for pipeline seismic retrofit and offshore platform reinforcement. Health Canada environmental assessments for acrylonitrile handling facilities constrain greenfield manufacturing investments. Montreal-area aerospace suppliers serve Bombardier and Airbus A220 production lines with qualified aramid and carbon fiber composites.
Mexico
Department of Defense domestic sourcing requirements are redirecting precursor chemical investments toward Mexican manufacturing zones near the US border. Nuevo León's Monterrey industrial corridor attracts carbon fiber composite fabrication for automotive Tier 1 suppliers serving Texas assembly plants. Mexican federal environmental regulations under SEMARNAT govern acrylonitrile emissions for new carbon fiber feedstock facilities.
Texas
Petrochemical infrastructure along the Gulf Coast supplies acrylonitrile feedstock for carbon fiber precursor production, though EPA emissions controls require retrofitted scrubber systems. Houston-area oilfield services companies specify synthetic fiber ropes for offshore mooring operations where corrosion resistance improves vessel economics. The Texas-Louisiana chemical corridor faces OSHA workplace exposure limit compliance costs for acrylonitrile handling at scale.
Michigan
Automotive OEMs in Detroit and Lansing integrate recycled carbon fiber fractions into non-structural interior panels for electric vehicle platforms. NHTSA Corporate Average Fuel Economy mandates pull carbon fiber reinforced polymers into battery enclosure designs. Michigan-based Tier 1 suppliers mold composite preforms for Ford and General Motors light-duty truck lightweighting programs.
North America High Performance Fibers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue recycled fiber reclamation and medical-grade polyethylene specialization. The vendor base concentrates around three strategic archetypes: integrated polymer-to-fiber manufacturers controlling precursor supply, aerospace-qualified prepreg suppliers with FAA certification status, and diversified chemical conglomerates leveraging materials science portfolios. Dominant competitive moves include backward integration into acrylonitrile precursor production and strategic partnerships with automotive OEMs for recycled fiber offtake agreements.
Within the integrated manufacturing tier, DuPont de Nemours Inc and Hexcel Corporation exemplify divergent scale strategies. DuPont anchors aramid production through Virginia and South Carolina polymer-to-yarn assets. Hexcel represents aerospace-qualified prepreg supply concentration. Toray Industries Inc occupies a position as the primary Japanese-owned carbon fiber producer with North American manufacturing presence.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Toray Industries Inc |
| DuPont de Nemours Inc |
| Teijin Ltd |
| SGL Carbon |
| Honeywell International Inc |
| Owens Corning |
| Solvay |
| W. L. Gore & Associates |
| Others |
Pricing and Supply Chain Analysis
Aerospace Tier 1 suppliers and automotive OEMs with multi-year offtake agreements command contract-based long-term pricing that insulates qualified fiber producers from spot market volatility. This buyer concentration forces pricing stratification across aerospace-qualified, automotive-structural, and industrial-commodity tiers, with FAA certification status and NHTSA compliance timelines determining margin premiums.
Pricing Analysis
Acrylonitrile feedstock volatility passes through to carbon fiber pricing with variable lag periods depending on contract duration. Three-tier pricing structure across aerospace-qualified, automotive-structural, and industrial-commodity levels separates Boeing-Airbus qualified prepreg from Tier 2 automotive applications and construction-grade reinforcement. Pricing pressure stems from recycled carbon fiber reclamation technology compressing mid-tier margins. Automotive OEMs exhibit highest price sensitivity due to steel-aluminum substitution alternatives, while aerospace primes prioritize qualification status over unit cost.
Supply Chain Analysis
Department of Defense domestic sourcing requirements are redirecting precursor chemical investments toward Mexican manufacturing zones near the US border. United States, Canada, and Mexico constitute the geographic supply triangle, with acrylonitrile feedstock drawing from Texas-Louisiana petrochemical infrastructure and carbonization capacity concentrating in South Carolina and Virginia. Single-source vulnerability runs through polyacrylonitrile precursor supply, where Toray's Spartanburg facility and Hexcel's Decatur assets anchor regional output. Distribution runs through qualified prepreg suppliers to aerospace Tier 1s and direct mill relationships with automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as electrification of transportation platforms pulls carbon fiber into structural battery enclosures and lightweight body-in-white components demanding premium specifications.
For Market Incumbents: To counter recycled carbon fiber reclamation technology compressing mid-tier margins, anchor position through backward integration into acrylonitrile precursor production in Texas-Louisiana chemical corridor. Secure multi-year offtake agreements with automotive OEMs for qualified recycled fiber fractions, leveraging FAA certification status as pricing power lever against commoditization pressure. For New Entrants and Emerging Players: Direct-to-autotive-Tier-2 digital procurement platforms offer route to bypass incumbent qualification barriers. Target Michigan and Ohio electric vehicle battery enclosure manufacturers with non-structural recycled fiber fractions, where NHTSA fuel economy mandates create specification pull without aerospace-grade certification requirements. Pursue medical-grade ultra-high molecular weight polyethylene specialization in Minnesota surgical device cluster. For Investors and Strategic Acquirers: Aerospace-qualified prepreg suppliers with FAA certification status are the most active acquirer category in this space, consolidating backward into precursor production. Five-to-ten year viability hinges on electrification-driven automotive lightweighting sustaining demand growth. Signal to monitor: Department of Defense procurement specification shifts redirecting supply chain investments toward Mexican manufacturing zones, indicating geographic reconfiguration inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylonitrile Precursor | DuPont and Hexcel control Virginia-South Carolina polymer-to-yarn assets against feedstock volatility. |
| Recycled Carbon Fiber Reclamation Scale-Up | Michigan automotive Tier 1s integrate reclaimed fractions into EV interior panels at accelerating rates. |
| Long-term Supply Agreement with Aerospace OEMs | Boeing Charleston and Everett facilities anchor multi-year prepreg contracts with qualified suppliers. |
| Geographic Expansion to Mexican Manufacturing Zones | Nuevo León Monterrey corridor attracts precursor investments under DoD domestic sourcing requirements. |
| Medical-Grade Polyethylene Specialization | Minnesota surgical device manufacturers specify ultra-high molecular weight filaments for orthopedic sutures. |
Research Methodology
Bottom-up aerospace and automotive demand modeling reconciled against top-down carbon fiber and aramid capacity tracking forms the analytical core. Primary interviews with plant managers at precursor production facilities, procurement leads at Boeing and Airbus Tier 1 suppliers, and technical R&D directors at composite fabricators combined with secondary validation from FAA airworthiness certification databases, NHTSA fuel economy compliance filings, and SEC 10-K disclosures from DuPont, Hexcel, and Toray. Triangulation across these sources yields supply-demand balance assessments.
Historical trendline analysis of carbon fiber adoption cycles in commercial aviation and automotive lightweighting programs informs projection parameters. Segmentation dimensions span material chemistry, end-use vertical, functional application, and manufacturing process technology, with CAGRs derived from elasticity modeling against NHTSA mandate stringency and FAA certification timeline compression. Forecast inputs include electric vehicle platform rollout schedules and Department of Defense procurement specification evolution.
The model assumes a particular technology adoption path; alternative pathways for recycled carbon fiber reclamation scale-up would alter the outlook. Forecasts reflect assumptions regarding acrylonitrile feedstock price stability, OSHA workplace exposure limit enforcement intensity, and aerospace qualification timeline compression sustainability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Textile Fibers Market
Synthetic Fibers
Nylon Fibers Market
Synthetic Fibers
Fiber Blends Market
Synthetic Fibers
Designer Fiber Market
Synthetic Fibers
Global Acrylic Fibers Market
Synthetic Fibers
Short Cut Polyester Fiber Market
Synthetic Fibers
South Korea Textile Market
Synthetic Fibers
Polyethylene Terephthalate (PET) Fiber Market
Synthetic Fibers
Latin America Textile Market
Synthetic Fibers
Nylon Tire Cord Fabrics Market
Synthetic Fibers
Global Synthetic Spider Silk Market
Synthetic Fibers
Polyester Tire Cord Fabrics Market
Synthetic Fibers
Polyester Filament Market
Synthetic Fibers
Carbon Fiber Strands Market
Synthetic Fibers
Polymer Nanofiber Market
Synthetic Fibers
Global High Performance Fibers Market