
 Polyethylene Terephthalate (PET) Fiber Market | 2026-2036
Polyethylene Terephthalate (PET) Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Polyethylene Terephthalate (PET) Fiber Market Insights
Recycled PET flake-to-fiber processing is tilting cost structures toward circular feedstocks. Indorama Ventures Public Company Limited leverages its integrated bottle-to-fiber recycling infrastructure across multiple continents. Toray Industries Inc. anchors its position through high-performance industrial yarn specialization. Tongkun Holding Group dominates filament capacity expansion along China's eastern seaboard.
Polyethylene terephthalate fiber consists of linear thermoplastic polyester polymerized from purified terephthalic acid and ethylene glycol, typically extruded at melt temperatures between 270°C and 290°C to form continuous filaments or cut staple for textile and industrial applications. Staple fiber commands the largest volume share in apparel and carpet manufacturing, while recycled fiber represents the fastest-expanding margin pool as brands enforce post-consumer content minimums. High tenacity fiber sustains premium pricing in automotive safety belt and industrial geotextile applications where tensile strength exceeds 7.5 grams per denier.
China's SAMR enforces GB standards for recycled content labeling in textile products, while the EU Green Deal's textile strategy mandates extended producer responsibility schemes across European member states. The US EPA oversees industrial emissions compliance at PET polymerization facilities under Clean Air Act provisions. Stakeholders must monitor how diverging recycled content certification schemes between jurisdictions reshape raw material sourcing decisions and capital allocation across fiber production networks.
Market Dynamics
Recycled flake-to-fiber processing infrastructure is consolidating feedstock access around integrated bottle recyclers, compressing merchant resin availability and tilting cost structures toward circular supply chains. Automotive lightweighting mandates and EU textile sustainability rules are accelerating capital deployment into chemically recycled feedstocks.
Growth Catalysts
- EU Green Deal textile strategy:Extended producer responsibility schemes mandate post-consumer content minimums across European member states, pulling virgin substitution demand toward certified recycled fiber.
- Automotive interior lightweighting:Tier-1 suppliers expand PET staple adoption in non-woven carpet backings and acoustic insulation to meet fleet emission targets.
- Zhejiang-Jiangsu manufacturing density:China's eastern seaboard clusters achieve 15-20% logistics cost advantages through shared utilities and captive monomer supply.
Market Restraints
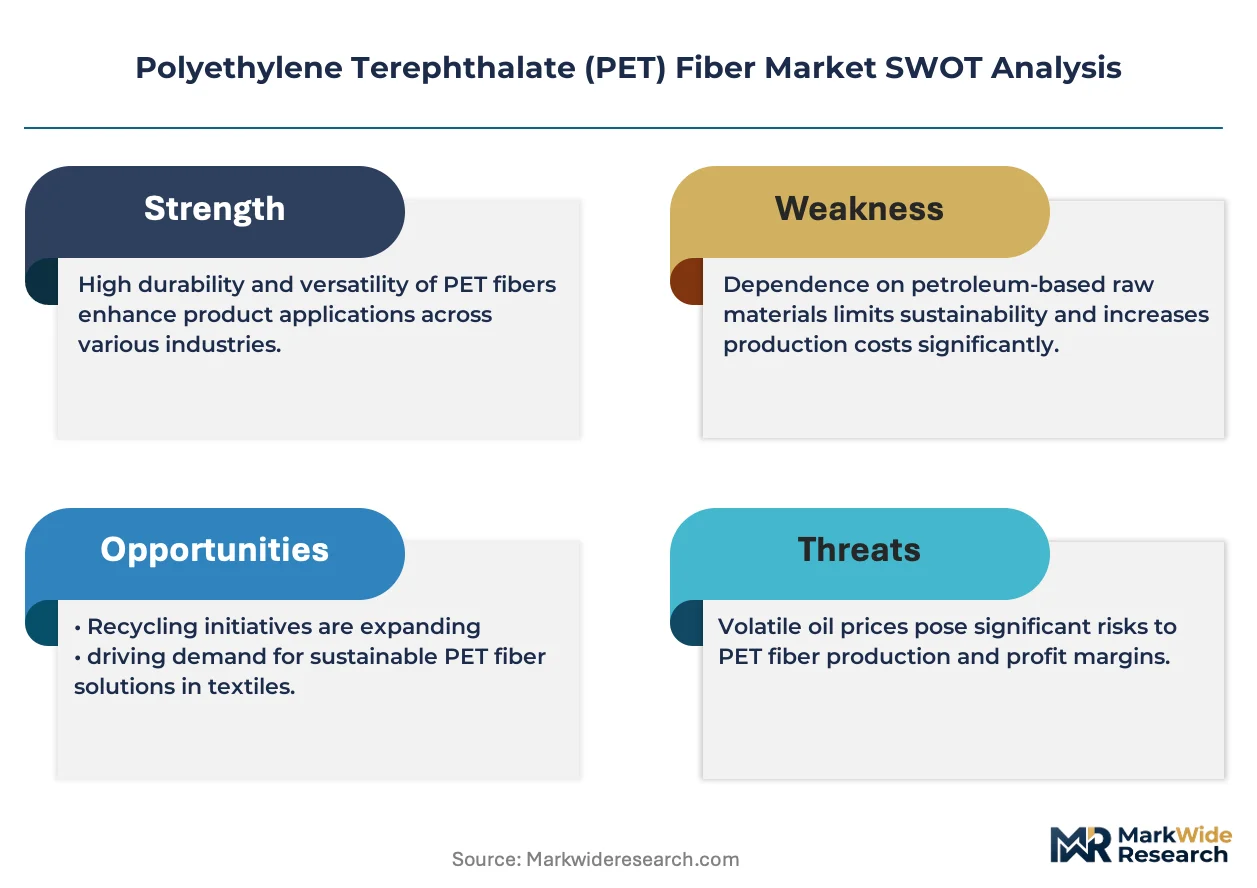
- PTA-MEG price volatility:Purified terephthalic acid and ethylene glycol feedstock costs swing with naphtha-cracker margins, compressing filament producer spreads during energy price spikes.
- Recycled flake supply concentration:Post-consumer bottle collection networks concentrate in OECD municipal systems, creating feedstock access asymmetries for non-integrated fiber producers.
- Melt viscosity degradation:Mechanical recycling limits reheat cycles to 3-4 passes before polymer chain scission degrades tensile performance in high-tenacity applications.
Strategic Opportunities
- India technical textile expansion:The country's PLI scheme for man-made fiber and technical textiles offers 5-10% capex subsidies for recycled-content capacity additions.
- Chemical recycling scale-up:Glycolysis and methanolysis routes enable infinite-loop PET recovery from colored and contaminated feedstocks currently rejected by mechanical processors.
- Digital textile printing compatibility:Disperse-dye receptive PET microfiber grades capture share in on-demand apparel production, reducing water intensity versus conventional wet processing.
Industry Challenges
- Recycled content certification lag:Diverging GRS, RCS, and EU PEFCR schemes create audit multiplicity, extending supplier qualification timelines by 6-12 months.
- Polymerization energy intensity:Solid-state polymerization to high-IV chip for industrial yarn requires 180-220 kWh per ton, exposing margins to carbon border adjustment mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyethylene Terephthalate (PET) Fiber Market |
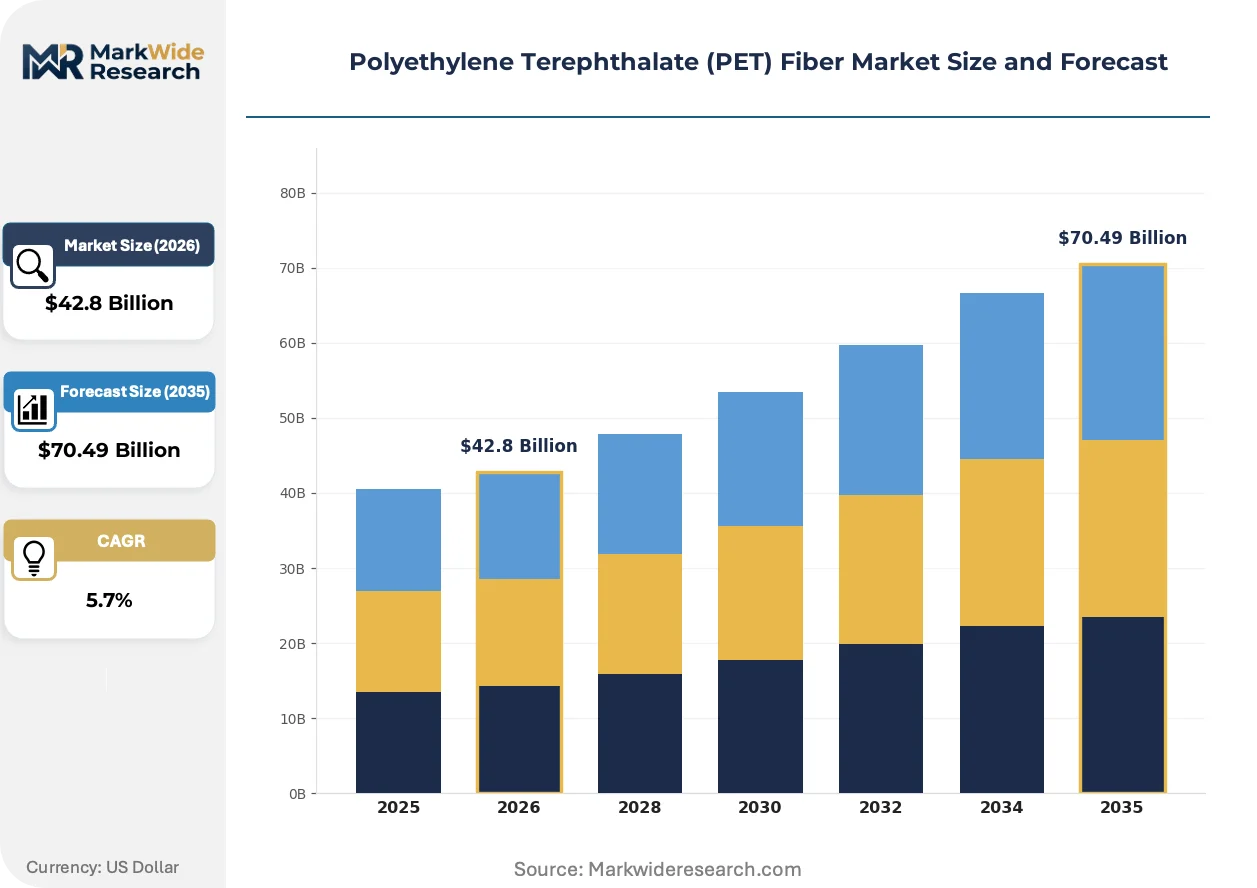
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $70.49 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filament, Staple Fiber, High Tenacity Fiber, Recycled Fiber Application: Textiles, Automotive, Industrial, Packaging End User: Apparel Manufacturers, Carpet Producers, Automotive Suppliers, Packaging Companies Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Reliance Industries Limited, Indorama Ventures Public Company Limited, Toray Industries Inc., Alpek S.A.B. de C.V., China Petrochemical Corporation, Sinopec Yizheng Chemical Fiber Limited Liability Company, Tongkun Holding Group, Zhejiang Hengyi Group Co., Ltd., Nan Ya Plastics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyethylene Terephthalate (PET) Fiber Market Trends and Innovations
Digital thread tracking and blockchain-enabled provenance systems are penetrating fiber supply chains, compressing verification costs and enabling mass-balance accounting for chemically recycled content. Three developments merit attention.
Artificial intelligence-driven defect detection is virtualizing quality control across melt-spinning operations. Machine vision systems identify filament breaks and denier variation at 2,000+ meters per minute. Major filament producers in China and Germany deploy these systems to reduce off-grade fiber by 40-60 basis points, compressing working capital tied to reprocessing inventory.
REACH restrictions on microplastic shedding are tightening test protocols for synthetic textiles sold in European markets. The European Chemicals Agency's 2023 restriction proposal targets release rates from washing machines, forcing fiber producers to modify cross-section geometries and surface coatings. Apparel brands with EU exposure accelerate sourcing of low-shedding trilobal and hollow-filament constructions.
Brand-led circular take-back programs are fragmenting traditional distributor relationships. Patagonia, H&M, and Decathlon operate direct collection networks that bypass wholesale channels, sourcing post-consumer feedstock through owned reverse logistics. This channel compression concentrates bargaining power with integrated recyclers capable of flake-to-fiber vertical coordination.
Polyethylene Terephthalate (PET) Fiber Market Segmentation
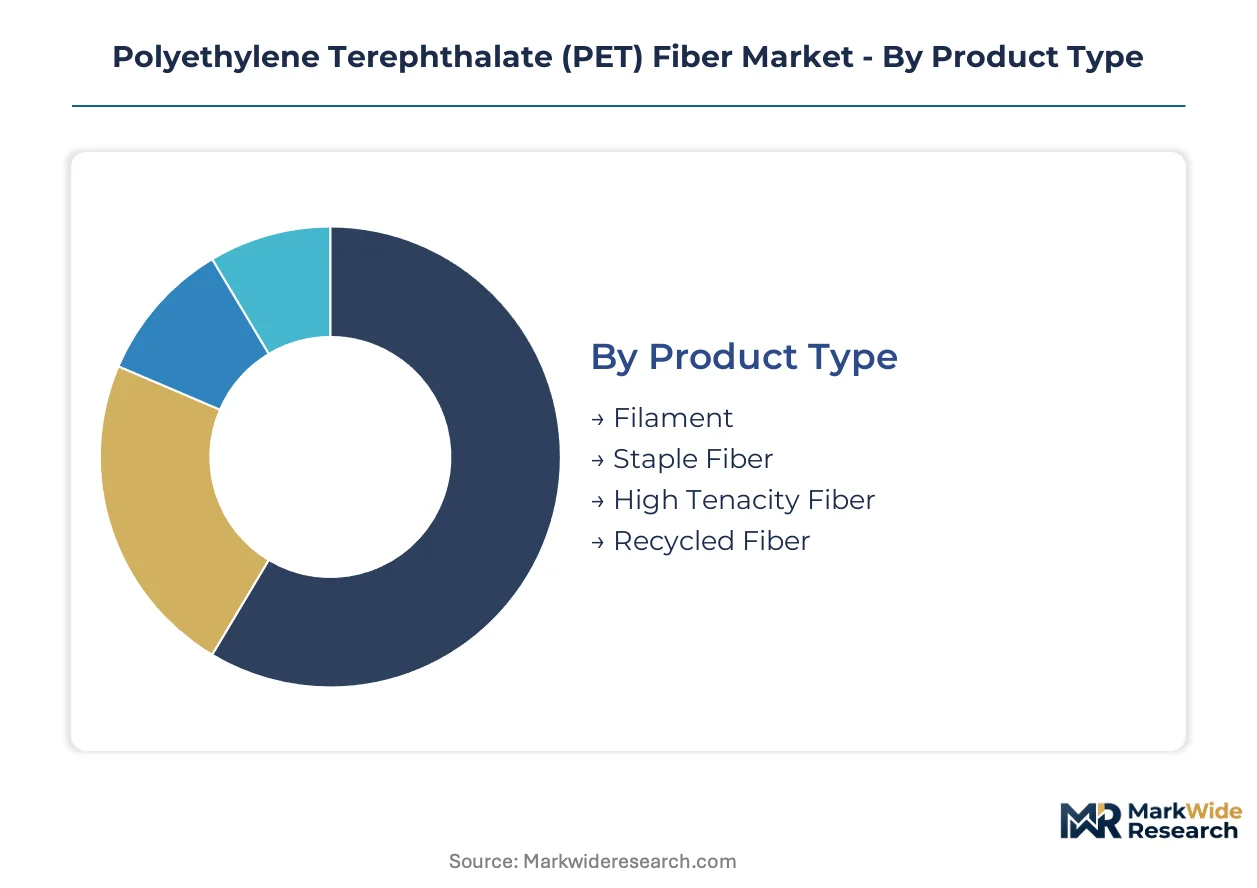
PET fiber segmentation reflects divergent technical specifications and circularity requirements across end-use verticals. Manufacturers configure melt-spinning parameters and polymerization routes specifically for each product tier, creating distinct margin pools and capital intensity profiles.
Product Type:
Mature staple formats dominate commodity textile volumes while emerging chemically recycled grades capture sustainability premiums.
- Filament:Continuous extruded strands spun at deniers ranging from 50 to 300, primarily consumed in China and India for warp-knitted apparel fabrics. Zhejiang province filament producers leverage shared monomer pipelines to compress conversion costs below regional competitors.
- Staple Fiber:Cut-length discontinuous filaments, typically 38-51mm for cotton-blend spinning and 64-102mm for wool-type applications. Carpet backings and non-woven geotextiles in the US Midwest absorb the largest volume blocks, though mechanical recycling limits reheat cycles before tensile degradation.
- High Tenacity Fiber:Solid-state polymerized to intrinsic viscosity above 0.9 dL/g for safety belts and tire cord. Automotive tier-1 suppliers in Germany and Japan specify tenacity exceeding 7.5 g/d for occupant restraint systems.
- Recycled Fiber:Processed from post-consumer bottle flake through mechanical or chemical depolymerization routes. EU Green Deal mandates are pulling brand procurement toward certified circular feedstocks with mass-balance traceability.
Staple fiber retains volume leadership; recycled fiber holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity textile consumption from specification-driven industrial and automotive grades.
- Textiles:Woven and knitted fabrics for apparel and home furnishings, representing the baseline consumption tier. Bangladesh and Vietnam garment exporters concentrate demand for standard-denier staple suitable for fast-fashion production cycles.
- Automotive:Lightweight interior components including seat fabrics, carpet backings, and acoustic insulation panels. Tier-1 suppliers in Stuttgart and Detroit expand PET adoption to meet fleet emission targets through mass reduction.
- Industrial:Geotextiles, rope and cordage, and filtration media requiring UV stabilization and creep resistance. Infrastructure projects in India and Brazil drive technical specifications for high-tenacity industrial yarn.
- Packaging:Strapping bands and non-woven protective wraps, typically utilizing lower-IV recycled chip. E-commerce fulfillment growth in China's Yangtze River Delta accelerates demand for woven polypropylene-PET hybrid strapping.
Textile applications command the widest demand base; automotive applications generate the highest per-kilogram value realization.
End User:
Customer type determines specification stringency and contract duration, with automotive suppliers imposing the most rigorous quality protocols.
- Apparel Manufacturers:Fast-fashion and athleisure producers in Southeast Asia and Turkey, sourcing standard staple and micro-denier filament for moisture-wicking constructions. Digital textile printing compatibility increasingly influences fiber cross-section selection.
- Carpet Producers:Residential and commercial broadloom manufacturers in Georgia and Belgium, consuming bulked continuous filament for face yarn and recycled staple for primary and secondary backings. REACH microplastic restrictions are forcing low-shedding fiber geometries.
- Automotive Suppliers:Tier-1 seating and interior trim specialists with IATF-certified quality systems. Safety belt webbing producers in Japan and Germany require lot-traceable high-tenacity yarn with documented polymerization parameters.
- Packaging Companies:Industrial strapping and protective packaging converters, often purchasing off-spec or wide-specification fiber at discounted indices. Reverse logistics networks for post-consumer collection are compressing traditional distributor relationships.
Apparel manufacturers absorb the largest tonnage; automotive suppliers enforce the tightest specification tolerances.
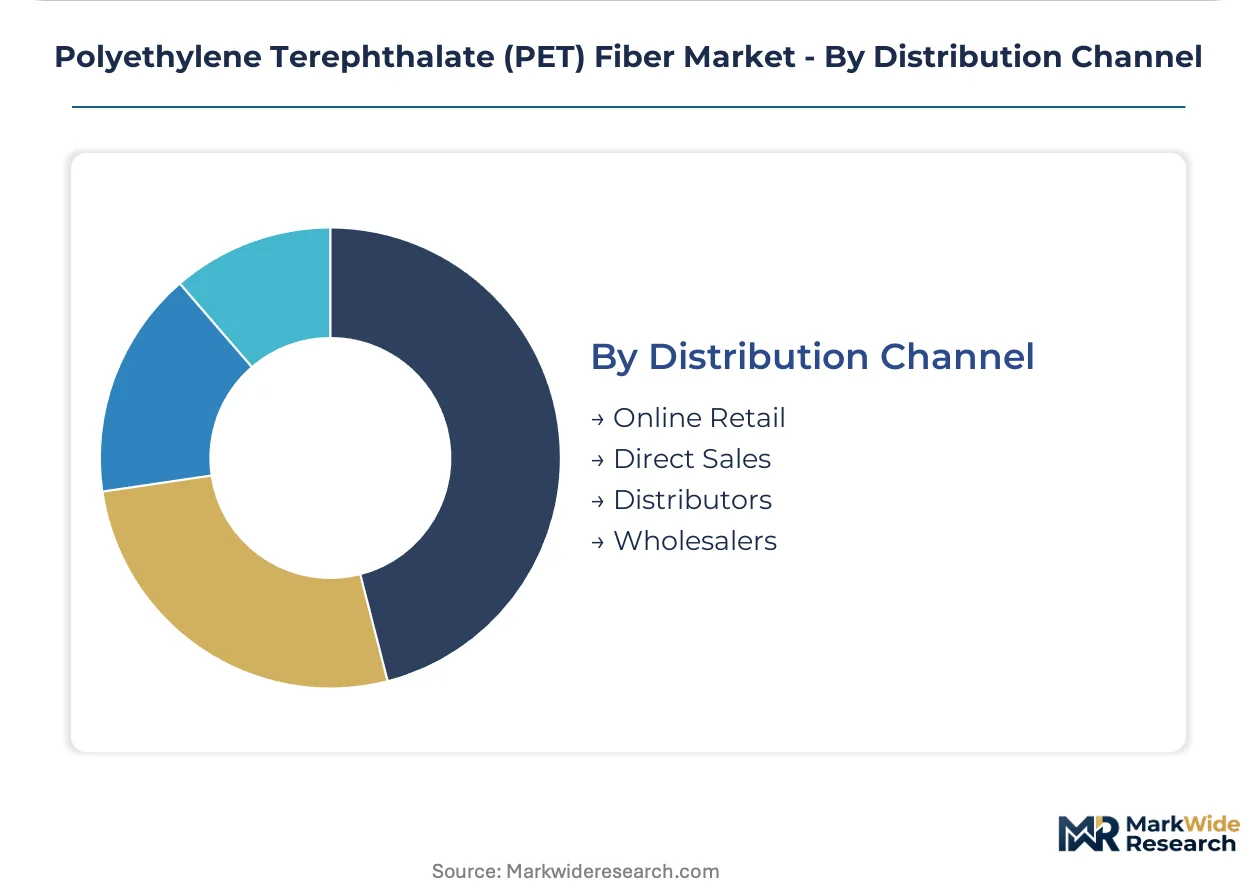
Distribution Channel:
Supply concentration favors direct mill relationships for volume accounts while fragmented wholesale channels serve smaller converters.
- Online Retail:Emerging channel for specialty and sample-quantity filament sales, particularly for small-batch textile designers and prototyping shops. Alibaba and IndiaMART platforms aggregate spot purchases from Zhejiang and Surat producers.
- Direct Sales:Long-term offtake agreements between integrated fiber producers and major textile mills or automotive tier-1s. Indorama Ventures and Tongkun Holding Group deploy dedicated account teams for top-20 global customers.
- Distributors:Regional stockists holding inventory for mid-size converters with variable demand patterns. European distributors face margin compression from brand-led circular take-back programs that bypass wholesale channels.
- Wholesalers:Commodity traders handling wide-specification and off-grade volumes for secondary applications. Price volatility in PTA-MEG feedstocks forces wholesalers to maintain shorter position durations.
Direct sales capture the highest volume concentration; online retail exhibits the fastest channel growth rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive tier-1 suppliers in Germany and Japan enforce the tightest specification protocols, while apparel manufacturers in Bangladesh and Vietnam absorb the highest fiber tonnage. Chemical recyclers in the United States and Netherlands are scaling glycolysis capacity to bypass mechanical recycling limitations. Regulatory divergence between the EU Green Deal and China's GB standards is fragmenting certification schemes.
China
Zhejiang and Jiangsu provinces host the densest PET fiber manufacturing clusters globally, with shared monomer pipelines compressing logistics costs by 15-20%. SAMR enforces GB standards for recycled content labeling in textile products. Tongkun Holding Group dominates filament capacity expansion along the eastern seaboard through captive PTA supply.
Germany
Automotive interior lightweighting mandates from Stuttgart-based tier-1 suppliers accelerate PET staple adoption in acoustic insulation and carpet backings. The EU Green Deal's extended producer responsibility schemes mandate post-consumer content minimums across member states. KBA certification requirements for safety belt webbing sustain premium pricing for high-tenacity industrial yarn.
United States
Carpet producers in Georgia consume bulked continuous filament for residential and commercial broadloom face yarn. The EPA oversees industrial emissions compliance at PET polymerization facilities under Clean Air Act provisions. Mechanical recyclers in the Southeast face feedstock access asymmetries as brand-led take-back programs concentrate post-consumer bottles with integrated processors.
India
Technical textile demand from infrastructure projects in Maharashtra and Gujarat drives specifications for UV-stabilized geotextiles. The PLI scheme for man-made fiber offers 5-10% capex subsidies for recycled-content capacity additions. Surat-based filament producers leverage IndiaMART platforms to aggregate spot purchases from smaller textile designers.
Japan
Safety belt webbing producers specify lot-traceable high-tenacity yarn with documented polymerization parameters exceeding 7.5 grams per denier. METI guidelines encourage circular material flows in automotive supply chains. Toray Industries anchors industrial yarn specialization through solid-state polymerization to intrinsic viscosity above 0.9 dL/g.
Polyethylene Terephthalate (PET) Fiber Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where integrated bottle-to-fiber recyclers command feedstock access advantages. The vendor base separates into three archetypes: integrated petrochemical conglomerates with captive monomer supply, specialized high-performance yarn producers, and regional filament specialists leveraging manufacturing density. Consolidation pressures concentrate around flake-to-fiber infrastructure as merchant resin availability tightens. Competitive moves emphasize backward integration into post-consumer collection networks and geographic expansion into technical textile growth markets.
Within the integrated recycler archetype, Indorama Ventures Public Company Limited exemplifies multi-continental bottle-to-fiber coordination. Toray Industries Inc. occupies a position in high-performance industrial yarn specialization. Tongkun Holding Group represents scale-driven filament capacity deployment along China's eastern seaboard. These three anchors illustrate how feedstock security and specification tier determine strategic positioning across the value chain.
| Leading Market Players |
|---|
| Reliance Industries Limited |
| Indorama Ventures Public Company Limited |
| Toray Industries Inc. |
| Alpek S.A.B. de C.V. |
| China Petrochemical Corporation |
| Sinopec Yizheng Chemical Fiber Limited Liability Company |
| Tongkun Holding Group |
| Zhejiang Hengyi Group Co., Ltd. |
| Nan Ya Plastics Corporation |
| Others |
Pricing and Supply Chain Analysis
Zhejiang and Jiangsu province manufacturing clusters concentrate PTA-MEG feedstock access along China's eastern seaboard, compressing conversion costs for captive producers while fragmenting margin pools for merchant-dependent spinners downstream. This geographic asymmetry funnels pricing power toward integrated conglomerates with in-house monomer supply, forcing non-integrated filament producers to absorb volatility through shorter contract durations and wider specification tolerance.
Pricing Analysis
Cost-plus contracts with PTA-MEG indexation dominate filament procurement between Zhejiang producers and Bangladeshi garment exporters, insulating converters from naphtha-cracker margin swings while compressing spinner spreads during energy price spikes. Price differentiation rests on certification grade—GRS-certified recycled fiber commands premiums over standard staple—and volume scale, with annual offtake above 5,000 tons unlocking dedicated production slots. Pricing pressure stems from flake-to-fiber infrastructure consolidation around integrated recyclers, tightening merchant resin availability. Carpet producers in Georgia exhibit highest price sensitivity due to substitute wool-nylon blending options, while automotive tier-1 suppliers in Stuttgart enforce specification premiums with limited elasticity.
Supply Chain Analysis
Export-control regimes on solid-state polymerization equipment from Germany and Japan constrain high-tenacity capacity expansion outside incumbent supply zones, limiting independent entrants from matching Toray Industries' industrial yarn specifications. Geographic supply concentrates in China, India, and Germany, with raw material dependencies on purified terephthalic acid, ethylene glycol, and post-consumer bottle flake. Single-source vulnerability concentrates around OECD municipal collection networks for recycled feedstock, creating access asymmetries for non-integrated fiber producers. Distribution runs through direct mill relationships for volume accounts, with regional distributors serving mid-size converters facing margin compression from brand-led circular take-back programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PET fiber market operates as a defensive-moat industry where regulatory entrenchment around EU Green Deal extended producer responsibility schemes creates durable switching costs for certified supply chain participants.
For Market Incumbents: Entrench feedstock security through backward integration into post-consumer bottle collection networks, mirroring Indorama Ventures' multi-continental flake-to-fiber coordination. Expand chemically recycled capacity ahead of mechanical recycling limitations on reheat cycles, securing mass-balance certification for infinite-loop feedstocks. Defend against emerging glycolysis specialists by locking long-term offtake with automotive tier-1 suppliers under IATF quality protocols. For New Entrants and Emerging Players: India's technical textile expansion under PLI scheme capex subsidies represents the most penetrable entry point for recycled-content capacity additions, with Maharashtra infrastructure projects driving UV-stabilized geotextile specifications. Surat-based filament producers' spot-market exposure through IndiaMART platforms reveals service gaps for small-batch digital textile printing compatibility. Pursue partnership routes with established mechanically recycled flake processors to bypass capital-intensive depolymerization scale-up. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European distributors facing channel compression from Patagonia and H&M direct take-back programs. Five-to-ten-year viability hinges on chemical recycling technology maturation and carbon border adjustment exposure for solid-state polymerization energy intensity. Watch for EU PEFCR scheme harmonization with China's GB standards as inflection indicator for cross-border certification audit rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Post-Consumer Collection | Secures flake feedstock access as brand-led take-back programs concentrate supply with integrated processors. |
| Chemical Recycling Scale-Up | Enables infinite-loop PET recovery from colored feedstocks rejected by mechanical glycolysis routes. |
| High-Tenacity Industrial Yarn Specialization | Captures automotive safety belt premiums requiring KBA-certified tenacity above 7.5 grams per denier. |
| Digital Textile Printing Compatibility Development | Targets on-demand apparel production growth with disperse-dye receptive microfiber grades. |
| EU Green Deal Certification Pre-Positioning | Aligns mass-balance accounting systems ahead of mandatory extended producer responsibility implementation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and ACC industry reports across the polyester value chain. Plant managers at Zhejiang filament facilities, procurement leads at Stuttgart automotive tier-1s, and distribution channel partners in European textile wholesale provided operational validation. Bottom-up capacity modeling triangulated against top-down consumption estimates from carpet backing and automotive interior applications.
Forecast inputs span staple versus filament format splits, recycled content certification tiers, and regional manufacturing density effects across the projection horizon. Segmentation dimensions include product type, end-use application, and customer specification stringency. CAGRs derive from demand elasticity modeling against EU Green Deal mandate timelines and automotive lightweighting fleet targets. Industry-specific inputs incorporate PTA-MEG spread volatility and mechanical recycling reheat cycle degradation curves.
Practitioners should monitor EU-China certification scheme divergence and chemical recycling capacity commissioning for early signals of feedstock access redistribution. Forecasts reflect assumptions around extended producer responsibility implementation pace and flake collection network expansion. Material shifts in carbon border adjustment mechanisms or solid-state polymerization energy cost structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Asia-Pacific Spandex Market
Synthetic Fibers
Polyester Strap for Manual Grade Market
Synthetic Fibers
Para-Aramid Fibers Market
Synthetic Fibers
Global Lyocell Fibers Market
Synthetic Fibers
Polyester Staple Fiber Market
Synthetic Fibers
US Textile Market
Synthetic Fibers
Aramid Fiber Market
Synthetic Fibers
Long Fiber Thermoplastics Market
Synthetic Fibers
Melt Spun Fibers Market
Synthetic Fibers
Microfiber Leather Market
Synthetic Fibers
Fiber Blends Market
Synthetic Fibers
Staple Fibers Market
Synthetic Fibers
Latin America Textile Market
Synthetic Fibers
Global Acrylic Fibers Market
Synthetic Fibers
Clothing Fibers Market
Synthetic Fibers
Extruded PLA Fiber Market