
 Modacrylic Fiber Market | 2026-2036
Modacrylic Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Modacrylic Fiber Market Intelligence
EN 11612 certification for protective clothing against heat and flame is bifurcating the competitive landscape into qualified and non-qualified suppliers. Kaneka Corporation leverages its proprietary polymerization technology to sustain leadership in high-tenacity flame-retardant grades. Teijin Limited anchors its position through backward integration into acrylonitrile precursors and captive control over polymer supply. Aksa Akrilik Kimya Sanayii competes on manufacturing scale at its Yalova complex, while Lenzing AG differentiates via specialty fiber variants for technical textile niches.
Modacrylic fiber is a modified acrylic polymer containing 35-85% acrylonitrile by weight with comonomers such as vinylidene chloride or vinyl bromide to impart inherent flame resistance, produced through wet or dry spinning of polymer solutions into fibrous form. Its primary commercial purpose centers on applications requiring self-extinguishing properties without chemical after-treatments, including protective workwear, high-pile faux fur, and technical insulation. Staple fibers currently occupy the largest volume share across product types due to their compatibility with conventional spinning equipment and broad textile processing flexibility. Flame retardant fabrics command the dominant application position, while specialty fibers for technical end-uses represent the fastest-expanding margin pool as buyers specify higher performance thresholds.
REACH compliance through ECHA governs monomer emissions and restricted substance thresholds for modacrylic fiber sold in Europe, while China's GB standards under SAMR oversight mandate flammability ratings for domestic protective textile applications. The US EPA and OSHA jointly influence industrial fiber specifications through workplace safety rules and chemical handling requirements. Stakeholders must monitor divergence between regional flammability test protocols and polymer composition disclosures as compliance costs increasingly determine market access tiers.
Market Dynamics
REACH compliance through ECHA is bifurcating the modacrylic fiber supplier base into qualified and non-qualified tiers, with certification costs now determining market access across European protective apparel procurement channels.
Growth Catalysts
- EN 11612 certification mandates:European industrial safety regulations now require heat and flame protective clothing in metalworking, welding, and foundry operations, pulling volume toward inherently flame-retardant fibers.
- China's state-led capacity expansion:Domestic textile manufacturing clusters in Jiangsu and Zhejiang provinces continue scaling technical fiber production for export-oriented protective apparel.
- Vinylidene chloride copolymer advances:Modified polymer compositions with enhanced char-forming properties are extending application range into aircraft interior textiles and technical insulation without after-treatment chemicals.
Market Restraints
- Acrylonitrile price volatility:Feedstock costs tied to propylene-ammonia chemistry create margin compression for non-integrated spinners lacking captive precursor supply.
- Supply concentration in East Asia:Wet spinning capacity clusters heavily in China and Japan, exposing buyers to logistics disruption and currency fluctuation risks.
- Aramid fiber substitution:Meta-aramid and para-aramid alternatives with higher thermal stability capture premium protective apparel segments above 400°C exposure thresholds.
Strategic Opportunities
- India protective apparel underpenetration:Domestic mining, oil and gas, and construction sectors lack compliance enforcement, creating latent demand as BIS standards tighten.
- Electric vehicle battery insulation:Thermal runaway protection requirements in lithium-ion pack designs are opening technical fiber applications in automotive gaskets and compression pads.
- EU Green Deal circularity mandates:Textile waste directives incentivize fiber-to-fiber recycling infrastructure, favoring modacrylic's thermoplastic recyclability over thermoset alternatives.
Industry Challenges
- Polymerization specialist scarcity:Wet spinning process engineers with vinylidene chloride handling expertise are concentrated at legacy facilities, constraining new plant commissioning.
- EN 11612 test house bottlenecks:Certification timelines stretch 8-14 months as notified bodies face backlog in heat and flame protective clothing conformity assessment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modacrylic Fiber Market |
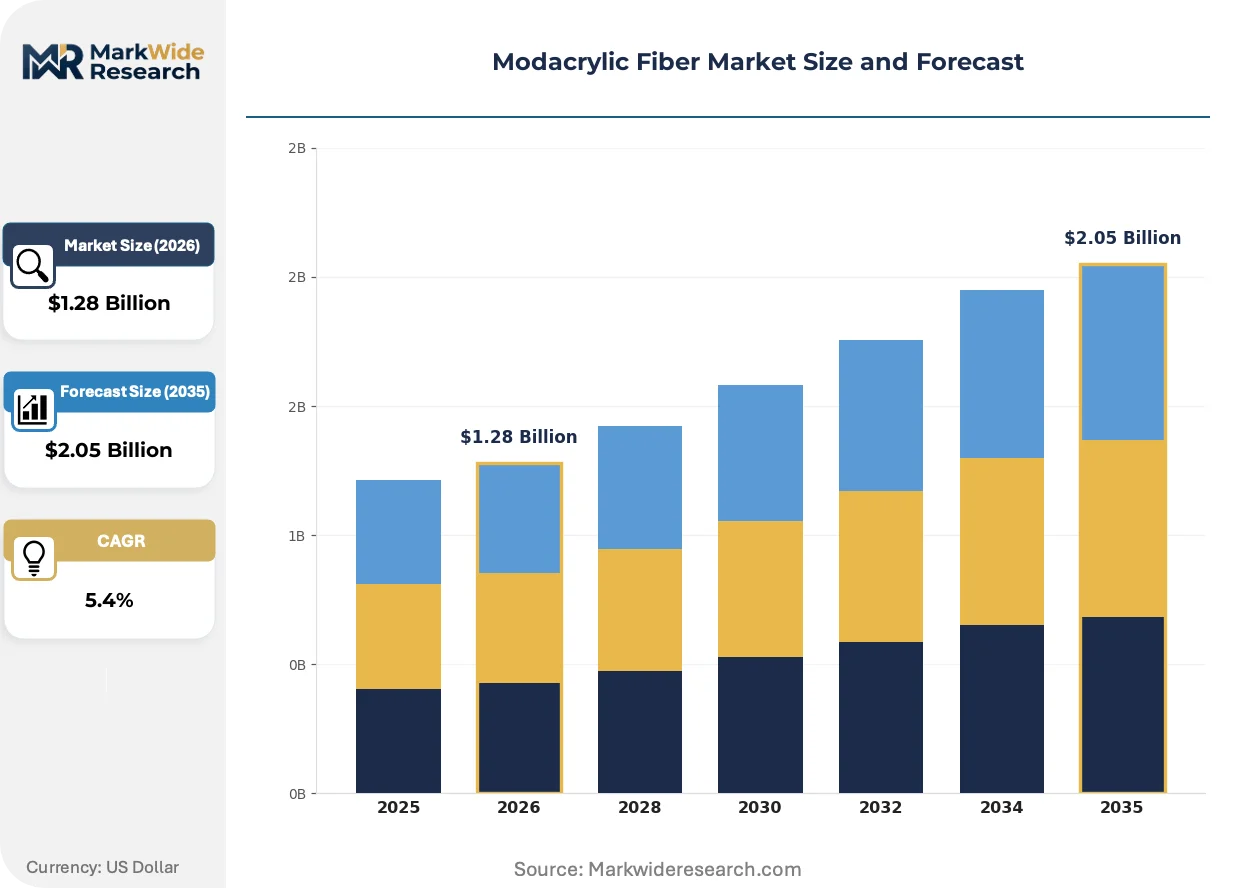
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.05 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blended Fibers, Staple Fibers, Continuous Filament, Specialty Fibers End User: Apparel, Home Textiles, Industrial Applications, Upholstery Application: Flame Retardant Fabrics, Outdoor Gear, Hairpieces, Insulation Materials Distribution Channel: Online Retail, Direct Sales, Specialty Stores, Wholesale |
| Companies Covered | Aksa Akrilik Kimya Sanayii, Teijin Limited, Kaneka Corporation, Lenzing AG, China National Petroleum Corporation, Aditya Birla Management Corporation, Taekwang Industrial, Eastman Chemical Company, Formosa Plastics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modacrylic Fiber Market Strategic Shifts & Innovations
Polymer modification techniques and regulatory test protocol evolution are compressing product development cycles while expanding performance specifications beyond traditional protective apparel boundaries.
Halogen-free phosphorus-nitrogen intumescent systems are displacing vinylidene chloride and vinyl bromide chemistries in next-generation flame-retardant fibers. Automotive seating suppliers and aircraft interior fabricators are piloting these compositions at scale to meet smoke toxicity specifications in FAR 25.853 and equivalent protocols. This displacement is compressing the addressable market for conventional modacrylic grades in transportation applications while opening technical fiber margins for compliant alternatives.
China's GB 8965.1-2020 standard for protective clothing against heat and flame is tightening flammability ratings and thermal shrinkage thresholds for domestic procurement. SAMR enforcement through market surveillance inspections is disqualifying non-compliant imports from Southeast Asian suppliers. Domestic Chinese spinners with in-house testing laboratories are capturing share from exporters facing certification delays.
Specification-driven procurement through certified supplier lists is consolidating buyer power among large industrial laundries and rental workwear providers. These operators now require fiber producers to maintain EN 11612 test reports with specific batch traceability, replacing spot-market purchasing. Germany's technical textile rental sector exhibits this pattern most acutely, with three national providers controlling majority protective apparel volume.
Modacrylic Fiber Market Segmentation
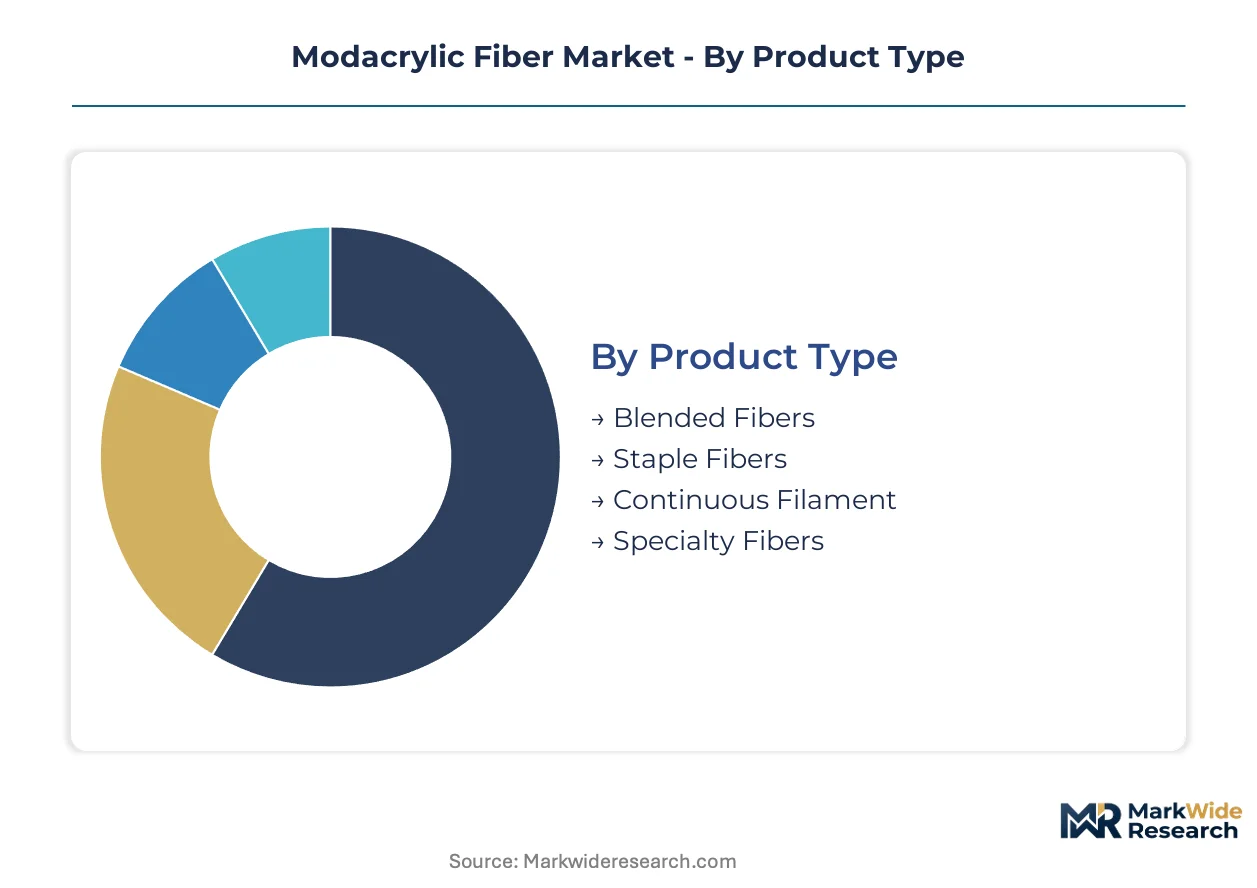
Modacrylic fiber segmentation reveals distinct channel economics across product forms and end-use specifications. Each category carries different margin structures, certification requirements, and buyer concentration patterns that determine competitive positioning.
Product Type:
Channel mix varies sharply by fiber form, with staple fibers flowing through textile distributors while specialty grades move via direct mill relationships.
- Staple Fibers:Short-cut fibers compatible with conventional cotton and wool spinning equipment dominate volume throughput. Jiangsu and Zhejiang textile clusters absorb the majority for protective apparel blending with cotton or aramid. EN 11612 certification requirements now mandate batch traceability from fiber to finished garment.
- Specialty Fibers:Engineered variants with modified vinylidene chloride copolymers for enhanced char formation command premium positioning. Aircraft interior textile suppliers and automotive seating manufacturers specify these grades for FAR 25.853 smoke toxicity compliance without halogenated after-treatments.
- Blended Fibers:Pre-compounded fiber mixtures with cotton, wool, or FR polyester reduce downstream processing steps for industrial laundries.
- Continuous Filament:Unbroken fiber strands serve high-pile faux fur and technical insulation applications requiring uniform denier.
By volume, staple fibers lead. By growth pace, specialty fibers are expanding most quickly.
End User:
Cost tier stratification separates specification-heavy industrial buyers from price-sensitive consumer segments.
- Industrial Applications:Metalworking, welding, and foundry operations mandate inherently flame-retardant protective clothing under EN 11612 and GB 8965.1-2020 standards. Rental workwear providers in Germany and France now require certified supplier lists with polymer batch documentation.
- Apparel:High-pile faux fur for fashion outerwear and costume applications drives consistent demand for lustrous, dye-receptive fiber grades. Chinese domestic brands and European fast fashion retailers specify modacrylic for animal-free alternatives with controlled flammability.
- Home Textiles:Flame-retardant blankets and decorative throws for hospitality and healthcare settings require compliance with regional fire safety codes.
- Upholstery:Contract furniture and public seating applications specify modacrylic pile for durability and cigarette-ignition resistance testing.
Industrial applications generate the highest per-kilogram margins. Apparel delivers the steadiest volume base.
Application:
Geographic concentration of demand pulls volume toward regulatory enforcement zones with active industrial safety inspection regimes.
- Flame Retardant Fabrics:Protective workwear against heat and flame represents the foundational commercial application. European metalworking sectors and Chinese state-owned energy enterprises drive procurement through certified channels with EN 11612 or GB 8965.1-2020 documentation.
- Insulation Materials:Thermal runaway protection in electric vehicle battery packs and aircraft interior insulation are opening technical specifications for char-forming fiber grades. Automotive OEMs in Germany and Japan are qualifying modacrylic for lithium-ion pack compression pads.
- Outdoor Gear:Synthetic fur trim and insulated garments for extreme cold weather applications require moisture-resistant fiber treatments.
- Hairpieces:Wig and hair extension manufacturers value modacrylic for heat-styling tolerance and color retention.
Flame retardant fabrics anchor current revenue. Insulation materials are gaining share fastest as transportation electrification accelerates.
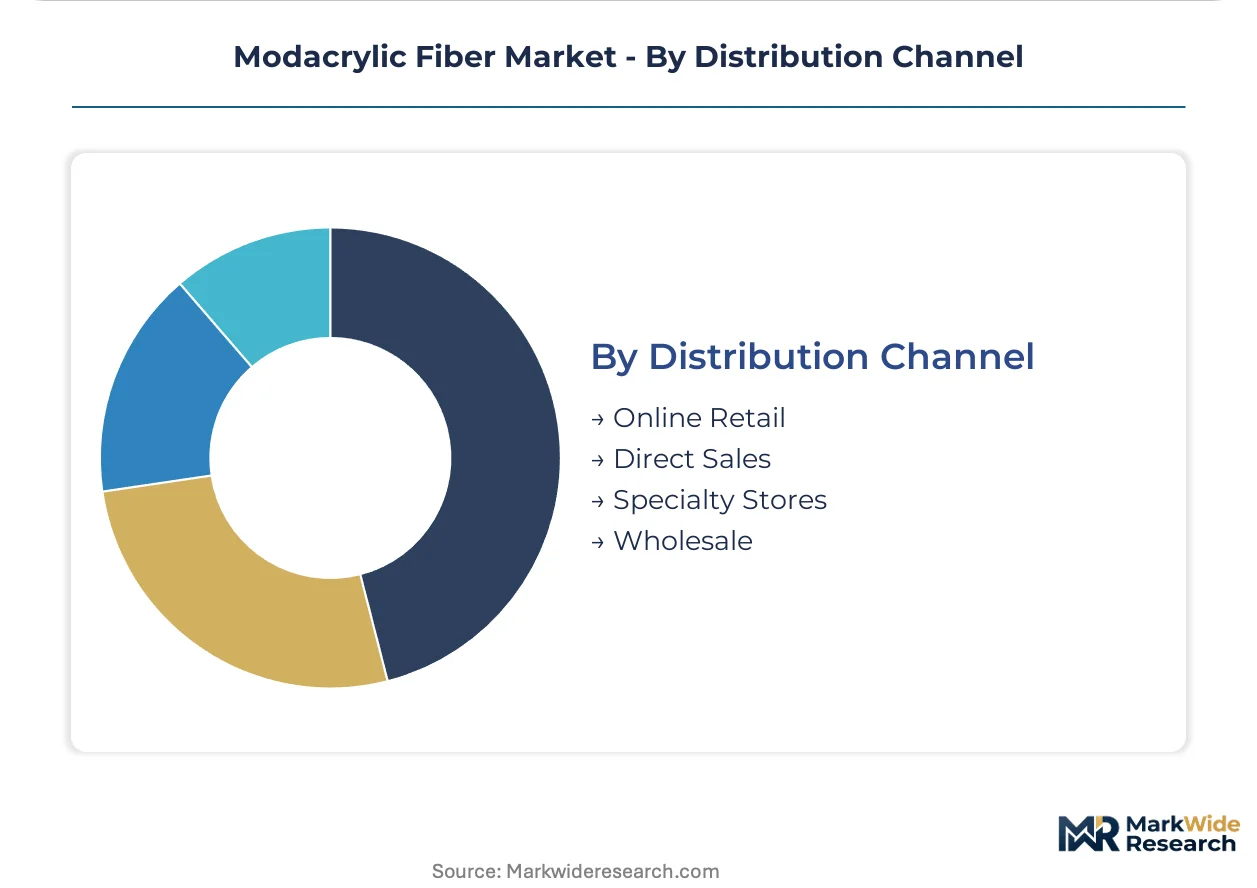
Distribution Channel:
Customer type determines channel selection, with large industrial laundries bypassing intermediaries while fragmented apparel makers rely on distributor networks.
- Direct Sales:Major modacrylic spinners maintain mill-direct relationships with European technical textile rental providers and Chinese state procurement channels. Kaneka and Teijin operate technical service teams for polymer specification and certification support.
- Wholesale:Regional textile distributors in Turkey, Pakistan, and Bangladesh stock staple fiber inventories for mid-scale protective apparel manufacturers lacking direct mill access.
- Specialty Stores:Niche suppliers serving theatrical costume, craft, and hobby segments provide small-lot fiber access with color matching services.
- Online Retail:E-commerce platforms facilitate spot purchases for research institutions, prototype developers, and small garment workshops.
Direct sales capture the highest-value contracts. Wholesale channels handle the greatest transaction frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial laundries and rental workwear providers concentrate procurement in regulatory enforcement zones with active safety inspection regimes. Chinese textile clusters absorb the largest volume share for protective apparel blending. European metalworking sectors drive premium-grade demand through certified supplier mandates.
China
State-owned energy enterprises and Jiangsu-Zhejiang textile clusters pull volume for export-oriented protective apparel. SAMR enforces GB 8965.1-2020 standards through market surveillance inspections that disqualify non-compliant imports. Yancheng and Shaoxing spinning facilities scale technical fiber production for domestic and European end-users.
Germany
Technical textile rental providers control majority protective apparel volume through specification-driven procurement with batch traceability requirements. ECHA REACH compliance governs monomer emissions and restricted substance thresholds for fiber sold in Europe. The Ruhr industrial belt sustains dense metalworking and foundry operations mandating EN 11612-certified workwear.
United States
OSHA workplace safety rules and EPA chemical handling requirements shape industrial fiber specifications for metalworking and welding sectors. The Department of Defense and federal procurement channels specify inherently flame-retardant fibers for uniform applications. Georgia and North Carolina textile manufacturing corridors process staple fibers for protective apparel blending.
Japan
METI industrial standards and aircraft interior textile specifications drive demand for halogen-free flame-retardant grades. Automotive OEMs in Nagoya and Tokyo metropolitan areas qualify modacrylic for lithium-ion battery pack compression pads. Kaneka Corporation's proprietary polymerization technology anchors domestic high-tenacity production.
India
Domestic mining, oil and gas, and construction sectors present latent demand as BIS standards tighten enforcement. DGFT import policies and PLI scheme incentives for technical textiles reshape domestic manufacturing capacity. Maharashtra and Gujarat industrial corridors develop protective apparel clusters for export to Middle Eastern markets.
Modacrylic Fiber Market Key Industry Players
Player mix skews toward integrated chemical conglomerates with captive acrylonitrile supply and specialty fiber spinners with polymer modification expertise. Structure concentrates around three archetypes: backward-integrated petrochemical giants controlling precursor costs, mid-scale wet spinning specialists with certification depth, and diversified technical textile suppliers spanning multiple fiber chemistries. Dominant competitive moves include capacity expansion in Chinese coastal provinces and technology licensing agreements for vinylidene chloride copolymer advances.
Within the integrated chemical tier, Kaneka Corporation and Teijin Limited exemplify players with upstream control over polymer supply. Aksa Akrilik Kimya Sanayii occupies a position among scale-driven specialists with concentrated manufacturing assets. Lenzing AG represents the diversified technical textile archetype spanning multiple fiber platforms. These three anchors illustrate how competitive positioning stratifies across supply chain control, manufacturing scale, and specialty application depth.
| Leading Market Players |
|---|
| Aksa Akrilik Kimya Sanayii |
| Teijin Limited |
| Kaneka Corporation |
| Lenzing AG |
| China National Petroleum Corporation |
| Aditya Birla Management Corporation |
| Taekwang Industrial |
| Eastman Chemical Company |
| Formosa Plastics Corporation |
| Others |
Cost & Logistics Intelligence
Halogen-free phosphorus-nitrogen intumescent systems displacing vinylidene chloride chemistries are simultaneously shifting supply geography toward European and Japanese specialty polymer houses and compressing pricing power for conventional wet-spinning operations in Chinese coastal provinces.
Pricing Analysis
Cost-plus contracts with acrylonitrile indexation dominate procurement between integrated spinners and industrial laundries. Three-tier pricing structure across EN 11612-certified premium grades, standard industrial staple, and economy faux fur tiers reflects certification depth and batch traceability investments. Pricing pressure stems from aramid substitution in above-400°C protective apparel segments. Rental workwear providers in Germany exhibit lowest price sensitivity due to specification-driven procurement, while Chinese apparel distributors face acute margin compression from propylene-ammonia feedstock volatility.
Supply Chain Analysis
Strategic stockpiling of acrylonitrile precursors characterizes backward-integrated producers, while non-integrated spinners maintain just-in-time vinylidene chloride inventories vulnerable to supply disruption. Wet spinning capacity concentrates in China, Japan, and Turkey. Raw material flows draw from Saudi Arabian propylene derivatives, Korean acrylonitrile, and domestic Chinese vinylidene chloride. Single-source vulnerability runs through Japanese specialty polymer technology licensing. Distribution runs through mill-direct channels for certified industrial buyers and regional textile distributors for mid-scale apparel manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification support services and polymer specification consulting are expanding faster than base fiber sales as rental workwear providers outsource EN 11612 compliance documentation.
For Market Incumbents: Compound certification depth through in-house testing laboratory investments to capture share from exporters facing 8-14 month EN 11612 test house bottlenecks. Deepen backward integration into acrylonitrile precursors to defend margin position against propylene-ammonia price volatility. Prioritize halogen-free polymer R&D to counter regulatory displacement of vinylidene chloride chemistries under EU REACH and China's evolving GB standards. For New Entrants and Emerging Players: Lead with India protective apparel as regulatory enforcement of BIS standards tightens in mining and oil and gas sectors. Target electric vehicle battery insulation specifications for automotive OEMs in Germany and Japan seeking thermal runaway protection materials. Anchor go-to-market strategy through direct technical service relationships with polymer specification support, bypassing wholesale distributor networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed wet spinning specialists in Chinese coastal provinces lacking captive precursor supply. Five-to-ten year viability hinges on certification infrastructure and halogen-free polymer transition capabilities. Acquisition targets should demonstrate in-house EN 11612 testing capacity and established supplier lists with European rental workwear providers. Watch for SAMR enforcement intensity in China as the signal indicating domestic share capture acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylonitrile Precursors | Captive supply from Saudi Arabian propylene derivatives insulates margin from feedstock volatility. |
| In-House EN 11612 Testing Laboratory Investment | Domestic Chinese spinners capture share from exporters facing certification delays under SAMR surveillance. |
| Halogen-Free Polymer Technology Licensing | Japanese specialty houses monetize phosphorus-nitrogen intumescent systems for FAR 25.853 compliance. |
| Long-Term Supply Agreement with Rental Workwear Providers | German technical textile rental sector consolidation favors certified suppliers with batch traceability. |
| Joint Venture for Indian Protective Apparel Manufacturing | Maharashtra and Gujarat corridors develop export capacity for Middle Eastern markets under tightening BIS standards. |
Research Approach
Desk research of customs trade databases, SEC chemical company filings, and ECHA REACH registration databases preceded structured interviews with wet spinning plant managers, procurement leads at European industrial laundries, technical textile rental provider operations heads, and polymer R&D directors at Japanese specialty fiber houses. Bottom-up volume estimates from named production facilities triangulated against top-down demand calculations from end-use industry consumption patterns.
Variance decomposition across staple fiber, specialty fiber, and continuous filament product types structured the analytical framework over the projection horizon. Modeled segmentation dimensions included fiber form, end-use application, certification tier, and regional regulatory cluster. CAGRs derived from historical production capacity utilization trends and announced expansion projects. Industry-specific inputs incorporated acrylonitrile price index trajectories and EN 11612 certification timeline distributions.
Underlying assumptions cover sustained enforcement of EU REACH and China's GB 8965.1-2020 standards, with deviation risk concentrated in halogen-free polymer substitution rates and electric vehicle battery insulation qualification timelines. Forecasts reflect documented assumptions without guaranteed outcomes. Revision becomes warranted when aramid fiber price-performance ratios cross thresholds enabling mass substitution in sub-400°C protective apparel segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Latin America Textile Market
Synthetic Fibers
Para-Aramid Fibers Market
Synthetic Fibers
Global Synthetic Spider Silk Market
Synthetic Fibers
Americas Spandex Market
Synthetic Fibers
Extruded PLA Fiber Market
Synthetic Fibers
Spandex Fiber Market
Synthetic Fibers
Rayon Fibers Market
Synthetic Fibers
Textile Fibers Market
Synthetic Fibers
Short Cut Polyester Fiber Market
Synthetic Fibers
Europe Nanofiber Market
Synthetic Fibers
Pan-Based Carbon Fiber Cloth Market
Synthetic Fibers
Anti-Static Fibers Market
Synthetic Fibers
Neoprene Fabric Market
Synthetic Fibers
Polymer Nanofiber Market
Synthetic Fibers
Clothing Fibers Market
Synthetic Fibers
Carbon Fiber Strands Market