
 Asia-Pacific Spandex Market | 2026-2036
Asia-Pacific Spandex Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Spandex Market Outlook
High-tenacity spandex above 40 denier is bifurcating the Asia-Pacific supply base into premium filament specialists and commodity producers. Hyosung Corporation leverages its integrated PTMEG-to-fiber pipeline in South Korea to sustain margin capture across the value chain. Taekwang Industrial anchors Vietnamese production capacity to compete on cost for North American-bound activewear orders. Zhejiang Huafon Spandex specializes in fine-denier grades for seamless underwear, differentiating through consistent dye-lot uniformity.
Spandex is a segmented polyurethane fiber engineered with 85% minimum segmented polyurethane content by weight, delivering elongation exceeding 500% with near-complete elastic recovery. Manufacturers produce it through solution dry-spinning of macro-glycol diisocyanate prepolymers into continuous filaments for stretch-woven and knit applications. Textile Spandex dominates volume throughput across the region, while Coated Spandex commands premium positioning in medical compression and swimwear where chlorine resistance determines replacement cycles. Activewear as an application segment leads absolute consumption, though Industrial Spandex in medical textiles posts the fastest trajectory as aging populations in Japan and South Korea expand therapeutic garment needs.
China's MIIT enforces GB standards on chemical fiber volatile organic compound emissions, compelling solvent-recovery investments that raise entry barriers for smaller dry-spinning operators. South Korea's MFDS regulates skin-contact elastic textiles under medical-device-adjacent frameworks, creating compliance costs that favor established exporters with certified testing protocols. Japan's METI promotes next-generation fiber innovation through its Society 5.0 initiative, channeling R&D subsidies toward bio-based polyurethane precursors. Stakeholders must monitor how divergent national chemical regulations reshape cross-border sourcing economics between Chinese cost bases and Korean-Japanese quality-tier positioning.
Market Dynamics
China's MIIT emission standards for chemical fiber production are compressing the supplier base by forcing solvent-recovery investments that smaller dry-spinning operators cannot absorb, consolidating volume toward integrated mills with captive PTMEG supply.
Growth Catalysts
- Activewear demand concentration:Athletic apparel brands in Zhejiang and Jiangsu provinces are scaling orders for high-elongation fiber as consumer preference pivots toward performance-driven garments with compression properties.
- GB standards enforcement:China's tightened volatile organic compound regulations are accelerating capital deployment into cleaner polyurethane spinning methods, raising technical barriers that protect incumbent producers.
- Aging demographic therapeutic needs:Medical compression garment demand in Japan and South Korea is expanding replacement cycles for chlorine-resistant coated spandex in post-surgical and circulatory therapy applications.
Market Restraints
- PTMEG feedstock volatility:Polytetramethylene ether glycol price swings transmit directly into spandex filament cost structures, squeezing margin capture for non-integrated spinners without captive precursor supply.
- Supply concentration in Zhejiang-Jiangsu corridor:Overreliance on integrated textile clusters along China's eastern seaboard creates geographic risk exposure to regional power rationing and port congestion.
- Polyester mechanical stretch substitution:Advances in textured PET yarn with moderate elasticity are capturing share in cost-sensitive basic apparel where extreme elongation is not specification-critical.
Strategic Opportunities
- Vietnamese production anchoring:Greenfield capacity deployment near Ho Chi Minh City offers tariff-advantaged export positioning for North American-bound activewear orders seeking China-plus-one sourcing.
- Bio-based polyurethane precursors:Japan's METI Society 5.0 R&D subsidies are channeling investment toward renewable macro-glycol feedstocks that command premium positioning in sustainability-certified garment lines.
- Direct-to-brand mill relationships:Bypassing traditional yarn traders, integrated producers are establishing dedicated supply agreements with multinational sportswear headquarters in Seoul and Shanghai.
Industry Challenges
- Dry-spinning engineering talent scarcity:Solvent-recovery system optimization requires specialized chemical engineers that Vietnam and Indonesia lack in sufficient depth, constraining capacity ramp timelines.
- MFDS skin-contact certification timelines:South Korea's medical-device-adjacent textile testing protocols extend product approval cycles by 8-14 months for therapeutic compression garments.
- Legacy dye-lot matching systems:Fine-denier seamless underwear production demands color consistency across batches that older spectrophotometry infrastructure cannot reliably deliver.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Spandex Market |
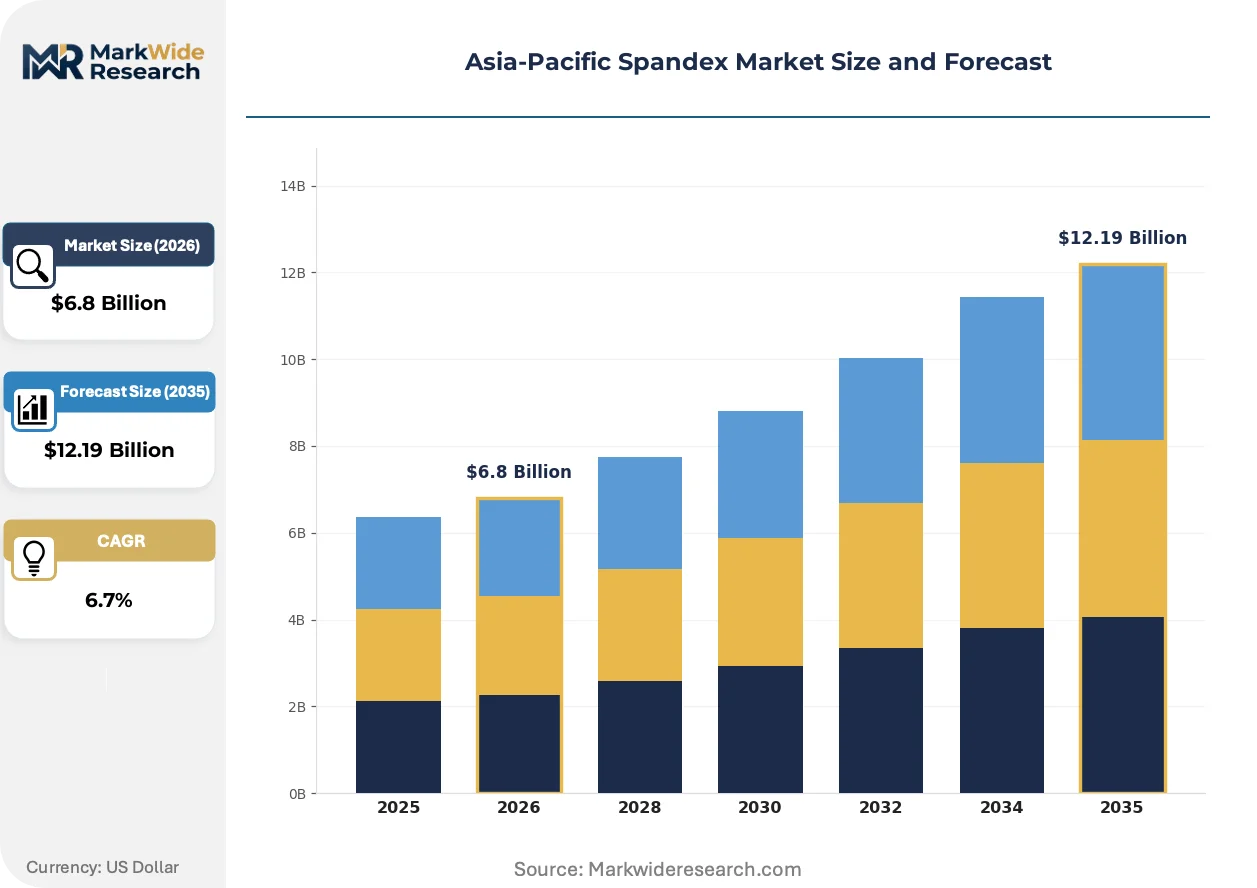
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textile Spandex, Coated Spandex, Non-woven Spandex, Industrial Spandex Application: Activewear, Swimwear, Loungewear, Underwear End User: Fashion Industry, Sports Industry, Healthcare, Retail Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Hyosung Corporation, Asahi Kasei Corporation, Taekwang Industrial Co., Ltd., Indorama Corporation, TK Chemical Corporation, Zhejiang Huafon Spandex Co., Ltd., Yantai Tayho Advanced Materials Co., Ltd., Xiamen Lilong Spandex Co., Ltd., Toray Industries, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Spandex Market Strategic Shifts
Polymer process innovation and regulatory chemistry mandates are fragmenting competitive advantage between capital-heavy integrated producers and specialized fine-denier specialists. Three developments merit particular attention.
Recycled-content spandex is decomposing the virgin-polyurethane premium by enabling closed-loop garment-to-fiber recovery systems. Activewear brands with public circularity commitments are specifying minimum recycled content thresholds in procurement tenders. This technology is compressing first-mover margin advantages for producers with pilot-scale chemical recycling partnerships.
China's MIIT GB standards on chemical fiber volatile organic compound emissions are mandating solvent-recovery system retrofits at all dry-spinning facilities above defined throughput thresholds. Mills without recovery infrastructure face production suspensions until compliance certification. Zhejiang-based integrated producers with captive recovery are absorbing displaced volume from suspended smaller competitors.
Brand technical teams are consolidating approved supplier lists to three-to-five mill relationships per fiber category, replacing fragmented multi-source purchasing. This concentration is elevating consistent dye-lot uniformity and documented carbon footprint data to primary selection criteria. The shift is most visible among Seoul-headquartered athletic apparel brands qualifying Zhejiang and Vietnamese mills for core program allocation.
Asia-Pacific Spandex Market Segmentation
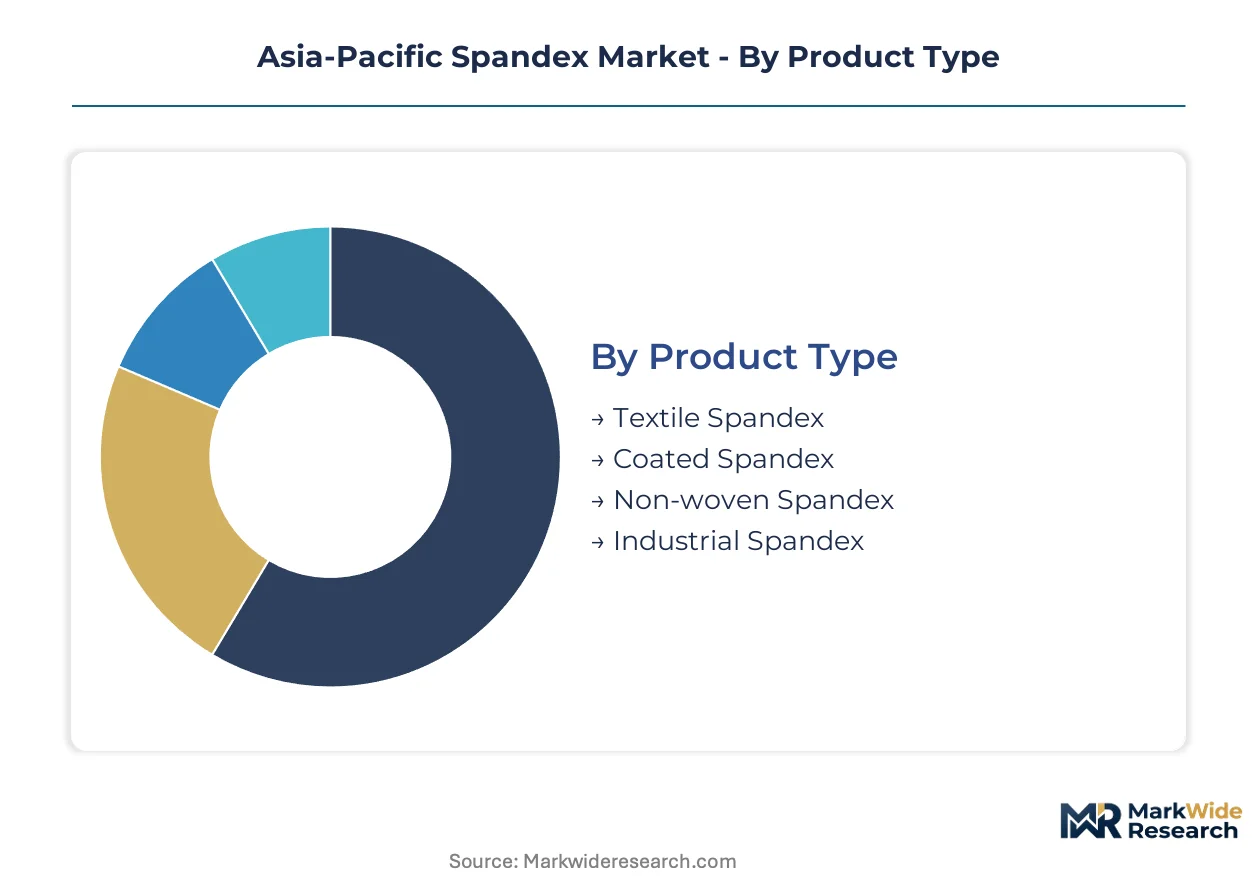
Segmentation in the Asia-Pacific spandex market reveals how regulatory chemistry mandates and end-use performance specifications fragment supply capabilities. Producers must align product portfolios with divergent compliance frameworks across Chinese MIIT emission rules, South Korean MFDS skin-contact protocols, and Japanese METI innovation subsidies.
Product Type:
MIIT's GB standards on volatile organic compound emissions create divergent compliance costs across product categories, concentrating volume toward integrated mills with captive solvent-recovery infrastructure.
- Textile Spandex:Solution dry-spun continuous filaments with 85% minimum segmented polyurethane content by weight dominate woven and knit stretch applications. Demand concentrates in Zhejiang and Jiangsu province clusters supplying domestic athletic apparel brands and export-oriented garment manufacturers. China's tightened emission standards favor integrated producers with captive PTMEG supply chains over smaller dry-spinning operators.
- Coated Spandex:Chlorine-resistant surface treatments extend replacement cycles in aquatic and therapeutic environments. Medical compression garment demand in Japan and South Korea drives specification for post-surgical and circulatory therapy applications. MFDS skin-contact certification timelines extend approval cycles, favoring established exporters with documented testing protocols.
- Non-woven Spandex:Staple fiber formats for disposable hygiene and medical applications compete on throughput scale against textile alternatives.
- Industrial Spandex:Heavy-denier grades for technical textiles and composite reinforcement target infrastructure and automotive end-uses with modulus specifications.
Textile Spandex handles the majority of throughput; Industrial Spandex is climbing the fastest on share as infrastructure investment accelerates across Southeast Asia.
Application:
Performance specifications diverge sharply between compression-driven athletic segments and comfort-oriented casual wear, creating distinct procurement channels.
- Activewear:High-elongation fiber with compression properties serves performance-driven garments from Seoul-headquartered multinational brands. Zhejiang mills scale procurement to meet technical specifications for moisture management and shape retention. Brand technical teams consolidate approved supplier lists to three-to-five mill relationships, elevating dye-lot consistency to primary selection criteria.
- Underwear:Fine-denier grades below 20 denier demand color uniformity across batches that older spectrophotometry infrastructure cannot reliably deliver. Zhejiang Huafon and similar specialists differentiate through consistent dye-lot matching for seamless construction.
- Swimwear:Chlorine resistance determines replacement cycles, favoring coated spandex with extended durability certifications.
- Loungewear:Moderate elasticity requirements allow polyester mechanical stretch substitution in cost-sensitive basic apparel segments.
Activewear absorbs the largest volume share; medical-adjacent compression applications within swimwear and activewear segments are expanding most quickly on therapeutic demand from aging populations.
End User:
Customer procurement sophistication ranges from technical specification teams at multinational headquarters to price-driven wholesale traders.
- Sports Industry:Technical teams at Seoul and Shanghai headquarters mandate documented carbon footprint data and recycled-content thresholds in procurement tenders. Direct-to-brand mill relationships bypass traditional yarn traders, concentrating volume toward integrated producers with pilot-scale chemical recycling partnerships.
- Healthcare:Therapeutic compression garment manufacturers in Japan and South Korea face MFDS and PMDA adjacent regulatory frameworks. Extended certification timelines protect incumbents with established testing infrastructure.
- Fashion Industry:Trend-driven seasonal procurement prioritizes dye-lot speed and minimum order flexibility over technical performance metrics.
- Retail:Private-label programs compete on landed cost, driving sourcing toward Vietnamese tariff-advantaged capacity for North American-bound orders.
Sports Industry commands premium positioning; Healthcare is gaining share fastest on demographic tailwinds and regulatory barrier effects.
Distribution Channel:
Channel economics reflect lot-size requirements and technical service intensity across customer segments.
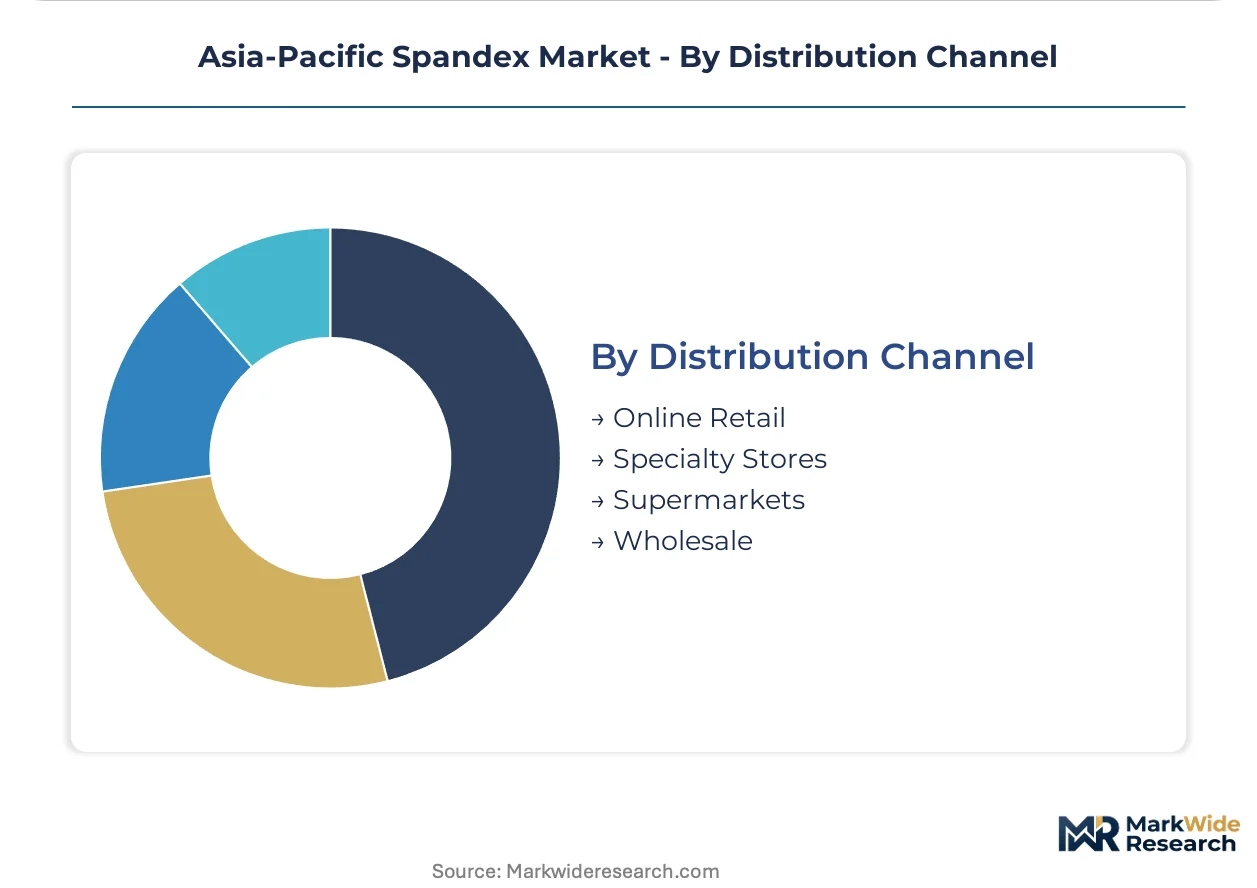
- Wholesale:Traditional yarn traders aggregate fragmented garment-maker demand across China's eastern seaboard textile clusters. Concentration risk from Zhejiang-Jiangsu corridor overreliance exposes buyers to regional power rationing and port congestion disruptions.
- Specialty Stores:Technical distributors serve mid-tier activewear brands with specification support and smaller lot flexibility.
- Online Retail:E-procurement platforms emerge for standardized grades where dye-lot matching requirements are less stringent.
- Supermarkets:Mass-market channels for basic apparel spandex compete primarily on unit economics and delivery reliability.
Wholesale retains dominant throughput; direct mill relationships through Specialty Stores are expanding most quickly as brand consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated textile clusters along China's eastern seaboard dominate regional spandex supply, while South Korean and Japanese producers differentiate through quality-tier positioning and regulatory compliance infrastructure.
China
Athletic apparel manufacturers in Zhejiang and Jiangsu provinces are scaling procurement of high-elongation fiber as consumer preference shifts toward performance-driven garments. MIIT tightened chemical fiber emission standards under GB regulations, pushing mills toward cleaner polyurethane spinning methods. The Zhejiang-Jiangsu corridor concentrates integrated textile clusters supplying domestic and export apparel brands.
South Korea
Medical compression garment demand is expanding replacement cycles for chlorine-resistant coated spandex in post-surgical and circulatory therapy applications. MFDS regulates skin-contact elastic textiles under medical-device-adjacent frameworks, creating compliance costs that favor established exporters with certified testing protocols. Hyosung Corporation leverages its integrated PTMEG-to-fiber pipeline to sustain margin capture across the value chain.
Japan
Therapeutic garment needs from aging populations are driving demand for medical-grade spandex in compression therapy applications. METI promotes next-generation fiber innovation through its Society 5.0 initiative, channeling R&D subsidies toward bio-based polyurethane precursors. Tokyo-headquartered technical teams at multinational sportswear brands are consolidating approved supplier lists to elevate dye-lot consistency criteria.
Vietnam
Greenfield capacity deployment near Ho Chi Minh City offers tariff-advantaged export positioning for North American-bound activewear orders seeking China-plus-one sourcing. Taekwang Industrial anchors Vietnamese production capacity to compete on cost for international brand procurement. The country's emerging textile infrastructure faces dry-spinning engineering talent scarcity that constrains capacity ramp timelines.
India
Domestic activewear brands are increasing technical fiber procurement as fitness culture penetrates tier-two cities. BIS standards on textile chemical safety are tightening compliance requirements for imported precursor materials. Maharashtra and Gujarat textile clusters are expanding synthetic fiber processing capabilities to reduce import dependency.
Asia-Pacific Spandex Market Competitive Environment
Concentration sits with integrated chemical-to-fiber conglomerates that control captive PTMEG supply chains. The supplier base compresses toward three strategic archetypes: Korean-Japanese quality-tier specialists with medical certification infrastructure, Chinese integrated mills with emission-compliant solvent recovery, and Southeast Asian cost-positioned greenfield operators. Dominant competitive moves include backward integration into precursor chemicals and direct-to-brand mill relationships that bypass traditional yarn traders.
Among Korean producers, Hyosung Corporation and Taekwang Industrial occupy positions across the premium and cost-optimized tiers respectively. Zhejiang Huafon Spandex exemplifies the Chinese fine-denier specialist archetype. Japanese participants Asahi Kasei Corporation and Toray Industries, Inc. represent quality-tier positioning with regulatory compliance depth. These named entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Hyosung Corporation |
| Asahi Kasei Corporation |
| Taekwang Industrial Co., Ltd. |
| Indorama Corporation |
| TK Chemical Corporation |
| Zhejiang Huafon Spandex Co., Ltd. |
| Yantai Tayho Advanced Materials Co., Ltd. |
| Xiamen Lilong Spandex Co., Ltd. |
| Toray Industries, Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Zhejiang integrated mills and Seoul-headquartered athletic apparel brands lock in both PTMEG feedstock access and eighteen-month price visibility, insulating procurement teams from polytetramethylene ether glycol spot volatility while committing volume to emission-compliant solvent-recovery facilities.
Pricing Analysis
MIIT GB standards dictate the pricing tier structure across the Asia-Pacific spandex market. Three-tier pricing structure across premium, standard, and economy levels separates medical-certified coated grades from commodity textile filament and industrial heavy-denier products. Price differentiation rests on certification depth and captive precursor supply. Cost compression in standard-grade textile spandex is intensifying because polyester mechanical stretch substitution captures share in basic apparel. Wholesale traders in China's eastern seaboard clusters exhibit highest price sensitivity; medical compression garment manufacturers in Japan and South Korea show lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Port congestion at Ningbo-Zhoushan and container availability constraints on the Shanghai-Los Angeles trade lane are elevating inbound logistics costs for Vietnamese greenfield capacity serving North American-bound orders. Supply concentrates in China, South Korea, and Vietnam. Raw material dependencies draw from PTMEG, MDI prepolymers, and chlorine-resistant coating chemistries. Single-source vulnerability in the Zhejiang-Jiangsu corridor exposes buyers to regional power rationing disruptions. Distribution runs through wholesale yarn traders aggregating fragmented garment-maker demand across integrated textile clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and dye-lot matching guarantees represent a service-attach opportunity expanding faster than virgin fiber sales, as Seoul and Shanghai brand headquarters consolidate approved supplier lists around consistent batch uniformity and documented carbon footprint data.
For Market Incumbents: Fortify margin capture by deepening backward integration into captive PTMEG production and deploying solvent-recovery infrastructure ahead of MIIT enforcement timelines. Polyester mechanical stretch substitution in loungewear and basic apparel presents the primary demand threat. Certification investment for MFDS skin-contact protocols protects Korean and Japanese market positioning against emerging Vietnamese cost competitors. For New Entrants and Emerging Players: Anchor in Vietnamese greenfield capacity near Ho Chi Minh City to capture tariff-advantaged export positioning for North American-bound activewear orders seeking China-plus-one sourcing. Medical compression garments for aging populations in Japan and South Korea represent the most penetrable white-space segment. Direct-to-brand mill relationships bypassing traditional yarn traders offer the clearest go-to-market angle. For Investors and Strategic Acquirers: Fine-denier specialists with consistent dye-lot uniformity capabilities and pilot-scale chemical recycling partnerships offer the most attractive acquisition target archetype. Long-term viability over the next decade hinges on regulatory compliance infrastructure amortization and bio-based precursor R&D positioning. The signal to monitor is brand technical team consolidation of approved supplier lists below five mill relationships per fiber category.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PTMEG | Captive precursor supply insulates margin capture from feedstock volatility and MIIT emission compliance costs. |
| Solvent-Recovery Infrastructure Deployment | GB standards enforcement suspends non-compliant smaller operators, concentrating volume toward equipped integrated mills. |
| Direct-to-Brand Mill Relationships | Bypassing wholesale yarn traders secures core program allocation from Seoul and Shanghai headquarters technical teams. |
| Bio-Based Polyurethane Precursor R&D | METI Society 5.0 subsidies channel investment toward renewable macro-glycol feedstocks commanding sustainability-certified premiums. |
| Vietnamese Production Anchoring | Tariff-advantaged export positioning captures North American-bound activewear orders seeking China-plus-one sourcing diversification. |
Study Parameters
The analysis maps textile spandex, coated spandex, and industrial heavy-denier grades, each validated through primary interviews with plant managers at integrated mills, procurement leads at downstream athletic apparel OEMs, distribution channel partners in Zhejiang and Jiangsu clusters, and technical R&D directors focused on bio-based precursors. Secondary validation draws from MIIT GB standard filings, MFDS medical-device-adjacent textile protocols, customs and trade data for PTMEG and filament imports, and SEC disclosures from listed chemical fiber producers. Bottom-up volume modeling triangulates against top-down macroeconomic elasticity assumptions.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models segmentation across product type, application, end user, and distribution channel dimensions, with regional regulatory cluster as an additional industry-specific layer. CAGRs derive from historical trajectory analysis adjusted for structural shifts including emission standard enforcement and brand supplier consolidation. Forecast inputs incorporate PTMEG feedstock price elasticity and therapeutic garment demand curves from aging demographic projections in Japan and South Korea.
Decision-makers should treat outputs as directional under assumptions of sustained MIIT enforcement stringency and continued brand technical team consolidation; material deviation in regulatory timelines or substitution technology penetration would warrant model refresh. Specific risk factors include PTMEG price volatility transmission, regional power rationing disruptions in the Zhejiang-Jiangsu corridor, and dry-spinning engineering talent scarcity constraining Vietnamese capacity ramps. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Short Cut Polyester Fiber Market
Synthetic Fibers
Polyimide Fiber Market
Synthetic Fibers
Pan-Based Carbon Fiber Cloth Market
Synthetic Fibers
IMO Fiber Market
Synthetic Fibers
North America High Performance Fibers Market
Synthetic Fibers
Performance Fabric Market
Synthetic Fibers
Global Lyocell Fibers Market
Synthetic Fibers
Extruded PLA Fiber Market
Synthetic Fibers
Kevlar Fiber Market
Synthetic Fibers
Modacrylic Fiber Market
Synthetic Fibers
Aramid Fiber Market
Synthetic Fibers
Fiberglass Roving Market
Synthetic Fibers
Conductive Fibers Market
Synthetic Fibers
Polyester Tire Cord Fabrics Market
Synthetic Fibers
US Textile Market
Synthetic Fibers
Global Synthetic Spider Silk Market