
 Parachute Fabric Market | 2026-2036
Parachute Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Parachute Fabric Market Analytics
Military end-use is consolidating share against recreational applications as defense budgets prioritize personnel airdrop and cargo delivery systems. Porcher leverages its European manufacturing heritage to sustain premium positioning in military canopy supply. Gelvenor anchors Southern Hemisphere demand through specialized nylon weaving capabilities for sport and tactical segments. Airborne Systems dominates North American defense contracts with integrated parachute system design and fabrication.
Parachute fabric denotes engineered textile materials manufactured to precise porosity, tensile strength, and tear resistance specifications for controlled descent applications. High-tenacity nylon 6,6 remains the dominant fiber, woven into ripstop constructions with calibrated permeability below 3 cfm/ft² to ensure stable inflation and descent trajectories. Nylon commands the largest material position due to proven strength-to-weight ratios and established military qualification pathways, while Kevlar penetrates specialized military segments requiring ballistic tolerance and thermal protection. Among finish types, PU-coated fabrics capture expanding share as zero-porosity requirements intensify for high-altitude precision drops, whereas water-repellent treatments face commoditization in recreational markets. The heavyweight category retains margin concentration in defense applications, while ultra-lightweight fabrics experience fastest volume expansion in competitive skydiving and BASE jumping equipment.
FAA Technical Standard Orders govern civilian parachute fabric certification in the United States, mandating burst strength and permeability testing that shapes supplier qualification timelines and R&D allocation. European military procurement aligns with CE marking and EASA oversight for dual-use aerial delivery platforms, while ISO 11475 provides international benchmark protocols for textile performance characterization. Stakeholders must monitor evolving defense procurement localization mandates and sport skydiving equipment refresh cycles to align capacity planning with demand volatility.
Market Dynamics
Defense procurement localization mandates are fragmenting established supply relationships as NATO allies enforce domestic content requirements for military canopy materials. Zero-porosity coating specifications now exclude non-qualified suppliers from precision airdrop contracts, compressing the vendor base to certified weaving operations with in-house finishing capabilities.
Growth Catalysts
- Personnel Airdrop Modernization:Military programs across NATO members prioritize high-altitude precision delivery systems, sustaining baseline demand for certified zero-porosity fabrics with burst strength exceeding 400 psi.
- FAA Technical Standard Orders:Updated civilian certification protocols for sport skydiving equipment mandate permeability testing below 3 cfm/ft², forcing equipment refresh cycles that pull fabric replacement demand.
- Ripstop Weaving Automation:Advanced jacquard looms with real-time tension monitoring enable tighter weave tolerances, reducing lot rejection rates for military canopy suppliers.
Market Restraints
- High-Tenacity Nylon 6,6 Supply Concentration:Fiber production clusters in the United States and China expose canopy weavers to petrochemical feedstock volatility and geopolitical supply disruptions.
- Zero-Porosity Coating Chemistry Limitations:Polyurethane formulations face performance degradation in extreme thermal environments above 120°F, restricting operational envelopes for precision cargo drops.
- REACH Compliance Burden:European chemical registration requirements for coating additives extend qualification timelines by 18-24 months for non-EU suppliers seeking defense contracts.
Strategic Opportunities
- India Defense Localization:PLI scheme incentives for textile manufacturing attract parachute fabric investment as the Indian Air Force expands its indigenous airdrop capability.
- Kevlar-Nylon Hybrid Constructions:Ballistic-tolerant canopy materials for special operations forces create premium positioning above commodity nylon segments.
- Direct Military Procurement Platforms:Defense agencies in Australia and Canada establish long-term supply agreements that bypass traditional distributor markups for certified suppliers.
Industry Challenges
- Master Weaver Skill Scarcity:Ripstop construction expertise for ultra-low porosity specifications concentrates among aging workforces in traditional textile regions of North Carolina and northern France.
- Military Qualification Timelines:NATO STANAG certification cycles extend 36-48 months, freezing capacity allocation decisions before demand materializes.
- Legacy Finishing Equipment Retrofit Costs:PU coating lines require seven-figure capital outlays for zero-porosity compliance, marginalizing mid-scale weaving operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parachute Fabric Market |
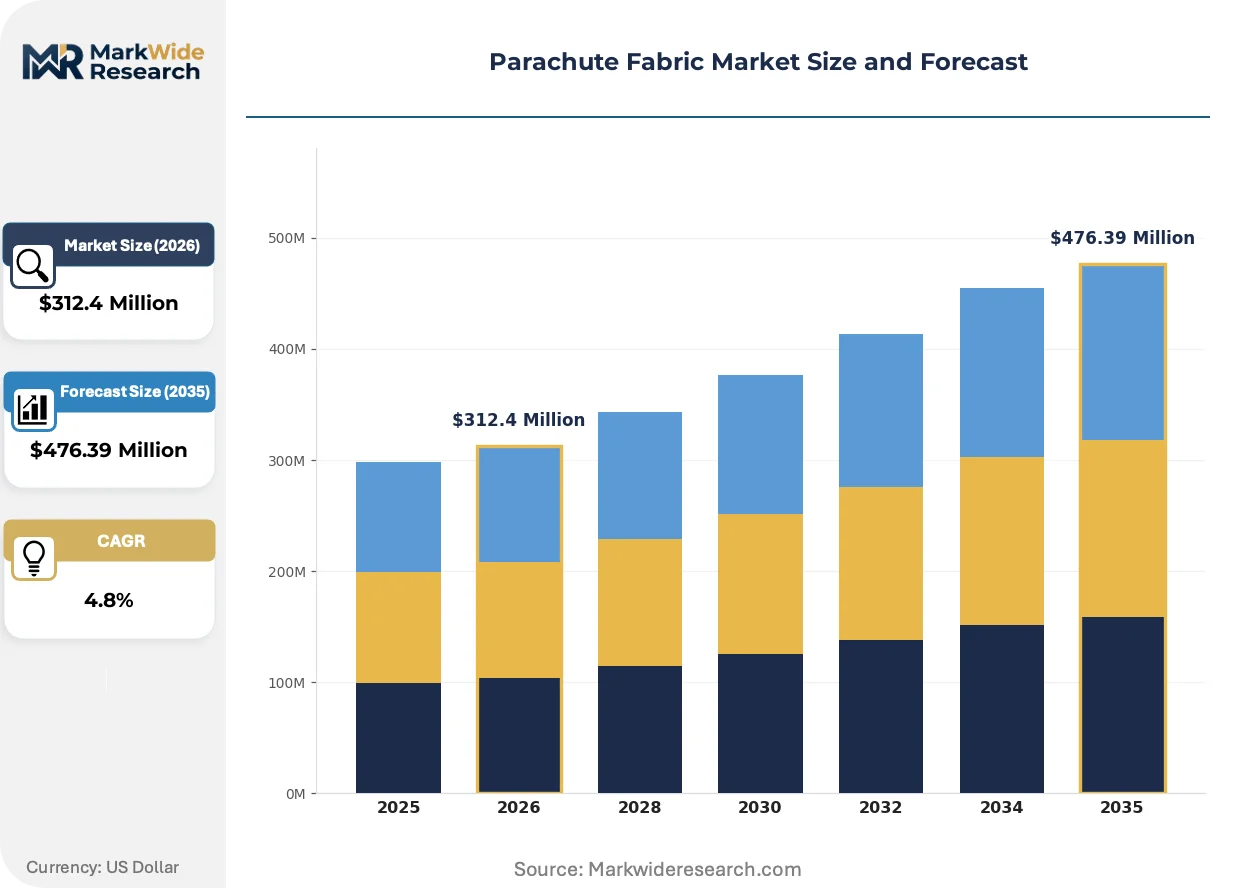
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Nylon, Polyester, Silk, Kevlar Application: Military, Sports, Recreation, Safety Finish Type: PUL, PU Coated, Water-Repellent, Flame Retardant Weight Category: Lightweight, Medium Weight, Heavyweight, Ultra-Lightweight |
| Companies Covered | Shahlon Group, Ruby Mills Ltd., Porcher, Kusumgar Corporates, Belton Industries, DELCOTEX, Gelvenor, Parachute Systems, Airborne Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parachute Fabric Market Evolving Landscape
Digital weaving controls and predictive porosity modeling are compressing development cycles for certified canopy materials. Suppliers now compete on qualification speed rather than commodity scale, reshaping R&D allocation across military and recreational segments.
AI-driven loom calibration is decentralizing production expertise from traditional textile clusters to newer manufacturing regions. Defense contractors in Poland and Romania adopt automated tension monitoring systems that previously required decades of master weaver experience. This capability diffusion enables geographic diversification of certified supply away from established US and French weaving centers.
EU Green Deal chemical restrictions are forcing coating reformulation across European military suppliers. REACH-registered alternatives to legacy solvent-based PU systems now dominate procurement specifications for NATO member states. German and French defense agencies prioritize aqueous-based zero-porosity finishes in tender evaluations, penalizing suppliers with legacy chemical portfolios.
Skydiving equipment buyers now demand modular canopy systems with standardized attachment points across manufacturers. This interoperability push compresses switching costs for sport jumpers and fragments brand loyalty that previously locked users into single-supplier ecosystems. The trend concentrates in the United States and Australia where large drop zones operate mixed-equipment fleets.
Parachute Fabric Market Segmentation
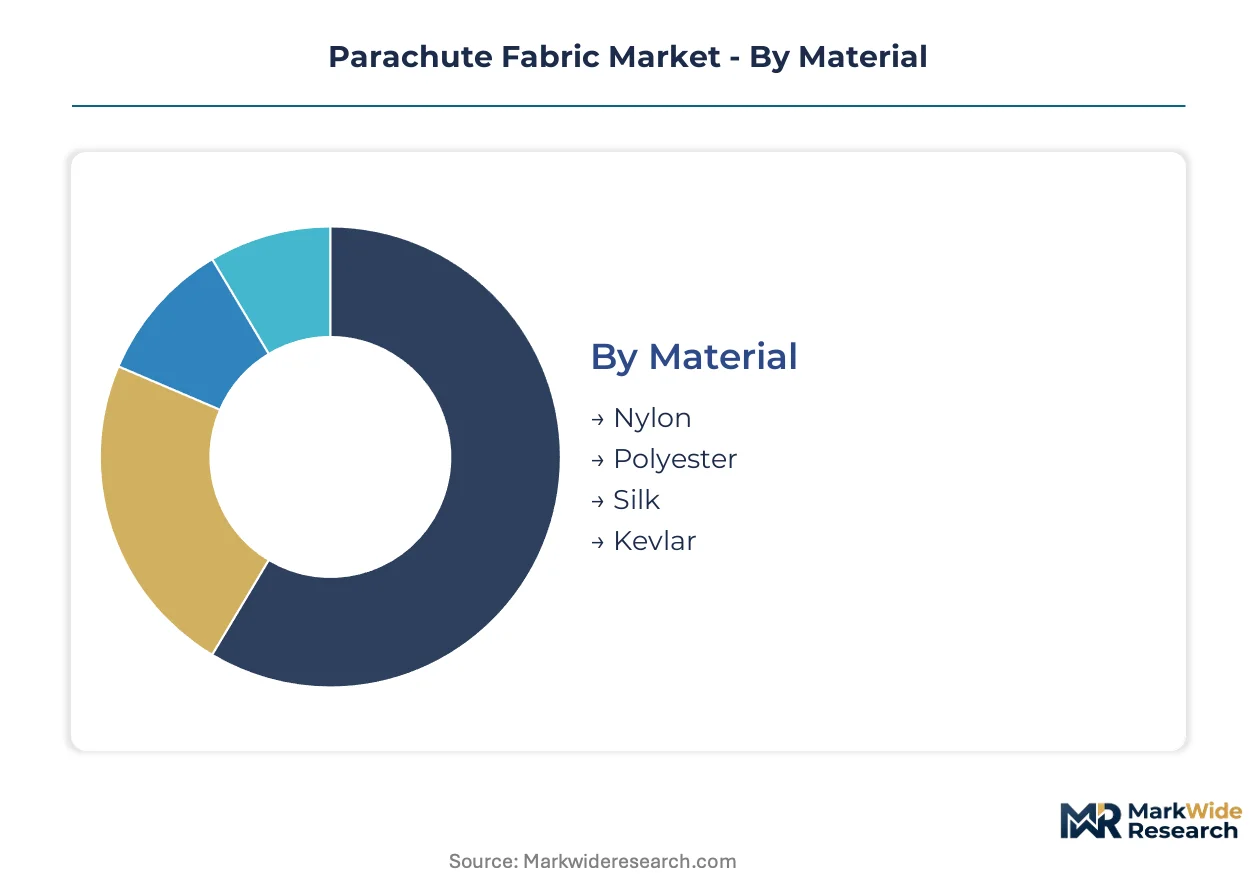
Parachute fabric segmentation maps directly to certification pathways and procurement specifications that govern military and civilian canopy deployment. Material selection and finish chemistry determine qualification timelines under FAA Technical Standard Orders and NATO STANAG protocols, while weight categories align with specific airdrop altitude and payload requirements.
Material:
FAA Technical Standard Orders and NATO STANAG certification burdens fall heaviest on high-tenacity synthetic fibers, with natural and hybrid constructions facing extended qualification timelines for military adoption.
- Nylon:High-tenacity nylon 6,6 dominates canopy construction through proven strength-to-weight ratios above 8.5 g/denier and established burst strength qualification above 400 psi. United States defense procurement anchors baseline demand, with domestic weaving operations in North Carolina sustaining military supply relationships.
- Kevlar:Aramid fiber constructions penetrate special operations segments requiring ballistic tolerance and thermal protection beyond nylon operational envelopes. European defense agencies prioritize Kevlar-nylon hybrids for precision cargo drops in contested airspace, though fiber cost premiums restrict volume expansion.
- Polyester:Lower-tenacity polyester serves recreational skydiving equipment where cost sensitivity outweighs military-grade performance specifications, particularly in Australian and Brazilian sport markets.
- Silk:Traditional silk weaving persists in ceremonial and vintage aircraft restoration applications, with Japanese and Indian textile houses maintaining artisanal production for heritage aviation collectors.
Nylon sits at the top of the volume ranking, with Kevlar climbing the fastest as special operations procurement intensifies.
Application:
Defense procurement localization mandates are reshaping demand concentration across application segments, with military contracts now requiring domestic content verification that excludes offshore recreational suppliers.
- Military:Personnel airdrop and precision cargo delivery systems sustain baseline demand for zero-porosity fabrics with permeability below 3 cfm/ft². United States Air Force procurement through Airborne Systems and European NATO allies through Porcher anchor volume concentration.
- Sports:Competitive skydiving and BASE jumping equipment refresh cycles pull fabric replacement demand under updated FAA certification protocols. Australian drop zones and United States skydiving centers drive fastest volume expansion in modular canopy systems.
- Recreation:Tandem skydiving operations and adventure tourism operators in Dubai and New Zealand prioritize cost-optimized nylon constructions with water-repellent finishes over military-grade specifications.
- Safety:Emergency evacuation systems for offshore oil platforms and high-rise buildings require flame-retardant finishes meeting ISO 11475 protocols, with North Sea operators and Singapore aviation authorities driving specification tightening.
Military applications command the steepest margin concentration, while sports segment expansion accelerates most quickly under equipment modernization mandates.
Finish Type:
Coating chemistry selection determines operational temperature envelopes and chemical compliance burdens, with aqueous-based systems gaining preference under EU Green Deal restrictions.
- PU Coated:Polyurethane zero-porosity coatings capture expanding share in high-altitude precision drop applications, though thermal degradation above 120°F restricts operational envelopes for desert theater deployments.
- PUL:Polyurethane laminate constructions serve sport skydiving equipment where flexibility and packability outweigh extreme environmental tolerance, dominating Australian and United States recreational markets.
- Water-Repellent:Silicone-based treatments face commoditization in recreational segments as equipment buyers prioritize cost over performance differentiation.
- Flame Retardant:Halogen-free formulations gain mandatory status under REACH-registered alternatives for European military procurement, with German and French defense agencies penalizing legacy solvent-based suppliers.
PU Coated finishes lead volume rankings for military applications, with Flame Retardant formulations gaining share fastest under chemical regulation tightening.
Weight Category:
Weight selection correlates directly with payload capacity and descent rate specifications, with defense procurement favoring heavyweight constructions that fragment into specialized supplier tiers.
- Heavyweight:Dense weave constructions above 7 oz/yd² retain margin concentration in defense applications, with burst strength requirements exceeding 400 psi freezing out mid-scale weaving operations lacking capital for coating line upgrades.
- Ultra-Lightweight:Sub-3 oz/yd² fabrics experience steepest volume expansion in competitive skydiving and wingsuit applications, where pack volume reduction enables performance advantages in United States and Australian sport markets.
- Medium Weight:4-6 oz/yd² specifications balance durability and packability for tandem skydiving operations and civilian emergency systems.
- Lightweight:3-4 oz/yd² constructions serve training parachutes and student equipment where cost optimization takes priority over competitive performance margins.
Heavyweight fabrics dominate defense procurement value, with Ultra-Lightweight categories expanding most quickly in sport equipment refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redrawing the parachute fabric production map as REACH compliance costs in Europe push coating operations toward jurisdictions with lighter chemical registration burdens. Manufacturers now optimize location decisions around qualification timeline differentials rather than labor costs alone.
United States
Defense procurement through the United States Air Force sustains demand for zero-porosity fabrics with burst strength above 400 psi. FAA Technical Standard Orders govern civilian certification, mandating permeability testing below 3 cfm/ft² that shapes supplier R&D allocation. North Carolina weaving clusters anchor military supply relationships through established ripstop construction expertise.
France
European military canopy supply concentrates in traditional textile regions where master weaver expertise supports ultra-low porosity specifications. EU Green Deal chemical restrictions are forcing aqueous-based coating reformulation, with ECHA registration requirements extending qualification timelines for non-EU suppliers. Northern French weaving centers face pressure from REACH-registered alternative mandates in defense tender evaluations.
India
PLI scheme incentives for textile manufacturing are attracting parachute fabric investment as the Indian Air Force expands indigenous airdrop capability. BIS standards alignment with ISO protocols enables faster military qualification pathways for domestic weavers. Gujarat and Maharashtra industrial corridors host emerging coating operations targeting defense localization mandates.
Australia
Sport skydiving equipment refresh cycles pull fabric replacement demand under updated TGA oversight of aerial sports safety. Direct military procurement platforms from the Australian Defence Force establish long-term supply agreements that bypass traditional distributor markups. Queensland and New South Wales drop zones drive fastest volume expansion in modular canopy systems.
Poland
Defense contractors adopt automated tension monitoring systems that decentralize production expertise from traditional textile clusters. NATO STANAG certification alignment enables Polish weaving operations to capture precision airdrop contracts previously concentrated in Western European suppliers. Silesian manufacturing regions benefit from geographic proximity to Ukrainian theater logistics requirements.
Parachute Fabric Market Competitive Landscape
Defense procurement localization dominates the current landscape as NATO allies enforce domestic content requirements that fragment established supply relationships. The vendor base compresses toward certified weaving operations with in-house finishing capabilities, freezing out mid-scale competitors lacking seven-figure coating line capital. Three archetypes define positioning: integrated system designers with captive fabric production, specialized military canopy weavers with NATO STANAG qualification, and recreational suppliers facing commoditization pressure. Geographic expansion and strategic partnerships represent the dominant competitive moves as suppliers chase qualification speed advantages.
Within the European heritage tier, Porcher exemplifies premium positioning through established military supply relationships. Among Southern Hemisphere specialists, Gelvenor occupies a position serving sport and tactical demand segments. At the integrated system end, Airborne Systems anchors North American defense contracting through combined design and fabrication capabilities. These three represent distinct qualification pathways that shape competitive access to procurement contracts.
| Leading Market Players |
|---|
| Shahlon Group |
| Ruby Mills Ltd. |
| Porcher |
| Kusumgar Corporates |
| Belton Industries |
| DELCOTEX |
| Gelvenor |
| Parachute Systems |
| Airborne Systems |
| Others |
Value Network & Pricing Analysis
Defense procurement agencies in NATO member states anchor pricing power through long-term offtake agreements that compress distributor margins and privilege certified suppliers with in-house finishing capabilities. Contract structures reward qualification speed and zero-porosity certification over commodity scale, creating tiered pricing separation between military-grade weavers and recreational suppliers.
Pricing Analysis
Distributor markups face compression as direct military procurement platforms in Australia and Canada bypass traditional channel layers. Three-tier pricing structure across premium, standard, and economy levels aligns with NATO STANAG certification tiers, with zero-porosity PU-coated fabrics commanding premium positioning. Cost compression in recreational nylon segments is intensifying because modular canopy interoperability fragments brand loyalty. Sport skydiving equipment buyers exhibit highest price sensitivity, while special operations procurement shows lowest sensitivity due to mission-critical performance requirements.
Supply Chain Analysis
High-tenacity nylon 6,6 supply rests on petrochemical feedstock clusters in the United States and China, exposing canopy weavers to upstream volatility. Ripstop weaving expertise concentrates in North Carolina and northern France, while coating operations face geographic displacement under REACH compliance burdens. Single-source vulnerability runs through master weaver skill scarcity in traditional textile regions. Distribution feeds from integrated system designers with captive fabric production, direct-to-military procurement platforms, and specialized recreational equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The parachute fabric market reads as a late-cycle quality story where defense procurement prioritizes zero-porosity specifications and qualification speed over commodity volume. Personnel airdrop modernization across NATO allies is shifting demand toward premium certified tiers with burst strength above 400 psi.
For Market Incumbents: Lock in NATO STANAG certification cycles ahead of demand materialization to freeze capacity allocation decisions. Deepen backward integration into high-tenacity nylon 6,6 supply through long-term fiber offtake agreements with United States and Chinese petrochemical producers. Master weaver skill scarcity in North Carolina and northern France threatens production continuity, making automated tension monitoring system deployment the priority capability investment. For New Entrants and Emerging Players: The price-point gap between premium Kevlar-nylon hybrids and commodity recreational nylon creates entry space for mid-tier sport suppliers. Target Australian and United States drop zones with modular canopy systems featuring standardized attachment points that reduce switching costs. Pursue BIS standards alignment in India under PLI scheme incentives as the fastest qualification pathway for defense localization mandates. For Investors and Strategic Acquirers: Integrated parachute system designers with captive fabric production are the most active acquirer in this space, consolidating certified weaving operations to secure supply chain control. Acquisition targets should screen for in-house zero-porosity coating capabilities and existing NATO STANAG qualification. The signal to watch is Indian Air Force indigenous airdrop capability expansion as a demand inflection trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Porosity Coating Line Investment | Seven-figure capital deployment excludes mid-scale competitors from precision airdrop contracts under FAA Technical Standard Orders. |
| Long-Term Military Supply Agreement | Direct procurement platforms in Australia and Canada bypass distributor markups and anchor volume visibility for certified suppliers. |
| Automated Tension Monitoring Deployment | AI-driven loom calibration decentralizes production expertise from aging master weaver clusters to emerging manufacturing regions. |
| REACH-Registered Coating Reformulation | Aqueous-based zero-porosity finishes enable continued European defense procurement under EU Green Deal chemical restrictions. |
| PLI Scheme Manufacturing Investment | Indian textile corridors attract parachute fabric capacity as domestic content mandates reshape supply geography. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with defense procurement officers, canopy system design engineers, textile plant managers, and master weavers with secondary validation against FAA Technical Standard Order filings, NATO STANAG documentation, BIS standards publications, and customs trade data for high-tenacity synthetic fiber imports. Bottom-up segment sizing and top-down market triangulation cross-validated volume and value estimates.
Segment-weighting across material, application, finish type, and weight category dimensions shaped the analytical framework over the projection horizon. CAGRs derived from historical trajectory analysis and demand driver elasticity modeling incorporated inputs from defense budget allocation patterns, sport skydiving equipment refresh cycles, and coating chemistry innovation pipelines.
Caveats apply where REACH compliance timeline extensions, geopolitical disruptions to nylon 6,6 feedstock supply, or master weaver labor attrition could materially shift the outlook. A small set of named triggers—Indian defense localization acceleration, EU Green Deal chemical restriction tightening, and zero-porosity coating thermal performance breakthroughs—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Microfiber Leather Market
Synthetic Fibers
Europe Aramid Fiber Market
Synthetic Fibers
Polyester Straps Market
Synthetic Fibers
Carbon Fiber Strands Market
Synthetic Fibers
Glass Fiber Yarn Market
Synthetic Fibers
Pan-Based Carbon Fiber Cloth Market
Synthetic Fibers
Rayon Fibers Market
Synthetic Fibers
Performance Fabric Market
Synthetic Fibers
Spandex Fiber Market
Synthetic Fibers
Fiber Blends Market
Synthetic Fibers
Conductive Fibers Market
Synthetic Fibers
Asia-Pacific Aramid Fiber Market
Synthetic Fibers
Polyolefin Fiber Market
Synthetic Fibers
Monofilament Market
Synthetic Fibers
Designer Fiber Market
Synthetic Fibers
Polyester Strap for Manual Grade Market