
 Synthetic Fabric Market | 2026-2036
Synthetic Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Fabric Market Analysis
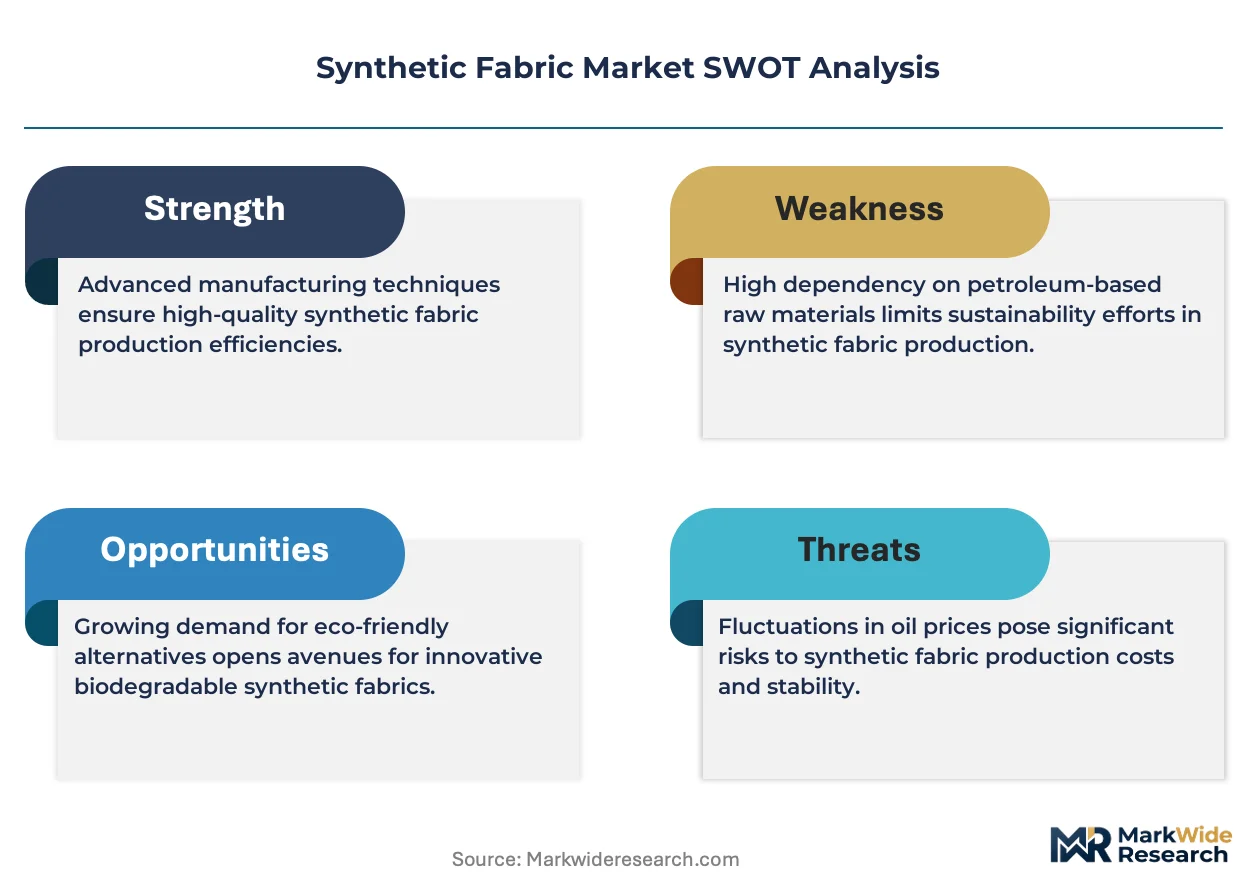
The EU Green Deal is hardening compliance requirements for synthetic textile producers, forcing reformulation of virgin polymer feedstocks. Toray Industries leverages its integrated polymer-to-fiber operations in Japan to sustain cost advantages in high-performance nylon. BASF anchors European supply of bio-based polyamide precursors, while Indorama Corporation dominates recycled PET flake capacity across Southeast Asia.
Synthetic fabric comprises man-made textile fibers engineered from petrochemical-derived polymers such as polyethylene terephthalate or polyamide, typically extruded through spinnerets and drawn to deniers between 0.5 and 20 for apparel-grade applications. Polyester commands the largest volume share due to its cost-efficiency in fast-fashion supply chains, though spandex captures disproportionate margin pools in athletic compression wear. Medical-grade antimicrobial nylon represents the fastest-growing application segment as hospitals phase out cotton-linen blends.
The EU ECHA enforces REACH restrictions on azo dyes and perfluorinated chemicals in synthetic fabrics, while the US EPA regulates antimicrobials under FIFRA for healthcare textiles. China's MEE implements wastewater discharge standards for polyester dye houses that elevate capital requirements for smaller mills. Stakeholders must monitor evolving extended producer responsibility schemes in the European Union and California that will reshape collection infrastructure obligations.
Market Dynamics
Polymer feedstock reformulation is compressing margins for virgin polyester producers while redirecting capital toward chemical recycling infrastructure and bio-based precursor development.
Growth Catalysts
- EU Green Deal Extended Producer Responsibility:Mandatory textile collection targets in the European Union are forcing brands to secure certified recycled fiber supply chains.
- Sportswear Performance Specifications:Athletic apparel brands specify recycled polyester with verified traceability for team uniforms and retail collections.
- Chemical Recycling Scale-Up:Depolymerization technologies are converting colored PET waste into virgin-quality resin for textile-grade filament.
Market Restraints
- Crude-Derived Feedstock Volatility:Paraxylene and purified terephthalic acid prices track Brent crude movements, eroding margin predictability for polyester chip producers.
- Collection Infrastructure Gaps:Post-consumer textile sorting capacity concentrates in Northern Europe and East Asia, leaving other regions supply-constrained for feedstock.
- Mechanical Recycling Quality Ceiling:Recycled PET fiber from bottle flake exhibits tenacity degradation after three thermal cycles, limiting closed-loop garment-to-garment pathways.
Strategic Opportunities
- India Formalization Gap:The country's fragmented power-loom sector lacks integrated rPET sourcing, creating first-mover advantage for regional flake-to-fiber operators.
- Medical Antimicrobial Nylon:Hospital linen service contracts specify pathogen-resistant synthetic blends, displacing cotton-polyester mixes in surgical and patient textiles.
- EU Ecodesign for Sustainable Products Regulation:Digital product passport mandates will reward early adopters of blockchain-traceable fiber supply chains with preferential procurement access.
Industry Challenges
- Polymer Science Talent Scarcity:Chemical recycling operations require expertise in catalysis and process engineering that textile regions lack.
- Multi-Certification Burden:Simultaneous pursuit of GRS, OEKO-TEX, and bluesign approvals extends product launch timelines by eight to fourteen months.
- Legacy Dyehouse Retrofit Costs:Waterless supercritical CO2 dyeing systems demand capital outlays that small-batch mills in Turkey and Bangladesh cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Fabric Market |
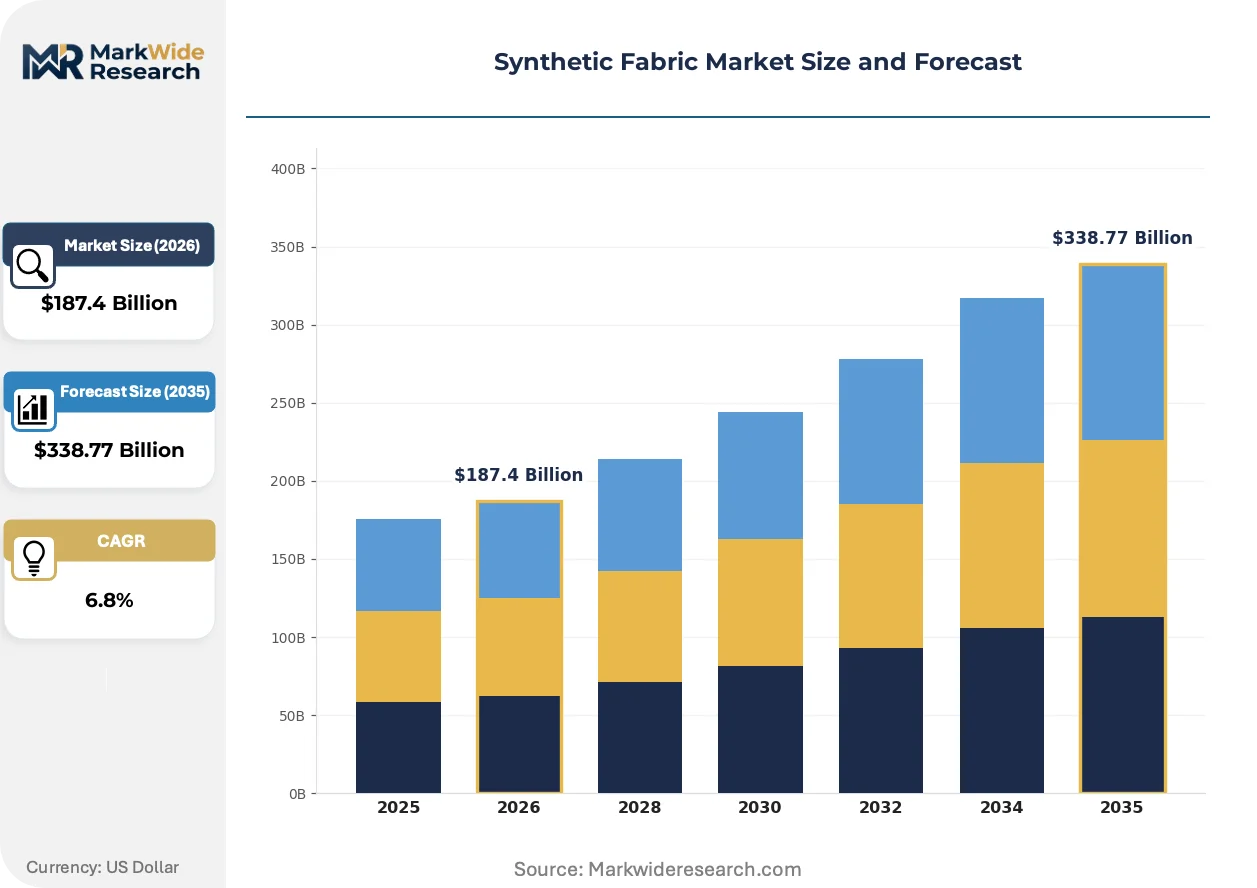
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Nylon, Acrylic, Spandex Application: Apparel, Upholstery, Industrial, Medical Feature: Moisture-Resistant, UV-Resistant, Stretchable, Breathable End User: Fashion Industry, Automotive, Healthcare, Sports |
| Companies Covered | DuPont, Toray Industries, BASF, Invista, Teijin Limited, Indorama Corporation, Reliance Industries Limited, Mitsubishi Chemical Corporation, Lenzing AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Fabric Market Emerging Trajectories
Bio-based polymer precursors, regulatory disclosure mandates, and circular procurement specifications are converging to restructure supplier qualification criteria and capital allocation across synthetic fiber value chains.
Algae-derived polyester intermediates are absorbing attention from specialty fiber divisions seeking to decouple from fossil feedstocks. Luxury fashion houses and outdoor equipment brands are piloting seaweed-based PET alternatives for capsule collections and limited technical apparel releases. This biotechnology is absorbing premium positioning that petroleum-derived fibers cannot claim, forcing conventional polymer producers to defend market access through price compression rather than sustainability credentials.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating durable water repellent chemistries from synthetic outerwear sold in the European Union. The European Chemicals Agency enforcement timeline is accelerating reformulation investments among coating suppliers and fabric finishers. Outdoor performance brands are most affected, responding with silicone-based and bio-wax alternatives that trade longevity for regulatory compliance.
Buyers are consolidating fiber procurement through direct mill relationships, bypassing traditional trader intermediaries for recycled polyester and specialty nylon. Large-scale sportswear and fast-fashion retailers are establishing multi-year offtake agreements with integrated polymer-to-yarn producers. This pattern is most visible in Vietnam and Indonesia, where vertically capable suppliers are capturing volume commitments that commodity traders previously intermediated.
Synthetic Fabric Market Segmentation
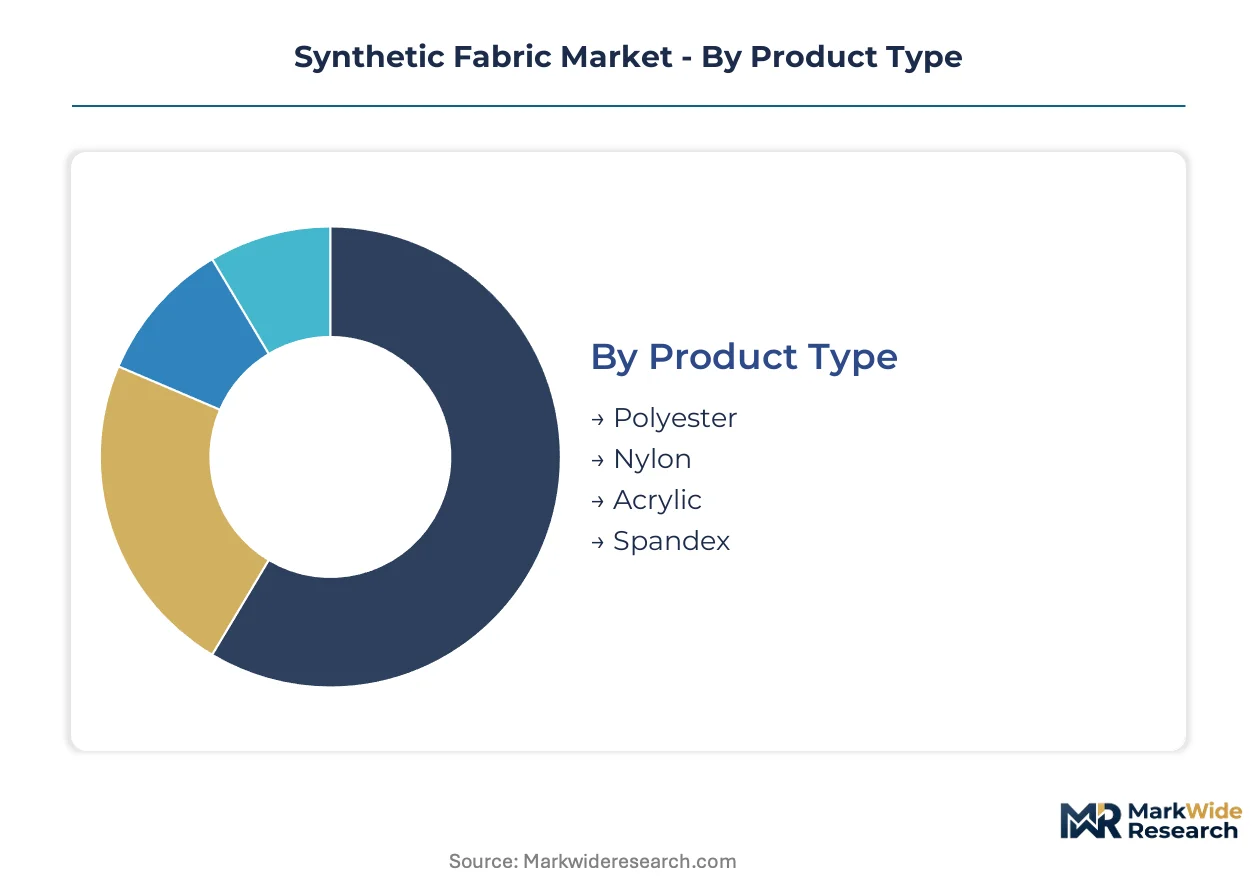
Synthetic fabric segmentation reveals how certification requirements stratify procurement decisions across fiber grades and end-use specifications. Product type and application categories carry divergent compliance burdens that reshape supplier qualification criteria and margin structures.
Product Type:
Certification intensity varies sharply across polymer chemistries, with recycled polyester demanding GRS and bluesign approvals while medical-grade nylon requires ISO 13485 and FDA 510(k) pathways. Virgin polymer producers face lighter documentation loads but heavier REACH substance scrutiny.
- Polyester:Polyethylene terephthalate fibers dominate apparel supply chains through melt-spun continuous filaments and staple variants. Fast-fashion retailers in Vietnam and Bangladesh specify recycled PET with verified mass-balance documentation to satisfy EU Green Deal disclosure rules. Mechanical recycling quality ceilings constrain closed-loop garment pathways after three thermal cycles.
- Nylon:Polyamide 6 and 6,6 variants deliver superior abrasion resistance and tenacity for performance applications. Medical antimicrobial grades are displacing cotton-linen blends in hospital linen service contracts across Germany and Japan, driven by pathogen-resistant specifications. Toray Industries leverages integrated polymer-to-fiber operations to sustain cost advantages in high-performance segments.
- Acrylic:Modacrylic and standard acrylic fibers mimic wool aesthetics at lower cost points for outerwear and furnishing applications.
- Spandex:Segmented polyurethane elastane captures disproportionate margin pools in athletic compression wear through stretch-recovery specifications.
Polyester sits at the top of the volume ranking, with nylon climbing the fastest.
Application:
End-use concentration determines capital intensity and dyehouse technology requirements, with medical and industrial applications demanding precision finishing that apparel and upholstery segments rarely require.
- Apparel:Woven and knitted constructions span fast-fashion through luxury tiers, with moisture-wicking and stretch specifications driving fiber blend decisions. Sportswear brands mandate recycled polyester with blockchain traceability for team uniforms and retail collections. EU Ecodesign digital product passport mandates reward early adopters with preferential procurement access.
- Upholstery:Heavy-duty woven and tufted constructions serve residential and contract furniture markets with flame-retardant and abrasion-resistance specifications.
- Industrial:High-tenacity filaments reinforce tires, conveyor belts, and geotextiles with strength-to-weight ratios that natural fibers cannot match.
- Medical:Antimicrobial and barrier-grade synthetics face FDA and EMA device regulations for surgical gowns, drapes, and implantable meshes. Hospital procurement committees specify pathogen-resistant synthetic blends that displace cotton-polyester mixes in surgical and patient textiles.
Apparel maintains the largest revenue footprint, though medical applications are expanding most quickly.
Feature:
Functional finishing determines chemical compliance exposure, with moisture-resistant and UV-resistant treatments facing the heaviest perfluorinated substance restrictions under REACH.
- Moisture-Resistant:Durable water repellent chemistries are reformulating under ECHA enforcement timelines eliminating PFAS from EU-sold outerwear. Silicone-based and bio-wax alternatives trade longevity for regulatory compliance.
- UV-Resistant:Titanium dioxide and benzotriazole additives protect outdoor textiles from photodegradation in marine and recreational applications.
- Stretchable:Elastane blends and mechanical stretch constructions serve activewear and fitted apparel segments.
- Breathable:Microporous membranes and moisture-vapor-transmission coatings balance waterproofing with comfort in technical outerwear.
Moisture-resistant treatments command premium positioning, with breathable constructions gaining share fastest in performance segments.
End User:
Customer procurement sophistication ranges from commodity spot purchasing in fashion to multi-year offtake agreements in automotive and healthcare.
- Fashion Industry:Fast-fashion and luxury houses consolidate fiber procurement through direct mill relationships, bypassing traditional trader intermediaries for recycled polyester. Large-scale retailers establish multi-year agreements with integrated polymer-to-yarn producers in Vietnam and Indonesia.
- Automotive:Tier-1 seating and interior suppliers specify flame-retardant polyester and nylon with IATF 16949 quality system compliance.
- Healthcare:Hospital linen service contracts and medical device manufacturers drive antimicrobial nylon specifications with FDA and EMA regulatory pathways.
- Sports:Athletic apparel brands specify recycled polyester with verified traceability for team uniforms and retail collections.
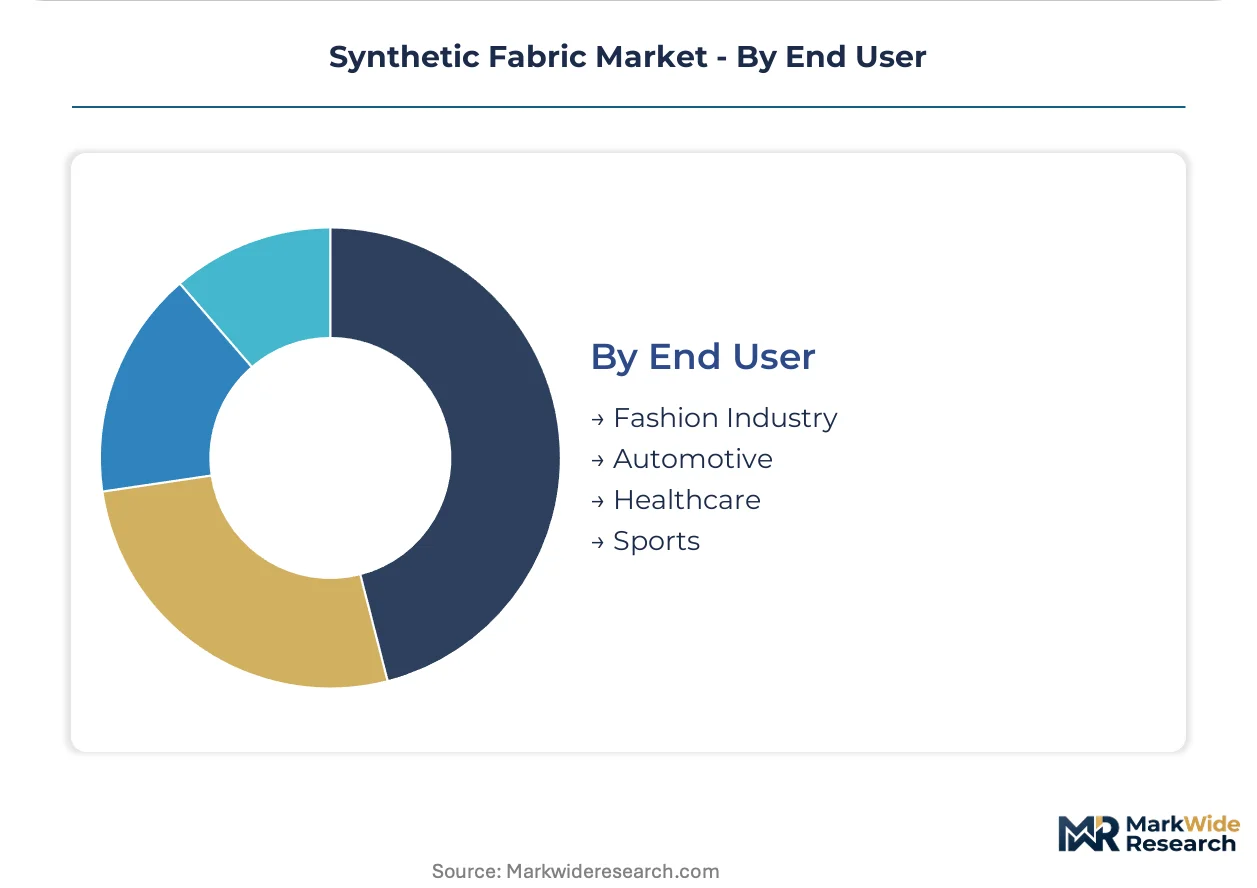
Fashion industry procurement volumes lead all end-user categories, with healthcare posting the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The synthetic fabric industry traces its modern scale to post-war polymerization advances in Germany and the United States, where petrochemical-to-fiber integration first achieved mass-market economics. Contemporary demand geography reflects this legacy while shifting toward Asian manufacturing clusters and European regulatory leadership.
China
Shaoxing and Shengze in Zhejiang Province host the world's densest concentration of polyester weaving and dyeing capacity, serving export-oriented apparel cut-make-trim operations. The MEE enforces wastewater discharge standards that elevate capital requirements for smaller mills, accelerating consolidation toward integrated producers. Jiangsu Province's chemical parks are absorbing depolymerization investments for chemically recycled PET feedstock.
United States
North Carolina's Piedmont Triad retains specialized nylon 6,6 capacity for tire cord and industrial applications, while South Carolina hosts automotive textile finishing for BMW and Volvo assembly plants. The EPA regulates antimicrobials under FIFRA for healthcare textiles, creating compliance differentiation between medical-grade and commodity producers. California's extended producer responsibility legislation is forcing brands to establish domestic collection infrastructure.
Germany
BASF's Ludwigshafen complex anchors European supply of bio-based polyamide precursors, while technical textile clusters in North Rhine-Westphalia serve automotive and industrial filtration markets. The EU Green Deal's extended producer responsibility mandates are tightening disclosure rules for textile waste, compelling reformulation of virgin polymer feedstocks. Bavaria's specialty chemical sector is piloting algae-derived polyester intermediates for luxury fashion applications.
India
Surat's power-loom sector processes the majority of domestic polyester consumption, though fragmented operations lack integrated rPET sourcing capabilities. The BIS certification framework is gradually formalizing quality standards for recycled fiber claims. Tamil Nadu's Tiruppur knitwear cluster is emerging as a testing ground for direct mill relationships with integrated polymer-to-yarn producers.
Vietnam
Ho Chi Minh City and surrounding provinces concentrate downstream demand from sportswear brands specifying recycled polyester with verified traceability. The government's industrial zone incentives are attracting filament yarn investments from regional polymer producers. Binh Duong Province is developing dyehouse capacity with waterless supercritical CO2 systems to meet EU Ecodesign compliance requirements.
Synthetic Fabric Market Vendor Landscape
Capital-heavy integrated producers compete with asset-light fiber traders and specialty compounders across distinct margin pools. The vendor base stratifies into three tiers: multinational polymer-to-fiber operators with captive petrochemical supply, regional yarn processors dependent on spot resin markets, and niche finishers commanding premiums for certified sustainable grades. Dominant competitive moves include backward integration into chemical recycling infrastructure and multi-year offtake agreements that bypass traditional trader intermediaries.
Among Asia-Pacific integrated producers, Toray Industries and Teijin Limited occupy positions exemplifying polymer-to-fiber operational control, while Indorama Corporation anchors recycled PET flake capacity across Southeast Asian supply chains. These entities represent the scale-driven archetype competing through vertical integration rather than sustainability certification premiums. BASF and DuPont sit within the specialty precursor tier, where bio-based polyamide development and high-performance polymer science differentiate positioning against commodity polyester producers.
| Leading Market Players |
|---|
| DuPont |
| Toray Industries |
| BASF |
| Invista |
| Teijin Limited |
| Indorama Corporation |
| Reliance Industries Limited |
| Mitsubishi Chemical Corporation |
| Lenzing AG |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal's extended producer responsibility mandates gate qualified supply access and premium-tier pricing power for certified recycled fiber producers, compressing margins for virgin polymer-dependent mills while rewarding blockchain-traceable supply chains with procurement preference.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the synthetic fabric market, with GRS-certified recycled polyester commanding 15-25% premiums over virgin grades and medical-grade antimicrobial nylon sitting atop the value hierarchy. Price differentiation hinges on certification intensity and volume scale, with fast-fashion retailers extracting steep discounts for multi-year offtake commitments while hospital procurement committees absorb premium pricing for pathogen-resistant specifications. Cost compression in virgin polyester intensifies as chemical recycling scale-up erodes feedstock cost advantages for mechanical recyclers. Fast-fashion retailers exhibit highest price sensitivity, whereas healthcare and outdoor performance brands prioritize compliance and functional specifications over unit economics.
Supply Chain Analysis
Post-consumer textile collection and sorting infrastructure—reverse-logistics flows from garment take-back programs through depolymerization facilities—concentrates capacity in Northern Europe and East Asia, leaving India and Southeast Asia supply-constrained for rPET feedstock. Primary manufacturing gravity centers on China, Vietnam, and Bangladesh, with Shaoxing's dyeing clusters and Ho Chi Minh City's sportswear assembly operations anchoring downstream output. Raw material dependencies rest on paraxylene and purified terephthalic acid from petrochemical refineries, bio-based polyamide precursors from European specialty chemical producers, and algae-derived polyester intermediates from pilot-scale biotechnology operations. Single-source vulnerability in chemical recycling catalyst supply threatens capacity expansion timelines. Distribution runs through direct mill relationships that displace traditional fiber traders, with integrated polymer-to-yarn producers capturing volume commitments from consolidated retail procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The synthetic fabric market reads as a late-cycle quality story, with hospital linen service contracts and EU Ecodesign mandates shifting procurement toward antimicrobial nylon and blockchain-traceable recycled polyester specifications that reward technical differentiation over commodity scale.
For Market Incumbents: Deploy chemical recycling capacity additions in Jiangsu Province and North Rhine-Westphalia to secure feedstock independence before mechanical recycling quality ceilings constrain closed-loop pathways. BASF and Toray Industries should deepen backward integration into bio-based polyamide precursors to defend margin position against algae-derived polyester challengers, while accelerating bluesign and OEKO-TEX certification timelines to capture EU Green Deal procurement preference. For New Entrants and Emerging Players: Algae-derived polyester intermediates offer technology-first entry into luxury fashion capsule collections where petroleum-derived fibers cannot claim sustainability positioning. India's fragmented Surat power-loom sector presents the most penetrable geography, with regional flake-to-fiber operators able to establish integrated rPET sourcing ahead of formalizing BIS standards. Target direct mill relationships with Tiruppur knitwear clusters, bypassing trader intermediaries through blockchain-traceable supply chain documentation. For Investors and Strategic Acquirers: Roll-up economics work for regional yarn processors with dyehouse assets in Vietnam and Indonesia because EU Ecodesign compliance requirements are forcing consolidation toward waterless supercritical CO2-capable facilities. Mid-term viability over the next decade hinges on exposure to medical antimicrobial applications and certified recycled fiber supply chains. Monitor ECHA enforcement timelines for perfluorinated substance restrictions and California extended producer responsibility implementation as inflection indicators for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Scale-Up | Depolymerization investments in Jiangsu Province convert colored PET waste into virgin-quality resin for textile-grade filament production. |
| Backward Integration into Bio-Based Precursors | BASF's Ludwigshafen complex anchors European supply of polyamide intermediates that decouple from fossil feedstock volatility. |
| Certification Acceleration | Simultaneous GRS and bluesign approvals compress product launch timelines and unlock EU Green Deal procurement preference. |
| Direct Mill Relationship Expansion | Multi-year offtake agreements with integrated polymer-to-yarn producers in Vietnam displace traditional fiber trader intermediation. |
| Waterless Dyehouse Retrofit | Supercritical CO2 systems in Binh Duong Province meet EU Ecodesign wastewater standards that smaller Turkish and Bangladeshi mills cannot finance. |
Methodological Framework
Bottom-up apparel and medical textile modeling reconciled against top-down polymer feedstock and chemical recycling capacity tracking forms the analytical core of this study. Primary interviews with plant managers at integrated fiber producers, procurement leads at sportswear and fast-fashion retailers, technical R&D directors at specialty chemical divisions, and hospital purchasing committee members informed demand-side assumptions. Secondary validation drew from customs and trade data, SEC filings of listed polymer producers, ECHA REACH restriction announcements, and EU Green Deal implementation guidance documents.
Historical trendline analysis across polymer price cycles, certification adoption curves, and regional manufacturing capacity expansions established baseline growth patterns. The forecast framework models segmentation across fiber chemistry, end-use application, functional finishing, and procurement sophistication tiers, with CAGRs derived from elasticity-adjusted demand projections and supply-side capacity absorption rates. Key inputs include paraxylene-PTA spread dynamics, chemical recycling yield assumptions, and EU Ecodesign digital product passport compliance timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to chemical recycling catalyst availability and bio-based precursor cost curves. Practitioners should monitor ECHA PFAS enforcement actions, California textile EPR rulemaking, and algae-derived polyester pilot-scale yields for early signals of supply chain restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Nanofibers Market
Synthetic Fibers
High End Synthetic Suede Market
Synthetic Fibers
South Korea Textile Market
Synthetic Fibers
Nylon Fibers Market
Synthetic Fibers
Staple Fibers Market
Synthetic Fibers
Spandex Fiber Market
Synthetic Fibers
Middle-East and Africa Aramid Fiber Market
Synthetic Fibers
Asia-Pacific Lyocell Fibers Market
Synthetic Fibers
High Temperature Fiber Market
Synthetic Fibers
North America High Performance Fibers Market
Synthetic Fibers
Polyester Straps Market
Synthetic Fibers
Polyolefin Fiber Market
Synthetic Fibers
Para-Aramid Fibers Market
Synthetic Fibers
Americas Spandex Market
Synthetic Fibers
Blended Fibers Market
Synthetic Fibers
Synthetic Fiber Market