
 Performance Fabric Market | 2026-2036
Performance Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Performance Fabric Market Intelligence
Aftermarket technical service revenue is narrowing as original equipment manufacturers embed predictive maintenance into coated fabric supply agreements. Teijin Limited leverages its aramid fiber vertical to dominate aerospace-grade performance textiles. DuPont de Nemours, Inc. anchors its position through Kevlar brand strength in industrial protective applications. Toray Industries, Inc. specializes in carbon fiber reinforced fabrics for structural composites.
Performance fabrics are engineered textiles combining synthetic polymers, natural fibers, and functional coatings to achieve specified tensile strength, thermal resistance, and moisture vapor transmission rates for demanding end-uses. Coated fabrics command premium margins due to multi-layer lamination complexity and barrier property requirements. Woven fabrics occupy the largest volume share across sports apparel and workwear applications where dimensional stability matters. Non-woven fabrics represent the fastest-growing product category in filtration and medical textile adjacencies.
EPA chemical safety assessments and REACH substance restrictions constrain fluorinated water-repellent chemistry choices across the United States and Europe. ISO 9001 quality management and OEKO-TEX Standard 100 certification govern market access for suppliers serving branded apparel manufacturers. Stakeholders must monitor bio-based polymer scalability and regional carbon border adjustment mechanisms to secure feedstock positioning.
Market Dynamics
REACH substance restrictions and EPA chemical safety assessments are forcing wholesale reformulation of fluorinated water-repellent chemistries across branded apparel supply chains.
Growth Catalysts
- Moisture-wicking synthetics:Athletic wear manufacturers in China are scaling technical textile procurement for high-output activity segments. Domestic sportswear brands drive volume expansion.
- Carbon fiber reinforcement:Aerospace and automotive structural composites demand is pulling through advanced woven and non-woven fabric categories. Toray Industries anchors supply security in this segment.
- REACH compliance certification:European material certification requirements are creating tiered access for OEKO-TEX Standard 100 holders. ISO 9001 quality management gates are tightening for non-compliant suppliers.
Market Restraints
- Petrochemical feedstock volatility:Synthetic polymer input costs fluctuate with crude oil derivatives and regional refinery capacity constraints. Margin compression hits coated fabric producers hardest.
- Aramid fiber supply concentration:Teijin Limited's vertical control over aerospace-grade fiber creates single-source risk for protective textile manufacturers. Alternative aramid suppliers lack comparable performance certification.
- Fluorinated chemistry substitution timeline:Bio-based water-repellent alternatives face performance gaps in extreme weather applications. EPA assessments extend approval cycles for new chemistries.
Strategic Opportunities
- Medical textile adjacencies:Non-woven filtration fabrics represent underpenetrated demand in surgical gown and barrier protection markets. ISO 13485 certification opens hospital procurement channels.
- EU Green Deal alignment:Carbon border adjustment mechanisms favor regional feedstock positioning for European suppliers. Bio-based polymer scalability determines long-term quota access.
- Predictive maintenance embedding:Coated fabric supply agreements are integrating sensor-enabled lifecycle monitoring. OEMs capture aftermarket service revenue previously held by technical service providers.
Industry Challenges
- Multi-layer lamination expertise:Coated fabric production requires specialized technicians for barrier property calibration. Talent scarcity constrains capacity expansion at mid-tier manufacturers.
- Dual certification timelines:Simultaneous EPA and REACH compliance extends product launch cycles by 18-24 months. Testing backlogs at accredited laboratories create queue bottlenecks.
- Legacy dyeing equipment retrofit:Waterless and supercritical CO2 dyeing adoption demands capital-intensive machinery replacement. Smaller woven fabric producers face stranded asset risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Performance Fabric Market |
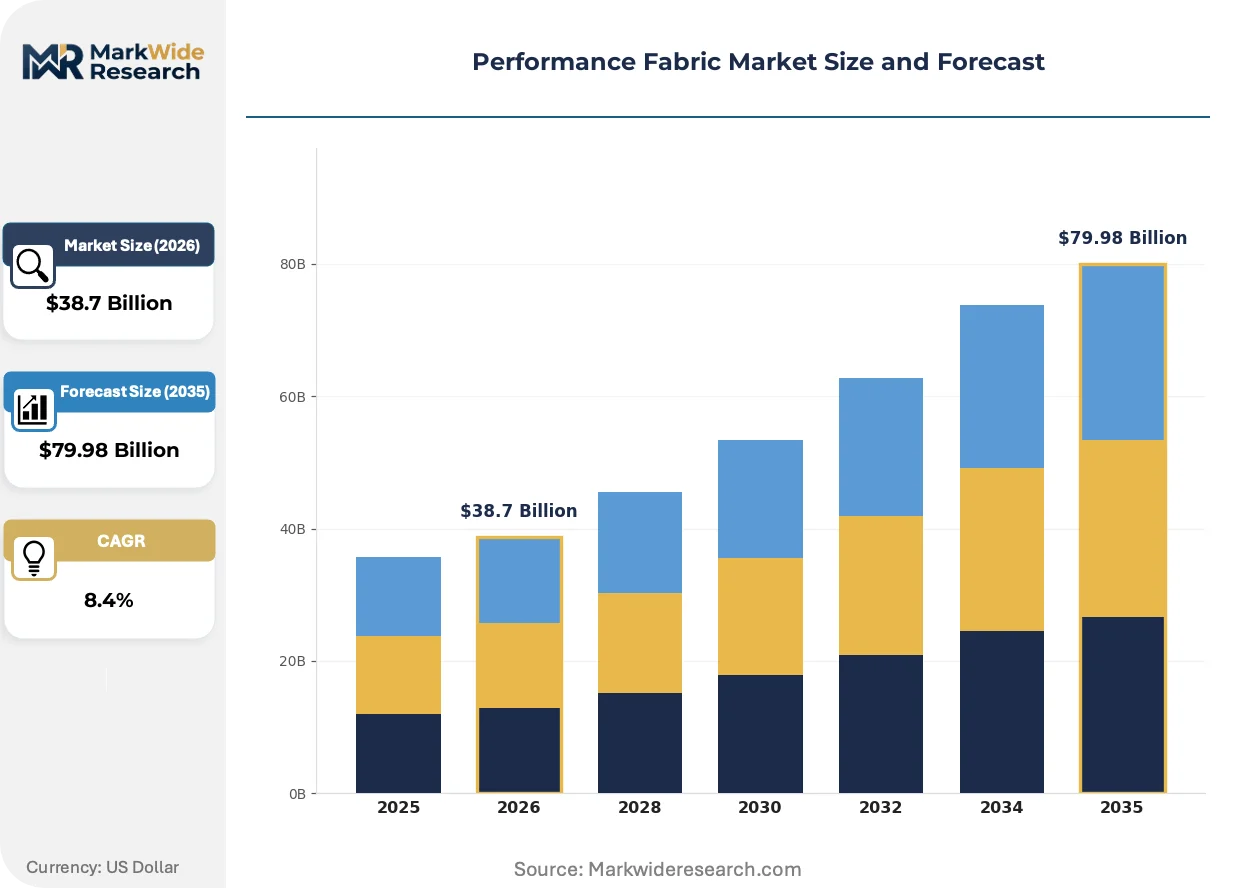
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Fabrics, Non-Woven Fabrics, Knitted Fabrics, Coated Fabrics End User: Athletic Wear, Outdoor Gear, Upholstery, Industrial Applications Feature: Moisture-Wicking, Breathable, UV Resistant, Stretchable Application: Sports Apparel, Workwear, Fashion, Home Textiles |
| Companies Covered | Teijin Limited, INVISTA Holdings, LLC, DuPont de Nemours, Inc., Owens Corning, Milliken & Company, Toray Industries, Inc., Hexcel Corporation, BASF SE, Royal TenCate N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Performance Fabric Market Strategic Shifts & Innovations
Digital twin technology is virtualizing fabric performance testing protocols before physical prototyping. This compression of development cycles is redrawing competitive boundaries between technical textile suppliers.
Recycled polyethylene terephthalate (rPET) fiber processing is virtualizing virgin polymer demand in sportswear applications. Major athletic brands now mandate post-consumer recycled content thresholds in supplier contracts. The structural consequence is a bifurcation between rPET-capable mills and conventional producers locked into fossil-based feedstocks.
EPA chemical safety assessments under the Toxic Substances Control Act are narrowing fluorinated chemistry options for water-repellent finishes. Industrial protective applications face reformulation mandates that degrade legacy performance specifications. DuPont's Kevlar brand strength provides regulatory navigation support for affected industrial buyers.
Direct-to-brand technical textile procurement is displacing traditional distributor intermediaries in Asia-Pacific supply chains. Chinese domestic sportswear manufacturers now source coated and woven fabrics through dedicated mill relationships. This channel compression concentrates volume with vertically integrated suppliers possessing in-house lamination and finishing capabilities.
Performance Fabric Market Segmentation
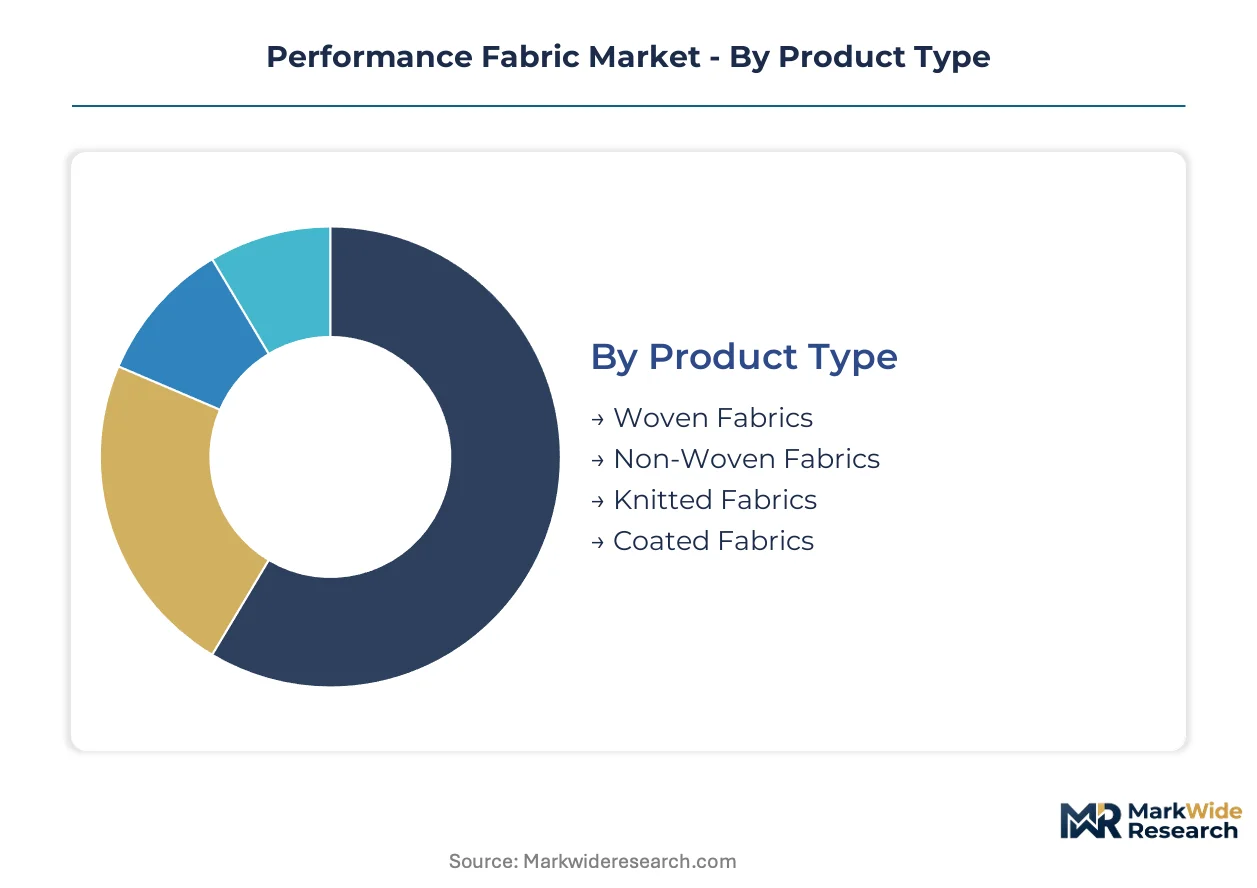
Performance fabric segmentation reveals how technical specifications map to distinct value chains. Material construction, end-use durability requirements, and functional coatings determine procurement patterns across branded apparel and industrial buyers.
Product Type:
Use-case spectrum spans from structural load-bearing textiles to disposable barrier materials, with lamination complexity driving margin differentiation.
- Woven Fabrics:Interlaced warp and weft construction delivers dimensional stability under mechanical stress. Sports apparel and workwear manufacturers in China specify high-tenacity polyester and nylon weaves for abrasion resistance. REACH compliance certification gates European access for woven suppliers serving branded athletic labels.
- Coated Fabrics:Multi-layer lamination of polymer films onto textile substrates creates barrier properties against liquids, chemicals, and gases. Aerospace and automotive structural composites demand coated aramid and carbon fiber prepregs from Toray Industries and Teijin Limited. Barrier calibration expertise concentrates capacity among specialized technicians.
- Non-Woven Fabrics:Bonded fiber webs without yarn interlacing enable rapid production of filtration and medical barrier textiles.
- Knitted Fabrics:Loop-based construction provides inherent stretch recovery for form-fitting athletic applications.
The dominant share belongs to Woven Fabrics, while Non-Woven Fabrics is closing the gap fastest.
End User:
Customer archetypes range from high-frequency replacement cycles in consumer apparel to decade-long procurement contracts in industrial safety.
- Athletic Wear:Moisture-wicking synthetic blends dominate high-output activity segments where sweat management affects performance. Chinese domestic sportswear brands scale technical textile procurement through direct mill relationships, bypassing traditional distributor channels. EPA chemical safety assessments constrain fluorinated water-repellent chemistry choices for outdoor athletic applications.
- Industrial Applications:Flame-resistant and cut-protective textiles serve manufacturing, oil and gas, and electrical utility sectors. DuPont's Kevlar brand anchors industrial protective specifications where regulatory reformulation support matters. ISO 9001 quality management certification gates supplier qualification for corporate safety programs.
- Outdoor Gear:Weather-resistant laminates for tents, backpacks, and technical shells face bio-based chemistry substitution timelines.
- Upholstery:Stain-resistant and durable textiles serve commercial furniture and automotive interior contracts.
Athletic Wear commands the largest procurement volume, with Industrial Applications expanding most quickly on safety regulation tightening.
Feature:
Functional performance attributes determine specification sheets and testing protocols across end-use categories.
- Moisture-Wicking:Engineered synthetic fibers with modified cross-sections transport perspiration from skin to outer surface through capillary action. Athletic wear manufacturers mandate this specification for base layer and training apparel. rPET fiber processing is displacing virgin polymer demand in moisture-wicking sportswear applications.
- Stretchable:Elastane blends and mechanical knit structures enable freedom of movement for activewear and workwear. Yoga and compression garment segments specify stretch recovery standards. Bio-based spandex alternatives face performance gaps in extreme elongation applications.
- Breathable:Microporous membranes and hydrophilic coatings allow water vapor transmission while blocking liquid water.
- UV Resistant:Additives and fiber modifications block ultraviolet radiation for outdoor and occupational applications.
Moisture-Wicking holds the specification frequency lead, though Stretchable is gaining share fastest on athleisure category expansion.
Application:
Downstream use cases segment by durability requirements, aesthetic priorities, and regulatory exposure.
- Sports Apparel:Performance-oriented garments combining multiple functional attributes for competitive and recreational athletes. Major athletic brands now mandate post-consumer recycled content thresholds in supplier contracts. Direct-to-brand procurement concentrates volume with vertically integrated mills.
- Workwear:Occupational garments meeting ANSI, OSHA, and industry-specific safety standards for hazard protection. Industrial laundries specify colorfastness and dimensional stability for high-cycle maintenance. Dual certification timelines for EPA and REACH compliance extend product launch cycles.
- Fashion:Aesthetic-driven adoption of technical fabrics for luxury and contemporary apparel.
- Home Textiles:Performance bedding, curtains, and upholstery with antimicrobial or easy-clean properties.
Sports Apparel maintains the application volume lead, while Workwear is climbing the fastest on safety regulation expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China absorb price premiums for aerospace-grade aramid prepregs without elasticity, while European apparel brands enforce strict cost discipline on commodity synthetics. This demand-elasticity contrast separates procurement strategies across major consuming regions.
United States
Industrial protective textile procurement from DuPont's Kevlar-centric supply chains dominates domestic offtake. EPA chemical safety assessments under TSCA constrain fluorinated water-repellent chemistry approvals, extending reformulation timelines for outdoor gear manufacturers. Technical textile clusters in North Carolina and South Carolina concentrate military and aerospace composite fabrication capacity.
China
Domestic sportswear brands scale moisture-wicking synthetic procurement through direct mill relationships, bypassing distributor intermediaries. MIIT industrial policy prioritizes carbon fiber self-sufficiency under dual carbon goals, redirecting state support toward Toray-competing domestic producers. Yangtze River Delta technical textile mills embed predictive maintenance sensors into coated fabric supply agreements for automotive OEMs.
Germany
Automotive structural composite demand pulls carbon fiber reinforced fabrics through Toray's European supply channels. REACH substance restrictions enforce OEKO-TEX Standard 100 certification gates for apparel suppliers serving branded athletic labels. Baden-Württemberg industrial clusters anchor aerospace prepregs manufacturing alongside automotive tier-1 integration.
Japan
Carbon fiber and aramid fiber vertical integration concentrates aerospace-grade output under Toray Industries and Teijin Limited control. METI industrial standards govern high-performance textile export certification protocols. Nagoya and Tokyo metropolitan areas host structural composite R&D facilities serving Boeing and Airbus supply chains.
India
Technical textile procurement for industrial protective applications expands on tightening factory safety regulations. BIS certification requirements create compliance thresholds for imported coated fabrics serving infrastructure and defense sectors. Gujarat and Maharashtra textile clusters scale woven fabric finishing capacity for workwear export contracts.
Performance Fabric Market Key Industry Players
Capability concentration sits with integrated fiber-to-fabric specialists; scale advantage sits with diversified chemical conglomerates with polymer feedstock positions. The market structures around three tiers: aramid and carbon fiber verticals commanding aerospace premiums, synthetic polymer specialists serving athletic apparel volume, and regional coating laminators capturing industrial protective contracts. Dominant competitive moves include backward integration into polymer feedstocks and geographic expansion through technical licensing arrangements.
Within the fiber vertical tier, Teijin Limited and Toray Industries exemplify integrated aramid and carbon fiber control. DuPont de Nemours, Inc. occupies a position as a Kevlar-brand industrial protective anchor. These three represent distinct archetypes: Japanese fiber-to-fabric integration, American brand-centric industrial specification, and diversified chemical portfolio scale.
| Leading Market Players |
|---|
| Teijin Limited |
| INVISTA Holdings, LLC |
| DuPont de Nemours, Inc. |
| Owens Corning |
| Milliken & Company |
| Toray Industries, Inc. |
| Hexcel Corporation |
| BASF SE |
| Royal TenCate N.V. |
| Others |
Cost & Logistics Intelligence
Overcapacity in China's Yangtze River Delta woven fabric mills compresses spot pricing for commodity synthetics while simultaneously elevating premiums for REACH-certified coated fabrics. This utilization divergence concentrates supplier bargaining power among aramid and carbon fiber specialists while squeezing mid-tier laminators dependent on petrochemical feedstock volatility.
Pricing Analysis
Aftermarket technical service revenue embedded in coated fabric supply agreements drives lifetime value for aerospace and automotive OEM contracts. Three-tier pricing structure across premium, standard, and economy levels separates OEKO-TEX Standard 100 certified mills from conventional producers, with brand-certified athletic wear manufacturers showing least price sensitivity and industrial protective buyers facing margin pressure from reformulation costs.
Supply Chain Analysis
Export-control regimes limiting carbon fiber and aramid technology transfers constrain supply security for aerospace-grade prepregs outside Japan and the United States. China, Japan, and Germany anchor production capacity, with synthetic polymer inputs drawing from regional petrochemical complexes and specialized lamination equipment sourcing from German and Italian machinery builders. Single-source vulnerability concentrates in Teijin's aerospace fiber vertical, while distribution runs through direct mill relationships displacing traditional distributor channels in Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Chinese domestic sportswear manufacturers consolidate procurement through direct mill relationships, bypassing intermediaries and extracting volume discounts from mid-tier suppliers.
For Market Incumbents: Insulate aerospace-grade aramid and carbon fiber positions through backward integration into polymer feedstocks and captive prepreg manufacturing. Expand ISO 13485 certification capacity to capture hospital procurement channels in medical textile adjacencies before regulatory timelines extend further.
For New Entrants and Emerging Players: Build out bio-based water-repellent chemistry capabilities targeting outdoor gear reformulation mandates, where performance gaps in extreme weather applications create white-space for EPA-compliant alternatives. Pursue direct-to-brand technical licensing arrangements with Chinese sportswear manufacturers seeking REACH certification without European mill premiums.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among coated fabric suppliers embedding predictive maintenance sensors into automotive OEM supply agreements. Long-term viability favors acquisition targets with in-house lamination expertise and OEKO-TEX certification, with signal to watch being MIIT policy acceleration of domestic carbon fiber self-sufficiency redirecting state support away from import-dependent processors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstocks | Captive supply of rPET and bio-based polymers secures margin protection against petrochemical volatility. |
| REACH and OEKO-TEX Certification Investment | European market access gates tighten as dual certification timelines extend product launch cycles. |
| Predictive Maintenance Sensor Embedding | OEMs capture aftermarket service revenue previously held by independent technical service providers. |
| Direct-to-Brand Mill Relationships | Chinese sportswear manufacturers consolidate procurement volume with vertically integrated suppliers. |
| Bio-Based Water-Repellent Chemistry Scale-Up | EPA fluorinated chemistry restrictions force reformulation mandates across outdoor athletic applications. |
Research Approach
The analysis maps woven, coated, non-woven, and knitted fabric sub-sectors, each validated through technical textile procurement directors, plant managers at laminating facilities, and regulatory compliance officers. Primary interviews with OEM sourcing leads and channel distribution partners combined with customs trade data, SEC filings of diversified chemical conglomerates, and OEKO-TEX certification registries enabled bottom-up and top-down triangulation.
Assumptions held fixed include REACH substance restriction timelines and EPA chemical safety assessment protocols, while variables included rPET fiber processing adoption rates and carbon border adjustment mechanism implementation across the analysis window. Segmentation by product construction, end-use durability requirements, and functional coating attributes modeled volume and value outputs, with CAGRs derived from regression against industrial production indices and athletic apparel consumption patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-supported Chinese carbon fiber producers would shift outcomes. Material shifts in fluorinated chemistry approval timelines or bio-based polymer scalability breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Para-Aramid Fibers Market
Synthetic Fibers
Polyester Tire Cord Fabrics Market
Synthetic Fibers
US Textile Market
Synthetic Fibers
Europe Nanofiber Market
Synthetic Fibers
Polymer Nanofiber Market
Synthetic Fibers
Polyolefin Fiber Market
Synthetic Fibers
Polybenzoxazole Fibers Market
Synthetic Fibers
Bio-Based Elastic Core-Spun Yarn for Denim Stretch Market
Synthetic Fibers
Polyimide Fiber Market
Synthetic Fibers
Global High Performance Fibers Market
Synthetic Fibers
Polyester Straps Market
Synthetic Fibers
Synthetic Fiber Market
Synthetic Fibers
Polyethylene Terephthalate (PET) Fiber Market
Synthetic Fibers
Anti-Static Fibers Market
Synthetic Fibers
High Performance Polyester Market
Synthetic Fibers
Kevlar Fiber Market