
 Nylon Tire Cord Fabrics Market | 2026-2036
Nylon Tire Cord Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Nylon Tire Cord Fabrics Market Analytics
Consolidation among passenger vehicle tire OEMs is restructuring supply chain leverage toward tier-one cord fabric suppliers. Hyosung Advanced Materials leverages its integrated nylon-6,6 polymer-to-fabric verticality to secure multi-year contracts with Korean and Chinese tire makers. Kordsa Teknik Tekstil A.S. anchors its position through R&D intensity in adhesion chemistry for high-performance radial constructions. SRF Ltd. competes on manufacturing scale at its Chennai and Gummidipoondi facilities, supplying domestic Indian tire producers with cost-optimized medium-tenacity grades.
Nylon tire cord fabrics are high-strength woven or braided textile reinforcements composed of polyamide-6 or polyamide-6,6 filaments, typically engineered with twist levels between 200 and 400 turns per meter and dip-coated with resorcinol-formaldehyde-latex (RFL) to ensure rubber adhesion in tire carcass plies. Their primary industrial purpose is to provide dimensional stability, fatigue resistance, and structural integrity to pneumatic tires under cyclic loading and thermal stress. High-tenacity product grades command the dominant margin pool as radial tire specifications tighten for passenger and commercial vehicle durability standards, while specialty blends incorporating aramid or hybrid filaments represent the fastest-growing niche for aircraft and off-road tire segments. Application demand in radial tires leads volume absorption, whereas retreaded tire applications remain structurally constrained by shorter cord life expectations and lower performance thresholds.
EPA emission standards for tire rolling resistance in the United States and REACH chemical registration requirements in Europe compel fabric producers to reformulate dip chemistries and validate alternative adhesion systems. India's BIS certification mandates for automotive textiles and China's GB standards for tire reinforcement materials create divergent compliance pathways that fragment quality assurance protocols across export destinations. Stakeholders must monitor regulatory divergence in chemical substance restrictions and carbon intensity disclosure rules to preempt supply chain qualification disruptions.
Market Dynamics
OEM tire manufacturers are consolidating procurement contracts around fewer approved suppliers while REACH compliance and EU Green Deal carbon-border adjustments raise material traceability requirements for European-bound exports.
Growth Catalysts
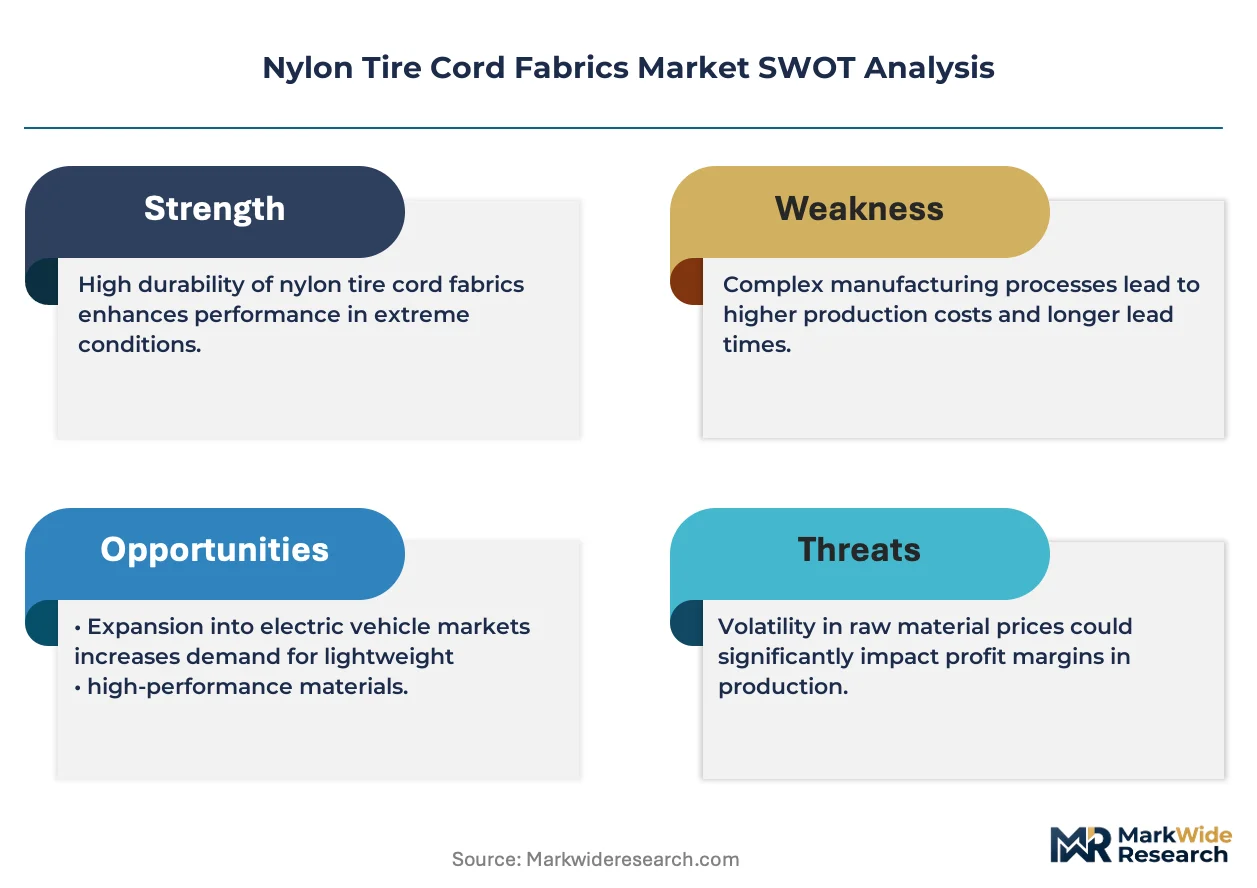
- Radial tire specification tightening:Passenger and commercial vehicle durability standards are elevating high-tenacity grade absorption across replacement and original equipment channels.
- India's PLI scheme for automotive textiles:Domestic tire production capacity scaling serves both local vehicle assembly and export markets, concentrating regional demand.
- RFL dip chemistry advancement:Resorcinol-formaldehyde-latex adhesion systems are improving fatigue resistance under cyclic loading conditions in tire carcass plies.
Market Restraints
- Caprolactam price volatility:Nylon-6,6 polymer feedstock costs fluctuate with benzene and cyclohexane supply disruptions, compressing fabric producer margins.
- REACH chemical registration friction:European-bound exports face extended validation timelines for alternative adhesion systems, fragmenting compliance pathways.
- Aramid hybrid substitution:Aircraft and off-road tire segments are migrating toward specialty blends incorporating aramid filaments for extreme thermal stress performance.
Strategic Opportunities
- Retreaded tire cord life extension:Shorter cord life expectations in retread applications create white space for medium-tenacity grade innovation with enhanced fatigue cycling.
- Carbon intensity disclosure alignment:EU Green Deal carbon-border adjustments reward producers with verified supply chain emissions tracking and polymer-to-fabric traceability.
- Hybrid filament convergence:Combining polyamide-6,6 with bio-based polyamides opens aircraft tire segments seeking weight reduction without sacrificing dimensional stability.
Industry Challenges
- Dip chemistry reformulation talent scarcity:EPA emission standards for tire rolling resistance require adhesion specialists capable of validating alternative resorcinol-formaldehyde-latex substitutes.
- Multi-jurisdiction certification timelines:India's BIS certification mandates for automotive textiles and China's GB standards for tire reinforcement materials create divergent quality assurance protocols.
- Legacy RFL system integration:Existing production lines require capital-intensive retrofitting to accommodate low-emission dip chemistries without throughput degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nylon Tire Cord Fabrics Market |
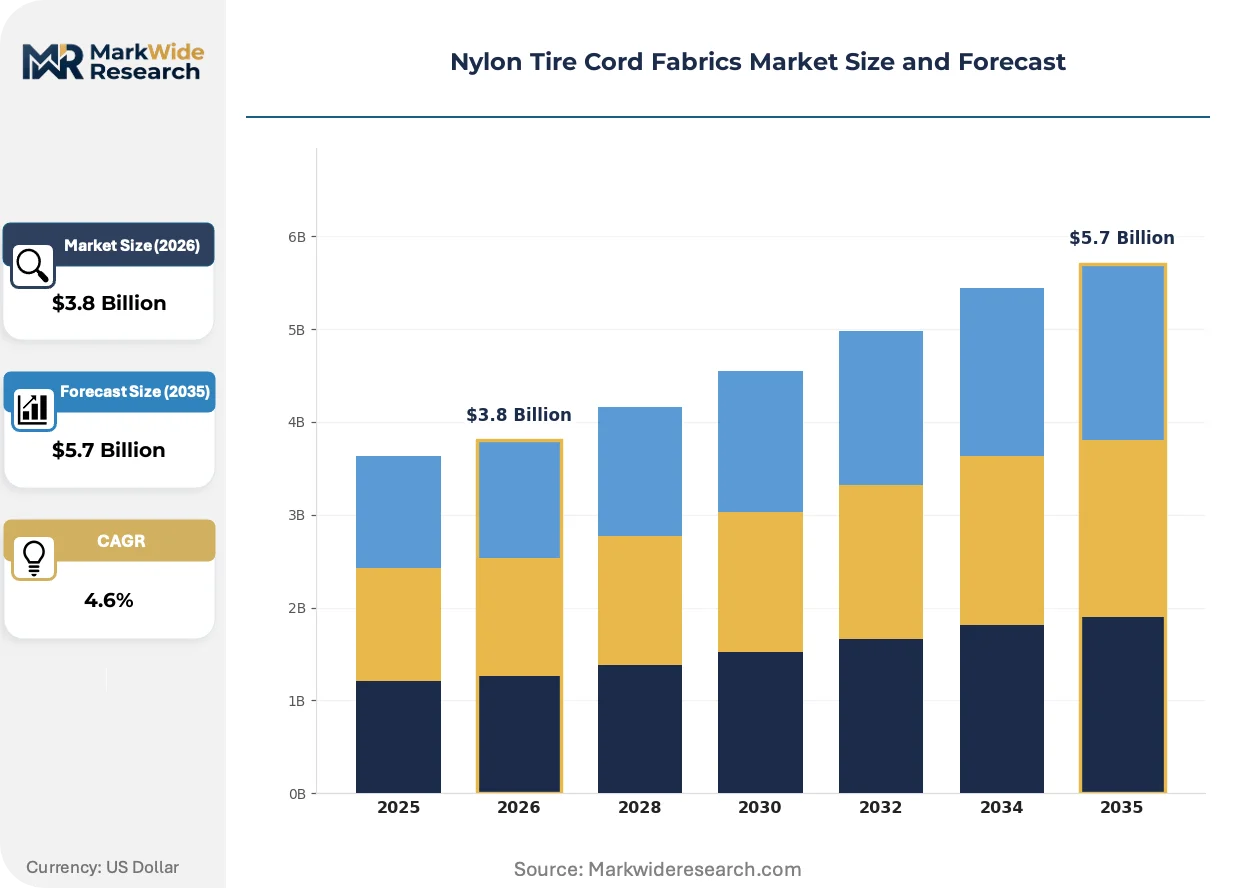
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Tenacity, Medium Tenacity, Low Tenacity, Specialty Blend End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Industrial Machinery Manufacturing Process: Weaving, Knitting, Braiding, Non-Woven Application: Radial Tires, Bias Tires, Specialty Tires, Retreaded Tires |
| Companies Covered | Hyosung Advanced Materials, Kordsa Teknik Tekstil A.S., Teijin Limited, SRF Ltd., Kolon Industries, Indorama Ventures, DuPont, Toray Industries, Century Enka Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nylon Tire Cord Fabrics Market Evolving Landscape
Adhesion chemistry innovation and procurement consolidation are restructuring how tire cord fabric producers qualify for multi-year supply contracts with tier-one tire manufacturers.
Hybrid aramid-nylon cord constructions are overtaking pure polyamide reinforcements in aircraft and heavy off-road tire specifications. Boeing and Airbus tire suppliers specify these blends for landing gear applications requiring extreme thermal shock resistance. The technology is overtaking conventional high-tenacity nylon in premium radial segments where durability premiums justify material cost differentials.
REACH authorization requirements for resorcinol and formaldehyde derivatives are compelling fabric producers to reformulate dip chemistries before sunset dates. ECHA's candidate list expansion forces validation of phenol-free or reduced-formaldehyde adhesion systems. European tire exporters are accelerating supplier audits to ensure polymer-to-fabric traceability documentation meets carbon-border adjustment verification protocols.
Buyer concentration among Korean and Chinese tire makers is compressing supplier qualification cycles from multi-year evaluations to accelerated pilot programs. Tier-one cord fabric producers now face direct technical collaboration requirements with OEM R&D centers rather than arm's-length specification compliance. This pattern concentrates most visibly in India where domestic tire capacity expansion demands rapid supplier onboarding with localized technical service capabilities.
Nylon Tire Cord Fabrics Market Segmentation
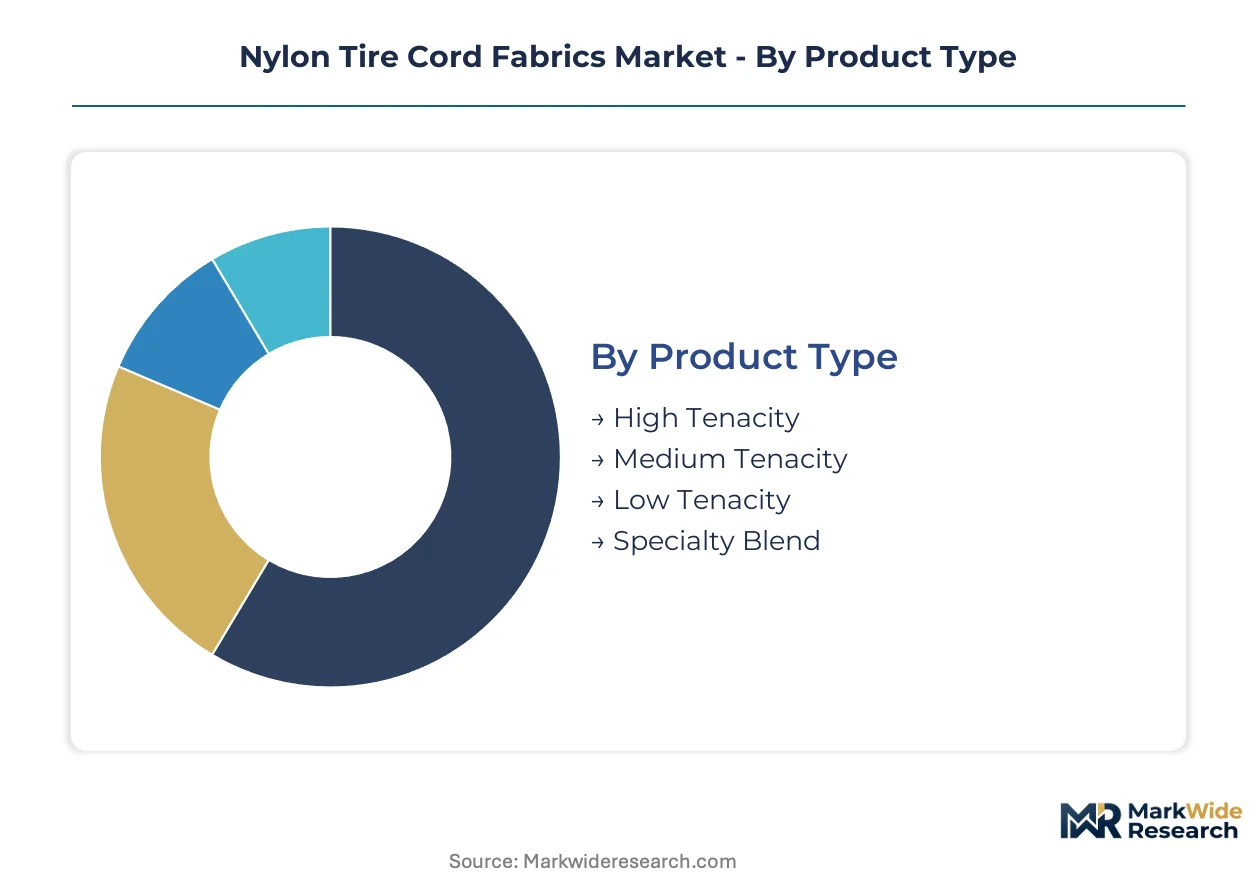
Nylon tire cord fabric producers configure product portfolios around tenacity grades and adhesion specifications that align with radial tire OEM qualification protocols. Procurement consolidation among tire makers rewards suppliers with manufacturing scale across multiple segment categories.
Product Type:
Supply concentration in high-tenacity grades reflects radial tire OEM procurement consolidation around fewer approved suppliers with proven fatigue resistance validation.
- High Tenacity:Engineered with twist levels between 200 and 400 turns per meter and dip-coated with resorcinol-formaldehyde-latex for rubber adhesion. Demand concentrates in passenger and commercial vehicle radial tires as durability standards tighten across replacement and original equipment channels.
- Specialty Blend:Hybrid constructions incorporating aramid or bio-based polyamide filaments for aircraft and off-road tire segments. Boeing and Airbus tire suppliers specify these blends for landing gear applications requiring extreme thermal shock resistance.
- Medium Tenacity:Cost-optimized grades serving domestic Indian tire producers from Chennai and Gummidipoondi manufacturing clusters.
- Low Tenacity:Entry-level reinforcement for bias-ply and retreaded tire applications with shorter cord life expectations.
Today's leader: High Tenacity. Tomorrow's challenger: Specialty Blend.
End User:
Application demand from passenger vehicle radial tires absorbs the dominant volume share as OEMs consolidate procurement contracts around multi-year supplier agreements.
- Passenger Vehicles:Radial tire specifications for sedans and SUVs drive absorption of high-tenacity grades with validated fatigue cycling performance under cyclic loading conditions.
- Commercial Vehicles:Heavy truck and bus tires require enhanced dimensional stability for extended mileage warranties, concentrating procurement with tier-one cord fabric suppliers.
- Two-Wheelers:Bias-ply dominant construction in emerging markets sustains medium-tenacity grade demand.
- Industrial Machinery:Off-the-road tires for mining and construction equipment specify specialty aramid-nylon hybrids for extreme thermal stress performance.
Passenger Vehicles anchor current procurement volumes. Commercial Vehicles are climbing the fastest as fleet operators extend replacement cycles.
Manufacturing Process:
Weaving dominates output volumes given established RFL dip chemistry integration lines, though braiding gains traction in aircraft tire specifications.
- Weaving:Conventional plain and twill weaves with post-dip RFL treatment serve standard radial and bias tire carcass plies.
- Braiding:Circular braiding configurations optimize fatigue resistance for aircraft tire beads and high-performance radial segments.
- Knitting:Warp-knitted structures for specialty tire applications requiring enhanced elongation recovery.
- Non-Woven:Emerging needle-punched formats for experimental tire reinforcement and industrial textile applications.
Weaving retains process dominance. Braiding shows the steepest expansion trajectory in premium specifications.
Application:
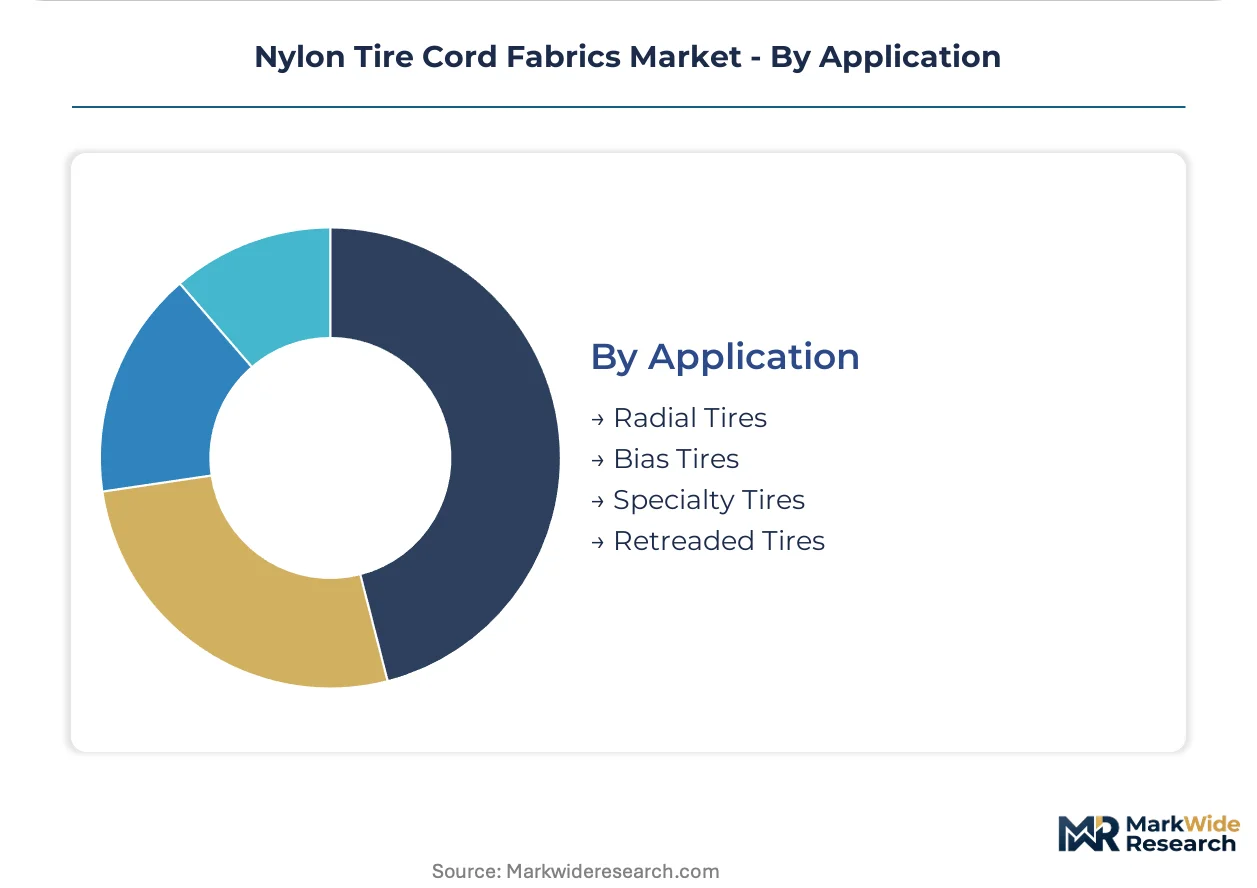
Radial tire constructions command the dominant margin pool as specifications tighten for rolling resistance and durability standards under EPA and REACH frameworks.
- Radial Tires:Belt and carcass ply reinforcements with high-tenacity nylon-6,6 filaments provide dimensional stability under inflation pressure and thermal stress.
- Specialty Tires:Aircraft, agricultural, and off-road constructions specify hybrid aramid-nylon cords for extreme load and temperature cycling.
- Bias Tires:Cross-ply constructions in two-wheeler and commercial vehicle segments sustain medium-tenacity grade demand.
- Retreaded Tires:Shorter cord life expectations constrain reinforcement quality, though fatigue cycling innovation creates white space for medium-tenacity grade advancement.
Radial Tires define current qualification standards. Specialty Tires are gaining share fastest as aircraft OEMs diversify supplier bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and India present divergent supply dynamics despite shared dominance in tire manufacturing expansion. While China pursues polymer-to-fabric integration under dual carbon goals, India leverages production-linked incentives to capture export-oriented tire assembly demand. Regulatory fragmentation between these markets complicates qualification protocols for multinational fabric suppliers.
China
Radial tire capacity expansion by domestic OEMs absorbs high-tenacity nylon cord volumes at unprecedented scale. GB standards for tire reinforcement materials mandate localized testing protocols that extend supplier validation timelines by months. The Yangtze River Delta hosts concentrated weaving and dip-coating facilities serving both domestic tire makers and European-bound export contracts.
India
The PLI scheme for automotive textiles accelerates domestic tire production capacity to serve ASEAN and Middle East export markets. BIS certification mandates for automotive textiles create compliance bottlenecks for imported fabric grades. Manufacturing clusters around Chennai and Gummidipoondi concentrate medium-tenacity production for cost-optimized bias-ply and radial tire constructions.
United States
EPA emission standards for tire rolling resistance compel fabric producers to reformulate dip chemistries for reduced volatile organic compound profiles. NHTSA durability testing protocols elevate fatigue resistance specifications for commercial vehicle radial tires. Southeast industrial corridors host compounders and weavers supplying domestic tire plants serving replacement and OEM channels.
Germany
REACH authorization timelines for resorcinol and formaldehyde derivatives force accelerated validation of phenol-free adhesion systems. KBA tire certification requirements integrate carbon intensity disclosure for imported reinforcement materials. The Ruhr industrial region maintains specialized dip chemistry R&D facilities supporting Continental and Michelin supplier qualification programs.
South Korea
Hyundai and Kumho Tire procurement consolidation rewards suppliers with captive polymer production and technical service proximity. MFDS chemical substance tracking requirements align with EU REACH protocols for European-bound export tire production. Busan-Ulsan manufacturing corridors concentrate integrated nylon-6,6 polymerization and cord fabric weaving operations.
Nylon Tire Cord Fabrics Market Competitive Landscape
Korean and Chinese producers anchor the integrated-manufacturing tier; Indian and European specialists hold positions in cost-optimized and premium-regulatory segments respectively. The market exhibits bifurcated concentration: a handful of polymer-to-fabric integrators capture multi-year OEM contracts while regional weavers serve replacement tire channels with commodity grades. Three archetypes dominate competitive positioning: backward-integrated chemical-to-textile conglomerates, regional scale manufacturers with localized technical service, and niche adhesion chemistry innovators. Capacity expansion and strategic partnerships represent the dominant competitive moves as tire OEMs consolidate approved supplier lists.
Within the integrated-manufacturing tier, Hyosung Advanced Materials and Kolon Industries exemplify Korean conglomerates with captive nylon-6,6 polymer supply chains. Kordsa Teknik Tekstil A.S. occupies a position among adhesion chemistry specialists serving European regulatory markets. These three anchors illustrate how geographic origin and corporate structure correlate with competitive archetype: the Korean entities represent chemical-to-textile integration, while the Turkish specialist exemplifies regulatory-compliance-focused formulation expertise.
| Leading Market Players |
|---|
| Hyosung Advanced Materials |
| Kordsa Teknik Tekstil A.S. |
| Teijin Limited |
| SRF Ltd. |
| Kolon Industries |
| Indorama Ventures |
| DuPont |
| Toray Industries |
| Century Enka Limited |
| Others |
Value Network & Pricing Analysis
Dip chemistry specialists in the Ruhr industrial region anchor labor-cost differentials that widen spreads between premium REACH-compliant grades and economy-tier Asian supply. This workforce concentration enables European producers to command certification premiums while Indian and Chinese manufacturers compete on scale-optimized medium-tenacity pricing.
Pricing Analysis
Capacity additions in India are reshaping price floors for medium-tenacity grades serving domestic tire OEMs. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by REACH certification status and fatigue resistance validation. Cost compression in standard grades is intensifying because Korean and Chinese tire makers are consolidating procurement around fewer approved suppliers. Replacement tire distributors exhibit highest price sensitivity, while aircraft tire OEMs prioritize thermal shock performance over unit economics.
Supply Chain Analysis
Skilled adhesion chemists in Germany and South Korea face tighter availability than weaving operators in India and China, creating input-cost asymmetries across manufacturing geographies. Supply concentrates in India, China, and South Korea, with each hub serving distinct qualification tiers. Raw material flows draw from caprolactam producers in Northeast Asia and benzene derivative suppliers in the Middle East. Single-source vulnerability in RFL dip chemistry feedstocks threatens continuity for European-bound exports. Distribution runs through tier-one tire OEM procurement centers with multi-year contract structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH authorization timelines for resorcinol derivatives are accelerating supplier consolidation and rewarding early movers in phenol-free adhesion chemistry.
For Market Incumbents: Deepen backward integration into captive nylon-6,6 polymer production to defend margin position against caprolactam price volatility. Secure multi-year technical collaboration agreements with Korean and Chinese tire OEM R&D centers before qualification cycles compress further. Invest in localized BIS certification capabilities at Indian manufacturing clusters to preempt compliance bottlenecks. For New Entrants and Emerging Players: Tier-two Indian tire producers seeking rapid supplier onboarding represent the most penetrable channel partner type for medium-tenacity grade specialists. Target retreaded tire applications with fatigue cycling innovation as incumbent producers prioritize radial OEM contracts. Pursue joint development programs with aircraft tire suppliers diversifying beyond Korean incumbents for aramid-nylon hybrid specifications. For Investors and Strategic Acquirers: Korean chemical-to-textile conglomerates are the most active acquirer in this space, seeking European regulatory expertise to complement their polymer-to-fabric scale. Five-to-ten-year viability favors adhesion chemistry innovators with validated phenol-free systems over commodity weavers facing margin compression. Watch ECHA candidate list expansion velocity as the inflection signal for alternative dip chemistry adoption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Production | Captive nylon-6,6 supply secures margin stability against benzene derivative volatility. |
| REACH-Compliant Dip Chemistry Certification | Phenol-free adhesion validation unlocks European OEM procurement qualification pathways. |
| Localized Technical Service Deployment | Indian tire capacity expansion demands rapid-response R&D collaboration capabilities. |
| Hybrid Filament Product Development | Aramid-nylon blends capture aircraft tire specifications from Boeing and Airbus suppliers. |
| Long-Term Supply Agreement Restructuring | Multi-year contracts with Korean and Chinese OEMs concentrate volume with tier-one integrators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement encompassed tire OEM procurement directors, dip chemistry R&D leads, automotive textile plant managers, and regulatory affairs specialists at European chemical agencies. Secondary validation drew from ECHA authorization databases, BIS certification registries, Korean MFDS substance tracking disclosures, and customs trade flows for caprolactam and tire cord fabric categories. Bottom-up volume modeling and top-down value reconciliation ensured cross-verification of segment outputs.
Segment-weighting applied product type, end user, manufacturing process, and application dimensions across the modeling period. High-tenacity, specialty blend, medium-tenacity, and low-tenacity grades received distinct growth coefficients reflecting radial tire specification tightening and aircraft OEM diversification. CAGRs were derived from elasticity-adjusted demand curves incorporating PLI scheme uptake rates in India and carbon-border adjustment implementation phasing in Europe. Feedstock cost trajectories and OEM procurement consolidation patterns informed scenario boundaries.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH sunset date acceleration and aramid hybrid substitution velocity in off-road segments. Assumptions underlying projections reflect documented regulatory milestones and disclosed capacity expansion timelines. Material deviation in ECHA candidate list expansion or Korean tire maker procurement consolidation velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
North America Aramid Fiber Market
Synthetic Fibers
Synthetic Sewing Thread Market
Synthetic Fibers
Asia-Pacific Spandex Market
Synthetic Fibers
Europe Aramid Fiber Market
Synthetic Fibers
Blended Fibers Market
Synthetic Fibers
Monofilament Market
Synthetic Fibers
Nanofibers Market
Synthetic Fibers
North America High Performance Fibers Market
Synthetic Fibers
Conductive Fibers Market
Synthetic Fibers
High Temperature Fiber Market
Synthetic Fibers
Aramid Fiber Market
Synthetic Fibers
Rayon Fibers Market
Synthetic Fibers
Parachute Fabric Market
Synthetic Fibers
Latin America Textile Market
Synthetic Fibers
Fiberglass Roving Market
Synthetic Fibers
Staple Fibers Market