
 Printed Textiles Market | 2026-2036
Printed Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
Printed Textiles Market Analytics
Premium custom-printed fabrics and commodity bulk rolls is decoupling as brand owners demand shorter runs with design agility. Kornit Digital leverages pigment-based ink systems to capture on-demand apparel workflows. Seiko Epson Corporation anchors its position through precision printhead architectures that reduce water consumption. Durst Group specializes in high-throughput industrial systems for interior décor applications.
Printed textiles encompass fabrics decorated with pigments, dyes, or reactive inks transferred via mechanical or digital processes, typically achieving colorfastness ratings of 4–5 on the ISO 105 scale for wash durability. These materials serve fashion houses, hospitality chains, and automotive trim suppliers seeking differentiated surface aesthetics. Digital printing technology leads in margin contribution due to negligible setup costs and zero screen inventory, while screen printing retains volume dominance in emerging-market commodity supply. Apparel commands the largest revenue pool, though home furnishings is accelerating as interior designers specify bespoke wall coverings and upholstery.
REACH in Europe restricts aromatic amines in azo dyes, compelling reformulation across export-oriented mills. EPA effluent guidelines under the Clean Water Act enforce pretreatment standards for textile wet processing facilities in the United States. ISO 105 and OEKO-TEX Standard 100 shape buyer qualification protocols for international procurement teams. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border supply chains.
Market Dynamics
Digital pigment ink systems are collapsing minimum order quantities from thousands of meters to single-unit production, fragmenting the traditional screen-printing volume hierarchy and forcing capital reallocation across dyehouse networks.
Growth Catalysts
- REACH aromatic amine restrictions:EU dye reformulation mandates are accelerating water-based pigment adoption among export-oriented mills in India and Turkey.
- On-demand apparel workflows:Direct-to-garment digital systems enable brand owners to compress design-to-retail cycles from months to days.
- Surat-Tiruppur cluster expansion:Indian government production-linked incentives are concentrating dye-sub capacity for synthetic fabric exports to Middle Eastern hospitality markets.
Market Restraints
- Reactive dye input volatility:Petrochemical feedstock fluctuations for naphthol and vinyl sulfone intermediates compress margin predictability for commodity roll producers.
- Water scarcity in Gujarat:Dyehouse concentration around the Tapi River basin faces seasonal allocation caps that constrain throughput expansion.
- Pigment fastness ceiling:ISO 105-C06 wash ratings for pigment prints plateau below reactive dye performance, limiting adoption in premium performance apparel.
Strategic Opportunities
- Brazilian home furnishings underpenetration:Interior décor digital printing for wall coverings and upholstery remains below 8% adoption in São Paulo design studios.
- EU Green Deal textile strategy:Mandatory recycled content thresholds for 2030 create pull for digitally printed deadstock fabric revival services.
- AI-driven color matching:Machine vision convergence with spectrophotometry is collapsing lab-dip approval cycles for custom hospitality projects.
Industry Challenges
- Digital printhead technician scarcity:Maintenance proficiency for piezoelectric arrays lags equipment deployment across mid-cap converters.
- Legacy ERP integration friction:Screen-printing workflow software requires costly middleware adaptation to interface with web-to-print order management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printed Textiles Market |
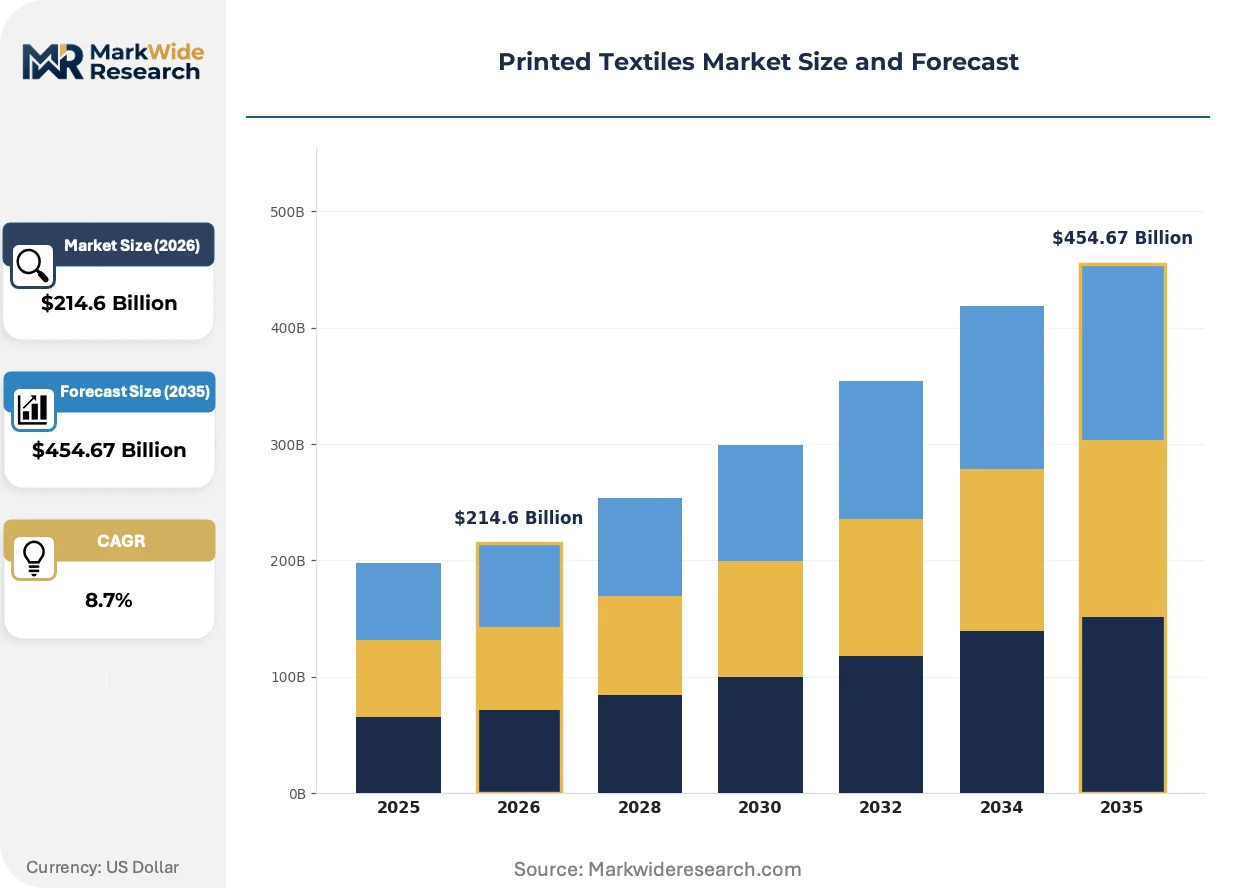
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $454.67 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Home Furnishings, Promotional Products, Industrial Textiles Printing Technology: Digital Printing, Screen Printing, Sublimation Printing, Flexography End User: Fashion Designers, Interior Designers, Advertising Agencies, Manufacturers Material: Cotton, Polyester, Silk, Linen |
| Companies Covered | Seiko Epson Corporation, Kornit Digital, Konica Minolta, Roland DGA Corporation, Fujifilm, Globe Textiles (India) Ltd, Mimaki Engineering, Durst Group, HP Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printed Textiles Market Evolving Landscape
Pigment-based single-pass digital printing is collapsing the traditional separation between sampling and bulk production, compressing capital requirements and reordering competitive advantage toward design velocity rather than scale economies.
Single-pass pigment inkjet arrays are rewriting the economics of short-run textile decoration. Fashion houses in Milan and Los Angeles now commission 50-meter test lots without screen engraving lead times. This compression is enabling micro-collection strategies that were economically unviable under rotary screen minimums.
EPA effluent guidelines under the Clean Water Act are tightening pretreatment standards for textile wet processing facilities across the southeastern United States. Mills in North Carolina and Georgia face capital decisions between upgrading legacy reactive dye lines or migrating to pigment digital systems with near-zero water discharge. The automotive trim supply chain is responding fastest, specifying OEKO-TEX Standard 100 certification for all interior fabric sourcing.
Brand owners now specify print-on-demand fulfillment models that displace traditional seasonal bulk purchasing. Direct-to-consumer apparel channels are replacing wholesale pre-commitment with data-triggered replenishment. This behavioral shift is most visible in German and UK markets, where sustainability-conscious consumers accept extended delivery windows for made-to-order garments.
Printed Textiles Market Segmentation
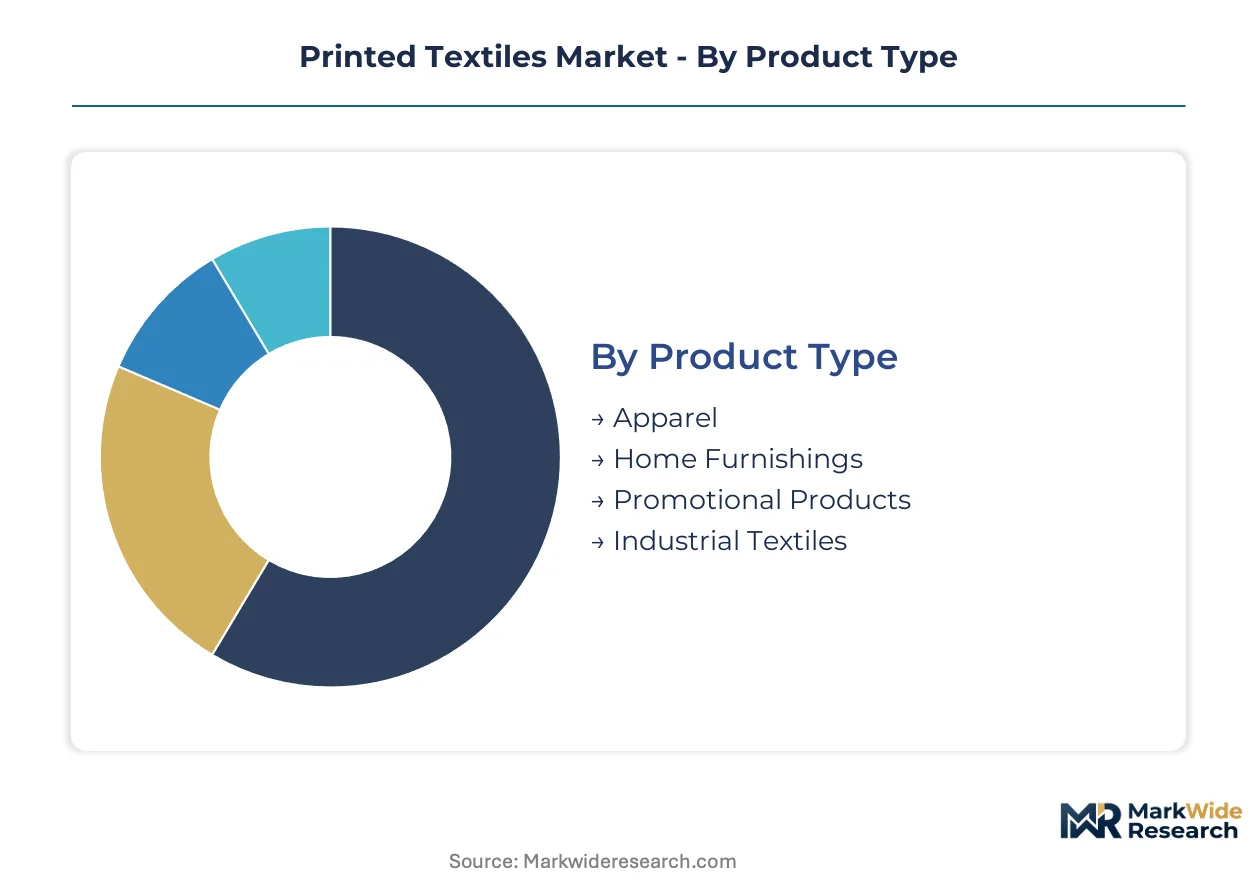
Segmentation in printed textiles reveals how supply-side capabilities and demand-side specifications diverge across product categories. Understanding these splits helps stakeholders align capital deployment with margin structures and regulatory exposure.
Product Type:
Supply concentration in Tiruppur and Surat clusters favors high-volume apparel runs, while fragmented converter networks in Europe and North America specialize in short-run home furnishing batches.
- Apparel:T-shirts, dresses, and activewear absorb the majority of reactive dye and pigment digital capacity. Fashion houses in Los Angeles and Milan commission sub-100-meter test lots that screen-printing economics cannot serve.
- Home Furnishings:Upholstery, curtains, and wall coverings require heavier fabric weights and specialized fixation equipment. Hospitality procurement teams in Dubai and Riyadh drive specification standards for flame-retardant printed linens.
- Promotional Products:Branded tote bags, banners, and event merchandise operate on compressed turnaround timelines. Advertising agencies in São Paulo source these through digital converters to avoid screen setup costs.
- Industrial Textiles:Technical fabrics for automotive trim, medical textiles, and filtration media demand ISO 105 colorfastness ratings above 4.5.
Apparel absorbs the bulk of installed capacity; home furnishings is expanding most quickly.
Printing Technology:
Capital intensity and water discharge profiles separate digital pigment systems from legacy wet-processing lines, reshaping where converters locate and how they quote.
- Digital Printing:Piezoelectric inkjet arrays deposit pigment or reactive inks directly onto fabric with negligible makeready waste. Kornit Digital and Seiko Epson Corporation dominate hardware supply for on-demand apparel workflows.
- Screen Printing:Rotary and flatbed systems retain cost advantage above 5,000-meter minimums. Indian export mills in Gujarat run these lines continuously for Middle Eastern hospitality bulk orders.
- Sublimation Printing:Heat-transfer chemistry bonds disperse dyes to polyester fibers at 200°C. Sports apparel brands specify this for all-over prints on synthetic performance wear.
- Flexography:Anilox roller metering suits non-woven and paper-based substrates with lower resolution requirements than textile-grade applications.
Screen printing retains the largest share of meterage output; digital printing claims the steepest expansion trajectory in value terms.
End User:
Procurement sophistication varies sharply across customer types, with fashion and interior designers demanding color lab-dip approval cycles that manufacturer-direct buyers compress or bypass.
- Fashion Designers:Seasonal collection development requires rapid sampling turnaround. Studios in London and New York now specify digital pigment proofs to validate colorways before bulk commitment.
- Interior Designers:Bespoke wall covering and upholstery projects run 50-200 meters with custom color matching. AI-driven spectrophotometry is collapsing approval cycles for hospitality fit-outs.
- Advertising Agencies:Event-driven demand peaks require 48-72 hour fulfillment windows that only digital workflows can satisfy.
- Manufacturers:Automotive trim suppliers and bedding producers integrate printing into captive finishing operations to control OEKO-TEX certification compliance.
Manufacturers absorb the bulk of installed capacity; fashion designers are gaining share fastest as direct-to-consumer channels proliferate.
Material:
Fiber selection dictates ink chemistry, fixation temperature, and regulatory compliance burden, with natural fibers facing stricter REACH aromatic amine scrutiny than synthetics.
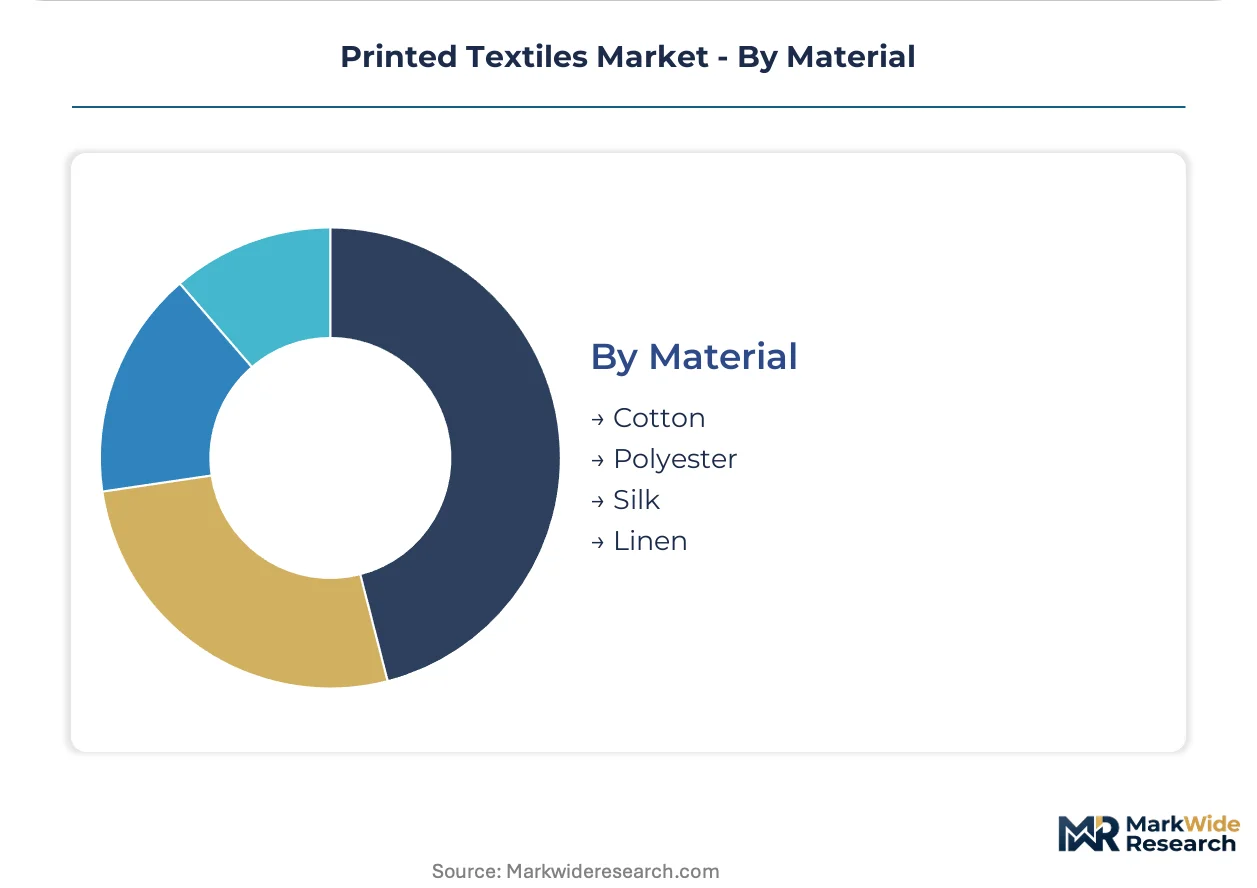
- Cotton:Cellulosic fiber accepts reactive dyes with superior wash fastness but requires extensive rinsing and steaming. Water scarcity in Gujarat constrains expansion of cotton-focused reactive dyehouses.
- Polyester:Hydrophobic synthetic enables sublimation transfer without wet processing. Chinese and Taiwanese chemical fiber producers supply the feedstock for Tiruppur's export-oriented dye-sub cluster.
- Silk:Protein fiber demands acid dye formulations and gentle handling. Italian and Indian luxury converters maintain artisanal screen-printing capacity for high-value scarf and furnishing applications.
- Linen:Bast fiber from flax provides textured substrate for rustic interior aesthetics. Belgian and French growers supply raw material to digital converters serving Scandinavian home furnishing brands.
Polyester absorbs the bulk of installed capacity; cotton is climbing the fastest among sustainability-positioned apparel brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surat anchors printed textiles production through its polyester fabric cluster, where dye-sublimation capacity expansion serves Middle Eastern hospitality procurement. Tiruppur's cotton knitwear belt complements this with reactive dyeing for European apparel brands. Regulatory divergence across major importing jurisdictions reshapes where converters invest in water-treatment infrastructure versus pigment digital migration.
United States
Automotive trim suppliers in North Carolina and Georgia drive OEKO-TEX Standard 100 compliance for interior fabric sourcing. EPA effluent guidelines under the Clean Water Act force capital decisions between legacy reactive dye upgrades and near-zero-discharge pigment systems. Mills in the Southeast corridor face seasonal water allocation pressure during drought cycles.
Germany
Sustainability-conscious consumers in Berlin and Hamburg accept extended delivery windows for made-to-order garments. REACH aromatic amine restrictions on azo dyes compel reformulation across import-dependent supply chains. The EU Green Deal textile strategy mandates recycled content thresholds that pull deadstock fabric revival services into the market.
India
Export-oriented mills in Surat and Tiruppur concentrate dye-sub capacity for synthetic fabric shipments to Dubai and Riyadh hospitality markets. PLI scheme production-linked incentives accelerate capital deployment in Gujarat's Tapi River basin despite seasonal water scarcity caps. BIS certification requirements shape qualification protocols for international procurement teams.
Italy
Fashion houses in Milan commission sub-100-meter digital pigment test lots that rotary screen economics cannot serve. ECHA enforcement of REACH dye restrictions maintains pressure on artisanal screen-printing capacity for luxury scarf applications. Lombardy-based converters specialize in acid dye formulations for silk protein fibers.
Brazil
Interior décor digital printing for wall coverings and upholstery remains below adoption thresholds in São Paulo design studios. ANVISA chemical safety protocols intersect with import dye certification requirements for hospitality fit-out projects. Advertising agencies in the Southeast region source promotional merchandise through digital converters to bypass screen setup costs.
Printed Textiles Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and water-treatment compliance vectors. The vendor base stratifies between precision printhead architects, high-throughput industrial system builders, and regional converter networks serving spot-market demand. Three archetypes dominate: hardware-anchored technology licensors, vertically integrated dyehouse operators, and web-to-print platform aggregators. Competitive moves concentrate on strategic partnerships for ink chemistry development and geographic expansion into underpenetrated home furnishings markets.
Within the hardware-anchored tier, Seiko Epson Corporation and Kornit Digital exemplify divergent technology bets. Seiko Epson Corporation occupies a position among precision printhead architects reducing water consumption across textile workflows. Kornit Digital represents the on-demand apparel vector through pigment-based ink system deployment. Durst Group anchors the high-throughput industrial segment for interior décor applications. Konica Minolta and Mimaki Engineering sit within the mid-cap converter equipment supply tier serving fragmented regional demand.
| Leading Market Players |
|---|
| Seiko Epson Corporation |
| Kornit Digital |
| Konica Minolta |
| Roland DGA Corporation |
| Fujifilm |
| Globe Textiles (India) Ltd |
| Mimaki Engineering |
| Durst Group |
| HP Inc. |
| Others |
Value Network & Pricing Analysis
Petrochemical feedstock indices for naphthol and vinyl sulfone intermediates cascade through reactive dye formulations into three distinct pricing tiers: premium pigment digital systems, standard reactive dye bulk rolls, and economy screen-printed commodity volumes. Mills in Gujarat and Tamil Nadu calibrate quotes against these input curves while water scarcity caps in the Tapi River basin prop up scarcity premiums for compliant capacity.
Pricing Analysis
Throughput-based pricing anchors converter quotations, with brand owners paying per-meter rates that scale inversely with run length and design complexity. Three-tier pricing structure across premium, standard, and economy levels separates OEKO-TEX certified hospitality linens from uncertified promotional merchandise. Pricing pressure stems from reactive dye input volatility compressing margin predictability for commodity roll producers. Advertising agencies exhibit highest price sensitivity, while automotive trim suppliers absorb certification premiums without volume negotiation.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Dubai, and Singapore coordinate hub-and-spoke patterns for ink chemistry and printhead component logistics. Manufacturing concentrates in India, China, and Turkey, with Surat's polyester cluster and Tiruppur's cotton belt anchoring global export volume. Raw material dependencies span disperse dyes from Chinese chemical fiber producers, piezoelectric printheads from Japanese precision manufacturers, and fixation equipment from Italian engineering specialists. Single-source vulnerability for specialized printhead arrays concentrates risk. Distribution runs through converter-direct relationships for bulk hospitality orders and web-to-print platforms for on-demand apparel workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water allocation caps in Gujarat's Tapi River basin constrain reactive dyehouse expansion, creating a supply-constrained environment that sustains pricing power for compliant pigment digital capacity.
For Market Incumbents: Anchor defensive positioning through backward integration into captive ink formulation capacity and certification investment for OEKO-TEX Standard 100 compliance. Seiko Epson Corporation and Kornit Digital exemplify technology licensors defending against hardware commoditization through precision printhead R&D and service contract bundling. Capacity addition in Tamil Nadu's PLI-subsidized zones counters water scarcity risks in Gujarat. For New Entrants and Emerging Players: Web-to-print platform routes offer lowest-friction entry into fashion designer and interior designer segments previously locked behind screen-printing minimums. Brazilian home furnishings digital printing, below 8% adoption in São Paulo studios, presents the most penetrable white-space target. AI-driven color matching tools collapse lab-dip approval cycles, enabling hospitality fit-out specialization without legacy spectrophotometry infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap converters with installed digital pigment capacity in water-stressed regions facing EPA effluent upgrade costs. Long-term viability hinges on 5-10 year migration from wet-processing to near-zero-discharge systems. The signal to watch is PLI scheme disbursement velocity in India, indicating state-supported capacity expansion pace.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ink Chemistry | Captive pigment formulation secures margin control against naphthol feedstock volatility from Indian petrochemical suppliers. |
| AI-Driven Color Matching Deployment | Machine vision convergence with spectrophotometry collapses approval cycles for Dubai hospitality procurement teams. |
| Water Treatment Infrastructure Upgrade | EPA Clean Water Act compliance in North Carolina and Georgia preserves automotive trim supplier qualification status. |
| Web-to-Print Platform Launch | Direct-to-consumer channels in Berlin and Hamburg capture sustainability-conscious buyers accepting extended delivery windows. |
| PLI Scheme Capacity Expansion | Government production-linked incentives in Tiruppur concentrate dye-sub capacity for Middle Eastern hospitality exports. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this printed textiles assessment. Primary interviews with digital printhead technicians, dyehouse operations managers, hospitality procurement directors, and fashion studio production leads combined with secondary validation from EPA effluent guideline documents, REACH restriction updates, and BIS certification protocols. Bottom-up meterage estimates from Surat and Tiruppur cluster surveys triangulated against top-down value projections from export trade data.
Segment-level granularity modeled printing technology, material fiber type, and end-user procurement sophistication across the analysis window. Product type splits captured apparel, home furnishings, promotional products, and industrial textiles with distinct colorfastness requirements. Geography-specific regulatory exposure shaped regional growth differentials. CAGRs derived from installed capacity trajectories, technology substitution curves, and buyer behavioral shifts toward on-demand fulfillment models.
Inputs from Indian government PLI scheme disbursement records and EU ECHA enforcement actions were available through the study window; gaps in real-time water allocation data from Gujarat irrigation authorities introduce uncertainty bands around Tiruppur versus Surat capacity expansion timelines. Forecasts reflect documented assumptions regarding pigment fastness improvement rates and REACH aromatic amine restriction enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Denim Fabric Market
Yarn and Fabric Manufacturing
E-Glass Fiber Yarn and Roving Market
Yarn and Fabric Manufacturing
Knitted Fabric Market
Yarn and Fabric Manufacturing
Asia Pacific Cotton Market
Yarn and Fabric Manufacturing
Cotton Bags Market
Yarn and Fabric Manufacturing
Outdoor Fabric Market
Yarn and Fabric Manufacturing
Canvas and Muslin Bags Market
Yarn and Fabric Manufacturing
Linen Fabric Market
Yarn and Fabric Manufacturing
Nylon 6 Filament Yarn Market
Yarn and Fabric Manufacturing
Polypropylene Yarn Market
Yarn and Fabric Manufacturing
Poly Cotton Market
Yarn and Fabric Manufacturing
Canvas Roll Market
Yarn and Fabric Manufacturing
Global Textile Yarn Market
Yarn and Fabric Manufacturing
Silica Yarn Market
Yarn and Fabric Manufacturing
Textile Fabrics Market
Yarn and Fabric Manufacturing
Global Arab Thobe Fabric Market