
 Regenerated Fibers Market | 2026-2036
Regenerated Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Regenerated Fibers Market Analytics
Apparel brands seeking carbon-negative material credentials is unwinding historical reliance on conventional polyester among mass-market retailers. Lenzing AG anchors European supply through its Tencel lyocell platform and integrated pulp-to-fiber operations in Austria and Czechia. Grasim Industries Limited dominates Indian viscose staple fiber output through its Nagda and Harihar complexes. Sateri competes on scale with its four Chinese mills running on certified sustainable wood sources.
Regenerated fibers are cellulosic textiles produced by dissolving pulp from wood, bamboo, or agricultural residues and extruding the solution through spinnerets into continuous filaments or staple fibers, with denier ranges from 1.2 to 6.0 for apparel applications and tenacity values of 2.5–4.0 g/denier depending on process chemistry. Lyocell commands premium positioning in the product type matrix due to its closed-loop N-methylmorpholine N-oxide solvent recovery rate exceeding 99%, while rayon retains volume leadership across price-sensitive home textiles and basic apparel. Technical textiles within the application dimension is attracting R&D investment for medical nonwovens and filtration media where biocompatibility and controlled degradation matter.
The EU Green Deal and REACH chemical registration protocols constrain European market access for viscose producers using carbon disulfide-intensive processes, while China's GB standards and dual carbon goals drive domestic mills toward energy-efficient lyocell retrofits. India's BIS certification and PLI scheme for man-made fibers incentivize domestic value addition over raw fiber imports. Stakeholders must track regulatory divergence between European chemical hazard classifications and Asian production cost structures when siting new capacity or qualifying supply chains.
Market Dynamics
Closed-loop solvent recovery systems are compressing the cost premium between lyocell and conventional viscose, forcing carbon-intensive producers to retrofit or exit European supply chains entirely.
Growth Catalysts
- EU Green Deal textile sustainability mandates:The EU Green Deal's extended producer responsibility rules are compelling apparel brands to certify fiber provenance, redirecting sourcing toward closed-loop lyocell producers with verified N-methylmorpholine N-oxide recovery systems.
- India PLI scheme for man-made fibers:India's production-linked incentive scheme is attracting downstream spinning investment to Karnataka and Tamil Nadu, building integrated viscose-to-yarn capacity that reduces import dependence.
- Medical nonwovens demand:Biocompatible lyocell filaments are displacing petroleum-based spunbond in surgical drapes and wound dressings where controlled hydrolysis matters for single-use sterility.
Market Restraints
- Dissolving pulp supply concentration:Brazilian and Indonesian pulp mills control over two-thirds of textile-grade dissolving pulp output, exposing fiber producers to freight volatility and currency swings.
- REACH carbon disulfide restrictions:ECHA's reclassification of carbon disulfide as a substance of very high concern is raising compliance costs for European viscose operations and blocking market access for non-compliant Asian imports.
- Mechanical recycling substitution:Post-consumer cotton mechanical recycling is achieving commercial scale for denim applications, capturing price-sensitive volume that regenerated fibers previously served.
Strategic Opportunities
- Agricultural residue feedstocks:Wheat straw and rice husk cellulose extraction is opening fiber production in grain-belt regions without competing for timber or food crops.
- Indonesia downstream expansion:The country's emerging garment export zones in Central Java offer tariff-advantaged locations for integrated pulp-to-apparel complexes serving ASEAN markets.
- Blockchain traceability integration:CanopyStyle and FSC chain-of-custody verification is enabling premium pricing for deforestation-free fiber lots in Scandinavian and German retail channels.
Industry Challenges
- Lyocell engineering talent scarcity:Solvent spinning process optimization requires specialized polymer chemists and spinning technicians that Southeast Asian labor markets currently lack.
- Multi-standard certification complexity:Simultaneous OEKO-TEX, GOTS, and EU Ecolabel compliance creates documentation burdens that delay product launches by 4-8 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Regenerated Fibers Market |
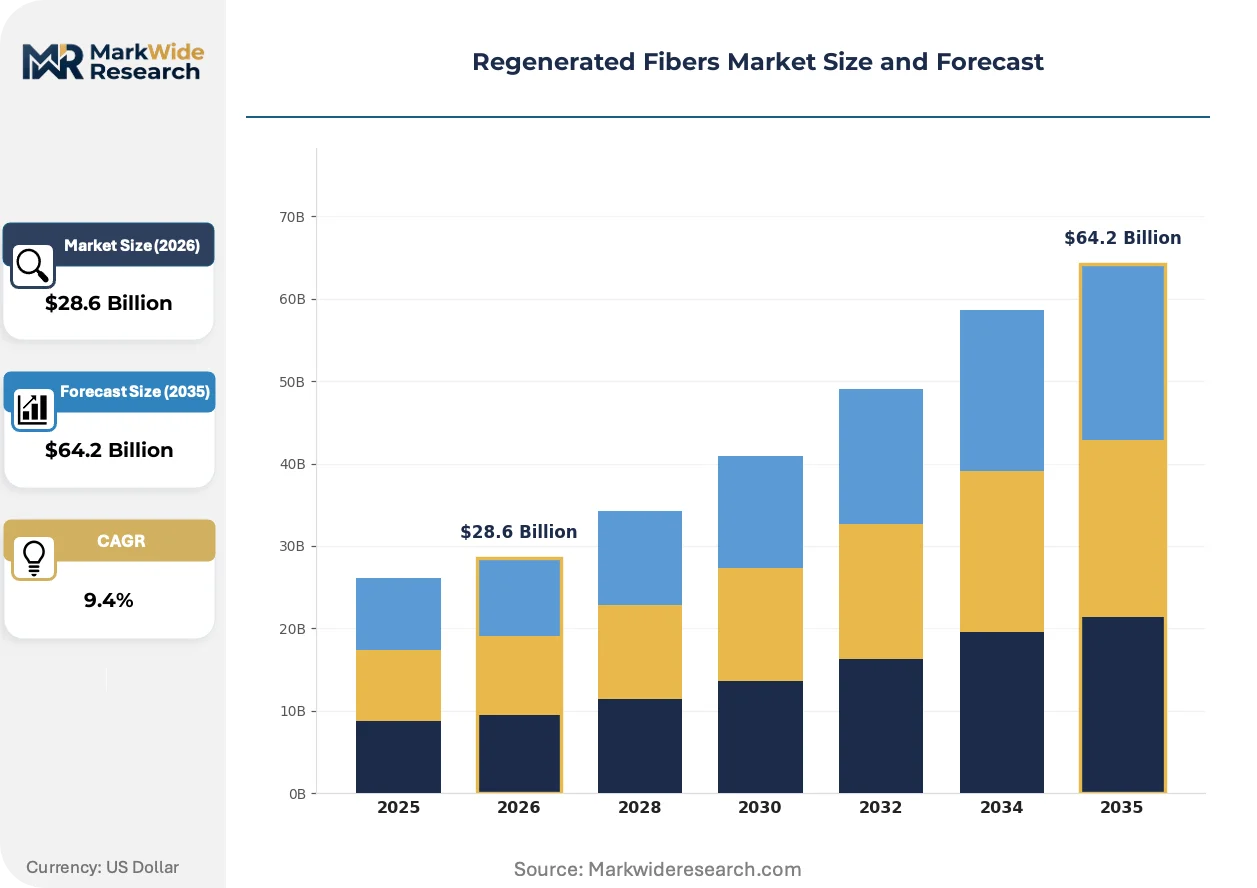
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rayon, Lyocell, Acetate, Modal End User: Fashion, Home Textiles, Automotive, Industrial Distribution Channel: Online Retail, Department Stores, Specialty Stores, Wholesale Application: Clothing, Upholstery, Nonwovens, Technical Textiles |
| Companies Covered | Lenzing AG, Sateri, Grasim Industries Limited, Fulida Group, Eastman Chemical Company, Kelheim Fibres GmbH, Birla Cellulose, Aditya Birla Group, GP Cellulose, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Regenerated Fibers Market Evolving Landscape
Digital traceability infrastructure and next-generation solvent systems are compressing the sustainability premium that once separated niche from mass-market cellulosic textiles.
Lyocell production technology is bifurcating between large-scale continuous spunlace systems for hygiene nonwovens and batch-oriented filament spinning for premium apparel. Denim brands in Los Angeles and Amsterdam are adopting the filament variant for its indigo uptake efficiency and reduced water footprint in garment finishing. The technology gap between these two process branches is widening capital requirements and fragmenting equipment supplier relationships.
China's GB standards for industrial wastewater and the dual carbon goals are mandating energy intensity reductions of 15-20% for viscose producers by 2030. Mills in Hebei and Jiangsu provinces are retrofitting sulfur recovery and biomass boiler systems to avoid production caps. The regulatory pressure is accelerating closures of small-batch viscose lines while consolidating output in Sateri-scale integrated facilities.
Brand procurement teams are consolidating fiber suppliers to reduce audit burden and secure volume commitments for carbon accounting disclosures. Mass-market retailers in Germany and France are shrinking approved vendor lists from 40-plus fiber sources to 8-12 strategic partners with verified Canopy green shirt ratings. The concentration is visible in annual sourcing reviews where lyocell and recycled cotton blends now dominate sustainable collection targets.
Regenerated Fibers Market Segmentation
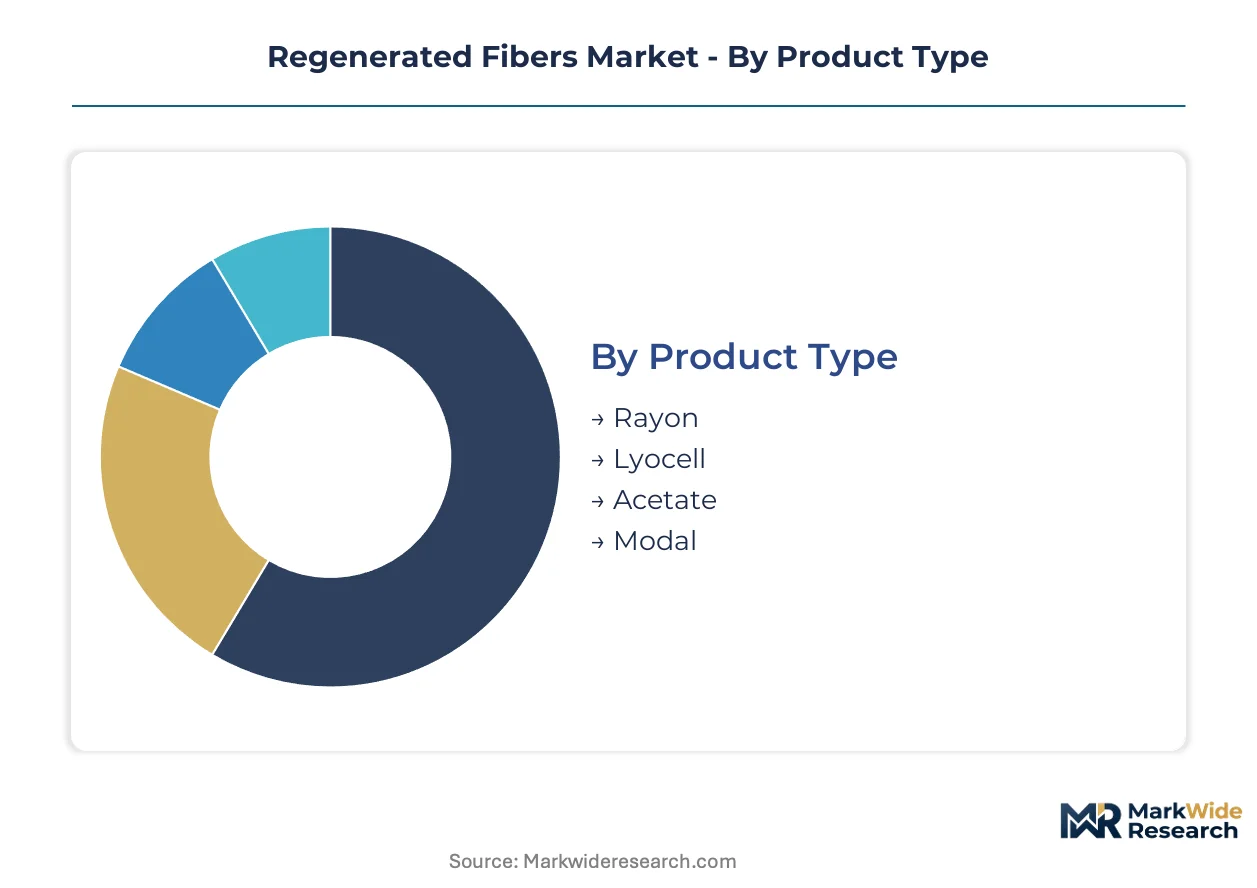
Margin capture in regenerated fibers hinges on solvent chemistry efficiency and end-use certification tiers. Producers align capacity investments with the regulatory gradient between European closed-loop mandates and Asian volume markets.
Product Type:
Premium positioning clusters around closed-loop solvent recovery rates, with N-methylmorpholine N-oxide systems commanding double-digit margin premiums over carbon disulfide-based output.
- Lyocell:Manufactured via direct cellulose dissolution in N-methylmorpholine N-oxide with recovery rates exceeding 99%. Denim and activewear brands in Los Angeles and Amsterdam are consolidating sourcing here for indigo uptake efficiency and reduced water footprints in garment finishing.
- Rayon:Conventional viscose process using carbon disulfide chemistry dominates volume output for home textiles and basic apparel. ECHA's reclassification of carbon disulfide as a substance of very high concern is blocking European market access for non-compliant Asian imports and forcing retrofit investments.
- Acetate:Cellulose acetate esterification produces silk-like drape for linings and high-fashion applications. Lenzing AG and Eastman Chemical maintain specialized filament capacity.
- Modal:High-wet-modulus variant of viscose with enhanced tenacity for underwear and loungewear. Grasim Industries Limited scales output from its Nagda and Harihar complexes for domestic Indian and export markets.
Rayon holds installed capacity. Lyocell is rotating up the share rankings.
End User:
Demand concentration tracks the sustainability disclosure burden, with sectors facing mandatory carbon accounting driving fastest adoption of certified fiber provenance.
- Fashion:Apparel brands seeking carbon-negative material credentials are unwinding historical reliance on conventional polyester. Mass-market retailers in Germany and France are shrinking approved vendor lists from 40-plus fiber sources to 8-12 strategic partners with verified Canopy green shirt ratings.
- Home Textiles:Rayon retains volume leadership across price-sensitive bedding and curtain applications where basic absorbency and dye affinity suffice.
- Automotive:Seat upholstery and interior trim applications favor lyocell for low VOC emissions and thermal stability. Tier-1 suppliers in Stuttgart and Toyota City are qualifying sustainable fiber sources for OEM sustainability scorecards.
- Industrial:Filtration media and reinforced composites use high-tenacity regenerated filaments. Technical specifications prioritize controlled degradation and biocompatibility over cost minimization.
Fashion holds installed capacity. Automotive is rotating up the share rankings.
Distribution Channel:
Channel economics diverge sharply between bulk commodity transactions and traceability-premium direct relationships.
- Wholesale:Volume consolidation through textile trading houses in Keqiao and Surat moves undifferentiated rayon and modal to price-sensitive spinning mills. Freight volatility and currency swings from Brazilian and Indonesian pulp concentration compress margins.
- Specialty Stores:Premium fabric retailers in Tokyo's Nippori and Milan's Via Mecenate stock certified lyocell and Tencel-branded materials for boutique designers.
- Online Retail:Direct-to-brand platforms enable small-batch procurement with blockchain traceability documentation. CanopyStyle and FSC chain-of-custody verification supports premium pricing in Scandinavian and German retail channels.
- Department Stores:Mass-market home textile sections source standardized rayon blends through centralized corporate procurement with basic OEKO-TEX compliance.
Wholesale holds installed capacity. Online Retail is rotating up the share rankings.
Application:
Performance specifications stratify across disposable versus durable use cases, with medical and technical segments rewarding biocompatibility premiums.
- Clothing:Denim brands adopt lyocell filament variants for indigo uptake efficiency. Activewear collections specify moisture-wicking lyocell for its closed-loop credentials.
- Technical Textiles:Medical nonwovens demand biocompatible lyocell filaments for surgical drapes and wound dressings where controlled hydrolysis matters for single-use sterility. R&D investment concentrates here for single-use sterility applications.
- Nonwovens:Spunlace systems for hygiene products use large-scale continuous lyocell production. The technology gap between continuous and batch spinning is widening capital requirements.
- Upholstery:Residential and contract furniture applications balance abrasion resistance with sustainability claims. Modal blends serve mid-tier positioning.
Clothing holds installed capacity. Technical Textiles is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites European supply security for N-methylmorpholine N-oxide solvent imports that feed closed-loop lyocell operations.
China
Denim brands in Guangdong province are expanding lyocell filament sourcing for indigo-efficient garment finishing. GB standards for industrial wastewater and dual carbon goals mandate 15-20% energy intensity reductions for viscose producers by 2030. Mills in Hebei and Jiangsu provinces are retrofitting sulfur recovery systems to avoid production caps.
Austria
Lenzing AG's integrated pulp-to-fiber complex anchors European Tencel supply for carbon-accounting apparel brands. EU Green Deal extended producer responsibility rules compel fiber provenance certification. The country's N-methylmorpholine N-oxide recovery systems exceed 99% efficiency, qualifying output for premium Scandinavian retail channels.
India
Spinning investment is concentrating in Karnataka and Tamil Nadu under the PLI scheme for man-made fibers. BIS certification requirements and domestic value-addition incentives reduce import dependence on raw fiber. Grasim Industries Limited's Nagda and Harihar complexes dominate national viscose staple fiber output.
Indonesia
Emerging garment export zones in Central Java offer tariff-advantaged locations for integrated pulp-to-apparel complexes. The country's dissolving pulp mills control substantial textile-grade output, exposing fiber producers to freight volatility. New capacity additions are targeting ASEAN market access with certified sustainable wood sourcing.
United States
Los Angeles denim brands are consolidating lyocell filament procurement for reduced water footprint in garment finishing. EPA industrial wastewater guidelines and California SB 657 supply chain transparency requirements constrain conventional viscose market access. The Port of Long Beach handles concentrated imports of closed-loop cellulosic fibers for West Coast apparel manufacturing.
Regenerated Fibers Market Competitive Landscape
Concentration sits with integrated pulp-to-fiber specialists and regional viscose scale players. European closed-loop operators command premium positioning through solvent recovery credentials, while Asian producers compete on volume throughput for price-sensitive home textile applications. Two strategic archetypes dominate: vertically integrated forest products conglomerates with captive dissolving pulp supply, and specialty chemical spinners with licensed lyocell technology. Competitive moves center on capacity expansion in tariff-advantaged jurisdictions and strategic partnerships with Canopy-rated pulp suppliers.
Among European integrated operators, Lenzing AG and Kelheim Fibres GmbH exemplify the closed-loop technology archetype with established N-methylmorpholine N-oxide recovery platforms. Sateri represents the Asian scale-driven model with multi-mill operations running on certified sustainable wood sources. Grasim Industries Limited anchors the Indian subcontinent's viscose output through large-scale manufacturing complexes serving domestic and export spinning markets.
| Leading Market Players |
|---|
| Lenzing AG |
| Sateri |
| Grasim Industries Limited |
| Fulida Group |
| Eastman Chemical Company |
| Kelheim Fibres GmbH |
| Birla Cellulose |
| Aditya Birla Group |
| GP Cellulose |
| Others |
Value Network & Pricing Analysis
Sixty-day dissolving pulp inventory cycles at European lyocell mills compress pricing power for carbon disulfide-based viscose producers facing REACH compliance costs. This lead-time exposure concentrates margin capture with integrated pulp-to-fiber operators in Austria and Czechia while forcing spot-market rayon buyers into volume-commitment contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates closed-loop lyocell with CanopyStyle certification from basic OEKO-TEX rayon and undifferentiated commodity viscose. Price differentiation rests on solvent recovery rates and FSC chain-of-custody documentation rather than base fiber specifications. Pricing pressure stems from mechanical recycling substitution in denim applications. Mass-market home textile buyers exhibit highest price sensitivity, while automotive Tier-1 suppliers accept premium positioning for low-VOC lyocell upholstery.
Supply Chain Analysis
Brazilian and Indonesian pulp mill concentration creates chokepoint exposure for textile-grade dissolving pulp supply. Raw material dependencies center on eucalyptus and acacia wood chips, sulfur chemistry for viscose processing, and N-methylmorpholine N-oxide solvent for lyocell spinning. Single-source vulnerability runs through Indonesian dissolving pulp output controlled by Asia Pulp & Paper affiliate structures. Distribution runs through Rotterdam chemical terminals for European closed-loop operations and Keqiao textile trading hubs for Asian volume markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regenerated fibers sit in early-cycle expansion as EU Green Deal extended producer responsibility rules force apparel brands to unwind polyester dependence. Penetration tailwinds concentrate in denim and activewear collections where indigo uptake efficiency and moisture-wicking performance justify sourcing shifts.
For Market Incumbents: Compound solvent recovery advantages by retrofitting carbon disulfide lines in Hebei and Jiangsu provinces ahead of China's dual carbon deadlines. Defend European market access through ECHA pre-registration of N-methylmorpholine N-oxide recovery systems. Prioritize backward integration into certified sustainable pulp supply through Canopy-rated partnerships in Indonesia and Brazil.
For New Entrants and Emerging Players: Blockchain traceability documentation gaps in Southeast Asian supply chains create white-space opportunity for integrated pulp-to-apparel complexes in Central Java. Agricultural residue feedstock extraction from wheat straw and rice husk cellulose offers the most penetrable entry point in grain-belt regions without timber competition. Lead with direct-to-brand online platforms enabling small-batch procurement with FSC chain-of-custody verification.
For Investors and Strategic Acquirers: Carve-out targets emerge from forest products conglomerates with non-core textile fiber divisions lacking lyocell technology licensing. Long-term viability favors closed-loop chemistry platforms over carbon disulfide exposure given REACH substance-of-very-high-concern trajectory. Watch for inflection in EU Green Deal textile sustainability mandate enforcement timelines as the signal for accelerated brand procurement consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Pulp Supply | Captures margin from Brazilian and Indonesian dissolving pulp concentration while securing CanopyStyle ratings. |
| Lyocell Capacity Expansion | Positions operators for EU Green Deal compliance advantage as ECHA carbon disulfide restrictions tighten. |
| Agricultural Residue Feedstock Development | Opens fiber production in grain-belt regions without competing for timber or food crop land use. |
| Blockchain Traceability Integration | Enables premium pricing for deforestation-free fiber lots in Scandinavian and German retail channels. |
| Medical Nonwovens R&D Partnership | Qualifies biocompatible lyocell filaments for surgical drapes and wound dressing applications. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with fiber production executives, brand sustainability officers, and textile procurement managers at mass-market retailers; and secondary validation through customs trade records, Lenzing AG and Grasim Industries SEC filings, and EU Ecolabel certification databases. Bottom-up capacity modeling triangulated against top-down apparel brand sourcing commitment disclosures.
Across the projection horizon, the analytical framework modeled segmentation across solvent chemistry tier, end-use application, and regional regulatory cluster. CAGRs derived from capacity expansion pipelines, brand procurement consolidation trends, and substitution elasticity estimates for mechanical recycling alternatives. Forecast inputs incorporated GB standards enforcement trajectories and PLI scheme uptake rates in Karnataka and Tamil Nadu.
Underlying assumptions cover sustained EU Green Deal implementation pace and China dual carbon goal adherence, with deviation risk concentrated in dissolving pulp freight volatility and carbon disulfide regulatory reclassification timing. Practitioners should keep alternative scenarios live as REACH substance-of-very-high-concern proceedings and Indonesia pulp mill certification audits evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Middle-East and Africa Aramid Fiber Market
Synthetic Fibers
Long Fiber Thermoplastics Market
Synthetic Fibers
Para-Aramid Fibers Market
Synthetic Fibers
Monofilament Market
Synthetic Fibers
Synthetic Fabric Market
Synthetic Fibers
Polyester Strap for Manual Grade Market
Synthetic Fibers
High-Strength Polyester Thread Market
Synthetic Fibers
Nanofibers Market
Synthetic Fibers
Pan-Based Carbon Fiber Cloth Market
Synthetic Fibers
Rayon Fibers Market
Synthetic Fibers
High End Synthetic Suede Market
Synthetic Fibers
Global Synthetic Spider Silk Market
Synthetic Fibers
Staple Fibers Market
Synthetic Fibers
Polyester Straps Market
Synthetic Fibers
Asia-Pacific Aramid Fiber Market
Synthetic Fibers
Asia-Pacific Spandex Market