
 Textile Tester Market | 2026-2036
Textile Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Tester Market Outlook
Modular instrument bundling is hardening as the dominant procurement pattern, with buyers favoring configurable platforms that combine mechanical, optical, and chemical testing in a single footprint. SGS Group leverages its laboratory network to anchor multi-protocol service contracts across Asia-Pacific manufacturing hubs. Bureau Veritas SA competes through specialized fire-resistance and color-fastness certification programs that extend its influence in European retail supply chains. Intertek Group Plc dominates digital measurement integration, positioning its platforms for smart-factory environments.
A textile tester is a precision instrument engineered to quantify physical, chemical, and optical properties of fibers, yarns, and finished fabrics, typically operating within calibrated force ranges from millinewtons to kilonewtons and temperature-controlled chambers for reproducible results. Its primary commercial purpose is to certify that materials meet specified performance thresholds before production scale-up or shipment to downstream buyers. Fabric testers lead the product type landscape due to their ubiquity across woven and knit production lines, while digital measurement technology captures the fastest expansion as manufacturers replace manual gauges with automated vision systems and IoT-connected sensors. Quality assurance applications command the largest share of installed base, though compliance testing generates premium pricing through third-party certification requirements.
REACH in Europe, GB standards administered by SAMR in China, and the FAA's textile specifications for aircraft interiors collectively shape product standards and market access across major trade corridors. The EU Green Deal's textile strategy is forcing investments in chemical-free dye testing and recyclability verification protocols that reshape instrument specifications. Stakeholders must monitor how dual carbon goals in China and evolving ESG disclosure rules in Europe redirect capital toward lifecycle assessment capabilities.
Market Dynamics
Modular instrument bundling is hardening as the dominant procurement pattern, with buyers favoring configurable platforms that combine mechanical, optical, and chemical testing in a single footprint. REACH compliance in Europe and GB standards administered by SAMR in China are tightening chemical testing requirements for imported textiles.
Growth Catalysts
- REACH chemical testing mandates:European textile importers must verify substance restrictions across entire supply chains, forcing investments in chromatography and spectrometry modules.
- Automotive upholstery flame-retardant protocols:Vehicle interior manufacturers in Germany, Japan, and the United States are expanding testing coverage for seat fabrics and headliners.
- Vietnam export manufacturing concentration:Garment production zones in Ho Chi Minh City and Hanoi are absorbing multi-protocol testing platforms to serve fast-fashion and technical apparel buyers.
Market Restraints
- Precision sensor import dependency:Load cells and optical encoders for force measurement concentrate among Japanese and German component suppliers, exposing buyers to currency volatility and lead-time extension.
- Calibration infrastructure scarcity:Accredited metrology laboratories capable of certifying kilonewton-range instruments remain limited outside Shanghai, Stuttgart, and Boston corridors.
- Manual gauge substitution resistance:Small-batch weavers in South Asia continue relying on handheld micrometers and visual inspection, compressing addressable market depth at the economy tier.
Strategic Opportunities
- EU Green Deal textile strategy:Chemical-free dye testing and recyclability verification protocols are redirecting instrument specifications toward lifecycle assessment capabilities.
- Smart-factory vision system convergence:Integration of automated optical inspection with IoT-connected sensors enables real-time defect detection on knit and woven production lines.
- Indonesia technical textiles expansion:Geotextile and medical nonwoven manufacturing in Surabaya and Bandung is generating demand for filtration and barrier-property testing modules.
Industry Challenges
- Multi-protocol technician scarcity:Operators capable of calibrating mechanical, optical, and chemical testing functions within single platforms command premium wages and extended recruitment cycles.
- Legacy gauge integration friction:Brownfield textile mills in Bangladesh and Pakistan face downtime costs when retrofitting automated systems alongside mechanical testers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Tester Market |
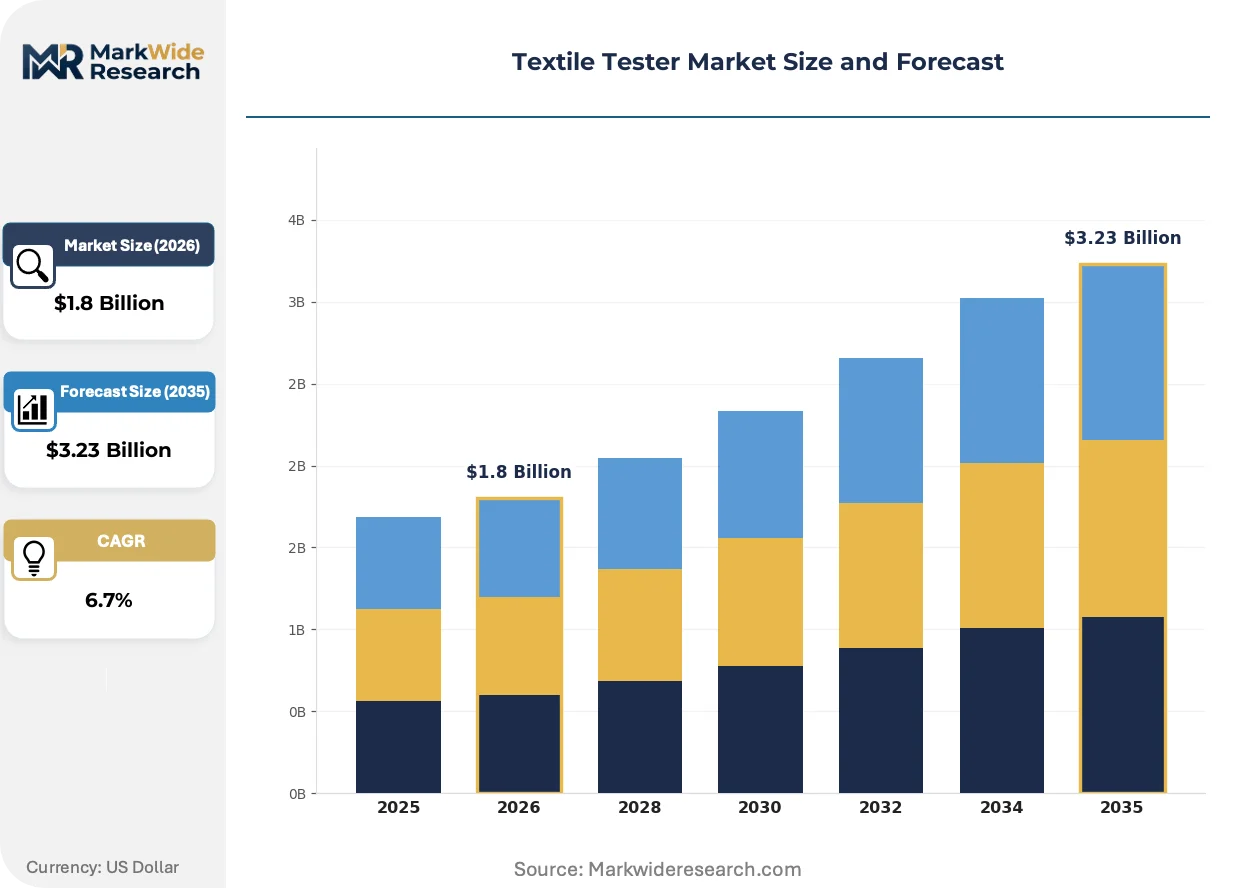
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fabric Tester, Color Fastness Tester, Strength Tester, Moisture Analyzer End User: Manufacturers, Quality Control Labs, Research Institutions, Retailers Technology: Mechanical Testing, Chemical Analysis, Optical Testing, Digital Measurement Application: Textile Production, Quality Assurance, Research & Development, Compliance Testing |
| Companies Covered | SGS Group, Bureau Veritas SA, Intertek Group Plc, AMETEK Inc., Qualitest International Inc., TUV SUD Group, TUV Rheinland Group, TESTEX Textile Testing Instruments, Eurofins Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Tester Market Strategic Shifts
Digital measurement technology is capturing the fastest expansion as manufacturers replace manual gauges with automated vision systems and IoT-connected sensors. Three developments are restructuring competitive requirements and buyer expectations.
Automated vision inspection systems are overtaking manual color-matching and defect-detection workflows in woven and knit finishing departments. Premium apparel manufacturers in Portugal and Turkey are deploying these platforms at line speed to eliminate batch-to-batch variation. The shift is compressing quality assurance headcount while raising capital intensity for tier-one suppliers.
REACH compliance deadlines are forcing investments in chromatography and mass spectrometry modules for restricted substance screening. European textile importers must verify SVHC thresholds across entire supply chains before customs clearance. Third-party certification laboratories in Rotterdam and Antwerp are expanding capacity to capture this mandated testing volume.
Buyers are consolidating vendor relationships around multi-protocol service contracts rather than discrete instrument purchases. Large garment exporters in Vietnam and Bangladesh now negotiate bundled calibration, maintenance, and certification coverage across their factory networks. This behavior concentrates procurement authority among testing service providers with regional laboratory footprints.
Textile Tester Market Segmentation
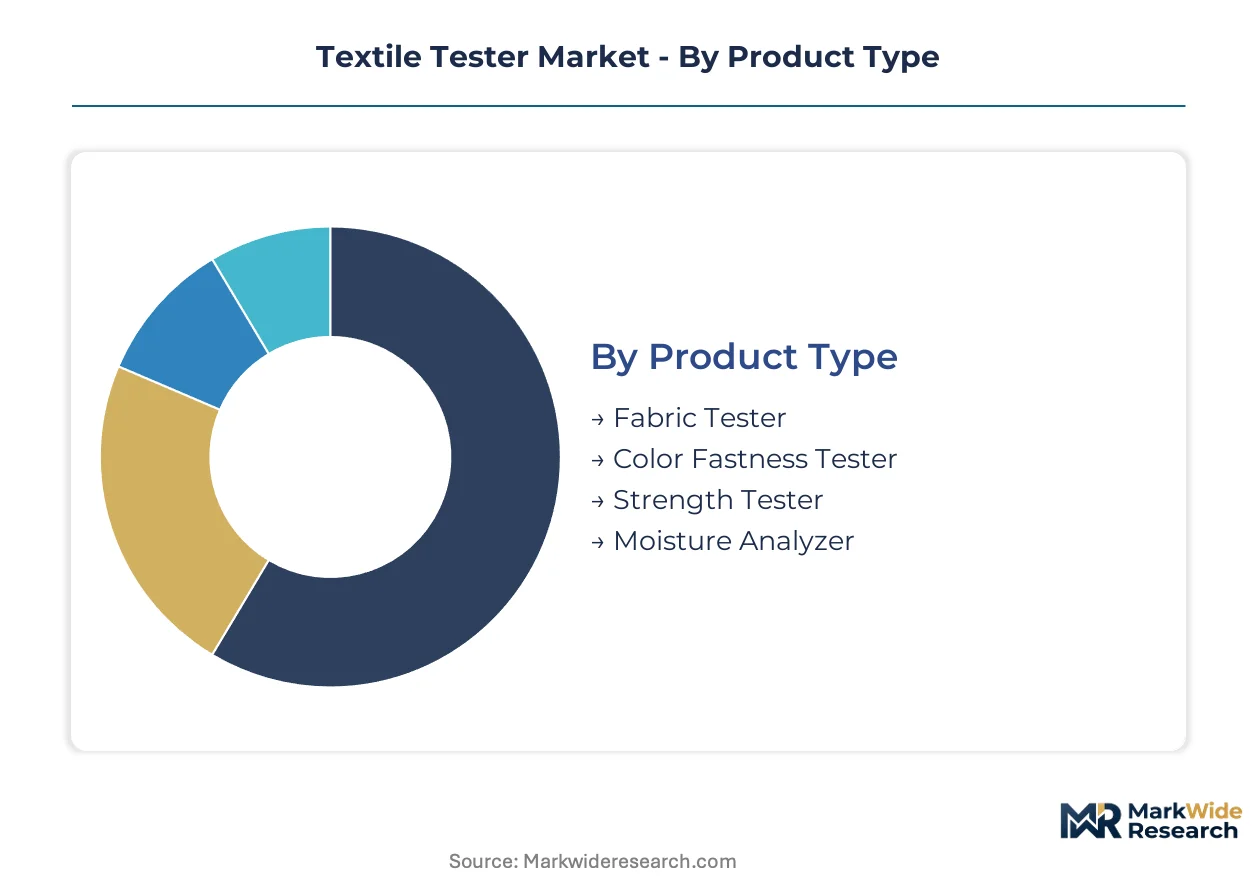
Textile tester procurement patterns diverge sharply by operational scale and regulatory exposure. Manufacturers prioritize throughput-optimized platforms for production-line integration, while compliance-driven buyers demand multi-protocol certification capabilities that third-party laboratories alone can provide.
Product Type:
Cost tier separates buyers seeking single-function instruments from those investing in bundled platforms.
- Fabric Tester:These instruments measure tensile strength, abrasion resistance, and dimensional stability across woven and knit constructions. Automotive upholstery suppliers in Germany and Japan deploy high-capacity units for flame-retardant certification of seat fabrics and headliners. Volume sits with fabric testers; growth tilts toward color fastness testers.
- Color Fastness Tester:Accelerated weathering chambers and crocking devices evaluate dye permanence under friction, light, and laundering stress. Premium apparel manufacturers in Portugal and Turkey are replacing manual color-matching with automated spectrophotometry to eliminate batch-to-batch variation.
- Strength Tester:Force measurement systems calibrated from millinewtons to kilonewtons quantify yarn tenacity and seam slippage for technical textile applications.
- Moisture Analyzer:Gravimetric and capacitive sensors determine residual moisture content in fiber bales and finished goods to prevent mold and dimensional distortion.
Revenue concentrates in fabric and strength testing; fastest expansion is occurring in color fastness instrumentation.
End User:
Application maturity distinguishes legacy manufacturing operations from emerging certification service providers.
- Manufacturers:In-house quality departments at garment factories and weaving mills deploy testers for lot release and process control. Vietnam's export-oriented production zones in Ho Chi Minh City and Hanoi are absorbing multi-protocol platforms to serve fast-fashion and technical apparel buyers.
- Quality Control Labs:Independent testing facilities offer third-party certification that unlocks customs clearance and retail shelf access. SGS Group and Bureau Veritas SA anchor regional laboratory networks across Asia-Pacific manufacturing hubs.
- Research Institutions:Academic and government laboratories develop novel fiber compositions and sustainable processing methods requiring specialized rheological and thermal analysis capabilities.
- Retailers:Brand owners maintain incoming inspection protocols to verify supplier compliance with material specifications and chemical safety thresholds.
Procurement volume rests with manufacturers; certification requirements are accelerating quality control lab expansion.
Technology:
Supply concentration among Japanese and German precision component suppliers shapes buyer vulnerability to lead-time volatility.
- Mechanical Testing:Load frames, abrasion drums, and pilling boxes apply controlled physical stress to predict garment durability. Brownfield textile mills in Bangladesh and Pakistan face downtime costs when retrofitting automated systems alongside legacy mechanical gauges.
- Chemical Analysis:Chromatography and mass spectrometry modules detect restricted substances under REACH mandates. European textile importers must verify SVHC thresholds across entire supply chains before customs clearance.
- Optical Testing:Microscopy and spectrophotometry systems characterize fiber morphology and color consistency with resolution exceeding human visual acuity.
- Digital Measurement:IoT-connected sensors and automated vision systems enable real-time defect detection on knit and woven production lines. Intertek Group Plc dominates this segment through platforms positioned for smart-factory environments.
Mechanical testing holds the largest installed base; digital measurement is climbing the fastest as manufacturers replace manual gauges.
Application:
Margin structure separates high-volume production testing from premium-priced compliance certification.
- Textile Production:In-line testers monitor yarn tension, fabric weight, and dimensional stability during continuous processing. Speed and durability specifications prioritize mechanical simplicity over analytical depth.
- Quality Assurance:Laboratory-based verification of material properties against buyer specifications commands the largest share of instrument utilization. Third-party certification laboratories in Rotterdam and Antwerp are expanding capacity to capture mandated testing volume.
- Research & Development:Exploratory testing of novel fiber blends and finishing chemistries requires configurable platforms with broad analytical versatility.
- Compliance Testing:Regulatory verification for REACH, FAA textile specifications, and GB standards administered by SAMR generates premium pricing through mandatory third-party certification requirements.
Quality assurance absorbs the greatest instrument hours; compliance testing extracts the highest revenue per test.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters in Asia-Pacific generate instrument demand, while European laboratories concentrate compliance certification capacity. The United States anchors automotive and aerospace testing protocols. This production-consumption divide shapes regional specialization in textile testing infrastructure.
China
GB standards administered by SAMR tighten chemical testing mandates for domestic and imported textiles. Dual carbon goals redirect capital toward lifecycle assessment capabilities in fiber processing hubs. Yangtze River Delta manufacturers in Jiangsu and Zhejiang provinces deploy multi-protocol platforms to serve export garment buyers.
Germany
Automotive upholstery suppliers expand flame-retardant testing coverage for seat fabrics and headliners serving BMW, Mercedes-Benz, and Volkswagen supply chains. REACH compliance deadlines force investments in chromatography modules for restricted substance screening. Stuttgart anchors high-capacity metrology laboratories certifying kilonewton-range instruments.
Vietnam
Export-oriented garment production zones in Ho Chi Minh City and Hanoi absorb configurable testing platforms for fast-fashion and technical apparel buyers. Bureau Veritas SA and SGS Group anchor regional laboratory networks across manufacturing hubs. SAMR-aligned GB standard verification supports re-export compliance for China-bound shipments.
United States
FAA textile specifications for aircraft interiors generate specialized testing demand in aerospace supply chains. NHTSA and OSHA standards extend coverage to automotive upholstery and industrial protective fabrics. Boston and Los Angeles metropolitan areas concentrate third-party certification laboratories serving retail and defense buyers.
Indonesia
Technical textile manufacturing in Surabaya and Bandung generates demand for filtration and barrier-property testing modules. Geotextile production for infrastructure projects requires strength and permeability verification. The country's national standards body aligns testing protocols with ASEAN harmonization frameworks.
Textile Tester Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across testing service and instrument manufacturing segments. The market structure consolidates around multi-protocol service providers with regional laboratory footprints, while instrument fabrication fragments across mechanical, optical, and chemical technology tiers. Three archetypes dominate: integrated testing service networks, precision instrument manufacturers, and modular platform specialists. Competitive moves center on geographic laboratory expansion and digital measurement integration.
Within the integrated service network tier, SGS Group, Bureau Veritas SA, and Intertek Group Plc exemplify archetypes spanning certification, fire-resistance specialization, and smart-factory digital integration respectively. These entities anchor multi-protocol service contracts across Asia-Pacific manufacturing hubs through regional laboratory presence. Their positioning reflects divergent strategic emphases: laboratory network density, specialized compliance programs, and automated vision system convergence.
| Leading Market Players |
|---|
| SGS Group |
| Bureau Veritas SA |
| Intertek Group Plc |
| AMETEK Inc. |
| Qualitest International Inc. |
| TUV SUD Group |
| TUV Rheinland Group |
| TESTEX Textile Testing Instruments |
| Eurofins Scientific |
| Others |
Value Chain & Pricing Dynamics
Precision sensor costs from Japanese and German load cell suppliers cascade through three distinct pricing tiers, with chromatography modules for REACH compliance commanding premium positioning against economy mechanical gauges in South Asian weaving operations.
Pricing Analysis
Cost compression in the economy tier accelerates as Bangladeshi and Pakistani brownfield mills resist automated gauge substitution, while premium multi-protocol platforms for European automotive upholstery absorb pricing power from REACH-mandated certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates bundled service contracts with SGS and Bureau Veritas from discrete instrument purchases and handheld micrometer reliance. Price differentiation hinges on certification level—ISO 17025-accredited laboratories extract substantial premiums over in-house quality departments. Small-batch weavers exhibit acute price sensitivity; compliance-driven automotive suppliers demonstrate inelastic demand.
Supply Chain Analysis
Refurbishment flows for precision load frames and optical encoders concentrate in Stuttgart and Shanghai corridors, extending instrument lifecycles for mid-tier buyers. Component supply draws from Japan, Germany, and China, with chromatography modules and spectrophotometry systems anchored in European and North American fabrication. Raw material dependencies span precision-machined aluminum frames, sapphire optical windows, and rare-earth magnet assemblies for force measurement. Single-source vulnerability permeates kilonewton-range calibration infrastructure, as accredited metrology laboratories remain scarce outside Boston, Stuttgart, and Shanghai. Distribution runs through direct OEM relationships for large garment exporters, regional service networks for quality control labs, and distributor channels for standalone instrument procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The textile tester market is becoming a vertical-integration race as precision sensor supply constraints and multi-protocol technician scarcity push incumbents toward captive component sourcing and in-house certification capabilities.
For Market Incumbents: Hedge against Japanese and German sensor supply concentration by cultivating secondary component relationships in South Korea and Taiwan. Deepen backward integration into precision load cell manufacturing to insulate margins from currency volatility. Defensive capacity expansion in Vietnam's Ho Chi Minh City corridor captures fast-fashion testing demand before Bureau Veritas and SGS consolidate regional laboratory networks. For New Entrants and Emerging Players: Begin with digital measurement platforms for Indonesia's Surabaya geotextile manufacturers, where filtration and barrier-property testing modules face limited incumbent saturation. Target technical textile applications in medical nonwovens and infrastructure geotextiles rather than commoditized fabric strength testing. A calibration-as-a-service model bypasses capital-intensive metrology laboratory buildout while capturing recurring revenue from small-batch weavers. For Investors and Strategic Acquirers: REACH compliance deadline acceleration is the leading indicator that European third-party certification capacity will consolidate around laboratory networks with chromatography and mass spectrometry depth. Long-term viability favors service providers with regional footprints spanning Rotterdam, Antwerp, and Asia-Pacific manufacturing hubs over pure-play instrument fabricators. Acquisition targets should demonstrate multi-protocol bundling capabilities and existing relationships with Vietnam's export garment zones.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Platform Integration | Combines mechanical, optical, and chemical testing to meet REACH and GB standard verification demands. |
| Regional Laboratory Network Expansion | Captures mandated testing volume in Vietnam and Indonesia garment manufacturing corridors. |
| Digital Measurement Convergence | Positions IoT-connected sensors and vision systems for smart-factory textile production environments. |
| Backward Integration into Precision Sensors | Reduces dependency on Japanese and German load cell suppliers exposed to currency volatility. |
| Lifecycle Assessment Capability Investment | Aligns with EU Green Deal chemical-free dye testing and recyclability verification protocols. |
Study Parameters
Trade databases, SAMR regulatory filings, and ECHA substance restriction announcements formed the secondary backbone, cross-referenced against primary interviews with quality control laboratory directors, automotive upholstery procurement leads, and precision instrument calibration technicians. Bottom-up triangulation across Vietnam's Ho Chi Minh City garment zones and Germany's Stuttgart automotive supply chain validated top-down market sizing.
Historical trendline analysis of instrument shipments and service contract values established baseline trajectories across the projection horizon. Segmentation dimensions modeled include product type, end-user archetype, technology tier, and application purpose. CAGRs derived from regression analysis against manufacturing output indices and regulatory compliance deadline schedules. Forecast inputs incorporated REACH implementation timelines and dual carbon goal capital redirection patterns in China.
Underlying measurement precision varies by segment; digital measurement and compliance testing carry tighter precision than economy mechanical gauge estimates. Forecasts reflect assumptions regarding regulatory enforcement consistency and sensor supply chain stability. Practitioners should monitor REACH SVHC list expansion, SAMR GB standard alignment pace, and Vietnam export manufacturing zone growth rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Industrial Laundry Market
Textile Machinery and Equipment
Embroidery Machine Market
Textile Machinery and Equipment
Mexico Screen Printing Mesh Market
Textile Machinery and Equipment
Netted Fabrics Market
Textile Machinery and Equipment
Technical Textile Production Equipment Market
Textile Machinery and Equipment
Textile Mill Electric Drives Market
Textile Machinery and Equipment
Multifunctional Clothes Folding Machine Market
Textile Machinery and Equipment
Electric Fabric Shaver Market
Textile Machinery and Equipment
Global Weaving Machinery Market
Textile Machinery and Equipment
Global Spinning Machinery Market
Textile Machinery and Equipment
Sewing Machine Component Market
Textile Machinery and Equipment
Yankee Dryer Market
Textile Machinery and Equipment
Europe Fabric Shavers Market
Textile Machinery and Equipment
Global Knitting Machinery Market
Textile Machinery and Equipment
Cloth Cutting Machines Market
Textile Machinery and Equipment
Middle East and Africa Textile Films Market