
 Space Semiconductor Market | 2026-2036
Space Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Space Semiconductor Market Analysis
Defense agencies and commercial constellation operators are bifurcating procurement priorities for radiation-hardened electronics. BAE Systems leverages decades of trusted foundry relationships with military satellite programs. Texas Instruments sustains broad catalog coverage across analog and power management die for space-grade applications. Infineon Technologies specializes in silicon carbide and gallium nitride power devices that tolerate extreme thermal cycling in orbital environments.
Space semiconductors are electronic components engineered to withstand ionizing radiation, extreme temperature swings from -55°C to +125°C, and vacuum conditions without performance degradation. These devices employ specialized substrate materials, triple-modular redundancy in logic design, and hermetic packaging to prevent outgassing during prolonged orbital exposure. Power Management integrated circuits currently anchor the largest revenue pool because every satellite bus requires voltage regulation and load switching across multiple power domains. GaN technology is gaining fastest among RF and power segments because its wide bandgap enables higher-frequency operation with reduced mass and thermal load versus legacy gallium arsenide solutions.
NASA'sEEE-INST-002 and ESA's ESCC 5000 qualification specifications govern component screening for American and European missions respectively, creating dual-track certification burdens for suppliers. The U.S. Department of Commerce export controls under EAR Category 9 further restrict foundry access for certain radiation-hardened process nodes. Stakeholders must monitor how ITAR reform discussions and emerging commercial space standards reshape the boundary between restricted military and exportable commercial component grades.
Market Dynamics
Low-Earth orbit constellation deployment is compressing qualification cycles and forcing foundries to reconcile commercial volume economics with heritage reliability protocols developed for geostationary missions.
Growth Catalysts
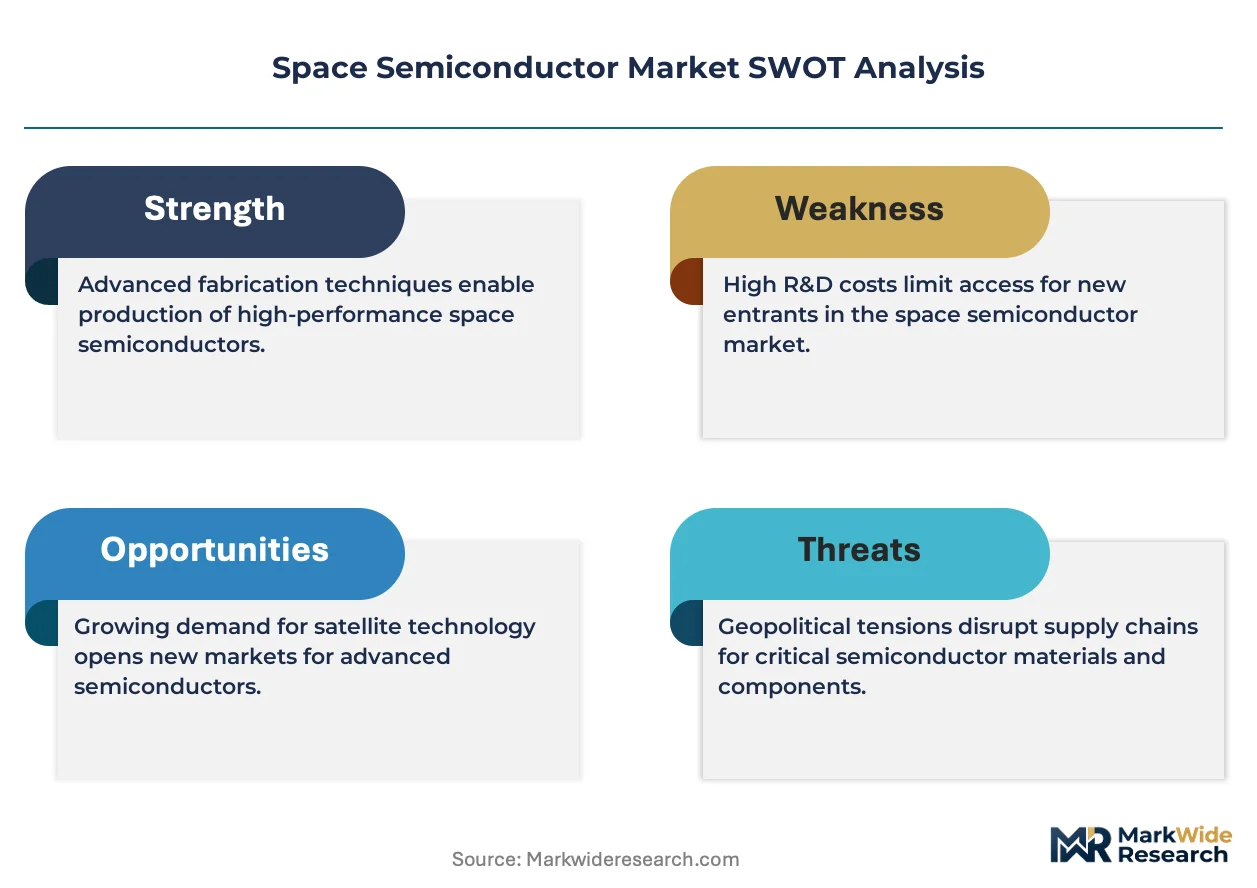
- GaN-on-SiC substrate adoption:Wide bandgap power devices enable higher switching frequencies with reduced thermal mass, cutting satellite bus weight for mega-constellation operators.
- ESA's ESCC 5000 qualification tightening:Stricter reliability benchmarks are filtering marginal suppliers and consolidating procurement around qualified foundries with proven radiation-hardened process libraries.
- Space Force resilient architecture mandates:Disaggregated satellite designs require distributed electronics rather than centralized processing, multiplying component counts per platform.
Market Restraints
- Qualified substrate scarcity:Silicon carbide wafer supply concentrates among a handful of vendors, creating input cost volatility for power device fabricators.
- Dual-track certification burden:NASA's EEE-INST-002 and ESA's ESCC 5000 impose non-harmonized test protocols, forcing redundant qualification spending for transatlantic suppliers.
- ITAR process node restrictions:U.S. Department of Commerce export controls under EAR Category 9 limit foundry access for certain radiation-hardened geometries, fragmenting supply options.
Strategic Opportunities
- Commercial space standard emergence:Industry consortia are developing intermediate reliability grades between full military qualification and terrestrial commercial, opening procurement to broader supplier bases.
- On-orbit servicing electronics:Refueling and repair missions require fault-tolerant computing for autonomous rendezvous, creating demand for rad-hard motor controllers and precision timing devices.
- India's Gaganyaan human spaceflight program:Indigenous crewed missions are accelerating local foundry partnerships and qualification infrastructure investment.
Industry Challenges
- Radiation effects engineering talent scarcity:Single-event upset modeling and hardened cell design require specialized expertise concentrated among aging practitioners in defense-aerospace ecosystems.
- Qualification timeline compression:Commercial constellation procurement cycles demand 18-24 month component availability, while traditional radiation lot acceptance testing requires 36-48 months.
- Hermetic packaging capacity constraints:Ceramic package supply for space-grade die lags wafer fabrication expansion, creating assembly bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Semiconductor Market |
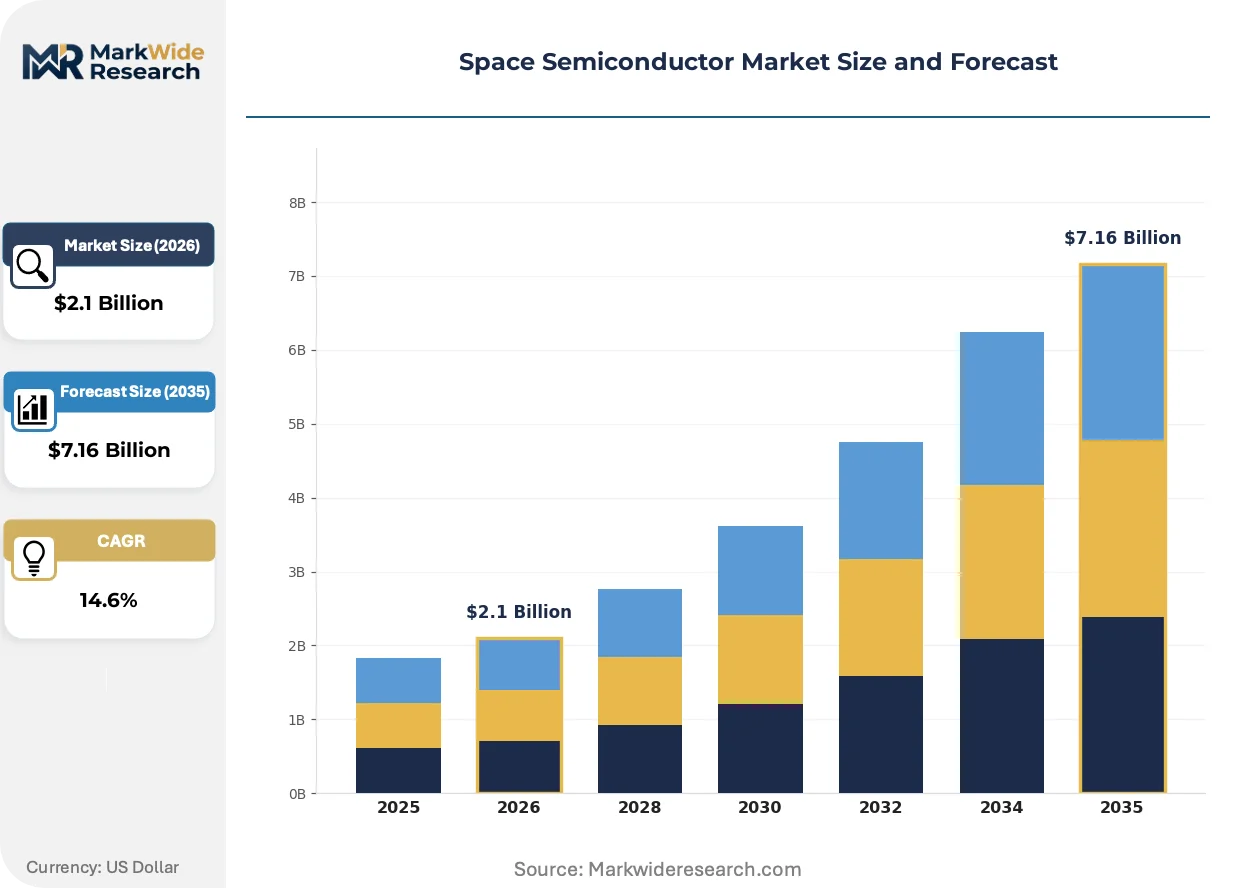
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.16 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Mixed-Signal, Power Management Technology: RF, CMOS, GaN, SiGe End User: Aerospace, Satellite Manufacturers, Research Institutions, Defense Application: Communication, Navigation, Remote Sensing, Scientific Exploration |
| Companies Covered | BAE Systems, RTX Corporation, STMicroelectronics, Thales Group, Lockheed Martin, Texas Instruments, Northrop Grumman, Teledyne Technologies, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Semiconductor Market Emerging Trajectories
Radiation-hardened electronics are undergoing architectural transformation as commercial space operators reject heritage cost structures while defense programs demand greater resilience against orbital threats.
System-in-package integration is miniaturizing satellite payload electronics by stacking memory, processing, and power management die within single hermetic enclosures. Constellation operators are adopting these modules aggressively to compress board area and reduce launch mass. This integration is miniaturizing traditional discrete component supply chains into consolidated subsystem procurement relationships.
REACH substance restrictions are forcing reformulation of solder alloys and conformal coatings used in space-grade assemblies. European satellite prime contractors are requalifying material sets to eliminate restricted substances from supply chains. ESA component procurement specifications are being revised to mandate compliant chemistries, affecting foundries serving European science and navigation missions.
Buyer concentration among mega-constellation operators is compressing supplier negotiation leverage and forcing fixed-price contracting for multi-year component supply. Tier-two foundries are responding by forming consortia to aggregate qualification costs and standardize process libraries. This consolidation is most visible in the United States, where SpaceX and Amazon's Project Kuiper anchor procurement volumes for radiation-hardened power management and RF components.
Space Semiconductor Market Segmentation
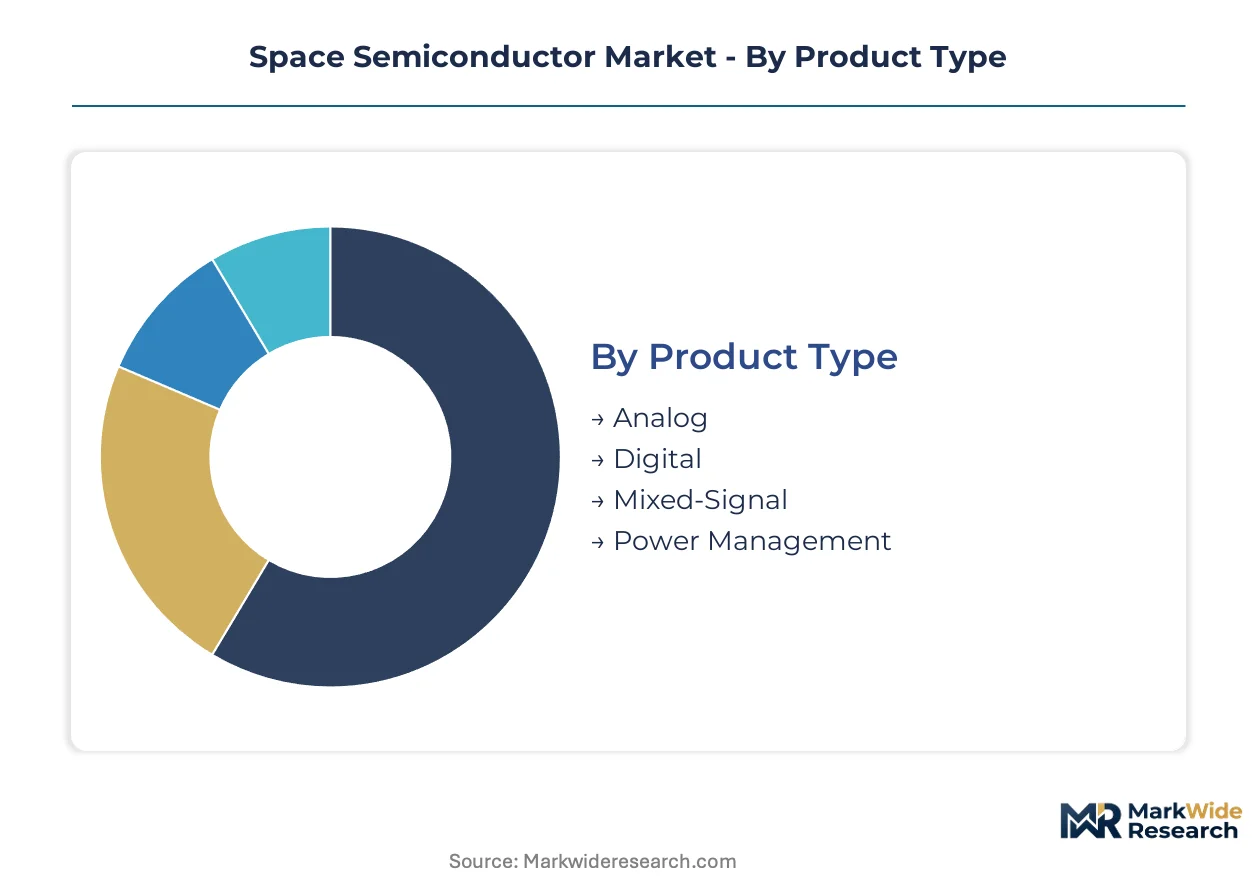
Segmentation in space semiconductors reveals how qualification standards, orbital mission profiles, and procurement hierarchies fragment supply relationships. Each dimension carries distinct regulatory overlays and technical performance thresholds that reshape vendor positioning.
Product Type:
NASA's EEE-INST-002 and ESA's ESCC 5000 impose divergent screening protocols across analog, digital, and power functions, creating non-interchangeable procurement tracks for transatlantic suppliers.
- Power Management:Voltage regulators, load switches, and DC-DC converters handle multiple power domains across satellite buses. Demand concentrates with mega-constellation operators in the United States where SpaceX and Amazon's Project Kuiper anchor procurement volumes for radiation-hardened power components.
- Analog:Operational amplifiers, voltage references, and data converters maintain signal integrity across extreme temperature swings. Satellite manufacturers in Europe prioritize these devices for science and navigation missions under tightening ESA qualification benchmarks.
- Digital:Processors and logic devices employ triple-modular redundancy to mitigate single-event upsets. Defense programs in the United States drive procurement through Space Force resilient architecture mandates.
- Mixed-Signal:ADCs and DACs bridge analog sensor outputs with digital processing chains. Research institutions leverage these for payload instrumentation requiring precision timing.
Established volume favors Power Management; emerging adoption favors Mixed-Signal.
Technology:
Substrate material selection directly determines thermal tolerance, switching frequency capability, and qualification timeline compression for commercial constellation deployment.
- GaN:Gallium nitride on silicon carbide substrates enables higher-frequency RF and power operation with reduced mass versus legacy solutions. Satellite manufacturers expanding low-Earth orbit constellations drive fastest adoption for cutting bus weight.
- CMOS:Complementary metal-oxide-semiconductor processes anchor digital logic and memory functions with mature radiation-hardened cell libraries. United States foundry capacity concentrates procurement for NASA and Space Force programs.
- RF:Specialized radio frequency processes handle uplink/downlink communications and radar payloads. Defense agencies in the United States bifurcate procurement between trusted heritage suppliers and commercial-grade alternatives.
- SiGe:Silicon germanium offers intermediate performance for mixed-signal applications requiring moderate radiation tolerance. Research institutions leverage these for cost-sensitive science missions.
Procurement gravity centers on GaN for new designs; CMOS sustains replacement demand.
End User:
Customer type determines contract structure, with defense programs mandating fixed-price multi-year supply and commercial operators compressing qualification cycles.
- Satellite Manufacturers:Prime contractors integrate radiation-hardened components across bus and payload subsystems. Low-Earth orbit constellation proliferation in the United States drives volume procurement through concentrated buyer relationships.
- Defense:Military satellite programs require ITAR-controlled process nodes and trusted foundry relationships. United States Space Force disaggregated architecture mandates multiply component counts per platform.
- Aerospace:Crewed mission electronics demand higher reliability grades for human-rated systems. India's Gaganyaan program accelerates indigenous foundry partnerships.
- Research Institutions:Science missions prioritize precision timing and low-noise instrumentation for deep-space exploration. European Space Agency procurement specifications govern component selection.
Defense anchors premium pricing; commercial satellite manufacturing scales volume.
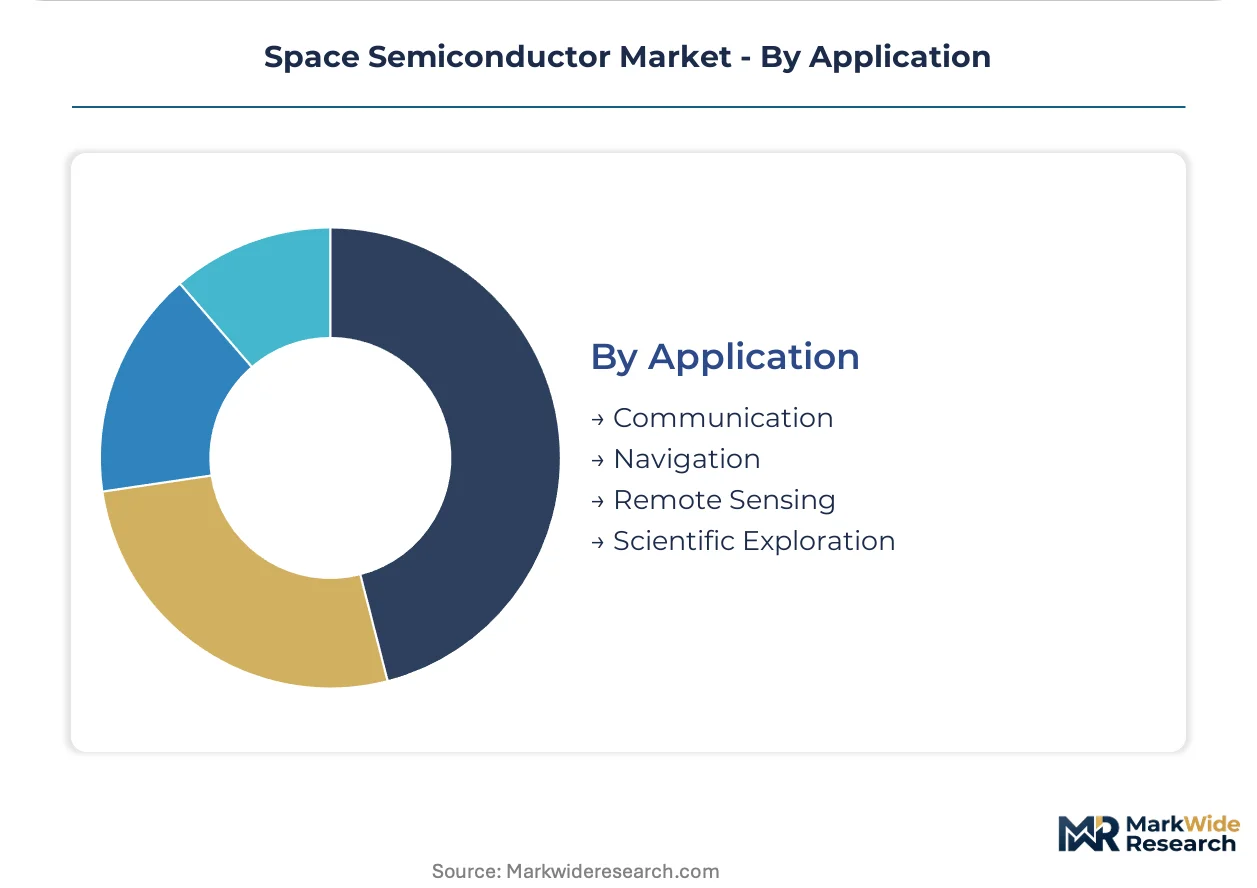
Application:
Mission function dictates radiation tolerance thresholds, with communication payloads requiring continuous operation and scientific instruments demanding precision stability.
- Communication:RF power amplifiers and digital signal processors enable broadband connectivity for mega-constellations. GaN technology displaces gallium arsenide for higher-frequency operation with reduced thermal load.
- Remote Sensing:Imaging payloads require low-noise analog front-ends and high-speed data converters. Satellite manufacturers prioritize system-in-package integration to compress board area.
- Navigation:Timing and positioning electronics demand atomic clock stability and radiation-hardened precision. European Galileo constellation procurement follows ESCC 5000 protocols.
- Scientific Exploration:Deep-space instruments tolerate extended qualification timelines for extreme reliability. NASA programs govern procurement through EEE-INST-002 specifications.
Communication commands production scale; scientific exploration sustains qualification heritage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German foundries export radiation-hardened power components to satellite manufacturers in France and the United States. Japan supplies precision timing devices to deep-space missions operated by NASA and ESA. South Korean memory fabricators serve constellation operators seeking high-reliability storage for low-Earth orbit platforms.
United States
Space Force disaggregated architecture mandates and NASA deep-space programs drive procurement of rad-hard processors and power management ICs. The Department of Commerce administers EAR Category 9 export controls that restrict foundry access for certain radiation-hardened geometries. Colorado's Front Range corridor hosts satellite prime contractors integrating components from domestic qualified foundries.
Germany
Infineon Technologies anchors European supply of silicon carbide power devices for thermal-cycling tolerance in orbital environments. The national aerospace regulator collaborates with ESA on ESCC 5000 qualification protocol implementation. Bavaria's semiconductor cluster around Munich concentrates substrate processing and hermetic packaging capacity for space-grade die.
France
Thales Group leverages trusted foundry relationships for military satellite electronics serving defense procurement agencies. ANSM oversees material compliance for REACH-restricted substances in space-grade solder alloys and conformal coatings. The Toulouse aerospace cluster integrates rad-hard components across payload subsystems for European navigation and Earth observation missions.
Japan
METI coordinates national investment in radiation-hardened CMOS process development for indigenous space programs and export markets. The Kyushu semiconductor corridor hosts foundries specializing in mixed-signal devices for scientific instrumentation requiring precision stability.
India
ISRO's Gaganyaan human spaceflight program accelerates local foundry partnerships and qualification infrastructure for crewed mission electronics. BIS develops national standards aligned with international space-grade component specifications. Karnataka's Bangalore-Tumkur corridor concentrates satellite subsystem integrators sourcing from emerging domestic semiconductor fabricators.
Space Semiconductor Market Vendor Landscape
Player mix skews toward defense-aerospace conglomerates with captive semiconductor divisions and diversified analog specialists with space-qualified process libraries. Market structure concentrates procurement around a handful of qualified foundries holding dual NASA and ESA certifications. Three archetypes dominate: integrated defense primes with trusted foundry access, broad-line analog suppliers with radiation-hardened catalog depth, and wide-bandgap power device specialists. Competitive moves center on strategic partnerships to aggregate qualification costs and capacity expansion in hermetic packaging to resolve assembly bottlenecks.
Among defense-aerospace conglomerates, BAE Systems, RTX Corporation, and Lockheed Martin occupy positions anchored by decades of military satellite program relationships. These entities exemplify the integrated prime archetype where captive semiconductor divisions serve restricted procurement channels. Texas Instruments and STMicroelectronics represent the diversified analog specialist tier, sustaining broad catalog coverage across voltage regulation and signal conditioning functions. Infineon Technologies sits within the wide-bandgap power device specialization, supplying silicon carbide and gallium nitride components that tolerate extreme thermal cycling. Thales Group, Northrop Grumman, and Teledyne Technologies each anchor regional supply relationships through qualified foundry partnerships.
| Leading Market Players |
|---|
| BAE Systems |
| RTX Corporation |
| STMicroelectronics |
| Thales Group |
| Lockheed Martin |
| Texas Instruments |
| Northrop Grumman |
| Teledyne Technologies |
| Infineon Technologies |
| Others |
Supply Flow & Price Mechanics
GaN-on-SiC substrate substitution for legacy gallium arsenide RF components is redrawing procurement geography toward United States and German foundries while compressing price premiums for wide-bandgap power devices. This materials transition simultaneously elevates input costs for silicon carbide wafers and collapses pricing power for gallium arsenide incumbent suppliers.
Pricing Analysis
GaN-on-SiC commands a technology-generation premium over legacy GaAs solutions while CMOS-based rad-hard logic sustains replacement-cycle pricing. Three-tier pricing structure across full military qualification, commercial space-grade, and terrestrial industrial levels separates heritage defense programs from mega-constellation procurement. Cost compression in commercial space-grade tiers is intensifying because SpaceX and Amazon's Project Kuiper negotiate multi-year fixed-price contracts. Commercial constellation operators exhibit highest price sensitivity; defense programs anchored by ITAR restrictions show lowest sensitivity.
Supply Chain Analysis
Silicon carbide wafer supply concentrates among United States, German, and Japanese substrate vendors, creating single-source vulnerability for power device fabricators. Qualified foundry capacity draws from radiation-hardened process libraries concentrated in Colorado's Front Range, Bavaria's Munich cluster, and Japan's Kyushu corridor. Ceramic hermetic packaging capacity lags wafer fabrication expansion, generating assembly bottlenecks. Distribution runs through satellite prime contractor direct procurement rather than distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical upswing driven by low-Earth orbit constellation deployment, with qualification cycle compression favoring suppliers with existing dual NASA-ESA certifications.
For Market Incumbents: Secure hermetic packaging capacity expansion ahead of wafer fabrication growth to resolve assembly bottlenecks threatening delivery commitments. Deepen backward integration into silicon carbide substrate supply to mitigate qualified wafer scarcity volatility. Lock in multi-year offtake agreements with SpaceX and Amazon's Project Kuiper before commercial space standards dilute certification barriers. For New Entrants and Emerging Players: Anchor in India's Gaganyaan program qualification infrastructure buildout, where indigenous foundry partnerships lack established supplier relationships. Target on-orbit servicing electronics for autonomous rendezvous missions, a segment with nascent vendor presence and fault-tolerant computing requirements. Pursue ESA ESCC 5000 pre-qualification to access European science and navigation mission procurement. For Investors and Strategic Acquirers: The market sits at an early-expansion phase that favors acquisition of qualified foundries with dual NASA-ESA certifications over greenfield capacity investment. Long-term viability rests on consolidation of radiation effects engineering talent concentrated among aging defense-aerospace practitioners. Watch ITAR reform discussions as the signal indicating boundary shifts between restricted military and exportable commercial component grades.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Simultaneous NASA EEE-INST-002 and ESA ESCC 5000 qualification opens transatlantic procurement channels. |
| Hermetic Packaging Capacity Expansion | Ceramic package supply addition resolves assembly bottlenecks constraining rad-hard die output. |
| GaN-on-SiC Process Library Development | Wide-bandgap power device qualification captures mega-constellation weight-reduction procurement. |
| Radiation Effects Engineering Acquisition | Talent consolidation addresses single-event upset modeling expertise scarcity. |
| Commercial Space Standard Alignment | Intermediate reliability grade positioning anticipates industry consortium specification emergence. |
Methodological Framework
Initial hypotheses were tested against primary input from satellite prime contractor procurement directors, radiation-hardened foundry process engineers, and Space Force program managers and refined through secondary validation. Primary fieldwork encompassed component qualification specialists at ESA and NASA, hermetic packaging vendors, and GaN substrate suppliers. Secondary sources included EEE-INST-002 and ESCC 5000 specification documents, Department of Commerce EAR Category 9 control lists, and satellite manufacturer procurement disclosures. Bottom-up demand modeling triangulated against top-down addressable market sizing.
Variance decomposition across product type, technology node, end-user category, and orbital mission application anchored the analytical framework. Segmentation dimensions modeled encompass power management function, substrate material, customer contract structure, and radiation tolerance threshold. CAGRs derived from fitted growth curves applied to qualification-corrected adoption rates. Industry-specific forecast inputs included mega-constellation deployment schedules and Space Force architecture mandate implementation timelines.
Material uncertainties — ITAR reform trajectory, commercial space standard adoption pace, silicon carbide wafer supply expansion — sit outside the modeled envelope. Forecasts reflect assumptions regarding qualification timeline compression limits and dual-track certification harmonization. Practitioners should keep alternative scenarios live as ESA procurement specification revisions and REACH substance restriction implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
LAMEA Space As a Service Market
Space
Space Launch Services Market
Space
US Reusable Launch Vehicle Market
Space
US Space Launch Services Market
Space
Electrically Powered Spacecraft Propulsion Market
Space
Astronaut Spacesuit Market
Space
Space-Based Solar Power Market
Space
Orbital Spaceflight Market
Space
Africa Space Electronics Market
Space
Space Ground System Market
Space
North America Spacesuit Market
Space
UK Space Propulsion System Market
Space
Space Sensors Market
Space
Rocket Launchpad Market
Space
Space Robotics Market
Space
Space Burial Service Market