
 Space Launch Services Market | 2026-2036
Space Launch Services Market Size, Share, and Industry Trends Forecast 2026-2036
Space Launch Services Market Analysis
Launch procurement channels for government and commercial payloads is rewriting how operators secure orbital access. SpaceX leverages vertical integration across rocket manufacturing, launch operations, and satellite deployment to control cost structures. United Launch Alliance sustains long-term national security contracts through Atlas and Vulcan vehicle families. Rocket Lab specializes in dedicated small satellite missions via its Electron rocket, occupying a distinct niche below heavy-lift competitors.
Space launch services encompass the end-to-end provision of orbital and suborbital payload delivery, including vehicle integration, range operations, and mission management, typically measured by payload mass to specific orbital altitudes and inclinations. The primary commercial purpose is placing satellites, scientific instruments, and crewed spacecraft into targeted trajectories with precision and reliability. Reusable launch vehicles are capturing margin pools through reduced refurbishment cycles and faster turnaround times between missions. Small satellite launch vehicles face structural pressure as rideshare options on heavy-lift rockets absorb price-sensitive demand from emerging constellation operators. Government end users maintain premium pricing tolerance for assured access to strategic orbits and responsive launch capabilities.
FAA licensing governs commercial launch operations in the United States, while FCC spectrum and orbital debris rules shape payload operator behavior. ESA member state regulations and EU space traffic management frameworks are tightening coordination requirements for congested orbital regimes. Military end users in multiple jurisdictions now mandate rapid launch responsiveness and supply chain security as baseline procurement criteria. Stakeholders must monitor how national security classifications and export control lists reshape vendor eligibility and cross-border partnership structures.
Market Dynamics
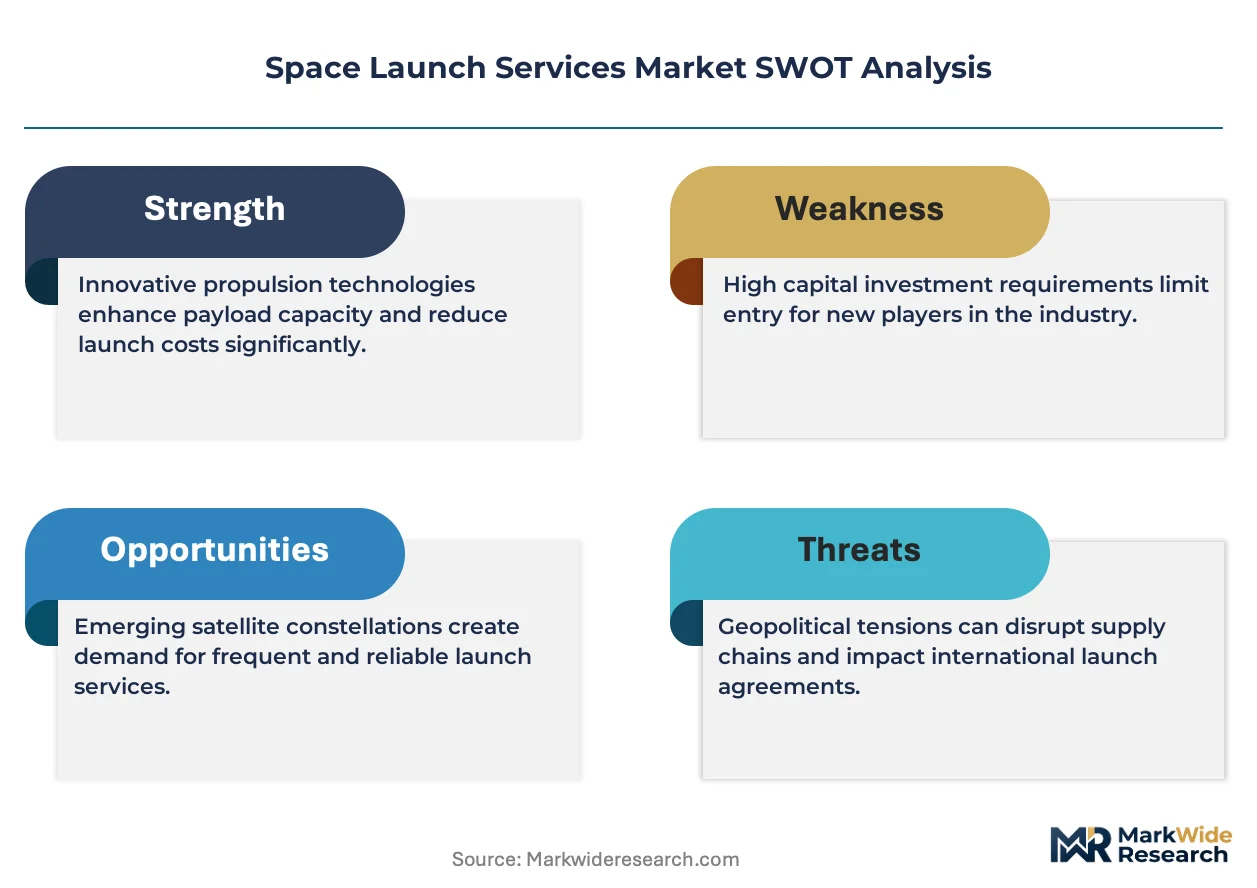
Reusable first-stage recovery is compressing marginal launch costs and forcing legacy expendable architectures into obsolescence. This single technological inflection is redistributing contract volumes toward operators with proven rapid-reuse capabilities.
Growth Catalysts
- LEO constellation deployment:Broadband satellite operators are procuring dedicated launch slots at scale. This end-use segment now accounts for the majority of commercial manifest bookings.
- FAA streamlined licensing:The regulator's Part 450 framework is reducing approval timelines for commercial orbital flights. Launch providers are accelerating cadence in response.
- India's spaceport expansion:Satish Dhawan Space Centre capacity additions are creating new Eastern launch azimuth options. This geography is attracting rideshare payloads previously concentrated at Cape Canaveral.
Market Restraints
- Engine supply concentration:Liquid oxygen/kerosene engine fabrication depends on a narrow supplier base in Russia and Ukraine. Disruption risk persists despite Western substitution efforts.
- Range capacity saturation:Eastern and Western launch ranges face scheduling bottlenecks. This infrastructure constraint limits annual launch cadence regardless of vehicle availability.
- Orbital debris liability:FCC conjunction assessment requirements are extending insurance costs and mission planning complexity. Smaller operators face disproportionate compliance burdens.
Strategic Opportunities
- Point-to-point suborbital cargo:Military logistics commands are evaluating rapid payload delivery to contested theaters. This application could unlock demand beyond traditional satellite markets.
- EU space traffic management:The bloc's collision avoidance service mandates are creating data-analytics revenue streams. Ground segment providers are positioning for service contracts.
- In-orbit servicing convergence:Robotic refueling and life-extension technologies are extending satellite operational lifespans. Launch demand is fragmenting across initial deployment and replacement cycles.
Industry Challenges
- Propulsion engineering scarcity:Turbomachinery and combustion specialist talent pools are shallow. Recruiting timelines are extending program development schedules.
- Type certification timelines:New vehicle families require extensive flight-heritage accumulation before qualifying for national security payloads. This validation period strains balance sheets.
- Supply chain reconfiguration:ITAR-controlled component sourcing is forcing dual-source strategies. Integration complexity is rising as providers qualify alternative vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Launch Services Market |
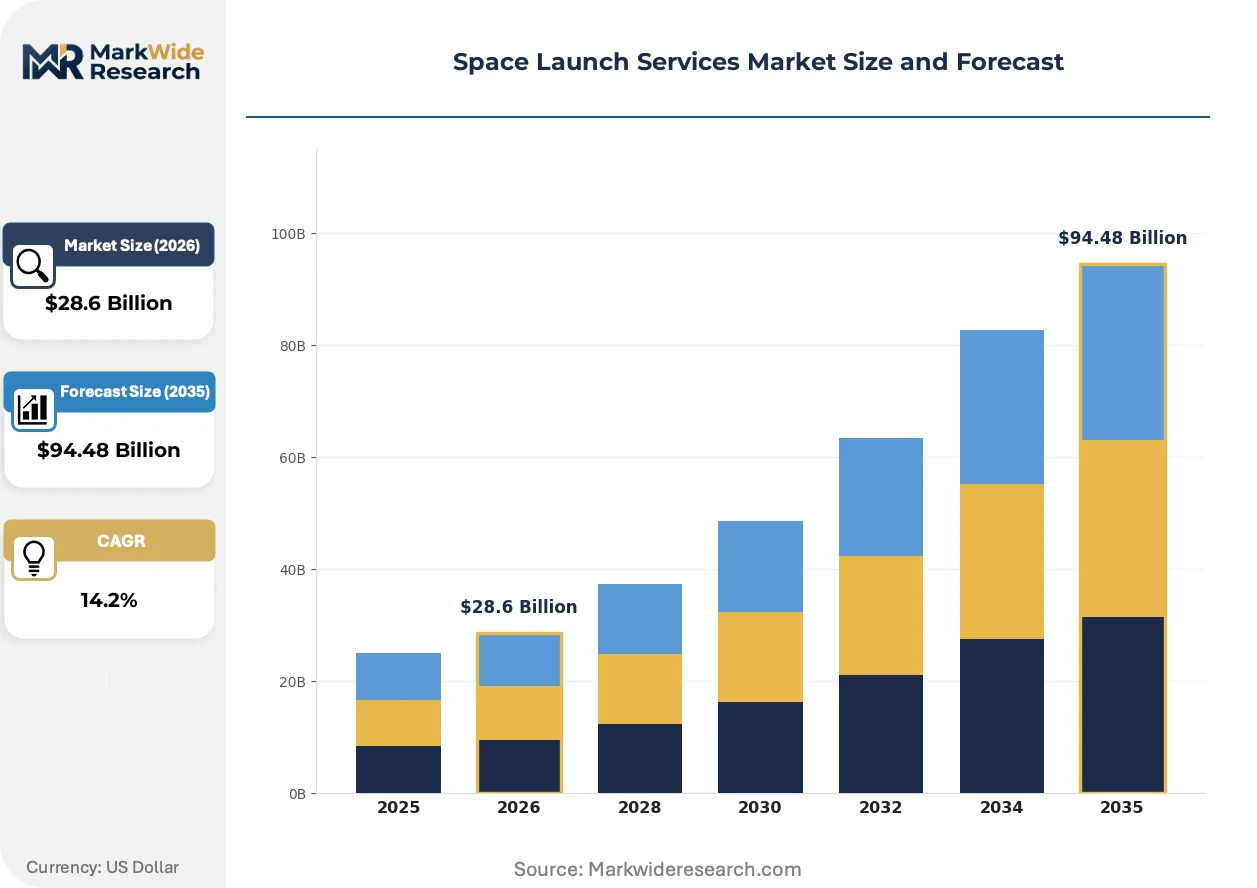
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Suborbital, Orbital, Dedicated, Rideshare Launch Vehicle: Expendable Launch Vehicle, Reusable Launch Vehicle, Small Satellite Launch Vehicle, Heavy-Lift Launch Vehicle End User: Government, Commercial, Research Institutions, Military Payload Type: Satellite, Scientific Probe, Cargo, Spacecraft |
| Companies Covered | SpaceX, United Launch Alliance, Arianespace, Blue Origin, China Aerospace Science and Technology Corporation, Northrop Grumman, Rocket Lab, Mitsubishi Heavy Industries, Antrix Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Launch Services Market Emerging Trajectories
Digital thread integration across design, manufacturing, and mission operations is compressing iteration cycles. This connectivity layer is enabling predictive maintenance and real-time anomaly detection previously unavailable to launch operators.
Autonomous flight safety systems are digitizing range operations and reducing ground-control staffing requirements. The FAA is mandating these capabilities for new vehicle certifications. Commercial operators are retrofitting existing fleets to maintain launch eligibility.
EU orbital debris mitigation rules are tightening post-mission disposal requirements for all spacecraft above specific mass thresholds. Satellite operators must now demonstrate deorbit capability prior to FCC or national regulator licensing. Constellation planners are redesigning spacecraft for active propulsion or passive drag augmentation.
Consolidated manifest purchasing is displacing spot-market rideshare bookings among large constellation operators. These buyers are negotiating multi-launch blocks with dedicated schedule guarantees. Price transparency is eroding as contracts shift from published price lists to privately negotiated enterprise agreements.
Space Launch Services Market Segmentation
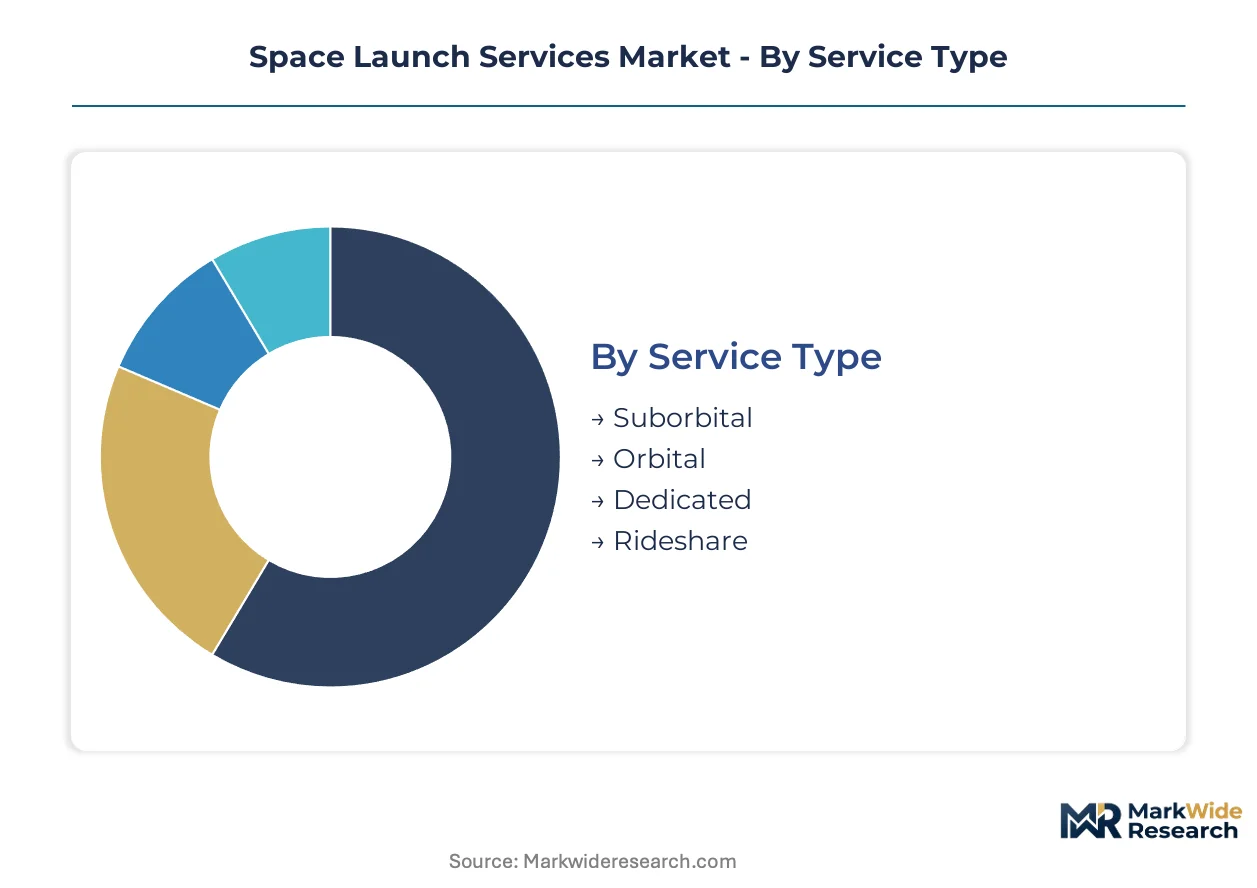
Segmentation in space launch services reveals how procurement patterns split across technical specifications, customer risk tolerance, and payload scale. Understanding these divisions exposes where pricing power concentrates and which vehicle architectures capture recurring demand.
Service Type:
Cycle times vary dramatically across service models, with rideshare missions turning weekly while dedicated orbital contracts span months of pre-launch integration.
- Suborbital:Brief trajectory missions reaching space without orbital insertion, typically for microgravity research and technology demonstration. Research institutions in the United States dominate procurement through NASA Flight Opportunities program contracts. These flights compress from contract signature to launch in under ninety days.
- Orbital:Full payload delivery to sustained Earth orbits, requiring precise trajectory calculations and extended mission planning. Commercial satellite constellation operators in the United States book the majority of annual orbital slots. Mission timelines extend twelve to twenty-four months from contract to launch.
- Dedicated:Exclusive vehicle allocation for single-payload missions with schedule certainty and custom integration. Government agencies pay substantial premiums for assured access to specific orbital planes.
- Rideshare:Secondary payload accommodation on missions with excess capacity, traded at per-kilogram spot rates. Small satellite operators accept schedule uncertainty for cost reduction.
Orbital services anchor the volume base while rideshare gains share at the steepest rate.
Launch Vehicle:
Cost tiers stratify sharply, with heavy-lift vehicles commanding tenfold premiums over small satellite alternatives yet delivering substantially lower per-kilogram economics.
- Expendable Launch Vehicle:Single-use architecture with no recovery systems, historically dominant but now losing share to reusable alternatives. National security payloads in the United States still mandate expendable vehicles for certain high-energy orbits.
- Reusable Launch Vehicle:First-stage recovery and rapid refurbishment capabilities, resetting industry cost structures through flight-proven turnaround cycles. Commercial constellation operators in the United States now specify reusable vehicles in procurement tenders. This segment captures the majority of new commercial manifest growth.
- Small Satellite Launch Vehicle:Purpose-built for payloads under five hundred kilograms to low Earth orbit, offering schedule responsiveness at higher per-kilogram rates. Emerging operators face pressure from rideshare competition on heavy-lift vehicles.
- Heavy-Lift Launch Vehicle:Maximum payload capacity exceeding twenty metric tons to geostationary transfer orbit, serving large geostationary satellites and interplanetary missions. Government deep-space exploration programs anchor demand.
Reusable vehicles anchor the volume base while small satellite launch vehicles gain share at the steepest rate.
End User:
Customer type determines pricing tolerance and contract structure, with military procurement emphasizing responsiveness over cost minimization.
- Government:Civil space agencies and national laboratories procuring through multi-year indefinite-delivery contracts. NASA and the FAA shape procurement specifications in the United States. Budget cycles extend across fiscal years with congressional appropriation dependencies.
- Commercial:Satellite operators, telecommunications providers, and private space ventures purchasing on commercial terms. Broadband constellation operators in the United States now represent the largest commercial demand pool. These customers negotiate multi-launch blocks with schedule guarantees.
- Research Institutions:Universities and scientific organizations accessing space through subsidized programs and competitive selection. NASA's CubeSat Launch Initiative provides primary access pathways in the United States.
- Military:Defense departments and intelligence agencies requiring assured access, rapid responsiveness, and supply chain security. The Space Force's National Security Space Launch program sets certification requirements in the United States.
Commercial end users anchor the volume base while military procurement gains share at the steepest rate.
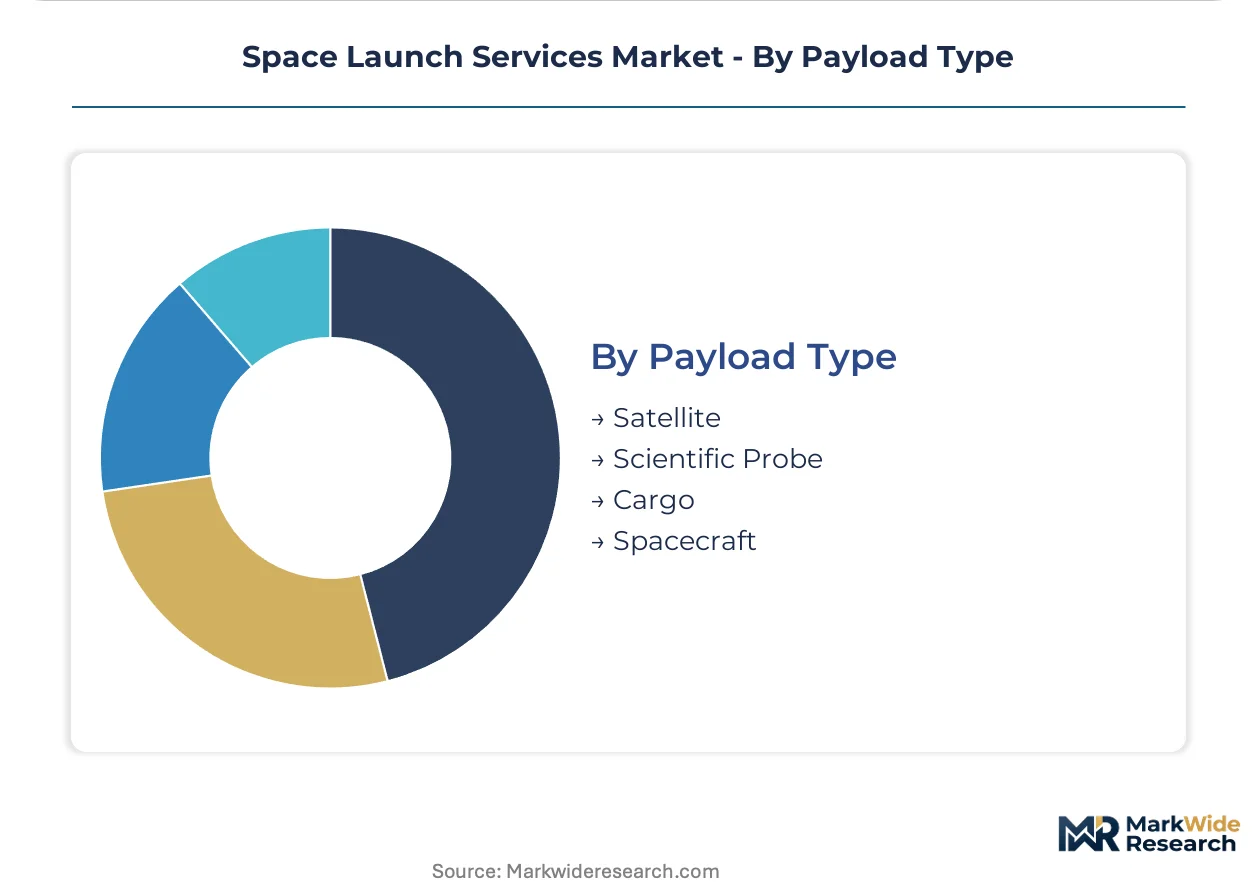
Payload Type:
Application focus shapes integration complexity and insurance requirements, with crewed spacecraft demanding the most extensive safety certification.
- Satellite:Communication, navigation, Earth observation, and technology demonstration spacecraft comprising the overwhelming majority of launched mass. Commercial broadband constellations in the United States drive deployment scale. Satellite payloads require precise separation systems and orbital insertion accuracy.
- Scientific Probe:Instruments designed for planetary exploration, astrophysics, or space environment characterization. NASA's Science Mission Directorate funds the primary demand in the United States. These payloads impose unique thermal, vibration, and electromagnetic compatibility requirements.
- Cargo:Logistics resupply for orbital platforms including food, equipment, and experimental materials. Commercial resupply services contracts to the International Space Station anchor demand in the United States.
- Spacecraft:Crewed vehicles and autonomous platforms with human-rating or high-reliability specifications. Commercial crew transportation services represent the highest-value contract category in the United States.
Satellite payloads anchor the volume base while cargo missions gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while cost-sensitive operators migrate procurement toward India and emerging Eastern launch corridors. This geographic asymmetry reflects infrastructure maturity, regulatory streamlining, and range capacity availability across competing jurisdictions.
United States
Commercial constellation operators and national security programs anchor demand through Cape Canaveral and Vandenberg Space Force Base. The FAA's Part 450 streamlined licensing framework compresses approval timelines for orbital flights. SpaceX, United Launch Alliance, and Blue Origin cluster manufacturing and launch operations across Texas, Florida, and California, capturing the majority of Western commercial manifest bookings.
China
Government-backed lunar and space station programs drive heavy-lift procurement through state-owned launch service providers. The China National Space Administration coordinates civil and military manifest allocation under centralized five-year planning cycles. Wenchang Space Launch Site on Hainan Island anchors southern latitude access for geostationary missions, with Xichang and Jiuquan supporting polar and sun-synchronous trajectories.
India
Cost-competitive rideshare services attract small satellite operators from Europe and Southeast Asia seeking Eastern launch azimuths. The Indian Space Research Organisation manages range operations at Satish Dhawan Space Centre with expanding commercial launch pad capacity. Sriharikota's geographic position enables low-inclination access previously concentrated at Cape Canaveral, fragmenting procurement geography.
France
Arianespace maintains geostationary transfer orbit service dominance through Ariane 6 heavy-lift operations from Guiana Space Centre. The European Space Agency coordinates member state contributions and mission assurance standards across Kourou launch infrastructure. French Guiana's equatorial latitude delivers payload mass advantages for telecommunications satellite operators targeting geostationary slots.
Japan
Precision manufacturing supply chains support H3 rocket development for government and commercial mixed manifests. The Japan Aerospace Exploration Agency governs Tanegashima and Uchinoura range operations under national space policy frameworks. Mitsubishi Heavy Industries anchors domestic vehicle production while pursuing Asia-Pacific commercial contract diversification beyond traditional government anchors.
Space Launch Services Market Vendor Landscape
Vertically integrated launch-stack operators and government-dependent legacy providers split the market along cost-responsiveness and mission-assurance axes. Three archetypes now dominate: rapid-reuse commercial operators capturing price-sensitive commercial volume; state-affiliated incumbents retaining national security and deep-space exploration contracts; and small-lift specialists serving schedule-critical constellation deployment. Competitive moves concentrate on reusable technology maturation and multi-launch block contracting.
Within the rapid-reuse tier, SpaceX exemplifies vertical control across manufacturing, launch operations, and satellite deployment. United Launch Alliance occupies the national security specialist position through long-term indefinite-delivery contracting with the Space Force. Rocket Lab represents the dedicated small-satellite archetype, anchoring responsive launch services below heavy-lift competitors.
| Leading Market Players |
|---|
| SpaceX |
| United Launch Alliance |
| Arianespace |
| Blue Origin |
| China Aerospace Science and Technology Corporation |
| Northrop Grumman |
| Rocket Lab |
| Mitsubishi Heavy Industries |
| Antrix Corporation |
| Others |
Supply Flow & Price Mechanics
Engine supply concentration in Russia and Ukraine determines both the premium spreads between assured-access and spot-market launches and the geographic reconfiguration of propulsion sourcing. Western substitution programs for liquid oxygen/kerosene turbomachinery are compressing margins on expendable vehicles while rewarding vertically integrated domestic producers.
Pricing Analysis
The customization-premium spread separates dedicated government missions from rideshare commodity slots by a factor exceeding ten on per-kilogram economics. Pricing stratifies across premium assured-access tiers for national security payloads, standard commercial constellation blocks, and economy rideshare accommodation on excess capacity. Cost compression in the economy tier is intensifying because heavy-lift reusable vehicles absorb price-sensitive small satellite demand. Research institutions exhibit the highest price sensitivity, accepting eighteen-month schedule uncertainty for fifty percent cost reduction.
Supply Chain Analysis
Contract manufacturing concentration for turbomachinery and combustion chambers rests on a narrow supplier base concentrated in the United States, Russia, and Ukraine. Liquid oxygen/kerosene engine fabrication draws from specialty forging operations in Russia and precision machining clusters in the United States. Single-source vulnerability persists for high-performance turbopump assemblies despite Western dual-source qualification programs. Distribution runs through prime contractor integration facilities in Texas, Florida, and California before range delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is emerging as LEO constellation deployment splits procurement between heavy-lift rideshare and dedicated small-vehicle missions, creating distinct competitive arenas.
For Market Incumbents: Pre-empt emerging small-lift specialists by accelerating reusable medium-lift development before Rocket Lab and similar operators capture schedule-critical constellation deployment contracts. Lock in multi-launch block agreements with broadband operators now negotiating dedicated schedule guarantees. Anchor national security certification for rapid-reuse vehicles through Space Force NSSL Phase 3 qualification. For New Entrants and Emerging Players: Point-to-point suborbital cargo for military logistics commands represents the most penetrable entry point outside saturated satellite launch markets. India's expanding Satish Dhawan capacity offers geographic differentiation for Eastern launch azimuth procurement previously concentrated at Cape Canaveral. Pursue ride-along positioning on ISRO commercial missions to accumulate flight heritage before standalone vehicle development. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors rapid-reuse operators with proven turnaround cycles over legacy expendable architectures. Long-term viability across the projection horizon rests on demonstrated refurbishment economics below twenty percent of new build cost. Monitor Space Force launch cadence acceleration as the signal indicating shift from assured-access premium pricing to responsiveness-at-scale procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Reusable First-Stage Certification | FAA Part 450 compliance enables streamlined licensing for rapid-turnaround commercial missions. |
| Multi-Launch Block Contracting | SpaceX and United Launch Alliance secure dedicated manifest slots through multi-year national security agreements. |
| Domestic Engine Supply Qualification | Blue Origin's BE-4 and SpaceX's Raptor reduce dependency on Russian RD-180 and Ukrainian turbomachinery. |
| Small Satellite Vehicle Development | Rocket Lab's Electron captures responsive launch demand below heavy-lift competitor minimum payload thresholds. |
| Orbital Debris Mitigation Compliance | FCC conjunction assessment mandates extend mission planning complexity and insurance requirements for all operators. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FAA licensing databases, FCC satellite filings, and ESA member state procurement records. Interviews with launch vehicle program managers, range operations directors, constellation procurement leads, and insurance underwriters informed demand-side calibration. SEC filings from publicly traded space companies, NASA contract award announcements, and Defense Department budget justification books provided supply-side validation. Bottom-up manifest analysis triangulates against top-down addressable market sizing across service type and vehicle class segments.
Forecast inputs include modeled expansion of LEO broadband constellation deployment, FAA licensing cadence acceleration under Part 450 frameworks, and national security launch demand responsiveness requirements. Segmentation dimensions span service type, launch vehicle architecture, end user category, and payload application. CAGRs were derived from trajectory analysis of annual launch mass to orbit and contract value aggregation. Industry-specific inputs incorporate range capacity constraints at Eastern and Western launch sites and propulsion engineering talent pipeline depth.
Stress conditions across engine supply disruption, range scheduling bottlenecks, and orbital debris liability regime tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reusable vehicle turnaround cycle achievement and regulatory streamlining continuity. Quarterly review of Space Force launch procurement awards and FCC satellite constellation licensing cadence is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space-Based C4ISR Market
Space
Space Blanket Market
Space
Space Burial Service Market
Space
Orbital Spaceflight Market
Space
US Space Launch Services Market
Space
Space-Based Smart Sensors Market
Space
Carrier Rocket Market
Space
Space Travel Market
Space
Asteroid Mining Market
Space
India Space Electronics Market
Space
Space As a Service Market
Space
Space in Orbit Refueling Market
Space
Space Debris Monitoring Market
Space
Rocket Launchpad Market
Space
UK Space Propulsion System Market
Space
Space Technology (Spacetech) Market