
 Space Burial Service Market | 2026-2036
Space Burial Service Market Size, Share, and Industry Trends Forecast 2026-2036
Space Burial Service Market Insights
Commercial launch pad availability in Florida and California is restructuring how space burial providers schedule payload manifests. Celestis leverages its first-mover heritage and established relationships with launch operators to sustain priority access to secondary payload slots. Elysium Space competes through streamlined booking platforms that reduce administrative friction for funeral homes and individual patrons. Mesoloft differentiates via high-altitude balloon services that occupy a lower-price tier below orbital missions.
Space burial service encompasses the launch, orbital placement, or atmospheric release of cremated human remains and memorial payloads using certified launch vehicles and payload deployment systems; capsules typically contain one to seven grams of ashes, withstand vacuum exposure, and transmit telemetry or imagery to ground stations for commemorative purposes. Cremated remains launch dominates current revenue as the most accessible entry point for individual patrons, while memorial satellite services represent the fastest-growing segment driven by persistent orbital visibility and multi-generational legacy appeal. Capsule burial retains premium pricing power due to bespoke design requirements and limited per-mission capacity constraints.
FAA Office of Commercial Space Transportation licensing governs U.S. launch operations, while FCC spectrum allocations regulate memorial satellite communications payloads; these frameworks shape demand by determining which providers qualify for flight approval and which customer segments can legally access services. Space agencies in Europe operate under ESA member state oversight with varying national implementation of payload safety standards. Stakeholders must monitor evolving orbital debris mitigation rules and spectrum auction outcomes that could restrict memorial satellite deployment windows or raise compliance costs.
Market Dynamics
Secondary payload slot scarcity at Cape Canaveral and Vandenberg Space Force Base is forcing providers to secure launch manifests eighteen to thirty-six months in advance, compressing operational flexibility and concentrating market access among established operators with priority contractor relationships.
Growth Catalysts
- Memorial satellite telemetry:Persistent orbital visibility creates multi-generational legacy appeal for individual patrons seeking lasting commemoration beyond atmospheric release missions.
- FAA streamlined payload review:The Office of Commercial Space Transportation has reduced memorial payload licensing timelines from ninety days to forty-five days for qualified operators.
- Funeral home channel expansion:Cremation service providers in the United States are adding space burial as a premium add-on, normalizing the offering within traditional end-of-life planning.
Market Restraints
- Launch cost volatility:Ride-share pricing for secondary payloads fluctuates with SpaceX Falcon 9 manifest availability and rideshare broker competition.
- Orbital debris mitigation:FCC and FAA rules on memorial satellite deorbit timelines add engineering complexity and limit mission duration options.
- Substitute service competition:High-altitude balloon releases from Mesoloft and similar providers capture price-sensitive demand below orbital mission thresholds.
Strategic Opportunities
- European regulatory harmonization:ESA member states are developing unified payload safety standards that could reduce cross-border operational friction for providers.
- Memorial data transmission services:Integration of two-way satellite messaging allows families to send digital tributes to orbiting capsules, creating recurring revenue streams.
- Direct-to-consumer booking platforms:Bypassing funeral home intermediaries via proprietary reservation systems reduces commission burdens and captures full margin.
Industry Challenges
- Aerospace-cremation skill convergence:Providers struggle to hire staff fluent in both payload engineering and funeral service regulations.
- Capsule certification timelines:Vacuum chamber testing and materials qualification for one-to-seven-gram ash containers extend product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Burial Service Market |
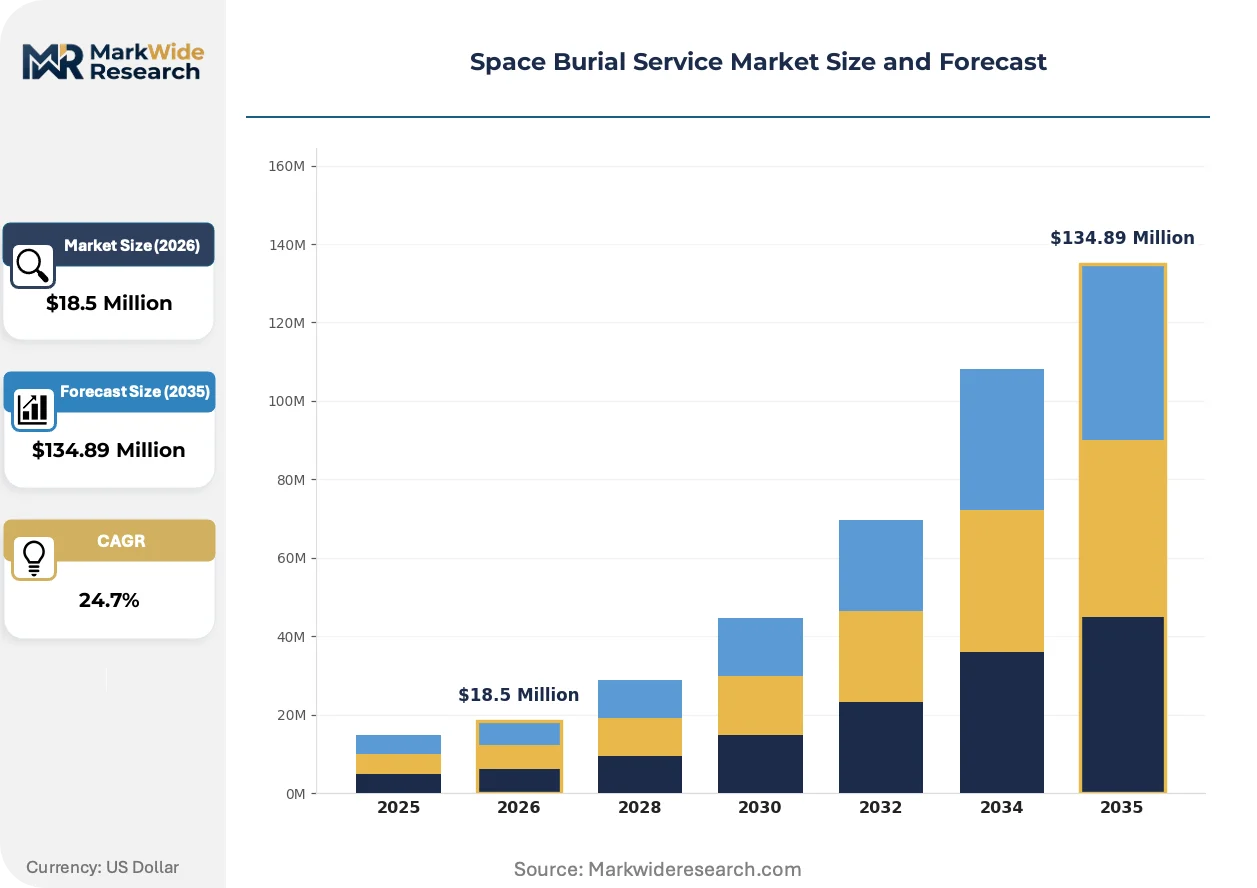
| Market Size in 2026 | $18.5 Million |
| Market Size in 2035 | $134.89 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cremated Remains Launch, Capsule Burial, Memorial Satellite, Orbital Ashes Deployment, Memorial Tree Planting Launch Vehicle: Falcon 9, Electron, Soyuz, Ariane 5, New Shepard Customer Type: Individual Patrons, Funeral Homes, Space Agencies, Memorial Organizations, Research Institutions Application: Personal Memorial, Scientific Commemoration, Cultural Tribute, Environmental Symbolism, Space Tourism |
| Companies Covered | Celestis, Elysium Space, Beyond Burials, Aura Flight, Argos Funeral Services, Elaníf, Space NTK, Mesoloft, StardustMe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Burial Service Market Trends and Innovations
Memorial payload design is pivoting from passive orbital placement to active telemetry and imagery transmission, transforming commemorative capsules into interactive legacy platforms that sustain family engagement across decades.
Nanomaterial thermal shielding is converging with miniaturized satellite bus architectures to extend memorial satellite operational lifespans from five years to fifteen years without proportional mass increases. Individual patrons purchasing premium-tier services are driving adoption of these extended-duration configurations. This convergence is compressing replacement cycle revenue for providers while raising upfront contract values and customer lifetime metrics.
FCC spectrum allocation proceedings for memorial satellite communications are tightening available frequency bands for new market entrants, favoring incumbent providers with grandfathered spectrum holdings. The industrial consequence is a bifurcation between established operators maintaining two-way telemetry capabilities and new entrants restricted to one-way beacon transmission. Memorial satellite services are responding by diversifying into optical downlink systems that circumvent radio frequency constraints.
Buyer preferences are fragmenting across generational cohorts, with younger patrons demanding app-based mission tracking and social media integration while older demographics prioritize physical keepsakes and family ceremony participation. Funeral homes are responding by unbundling space burial from traditional service packages and offering standalone digital commemoration tiers. This shift is most visible in California and Florida, where space burial penetration exceeds national averages by significant margins.
Space Burial Service Market Segmentation
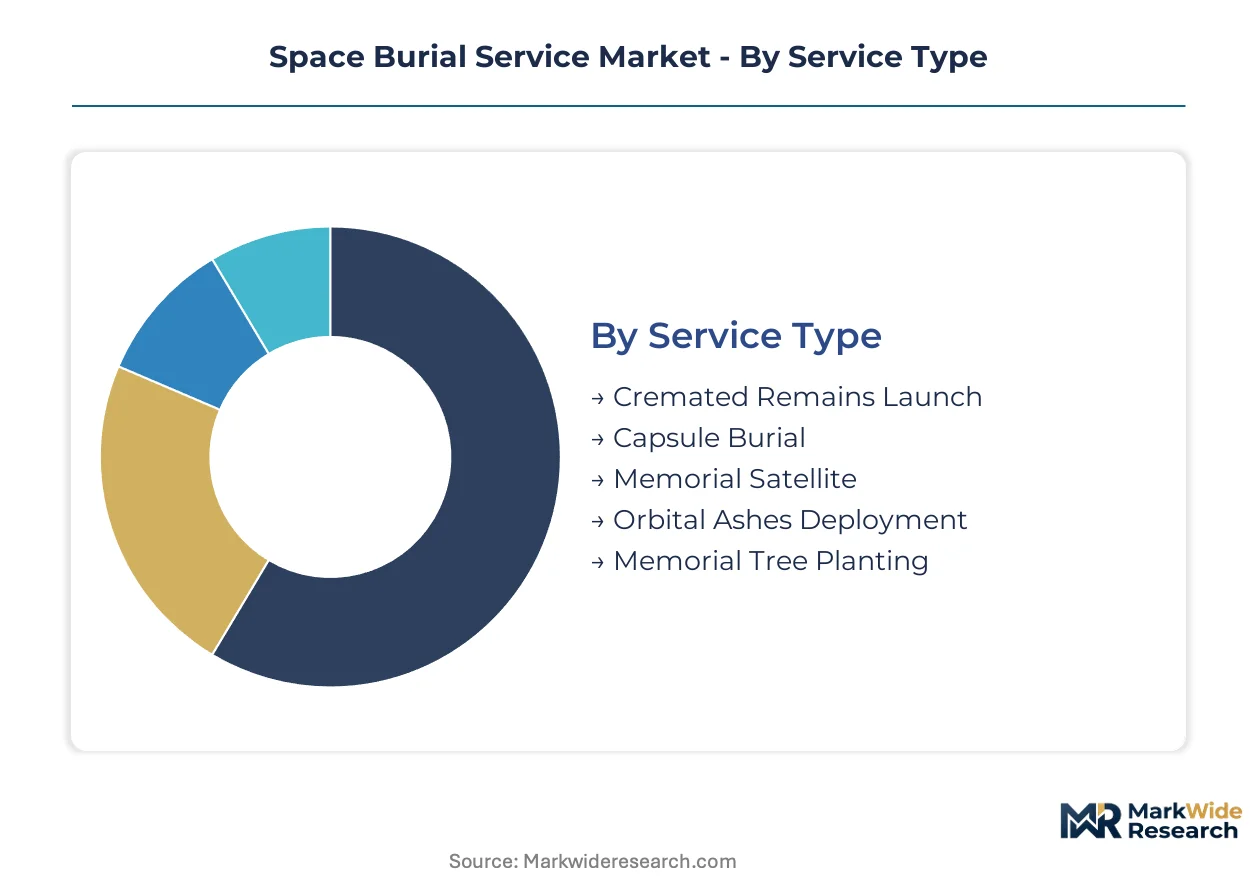
Segmentation in the space burial service market reveals how payload specifications, launch economics, and customer sophistication create distinct operational tiers. Each dimension shapes provider capabilities, pricing architectures, and regulatory compliance pathways differently.
Service Type:
Standalone memorial services operate independently of traditional funeral infrastructure, while embedded offerings integrate with cremation workflows and estate planning.
- Cremated Remains Launch:Standardized one-to-seven-gram ash capsules deploy via secondary payload slots on certified launch vehicles. Demand concentrates among individual patrons in Florida and California seeking accessible entry points without bespoke engineering.
- Memorial Satellite:Active orbital platforms transmit telemetry and imagery to ground stations, creating persistent visibility for multi-generational legacy appeal. This segment climbs fastest as younger demographics prioritize digital commemoration over physical keepsakes.
- Capsule Burial:Premium-tier missions feature custom capsule design with vacuum-qualified materials and extended operational lifespans. Limited per-mission capacity sustains pricing power for high-net-worth estates.
- Orbital Ashes Deployment:Atmospheric release missions at sub-orbital altitudes occupy a mid-price tier between balloon services and full orbital placement. Mesoloft and similar providers dominate this niche through streamlined logistics.
- Memorial Tree Planting:Terrestrial bio-commemoration pairs ash integration with reforestation certification, appealing to environmentally motivated patrons who reject launch emissions.
Cremated remains launch leads volumes today; memorial satellite is gaining share fastest.
Launch Vehicle:
Vehicle selection stratifies across payload capacity, flight frequency, and FAA licensing maturity, with cost tiers directly mapping to launch cadence and manifest flexibility.
- Falcon 9:SpaceX's rideshare program dominates secondary payload economics through frequent manifest availability and standardized integration interfaces. Established providers secure eighteen-to-thirty-six-month advance bookings at Cape Canaveral and Vandenberg.
- Electron:Rocket Lab's dedicated small-lift capability enables custom orbital parameters for memorial satellites requiring specific altitude or inclination. Premium pricing reflects mission-specific trajectory control unavailable on rideshare missions.
- Soyuz:Roscosmos launch services access polar and high-inclination orbits for persistent northern hemisphere visibility. Regulatory complexity limits adoption to providers with established Russian federation payload safety certifications.
- Ariane 5:ESA member state missions offer European-sourced alternatives for patrons prioritizing continental launch infrastructure over transatlantic logistics.
- New Shepard:Blue Origin's sub-orbital platform supports brief microgravity exposure with immediate capsule recovery, serving price-sensitive demand below orbital thresholds.
Falcon 9 anchors current capacity; Electron shows steepest expansion trajectory among dedicated small-lift alternatives.
Customer Type:
Channel structure differentiates between direct-to-consumer platforms capturing full margin and intermediary-dependent models sharing revenue with funeral service networks.
- Individual Patrons:Direct purchasers research providers through proprietary booking platforms, bypassing traditional funeral home markups. California and Florida penetration exceeds national averages significantly.
- Funeral Homes:Cremation service providers add space burial as premium add-ons, normalizing orbital commemoration within conventional end-of-life planning. Channel expansion reduces customer acquisition costs for established operators.
- Space Agencies:Institutional purchasers commission scientific commemoration missions honoring astronaut legacies or program milestones.
- Memorial Organizations:Non-profit and veteran associations aggregate demand for group tribute missions, achieving volume pricing unavailable to individual patrons.
- Research Institutions:Universities and aerospace laboratories utilize memorial payloads for materials science validation under actual space environment exposure.
Individual patrons drive absolute transaction volumes; funeral home channel integration expands most quickly as distribution normalizes.
Application:
Use case maturity spans from established personal memorial conventions to emerging commercial categories still negotiating regulatory and social acceptance.
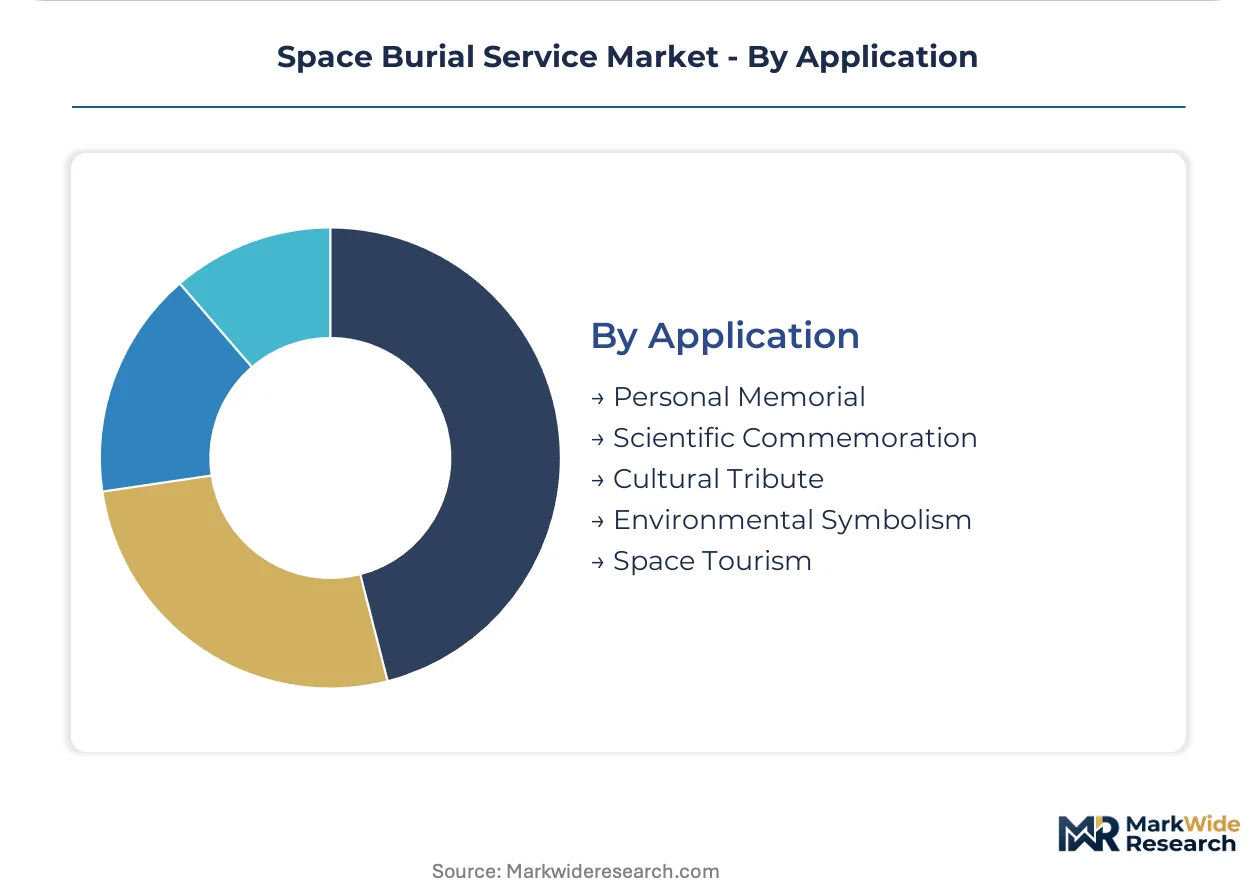
- Personal Memorial:Individual legacy preservation dominates current revenue, with capsule design and telemetry customization sustaining premium pricing tiers.
- Scientific Commemoration:Research institutions and space agencies honor technical contributions through instrument-bearing memorial satellites combining tribute with data collection utility.
- Cultural Tribute:Indigenous nations and ethnic communities pursue orbital placement of symbolic materials, navigating FCC spectrum and FAA payload review for non-traditional memorial contents.
- Environmental Symbolism:Carbon-offset messaging and reforestation pairing attract climate-conscious demographics skeptical of launch emissions.
- Space Tourism:Pre-cremation reservation of future orbital placement allows living patrons to secure commemorative capacity ahead of medical necessity.
Personal memorial commands current revenue concentration; scientific commemoration demonstrates strongest margin expansion as institutional budgets supplement individual patron spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands orbital launch infrastructure density that Germany and Japan cannot replicate, while regulatory familiarity concentrates demand in North American markets. European providers navigate fragmented national implementations of payload safety standards. Asian markets remain nascent, constrained by limited commercial launch cadence and unfamiliar cremation-to-orbit service conventions.
United States
Florida and California host the dominant commercial launch complexes, with Cape Canaveral and Vandenberg Space Force Base processing the majority of memorial payload manifests. FAA Office of Commercial Space Transportation licensing governs all orbital deployments, with streamlined forty-five-day review timelines for qualified operators. Houston and Denver clusters concentrate provider headquarters and customer service operations, leveraging proximity to aerospace talent pools.
Germany
ESA member state oversight creates regulatory complexity for memorial satellite operators seeking cross-border European service coverage. The country's national space agency coordinates with BfS radiation safety standards for payload materials qualification. Munich and Bremen industrial corridors host emerging providers targeting high-net-worth estates with premium capsule burial tiers.
United Kingdom
Post-Brexit regulatory divergence from EU frameworks forces providers to maintain separate UK payload safety certifications. The UK Space Agency administers launch licensing through its commercial spaceflight programme. Cornwall and Scottish spaceport developments in Sutherland and Shetland are attracting providers seeking secondary payload slots outside US manifest congestion.
Japan
Strict cremation customs and limited commercial launch infrastructure constrain market penetration despite high disposable income demographics. METI oversees industrial standards for memorial payload materials under existing satellite manufacturing regulations. Tokyo and Osaka metropolitan areas concentrate early-adopter demand among technology-sector professionals seeking orbital commemoration.
United Arab Emirates
Dubai and Abu Dhabi wealth concentrations generate demand for premium-tier capsule burial services, though no indigenous launch capability exists. The country's national space regulator coordinates with international partners for payload integration at foreign launch sites. Local providers are emerging as booking intermediaries connecting Gulf patrons with US and European launch operators.
Space Burial Service Market Competitive Landscape
US providers anchor the premium orbital tier; European and Asian specialists hold sub-scale positions in balloon services and booking intermediation. Market structure concentrates around three to five established operators with priority launch manifest relationships, while numerous regional entrants compete on price for atmospheric release missions. Archetypes include heritage first-movers with launch operator relationships, digital-native booking platforms, and high-altitude balloon specialists. Dominant competitive moves involve securing eighteen-to-thirty-six-month advance launch manifests and expanding funeral home distribution partnerships.
Within the heritage operator tier, Celestis occupies a position exemplifying first-mover advantages in secondary payload access. Elysium Space and Mesoloft represent contrasting archetypes: the former anchors digital platform specialization for streamlined patron booking, while the latter exemplifies price-tier differentiation through high-altitude balloon services below orbital thresholds. These three companies collectively illustrate how market positioning fragments across launch infrastructure access, administrative friction reduction, and alternative altitude service models.
| Leading Market Players |
|---|
| Celestis |
| Elysium Space |
| Beyond Burials |
| Aura Flight |
| Argos Funeral Services |
| Elaníf |
| Space NTK |
| Mesoloft |
| StardustMe |
| Others |
Pricing and Supply Chain Analysis
Falcon 9 rideshare slot pricing cascades through memorial payload economics, compressing margins for providers lacking eighteen-to-thirty-six-month advance manifest commitments while concentrating pricing power among established operators with priority SpaceX contractor relationships.
Pricing Analysis
Funeral home channel margins absorb fifteen-to-twenty-five percent markups before reaching individual patrons, while direct-to-consumer platforms capture full contract value. Three-tier pricing structure across premium capsule burial, standard memorial satellite, and economy atmospheric release tiers differentiates by orbital permanence and telemetry capability. Pricing pressure stems from Mesoloft balloon services capturing price-sensitive demand below orbital thresholds. Individual patrons in California and Florida show lowest price sensitivity; funeral home intermediaries face highest margin compression.
Supply Chain Analysis
Capsule recovery and refurbishment flows remain minimal given memorial payload disposability, though telemetry module reuse creates limited reverse logistics activity. Component manufacturing concentrates in the United States, Germany, and Japan for vacuum-qualified materials and miniaturized satellite bus architectures. Supply chains draw from aerospace-grade aluminum suppliers, satellite communications chip fabricators, and cremation service networks. Single-source vulnerability persists in FCC-licensed spectrum modules for two-way telemetry. Distribution runs through funeral home intermediaries and proprietary booking platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in memorial satellite telemetry subscriptions and direct-to-consumer platform adoption, both displacing intermediary markups and extending customer lifetime value beyond single-transaction cremated remains launches.
For Market Incumbents: Anchor priority access to Falcon 9 secondary payload slots through eighteen-to-thirty-six-month advance manifest commitments, insulating against emerging booking platform competitors. Defend against Elysium Space digital-native intermediation by expanding proprietary reservation systems that bypass funeral home markups. Vertical integration into capsule manufacturing compresses materials qualification timelines and captures upstream margin. For New Entrants and Emerging Players: The premium-to-economy price gap in orbital services invites mid-tier positioning between Celestis heritage pricing and Mesoloft balloon economy tiers. White-space opportunities concentrate in European regulatory harmonization zones where unified ESA payload safety standards reduce cross-border friction. Memorial data transmission subscriptions offer recurring revenue architecture absent from incumbent one-time launch models. Target app-based mission tracking and social media integration for younger demographic penetration in California and Florida. For Investors and Strategic Acquirers: Consolidation pressure builds where FAA licensing backlogs and spectrum scarcity strand sub-scale operators without grandfathered frequency holdings. Long-term viability favors providers with dual capability in active telemetry satellites and passive orbital placement, hedging against FCC spectrum auction outcomes. Acquisition targets display established launch operator relationships and funeral home distribution contracts. Practitioners should monitor FAA payload review timeline extensions and orbital debris mitigation rule tightening as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Bypasses funeral home markups and captures full margin from individual patrons. |
| Memorial Satellite Telemetry Integration | Transforms one-time launches into recurring subscription revenue through two-way messaging. |
| European Regulatory Harmonization | Reduces cross-border operational friction under unified ESA payload safety standards. |
| Capsule Manufacturing Backward Integration | Compresses vacuum chamber testing timelines and secures materials qualification control. |
| Optical Downlink System Development | Circumvents FCC spectrum constraints restricting new entrant radio frequency access. |
Research Methodology
Bottom-up individual patron demand modeling reconciled against top-down launch manifest capacity tracking forms the analytical core. Primary interviews with funeral home operators, memorial satellite payload engineers, FAA licensing officials, and cremation service providers combined with secondary validation against FAA Office of Commercial Space Transportation filings, FCC spectrum allocation proceedings, and SpaceX rideshare manifest disclosures. Triangulation across stakeholder inputs and regulatory documentation ensures segment-level accuracy.
Historical trendline analysis of cremated remains launch volumes and memorial satellite deployment frequencies established baseline growth patterns across the projection horizon. Segmentation modeling incorporated service type, launch vehicle class, customer channel structure, and regional regulatory cluster dimensions. CAGRs derived from launch cadence projections and per-mission capacity constraints, with inputs from aerospace manufacturing lead times and funeral home channel expansion rates.
Caveats apply where FAA payload review timeline reversals or orbital debris mitigation rule changes could materially shift the outlook. Forecasts reflect assumptions about secondary payload slot availability and spectrum allocation stability. Practitioners should monitor SpaceX manifest pricing volatility and European ESA harmonization implementation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Travel Market
Space
Space Oscillator Market
Space
Space in Orbit Refueling Market
Space
Suborbital Space Tourism Market
Space
Asia-Pacific Space Electronics Market
Space
Space Technology (Spacetech) Market
Space
Space on Board Computing Platform Market
Space
Spacesuit Market
Space
France Space Electronics Market
Space
Space-Based C4ISR Market
Space
Space Frame Market
Space
India Space Electronics Market
Space
Space Debris Monitoring Market
Space
Space Robotics Market
Space
Space Colonization Market
Space
Deep Space Exploration Market