
 Astronaut Spacesuit Market | 2026-2036
Astronaut Spacesuit Market Size, Share, and Industry Trends Forecast 2026-2036
Astronaut Spacesuit Market Analysis
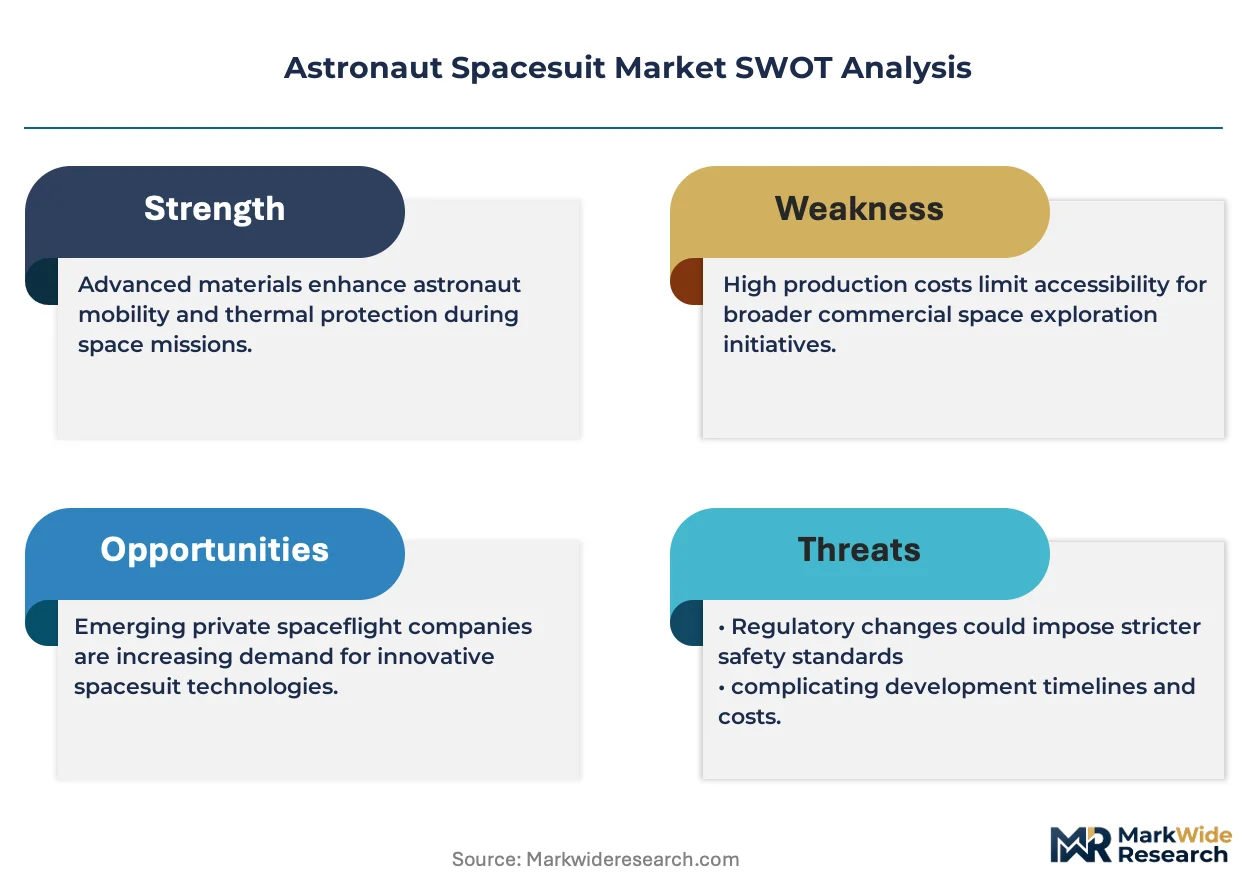
Private space tourism is restructuring the end-use vertical mix, drawing orders from commercial operators alongside traditional agency programs. Space Exploration Technologies Corp leverages vertical integration to control manufacturing timelines for crewed missions. ILC Dover anchors NASA supply chains through decades of EMU production heritage. Axiom Space competes as a private alternative for orbital and lunar suit development.
An astronaut spacesuit is a self-contained anthropomorphic spacecraft engineered to sustain human life in vacuum, thermal extremes, and micrometeoroid environments, typically incorporating a hard upper torso, pressure bladder, thermal micrometeoroid garment, and portable life support system rated for hours of independent operation. Its primary purpose is enabling crewed extravehicular activity while protecting against decompression, radiation, and temperature swings from minus 150 to plus 120 degrees Celsius. ACES and EMU categories dominate institutional procurement with mature margin pools, while XEMU configurations represent the fastest-growing segment as Artemis-generation lunar requirements displace legacy orbital designs. Material selection concentrates in Kevlar and Mylar laminates for thermal protection, with Gore-Tex layers gaining share in next-generation breathable pressure garments.
NASA's Office of Safety and Mission Assurance, ESA's Product Assurance and Safety Department, and ISO 14620 space systems standards collectively shape certification requirements, flight qualification protocols, and market access conditions for suit manufacturers. NASA's updated human-rating requirements for lunar surface operations are forcing redesign cycles that compress development windows and elevate testing costs. Stakeholders must monitor how ESA's Moonlight infrastructure program and emerging national space agency procurements redistribute contract volumes across the supplier base.
Market Dynamics
NASA's human-rating protocol overhaul for lunar surface operations is compressing development timelines and elevating qualification costs, forcing suit manufacturers to restructure R&D cadences around Artemis mission schedules rather than traditional orbital program cycles.
Growth Catalysts
- Artemis lunar architecture:NASA's Artemis program mandates next-generation extravehicular mobility units rated for 14-day lunar surface sorties, creating sustained procurement pipelines through 2035.
- REACH material standards:ECHA's updated chemical safety frameworks for long-duration spaceflight materials are accelerating adoption of fluoropolymer-free pressure bladder laminates across European supplier networks.
- Commercial orbital stations:Private low-Earth orbit habitat operators are issuing multi-suit service contracts that displace single-mission purchase models.
Market Restraints
- Z-2 prototype qualification costs:NASA's revised safety verification protocols for lunar dust abrasion resistance have extended pre-flight testing from 18 to 42 months, locking capital in work-in-progress inventory.
- Domestic supply concentration:Hard upper torso carbon-fiber shell fabrication depends on a single Delaware-based autoclave facility with 14-month order backlogs.
- EMU obsolescence risk:Legacy orbital suit architectures face functional displacement as XEMU configurations absorb procurement budgets.
Strategic Opportunities
- India's Gaganyaan program:ISRO's crewed orbital missions lack domestic suit production capability, creating technology-transfer partnership openings for established NASA contractors.
- On-orbit servicing integration:Convergence of robotic servicing platforms with human-tended maintenance is spawning demand for hybrid dexterity suits combining pressurized gloves with telerobotic interfaces.
- UAE Mars 2117 framework:The Emirates' long-duration habitat research initiative is funding prototype development for fractional-gravity suit architectures.
Industry Challenges
- Specialized seamstress attrition:The skilled workforce capable of hand-stitching thermal micrometeoroid garment layers is aging out without replacement pipelines, constraining production scaling.
- Portable life support system integration:Miniaturized CO2 scrubber and water reclamation subsystems from disparate vendors create electromagnetic interference failures during integrated system testing.
- ISO 14620-1 certification lag:Third-party verification bodies lack capacity to process flight qualification documentation within mission-critical timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Astronaut Spacesuit Market |
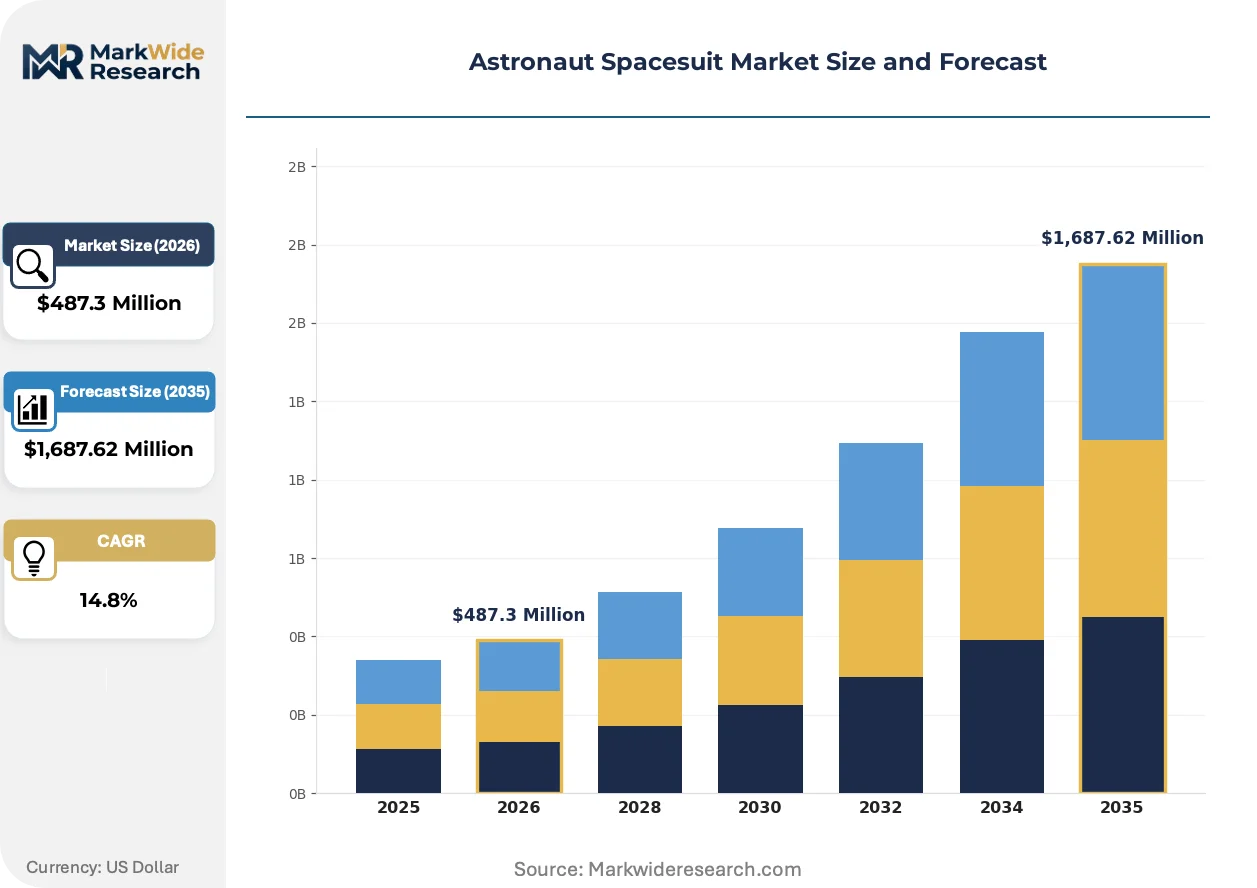
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,687.62 Million |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ACES, EMU, Orlan, XEMU Application: Extravehicular Activities, Atmospheric Research, Spacecraft Operations, Training Simulations End User: NASA, ESA, Private Space Companies, Research Institutions Material: Nomex, Kevlar, Mylar, Gore-Tex |
| Companies Covered | David Clark Company, The Boeing Company, Collins Aerospace, NPP Zvezda, Space Exploration Technologies Corp, ILC Dover, Oceaneering International, Final Frontier Design, Axiom Space, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Astronaut Spacesuit Market Emerging Trajectories
Artemis-generation requirements are dismantling the four-decade EMU design monopoly, opening technical specifications to architectures optimized for lunar gravity, abrasive regolith, and extended sortie durations rather than micro-orbital maintenance.
Soft-robotic actuation layers embedded in pressure garment joints are modularizing mobility subsystems. NASA's Johnson Space Center is flight-testing these configurations for Artemis III surface operations. This modularity enables field-replacement of damaged joint assemblies without full suit return-to-Earth, compressing maintenance cycles from months to hours.
REACH Annex XVII restrictions on perfluorinated compounds are forcing reformulation of pressure bladder fabrics. ESA's Product Assurance and Safety Department is validating Gore-Tex alternatives for lunar vacuum exposure. European suit suppliers are responding with silicone-coated nylon laminates that trade some gas retention efficiency for regulatory compliance and supply security.
Agency procurement offices are unbundling suit acquisition from integrated life support provision. NASA's Exploration Extravehicular Activity Services contract separates pressure garment delivery from portable life support system sustainment. This shift is most visible in United States lunar program contracting, where Axiom Space and Collins Aerospace compete for discrete subsystem awards rather than turnkey system delivery.
Astronaut Spacesuit Market Segmentation
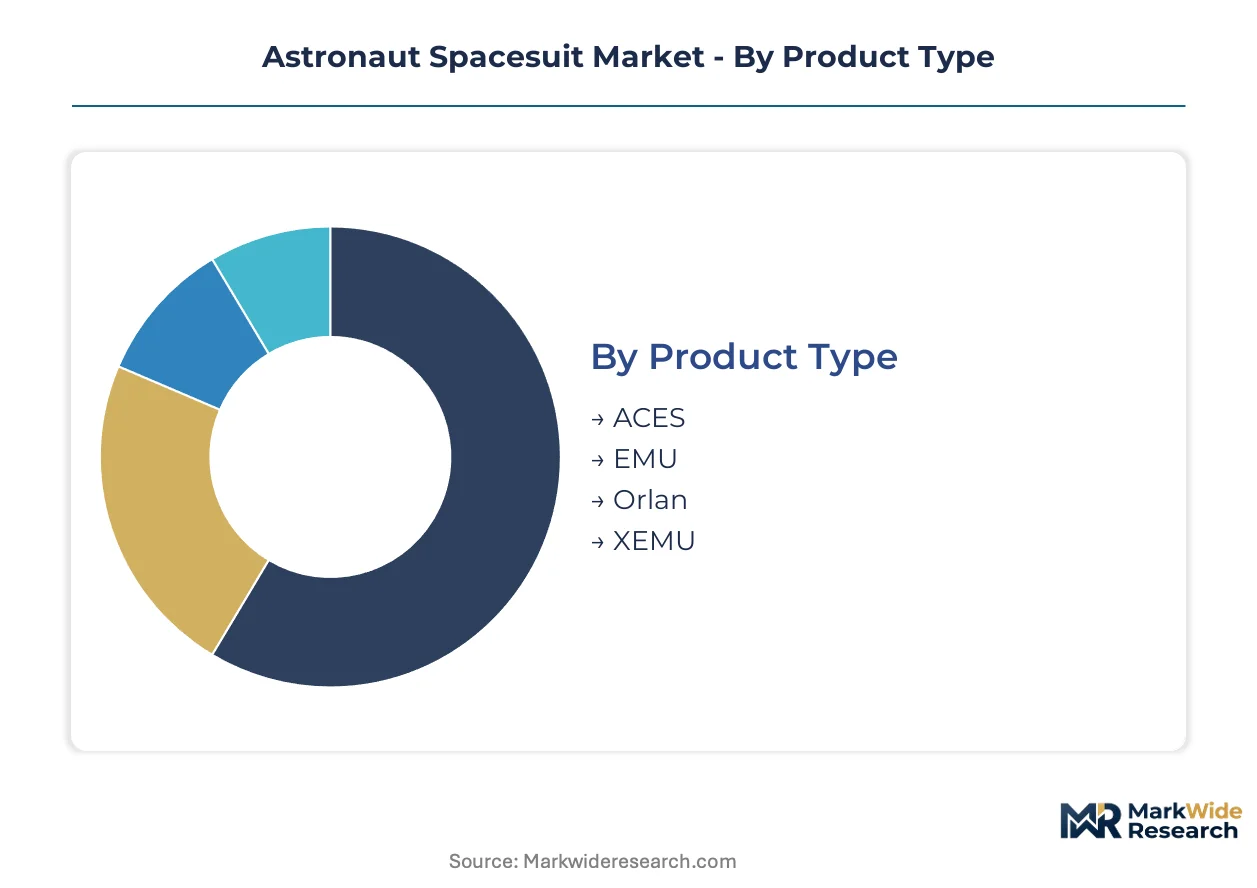
Spacesuit procurement diverges sharply across mission profiles, with lunar surface requirements commanding fundamentally different engineering specifications than orbital maintenance or training applications. Segment boundaries reflect institutional budget cycles, material certification pathways, and the operational distinction between vacuum exposure duration and gravitational loading conditions.
Product Type:
Supply concentration in hard upper torso fabrication tilts procurement leverage toward established NASA contractors with autoclave capacity and EMU heritage.
- EMU:The Extravehicular Mobility Unit incorporates a hard upper torso with integrated life support connections, rated for microgravity orbital operations. NASA's Johnson Space Center sustains demand through International Space Station maintenance schedules, though procurement volumes face compression as Artemis lunar budgets redirect funding.
- XEMU:Exploration Extravehicular Mobility Units redesign pressure garments for 1/6 Earth gravity and abrasive regolith exposure, with modular joint architectures enabling field replacement. Artemis program milestones in the United States are accelerating qualification timelines and concentrating development investment in this configuration.
- ACES:Advanced Crew Escape Suits serve launch and re-entry phases with orange pressure garments optimized for emergency bailout scenarios.
- Orlan:Russian-designed suits with rear-entry hatch architecture, historically procured by Roscosmos and select partner agencies for Soyuz and ISS operations.
Today's leader: EMU. Tomorrow's challenger: XEMU.
Application:
Cost tier stratification separates flight-qualified hardware from ground-based training assets, with extravehicular applications commanding 5-8x unit premiums over simulation equivalents.
- Extravehicular Activities:Vacuum-rated operations demand full thermal micrometeoroid garment integration and portable life support systems with redundant oxygen loops. NASA's Artemis lunar sorties and commercial orbital station maintenance contracts in the United States are concentrating procurement volume here.
- Spacecraft Operations:Intra-vehicular pressure garments prioritize mobility over thermal protection, with lighter fabric assemblies and tethered life support.
- Training Simulations:Neutral buoyancy facility suits replicate EVA kinematics without flight certification overhead, serving Johnson Space Center and European astronaut preparation programs.
- Atmospheric Research:High-altitude pressure suits adapted from spacesuit architectures support stratospheric balloon operations and suborbital flight profiles.
Flight hardware claims margin concentration. Simulation assets scale volume.
End User:
Customer type fragmentation splits procurement between agency milestone-driven programs and commercial operator service contracts with different technical authority structures.
- NASA:Artemis lunar architecture and ISS sustainment generate sustained demand through Exploration Extravehicular Activity Services contracts with unbundled subsystem awards.
- Private Space Companies:Axiom Space and orbital habitat operators issue multi-suit service agreements displacing single-mission purchase models.
- ESA:European procurement concentrates through the Product Assurance and Safety Department with REACH-compliant material specifications.
- Research Institutions:Academic and museum collections acquire retired flight units or ground-test prototypes for display and analog research.
Agency programs anchor technical specifications. Commercial operators reshape contract economics.
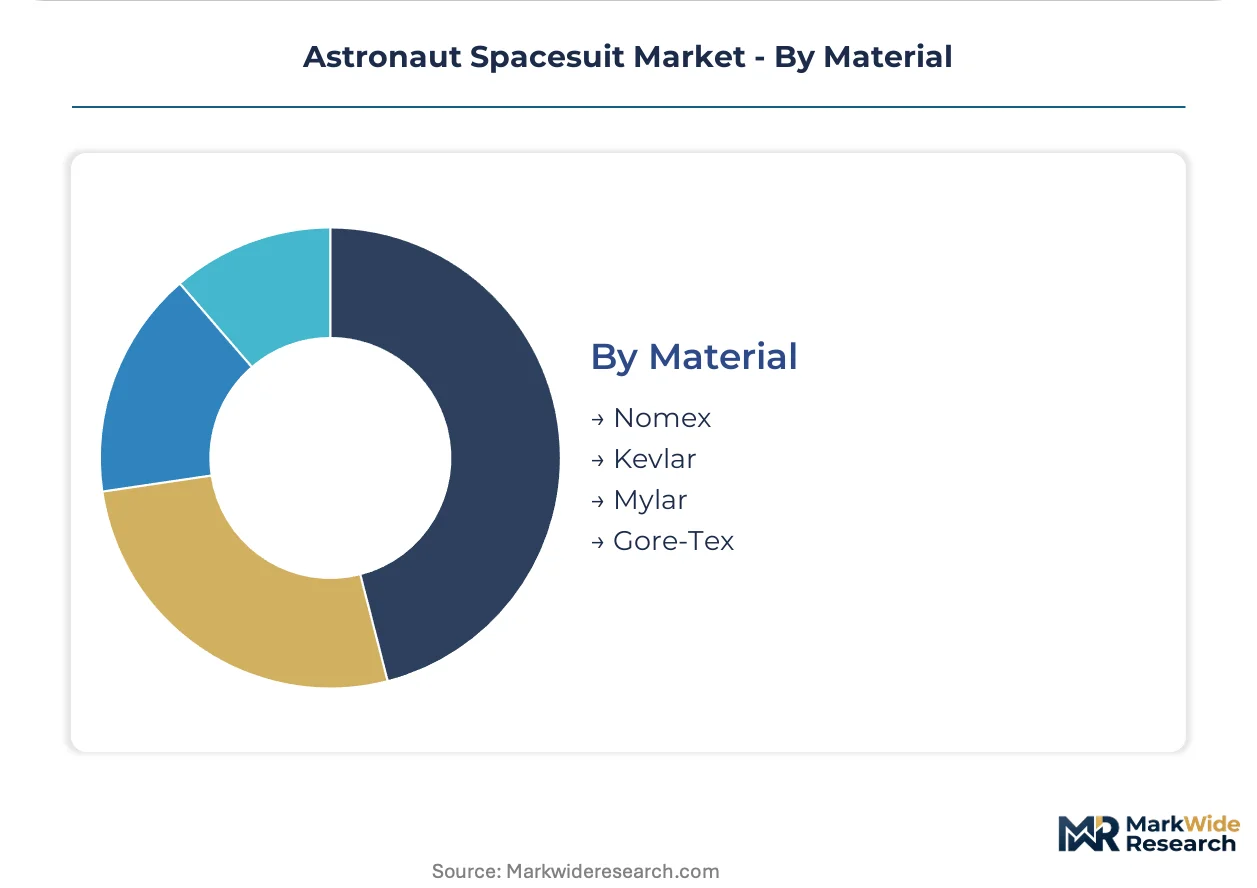
Material:
Maturity gradients separate decades-qualified laminates from next-generation alternatives navigating regulatory transition windows.
- Kevlar:Aramid fiber layers in thermal micrometeoroid garments provide proven impact resistance and thermal stability across orbital and lunar environments. NASA's existing qualification data sustains procurement preference despite weight penalties versus newer alternatives.
- Gore-Tex:Expanded polytetrafluoroethylene membranes face REACH Annex XVII restrictions, forcing European suppliers toward silicone-coated nylon reformulations that trade gas retention for regulatory compliance.
- Mylar:Metallized polyester films form radiation-reflective layers in multi-layer insulation assemblies.
- Nomex:Fire-resistant aramid fabrics protect against launch abort scenarios and cabin fire events in launch-entry suits.
Heritage materials defend installed base. Regulatory pressure elevates substitution risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping spacesuit manufacturing geography, with REACH compliance costs in Europe pushing pressure bladder laminate production toward jurisdictions with less stringent chemical safety frameworks. NASA's domestic procurement preferences simultaneously concentrate hard upper torso fabrication in the United States.
United States
Artemis lunar program milestones and ISS sustainment contracts anchor institutional demand. NASA's Johnson Space Center in Houston drives qualification protocols, while Delaware-based autoclave facilities handle carbon-fiber hard upper torso production. The FAA's commercial spaceflight regulations shape private operator certification pathways.
Russia
Roscosmos maintains Orlan suit production for Soyuz and ISS operations through NPP Zvezda. Domestic procurement insulates suppliers from Western REACH restrictions. Moscow-region manufacturing clusters concentrate rear-entry hatch fabrication and thermal garment assembly.
France
ESA's Product Assurance and Safety Department in Paris mandates REACH-compliant material specifications for European astronauts. Toulouse-based aerospace suppliers are reformulating pressure bladder fabrics to meet Annex XVII perfluorinated compound restrictions. The country's chemical safety framework is accelerating silicone-coated nylon adoption.
China
Independent crewed space station operations generate sustained intravehicular and extravehicular suit demand. MIIT standards govern pressure garment certification. Beijing-Tianjin industrial corridors concentrate life support system integration capabilities.
India
ISRO's Gaganyaan program lacks domestic suit production infrastructure, creating technology-transfer partnership openings. The country's national space regulator oversees crewed mission safety protocols. Bengaluru's aerospace cluster hosts subsystem testing facilities.
Astronaut Spacesuit Market Vendor Landscape
Capacity expansion dominates the current landscape as established contractors scale autoclave throughput and portable life support system integration lines. The vendor base concentrates around NASA heritage suppliers with flight-qualified manufacturing processes and ESA-aligned European specialists navigating REACH reformulation cycles. Two strategic archetypes prevail: legacy institutional contractors with multi-decade agency relationships, and private commercial operators unbundling subsystem procurement. M&A activity and strategic technology licensing represent the dominant competitive vectors.
Among heritage NASA contractors, ILC Dover and David Clark Company exemplify the institutional archetype with decades of EMU and ACES production lineage. Space Exploration Technologies Corp occupies a distinct position as a vertically integrated commercial operator controlling manufacturing timelines for crewed missions. These three anchors illustrate the bifurcation between agency-dependent incumbents and privately capitalized challengers reshaping contract economics.
| Leading Market Players |
|---|
| David Clark Company |
| The Boeing Company |
| Collins Aerospace |
| NPP Zvezda |
| Space Exploration Technologies Corp |
| ILC Dover |
| Oceaneering International |
| Final Frontier Design |
| Axiom Space |
| Others |
Supply Flow & Price Mechanics
Carbon-fiber prepreg pricing indices from the aerospace composites sector cascade through astronaut spacesuit manufacturing, compressing margins at hard upper torso fabrication stages while amplifying cost differentials between flight-qualified EMU units and training-grade alternatives.
Pricing Analysis
Direct-to-NASA contracting eliminates distributor margins, concentrating price leverage at the OEM tier where ILC Dover and Collins Aerospace negotiate subsystem awards. Pricing stratifies across flight-certified, engineering-model, and training-simulator tiers, with certification grade and portable life support system integration level as primary differentiation drivers. Cost compression in training-grade suits is intensifying because commercial orbital operators demand volume discounts on multi-suit service contracts. Research institutions exhibit highest price sensitivity, while Artemis lunar program offices accept premium positioning for XEMU configurations with modular joint architectures.
Supply Chain Analysis
Hard upper torso carbon-fiber shell fabrication rests on Delaware-based autoclave capacity with order backlogs extending fourteen months, tethering production timelines to a single-source facility. Kevlar aramid fiber supply draws from United States and European weaving operations, while REACH-compliant silicone-coated nylon laminates for pressure bladders source from French and German chemical processors. Single-source vulnerability in autoclave capacity creates bottleneck risk for Artemis schedule adherence. Distribution runs through NASA Johnson Space Center qualification protocols before field deployment, with ESA Product Assurance and Safety Department parallel tracks for European astronaut missions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The astronaut spacesuit market functions as a stable compounder, with Artemis lunar architecture generating sustained procurement pipelines through 2035 that insulate contracted suppliers from demand volatility.
For Market Incumbents: Lock in autoclave capacity expansion ahead of Artemis III milestone acceleration, securing carbon-fiber shell fabrication slots against emerging XEMU competitors. Deepen backward integration into Kevlar thermal micrometeoroid garment weaving to defend margin position against REACH-driven material substitution costs from European suppliers.
For New Entrants and Emerging Players: Soft-robotic joint actuation modules offer a technology-first wedge into the lunar suit subsystem market, bypassing entrenched EMU heritage barriers. ISRO Gaganyaan technology-transfer partnerships represent the most penetrable geography, with subsystem qualification services as the viable go-to-market angle rather than full-system competition.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized portable life support system integrators possessing ISO 14620-1 certification track records. Five-to-ten year viability hinges on Artemis program continuity and commercial orbital station deployment schedules. Watch NASA Exploration Extravehicular Activity Services contract award timing as the critical inflection signal for valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Autoclave Capacity Expansion | Secures hard upper torso fabrication slots for Artemis lunar suit production schedules. |
| REACH-Compliant Material Reformulation | Enables ESA supply chain participation through silicone-coated nylon laminate qualification. |
| Modular Joint Architecture Development | Supports field-replacement capabilities that compress lunar surface maintenance cycles. |
| Technology Transfer Partnership | Opens ISRO Gaganyaan procurement channels for established NASA subsystem suppliers. |
| Multi-Suit Service Contract Model | Aligns pricing structures with commercial orbital operator budget cycles versus milestone-based agency awards. |
Methodological Framework
Direct dialogue with NASA procurement officers, ESA Product Assurance directors, ILC Dover manufacturing engineers, and Axiom Space program managers grounded qualitative assessment in operational realities. Secondary validation drew from FAA commercial spaceflight regulations, NASA Office of Safety and Mission Assurance protocols, ECHA REACH Annex XVII documentation, and ISO 14620 space systems standards. Bottom-up segment sizing triangulated against top-down agency budget allocation analysis across the projection horizon.
Bottom-up modeling built from unit economics of EMU, XEMU, ACES, and Orlan configurations, cross-referenced with portable life support system subsystem costs and thermal micrometeoroid garment material inputs. Top-down verification anchored in NASA Exploration Extravehicular Activity Services contract structures, ESA Moonlight infrastructure procurement timelines, and commercial orbital station operator multi-suit service agreement disclosures. CAGRs derived from Artemis program milestone pacing and lunar surface sortie duration requirements modeled across the analysis window.
The model holds under sustained Artemis funding authorization and commercial orbital station deployment schedules; deviation in NASA human-rating protocol timelines or REACH enforcement intensity would shift supplier competitiveness rankings. Forecasts incorporate assumptions regarding carbon-fiber autoclave capacity expansion and skilled seamstress workforce replacement pipeline development. A small set of named triggers—Artemis III launch delays, ESA independent lunar suit procurement decisions, and Chinese crewed lunar program acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Radar Market
Space
Suborbital Space Tourism Market
Space
India Aviation, Defense, and Space Market
Space
China Space Propulsion System Market
Space
Space Technology (Spacetech) Market
Space
Space Ground Station Equipment Market
Space
UK Space Electronics Market
Space
Space Rover Market
Space
Space on Board Computing Platform Market
Space
Space As a Service Market
Space
Space Lander and Rover Market
Space
Space Frame Market
Space
North America Spacesuit Market
Space
Mexico Space Electronics Market
Space
Japan Space Electronics Market
Space
Africa Space Electronics Market