
 Space Ground System Market | 2026-2036
Space Ground System Market Size, Share, and Industry Trends Forecast 2026-2036
Space Ground System Market Insights
The EU Green Deal and associated sustainability disclosure mandates for government contractors is realigning procurement criteria across European space agencies. General Dynamics Corporation leverages its vertically integrated manufacturing base to sustain long-term service contracts with military buyers. L3Harris Technologies, Inc. competes through specialized waveform processing capabilities that anchor its position in signal intelligence ground stations. RTX dominates integrated air and space defense networks, extending its footprint across multi-domain command architectures.
Space ground systems comprise the terrestrial infrastructure enabling satellite command, telemetry acquisition, payload data reception, and orbit determination through antenna arrays operating across S-band to Ka-band frequencies. These systems process raw satellite downlinks into actionable intelligence for weather prediction, broadband distribution, and strategic surveillance missions. Telemetry Systems and Command & Control Systems occupy the core revenue pool given their indispensability across every orbital mission profile, while Artificial Intelligence and Machine Learning segments within the Technology dimension represent the fastest structural expansion as operators automate anomaly detection and predictive maintenance workflows. Cloud Computing adoption in ground architectures is displacing on-premise data centers, redistributing margin pools toward managed service providers.
FAA licensing requirements for commercial spaceports and FCC spectrum allocation rules govern U.S. ground station deployment density and interference coordination. ESA procurement guidelines and EU Space Programme security standards shape European vendor qualification pathways, while ISO 27001 and ITU-R radio regulations establish baseline cybersecurity and frequency management protocols internationally. Stakeholders must monitor evolving spectrum reallocation proceedings and dual-use export control classifications that will determine which ground technology suppliers retain market access across allied defense programs.
Market Dynamics
Software-defined ground architectures are compressing hardware refresh cycles across military and commercial satellite networks, redistributing capital toward software development and cloud integration layers.
Growth Catalysts
- Space Force Modernization:United States Space Force procurement programs mandate resilient command infrastructure upgrades across military ground stations, creating sustained demand for next-generation telemetry and tracking systems.
- REACH Chemical Compliance:European space agencies now require full material disclosure for ground station electronics under extended REACH substance restrictions, accelerating component replacement schedules.
- AI-Driven Automation:Machine learning anomaly detection is reducing manual satellite monitoring requirements, enabling ground operators to manage larger constellation fleets with existing staffing levels.
Market Restraints
- GaN Semiconductor Supply:Gallium nitride RF component fabrication concentrates in limited foundry capacity, creating input bottlenecks for high-power ground station amplifiers.
- ITU-R Coordination Delays:International frequency allocation proceedings extend licensing timelines for new ground station deployments by 18-36 months in contested spectrum bands.
- Optical Ground Station Substitution:Laser-based satellite communication terminals threaten to displace RF ground infrastructure for high-bandwidth applications, constraining long-term RF equipment investment.
Strategic Opportunities
- India Constellation Buildout:ISRO's commercial arm NSIL is procuring ground segment capacity for regional navigation and earth observation fleets, opening vendor access previously restricted to domestic suppliers.
- EU Green Deal Procurement:Sustainability disclosure mandates for government contractors now weight carbon footprint in ESA ground system awards, favoring vendors with renewable-powered data centers.
- 5G NTN Convergence:Integration of satellite ground stations with terrestrial 5G core networks enables direct-to-device messaging services, creating hybrid infrastructure demand from telecom operators.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized microwave and antenna design expertise pools have not expanded with constellation deployment rates, extending recruitment cycles for critical ground station projects.
- Legacy System Interoperability:Military buyers require backward compatibility with decades-old command protocols, forcing vendors to maintain obsolete codebases alongside modern software stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Ground System Market |
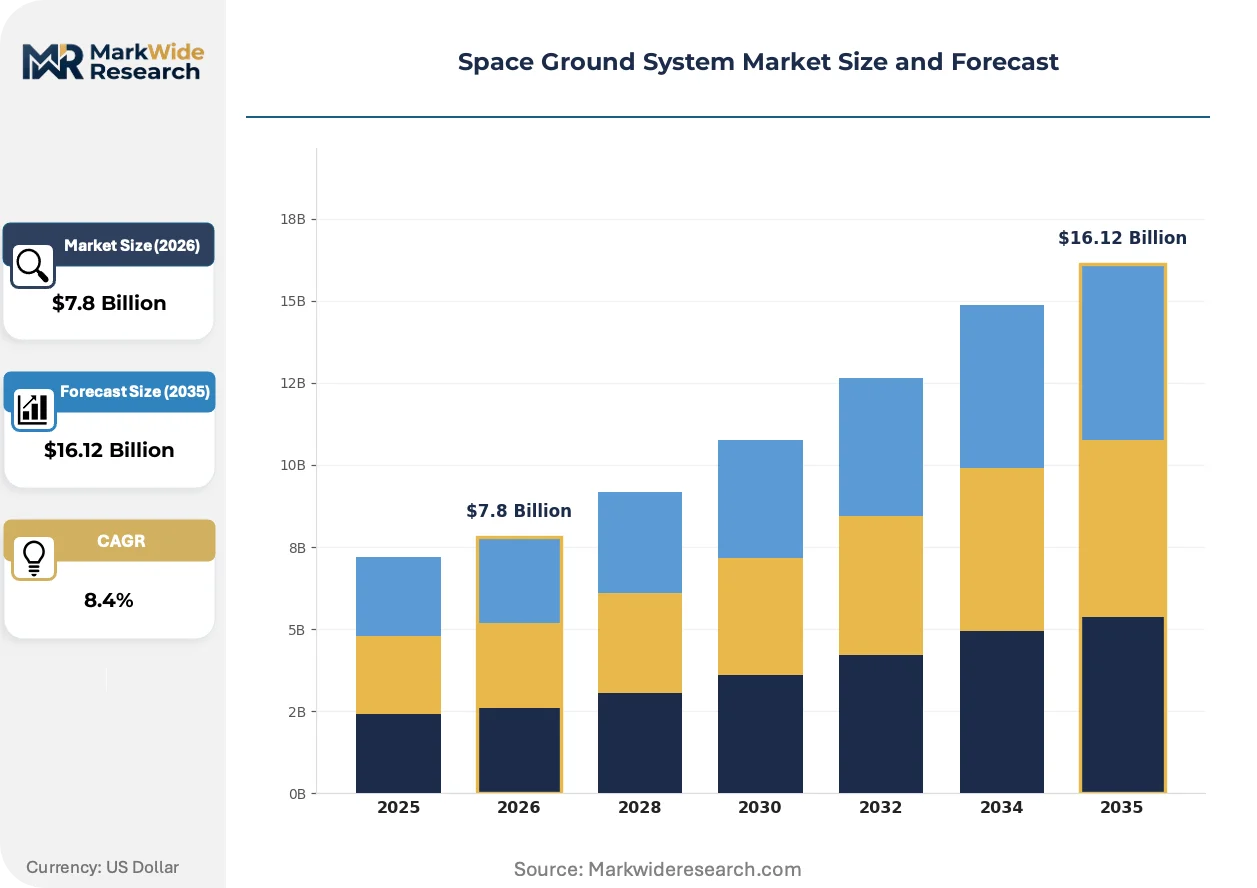
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Telemetry Systems, Command & Control Systems, Data Processing Systems, Tracking Systems, Antenna Systems Technology: Software Defined Radio, Digital Signal Processing, Cloud Computing, Artificial Intelligence, Machine Learning Application: Earth Observation, Satellite Communications, Space Exploration, Weather Monitoring, Defense Surveillance End User: Space Agencies, Research Institutions, Defense Organizations, Telecommunication Providers, Satellite Operators |
| Companies Covered | General Dynamics Corporation, L3Harris Technologies, Inc., RTX, Airbus, Lockheed Martin Corporation, Thales Group, Viasat, Inc., Inmarsat Global Limited, SES S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Ground System Market Trends and Innovations
Three intersecting developments are restructuring how ground infrastructure is procured, deployed, and operated across defense and commercial satellite ecosystems.
Virtualized baseband processing is electrifying ground station economics by replacing dedicated hardware demodulators with software running on standard servers. Satellite operators including geostationary broadcasters and low-earth-orbit constellation managers are adopting these platforms to reconfigure waveforms without hardware swaps. This compression of capital requirements is enabling smaller operators to establish independent ground presence rather than leasing from incumbent providers.
FCC spectrum reallocation proceedings for the 3.7-4.2 GHz C-band are forcing ground station operators to retune or replace existing antennas, creating equipment replacement windows. The industrial consequence is accelerated migration to Ka-band and optical alternatives for high-throughput applications. Commercial satellite service providers in North America are responding by pre-positioning multi-band capable ground assets to maintain service continuity through regulatory transitions.
Managed ground services are displacing capital ownership models as constellation operators prioritize operational expenditure flexibility. Satellite fleet managers now contract antenna-as-a-service from specialized providers rather than building owned infrastructure, compressing the addressable market for equipment vendors while expanding recurring revenue pools for service integrators. This pattern is most visible among commercial earth observation and IoT constellation ventures in Europe and North America.
Space Ground System Market Segmentation
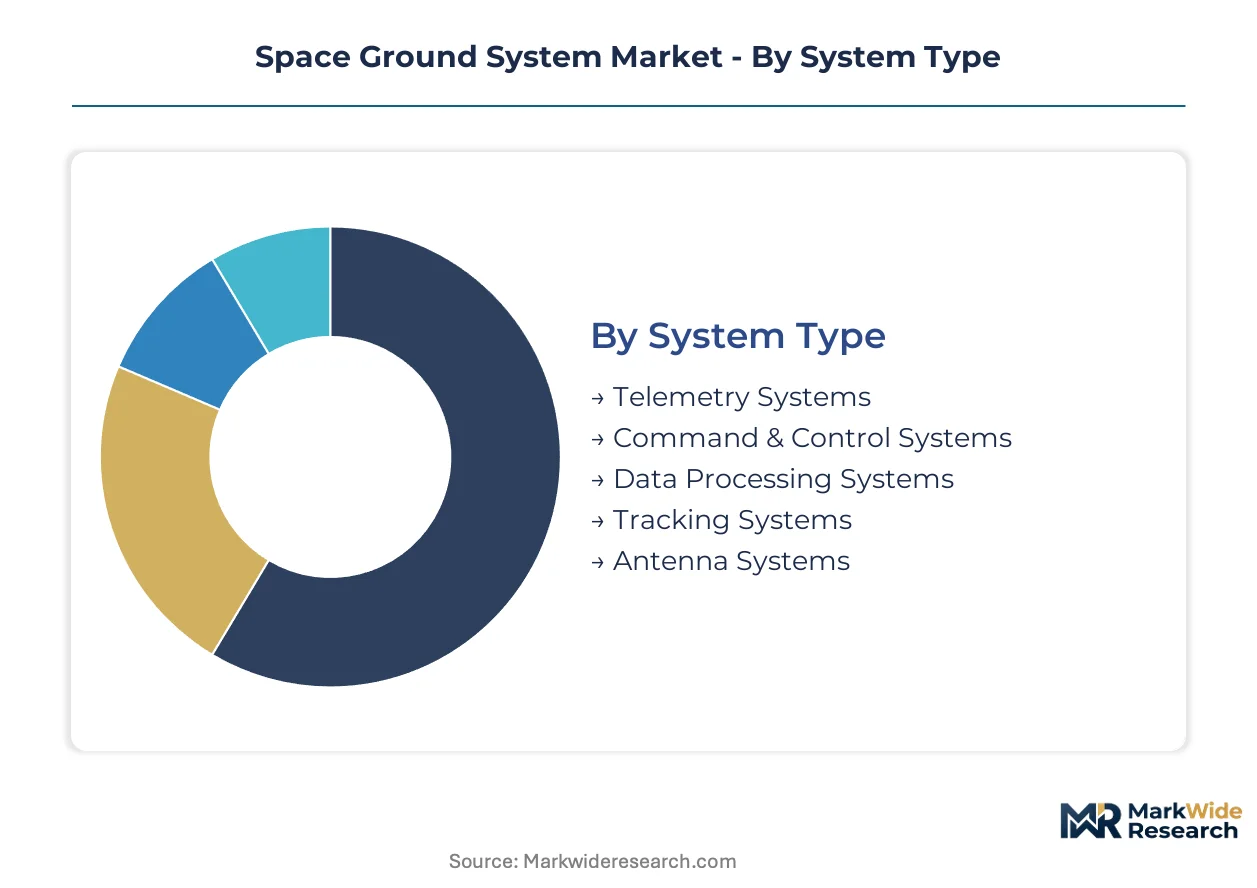
Ground system procurement patterns diverge sharply across mission profiles, with defense buyers prioritizing resilience and commercial operators optimizing for throughput economics. Technology selection now determines vendor competitiveness more than hardware specifications alone.
System Type:
Cost tier differentiation separates military-grade redundancy requirements from commercial lean-architecture preferences.
- Telemetry Systems:These systems acquire satellite health data and payload status through S-band and X-band links, processing analog signals into digital telemetry streams. United States Space Force ground stations are modernizing these assets under resilient infrastructure mandates, with procurement concentrated in Colorado and California installations.
- Command & Control Systems:Mission-critical infrastructure enabling orbital maneuvering, payload reconfiguration, and emergency response protocols. European space agencies under ESA procurement guidelines are prioritizing cybersecurity-hardened variants with ISO 27001 certification for Galileo and Copernicus ground segments.
- Data Processing Systems:High-throughput computing clusters converting raw downlinks into distribution-ready products for weather and imagery services.
- Tracking Systems:Radar and optical assets providing precise orbit determination for collision avoidance and rendezvous operations.
- Antenna Systems:Parabolic and phased-array installations spanning L-band through Ka-band frequencies for link acquisition.
Volume sits with Telemetry Systems; growth tilts toward Command & Control Systems.
Technology:
Application maturity varies from deployed commercial standards to experimental defense prototypes.
- Software Defined Radio:Reconfigurable RF platforms replacing fixed-function hardware demodulators. Commercial satellite operators in North America are adopting these for multi-constellation support, reducing equipment swap costs during fleet transitions.
- Artificial Intelligence:Neural network architectures automating anomaly detection in telemetry streams and predicting component failures before mission impact. United States defense ground stations are deploying these for reduced staffing requirements across expanded satellite portfolios.
- Digital Signal Processing:Algorithmic waveform manipulation enabling interference mitigation and spectral efficiency gains.
- Cloud Computing:Distributed processing architectures displacing on-premise data centers for elastic workload management.
- Machine Learning:Pattern recognition systems optimizing antenna pointing and link budget allocation in real-time.
Deployment density favors Software Defined Radio; capability investment flows fastest into Artificial Intelligence.
Application:
Customer type fragmentation separates government-funded science missions from revenue-driven commercial services.
- Earth Observation:Ground infrastructure supporting optical and synthetic aperture radar satellites for agriculture, insurance, and environmental monitoring. Commercial constellation operators in Europe are contracting managed ground services to minimize capital deployment.
- Satellite Communications:High-throughput broadband distribution requiring Ka-band gateway density and terrestrial backhaul integration. United States FCC spectrum reallocation proceedings are forcing C-band infrastructure retuning across existing installations.
- Space Exploration:Deep-space networks with specialized large-aperture antennas for lunar and interplanetary missions.
- Weather Monitoring:Continuous data reception from geostationary and polar-orbiting meteorological satellites.
- Defense Surveillance:Classified signal intelligence and missile warning architectures with hardened electromagnetic protection.
Revenue concentration rests with Satellite Communications; capability expansion runs strongest through Earth Observation.
End User:
Procurement authority structures determine contract vehicle complexity and payment term flexibility.
- Defense Organizations:Classified program offices with multi-year appropriations and stringent security clearance requirements. NATO member states are expanding resilient satellite command infrastructure procurement under collective defense modernization initiatives.
- Satellite Operators:Commercial fleet managers prioritizing operational expenditure models over capital ownership. These buyers are driving managed ground services adoption across low-earth-orbit constellation deployments.
- Space Agencies:Civil government bodies with international cooperation mandates and public transparency obligations.
- Telecommunication Providers:Mobile network operators integrating satellite backhaul for rural coverage extension.
- Research Institutions:University and laboratory ground stations with limited budgets and specialized scientific objectives.
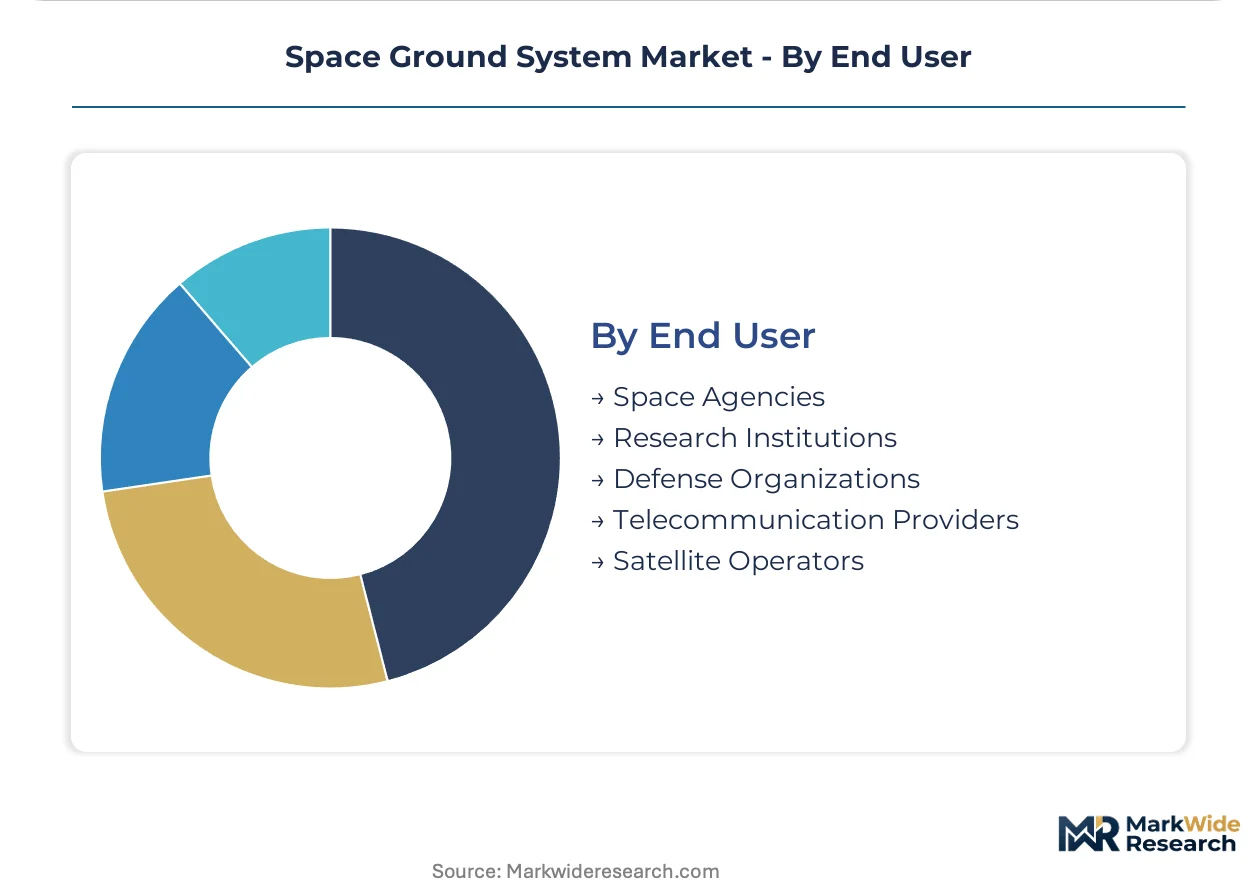
Contract value aggregates with Defense Organizations; addressable market expansion tracks Satellite Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colorado Springs anchors the densest concentration of military ground station procurement in the United States, with Space Force installations driving resilient infrastructure upgrades across the Front Range corridor. National procurement patterns diverge sharply between defense-led modernization in North America and commercial constellation buildouts across Asia-Pacific and European markets.
United States
Space Force modernization programs mandate next-generation telemetry and tracking systems across Colorado and California installations. FCC spectrum reallocation proceedings for the 3.7-4.2 GHz C-band force ground station operators to retune or replace existing antennas, compressing equipment replacement cycles. The Denver-Aurora aerospace corridor concentrates prime contractor engineering centers and specialized RF component suppliers serving military buyers.
Germany
ESA procurement guidelines under EU Space Programme security standards prioritize cybersecurity-hardened command systems for Galileo ground segments. REACH chemical compliance mandates now require full material disclosure for ground station electronics, accelerating component replacement schedules across Bavarian manufacturing clusters. The Munich-Stuttgart industrial corridor hosts specialized antenna fabricators and signal processing engineering centers serving European defense programs.
India
ISRO's commercial arm NSIL procures ground segment capacity for regional navigation and earth observation fleets, opening vendor access previously restricted to domestic suppliers. BIS certification requirements and DGFT dual-use export classifications govern foreign equipment qualification pathways for defense-adjacent installations. The Bengaluru-Hyderabad technology corridor concentrates ISRO facilities and emerging private ground station operators serving commercial constellation ventures.
United Kingdom
UK Space Agency funding for sovereign satellite control capabilities drives ground segment modernization across government and commercial programs. National security classifications and export control frameworks from the country's national defense regulator shape vendor qualification for classified signal intelligence architectures. The Harwell-Oxfordshire space cluster anchors specialized ground software development and satellite operations centers serving European and Commonwealth markets.
Japan
METI strategic technology roadmaps prioritize optical ground station development for next-generation satellite communication networks. JIS standards and the country's national space agency technical specifications govern ground system interoperability for domestic and international mission participation. The Tsukuba science city and Tokyo metropolitan area concentrate JAXA facilities and commercial ground station operators expanding capacity for earth observation constellations.
Space Ground System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across defense certification and software-defined architecture capabilities. The vendor base stratifies between vertically integrated prime contractors holding long-term military service contracts and specialized subsystem suppliers competing on waveform processing and antenna technologies. Two strategic archetypes dominate: full-spectrum platform integrators and focused component specialists. Competitive dynamics center on strategic partnerships for constellation ground networks and technology licensing for virtualized baseband processing platforms.
Within the defense prime contractor tier, General Dynamics Corporation and L3Harris Technologies, Inc. exemplify contrasting positioning strategies. General Dynamics leverages its vertically integrated manufacturing base to sustain long-term service contracts with military buyers. L3Harris competes through specialized waveform processing capabilities that anchor its position in signal intelligence ground stations. RTX occupies a position across integrated air and space defense networks, extending its footprint through multi-domain command architectures. These three entities represent the dominant competitive anchors shaping procurement outcomes across NATO member state programs and United States Space Force modernization initiatives.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| L3Harris Technologies, Inc. |
| RTX |
| Airbus |
| Lockheed Martin Corporation |
| Thales Group |
| Viasat, Inc. |
| Inmarsat Global Limited |
| SES S.A. |
| Others |
Pricing and Supply Chain Analysis
Captive in-house production of GaN RF power amplifiers anchors pricing power for vertically integrated defense primes while exposing commercial ground station vendors to foundry bottlenecks. This integration choice concentrates margin capture among military suppliers with captive semiconductor fabrication, forcing price-sensitive commercial operators toward managed service models that externalize hardware ownership.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for mission-critical defense ground segments, with premiums scaling to five-nines reliability commitments. Three-tier pricing structure across military-grade, enterprise-hardened, and commercial-lean configurations separates certification-burdened systems from commodity antenna farms. Cost compression in commercial telemetry hardware intensifies because virtualized baseband processing displaces dedicated demodulator chassis. Satellite operators exhibit highest price sensitivity, while Space Force program offices prioritize resilience over unit economics.
Supply Chain Analysis
Refurbishment flows for retired military ground stations now feed secondary markets in India and Southeast Asia, extending equipment lifecycles beyond original design horizons. GaN semiconductor fabrication concentrates in the United States, Japan, and South Korea, with RF component sourcing tethered to limited foundry capacity. Gallium nitride substrates, high-power traveling wave tubes, and precision antenna servomechanisms represent critical input dependencies. Single-source vulnerability runs through military-qualified GaN foundries. Distribution runs through prime contractor integration centers rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GaN foundry capacity scarcity props pricing for RF power components, constraining supply elasticity across defense and commercial ground station builds. This bottleneck sustains margin pools for captive producers while forcing non-integrated vendors toward alternative architectures.
For Market Incumbents: Anchor long-term service contracts through backward integration into GaN amplifier production, securing input supply against foundry allocation constraints. Deepen software-defined architecture roadmaps to offset hardware margin compression from virtualized baseband competition. Prioritize ISO 27001 certification investments for ESA procurement qualification pathways.
For New Entrants and Emerging Players: Capture managed ground service contracts from earth observation constellation operators seeking operational expenditure flexibility over capital ownership. The most penetrable segment lies in commercial LEO fleet ground segments across Europe and North America. Lead with antenna-as-a-service offerings that bundle waveform processing with cloud-native data delivery.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by defense primes seeking specialized waveform processing capabilities. Long-term viability favors vendors with dual-use technology positions spanning military certification and commercial scalability. Monitor FCC spectrum reallocation proceedings for C-band as an inflection indicator for equipment replacement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Architecture Migration | Virtualized baseband processing displaces dedicated hardware demodulators across Space Force installations. |
| GaN Foundry Capacity Expansion | Captive semiconductor fabrication secures RF power amplifier supply against single-source bottlenecks. |
| Managed Ground Service Launch | Antenna-as-a-service models capture recurring revenue from commercial constellation operators. |
| REACH Compliance Certification | Full material disclosure qualifies vendors for ESA procurement under EU Green Deal mandates. |
| Optical Ground Station Development | Laser communication terminals threaten RF infrastructure for high-bandwidth satellite links. |
Research Methodology
Independent corroboration across primary interviews with satellite operations directors, RF systems engineers, defense procurement officers, and cloud infrastructure architects underwrites the qualitative findings. Secondary validation draws from FCC spectrum allocation dockets, ESA procurement guidelines, SEC 10-K disclosures from listed primes, and ITU-R regulatory filings. Bottom-up segmentation modeling triangulates against top-down macroeconomic anchors across the analysis window.
Comparable historical refresh cycles from legacy hardware-dependent ground networks anchor the projection horizon. The forecast framework models system type, technology adoption curve, application mission profile, and end-user procurement authority as core segmentation dimensions. CAGRs derive from equipment replacement velocity and managed service penetration rates. Inputs include Space Force modernization appropriation trajectories and commercial constellation deployment schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to optical ground station substitution rates and ITU-R coordination timeline extensions. Practitioners should monitor GaN foundry utilization rates and FCC C-band reallocation enforcement dates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Mexico Space Electronics Market
Space
Near Space Robotics Market
Space
UK Space Electronics Market
Space
Spacecraft Market
Space
Space Launch Services Market
Space
Space Robotics Market
Space
Space Mobile Service Market
Space
Space Designing Market
Space
Space As a Service Market
Space
US Space Electronics Market
Space
Space Wheel Market
Space
Space-Based Solar Power Market
Space
China Space Electronics Market
Space
Space on Board Computing Platform Market
Space
Space Ground Station Equipment Market
Space
Space Robots Market