
 Rocket Launchpad Market | 2026-2036
Rocket Launchpad Market Size, Share, and Industry Trends Forecast 2026-2036
Rocket Launchpad Market Analysis
Buyer concentration among satellite constellation operators is expanding as SpaceX and Amazon's Project Kuiper consolidate launch procurement into multi-year pad commitments. SpaceX leverages its Starship development program to anchor demand for next-generation launch infrastructure. Blue Origin sustains investment in its Cape Canaveral and West Texas facilities to compete for national security missions. United Launch Alliance dominates the Atlas and Delta legacy pad network while navigating transition to Vulcan Centaur operations.
A rocket launchpad is a reinforced ground facility engineered to withstand thrust loads exceeding several meganewtons, incorporating flame deflectors, sound suppression systems, and propellant handling infrastructure to enable controlled orbital vehicle ascent. Fixed launchpad installations retain the largest installed base due to their integration with heritage range infrastructure, though mobile launchpad configurations are gaining share among responsive launch providers seeking rapid redeployment capability. Electromechanical and hydraulic technology segments command the dominant share of current pad control systems, while automated launchpad technology is attracting R&D investment as operators pursue reduced turnaround intervals between missions.
FAA launch site licensing and EPA National Environmental Policy Act reviews shape commercial launchpad development timelines and site selection across the United States. NASA range safety requirements and Department of Defense launch range standards further constrain design parameters for facilities supporting government missions. Stakeholders must monitor evolving FAA Part 450 commercial space transportation regulations and state-level spaceport incentive structures as these frameworks determine viable expansion pathways without assuming specific implementation calendars.
Market Dynamics
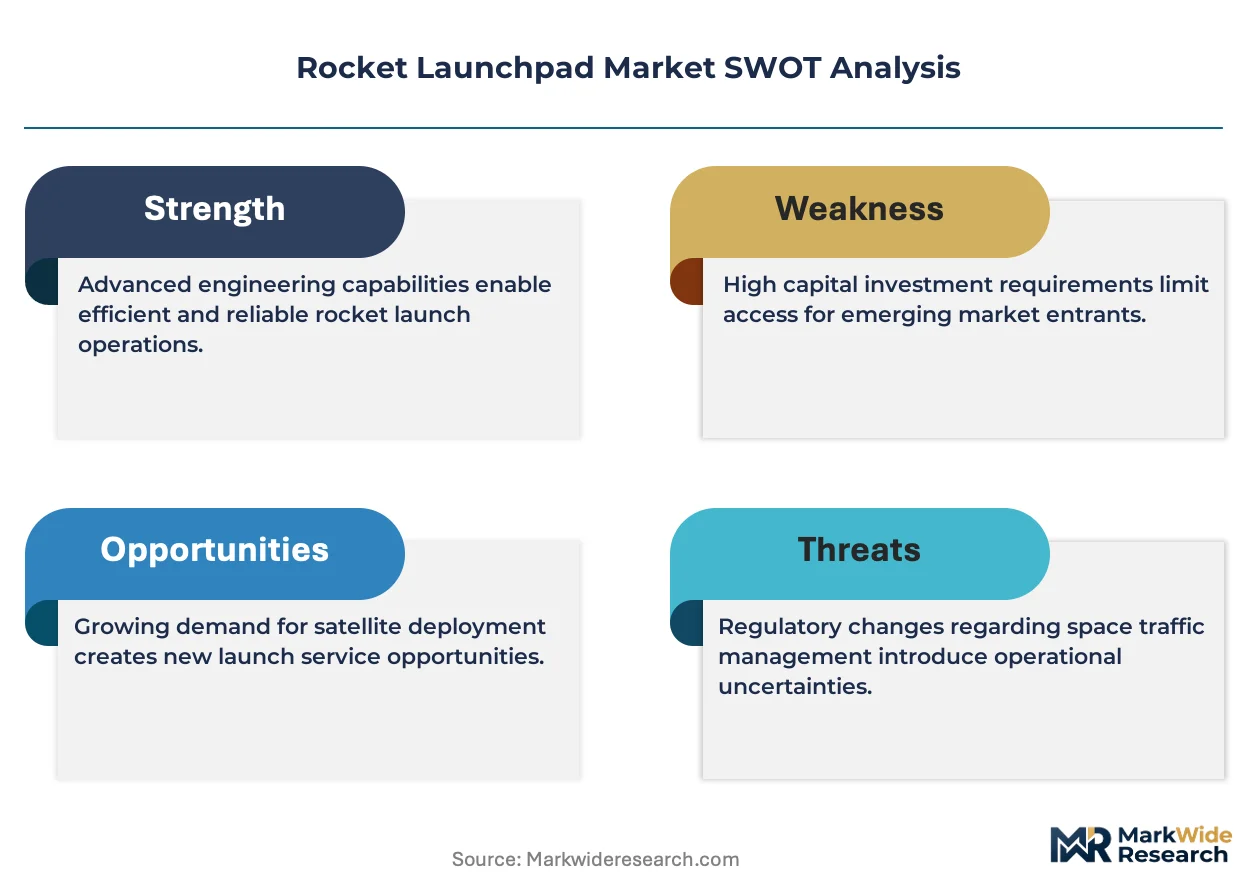
The rocket launchpad sector faces structural pressure from the shift toward reusable heavy-lift vehicles, which demands reinforced flame trench designs and accelerated turnaround protocols that legacy concrete infrastructure cannot accommodate without substantial retrofit investment.
Growth Catalysts
- LEO Constellation Deployment:Satellite constellation operators are securing dedicated launchpad capacity through multi-year infrastructure commitments, locking in pad availability ahead of manufacturing scale-up.
- FAA Part 450 Streamlining:The FAA's consolidated commercial space transportation licensing framework is reducing approval timelines for new launch site operators, expanding viable development pathways.
- Mobile Launch Systems:Responsive launch providers are deploying transportable launchpad configurations to access polar and equatorial trajectories without fixed infrastructure investment.
Market Restraints
- Specialized Steel Supply Concentration:High-grade alloy plate for flame deflectors sources from a limited supplier base concentrated in East Asian foundries, exposing pad construction to input cost volatility.
- Range Safety Integration:NASA and Department of Defense launch range standards impose design constraints that extend engineering cycles and limit architectural flexibility for commercial-only facilities.
- Environmental Review Duration:EPA National Environmental Policy Act reviews for coastal launch sites routinely extend development timelines by 24-36 months, compressing project returns.
Strategic Opportunities
- Automated Launch Control:Electromechanical and hydraulic pad control systems are converging with machine-vision inspection protocols, enabling unmanned turnaround operations between missions.
- State Incentive Capture:Florida and Texas spaceport development authorities are offering infrastructure tax abatements and range access fee reductions to anchor commercial launch activity.
- Sound Suppression Innovation:Water deluge system manufacturers are integrating recycled brine handling to address freshwater scarcity constraints at arid launch sites.
Industry Challenges
- Range Control Talent Scarcity:Licensed range safety officers with combined FAA and NASA certification credentials command premium compensation, constraining operator expansion.
- Propellant Handling Integration:Cryogenic fuel farm construction requires specialized civil engineering expertise that general infrastructure contractors lack, extending subcontractor procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rocket Launchpad Market |
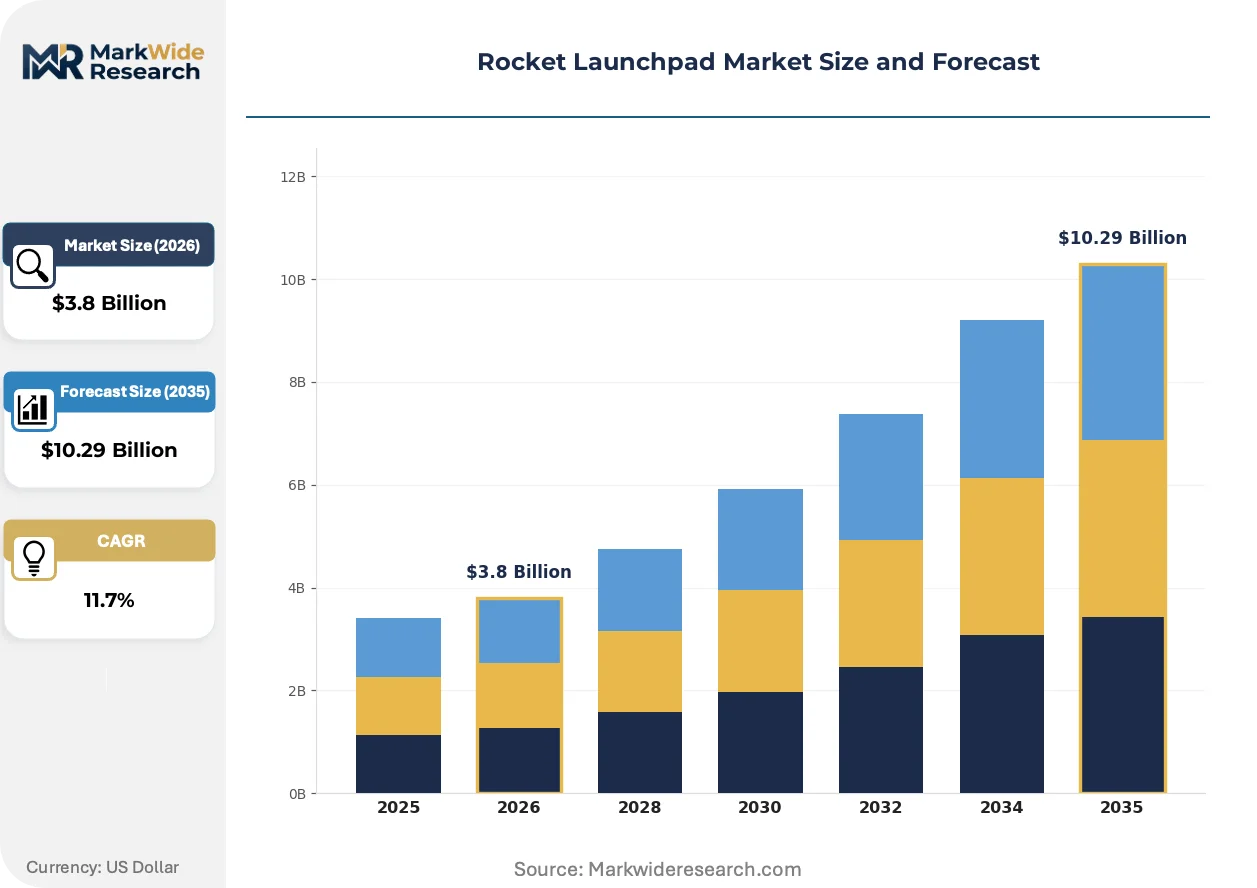
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Launchpad, Mobile Launchpad, Semi-Mobile Launchpad, Hybrid Launchpad Installation Type: Onshore, Offshore, Modular, Permanent Technology: Electromechanical, Pneumatic, Hydraulic, Automated End User: Government Agencies, Private Companies, Research Institutions, Educational Organizations |
| Companies Covered | SpaceX, United Launch Alliance, Blue Origin, Northrop Grumman, Arianespace, Rocket Lab, Relativity Space, China Aerospace Science and Technology Corporation, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rocket Launchpad Market Emerging Trajectories
Launchpad architecture is undergoing material and operational transformation as operators confront the thermal and acoustic loads of next-generation reusable vehicles. Three developments are restructuring capital deployment and competitive positioning.
Modular flame deflector systems using refractory ceramic matrix composites are decentralizing pad maintenance economics. SpaceX and Blue Origin are retrofitting fixed installations with segmented deflector assemblies that permit component-level replacement rather than full structure rebuilds. This architecture compresses turnaround intervals from weeks to days, enabling higher launch cadence without parallel pad construction.
The EPA is intensifying scrutiny of coastal launch site thermal pollution and marine ecosystem impacts under reinvigorated Clean Water Act enforcement. Facilities in Florida's Space Coast must now integrate advanced cooling water recycling and diffuser redesign to satisfy discharge permits. Operators are responding by front-loading environmental engineering into preliminary design phases, extending pre-construction timelines but reducing regulatory risk.
Launch service procurement is consolidating under multi-year pad reservation agreements that transfer capacity risk from operators to launch providers. Satellite constellation developers are abandoning per-mission slot purchasing in favor of dedicated infrastructure commitments spanning five to seven years. This shift is most pronounced among LEO broadband operators in the United States, where launch cadence requirements exceed available shared capacity.
Rocket Launchpad Market Segmentation
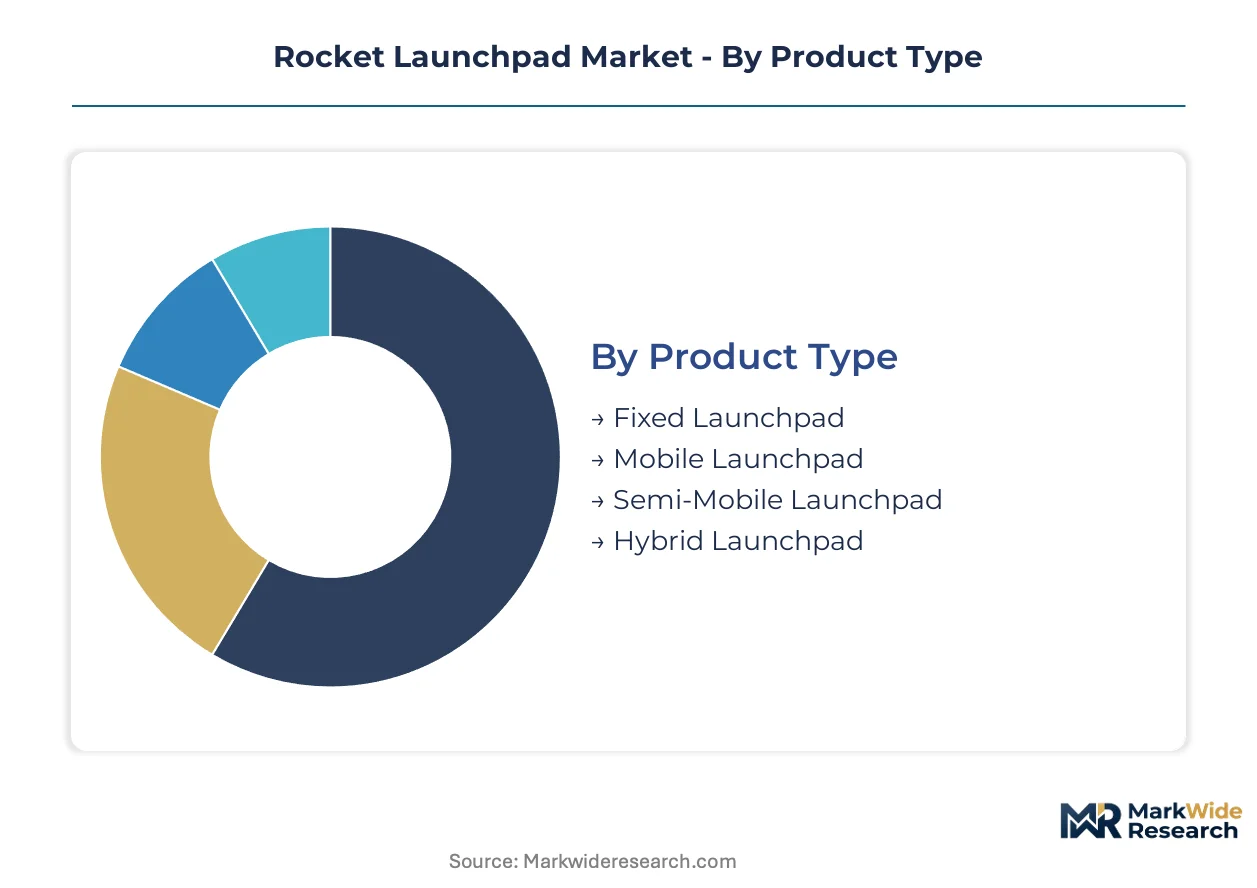
Rocket launchpad segmentation reveals how infrastructure investment splits between heritage fixed installations and emerging mobile configurations. Understanding these divides helps suppliers align R&D spending with operator procurement patterns across government and commercial missions.
Product Type:
Structural configuration determines pad resilience against thrust loads and governs redeployment economics for responsive launch architectures.
- Fixed Launchpad:Reinforced concrete installations with integrated flame trenches and propellant farms anchor heritage range infrastructure. NASA and Department of Defense missions in the United States concentrate procurement here due to range safety certification requirements and multi-decade amortization horizons.
- Mobile Launchpad:Transportable steel platforms with containerized support systems enable rapid trajectory access without fixed infrastructure commitment. Responsive launch providers in the United States are expanding procurement for polar and equatorial missions where pad sharing is uneconomical.
- Semi-Mobile Launchpad:Hybrid designs combining fixed foundations with movable launch towers balance turnaround speed against foundation costs.
- Hybrid Launchpad:Configurable architectures supporting both vertical and horizontal vehicle integration for multi-user range flexibility.
Fixed Launchpad leads on scale; Mobile Launchpad leads on momentum.
Installation Type:
Site preparation intensity and environmental permitting burden vary sharply across installation approaches, shaping project timelines and capital recovery profiles.
- Onshore:Coastal and inland ground installations dominate current capacity, with Florida's Space Coast and Texas Gulf facilities representing the densest clusters. EPA National Environmental Policy Act reviews for coastal sites routinely extend development timelines.
- Offshore:Platform-mounted pads positioned beyond territorial waters reduce population exposure and expand azimuth flexibility. FAA launch site licensing for offshore structures remains underdeveloped, constraining near-term deployment.
- Modular:Prefabricated pad components assembled on-site compress construction schedules and enable phased capacity expansion.
- Permanent:Monolithic concrete installations with 50-year design lives support high-cadence reusable vehicle operations.
Onshore retains dominant share; Offshore climbs the fastest as coastal congestion intensifies.
Technology:
Control system architecture governs turnaround intervals, labor requirements, and integration complexity with vehicle avionics.
- Electromechanical:Motor-driven pad mechanisms with programmable logic controllers command the largest installed base. United States launch ranges specify electromechanical systems for government mission compatibility.
- Hydraulic:Fluid-power actuation delivers higher force density for heavy-lift vehicle support systems and flame deflector positioning.
- Automated:Machine-vision inspection and robotic pad servicing enable unmanned turnaround operations. Satellite constellation operators are driving R&D investment here to compress inter-mission intervals below 24 hours.
- Pneumatic:Compressed-air systems for sound suppression and quick-disconnect applications offer simplicity but limited force output.
Electromechanical leads on scale; Automated leads on momentum.
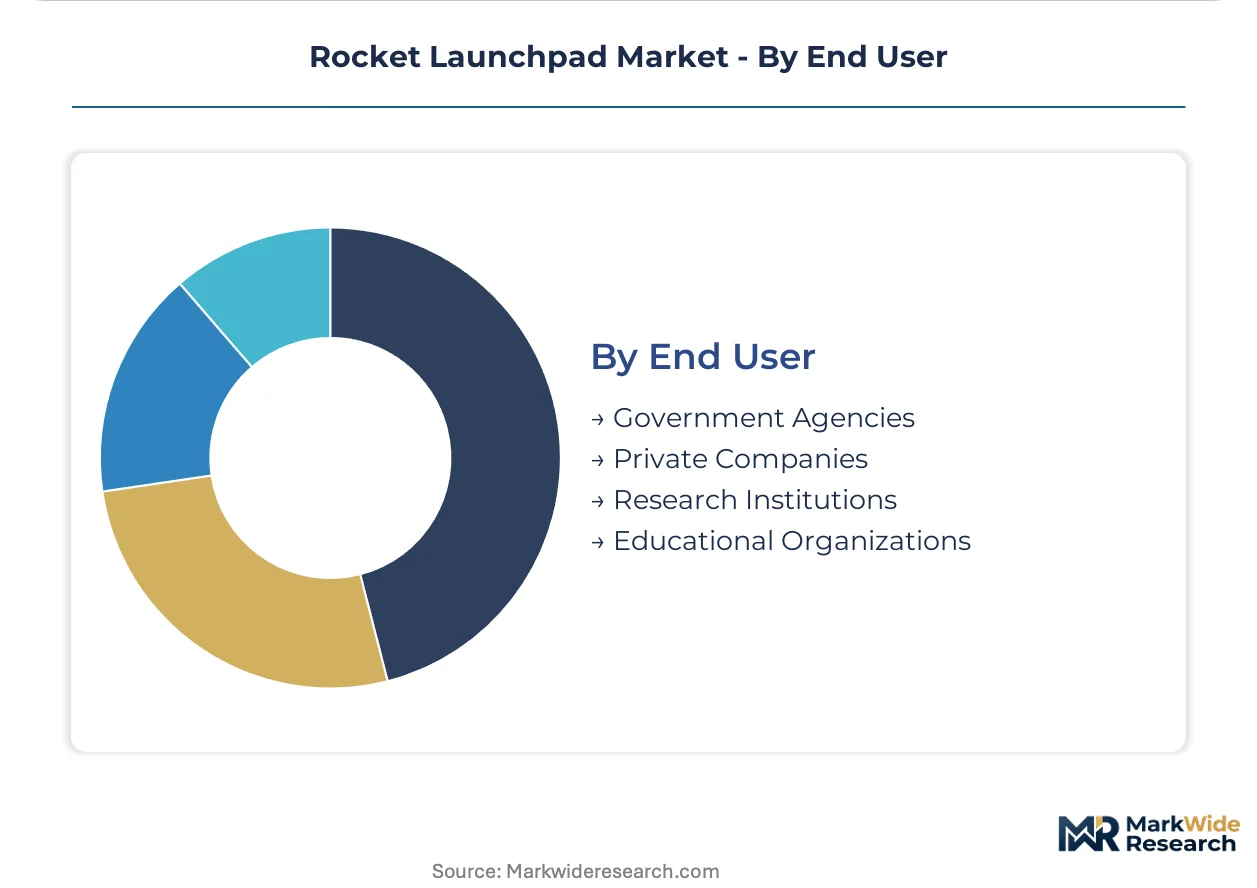
End User:
Procurement authority and mission requirements diverge sharply between government range users and commercial constellation deployers.
- Government Agencies:NASA and Department of Defense missions impose stringent range safety and environmental compliance standards. These users prioritize pad reliability and certification pedigree over turnaround speed.
- Private Companies:Satellite constellation operators and launch service providers dominate capacity expansion demand. SpaceX and Amazon's Project Kuiper are securing multi-year pad commitments to lock in launch cadence.
- Research Institutions:Universities and national laboratories operate suborbital and small-lift pads with lower thrust load requirements.
- Educational Organizations:Student rocketry programs and STEM facilities drive demand for simplified, low-throughput pad designs.
Private Companies lead on scale; Government Agencies anchor pricing stability through long-term contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Licensed range safety officers with combined FAA and NASA certification credentials concentrate in coastal aerospace corridors, anchoring launchpad development to established spaceport ecosystems rather than greenfield sites.
United States
SpaceX and Blue Origin drive pad construction across Florida's Space Coast and Texas Gulf facilities. FAA Part 450 licensing streamlines commercial approvals while EPA National Environmental Policy Act reviews extend coastal timelines. Cape Canaveral and Boca Chica host the densest clusters of next-generation reusable vehicle infrastructure.
China
China Aerospace Science and Technology Corporation expands pad capacity at Wenchang and Jiuquan centers for crewed and heavy-lift missions. MIIT and national space administration directives prioritize dual-use launch infrastructure. Hainan island hosts the Wenchang Satellite Launch Center with expanded propellant handling capabilities.
France
Arianespace sustains Ariane 6 pad operations at Guiana Space Centre while adapting infrastructure for reusable vehicle compatibility. ESA and CNES safety protocols govern range design standards. Kourou maintains Europe's primary equatorial launch access with modernized flame deflector systems.
Japan
Mitsubishi Heavy Industries operates H3 vehicle pads at Tanegashima Space Center with METI support for commercial mission expansion. JAXA range safety requirements constrain architectural flexibility for shared-use facilities. Tanegashima and Uchinoura clusters concentrate domestic orbital launch capacity.
New Zealand
Rocket Lab's Electron operations at Mahia Peninsula demonstrate mobile launchpad economics for small-lift responsive missions. New Zealand Space Agency licensing frameworks accommodate rapid pad redeployment. Mahia's remote coastal location minimizes population exposure constraints for polar trajectory access.
Rocket Launchpad Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across rocket launchpad development and operation. The market structure concentrates around vertically integrated launch service providers who control their own pad infrastructure, alongside government-backed aerospace contractors maintaining legacy range facilities. Three archetypes dominate: constellation-anchored operators securing dedicated multi-year pad commitments, responsive launch specialists deploying transportable configurations, and legacy prime contractors transitioning heritage infrastructure to next-generation vehicles. Capacity reservation agreements and automated turnaround technology licensing represent the dominant competitive moves reshaping supplier relationships.
Within the constellation-anchored operator tier, SpaceX exemplifies vertical control over launch infrastructure through its Starship development program. United Launch Alliance occupies a position bridging legacy Atlas and Delta pad networks toward Vulcan Centaur operations. Blue Origin represents the diversified aerospace conglomerate archetype sustaining multi-site investments across Cape Canaveral and West Texas facilities.
| Leading Market Players |
|---|
| SpaceX |
| United Launch Alliance |
| Blue Origin |
| Northrop Grumman |
| Arianespace |
| Rocket Lab |
| Relativity Space |
| China Aerospace Science and Technology Corporation |
| Mitsubishi Heavy Industries |
| Others |
Supply Flow & Price Mechanics
High-grade alloy plate for flame deflectors originates from East Asian foundries and flows through three pricing tiers before reaching pad construction contractors, with NASA-certified installations commanding premium multiples over commercial-only facilities due to range safety integration requirements.
Pricing Analysis
Bundled pad reservation agreements dominate procurement for satellite constellation operators, while unbundled per-mission slot purchasing persists among research institutions. Price differentiation rests on certification pedigree and launch cadence commitments. Cost compression in commercial-only tiers is intensifying because mobile launchpad providers are undercutting fixed installation economics. Government agencies exhibit the least price sensitivity due to mission-critical reliability requirements, whereas responsive launch startups face acute budget constraints.
Supply Chain Analysis
Freight costs for oversized flame trench components and cryogenic fuel farm vessels concentrate supply chain leverage with specialized heavy-lift logistics providers serving Japan, Germany, and the United States. Raw material dependencies include nickel-based superalloys, high-density concrete additives, and marine-grade structural steel. Single-source vulnerability in East Asian alloy plate exposes pad construction to input cost volatility. Distribution runs through prime contractor-led consortia integrating civil engineering, environmental compliance, and range safety certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FAA Part 450 licensing streamlines commercial approvals while EPA National Environmental Policy Act reviews extend development timelines, creating sustained demand for environmental engineering and range safety expertise.
For Market Incumbents: To counter mobile launchpad erosion of fixed installation share, incumbents should anchor multi-year pad reservation agreements with constellation operators and deepen backward integration into automated launch control systems. Certification investment in FAA-NASA dual credentials for range safety officers preserves pricing power against emerging competitors.
For New Entrants and Emerging Players: Automated turnaround technology licensing offers the most penetrable wedge against entrenched electromechanical incumbents. Target offshore platform-mounted pads where FAA licensing frameworks remain underdeveloped. Pursue state spaceport incentive capture in Florida and Texas as the primary go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where range safety talent scarcity constrains operator expansion. Long-term viability favors vertically integrated launch service providers controlling captive pad infrastructure. Watch for inflection in state-level spaceport tax abatement intensity as a signal of capacity oversupply risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Launch Control Deployment | Machine-vision inspection protocols enable unmanned turnaround operations below 24-hour intervals. |
| Modular Flame Deflector Retrofit | Segmented ceramic matrix assemblies compress maintenance from weeks to days for reusable vehicles. |
| State Incentive Capture Program | Florida and Texas infrastructure tax abatements anchor commercial launch activity against competing jurisdictions. |
| Offshore Platform Development | Platform-mounted pads beyond territorial waters expand azimuth flexibility while reducing population exposure. |
| Range Safety Talent Pipeline | FAA-NASA dual certification programs address licensed officer scarcity constraining operator expansion. |
Methodological Framework
Multiple input streams — launch range operators, pad construction contractors, satellite constellation procurement leads, and environmental engineering consultants — were reconciled against FAA licensing databases, EPA NEPA review records, and state spaceport authority filings. Primary interviews with range safety officers and propellant handling specialists were validated through secondary analysis of NASA range safety requirements and Department of Defense launch range standards. Bottom-up pad capacity estimates and top-down infrastructure investment flows were triangulated to establish market boundaries.
Data-stream reconciliation across fixed, mobile, and semi-mobile installation types, electromechanical and automated control technologies, and government versus private end-user segments shaped the analytical framework throughout the projection horizon. CAGRs were derived from trajectory modeling of constellation deployment schedules and licensing approval velocity. Industry-specific forecast inputs included Starship development cadence and Ariane 6 transition timelines.
The model holds under steady FAA Part 450 implementation and stable EPA enforcement intensity; deviation in NEPA review duration or alloy plate supply disruption would shift capacity expansion timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Africa Space Electronics Market
Space
Italy Space Electronics Market
Space
Space Ground Station Equipment Market
Space
Canada Space Electronics Market
Space
Space Blanket Market
Space
Space in Orbit Refueling Market
Space
Germany Space Electronics Market
Space
Space Burial Service Market
Space
North America Spacesuit Market
Space
Japan Space Electronics Market
Space
Space Management Solutions Market
Space
Spain Space Electronics Market
Space
Deep Space Exploration Market
Space
China Space Electronics Market
Space
Space Semiconductor Market
Space
Space Technology (Spacetech) Market