
 Space Sensors Market | 2026-2036
Space Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Space Sensors Market Analytics
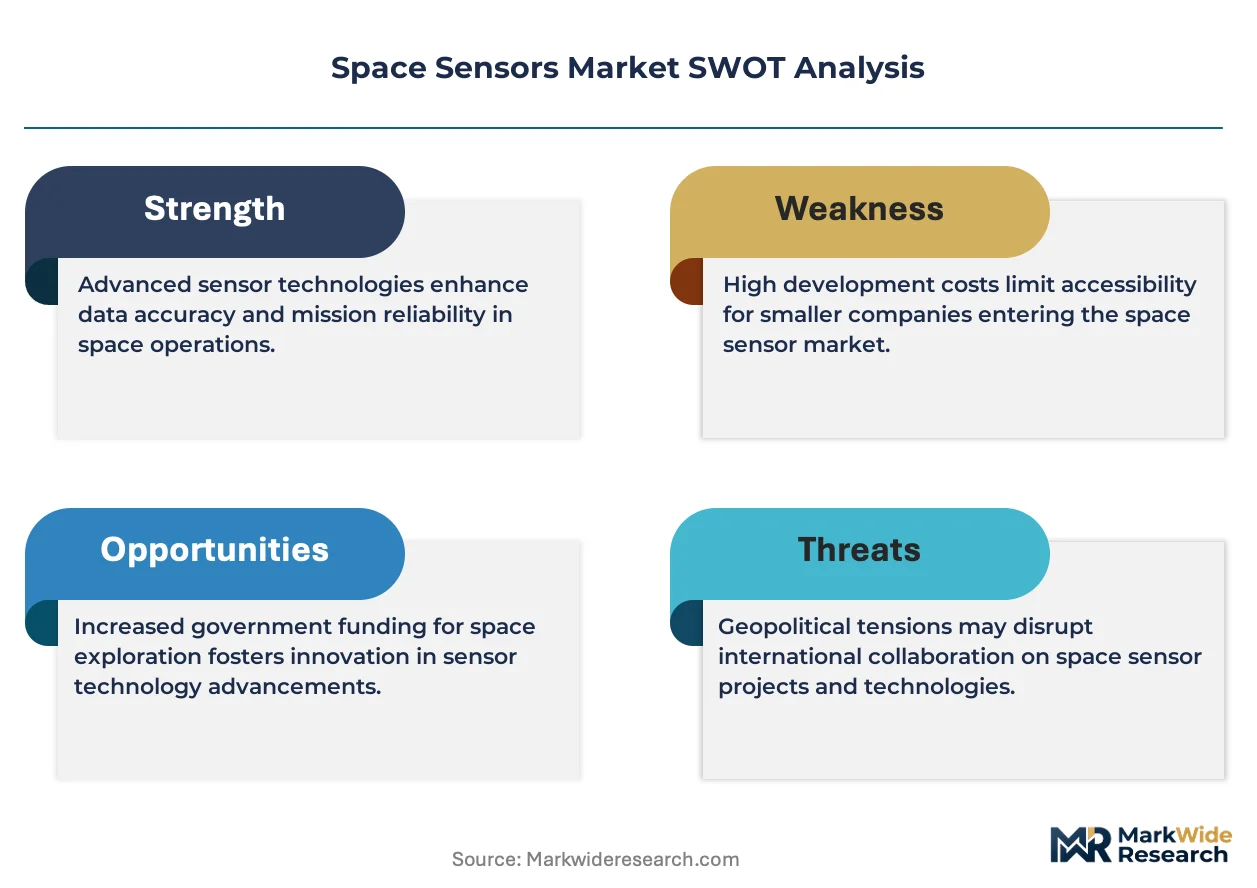
AS9100 certification is collapsing as the baseline qualification for Tier-1 space sensor suppliers, compressing the vendor pool to firms with sustained aerospace quality management investment. Honeywell International Inc. leverages its radiation-hardened MEMS heritage across satellite attitude control systems. Teledyne Technologies Incorporated sustains dual-use imaging sensor production for both civilian Earth observation and defense payloads. Safran anchors European sovereign capability through inertial reference units qualified for Ariane and Galileo programs.
Space sensors are precision transducers engineered to detect electromagnetic radiation, thermal gradients, or inertial forces in orbital environments where vacuum exposure and ionizing radiation demand hermetic packaging and single-event upset tolerance; their primary purpose is generating actionable telemetry for spacecraft guidance, remote sensing, and environmental monitoring. Optical sensors occupy the largest revenue share due to persistent demand for high-resolution Earth imaging constellations. MEMS sensors represent the fastest-expanding technology segment as miniaturization reduces launch mass penalties for smallsat operators. Solid-state sensors command premium pricing in interplanetary missions where component longevity exceeds fifteen years operational life.
ITAR controls in the United States restrict sensor technology transfer, while ESA's ECSS standards govern European qualification protocols; both frameworks elevate compliance costs but protect incumbent suppliers from commoditization. China's GB standards and MIIT directives are cultivating a parallel domestic supply chain for BeiDou and Chang'e mission sensors. Stakeholders must monitor export control harmonization between the U.S. State Department and European Union dual-use regulations, as divergence would fragment procurement strategies for multinational satellite operators.
Market Dynamics
Radiation-hardened component qualification timelines are compressing procurement cycles as NASA Artemis and ESA Copernicus expansion accelerate mission deployment schedules, forcing suppliers to absorb AS9100 compliance costs upfront or exit the vendor pool.
Growth Catalysts
- LEO constellation deployment:Satellite communication networks are scaling optical and radar sensor procurement volumes. Smallsat operators demand miniaturized payloads that reduce per-unit launch mass penalties.
- ITAR-controlled technology pipelines:United States export restrictions create protected domestic markets for radiation-hardened MEMS and solid-state sensor manufacturers serving Space Force budgets.
- Copernicus program expansion:ESA's Earth observation mandate drives qualification requirements for European sovereign sensor capabilities, particularly inertial reference units for Galileo navigation payloads.
Market Restraints
- Single-source radiation-hardened semiconductor supply:Foundry capacity for space-grade electronics concentrates among limited qualified suppliers, exposing procurement to queue-time volatility.
- ECSS qualification cost burden:European Space Agency standards impose multi-year validation protocols that lock out mid-tier sensor developers lacking sustained aerospace quality management investment.
- Optical sensor thermal management complexity:Vacuum environment heat dissipation limitations constrain high-resolution imaging payload duty cycles and operational lifespans.
Strategic Opportunities
- Interplanetary mission longevity premiums:Solid-state sensors commanding fifteen-plus year operational life specifications create pricing power in deep-space probe applications beyond Earth orbit.
- China parallel supply chain cultivation:MIIT directives and GB standards are building captive domestic capabilities for BeiDou navigation and Chang'e lunar mission sensors.
- MEMS-lidar convergence:Miniaturized inertial measurement units integrated with photonic ranging systems enable autonomous navigation for emerging on-orbit servicing spacecraft.
Industry Challenges
- Radiation effects engineering talent scarcity:Single-event upset mitigation and total ionizing dose hardening expertise resides within aging workforce cohorts at legacy aerospace primes.
- Hermetic packaging capex intensity:Vacuum-sealed sensor housing fabrication requires specialized brazing and welding equipment with decade-long depreciation horizons.
- Dual-use classification ambiguity:ITAR jurisdiction determinations for commercial Earth observation payloads create licensing delays that compress satellite integration schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Sensors Market |
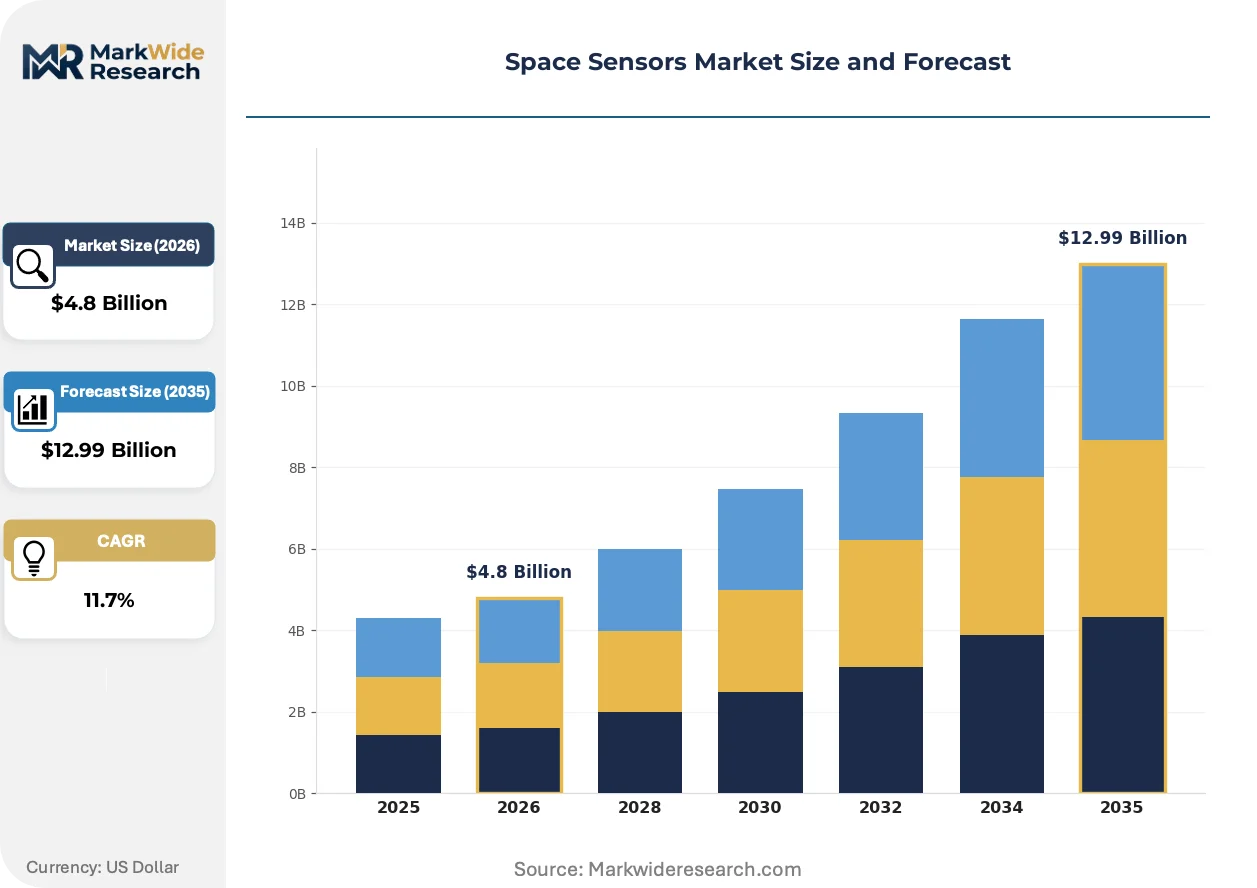
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Optical Sensors, Radar Sensors, Infrared Sensors, Temperature Sensors Application: Satellite Communication, Earth Observation, Space Exploration, Scientific Research End User: Aerospace Agencies, Commercial Space Companies, Defense Organizations, Research Institutions Technology: Active Sensors, Passive Sensors, Solid-State Sensors, MEMS Sensors |
| Companies Covered | Honeywell International Inc., Teledyne Technologies Incorporated, Moog Inc., Airbus, Safran, L3Harris Technologies Inc., Ametek Inc., TE Connectivity Ltd., RUAG Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Sensors Market Evolving Landscape
Optical sensor architectures are bifurcating between high-resolution government payloads and commoditized commercial constellations, while qualification frameworks fragment across ITAR, ECSS, and emerging Chinese standards.
Photonic integrated circuits are fragmenting traditional discrete optical sensor assemblies. Smallsat operators are adopting silicon photonics for star trackers and coarse sun sensors at volumes exceeding ten thousand units annually. This technology is fragmenting the supplier base by enabling fabless design houses to bypass legacy aerospace prime manufacturing relationships.
ECSS-Q-ST-60-02C qualification protocols are tightening radiation hardness assurance requirements for European-flagged missions. Component suppliers must now document single-event latchup thresholds across full mission dose profiles. Earth observation primes in Germany and France are responding by pre-qualifying dual-source sensor architectures to mitigate schedule risk from single-foundry dependencies.
Constellation operators are consolidating procurement through direct sensor payload specification rather than spacecraft prime contractor intermediation. Commercial imagery providers now contract optical focal plane assemblies separately from bus integration, compressing traditional supply chain tiers. This pattern is most visible in United States smallsat clusters where Cape Canaveral launch cadence supports rapid iteration cycles.
Space Sensors Market Segmentation
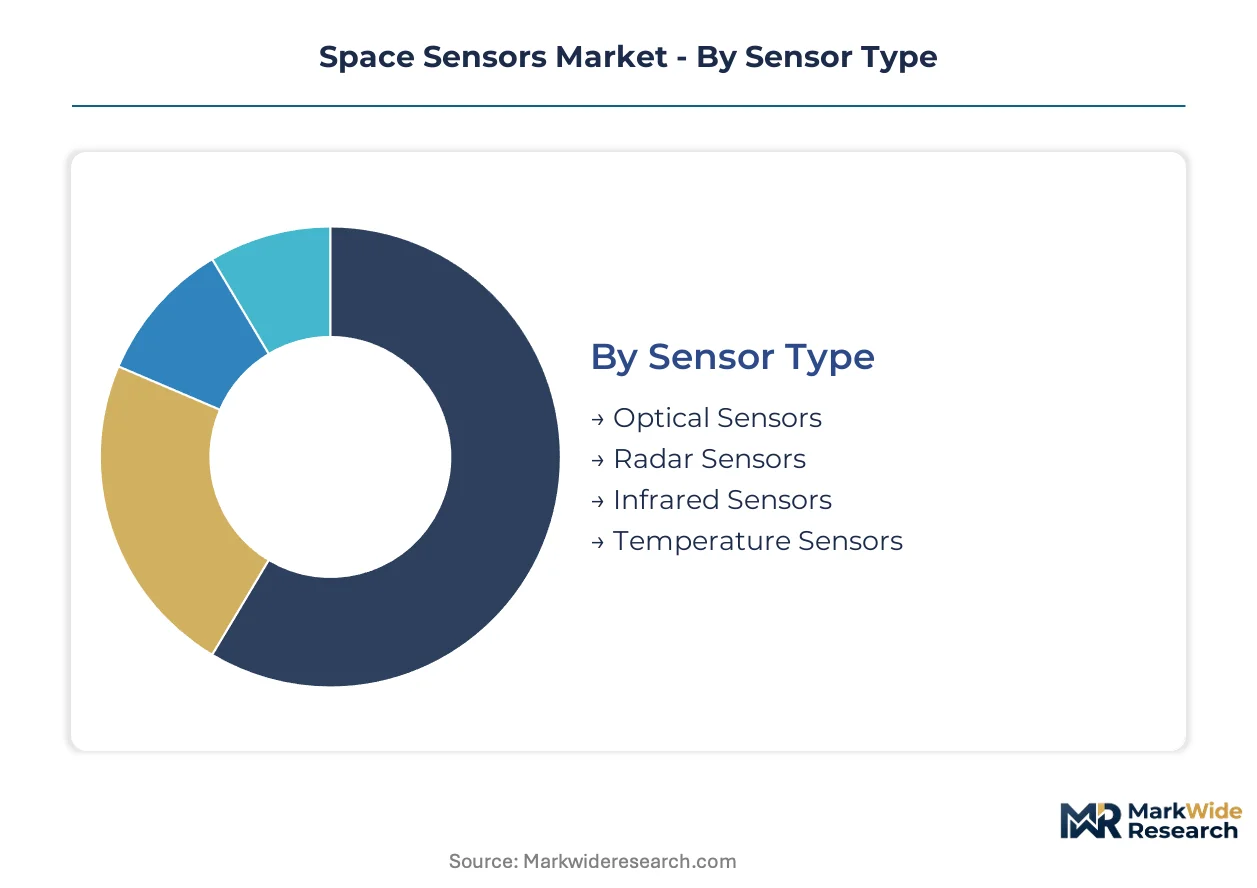
Space sensor procurement patterns diverge sharply across mission profiles, with Earth observation constellations driving volume demand while deep-space exploration sustains premium pricing tiers. Understanding these segment boundaries reveals where qualification investments concentrate and which technology platforms capture disproportionate value.
Sensor Type:
Optical and radar sensors anchor United States domestic procurement through NASA and Space Force budgets, while infrared and temperature sensors flow more heavily into export markets serving European and Asian constellation operators.
- Optical Sensors:Precision focal plane arrays and multispectral imagers detect electromagnetic radiation across visible and near-infrared wavelengths. Demand concentrates in United States commercial Earth observation constellations launching from Cape Canaveral, where high-resolution imaging specifications drive qualification cycles for radiation-hardened detector substrates.
- Radar Sensors:Synthetic aperture radar and altimetry payloads penetrate cloud cover and darkness using active microwave transmission. European procurement through ESA's Copernicus expansion and German-Italian government programs sustains dual-use manufacturing lines that serve both civilian and defense applications.
- Infrared Sensors:Thermal detection arrays for space situational awareness and climate monitoring.
- Temperature Sensors:Cryogenic and thermal gradient monitors for propulsion system health.
Optical sensors command the established base. The steepest expansion runs through radar sensors.
Application:
Mission duration and orbital regime determine cost tier stratification, with geostationary and deep-space applications sustaining premium pricing against commoditized low-Earth orbit payloads.
- Satellite Communication:RF payload sensors and antenna pointing mechanisms maintain link stability across orbital perturbations. Starlink and OneWeb constellation scale-up in the United States and United Kingdom compresses procurement cycles for attitude determination sensors qualified for fifteen-year operational life.
- Earth Observation:Multispectral and hyperspectral imagers generate geospatial intelligence and agricultural analytics. French and German prime contractors pre-qualify dual-source sensor architectures under ECSS protocols to mitigate schedule risk from single-foundry dependencies for Copernicus expansion timelines.
- Space Exploration:Interplanetary probe instrumentation for lunar and Mars missions.
- Scientific Research:Astrophysics and heliophysics mission sensors for institutional investigators.
Earth observation captures the volume base. The most rapid climb occurs in satellite communication.
End User:
Customer type dictates procurement channel structure, with defense and agency buyers requiring prime contractor intermediation while commercial operators increasingly specify payloads directly.
- Aerospace Agencies:NASA, ESA, and JAXA mission assurance requirements impose multi-year qualification protocols. Artemis program timelines in the United States and Copernicus expansion in Europe accelerate radiation-hardened component procurement through established prime relationships.
- Commercial Space Companies:Smallsat operators and constellation developers iterate sensor specifications rapidly. Cape Canaveral launch cadence supports direct payload contracting separate from bus integration, compressing traditional supply chain tiers for United States-based imagery providers.
- Defense Organizations:Classified payload requirements with ITAR-controlled technology pipelines.
- Research Institutions:University and laboratory mission sensors with relaxed qualification standards.
Aerospace agencies anchor the qualification infrastructure. Commercial space companies are gaining share fastest.
Technology:
Manufacturing maturity separates segments, with solid-state and MEMS platforms displacing legacy electromechanical architectures in volume applications.
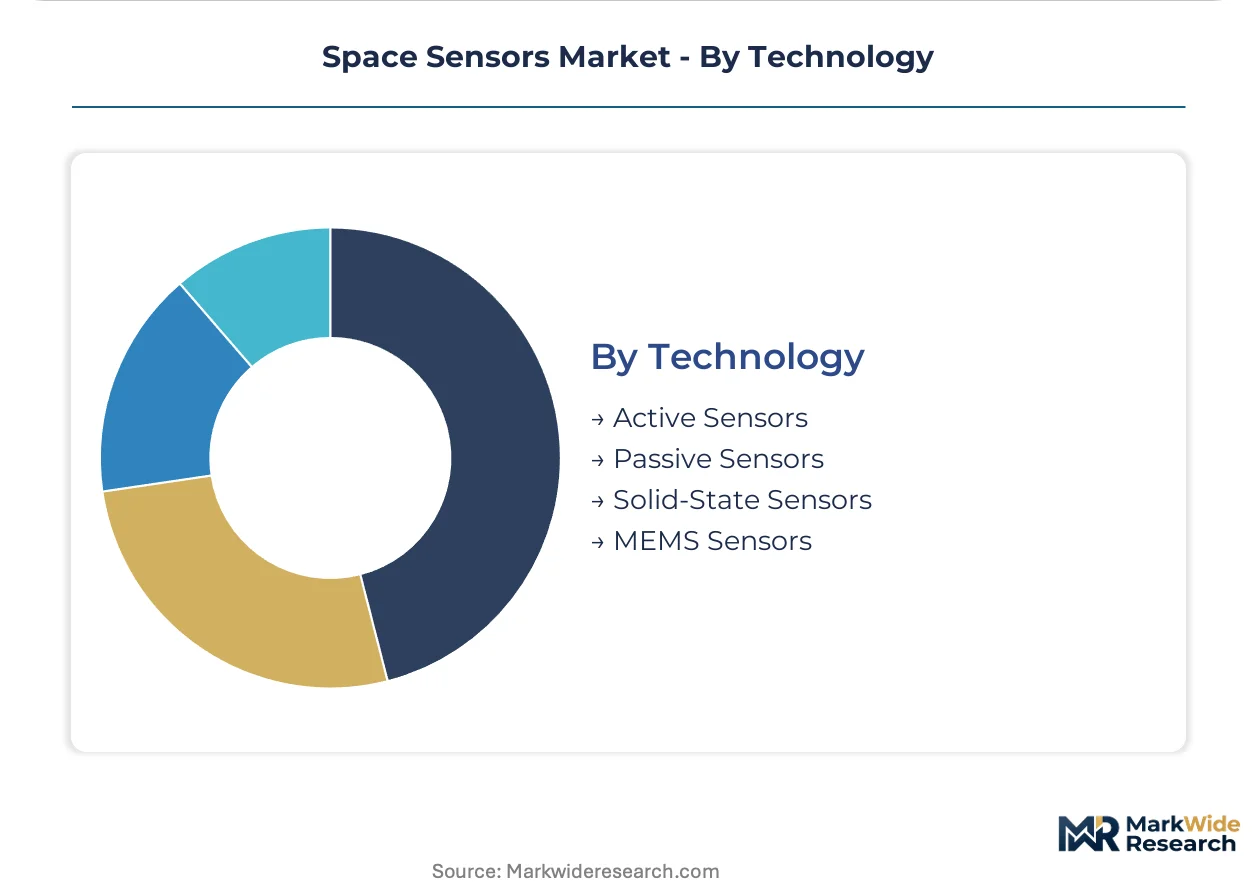
- MEMS Sensors:Miniaturized inertial measurement units and micro-accelerometers reduce launch mass penalties. Smallsat operators in the United States adopt silicon photonics-integrated MEMS for star trackers at volumes exceeding ten thousand units annually, fragmenting the supplier base toward fabless design houses.
- Solid-State Sensors:Radiation-hardened semiconductor devices with no moving parts sustain fifteen-plus year operational life. Deep-space probe applications beyond Earth orbit command premium pricing for interplanetary missions where component longevity exceeds standard LEO specifications.
- Active Sensors:Radar and lidar systems with onboard signal generation.
- Passive Sensors:Detectors relying on external electromagnetic or thermal sources.
Solid-state sensors retain the premium tier. MEMS sensors show the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement clusters and commercial launch infrastructure concentrate demand among a narrow set of national buyers. NASA Artemis timelines and Space Force budgets anchor United States procurement volumes. ESA Copernicus expansion and sovereign navigation programs drive European qualification requirements. China's BeiDou and Chang'e missions cultivate parallel domestic supply chains.
United States
Space Force budgets and Cape Canaveral launch cadence sustain the largest addressable sensor market. ITAR controls restrict technology transfer while protecting domestic radiation-hardened MEMS manufacturers. Vandenberg Space Force Base and the Colorado aerospace corridor concentrate prime contractor integration facilities for classified and civilian payloads alike.
France
Ariane launch vehicle production and Galileo navigation payload development anchor European sovereign capability. ESA ECSS-Q-ST-60-02C qualification protocols impose multi-year validation requirements for radiation hardness assurance. Toulouse and Paris-Saclay clusters host Earth observation primes pre-qualifying dual-source sensor architectures for Copernicus expansion timelines.
Germany
Copernicus ground segment operations and SAR payload manufacturing sustain dual-use sensor production lines. National space agency DLR procurement aligns with ESA standards while supporting independent Earth observation missions. Munich and Bremen industrial bases concentrate optical focal plane assembly integration for export and domestic constellation operators.
China
MIIT directives and GB standards cultivate captive supply chains for BeiDou navigation and Chang'e lunar mission sensors. State-directed investment targets radiation-hardened component independence from Western qualification frameworks. Beijing and Shanghai aerospace clusters integrate domestic MEMS and solid-state sensor production for sovereign satellite programs.
Japan
JAXA H3 launch vehicle deployment and Earth observation satellite renewal programs sustain precision sensor demand. METI industrial policy coordinates domestic supply chain resilience for space-grade electronics. Tsukuba and Nagoya manufacturing corridors concentrate inertial reference unit production for institutional and commercial smallsat operators.
Space Sensors Market Competitive Landscape
Player mix skews toward diversified aerospace conglomerates with sustained AS9100 quality management investment. Tier-1 suppliers absorb multi-year qualification costs upfront or exit the vendor pool entirely. Two strategic archetypes dominate: radiation-hardened heritage primes leveraging MEMS and solid-state legacies, and European sovereign capability anchors qualified for Ariane and Galileo programs. Competitive moves center on direct payload specification by constellation operators and pre-qualified dual-source architectures to mitigate single-foundry schedule risks.
Within the heritage prime tier, Honeywell International Inc. and Teledyne Technologies Incorporated exemplify sustained aerospace quality management investment. Honeywell's position reflects radiation-hardened MEMS heritage across satellite attitude control applications. Teledyne occupies a role sustaining dual-use imaging sensor production for civilian Earth observation and defense payloads. Safran S.A. anchors European sovereign capability through inertial reference units, representing the continental qualification infrastructure that ESA programs depend upon. These three firms collectively illustrate how AS9100 certification collapse compresses the vendor pool toward entities with decade-long compliance track records.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Teledyne Technologies Incorporated |
| Moog Inc. |
| Airbus |
| Safran |
| L3Harris Technologies Inc. |
| Ametek Inc. |
| TE Connectivity Ltd. |
| RUAG Group |
| Others |
Value Network & Pricing Analysis
Eighteen-month qualification queues for radiation-hardened foundry slots concentrate pricing power among AS9100-certified incumbents while compressing margins for mid-tier suppliers locked out of NASA and ESA procurement pipelines. This lead-time asymmetry stratifies the vendor pool into cost-plus contract tiers indexed to semiconductor commodity benchmarks and mission-criticality premiums.
Pricing Analysis
Cost-plus contracts with labor and materials indexation dominate procurement for aerospace agency missions, while commercial constellation operators negotiate fixed-price multi-unit agreements. Price differentiation rests on ECSS qualification grade and ITAR certification tier, with uncontrolled technology commanding substantial discounts. Pricing pressure stems from smallsat operators demanding MEMS commoditization at ten-thousand-unit scale. Commercial space companies exhibit highest price sensitivity; deep-space probe programs show lowest.
Supply Chain Analysis
Inventory buffers of six-to-nine months for space-grade semiconductor wafers reflect single-source dependencies on United States, European, and Japanese radiation-hardened foundries. Supply chains draw from germanium substrates, indium gallium arsenide detectors, and hermetic packaging alloys. Single-foundry vulnerability concentrates schedule risk for Copernicus and Artemis timelines. Distribution runs through prime contractor integration facilities at Cape Canaveral, Vandenberg, and Kourou.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Space sensors constitute a high-growth disruption as photonic integrated circuits fragment traditional discrete optical assemblies and enable fabless design houses to bypass legacy prime relationships. This technology inflection compresses incumbent margins while opening white-space for qualified new entrants.
For Market Incumbents: Consolidate radiation-hardened foundry relationships through long-term capacity reservations at qualified suppliers in the United States and Europe. Deepen backward integration into hermetic packaging fabrication to capture margin pools currently leaking to specialized brazing subcontractors. Lock in dual-source architectures before ECSS-Q-ST-60-02C tightening accelerates pre-qualification costs. For New Entrants and Emerging Players: Differentiate on silicon photonics integration for smallsat star trackers and coarse sun sensors where annual volumes exceed legacy aerospace prime production economics. Target United States commercial constellation operators contracting payloads directly rather than through spacecraft bus integrators. Pursue fabless design partnerships with established MEMS foundries to bypass decade-long AS9100 compliance timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified aerospace conglomerates seeking to monetize non-core sensor divisions lacking scale for sustained ECSS investment. Five-to-ten-year viability hinges on qualification infrastructure amortization across expanding constellation demand. Signal to watch: Cape Canaveral launch cadence sustaining direct payload specification trends that compress traditional supply chain tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Radiation-Hardened Foundry Capacity Reservation | Locks in semiconductor supply for NASA Artemis and ESA Copernicus procurement pipelines. |
| Silicon Photonics Platform Launch | Enables fabless entry into smallsat star tracker volumes exceeding ten thousand units annually. |
| Dual-Source Architecture Pre-Qualification | Mitigates schedule risk from single-foundry dependencies under tightening ECSS protocols. |
| Hermetic Packaging Backward Integration | Captures margin pools from specialized brazing equipment with decade-long depreciation horizons. |
| Direct Payload Specification Partnership | Bypasses spacecraft prime intermediation for commercial imagery providers at Cape Canaveral. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with satellite program managers, radiation effects engineers, procurement officers at constellation operators, and ECSS qualification specialists; and secondary validation through NASA contract announcements, ESA Copernicus procurement databases, ITAR jurisdiction determinations, and semiconductor foundry capacity disclosures. Bottom-up sensor unit economics triangulated against top-down agency budget allocations.
Across the analysis window, forecasts model technology platform displacement curves, mission profile segmentation by orbital regime, and end-user channel structure evolution. CAGRs derive from unit volume build-ups by sensor type crossed with pricing tier stratification. Key inputs include Space Force budget appropriations, Cape Canaveral launch manifest density, and ESA member state contribution shares to Copernicus expansion.
Decision-makers should treat outputs as directional under assumptions of sustained Artemis timeline acceleration and ITAR-EU dual-use regulatory harmonization; material deviation in either would warrant model refresh. Specific risks include single-event upset hardening talent scarcity and hermetic packaging equipment lead-time extension. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Europe Space Logistics Market
Space
Space Robots Market
Space
UK Space Electronics Market
Space
South Korea Space Electronics Market
Space
France Space Electronics Market
Space
China Space Electronics Market
Space
Space Mining Market
Space
Space Launch Services Market
Space
UK Space Propulsion System Market
Space
US Space Electronics Market
Space
US Space Launch Services Market
Space
Asia-Pacific Space Logistics Market
Space
Private Space Travel Market
Space
Africa Space Propulsion System Market
Space
Asteroid Mining Market
Space
Space Battery Market