
 US Space Launch Services Market | 2026-2036
US Space Launch Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Space Launch Services Market Insights
Market Context
Heavy-lift certification standards is rotating the US Space Launch Services Market toward higher-reliability orbits. SpaceX leverages its Starship development program to capture NASA Artemis logistics contracts. United Launch Alliance anchors national security missions through its Vulcan Centaur platform. Blue Origin competes via its New Glenn reusable architecture and BE-4 engine manufacturing scale.
Technical Definition and Segments
US Space Launch Services encompass the end-to-end provision of orbital insertion capability, encompassing propulsion systems rated for specific payload masses to precise altitudes and inclinations, with primary industrial purpose spanning satellite deployment, crewed missions, and interplanetary probes. Reusable launch vehicles command expanding share as refurbishment cycles compress turnaround intervals below expendable alternatives. Dedicated launch services concentrate margin pools where government and defense payloads prioritize schedule certainty over rideshare economics. Small satellite launchers face structural pressure as heavy-lift rideshare options absorb formerly fragmented demand.
Regulatory Framework
FAA Part 450 regulations, FCC spectrum licensing for satellite constellations, and NASA safety standards govern market access and operational tempo across US launch sites. These frameworks shape demand by dictating pad utilization rates, environmental review scope, and payload integration timelines. Stakeholders must monitor how evolving FAA streamlining interacts with NEPA litigation risk at coastal launch facilities.
Market Dynamics
Reusable heavy-lift architecture is compressing launch economics while concentrating operational gravity in Texas and Florida coastal corridors, fundamentally restructuring how payload providers contract for orbital access.
Growth Catalysts
- FAA Part 450 Streamlining:The FAA's consolidated launch licensing framework collapses approval timelines from 180 days toward 90 days, accelerating pad turnover rates at Cape Canaveral and Boca Chica.
- National Security Payload Demand:USSF and NRO missions prioritize domestic launch capacity, mandating assured access to space through certified heavy-lift providers under National Security Space Launch Phase 3 requirements.
- Propulsion Refurbishment Cycles:Rapid engine turnaround protocols are compressing booster reuse intervals below 60 days, displacing expendable alternatives in commercial satellite deployment.
Market Restraints
- Launch Site Concentration Risk:Over 80% of US orbital capacity sits within hurricane-exposed Florida and Texas coastlines, creating weather-driven schedule vulnerability.
- Specialized Alloy Supply Bottlenecks:Inconel and titanium sourcing for combustion chambers concentrates with a limited qualified supplier base, constraining production scaling.
- NEPA Litigation Exposure:Environmental review challenges at coastal facilities extend pad modification timelines, creating regulatory friction distinct from FAA licensing efficiency gains.
Strategic Opportunities
- California Polar Corridor Development:Vandenberg Space Force Base expansion for sun-synchronous orbits offers underutilized capacity for earth observation constellations.
- In-Space Servicing Convergence:Orbital refueling and satellite life extension technologies are creating demand for precision heavy-lift to specific orbital planes.
- IRA Clean Manufacturing Incentives:Domestic production tax credits for green hydrogen and sustainable aviation fuels apply to propellant supply chain investments.
Industry Challenges
- Propulsion Engineering Talent Scarcity:Full-flow staged combustion and methane engine expertise concentrates with a narrow cohort of experienced designers, constraining workforce scaling.
- Human-Rating Certification Complexity: NASA Commercial Crew safety standards impose 300+ verification requirements, extending development timelines for crew-capable vehicles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Space Launch Services Market |
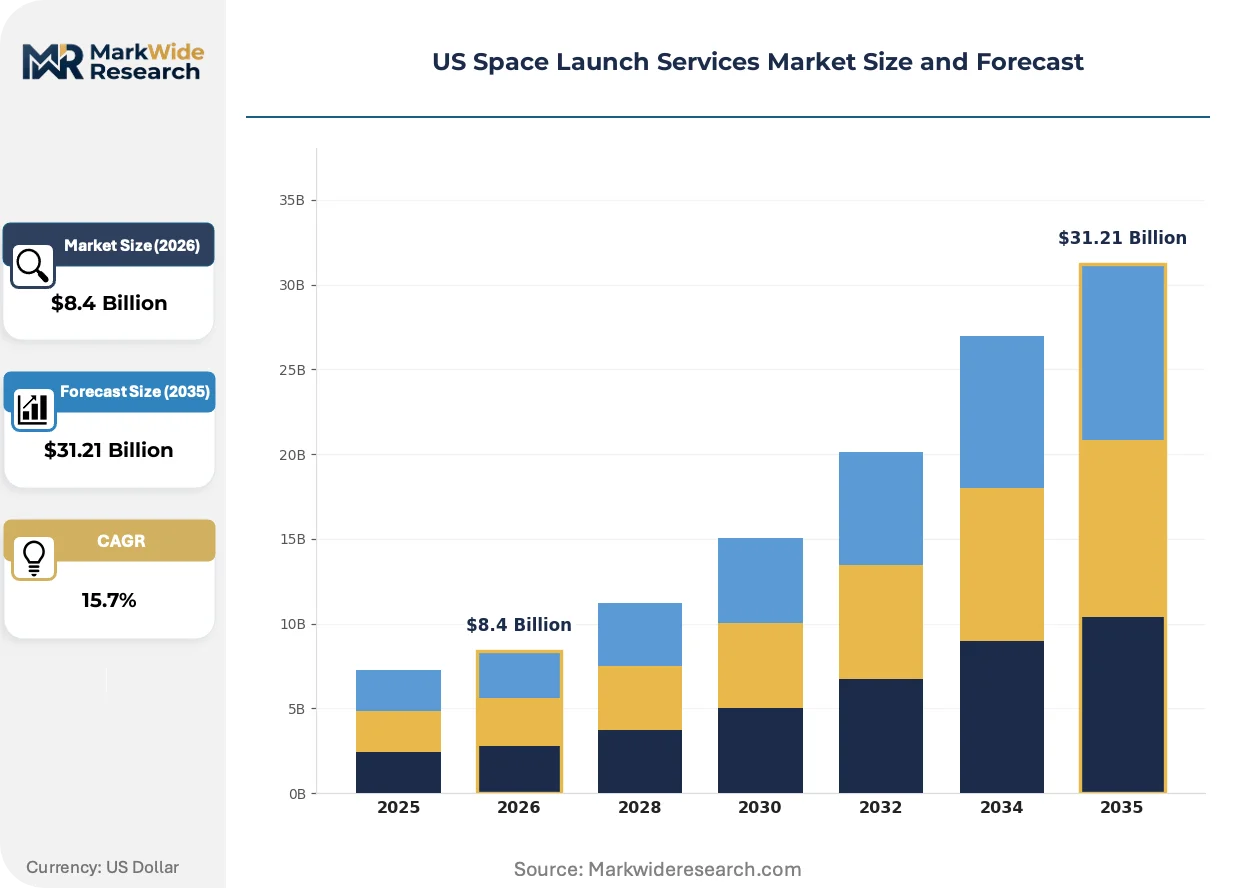
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $31.21 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Launch Vehicle Type: Reusable, Expendable, Small Satellite Launchers, Heavy Launchers End User: Government, Commercial, International Space Agencies, Academic Institutions Service Type: Dedicated Launch Services, Rideshare Launches, Test Launches, Cargo Delivery Application: Satellite Deployment, Scientific Research, Human Spaceflight, Space Exploration |
| Companies Covered | Northrop Grumman, Relativity Space, SpaceX, Lockheed Martin, Firefly Aerospace, Blue Origin, Rocket Lab, Intuitive Machines, United Launch Alliance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Space Launch Services Market Trends and Innovations
Active propulsion architecture and regulatory streamlining are converging to compress cost structures while opening orbital access to previously price-excluded payload categories.
Stainless steel alloy construction for cryogenic tanks is displacing carbon fiber composites in next-generation heavy-lift vehicles. SpaceX and Blue Origin both pursue this material transition for its thermal tolerance and manufacturing simplicity. The shift is miniaturizing per-kilogram structural costs while enabling rapid field repair protocols.
FCC spectrum licensing for mega-constellations now mandates debris mitigation and collision avoidance capabilities as condition of market access. This regulatory tightening accelerates investment in autonomous maneuvering systems and end-of-life disposal propulsion. Smallsat operators face the steepest compliance burden, driving consolidation toward integrated launch-and-satellite service bundles.
Payload aggregators are unbundling the traditional prime contractor model, allowing satellite operators to contract directly with launch providers while purchasing integration services separately. This channel disintermediation compresses margin capture by legacy aerospace integrators. The pattern is most visible in commercial remote sensing, where operators now source launch, insurance, and ground segment independently.
US Space Launch Services Market Segmentation
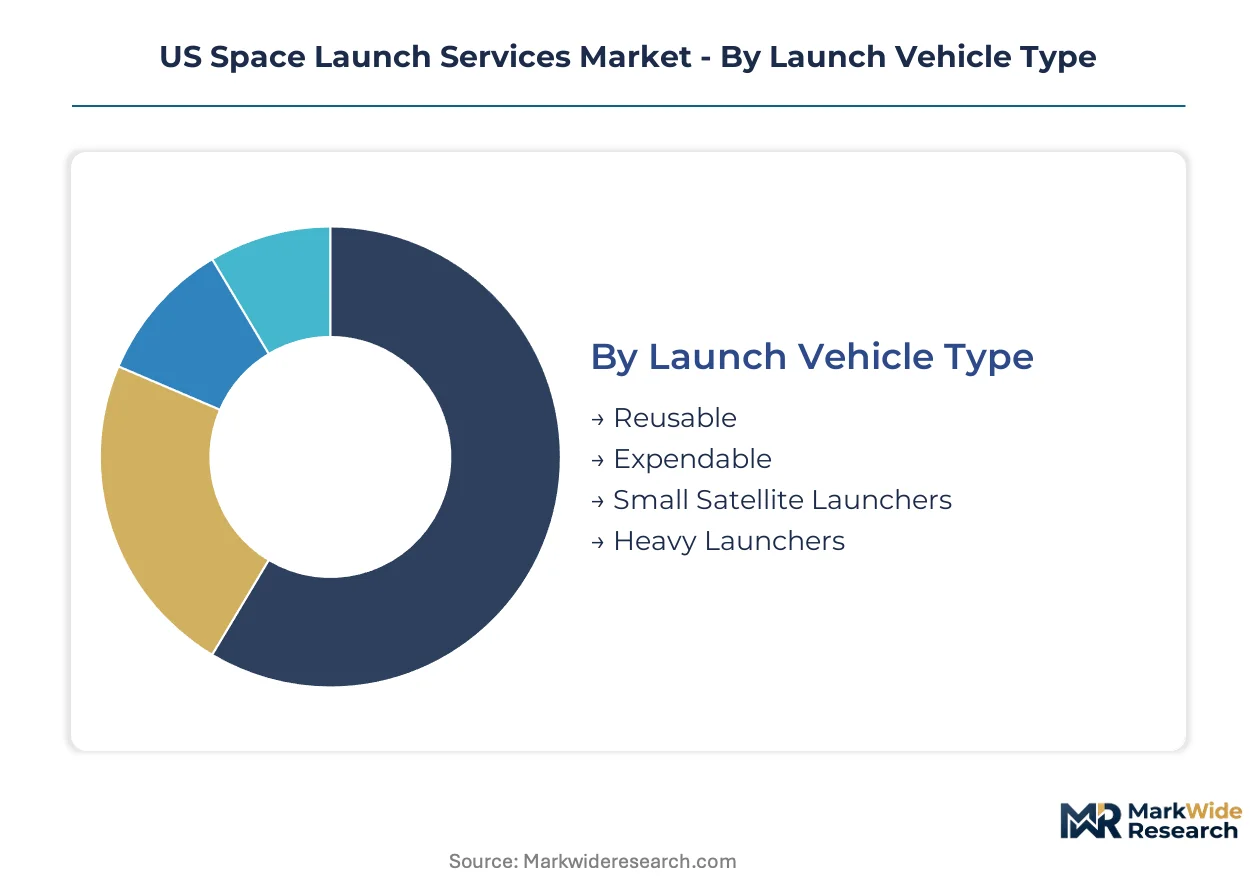
Launch vehicle classification determines regulatory pathways, insurance requirements, and payload integration protocols across the US orbital services landscape. Segment boundaries reflect how FAA Part 450 licensing, NASA safety standards, and USSF mission assurance criteria create distinct operational envelopes for each category.
Launch Vehicle Type:
FAA Part 450 streamlines licensing differently based on vehicle reusability and payload mass thresholds, creating tiered approval timelines that favor rapid-turnaround architectures.
- Reusable:Propulsion systems designed for multiple flight cycles with post-landing refurbishment protocols. Texas and Florida launch corridors concentrate demand as SpaceX and Blue Origin compress turnaround intervals below 60 days through rapid engine inspection regimes.
- Heavy Launchers:Vehicles rated for 20,000+ kg to low Earth orbit, commanding premium pricing for national security and interplanetary missions. USSF Phase 3 certification requirements anchor procurement at Cape Canaveral and Vandenberg, with schedule certainty outweighing cost considerations for defense payloads.
- Expendable:Single-use architectures retaining niche roles for high-energy orbits where reuse economics fail.
- Small Satellite Launchers:Dedicated vehicles for under 500 kg payloads facing structural pressure from heavy-lift rideshare alternatives.
Established volume favors Heavy Launchers; emerging adoption favors Reusable architectures.
End User:
Customer type dictates contract structures, from cost-plus government procurement to fixed-price commercial arrangements with divergent risk allocation.
- Government:NASA and USSF payloads prioritizing mission assurance over unit economics. National Security Space Launch Phase 3 mandates domestic launch capacity, concentrating procurement among certified heavy-lift providers with proven flight histories.
- Commercial:Satellite operators and telecommunications constellations optimizing for cost-per-kilogram to specific orbital planes. Payload aggregators now enable direct launch provider contracting, disintermediating legacy aerospace integrators in remote sensing and broadband deployment.
- International Space Agencies:Foreign government missions seeking US launch capacity for reliability or orbit access unavailable domestically.
- Academic Institutions:University research payloads and educational CubeSat programs accessing rideshare opportunities.
Government contracts anchor near-term revenue stability; commercial procurement expands most quickly as constellation deployment accelerates.
Service Type:
Service configuration determines margin capture, with dedicated launches commanding premiums against rideshare commoditization.
- Dedicated Launch Services:Exclusive vehicle allocation for single-payload missions with precise schedule and orbital requirements. Government and defense customers absorb premium pricing for priority pad access and customized integration timelines.
- Rideshare Launches:Multiple payloads co-manifested to common orbital destinations, compressing per-unit costs through volume aggregation. FCC spectrum licensing for mega-constellations drives demand as debris mitigation requirements favor integrated launch-and-satellite service bundles.
- Test Launches:Demonstration and qualification flights for new vehicle certification or payload validation.
- Cargo Delivery:Resupply missions to orbital platforms and future commercial space stations.
Margin concentration favors Dedicated Launch Services; volume scaling favors Rideshare Launches.
Application:
Orbital destination and mission profile shape vehicle selection, from low Earth orbit broadband deployment to translunar injection requirements.
- Satellite Deployment:Commercial communications, earth observation, and navigation constellation insertion. FCC mandates on debris mitigation and collision avoidance accelerate investment in autonomous maneuvering systems for post-deployment operations.
- Human Spaceflight:Crew transport to orbital platforms with NASA Commercial Crew safety standards imposing 300+ verification requirements. Human-rating certification complexity extends development timelines and limits qualified provider pools.
- Scientific Research:Instrumented payloads for atmospheric, astronomical, and microgravity investigations.
- Space Exploration:Interplanetary probes and lunar logistics missions requiring high-energy trajectories and extended coast phases.
Current revenue concentration favors Satellite Deployment; steepest expansion trajectory favors Space Exploration as Artemis logistics contracts materialize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orbital launch capacity clusters along coastal corridors where FAA licensing, weather patterns, and payload demand intersect. Texas and Florida anchor national heavy-lift operations, while California retains specialized polar orbit access.
Texas
Boca Chica and McGregor anchor the state's launch infrastructure, with SpaceX driving rapid engine refurbishment cycles below 60 days. FAA Part 450 streamlining accelerates pad turnover rates along the Gulf Coast. The Rio Grande Valley concentration is absorbing propulsion engineering talent from aerospace programs at Texas A&M and UT Austin.
Florida
Cape Canaveral Space Force Station and Kennedy Space Center host USSF Phase 3 certified heavy-lift operations for national security missions. NASA's Artemis logistics contracts concentrate procurement among proven flight-history providers. The Space Coast cluster faces hurricane-driven schedule vulnerability, with over 80% of eastern range capacity exposed to seasonal weather disruption.
California
Vandenberg Space Force Base offers underutilized sun-synchronous orbit capacity for earth observation constellations. NEPA litigation exposure extends pad modification timelines, creating regulatory friction distinct from FAA licensing efficiency gains. The Central Coast corridor attracts polar orbit demand from commercial remote sensing operators.
Alabama
Huntsville's propulsion manufacturing base supplies engine components for heavy-lift vehicles, with Blue Origin's BE-4 production anchoring regional aerospace employment. NASA Marshall Space Flight Center's safety standards influence human-rating certification protocols. The Tennessee Valley concentration specializes in combustion chamber alloys and turbopump assembly.
Colorado
Denver-Boulder anchors satellite operator headquarters and mission control infrastructure for constellation deployment. FCC spectrum licensing mandates from Washington shape debris mitigation investment decisions. The Front Range cluster concentrates payload integration expertise and ground segment engineering for rideshare missions.
US Space Launch Services Market Competitive Landscape
Concentration sits with vertically integrated heavy-lift developers and heritage defense contractors. The market structure tiers across rapid-reuse innovators, certified national security providers, and emerging small-launch specialists. Strategic archetypes include propulsion-integrated platform builders, government-assured access incumbents, and rideshare aggregators. Dominant competitive moves encompass engine manufacturing scale-up and launch site capacity expansion.
Within the heritage defense tier, Northrop Grumman and Lockheed Martin occupy positions shaped by decades of national security mission execution. SpaceX exemplifies the rapid-reuse archetype through its Starship development program and compressed refurbishment protocols. United Launch Alliance represents the certified-access model, anchoring USSF Phase 3 procurement with proven flight histories. Blue Origin sits within the integrated-propulsion category via its New Glenn architecture and BE-4 engine manufacturing scale.
| Leading Market Players |
|---|
| Northrop Grumman |
| Relativity Space |
| SpaceX |
| Lockheed Martin |
| Firefly Aerospace |
| Blue Origin |
| Rocket Lab |
| Intuitive Machines |
| United Launch Alliance |
| Others |
Pricing and Supply Chain Analysis
Stainless steel alloy construction displacing carbon fiber composites in cryogenic tank manufacturing simultaneously shifts propulsion component sourcing toward domestic steel corridors and compresses per-kilogram structural costs below legacy composite economics.
Pricing Analysis
FAA Part 450 dictates the pricing tier structure across launch service procurement. Three-tier pricing structure across premium, standard, and economy levels separates dedicated national security missions from rideshare commercial payloads and test demonstration flights. Cost compression in rideshare tiers is intensifying because heavy-lift surplus capacity absorbs formerly fragmented small-satellite demand. Commercial satellite operators exhibit highest price sensitivity; government mission assurance requirements render defense payloads least responsive to unit cost variation.
Supply Chain Analysis
Alabama, Texas, and Florida anchor propulsion manufacturing and final assembly operations. Inconel and titanium alloys for combustion chambers draw from a narrow qualified supplier base concentrated in the Tennessee Valley and Gulf Coast regions. Single-source vulnerability for specialized alloy feedstock constrains production scaling during demand surges. Distribution runs through vertically integrated launch providers controlling engine production, vehicle integration, and pad operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US orbital services market rewards concentrated expertise in full-flow staged combustion engineering and rapid refurbishment protocols, with qualified talent pools limiting how quickly new capacity can enter production.
For Market Incumbents: Compound certification advantages by accelerating human-rating verification investments ahead of NASA Commercial Crew expansion, while capturing BE-4 and Raptor engine manufacturing scale to lock in propulsion supply security against emerging reusable competitors. For New Entrants and Emerging Players: Lead with Vandenberg polar corridor specialization for sun-synchronous earth observation constellations, where underutilized capacity and NEPA litigation delays at legacy pads create service gaps for dedicated small-launch providers with streamlined environmental compliance. For Investors and Strategic Acquirers: The market sits at a heavy-lift consolidation phase that favors vertically integrated platform developers with captive engine production and proven flight histories. Five-to-ten year viability hinges on Artemis logistics contract capture and USSF Phase 3 certification maintenance. Acquisition targets should demonstrate rapid refurbishment protocols below sixty-day turnaround cycles. The signal to watch is FCC spectrum licensing velocity for mega-constellations, which dictates rideshare demand absorption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Engine Manufacturing Scale-Up | Captive BE-4 and Raptor production secures supply chain independence from specialized alloy bottlenecks. |
| Polar Corridor Infrastructure Investment | Vandenberg expansion captures sun-synchronous demand from commercial remote sensing operators. |
| Human-Rating Certification Acceleration | NASA Commercial Crew verification opens crew transport margins above cargo-only economics. |
| Refurbishment Protocol Standardization | Sixty-day engine turnaround cycles displace expendable alternatives in commercial satellite deployment. |
| Debris Mitigation Technology Integration | FCC-mandated collision avoidance capabilities create bundled launch-and-satellite service premiums. |
Research Methodology
A standing panel of propulsion engineering directors, FAA licensing officers, USSF procurement leads, and satellite operator mission managers provided ongoing calibration across primary fieldwork and secondary validation. FCC spectrum licensing databases, FAA Part 450 approval records, NASA contract award announcements, and USSF budget justification documents supplied triangulation anchors. Bottom-up segment modeling and top-down macroeconomic cross-checks converged on volume and value estimates.
Consistency checks against external benchmarks validated projections across the analysis window. Modeled dimensions spanned launch vehicle reusability class, end-user procurement type, service configuration, and orbital destination application. CAGRs derived from segment-level growth trajectory aggregation and elasticity-adjusted demand curve fitting. Industry-specific inputs included Artemis logistics contract award timing and mega-constellation deployment schedules.
The analysis sits within stated boundaries; outcomes outside sustained government payload demand or FAA streamlining continuity would require recalibration. Forecasts reflect documented assumptions regarding propulsion refurbishment cycle achievement and specialized alloy supply stability. Recalibration cycles align with material shifts in National Security Space Launch procurement phases and FCC spectrum licensing velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Technology (Spacetech) Market
Space
Space-Based Smart Sensors Market
Space
Asteroid Mining Market
Space
US Space Electronics Market
Space
France Space Electronics Market
Space
North America Spacesuit Market
Space
Space Transportation Market
Space
Space in Orbit Refueling Market
Space
UK Space Electronics Market
Space
LAMEA Space As a Service Market
Space
Space Mining Market
Space
Space Sensors Market
Space
Space-Based C4ISR Market
Space
Africa Space Propulsion System Market
Space
Italy Space Electronics Market
Space
Space Frame Market