
 Africa Space Electronics Market | 2026-2036
Africa Space Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Space Electronics Market Analytics
ISO 19683 qualification for space-grade electronic components is redrawing competitive boundaries across the continent. Astrofica Technologies leverages its Addis Ababa engineering base to sustain satellite subsystem development for regional operators. African Geospace anchors downstream service contracts with government earth observation programs in East Africa.
Africa space electronics encompasses radiation-hardened semiconductors, RF subsystems, and power management units engineered for orbital and ground station deployment, typically manufactured to withstand total ionizing dose thresholds above 100 krad(Si) and operating temperatures from -55°C to +125°C. Satellite Components dominates product-level revenue as launch manifests from African states multiply, while Software Defined Radio technology is gaining structural share by enabling multi-band communication payloads without hardware swaps. Earth Observation applications concentrate margin pools through long-term service contracts tied to agricultural monitoring and maritime surveillance.
South Africa's National Regulator for Compulsory Specifications enforces local content thresholds on public space procurements, while Nigeria's National Space Research and Development Agency sets technical standards for satellite subsystem acceptance. ISO 19683 and ITU-R radio regulations jointly constrain which suppliers qualify for national programs, filtering market access toward certified manufacturers. Stakeholders must track how evolving national space legislation across additional African states redefines certification requirements and procurement eligibility before committing regional expansion capital.
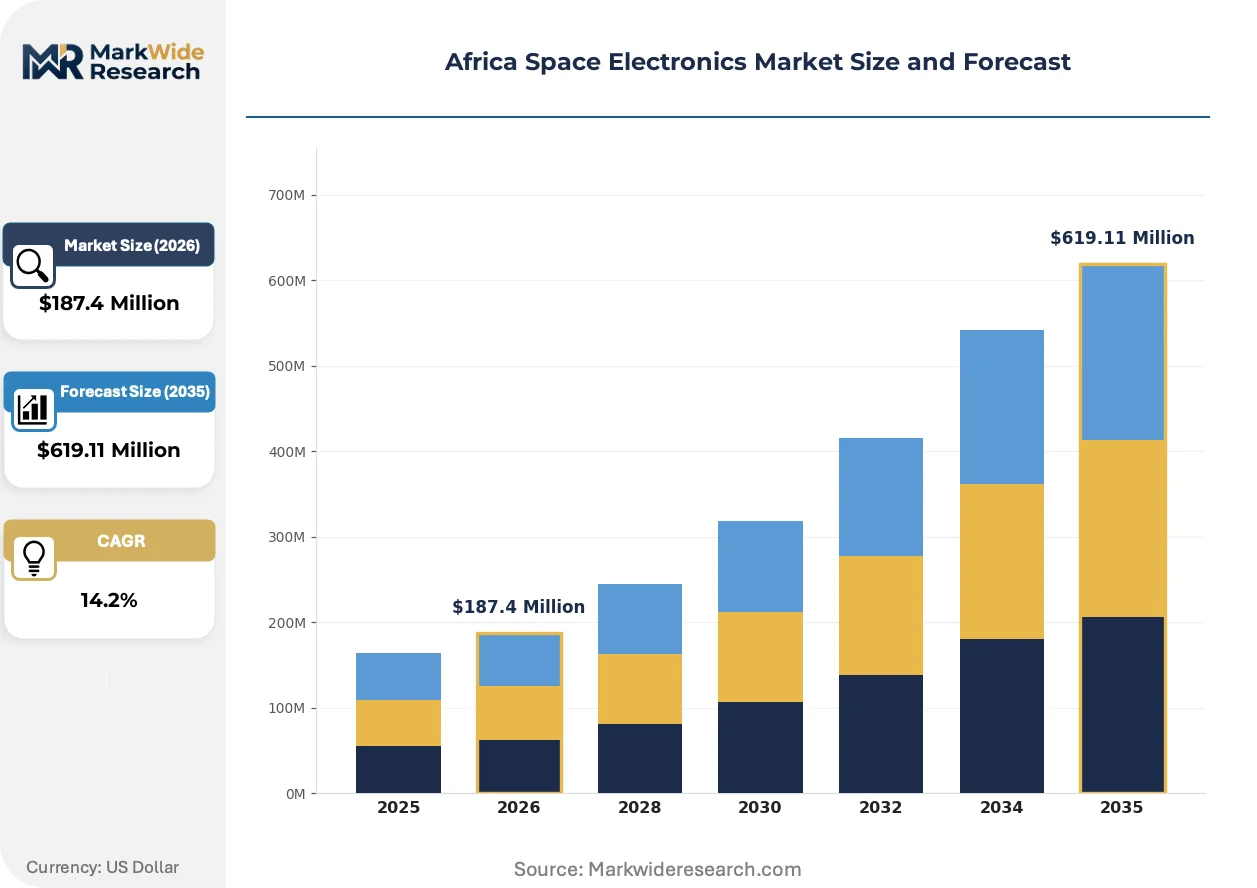
Market Dynamics
ISO 19683 qualification requirements are redrawing competitive boundaries across Africa's space electronics sector, filtering market access toward certified manufacturers while national space legislation in Nigeria and South Africa creates formal procurement pathways for domestic suppliers.
Growth Catalysts
- National Space Legislation:Nigeria's National Space Research and Development Agency and South Africa's space framework establish formal procurement pathways that prioritize domestic electronics suppliers for satellite subsystem contracts.
- Earth Observation Demand:Agricultural ministries across the continent are expanding satellite-based monitoring programs, creating sustained pull for radiation-hardened imaging payloads and data processing units.
- Software Defined Radio:This technology enables multi-band communication payloads without hardware swaps, reducing satellite mass and extending operational lifespans for regional operators.
Market Restraints
- Input Cost Volatility:Specialty substrates for radiation-hardened semiconductors face concentrated supply from North American and European foundries, exposing African assemblers to currency fluctuation risks.
- Technical Limitation:Total ionizing dose thresholds above 100 krad(Si) require imported testing infrastructure, as no African facility currently operates comprehensive radiation qualification labs.
- Regulatory Friction:ITU-R radio regulations create multi-year coordination timelines for frequency assignments, delaying payload integration and launch scheduling for new satellite operators.
Strategic Opportunities
- Underpenetrated Geography:Ethiopia's emerging space program and Kenya's satellite development initiatives present first-mover opportunities for subsystem suppliers establishing East African engineering presence.
- Regulatory Tailwind:South Africa's National Regulator for Compulsory Specifications enforces local content thresholds on public space procurements, mandating minimum domestic value-add in electronics sourcing.
- Technology Convergence:Integration of artificial intelligence with onboard satellite processing is opening demand for edge-computing architectures that combine radiation-hardened CPUs with machine learning accelerators.
Industry Challenges
- Certification Timeline:ISO 19683 qualification processes extend 18-36 months for new component entrants, compressing window for technology refresh cycles and locking in incumbent supplier relationships.
- Talent Gap:Radiation effects engineering and space-grade PCB design expertise concentrates in South Africa's Western Cape corridor, limiting scaling capacity for programs in other African states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Space Electronics Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Satellite Components, Ground Station Equipment, Communication Systems, Power Systems End User: Government Agencies, Research Institutions, Commercial Enterprises, NGOs Technology: Microelectronics, Software Defined Radio, Propulsion Systems, Antenna Systems Application: Earth Observation, Communication, Scientific Research, Navigation |
| Companies Covered | Astrofica Technologies, African Geospace, Angel Technology (ANGETEC), LocateIT Limited, Panafric Space, Eureka Geo, BigData Ghana Ltd, RADA 360 LIMITED, Robocare, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Space Electronics Market Evolving Landscape
Three forces are actively reshaping Africa's space electronics landscape: component-level qualification standards are tightening, national procurement frameworks are favoring domestic suppliers, and satellite operators are demanding more flexible payload architectures.
Software Defined Radio technology is displacing traditional fixed-frequency RF subsystems in African satellite programs. Regional operators including agricultural monitoring consortia and maritime surveillance agencies are adopting SDR-based payloads to enable post-launch frequency reconfiguration. This flexibility is displacing hardware-swapped legacy designs and compressing procurement cycles for communication satellites.
South Africa's National Regulator for Compulsory Specifications has expanded local content mandates to space electronics procurement, requiring minimum domestic manufacturing value-add for public satellite contracts. This industrial policy redirects component sourcing toward certified domestic suppliers. Satellite subsystem integrators in the Western Cape corridor are responding by qualifying local PCB fabrication and assembly houses to meet these thresholds.
Public sector buyers are consolidating satellite service contracts into multi-year earth observation frameworks with embedded electronics refresh clauses. Agricultural ministries and maritime security agencies now specify performance outcomes rather than equipment specifications, transferring obsolescence risk to subsystem suppliers. This contracting evolution is most visible in Nigeria and Kenya, where national space agencies act as central procurement authorities for downstream government users.
Africa Space Electronics Market Segmentation
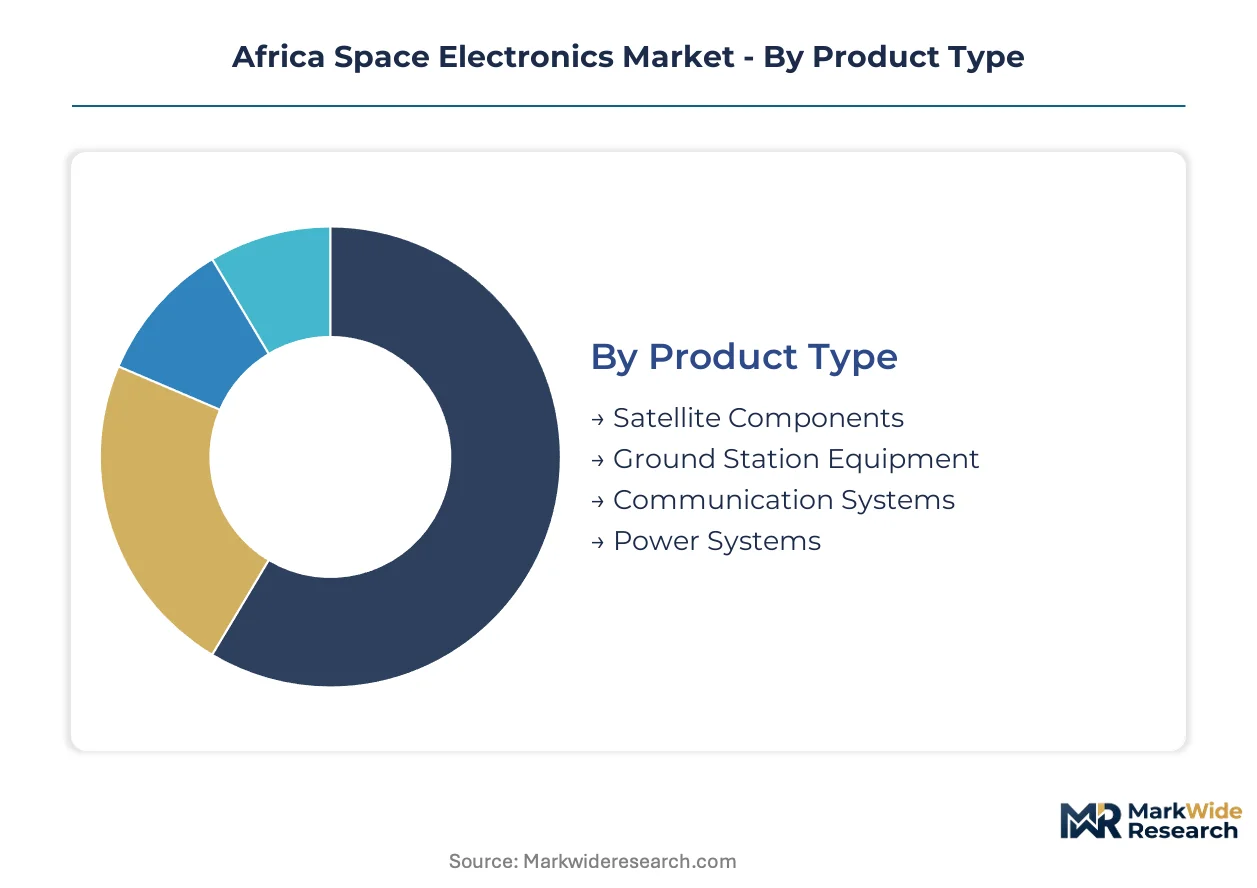
Segmentation reveals how procurement pathways and technical specifications diverge across African space programs. Understanding these divisions exposes where domestic manufacturing requirements intersect with imported subsystem dependencies.
Product Type:
Domestic production concentrates in ground station assemblies and power distribution units, while satellite components remain import-dependent due to radiation-hardening requirements.
- Satellite Components:Radiation-hardened semiconductors, RF subsystems, and imaging payloads engineered for total ionizing dose thresholds above 100 krad(Si). Demand clusters in South Africa's Western Cape corridor where SANSA anchors subsystem procurement for national programs.
- Ground Station Equipment:Antenna arrays, signal processing racks, and telemetry receivers assembled from imported RF modules. Nigeria's NASRDA procurement frameworks prioritize local integration of ground segment hardware.
- Communication Systems:Transponder chains and modems for satellite-to-ground links.
- Power Systems:Solar array regulators, battery management units, and DC-DC converters.
Satellite Components holds the largest share; momentum sits with Ground Station Equipment as local content mandates expand.
End User:
Cost tier segmentation separates capital-intensive government programs from constrained NGO budgets, with research institutions occupying a hybrid funding position.
- Government Agencies:National space agencies, defense ministries, and agricultural departments operating multi-year satellite service contracts. Nigeria's NASRDA and South Africa's SANSA dominate procurement volume through centralized earth observation frameworks.
- Research Institutions:University engineering departments and national laboratories developing CubeSat platforms. Stellenbosch University and Cairo University anchor academic demand for educational satellite subsystems.
- Commercial Enterprises:Regional telecom operators and agricultural analytics startups.
- NGOs:International development organizations deploying satellite connectivity for rural health and education programs.
Government Agencies holds the largest share; momentum sits with Research Institutions as university CubeSat programs multiply across the continent.
Technology:
Application focus varies by deployment phase—microelectronics dominate orbital hardware while Software Defined Radio enables flexible ground and payload architectures.
- Microelectronics:Radiation-hardened CPUs, FPGAs, and memory modules fabricated to MIL-STD-883 screening protocols. Ethiopian operators source these through Astrofica Technologies for regional satellite programs.
- Software Defined Radio:Reconfigurable RF platforms enabling multi-band communication without hardware swaps. Kenyan agricultural monitoring consortia adopt SDR payloads for post-launch frequency adaptation.
- Propulsion Systems:Electric thrusters and cold gas systems for station-keeping maneuvers.
- Antenna Systems:Phased arrays and deployable reflectors for high-gain communication links.
Microelectronics holds the largest share; Software Defined Radio gains share fastest as operators prioritize payload flexibility over fixed-frequency designs.
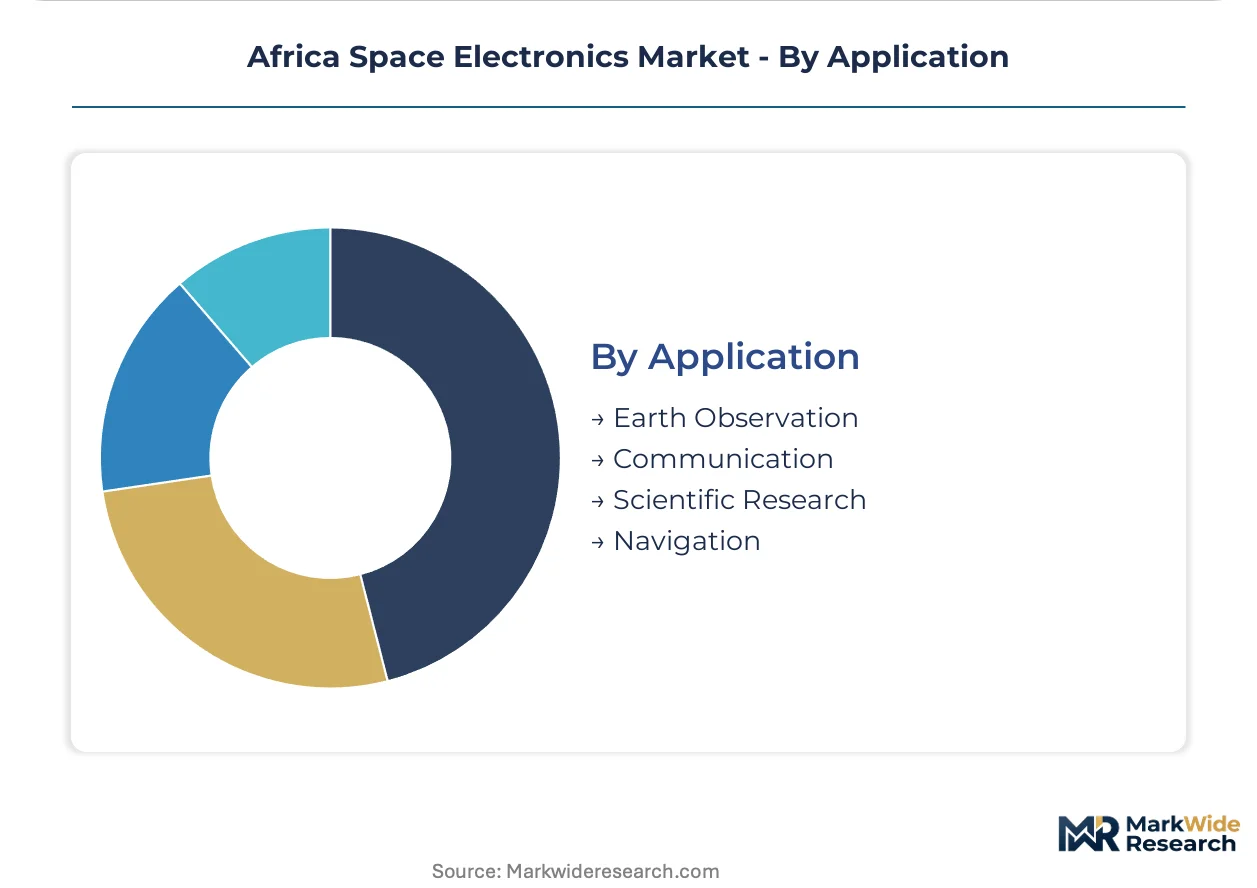
Application:
Customer type segmentation distinguishes program-driven scientific missions from commercially contracted earth observation services.
- Earth Observation:Multispectral and synthetic aperture radar payloads for agricultural monitoring, maritime surveillance, and urban planning. African Geospace anchors downstream contracts with East African government programs.
- Communication:Broadcast transponders and broadband connectivity payloads for regional telecom coverage. Maritime security agencies across West Africa drive demand for reliable satcom links.
- Scientific Research:Space weather sensors and astronomy platforms for ionospheric studies.
- Navigation:GNSS augmentation payloads and timing signal distribution systems.
Earth Observation holds the largest share; momentum sits with Communication as regional operators expand connectivity infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National space legislation across African states is redirecting procurement toward domestic electronics suppliers, creating geographically concentrated development corridors anchored by established space agencies and university research clusters.
South Africa
The South African National Space Agency drives subsystem procurement for earth observation and communication satellites, with the Western Cape corridor hosting concentrated engineering expertise. The National Regulator for Compulsory Specifications enforces local content thresholds on public space contracts, mandating minimum domestic value-add. Stellenbosch University and Cape Town-based research clusters anchor satellite subsystem development for regional programs.
Nigeria
The National Space Research and Development Agency operates centralized procurement frameworks for government earth observation services, creating formal pathways for domestic electronics suppliers. Technical standards for satellite subsystem acceptance filter market access toward certified manufacturers. Abuja and Lagos anchor the national space program with university engineering departments developing CubeSat platforms.
Ethiopia
Addis Ababa-based engineering operations support regional satellite subsystem development for earth observation and communication payloads. The emerging national space program presents first-mover opportunities for subsystem suppliers establishing East African presence. The capital's research institutions anchor educational satellite initiatives with growing demand for radiation-hardened component sourcing.
Kenya
Agricultural monitoring consortia and maritime surveillance agencies drive adoption of Software Defined Radio payloads for post-launch frequency adaptation. National satellite development initiatives create procurement channels for ground station equipment and communication subsystems. Nairobi anchors government earth observation programs with university CubeSat research expanding technical capacity.
Egypt
Cairo University engineering departments anchor academic demand for educational satellite subsystems and space-grade component research. The national space program supports indigenous satellite manufacturing with procurement frameworks prioritizing domestic integration capabilities. The Nile Delta corridor concentrates electronics assembly capacity serving regional space applications.
Africa Space Electronics Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with ISO 19683 qualification requirements filtering market access toward certified manufacturers. The vendor base organizes around three strategic archetypes: subsystem integrators with radiation-hardening partnerships, ground station specialists capturing local content mandates, and university spin-offs serving research institution procurement. Dominant competitive moves include strategic partnerships with international qualification labs and geographic expansion into underpenetrated East African markets.
Among Ethiopia-based engineering operations, Astrofica Technologies occupies a position within the subsystem integrator archetype, while African Geospace exemplifies the downstream service specialist model serving government earth observation programs across East Africa. Angel Technology represents the research-to-commercial pathway archetype with origins in academic satellite development.
| Leading Market Players |
|---|
| Astrofica Technologies |
| African Geospace |
| Angel Technology (ANGETEC) |
| LocateIT Limited |
| Panafric Space |
| Eureka Geo |
| BigData Ghana Ltd |
| RADA 360 LIMITED |
| Robocare |
| Others |
Value Network & Pricing Analysis
Long-term earth observation service contracts with embedded electronics refresh clauses lock in supply access for radiation-hardened components while providing price visibility across multi-year frameworks. South Africa's local content mandates and Nigeria's centralized procurement pathways create divergent pricing pressures for domestic versus import-dependent subsystem tiers.
Pricing Analysis
Certification level (ISO 19683-grade) creates the primary spread between qualified and unqualified component suppliers. Project-based pricing dominates government satellite contracts, while subscription frameworks emerge for downstream earth observation services. Price differentiation stems from radiation-hardening grade and domestic manufacturing value-add. Cost compression in ground station equipment is intensifying because local assembly houses compete for public contracts. Research institutions exhibit highest price sensitivity due to constrained CubeSat budgets, whereas government agencies prioritize qualification over unit cost.
Supply Chain Analysis
Strategic stockpiling of specialty substrates precedes qualification runs, as 18-36 month ISO 19683 timelines prevent just-in-time procurement for new entrants. Geographic supply concentration centers on North American and European foundries for radiation-hardened semiconductors, with South Africa and Egypt anchoring regional PCB fabrication. Raw material dependencies include silicon carbide substrates, gallium nitride wafers, and space-grade aluminum alloys. Single-source vulnerability persists for total ionizing dose testing infrastructure, as no African facility operates comprehensive radiation qualification labs. Distribution runs through national space agency procurement frameworks with mandated local content thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across national procurement frameworks creates niche opportunities for subsystem suppliers aligned with specific local content regimes. The shift toward Software Defined Radio payloads fragments demand across reconfigurable versus fixed-frequency architectures.
For Market Incumbents: Secure qualification partnerships with international radiation-testing facilities to maintain ISO 19683 certification validity. Lock in long-term substrate supply agreements with North American foundries before currency volatility escalates. Vertical integration into local PCB assembly addresses South Africa's domestic value-add mandates while defending against emerging Ethiopian subsystem integrators. For New Entrants and Emerging Players: Lead with Software Defined Radio payload development for Kenyan agricultural monitoring consortia seeking post-launch frequency flexibility. Target Ethiopia's emerging space program before qualification requirements formalize. Establish engineering presence in Addis Ababa or Nairobi to capture first-mover advantage in East African ground station deployment. For Investors and Strategic Acquirers: University spin-offs with CubeSat heritage and existing SANSA or NASRDA contract relationships represent prime acquisition targets. Long-term viability hinges on positioning within national procurement frameworks rather than pure technology differentiation. Watch for ISO 19683 qualification timeline compression as the inflection signal for supplier consolidation. Revision becomes warranted when local content threshold enforcement crosses 40% domestic value-add.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 19683 Qualification Partnership | Unlocks access to Nigeria's NASRDA and South Africa's SANSA procurement frameworks. |
| Software Defined Radio Platform Launch | Captures Kenyan agricultural consortia seeking payload reconfiguration without hardware swaps. |
| Local Content Compliance Investment | Satisfies South Africa's National Regulator for Compulsory Specifications domestic value-add mandates. |
| East African Engineering Expansion | Positions suppliers for Ethiopia's emerging space program and Kenya's satellite initiatives. |
| Radiation-Testing Infrastructure Joint Venture | Addresses Africa's absence of comprehensive total ionizing dose qualification facilities. |
Research Methodology
Desk research of satellite procurement databases, national space legislation filings, and ITU-R frequency coordination records preceded structured interviews with SANSA procurement officers, NASRDA technical standards leads, subsystem engineering directors at Stellenbosch University, and agricultural ministry remote sensing coordinators. Secondary validation drew from ISO certification registries, customs import data for radiation-hardened components, and university CubeSat program disclosures. Bottom-up component demand modeling and top-down national budget allocation analysis were triangulated against launch manifest projections.
Variance decomposition across product type, end user, technology, and application dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented demand buildup reconciled with national space program budget trajectories. Modeled dimensions included radiation-hardening grade tiers, government versus research institution procurement pathways, fixed versus reconfigurable payload architectures, and regional regulatory cluster alignment. Forecast inputs incorporated Software Defined Radio adoption curves and local content mandate enforcement intensity.
Forecasts assume regulatory continuity in South Africa's National Regulator for Compulsory Specifications regime and Nigeria's NASRDA technical standards framework; material policy shifts would require re-modeling procurement eligibility and domestic value-add thresholds. Forecasts reflect assumptions regarding ISO 19683 qualification timeline stability, substrate supply chain continuity from North American foundries, and ITU-R frequency coordination procedural consistency. Revision becomes warranted when local content enforcement intensity or radiation-testing infrastructure localization crosses material thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Europe Space Electronics Market
Space
Space Technology (Spacetech) Market
Space
Private Space Travel Market
Space
Space Mining Market
Space
Space Sensors Market
Space
Space Transportation Market
Space
Space Tourism Market
Space
Space in Orbit Refueling Market
Space
Suborbital Space Tourism Market
Space
US Space Electronics Market
Space
Space Oscillator Market
Space
US Space Launch Services Market
Space
Africa Space Propulsion System Market
Space
Space Debris Monitoring Market
Space
Space Propulsion Systems Market
Space
Space Radar Market