
 Military Phased Array Antenna Market | 2026-2036
Military Phased Array Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Military Phased Array Antenna Market Insights
Naval surface combatant modernization is shifting procurement priority toward multi-function phased array suites capable of simultaneous air defense and ballistic missile tracking. Lockheed Martin leverages its Aegis combat system integration heritage to anchor naval contracts across multiple allied fleets. Raytheon Technologies competes through gallium nitride foundry investments that sustain higher power density than legacy alternatives.
A military phased array antenna is an antenna system composed of multiple radiating elements whose relative phases are electronically controlled to steer the beam direction without mechanical movement, typically operating across microwave and millimeter-wave bands with beam switching times under microseconds. Its primary purpose is to enable rapid target acquisition, track multiple threats simultaneously, and support electronic countermeasures in contested electromagnetic environments. Active Electronically Scanned Array architectures now dominate new procurement owing to their fault tolerance and simultaneous multi-mode operation, while Gallium Nitride technology captures expanding share as thermal performance requirements intensify for next-generation radar systems. Digital Phased Array designs represent the fastest-growing product category as software-defined beamforming enables post-deployment capability upgrades without hardware replacement.
FCC spectrum allocations and ITU-R coordination frameworks shape transmit frequency bands and cross-border electromagnetic compatibility requirements for deployed systems. NATO Standardization Office and national defense acquisition regulations in the United States, the United Kingdom, and Israel mandate interoperability standards that constrain vendor selection to qualified suppliers with certified manufacturing traceability. Stakeholders must monitor gallium nitride substrate supply concentration and sovereign foundry investments as these factors determine which contractors can meet accelerated procurement timelines for integrated air and missile defense programs.

Market Dynamics
Gallium nitride transistor technology is compressing procurement timelines for active electronically scanned array systems as NATO allies accelerate integrated air and missile defense modernization. Foundry capacity concentration in sovereign semiconductor facilities is creating supply-side bottlenecks that reshape contractor qualification requirements.
Growth Catalysts
- Integrated Air and Missile Defense Procurement:NATO Standardization Office interoperability mandates require simultaneous multi-mode radar capabilities across allied fleets. Naval surface combatants and airborne early warning platforms drive active electronically scanned array adoption.
- FCC Spectrum Allocations:Microwave and millimeter-wave band designations enable higher transmit power densities for next-generation radar systems. ITU-R coordination frameworks facilitate cross-border electromagnetic compatibility for deployed assets.
- Gallium Nitride Thermal Performance:Power density advantages over legacy gallium arsenide architectures satisfy intensifying thermal requirements for naval and airborne platforms. Foundry investments in the United States and Israel anchor supply security.
Market Restraints
- Gallium Nitride Substrate Supply Concentration:Limited qualified foundry capacity constrains accelerated production scaling for defense procurement programs. Sovereign semiconductor investments in the United States and United Kingdom partially mitigate this structural bottleneck.
- Certified Manufacturing Traceability Requirements:National defense acquisition regulations mandate vendor qualification to stringent interoperability standards. Small and mid-tier suppliers face exclusion from prime contractor supply chains.
- Digital Phased Array Development Costs:Software-defined beamforming architectures require substantial upfront engineering investment. Post-deployment upgrade pathways demand sustained software maintenance commitments.
Strategic Opportunities
- Israeli Defense Export Expansion:Israeli integrated air and missile defense networks demonstrate operational validation of gallium nitride-based active electronically scanned arrays. Export-oriented partnerships with European and Asia-Pacific navies create white space.
- Digital Phased Array Convergence:Software-defined radio architectures merge with solid-state radar transmit-receive modules. This technology pairing enables post-deployment capability insertion without hardware replacement cycles.
- United Kingdom Sovereign Foundry Incentives:National semiconductor capability investments reduce import dependency for critical gallium nitride substrates. Domestic sourcing mandates strengthen qualified supplier positions.
Industry Challenges
- Radio Frequency Engineering Talent Scarcity:Specialized microwave and millimeter-wave design expertise concentrates in legacy defense contractors. Startups and mid-tier suppliers struggle to recruit experienced phased array architects.
- Legacy Combat System Integration Complexity:Aegis combat system heritage creates path dependency for naval procurement decisions. New entrants face technical barriers to achieving qualified subsystem status.
- ITU-R Coordination Timeline Compression:Cross-border electromagnetic compatibility negotiations extend deployment schedules for multinational allied operations. Accelerated procurement programs strain regulatory clearance capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Phased Array Antenna Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.6 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Electronically Scanned Array, Passive Electronically Scanned Array, Digital Phased Array, Hybrid Phased Array, Wideband Phased Array Technology: Gallium Nitride, Gallium Arsenide, Silicon Germanium, RF MEMS, MMIC Application: Radar Systems, Electronic Warfare, Surveillance, Command & Control, Target Tracking End User: Defense Forces, Defense Contractors, Aerospace Manufacturers, National Security Agencies, Research Institutions |
| Companies Covered | Thales Group, Lockheed Martin, Northrop Grumman, SAAB, Leonardo, Raytheon Technologies, L3Harris Technologies, Elbit Systems, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Phased Array Antenna Market Trends and Innovations
Beam-steering architectures are converging with software-defined processing to enable post-deployment capability evolution without hardware obsolescence. This structural shift compresses replacement cycles and redirects contractor investment toward firmware sustainment.
Gallium nitride high-electron-mobility transistors are electrifying power amplifier performance in active electronically scanned array transmit-receive modules. Naval surface combatant programs in the United States and United Kingdom are adopting these devices at accelerated procurement tempos. Higher thermal tolerance is electrifying simultaneous multi-mode operation previously unattainable under gallium arsenide thermal constraints.
REACH substance restrictions and EU defense procurement directives are tightening material traceability and cross-border transfer compliance for radar subsystem suppliers. Industrial consequence includes mandatory supply chain documentation for gallium nitride substrate provenance. European naval modernization programs are responding with qualified vendor consolidation to simplify certification burden.
Defense procurement offices are consolidating prime contractor relationships to reduce subsystem integration risk on complex phased array programs. Traditional component supply channels face disintermediation as platform integrators assume direct module sourcing responsibility. This pattern is most visible in United States Navy integrated air and missile defense contracts where Lockheed Martin and Raytheon Technologies anchor multi-year production agreements.
Military Phased Array Antenna Market Segmentation
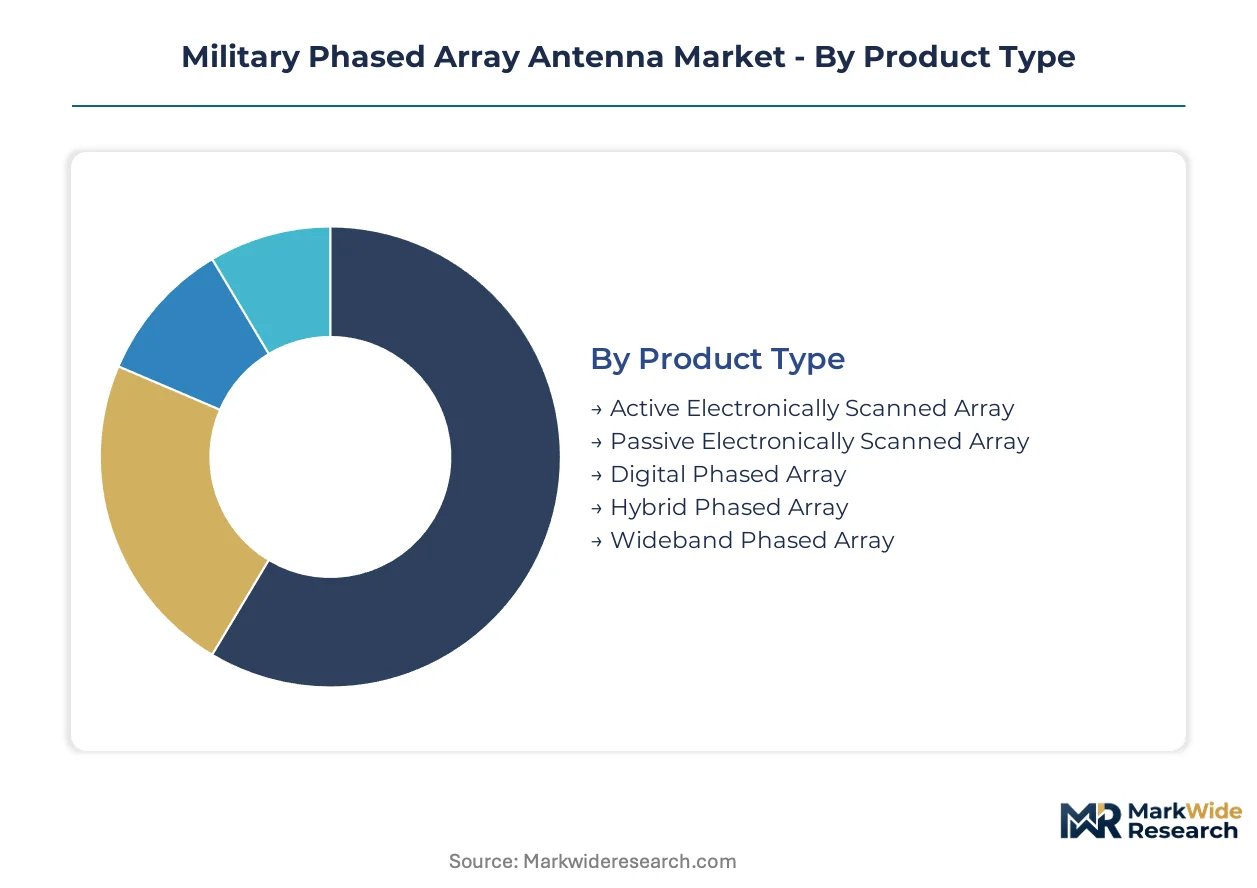
Military phased array antenna procurement decisions pivot on subsystem interoperability, thermal performance thresholds, and sovereign manufacturing traceability. Segment boundaries reflect competing pressures between legacy platform integration requirements and next-generation capability insertion pathways.
Product Type:
Supply concentration for transmit-receive module foundries shapes competitive positioning across product architectures, with qualified vendor pools determining which designs achieve production scale.
- Active Electronically Scanned Array:Solid-state transmit-receive modules at each radiating element enable electronic beam steering with microsecond switching speeds. United States Navy surface combatant modernization concentrates procurement here, driven by NATO Standardization Office interoperability mandates for simultaneous multi-mode operation.
- Digital Phased Array:Software-defined beamforming replaces analog phase shifters with digital processing at each element, enabling post-deployment algorithm upgrades without hardware replacement. Defense procurement offices in Israel and the United Kingdom prioritize this architecture for integrated air and missile defense network modernization.
- Passive Electronically Scanned Array:Centralized transmitter with phase-controlled radiating elements offers lower cost for legacy platform retrofits.
- Hybrid Phased Array:Combines analog and digital beamforming stages to balance cost against capability in mid-tier surveillance applications.
- Wideband Phased Array:Frequency-agile architectures spanning multiple radar bands support electronic countermeasure missions.
Today's leader: Active Electronically Scanned Array. Tomorrow's challenger: Digital Phased Array.
Technology:
Foundry capacity allocation across compound semiconductor substrates determines which technology nodes achieve defense qualification status and production volume.
- Gallium Nitride:High-electron-mobility transistors deliver power densities exceeding legacy alternatives by substantial margins, with thermal tolerance enabling simultaneous multi-mode radar operation. United States and Israeli sovereign foundry investments anchor supply security for naval and airborne early warning platforms.
- Gallium Arsenide:Mature fabrication processes and established reliability data sustain procurement for legacy system sustainment and cost-constrained programs.
- Silicon Germanium:BiCMOS integration enables low-cost receive chains in distributed sensor networks.
- RF MEMS:Microelectromechanical phase shifters offer low-loss analog beam steering for specific electronic warfare applications.
- MMIC:Monolithic microwave integrated circuits consolidate multifunction RF front-ends for space-constrained platforms.
Gallium Nitride commands prime contractor attention. Silicon Germanium expands fastest in peripheral sensor applications.
Application:
Platform integration complexity and combat system heritage requirements segment demand by mission-critical performance thresholds.
- Radar Systems:Multi-function phased array suites for air defense and ballistic missile tracking dominate procurement volume. Naval surface combatant programs in the United States and United Kingdom specify active electronically scanned array architectures with gallium nitride power amplifiers.
- Electronic Warfare:Direction-finding and jamming systems require rapid beam nulling and spatial filtering capabilities. Israeli defense exports demonstrate operational validation of wideband phased arrays in contested electromagnetic environments.
- Surveillance:Persistent wide-area coverage drives demand for digital beamforming and software-defined processing.
- Command & Control:Communications arrays prioritize reliability and interoperability over raw performance.
- Target Tracking:Fire control radars demand precision angle measurement and low-latency track updates.
Radar Systems absorbs the largest procurement budgets. Electronic Warfare shows the steepest expansion trajectory as spectrum contestation intensifies.
End User:
Defense acquisition regulations and certified manufacturing traceability requirements stratify vendor access by customer tier.
- Defense Forces:National military services specify platform-integrated phased array suites through prime contractor relationships. United States Navy integrated air and missile defense contracts consolidate around Lockheed Martin Aegis combat system integration and Raytheon Technologies gallium nitride foundry supply.
- Defense Contractors:Subsystem suppliers and platform integrators procure transmit-receive modules and beamforming networks for incorporation into larger systems.
- Aerospace Manufacturers:Airframe primes source radar apertures and electronic warfare suites for airborne early warning and fighter platforms.
- National Security Agencies:Intelligence community procurement emphasizes specialized surveillance and signals intelligence applications.
- Research Institutions:Laboratory development contracts support technology maturation prior to defense qualification.
Defense Forces set technical specifications that cascade through supply chains. Defense Contractors face tightening qualification barriers as prime consolidation accelerates.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics favor production migration toward jurisdictions with streamlined defense export controls and sovereign foundry incentives. The United States, United Kingdom, Israel, Germany, and Japan concentrate procurement authority and manufacturing capability for gallium nitride-based active electronically scanned array systems.
United States
Integrated air and missile defense modernization drives naval surface combatant and airborne early warning procurement. FCC spectrum allocations and ITU-R coordination frameworks shape cross-border electromagnetic compatibility requirements. Texas and Arizona host sovereign gallium nitride foundry investments that anchor supply security for prime contractor production timelines.
United Kingdom
National semiconductor capability investments reduce import dependency for critical substrate sourcing. EU defense procurement directives and REACH substance restrictions tighten material traceability compliance for radar subsystem suppliers. Scotland and South West England concentrate qualified vendor consolidation for naval modernization programs.
Israel
Operational validation of gallium nitride-based architectures in contested electromagnetic environments supports defense export expansion. Israeli defense acquisition regulations mandate interoperability standards that constrain vendor selection. Haifa and Tel Aviv metropolitan clusters anchor export-oriented partnerships with European and Asia-Pacific navies.
Germany
Airborne early warning platform modernization and electronic warfare capability gaps drive active electronically scanned array adoption. ECHA regulatory frameworks and EU defense procurement directives shape cross-border transfer compliance. Bavaria and Baden-Württemberg host aerospace-defense industrial clusters with established radar subsystem integration heritage.
Japan
Maritime patrol aircraft and surface combatant radar upgrades prioritize simultaneous multi-mode operation. METI industrial policy and JIS standards govern defense technology transfer and manufacturing traceability. Nagoya and Tokyo-Yokohama metropolitan areas concentrate precision manufacturing capability for transmit-receive module assembly.
Military Phased Array Antenna Market Competitive Landscape
Prime contractor consolidation dominates the current landscape as defense procurement offices reduce subsystem integration risk on complex phased array programs. The vendor base stratifies between platform integrators with combat system heritage and compound semiconductor foundry operators with sovereign supply security. Three archetypes prevail: Aegis-heritage naval integrators, gallium nitride foundry specialists, and Israeli defense exporters with operational validation credentials. M&A activity and sovereign foundry investments represent the dominant competitive moves reshaping qualification requirements.
Within the platform-integrator tier, Lockheed Martin and Raytheon Technologies exemplify contrasting strategic positions. Lockheed Martin occupies a position anchored by Aegis combat system integration heritage across multiple allied fleets. Raytheon Technologies sits within the compound semiconductor supply security archetype through gallium nitride foundry investments. Elbit Systems represents the Israeli defense export expansion model with demonstrated operational validation in integrated air and missile defense networks.
| Leading Market Players |
|---|
| Thales Group |
| Lockheed Martin |
| Northrop Grumman |
| SAAB |
| Leonardo |
| Raytheon Technologies |
| L3Harris Technologies |
| Elbit Systems |
| BAE Systems |
| Others |
Pricing and Supply Chain Analysis
RF engineering talent concentration in the United States and Israel widens labor-cost differentials between legacy defense hubs and emerging supply zones, compressing pricing-tier spreads for gallium nitride-based active electronically scanned array modules.
Pricing Analysis
Prime contractor direct-to-defense-procurement discounts dominate channel economics, with Lockheed Martin and Raytheon Technologies bypassing traditional distributor markups for integrated air and missile defense contracts. Pricing stratifies across ITAR-restricted, NATO-interoperable, and export-controlled tiers, with certification-grade differentiation widening spreads between qualified and unqualified supplier bids. Cost compression in digital phased array development is intensifying because software-defined architectures demand sustained engineering overhead without hardware refresh cycles. Mid-tier surveillance applications show highest price sensitivity, while naval surface combatant programs demonstrate lowest sensitivity due to combat system integration lock-in.
Supply Chain Analysis
Single-source vulnerability sits with United States and Israeli sovereign gallium nitride foundries, where qualified high-electron-mobility transistor fabrication anchors defense procurement timelines. Substrate supply draws from Japan, Germany, and domestic United States facilities, with silicon carbide wafers and rare-earth magnet materials feeding transmit-receive module assembly. Tariff exposure on compound semiconductor imports strains cross-border electromagnetic compatibility certification pathways. Distribution runs through prime contractor direct sourcing, disintermediating traditional component channels as platform integrators assume module procurement responsibility.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with FCC spectrum allocations and NATO Standardization Office interoperability mandates accelerating procurement of multi-function phased array suites across allied fleets.
For Market Incumbents: Deploy gallium nitride foundry capacity expansion in Texas and Arizona to secure supply continuity against sovereign semiconductor investment competition from the United Kingdom. Lockheed Martin should deepen Aegis combat system firmware sustainment capabilities to defend against digital phased array entrants offering post-deployment upgrade pathways. Raytheon Technologies must accelerate ITU-R coordination pre-clearance to compress deployment timelines for multinational allied operations. For New Entrants and Emerging Players: Enter via Israeli defense export partnerships targeting European and Asia-Pacific navies seeking operational validation credentials for integrated air and missile defense networks. White space concentrates in wideband phased arrays for electronic warfare applications, where beam nulling and spatial filtering capabilities remain undersupplied. A software-defined radio convergence go-to-market angle enables post-deployment capability insertion without hardware replacement cycles. For Investors and Strategic Acquirers: Prime contractors with combat system heritage are the most active acquirer in this space, consolidating subsystem suppliers to reduce integration risk on complex phased array programs. Long-term viability rests on sovereign foundry access and certified manufacturing traceability rather than pure technology differentiation. Watch gallium nitride substrate supply concentration as the inflection indicator for qualified vendor pool expansion or contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Gallium Nitride Foundry Investment | Sovereign semiconductor facilities in Texas anchor supply security for naval procurement timelines. |
| Digital Phased Array Convergence | Software-defined beamforming merges with solid-state radar modules for post-deployment upgrades. |
| Israeli Defense Export Partnership | Operational validation credentials open European and Asia-Pacific navy procurement channels. |
| Aegis Combat System Integration | Lockheed Martin leverages heritage to anchor multi-year production agreements across allied fleets. |
| ITU-R Coordination Pre-clearance | Accelerated regulatory clearance compresses deployment schedules for multinational operations. |
Research Methodology
Multiple input streams — primary interviews with radar subsystem engineers and defense procurement officers, secondary validation through NATO Standardization Office documentation and FCC spectrum allocation records, and trade data from compound semiconductor substrate suppliers — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations included active electronically scanned array architects at prime contractors, gallium nitride foundry operations managers, naval surface combatant program executives, and electronic warfare systems integrators. Secondary sources comprised ITU-R coordination filings, national defense acquisition regulations, and sovereign semiconductor investment disclosures.
Historical procurement patterns were cross-referenced against panel input from defense procurement offices to model volume trajectories across the projection horizon. Segmentation dimensions included product architecture (active versus digital versus passive electronically scanned array), compound semiconductor technology node (gallium nitride versus gallium arsenide versus silicon germanium), platform application (naval surface combatant versus airborne early warning versus electronic warfare), and end-user tier (defense forces versus defense contractors versus aerospace manufacturers). CAGRs were derived from fitted growth curves applied to qualified vendor production capacity expansion schedules and platform modernization program announcements.
Inputs from prime contractor earnings disclosures and national defense budget appropriations were available through the study window; gaps in classified program timelines and specific gallium nitride substrate yield rates introduce uncertainty bands around procurement volume projections. Forecasts reflect assumptions regarding NATO interoperability mandate adherence, sovereign foundry qualification timelines, and ITU-R coordination throughput capacity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Military Aerospace and Defense Lifecycle Management Market
Defense and Military Systems and Equipment
Battle Management System (BMS) Market
Defense and Military Systems and Equipment
Defense Tactical Computers Market
Defense and Military Systems and Equipment
Missiles and Missile Defense Systems Market
Defense and Military Systems and Equipment
Network Centric Warfare (NCW) Market
Defense and Military Systems and Equipment
Anti-Drone Guns Market
Defense and Military Systems and Equipment
Military Actuators Market
Defense and Military Systems and Equipment
Military Parachute Market
Defense and Military Systems and Equipment
India Defense Market
Defense and Military Systems and Equipment
Saudi Arabia Defense Market
Defense and Military Systems and Equipment
Global Battlefield Management System Market
Defense and Military Systems and Equipment
Military Load Carriage System Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Display Systems Market
Defense and Military Systems and Equipment
Military Exoskeleton Market
Defense and Military Systems and Equipment
Radar Warning Receiver Market
Defense and Military Systems and Equipment
GCC Defense Market