
 South America Repair and Rehabilitation Market | 2026-2036
South America Repair and Rehabilitation Market Size, Share, and Industry Trends Forecast 2026-2036
South America Repair and Rehabilitation Market Analytics
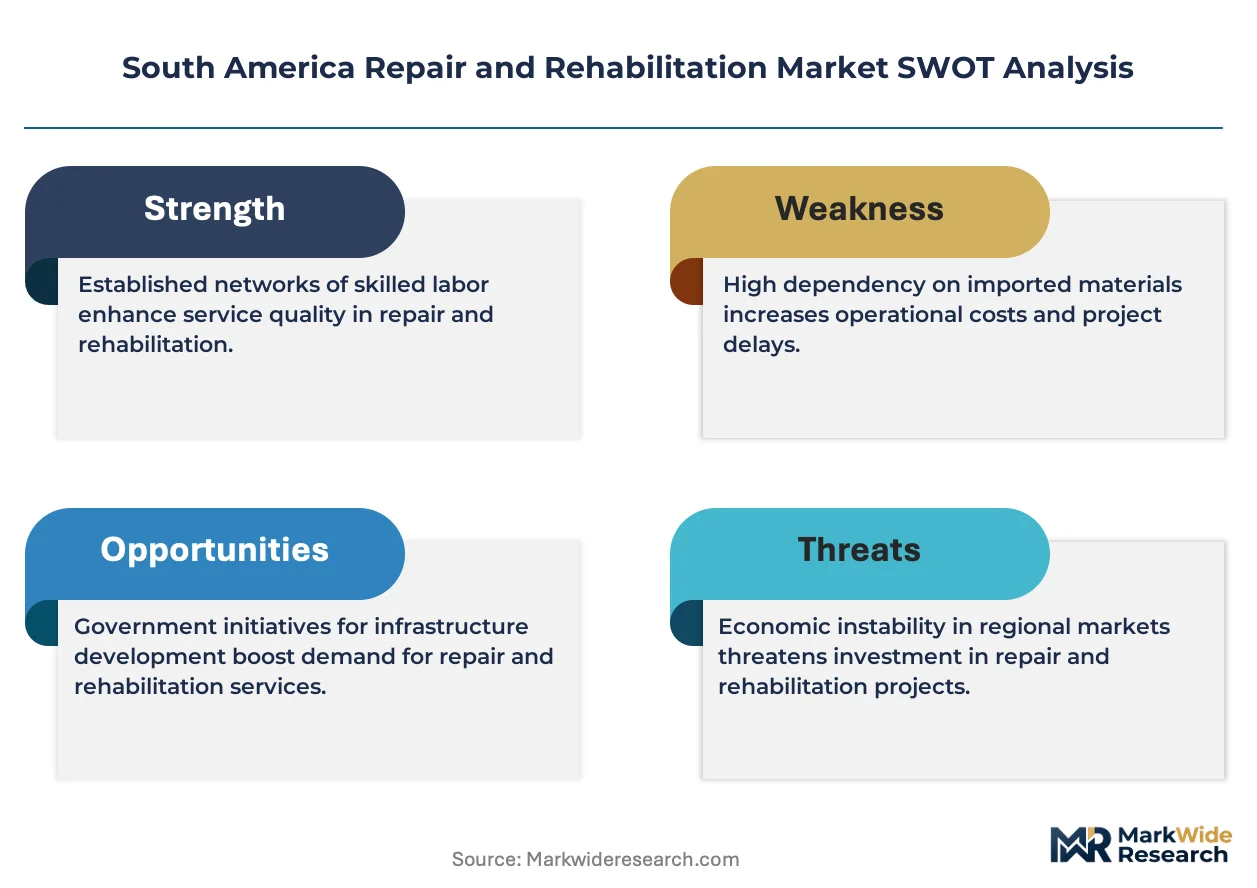
Brazil's updated infrastructure resilience standards is decoupling repair demand from pure new-build construction cycles. Mapei SpA anchors its regional position through specialized mortar and grouting formulations for seismic retrofitting. BASF SE leverages its polymer chemistry portfolio to supply high-performance bonding agents for concrete restoration across Andean projects. Akzo Nobel Chemicals AG competes on protective coating systems that extend steel bridge service life in coastal environments.
Repair and rehabilitation encompasses the structural restoration, surface renewal, and functional upgrading of existing civil and industrial assets using engineered materials and diagnostic techniques. Epoxy injection systems typically achieve compressive strengths exceeding concrete substrate ratings, enabling load-transfer restoration in cracked structural members. Structural Repair commands the largest value share given the complexity of foundation and load-bearing interventions across aging infrastructure portfolios. Advanced Materials within the Technology dimension represents the fastest-expanding margin pool, driven by carbon-fiber reinforcement and self-healing concrete admixtures that reduce lifecycle intervention frequency.
Brazil's national infrastructure regulator and Argentina's public works oversight body enforce progressively stricter structural assessment protocols that mandate periodic evaluation of bridges, dams, and public buildings. Chile's building code amendments following seismic events have tightened retrofitting requirements for reinforced concrete structures in high-risk zones. Stakeholders must monitor how evolving national standards across the continent redefine minimum performance thresholds for repair materials and contractor certification.
Market Dynamics
Brazil's updated infrastructure resilience standards are decoupling repair demand from pure new-build construction cycles across the continent. State agencies now mandate stricter load-bearing assessments for aging public works, creating sustained contract flows independent of GDP-linked capital expenditure programs.
Growth Catalysts
- Seismic retrofitting mandates:Chile's building code amendments following recent seismic events tightened requirements for reinforced concrete structures in high-risk zones. Contractors face expanded retrofit obligations.
- Coastal corrosion protection:Steel bridge maintenance contracts are accelerating across Brazil's southeastern seaboard. Salt-laden atmospheric exposure drives protective coating system replacements at shortened intervals.
- Carbon-fiber reinforcement adoption:Advanced composite materials reduce lifecycle intervention frequency for structural members. Asset owners prioritize total cost-of-ownership reductions over first-cost minimization.
Market Restraints
- Specialized polymer supply concentration:High-performance bonding agents for concrete restoration depend on imported epoxy formulations. Currency volatility affects input cost predictability for Brazilian contractors.
- Technical limitation in subsurface diagnostics:Foundation assessment beneath existing structures requires invasive investigation methods. Non-destructive testing penetration remains incomplete for deep pile evaluations.
- Regulatory friction from overlapping jurisdictions:Brazil's national infrastructure regulator and state-level environmental licensing bodies impose sequential approval requirements. Project timelines extend through redundant compliance layers.
Strategic Opportunities
- Argentina's underpenetrated provincial markets:Interior municipalities lack technical capacity for structural safety upgrades. Specialized contractors from Buenos Aires corridor can extend service networks.
- Self-healing concrete admixtures:Autonomous crack-sealing technologies reduce manual intervention requirements. Pilot installations demonstrate viability for dam and reservoir applications.
- Performance-based contractor certification:ANVISA and counterpart agencies develop material qualification frameworks. Early certification holders gain preferential positioning in public tender processes.
Industry Challenges
- Structural engineering talent scarcity:Seismic retrofitting design requires specialized expertise in nonlinear analysis. Regional universities produce insufficient graduates with relevant skill profiles.
- Capex intensity for diagnostic equipment:Ground-penetrating radar and ultrasonic testing arrays demand substantial upfront investment. Mid-tier contractors face equipment financing constraints.
- Legacy asset documentation gaps:Original construction records for 1970s-era infrastructure are frequently incomplete or unavailable. Engineers must reconstruct as-built conditions through destructive sampling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Repair and Rehabilitation Market |
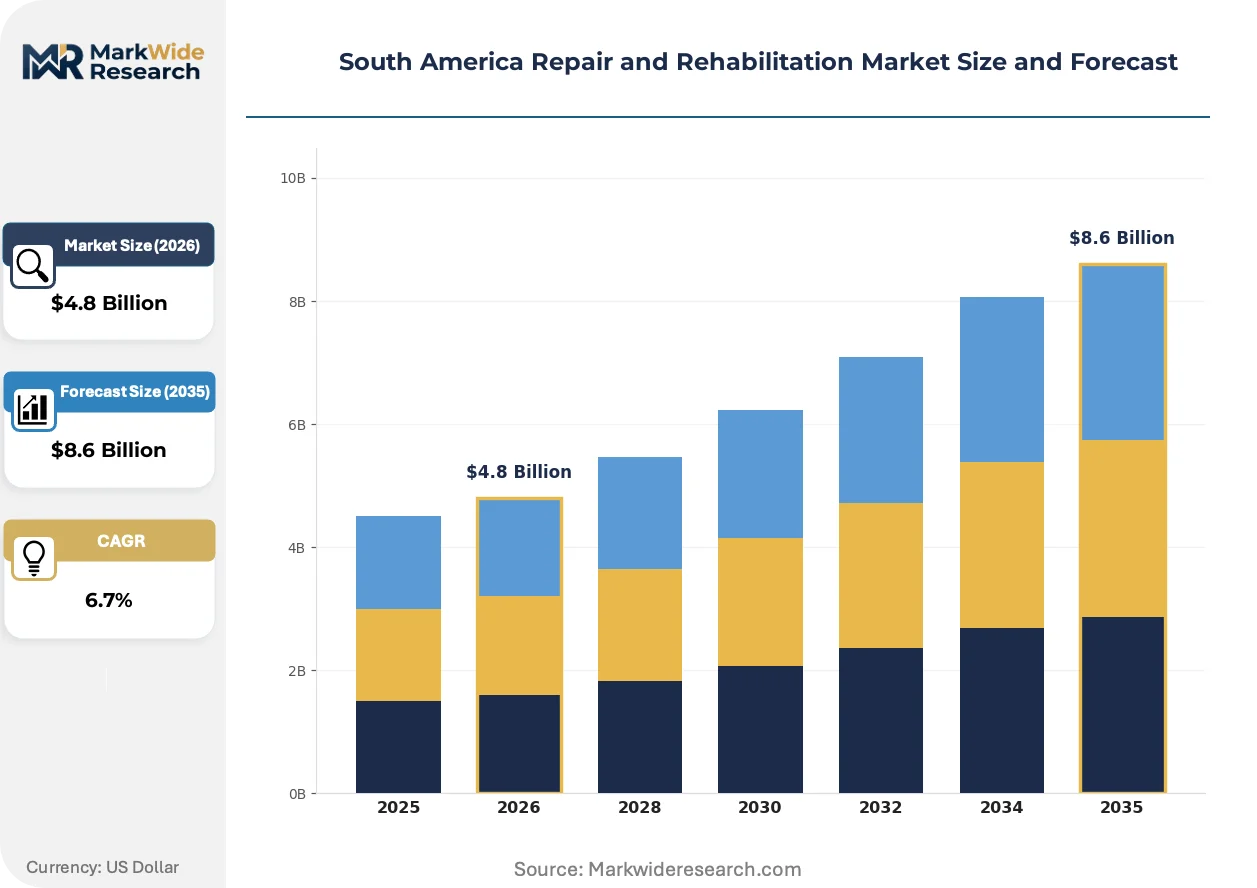
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Structural Repair, Surface Restoration, Waterproofing, Coating Application: Commercial Buildings, Residential Structures, Infrastructure Projects, Industrial Facilities Material: Concrete, Asphalt, Steel, Polymer Technology: Traditional Methods, Advanced Materials, Smart Sensors, Eco-friendly Solutions |
| Companies Covered | Mapei SpA, Resistoflex, 3M, Fabreeka, ContiTech Deutschland GmbH, Akzo Nobel Chemicals AG, BASF SE, HUTCHINSON, Arkema SA, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Repair and Rehabilitation Market Evolving Landscape
Digital inspection technologies and advanced material formulations are compressing project timelines while extending asset service life across South American infrastructure portfolios. These developments reshape contractor capability requirements and client procurement criteria simultaneously.
Drone-mounted photogrammetry and LiDAR scanning is automating bridge deck condition assessments that previously required lane closures and manual survey crews. Brazilian state highway departments deploy these systems for network-wide inventory updates. The technology is automating crack detection and spall mapping at throughput rates impossible for ground-based inspection teams.
ANVISA's updated construction product registration pathways streamline approval timelines for imported repair materials. Foreign suppliers gain accelerated market access for epoxy injection systems and carbon-fiber laminates. Brazilian contractors respond by expanding approved vendor lists and qualifying alternative supply sources.
Asset owners increasingly unbundle engineering design from material supply and installation execution. São Paulo metropolitan corridor public authorities now tender these scopes separately. Chilean mining sector clients pioneered this tripartite structure for tailings dam rehabilitation projects.
South America Repair and Rehabilitation Market Segmentation
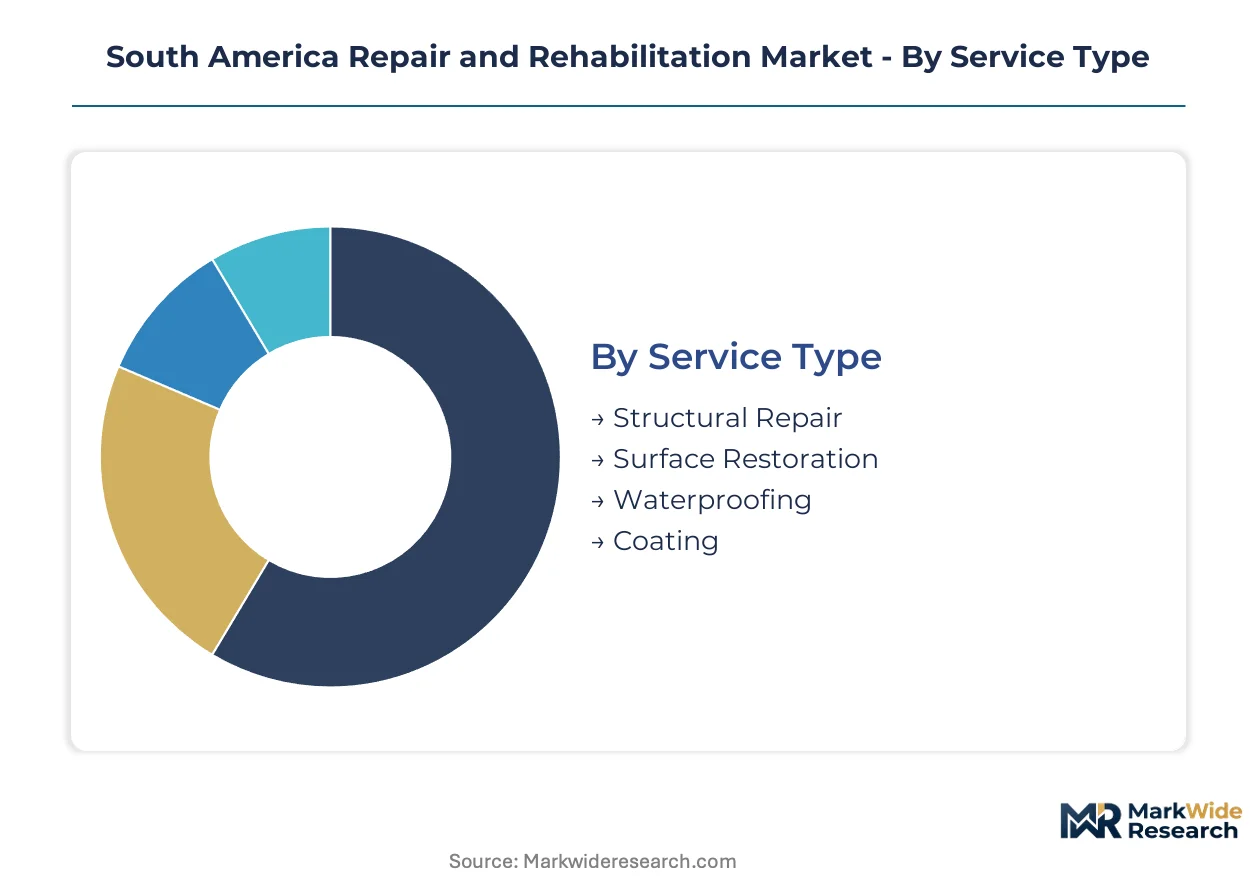
Segmentation reveals how repair demand fragments across technical specializations, asset classes, and material systems. Procurement patterns diverge sharply between public infrastructure tenders and private commercial retrofits. Understanding these divisions exposes where certification requirements concentrate and where margin structures differ most significantly.
Service Type:
ANVISA construction product registration requirements vary substantially across service categories, with structural interventions demanding the most extensive material qualification documentation.
- Structural Repair:Foundation stabilization, load-bearing member reinforcement, and seismic retrofitting using carbon-fiber laminates and epoxy injection systems. Brazilian state highway departments and São Paulo municipal authorities channel the heaviest contract volumes here, driven by mandatory bridge safety assessments under updated national standards.
- Surface Restoration:Concrete spall repair, facade renewal, and aesthetic refinishing of weathered substrates. Demand clusters in Rio de Janeiro's coastal commercial corridor where salt degradation accelerates maintenance cycles for high-visibility structures.
- Waterproofing:Membrane systems and integral crystalline admixtures for below-grade and roofing applications.
- Coating:Protective and decorative finishes extending substrate service life in aggressive environments.
Structural Repair sits at the top of the volume ranking, with Waterproofing climbing the fastest as basement and tunnel rehabilitation expands.
Application:
Cost tier stratification separates high-budget infrastructure tenders from fragmented residential maintenance spending across the continent.
- Infrastructure Projects:Highway bridges, dams, tunnels, and public transit systems requiring engineered intervention. Chile's Ministry of Public Works and Brazil's DNIT sustain the deepest project pipelines, with seismic retrofitting mandates in Santiago and load-bearing upgrades across Minas Gerais state networks.
- Commercial Buildings:Office towers, retail complexes, and hospitality assets undergoing functional modernization. Buenos Aires' central business district and São Paulo's Faria Lima corridor generate concentrated retrofit demand as landlords compete for tenant retention.
- Residential Structures:Single-family and multi-family building envelope and structural maintenance.
- Industrial Facilities:Manufacturing plants, warehouses, and processing infrastructure requiring corrosion protection and floor slab rehabilitation.
Infrastructure Projects command the largest absolute spend, while Commercial Buildings gain share fastest as private capital flows into asset modernization.
Material:
Supply concentration patterns differ markedly between commodity-grade inputs and specialized polymer systems subject to import dependency.
- Concrete:Repair mortars, shotcrete, and specialized grouts for structural restoration. Argentine provincial contractors and Colombian infrastructure developers absorb the highest volumes, though quality variability between local batch plants complicates specification compliance.
- Polymer:Epoxy resins, polyurethane foams, and methacrylate systems for bonding, sealing, and flexible waterproofing. Brazilian contractors face currency-driven cost volatility given import concentration from European and Asian suppliers.
- Asphalt:Pavement overlays, crack sealants, and recycling agents for roadway rehabilitation.
- Steel:Plate bonding, section replacement, and corrosion protection for bridge and building superstructures.
Concrete dominates material tonnage, with Polymer expanding most quickly as advanced composite reinforcement displaces traditional techniques.
Technology:
Maturity gradients separate established contractor capabilities from emerging methods requiring capital equipment investment and workforce retraining.
- Advanced Materials:Carbon-fiber reinforced polymers, self-healing concrete admixtures, and high-performance geopolymer binders. Chilean mining sector tailings dam projects and Brazilian hydroelectric facility upgrades are early adopters, prioritizing lifecycle cost reduction over first-cost minimization.
- Smart Sensors:Embedded strain gauges, corrosion monitoring probes, and wireless data acquisition for predictive maintenance. Deployment concentrates in Peru's mining infrastructure and Colombia's strategic bridge inventory where real-time condition assessment justifies hardware investment.
- Traditional Methods:Conventional concrete removal, patching, and surface preparation techniques.
- Eco-friendly Solutions:Low-carbon binders, bio-based coatings, and recycled aggregate systems.
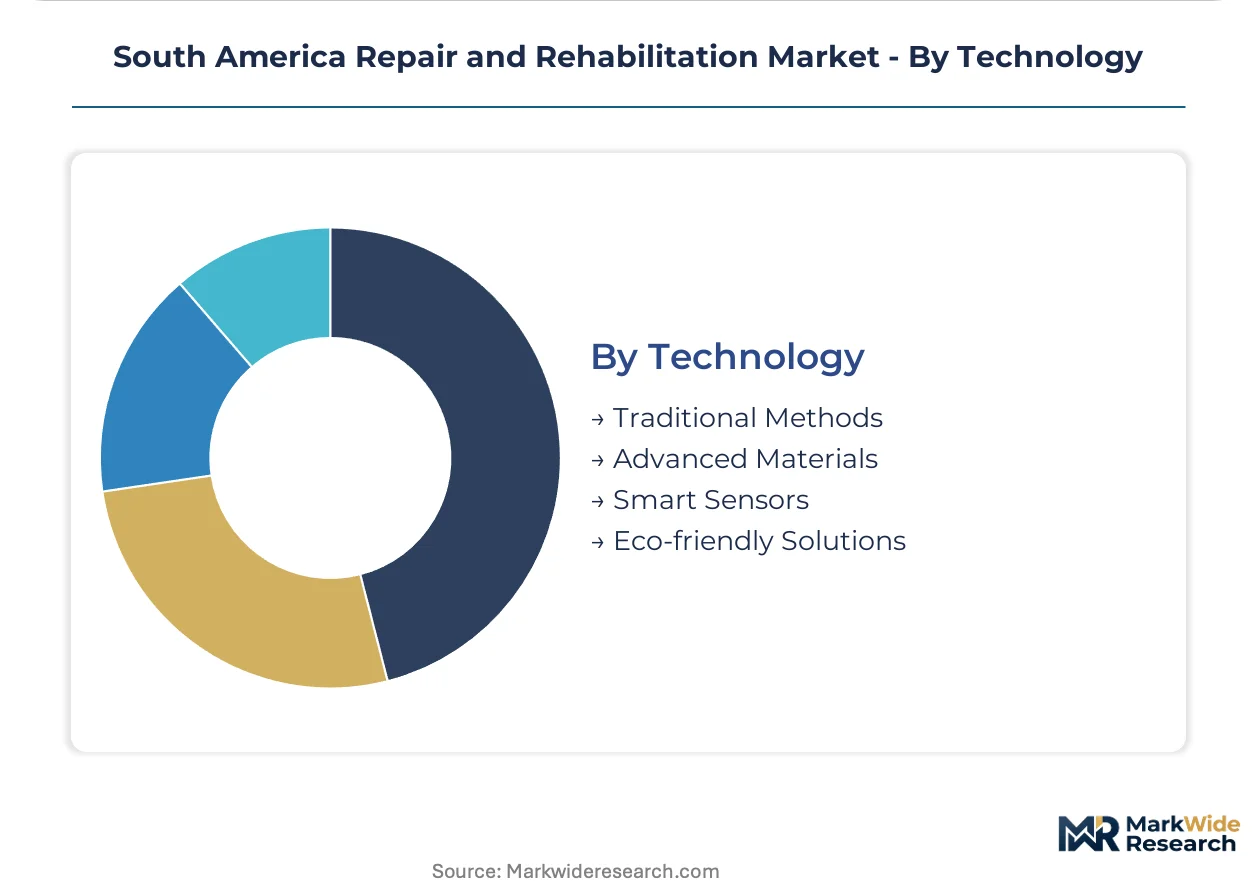
Traditional Methods still account for the majority of project executions, though Advanced Materials are gaining share fastest as asset owners accept higher upfront costs for extended service intervals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil pioneered large-scale infrastructure rehabilitation programs across South America during the 1990s federal highway modernization initiative. State agencies in São Paulo and Minas Gerais developed contracting frameworks that neighboring countries later adapted. This institutional legacy continues shaping procurement standards continent-wide.
Brazil
Bridge maintenance contracts are expanding as DNIT and state highway departments prioritize structural safety upgrades. ANVISA construction product registration requirements for epoxy injection systems and carbon-fiber laminates streamline approval timelines for foreign suppliers. São Paulo's metropolitan corridor concentrates commercial retrofitting demand where landlords compete for tenant retention through facade renewal.
Argentina
Interior municipalities lack technical capacity for structural safety upgrades, creating service network extension opportunities from Buenos Aires-based contractors. The country's public works oversight body enforces progressively stricter structural assessment protocols for aging public buildings. Córdoba and Mendoza provincial networks absorb growing volumes of repair mortars despite quality variability between local batch plants.
Chile
Seismic retrofitting mandates tightened following recent seismic events, expanding contractor obligations for reinforced concrete structures. The Ministry of Public Works sustains deep project pipelines for dam and public transit rehabilitation. Santiago's high-risk zones concentrate carbon-fiber reinforcement adoption as asset owners prioritize lifecycle cost reduction.
Colombia
Strategic bridge inventory programs justify embedded sensor deployment for real-time condition assessment. The national infrastructure regulator mandates periodic evaluation requirements that reshape minimum performance thresholds. Bogotá's Andean infrastructure corridor drives protective coating system replacements for steel superstructures in variable climate exposure.
Peru
Mining infrastructure operators deploy smart sensor arrays for predictive maintenance of tailings dams and processing facilities. The country's national infrastructure standards emphasize structural resilience for resource extraction assets. Lima's coastal commercial district accelerates waterproofing membrane installations as salt-laden atmospheric exposure shortens maintenance cycles.
South America Repair and Rehabilitation Market Competitive Landscape
Capital-heavy producers compete with asset-light specialty formulators across material supply tiers. The market structure concentrates around integrated chemical conglomerates with polymer chemistry portfolios and regional mortar specialists with localized distribution networks. Three archetypes dominate: European-headquartered multinationals leveraging global R&D platforms, Latin American regional champions with formulation adaptation capabilities, and niche composite material suppliers serving mining sector clients. Competitive positioning depends on ANVISA certification timing and backward integration into resin production.
Among European-based chemical suppliers, Mapei SpA and BASF SE exemplify archetypes with differentiated technical positioning. BASF SE anchors the polymer chemistry tier through high-performance bonding agent supply chains. Akzo Nobel Chemicals AG occupies a position within protective coating systems for coastal corrosion environments. Regional specialists including Resistoflex and Fabreeka represent the application-engineering tier, translating material specifications into project-specific solutions for seismic retrofitting and vibration isolation contracts.
| Leading Market Players |
|---|
| Mapei SpA |
| Resistoflex |
| 3M |
| Fabreeka |
| ContiTech Deutschland GmbH |
| Akzo Nobel Chemicals AG |
| BASF SE |
| HUTCHINSON |
| Arkema SA |
| Others |
Value Network & Pricing Analysis
Family-owned Brazilian mortar specialists anchor regional supply networks while exercising pricing discipline through long-standing relationships with state highway departments. Their localized production footprint buffers currency-driven input volatility that pressures multinational polymer suppliers. This ownership structure reinforces project-based contracting with public agencies seeking predictable lifecycle costs over first-bid minimization.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and volume scale. ANVISA-registered epoxy systems command substantial premia over unregistered imports due to liability reduction for public contractors. Cost compression in standard-grade concrete mortars is intensifying because Argentine provincial batch plants expand capacity without quality standardization. Municipal infrastructure tenders exhibit highest price sensitivity; mining sector tailings dam projects show least sensitivity due to failure-cost exposure.
Supply Chain Analysis
Specialized seismic retrofitting engineers concentrate in Santiago and São Paulo metropolitan clusters, constraining project execution capacity across interior provinces. High-performance polymer resins draw from German and Japanese chemical producers, while carbon-fiber laminates source primarily from Chinese and European composite manufacturers. Single-source vulnerability pervades epoxy formulation supply given ANVISA registration barriers for new entrants. Distribution runs through authorized applicator networks that combine material supply with installation certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America Repair and Rehabilitation Market compounds steadily as mandatory structural assessment protocols across Brazil, Chile, and Argentina generate contract flows decoupled from GDP-linked capital expenditure cycles.
For Market Incumbents: Acquire specialized seismic engineering consultancies to capture design-phase influence before material specification locks. BASF SE and Mapei SpA should deepen backward integration into resin production to offset currency-driven input cost volatility threatening Brazilian contractor margins. Cement this position by accelerating ANVISA certification for self-healing concrete admixtures before regulatory windows narrow. For New Entrants and Emerging Players: Digital inspection technology partnerships offer a lower-capital route to project involvement without heavy diagnostic equipment ownership. Argentina's Córdoba and Mendoza provincial networks represent the most penetrable geography given technical capacity gaps in structural safety upgrades. Target these municipalities through Buenos Aires-based contractor alliances that transfer seismic retrofitting expertise. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier applicator networks with ANVISA certification but limited geographic reach. The five-to-ten year viability thesis rests on regulatory ratcheting that expands mandatory assessment scope beyond bridges into dams and public buildings. Watch for ANVISA construction product registration pathway simplification as the inflection signal that accelerates foreign supplier competition and compresses domestic specialist margins.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Certification Acceleration | Early registration holders gain preferential positioning in Brazilian public tender processes before pathway simplification. |
| Carbon-Fiber Reinforcement Capacity Expansion | Chilean mining sector demand for tailings dam retrofitting outstrips qualified applicator supply. |
| Self-Healing Concrete Admixture Pilot Programs | Autonomous crack-sealing technologies reduce manual intervention frequency for dam and reservoir applications. |
| Provincial Service Network Extension | Argentine interior municipalities lack technical capacity for structural safety upgrades mandated by public works oversight. |
| Digital Inspection Technology Partnership | Drone-mounted photogrammetry automates bridge assessments previously requiring lane closures and manual crews. |
Research Methodology
Bottom-up infrastructure project pipeline modeling reconciled against top-down polymer import tracking forms the analytical core of this study. Primary interviews with bridge maintenance directors at Brazilian state highway departments, seismic retrofitting contractors in Santiago, ANVISA regulatory affairs specialists, and mining sector asset managers in Peru validated demand assumptions. Secondary sources include DNIT contract award databases, Chile Ministry of Public Works project registries, ANVISA construction product registration filings, and customs records for epoxy resin and carbon-fiber laminate imports.
Input-output matrices segment volume and value across service type, application, material system, and technology maturity tiers throughout the forecast period. Modeled dimensions include structural versus surface intervention categories, infrastructure versus commercial versus industrial end-uses, concrete versus polymer versus steel material classes, and traditional versus advanced material technology tiers. CAGRs derive from project backlog analysis, regulatory mandate implementation timelines, and material substitution elasticity estimates for carbon-fiber reinforcement displacing conventional steel plate bonding.
The model assumes a particular technology adoption path; alternative pathways for self-healing concrete admixtures would alter the outlook if autonomous crack-sealing achieves cost parity with manual intervention faster than projected. Forecasts reflect assumptions about ANVISA registration pathway stability, Brazilian real exchange rate volatility bands, and seismic code amendment implementation consistency across Chilean provinces. Material deviation in regulatory ratcheting intensity, currency trajectory, or technology cost curves warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Offshore Pipeline Infrastructure Market
Infrastructure Construction
Vietnam Data Center Construction Market
Infrastructure Construction
India Transportation Infrastructure Construction Market
Infrastructure Construction
Taiwan Data Center Construction Market
Infrastructure Construction
Brazil Data Center Construction Market
Infrastructure Construction
Aerial Cable Car Equipment Market
Infrastructure Construction
Pipeline Construction Market
Infrastructure Construction
New Zealand Data Center Construction Market
Infrastructure Construction
Utility System Construction Market
Infrastructure Construction
Composite Railroad Tie Market
Infrastructure Construction
Pipeline Network Market
Infrastructure Construction
South America Data Center Construction Market
Infrastructure Construction
Vietnam Infrastructure Market
Infrastructure Construction
Thailand Data Center Construction Market
Infrastructure Construction
Italy Infrastructure Investment Market
Infrastructure Construction
China Infrastructure Market