
 Utility System Construction Market | 2026-2036
Utility System Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Utility System Construction Market Analytics
Data center electrification is recalibrating utility construction priorities as hyperscale facilities require dedicated substations and redundant feeder networks. Quanta Services Inc. leverages its specialized transmission workforce to capture these high-amperage projects across Texas and Virginia. MasTec Inc. anchors its growth in renewable interconnection, building collector systems for solar and wind farms throughout the Southwest. MYR Group Inc. competes in the industrial utility segment, sustaining long-term service agreements with manufacturing clients requiring on-site power infrastructure.
Utility system construction encompasses the engineering, procurement, and installation of electric power generation, transmission, and distribution infrastructure, typically involving voltage classes from 4 kV distribution to 765 kV transmission with material specifications for galvanized steel lattice towers, aluminum conductor steel reinforced cable, and sulfur hexafluoride or vacuum circuit breakers. Its primary purpose is delivering reliable electricity from generation sources to end-users while maintaining grid stability and regulatory compliance. Renewable Energy projects within the Project Type dimension are attracting disproportionate capital allocation as offshore wind and solar-plus-storage complexes require entirely new transmission corridors rather than retrofitting existing lines. Prefabricated methods under Construction Method are expanding fastest among utilities seeking to compress substation commissioning schedules and reduce on-site labor exposure.
The US Federal Energy Regulatory Commission sets cost allocation rules for interstate transmission, while the EPA regulates sulfur hexafluoride emissions from switchgear, and OSHA governs live-line work standards that shape contractor training investments and project timelines. The EU Green Deal and F-Gas Regulation are accelerating SF6-free equipment adoption, forcing material substitutions in European projects. Stakeholders must monitor how permitting reform debates in Washington and Brussels affect project cycle times relative to equipment procurement lead times.
Market Dynamics
Data center electrification and renewable interconnection mandates are compressing utility construction timelines while simultaneously stretching contractor capacity across high-voltage transmission corridors. The collision between hyperscale power demand and grid hardening requirements is forcing simultaneous investment in generation, transmission, and distribution infrastructure.
Growth Catalysts
- US Inflation Reduction Act transmission incentives:Direct payment mechanisms and loan guarantees accelerate capital deployment for interstate high-voltage direct current corridors, reducing project finance risk.
- Offshore wind collector systems:European and North American lease auctions require dedicated export cables and platform substations, creating specialized construction demand.
- SF6-free switchgear mandates:The EU F-Gas Regulation and state-level procurement rules in Germany and California are accelerating vacuum and clean air insulation retrofits.
Market Restraints
- Transformer core steel concentration:Grain-oriented electrical steel supply concentrates among Japanese and European mills, extending lead times for power transformers beyond 24 months.
- High-voltage cable installation vessel scarcity:Purpose-built cable-laying ships for subsea interconnection remain limited to a handful of European and Asian operators.
- Interstate permitting fragmentation:US state-level siting authority under FERC Order 1000 creates jurisdictional complexity for multi-state transmission projects.
Strategic Opportunities
- Prefabricated substation modules:Factory-built transformer and switchgear skids compress field commissioning schedules for utilities facing skilled labor shortages.
- Battery-plus-solar hybrid interconnection:Co-located storage requires upgraded collector substations and inverters, expanding the addressable project scope beyond pure generation.
- Grid-enhancing technologies:Dynamic line rating and topology optimization software create retrofit demand for sensor installation and control system integration.
Industry Challenges
- Live-line technician certification pipelines:OSHA 1910.269 compliance and utility-specific apprenticeship programs cannot scale to match retirement-driven workforce attrition.
- Legacy SCADA integration complexity:New digital substation architectures using IEC 61850 protocols must interface with decades-old proprietary control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utility System Construction Market |
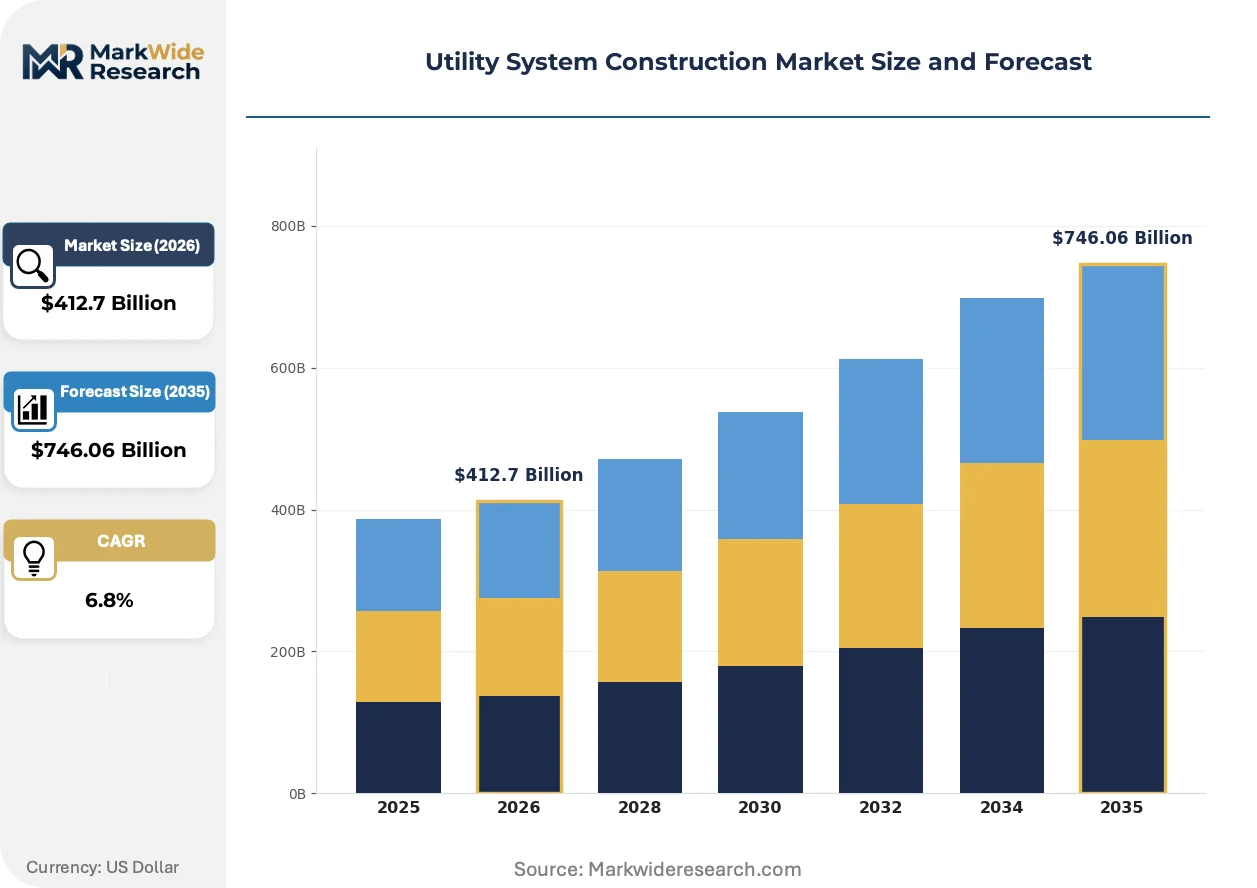
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $746.06 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Residential, Commercial, Industrial, Renewable Energy Construction Method: Traditional, Modular, Prefabricated, Sustainable Practices Client Type: Government, Private Sector, Utilities, Non-profit Organizations Service Type: Design, Engineering, Project Management, Maintenance |
| Companies Covered | Vinci SA, MasTec Inc., China State Construction Engineering Corporation Limited, MYR Group Inc., Balfour Beatty plc, China Railway Construction Corporation Limited, Quanta Services Inc., Michels Corporation, Power Construction Corporation of China, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utility System Construction Market Evolving Landscape
Digital substation architectures and modular construction methods are compressing project delivery timelines while regulatory pressure on sulfur hexafluoride accelerates material substitution across switchgear portfolios.
Gas-insulated switchgear using vacuum interrupters and clean air insulation is expanding into 145 kV and 420 kV applications previously dominated by SF6 technology. German utilities and California municipal power agencies are specifying SF6-free equipment in procurement tenders despite 15-20% capital cost premiums. This transition is expanding into the high-voltage transmission segment faster than equipment manufacturers anticipated, forcing capacity reallocation across European and Asian production lines.
The EU F-Gas Regulation mandates 80% SF6 emission reductions by 2030 and complete phase-out in new medium-voltage equipment by 2026. This regulatory pressure is compressing R&D timelines for alternative insulation technologies and reshaping supplier qualification requirements. European transmission system operators in Germany, Denmark, and the Netherlands are now requiring SF6-free designs for all new substation projects, accelerating vendor certification programs.
Engineering-procurement-construction firms are unbundling long-term service agreements from initial construction contracts, allowing utilities to separate capital and operating expenditures. This procurement restructuring is displacing traditional integrated project delivery in the United States and United Kingdom, where rate-base treatment favors distinct capitalization. Texas and Virginia markets exhibit the most pronounced shift, with independent power producers and hyperscale data center operators driving demand for flexible contract structures.
Utility System Construction Market Segmentation
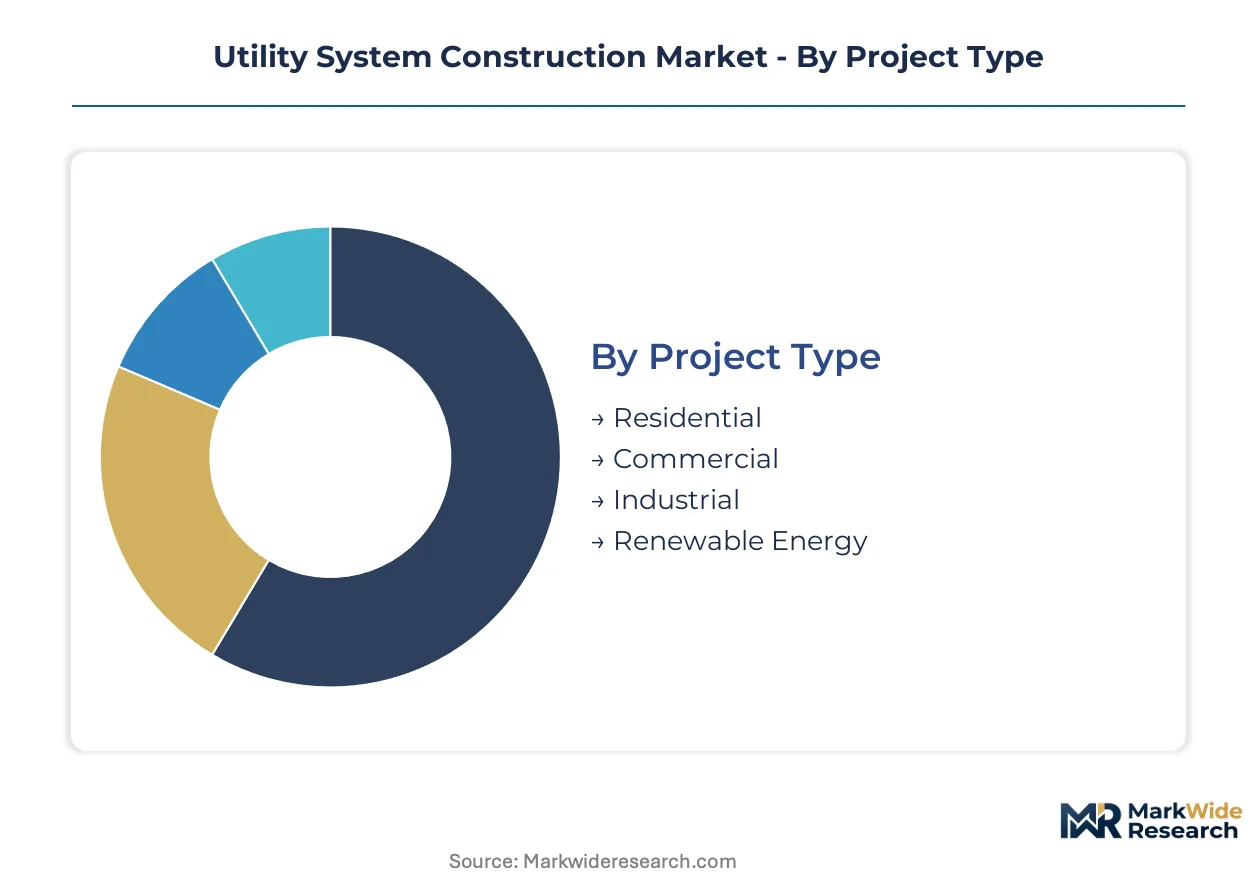
Utility system construction segments by project scale, delivery method, and client procurement structure. Each dimension shapes contractor capability requirements and margin profiles differently across transmission, distribution, and generation infrastructure.
Project Type:
Scale and voltage class differentiate buyer technical requirements and regulatory exposure.
- Industrial:Dedicated substations for manufacturing campuses and hyperscale data centers demand redundant feeder networks and specialized high-amperage switchgear. Demand concentrates in Texas and Virginia where data center load growth is forcing transmission upgrades ahead of generation capacity.
- Renewable Energy:Offshore wind and solar-plus-storage complexes require entirely new transmission corridors rather than retrofitting existing lines. Collector systems and export cables in Germany and the United States are stretching contractor capacity for specialized marine and high-voltage installation.
- Residential:Last-mile distribution extensions and service upgrades for electrification retrofits.
- Commercial:Mixed-use developments requiring on-site transformer vaults and medium-voltage distribution.
Volume sits with Industrial; growth tilts toward Renewable Energy.
Construction Method:
Schedule compression and labor risk transfer distinguish procurement preferences across client types.
- Prefabricated:Factory-built transformer and switchgear skids compress field commissioning schedules for utilities facing skilled technician shortages. European transmission operators in Germany and the Netherlands are mandating modular approaches to reduce live-line work exposure.
- Modular:Standardized substation enclosures and plug-in cable systems enable parallel construction workflows. California municipal utilities specify modular designs to accelerate renewable interconnection timelines constrained by permitting delays.
- Traditional:Stick-built construction with on-site assembly of galvanized steel structures and poured foundations.
- Sustainable Practices:Low-carbon concrete, recycled steel, and construction waste reduction protocols.
Traditional methods still dominate installed base; prefabricated approaches are climbing the fastest as labor scarcity intensifies.
Client Type:
Capital source and rate-base treatment determine contract structure and payment security.
- Utilities:Investor-owned and municipal power companies with rate-base capitalization favor long-term service agreements unbundled from initial construction. United States utilities under FERC jurisdiction are separating capital and operating expenditures to optimize return-on-equity treatment.
- Private Sector:Independent power producers and hyperscale data center operators drive demand for flexible contract structures. Texas and Virginia markets exhibit pronounced shifts toward design-build arrangements with fixed-price risk transfer.
- Government:Federal and state agencies funding grid hardening under the US Inflation Reduction Act.
- Non-profit Organizations:Rural electric cooperatives and community choice aggregators with limited balance sheet capacity.
Utilities command the deepest project backlog; private sector clients are gaining share fastest in high-voltage transmission.
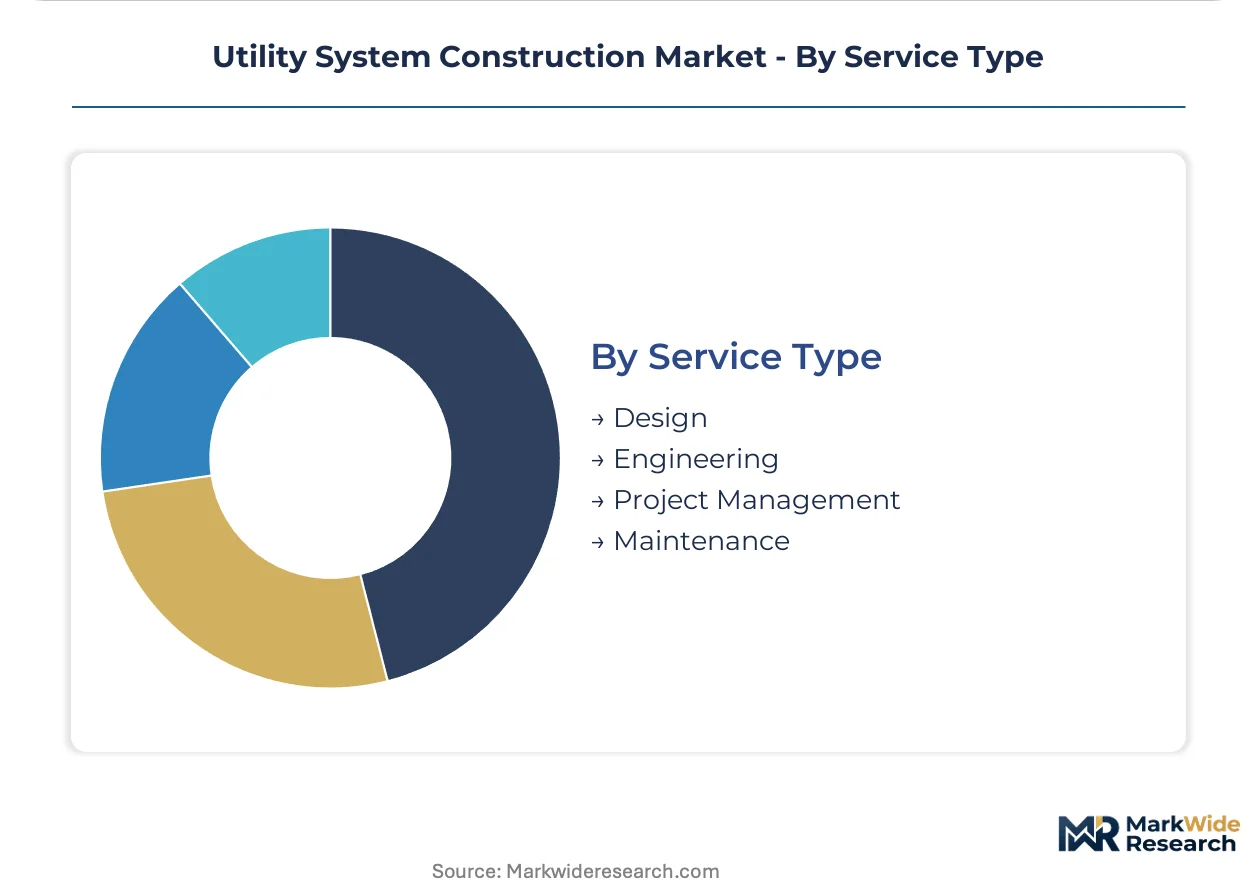
Service Type:
Technical scope and risk allocation separate procurement packages along the project lifecycle.
- Engineering:Front-end design and system integration for complex interconnection projects. European engineering firms are capturing offshore wind collector system work requiring marine geotechnical and high-voltage expertise.
- Project Management:Owner's engineer and construction management services for multi-contractor transmission builds. Demand is concentrating in Germany where offshore wind timelines require coordination between cable manufacturers, platform fabricators, and installation vessel operators.
- Design:Feasibility studies, routing optimization, and permitting support.
- Maintenance:Long-term service agreements and asset management contracts.
Engineering holds the largest revenue pool; project management is expanding most quickly as project complexity fragments contractor scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction output concentrates in markets where grid modernization mandates collide with data center load growth, while supply chains for specialized equipment remain tethered to Asian and European manufacturing hubs.
United States
Interstate high-voltage direct current corridors and hyperscale data center substations dominate contractor backlogs. The Inflation Reduction Act's direct payment mechanisms accelerate capital deployment for transmission hardening. Northern Virginia and Dallas-Fort Worth clusters absorb the bulk of specialized high-amperage switchgear installations.
Germany
Offshore wind collector systems and North Sea export cable networks strain installation vessel capacity. The EU F-Gas Regulation mandates 80% sulfur hexafluoride emission reductions by 2030, forcing vacuum interrupter adoption. Hamburg and Bremerhaven anchor marine construction activity for platform substations.
China
Ultra-high voltage transmission corridors spanning 800 kV and 1100 kV classes drive domestic equipment procurement. State Grid Corporation's dual carbon goals redirect capital toward renewable interconnection infrastructure. Yangtze River Delta and Pearl River Delta urban clusters prioritize smart substation deployment.
United Kingdom
North Sea offshore wind lease auctions require dedicated export cables and converter stations. The national regulator's cost allocation rules shape transmission owner procurement structures. Scottish waters and East Anglia concentrate marine installation demand for floating and fixed-bottom wind platforms.
India
Green Energy Corridors and interstate transmission schemes expand high-voltage network capacity. The Central Electricity Authority mandates smart grid standards for distribution utilities. Gujarat and Rajasthan host solar park collector systems requiring upgraded substation infrastructure.
Utility System Construction Market Competitive Landscape
Top-tier vendors anchor transmission and generation infrastructure, while regional specialists capture distribution and industrial substation niches. The market exhibits tiered consolidation around engineering-procurement-construction capabilities, equipment manufacturing integration, and specialized installation fleets. Three archetypes dominate: full-service EPC integrators, transmission-focused specialty contractors, and state-linked infrastructure conglomerates. Competitive positioning hinges on M&A-driven geographic expansion and prefabrication capacity investments that compress project delivery timelines.
Within the full-service EPC tier, Vinci SA and Balfour Beatty plc represent European-anchored operators with integrated civil and electrical capabilities. MasTec Inc. and MYR Group Inc. exemplify North American specialty contractors positioned for renewable interconnection and data center electrification demand. Quanta Services Inc. occupies a position in high-voltage transmission workforce deployment. These named entities serve as reference points for capability segmentation rather than exhaustive market enumeration.
| Leading Market Players |
|---|
| Vinci SA |
| MasTec Inc. |
| China State Construction Engineering Corporation Limited |
| MYR Group Inc. |
| Balfour Beatty plc |
| China Railway Construction Corporation Limited |
| Quanta Services Inc. |
| Michels Corporation |
| Power Construction Corporation of China |
| Others |
Value Network & Pricing Analysis
Grain-oriented electrical steel from Japanese and European mills feeds into power transformer pricing tiers that stratify across premium, standard, and economy levels based on core material grade and delivery certainty. This input concentration cascades through EPC contractor bids to utility procurement desks, where SF6-free switchgear specifications command capital cost premiums against conventional vacuum interrupter alternatives.
Pricing Analysis
Margin tightening in high-voltage transmission projects reflects grain-oriented electrical steel allocation bottlenecks and extended transformer lead times. Three-tier pricing structure across premium, standard, and economy levels separates utilities with long-term offtake agreements from spot-market buyers facing 15-20% capital cost premiums for SF6-free equipment. Cost-down pressure on distribution infrastructure accelerates as municipal utilities prioritize rate-base treatment over upfront capital efficiency. Private sector data center operators exhibit lowest price sensitivity due to load-critical redundancy requirements, while rural electric cooperatives face acute procurement constraints.
Supply Chain Analysis
High-voltage cable manufacturing rests on European and Asian vessel operators with purpose-built installation fleets for subsea interconnection. Critical inputs include aluminum conductor steel reinforced cable, sulfur hexafluoride or vacuum circuit breakers, and galvanized steel lattice towers. Single-source vulnerability concentrates around Japanese and European grain-oriented electrical steel mills. Distribution runs through engineering-procurement-construction firms unbundling long-term service agreements from initial construction contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Utility system construction is becoming a vertical-integration race where EPC contractors pursue captive supply of prefabricated substation modules to compress commissioning schedules and capture margin otherwise lost to equipment manufacturers.
For Market Incumbents: Deploy prefabrication capacity investments to defend against specialized marine contractors capturing offshore wind collector system work. Backward integration into modular switchgear skids protects margin from SF6-free equipment suppliers while accelerating project delivery timelines for utilities facing skilled technician shortages. Rate-base optimization under FERC jurisdiction remains the priority lever for investor-owned utility clients. For New Entrants and Emerging Players: Independent power producers in Texas and Virginia represent the most penetrable client archetype as hyperscale data center load growth forces transmission upgrades ahead of generation capacity. Prefabricated substation modules for industrial campus electrification offer white-space entry with lower certification barriers than high-voltage transmission. Design-build arrangements with fixed-price risk transfer provide the strongest go-to-market angle against incumbent integrated project delivery. For Investors and Strategic Acquirers: FERC Order 1000 permitting reform debates are the leading indicator that interstate transmission project cycle times may compress or extend relative to equipment procurement lead times. Long-term viability favors EPC integrators with marine installation vessel access or prefabrication facility footprints in Germany and the Netherlands. Watch EU F-Gas Regulation enforcement timelines as the signal for SF6-free equipment adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Prefabrication Facility Buildout | Factory-built transformer skids compress field commissioning schedules for utilities facing OSHA 1910.269 technician shortages. |
| Marine Installation Vessel Acquisition | Purpose-built cable-laying ships capture offshore wind export cable demand concentrated in North Sea lease auctions. |
| SF6-Free Equipment Certification | Vacuum interrupter and clean air insulation qualifications unlock procurement tenders from German transmission system operators. |
| Long-Term Service Agreement Unbundling | Separating capital and operating expenditures optimizes rate-base treatment for United States utilities under FERC jurisdiction. |
| Transmission Hardening Partnership | Grid-enhancing technology integration creates retrofit demand for dynamic line rating sensor installation and SCADA upgrades. |
Research Methodology
Independent corroboration across utility planning officers, EPC project developers, grid operators, and equipment procurement specialists underwrites the qualitative findings. Secondary validation draws from FERC filings, EIA transmission project databases, EU Green Deal implementation reports, and IEA grid investment tracking. Bottom-up project pipeline aggregation triangulates against top-down capital expenditure forecasts across voltage classes and construction methods.
Rate-of-change decomposition across the analysis window segments volume and value outputs by project type, construction method, client procurement structure, and service scope. CAGRs derive from modeled deployment timelines for high-voltage direct current corridors, offshore wind collector systems, and data center substation infrastructure. Forecast inputs incorporate Inflation Reduction Act incentive uptake trajectories and EU F-Gas Regulation compliance deadlines.
Caveats apply where permitting reform outcomes, grain-oriented electrical steel allocation shocks, or cable-laying vessel availability constraints could materially shift the outlook. Forecasts reflect assumptions about regulatory continuity and supply chain normalization. A small set of named triggers—FERC Order 1000 implementation, Japanese mill capacity expansion, and North Sea lease auction timing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Global Rail Infrastructure Market
Infrastructure Construction
Denmark Data Center Construction Market
Infrastructure Construction
Switzerland Transportation Infrastructure Construction Market
Infrastructure Construction
Israel Data Center Construction Market
Infrastructure Construction
Global Manhole Covers Market
Infrastructure Construction
Netherlands Transportation Infrastructure Construction Market
Infrastructure Construction
North America Transportation Infrastructure Construction Market
Infrastructure Construction
Aerial Cable Car Equipment Market
Infrastructure Construction
Brazil Data Center Construction Market
Infrastructure Construction
Transmission and Distribution Infrastructure Market
Infrastructure Construction
Bahrain Construction Market
Infrastructure Construction
Heavy Movable Bridges Market
Infrastructure Construction
Cofferdam Market
Infrastructure Construction
Russia Transportation Infrastructure Construction Market
Infrastructure Construction
Norway Transportation Infrastructure Construction Market
Infrastructure Construction
India Transportation Infrastructure Market