
 Taiwan Data Center Construction Market | 2026-2036
Taiwan Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Data Center Construction Market Insights
Buyer concentration among domestic cloud service providers and international hyperscalers is recalibrating procurement dynamics for Taiwan data center construction. TECO Corporation leverages its electromechanical manufacturing depth to supply critical power infrastructure for these facilities. CTCI Group anchors large-scale EPC execution through its established presence in industrial construction across the island. Exyte competes on cleanroom and controlled-environment expertise that transfers directly to high-specification data hall builds.
Taiwan data center construction encompasses the engineering, physical build-out, and commissioning of facilities designed to house IT infrastructure with controlled temperature, humidity, and power continuity parameters, typically maintaining ambient conditions within 18-27°C and 40-60% relative humidity for optimal server operation. The primary purpose centers on creating resilient, scalable environments that support enterprise and cloud computing workloads while minimizing thermal and electrical failure risks. Hyperscale data centers command the largest capital commitments as international operators expand footprint, while liquid cooling segments are gaining structural attention due to rising rack power densities exceeding 50kW in AI training clusters. Modular design approaches are capturing margin pools by compressing construction schedules and reducing on-site labor dependencies in Taiwan's constrained skilled workforce environment.
Taiwan's Ministry of Economic Affairs enforces industrial electricity allocation frameworks that shape data center site selection and power redundancy planning, while the Bureau of Standards, Metrology and Inspection administers building energy codes affecting cooling system specifications. The National Communications Commission regulates submarine cable landing stations that interconnect Taiwan-built facilities to international networks, creating compliance layers around physical security and redundancy. Stakeholders must monitor how evolving carbon accounting rules and renewable energy certificate requirements reshape total cost of ownership calculations for new capacity decisions.
Market Dynamics
AI training clusters exceeding 50kW per rack are forcing liquid cooling retrofits into legacy facility designs while Taiwan's Electricity Act amendments redirect power procurement toward renewable sources, compressing development timelines for new hyperscale campuses.
Growth Catalysts
- Submarine Cable Expansion:New landing stations in New Taipei and Taichung are reducing latency to Southeast Asian cloud regions. Hyperscalers anchor build decisions to these cable convergence points.
- Electricity Act Amendments:Renewable energy procurement mandates under Taiwan's Bureau of Energy rules are accelerating corporate power purchase agreements. Data center operators secure long-term green tariffs to satisfy carbon accounting requirements.
- AI Compute Demand:GPU-intensive training workloads from domestic semiconductor design houses are driving demand for high-density halls. Rack densities above 30kW now dominate new construction specifications.
Market Restraints
- Land Scarcity:Industrial zoned parcels suitable for 50MW+ facilities concentrate in Taipei and Taichung corridors. Competition from semiconductor fabrication plants elevates land acquisition costs.
- Skilled Labor Bottleneck:Taiwan's construction sector faces acute shortages of MEP engineers certified for mission-critical infrastructure. Project timelines extend 15-20% due to workforce constraints.
- Grid Interconnection Queues:Taipower's transmission upgrade schedules create 18-24 month delays for facilities exceeding 100MW demand. Developers pre-commit to substation investments to secure queue position.
Strategic Opportunities
- Modular Prefabrication:Factory-built power and cooling modules compress on-site construction windows. International EPC contractors are establishing Taiwan manufacturing partnerships to localize supply.
- Kaohsiung Secondary Market:Southern Taiwan's underdeveloped data center corridor offers land cost advantages. Submarine cable diversity through alternative landing points reduces seismic concentration risk.
- Waste Heat Recovery:District heating integration with nearby industrial parks creates secondary revenue streams. Municipal governments in Taoyuan pilot thermal export frameworks for data center operators.
Industry Challenges
- Commissioning Complexity:Integrated systems testing for concurrent maintainability requires specialized commissioning agents. Taiwan's limited pool of Tier III/IV certified engineers creates project bottlenecks.
- Legacy Cooling Retrofit:Existing facilities designed for 10-15kW racks face stranded asset risk. Operators balance partial liquid cooling deployment against full reconstruction economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Data Center Construction Market |
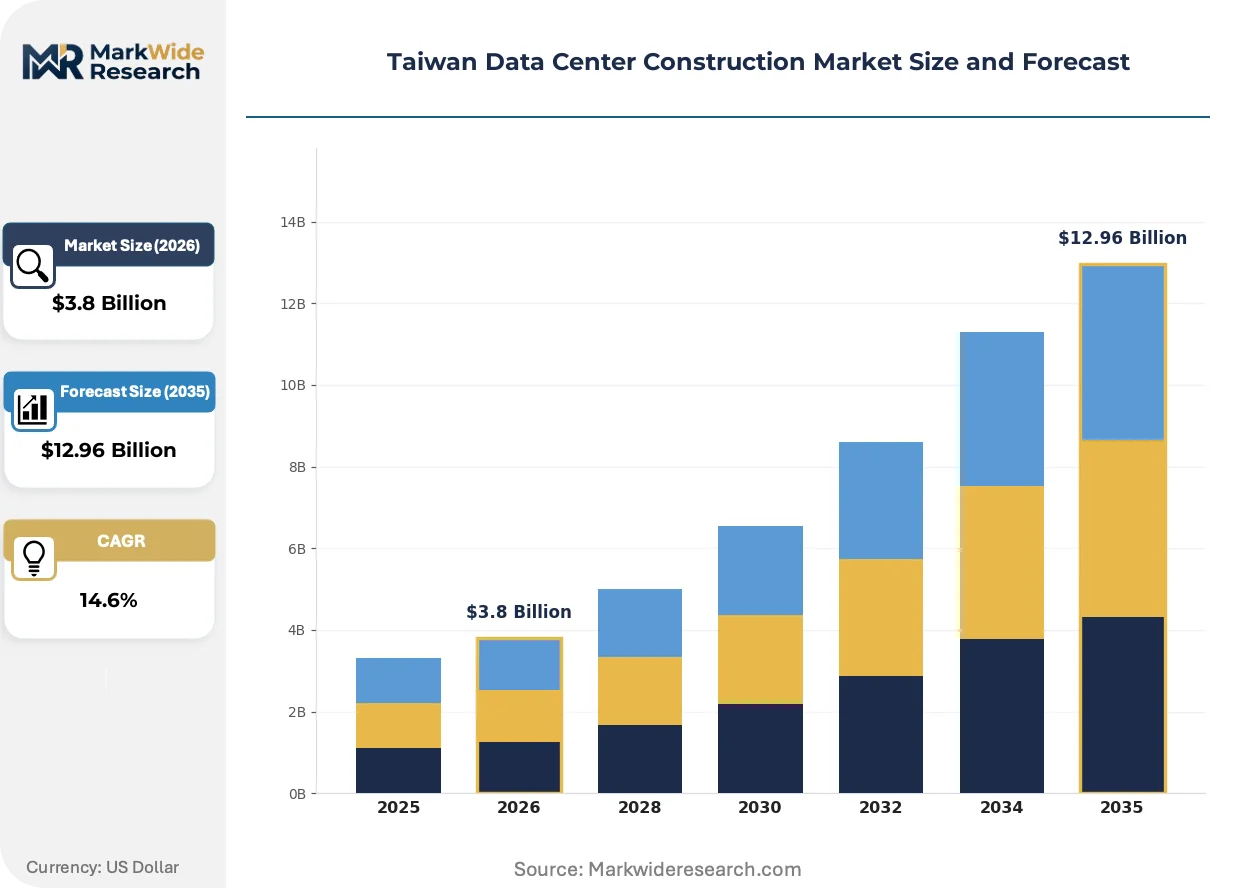
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Enterprise Data Centers, Colocation Facilities, Hyperscale Data Centers, Edge Data Centers Cooling Technology: Air Cooling, Liquid Cooling, Evaporative Cooling, Immersion Cooling Power Source: Grid Power, Renewable Energy, Backup Generators, Battery Storage Building Structure: Modular Design, Raised Floor, Containerized, Traditional Buildings |
| Companies Covered | TECO Corporation, CTCI Group, Exyte, AECOM, M+W Group, United Integrated Services, MAA Group, Pacific Engineers and Constructors, Ruentex Engineering and Construction, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Data Center Construction Market Trends and Innovations
Liquid cooling architectures and AI-driven facility management systems are compressing capital deployment cycles while reshaping operator skill requirements across Taiwan's data center pipeline.
Immersion cooling systems using dielectric fluids are automating thermal management for AI training clusters. Domestic cloud providers and international hyperscalers are piloting single-phase and two-phase immersion in Taoyuan facilities. This technology is automating the elimination of mechanical refrigeration for racks above 75kW, reducing mechanical complexity and water consumption in Taiwan's subtropical climate.
Taiwan's Bureau of Standards, Metrology and Inspection has tightened building energy codes affecting cooling system efficiency thresholds. New construction must demonstrate 15% improvement over baseline power usage effectiveness metrics. Hyperscale operators are responding with advanced economizer designs and machine learning-based cooling optimization to satisfy pre-occupancy compliance verification.
Design-build contracts are displacing traditional bid-build procurement for facilities above 20MW. Enterprise buyers and cloud operators now consolidate architecture, engineering, and construction under single-source accountability to compress 18-month schedules. This shift is most visible in Taipei and Taichung where land holding costs and power interconnection delays create schedule pressure.
Taiwan Data Center Construction Market Segmentation

Taiwan data center construction segments reflect divergent compliance burdens across facility scale and mission-critical specifications. Certification requirements from the Bureau of Standards, Metrology and Inspection and Taipower interconnection standards create tiered approval timelines that reshape procurement strategies for each segment category.
Facility Type:
Certification burdens escalate with facility scale, with hyperscale campuses requiring multi-agency coordination across the National Communications Commission for cable landing security and the Bureau of Energy for renewable procurement verification.
- Hyperscale Data Centers:These facilities exceed 50MW of critical IT load and demand concurrent maintainability certification under Tier III/IV standards. Taipei and Taichung corridors concentrate development where submarine cable access intersects with Taipower transmission capacity.
- Enterprise Data Centers:Single-tenant facilities serving domestic semiconductor design houses and financial institutions typically range 5-20MW. Corporate buyers prioritize proximity to headquarters in Hsinchu Science Park and Neihu Technology Park over hyperscale economics.
- Colocation Facilities:Multi-tenant environments offering rack-level leasing to mid-market enterprises and cloud resellers. Operators compete on cross-connect density to domestic carriers Chunghwa Telecom and Far EasTone.
- Edge Data Centers:Sub-1MW deployments positioned for ultra-low latency to manufacturing IoT networks and autonomous vehicle testing zones. Taoyuan and Tainan industrial clusters drive modular prefabrication demand.
Leading the category by volume: Hyperscale Data Centers. Growing fastest: Edge Data Centers.
Cooling Technology:
Cost tiers separate legacy mechanical systems from emerging liquid architectures, with capital intensity doubling between air-cooled baseline and immersion-cooled AI training halls.
- Liquid Cooling:Direct-to-chip and rear-door heat exchanger systems address rack densities above 30kW. Domestic cloud providers and international hyperscalers mandate liquid cooling specifications for new Taoyuan builds to support GPU-intensive training clusters.
- Immersion Cooling:Single-phase and two-phase dielectric fluid systems eliminate mechanical refrigeration for racks exceeding 75kW. Pilot deployments in Taipei facilities demonstrate 40% reduction in mechanical complexity versus traditional chilled water plants.
- Air Cooling:Raised-floor perimeter CRAC units remain standard for legacy enterprise facilities under 15kW per rack. Operators face stranded asset risk as density requirements escalate.
- Evaporative Cooling:Adiabatic and wetted media systems exploit Taiwan's subtropical humidity patterns. Taichung facilities integrate evaporative economizers to satisfy Bureau of Energy efficiency thresholds with lower water consumption than full mechanical plants.
Dominating installed base: Air Cooling. Steepest expansion trajectory: Immersion Cooling.
Power Source:
Application context determines power architecture, with financial services demanding generator-backed resiliency while AI training clusters prioritize renewable procurement for carbon accounting.
- Renewable Energy:Corporate power purchase agreements under Electricity Act amendments now dominate hyperscale procurement. Developers secure 15-20 year green tariffs from offshore wind and solar projects to satisfy Bureau of Energy compliance.
- Grid Power:Taipower's 345kV transmission serves as primary feed for facilities under 50MW. Interconnection queues extending 18-24 months force early substation pre-commitment in Taipei and Taichung corridors.
- Backup Generators:Diesel and natural gas gensets provide N+1 resiliency for Tier III certification. Emissions regulations from the Environmental Protection Administration constrain fuel storage quantities and testing frequencies.
- Battery Storage:Lithium-ion and emerging sodium-ion systems bridge generator start sequences and enable peak shaving. Taoyuan pilots integrate battery storage with waste heat recovery for district heating export.
Primary procurement focus: Renewable Energy. Fastest policy-driven shift: Battery Storage.
Building Structure:
Customer type separates speed-to-market priorities, with cloud operators demanding modular compression while enterprise buyers favor traditional build-to-suit permanence.
- Modular Design:Factory-built power modules and cooling skids compress on-site construction by 40-60%. International EPC contractors establish Taiwan manufacturing partnerships to localize supply and evade skilled labor bottlenecks.
- Containerized:ISO-standard and custom-width containers enable rapid deployment for edge and tactical applications. Kaohsiung's underdeveloped data center corridor attracts containerized builds for seismic diversification.
- Raised Floor:Traditional plenum-based air distribution persists in legacy enterprise retrofits. Operators balance partial liquid cooling deployment against full reconstruction economics.
- Traditional Buildings:Reinforced concrete shell construction with custom MEP integration serves financial and government buyers. Extended commissioning timelines reflect integrated systems testing for concurrent maintainability.
Highest volume deployment: Modular Design. Gaining share fastest: Containerized.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's silicon wafer and advanced packaging substrate supply chains anchor data center construction demand. Submarine cable landing points and renewable energy zones determine facility siting across the island's metropolitan corridors.
Taipei Metro
Hyperscale operators anchor build decisions to New Taipei's cable landing stations for Southeast Asian connectivity. The National Communications Commission enforces physical security protocols around submarine cable infrastructure. Nangang Technology Park and Neihu Technology Park concentrate enterprise data center demand from domestic semiconductor design houses.
Taichung Corridor
Grid interconnection capacity and land availability attract 50MW-plus campus developments. Taipower's transmission upgrade schedules create 18-24 month delays, forcing early substation pre-commitment. Taichung's industrial zones compete with semiconductor fabrication plants for zoned parcels.
Taoyuan Science Park
AI training clusters exceeding 50kW per rack drive liquid cooling pilot deployments. The Bureau of Standards, Metrology and Inspection mandates 15% efficiency improvements over baseline power usage effectiveness metrics. Municipal governments pilot waste heat recovery frameworks for district heating export to nearby industrial parks.
Kaohsiung Secondary Market
Southern Taiwan's underdeveloped data center corridor offers land cost advantages over northern saturation. Alternative submarine cable landing points reduce seismic concentration risk. Containerized and modular builds dominate early-stage development.
Hsinchu Science Park
Enterprise data centers serving fabless semiconductor companies prioritize proximity to headquarters. Single-tenant facilities range 5-20MW with strict latency requirements for design workflow integration. Corporate buyers favor traditional build-to-suit permanence over speed-to-market compression.
Taiwan Data Center Construction Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular prefabrication and liquid cooling specialization. The market structures around three tiers: electromechanical manufacturers with power infrastructure depth, industrial construction conglomerates with EPC execution scale, and international specialists with cleanroom expertise. Competitive moves concentrate on design-build contract consolidation and Taiwan manufacturing partnerships to localize supply chains.
Within the electromechanical tier, TECO Corporation anchors domestic power infrastructure supply. CTCI Group exemplifies large-scale EPC execution through its industrial construction presence. Exyte occupies a position among international cleanroom specialists transferring controlled-environment expertise to high-specification data hall builds.
| Leading Market Players |
|---|
| TECO Corporation |
| CTCI Group |
| Exyte |
| AECOM |
| M+W Group |
| United Integrated Services |
| MAA Group |
| Pacific Engineers and Constructors |
| Ruentex Engineering and Construction |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud operators and domestic semiconductor design houses concentrate procurement decisions among fewer than fifteen active buyers, compressing margin pools and forcing EPC contractors toward design-build consolidation and long-term service bundling to defend pricing power.
Pricing Analysis
Volume concentration among hyperscale campuses above 50MW separates thin-margin execution contracts from premium-tier integrated commissioning engagements. Three-tier pricing structure across Tier IV concurrent maintainability, Tier III redundant, and Tier II basic resiliency levels anchors differentiation, with certification grade and liquid cooling integration as primary price escalators. Cost compression in standard air-cooled builds intensifies as modular prefabrication localizes supply and compresses on-site labor exposure. Enterprise data center buyers in Hsinchu Science Park exhibit lowest price sensitivity due to proximity premiums, while colocation operators face acute margin pressure from cross-connect density competition.
Supply Chain Analysis
Regional distribution centers in Taoyuan and Taichung coordinate hub-and-spoke logistics for MEP equipment, with critical power infrastructure drawing from Taiwan, Japan, and Germany. Supply chains for diesel generators and precision cooling units rest on single-source vulnerabilities from European and Japanese OEMs. Tariff exposure on electrical switchgear and copper busbar assemblies creates cost volatility for projects with extended procurement windows. Distribution runs through Taipower-certified contractors for grid interconnection components, while factory-built modules bypass traditional construction material channels.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled MEP engineer scarcity and 18-24 month grid interconnection queues constrain deliverable capacity, propping pricing power for contractors with certified workforce depth and advance substation commitments.
For Market Incumbents: To counter modular prefabrication entrants eroding traditional EPC margins, anchor design-build contracts with 15-20 year O&M service attachments and deepen backward integration into power module manufacturing through Taoyuan production partnerships. For New Entrants and Emerging Players: Begin with Kaohsiung's underdeveloped southern corridor where land cost spreads and seismic diversification demand outstrip established contractor presence, targeting containerized edge deployments for manufacturing IoT networks with rapid-deployment value propositions. For Investors and Strategic Acquirers: The window for entry favors EPC specialists with Tier III/IV commissioning agent certification and advance Taipower queue positions; watch for Bureau of Energy renewable procurement rule tightening as inflection signal for stranded asset risk in fossil-dependent legacy facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Design-Build Contract Consolidation | Compresses 18-month delivery schedules by eliminating bid-build handoff friction in Taipei corridor. |
| Modular Manufacturing Localization | Establishes Taoyuan factory partnerships to evade skilled labor bottlenecks and reduce import exposure. |
| Liquid Cooling Integration | Captures 50kW-plus rack density premiums from AI training cluster demand in domestic cloud builds. |
| Renewable Power Purchase Agreements | Secures Bureau of Energy compliance for hyperscale campuses through 15-20 year offshore wind tariffs. |
| Waste Heat Recovery Infrastructure | Creates secondary revenue streams via district heating export to Taoyuan industrial parks under municipal pilot frameworks. |
Research Methodology
Multi-period observation of hyperscale capex commitments, Taipower interconnection queue lengths, and Bureau of Energy renewable procurement filings anchored the trend analysis, supplemented by interviews with data center development executives, EPC project directors, MEP engineering leads, and Taipower grid planning officers. Secondary validation drew from National Communications Commission submarine cable licensing records, Bureau of Standards building energy code filings, and corporate power purchase agreement disclosures. Bottom-up project pipeline aggregation triangulated against top-down construction spending estimates from industrial construction consortium reports.
Input-output matrices mapped facility type, cooling technology, and power source segments against construction cost intensity and regional land availability constraints throughout the projection horizon. CAGRs derived from installed base growth curves adjusted for grid interconnection delay probabilities and skilled labor supply elasticity. Forecast inputs incorporated Electricity Act amendment implementation timelines and immersion cooling technology adoption S-curves from pilot deployment data.
Underlying measurement precision varies by segment; hyperscale and enterprise facility categories carry tighter precision than emerging edge deployments due to disclosure transparency differences. Forecasts reflect documented assumptions on regulatory enforcement consistency and transmission upgrade schedule adherence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Australia Transportation Infrastructure Construction Market
Infrastructure Construction
Composite Railroad Tie Market
Infrastructure Construction
United States Transportation Infrastructure Construction Market
Infrastructure Construction
Vietnam Data Center Construction Market
Infrastructure Construction
US Pipeline Construction Market
Infrastructure Construction
Transmission and Distribution Infrastructure Market
Infrastructure Construction
Aerial Cable Car Equipment Market
Infrastructure Construction
Road & Highway Infrastructure Market
Infrastructure Construction
India Transportation Infrastructure Market
Infrastructure Construction
Offshore Pipeline Infrastructure Market
Infrastructure Construction
India Transportation Infrastructure Construction Market
Infrastructure Construction
Qatar Infrastructure Sector Market
Infrastructure Construction
Ship Port Infrastructure Market
Infrastructure Construction
Switzerland Transportation Infrastructure Construction Market
Infrastructure Construction
Russia Transportation Infrastructure Construction Market
Infrastructure Construction
China Transportation Infrastructure Construction Market