
 India Transportation Infrastructure Construction Market | 2026-2036
India Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
India Transportation Infrastructure Construction Market Foresight
Specialized bridge engineering and tunneling labor pools is reorganizing project execution timelines across India's transportation construction sector. Larsen & Toubro dominates complex EPC contracts for elevated corridors and underground metro systems. AFCONS Infrastructure anchors marine and coastal infrastructure with deep expertise in port modernization and sea-link construction. Tata Projects sustains integrated delivery models spanning design, procurement, and commissioning for greenfield airport developments.
India transportation infrastructure construction encompasses the planning, engineering, and physical assembly of mobility assets including highways, rail networks, aviation facilities, and maritime terminals, typically involving concrete grades of M40-M60 for bridge superstructures, hot-mix asphalt with polymer modified binders for flexible pavements, and structural steel conforming to BIS IS 2062 for elevated transit corridors. Roadways command the dominant share of annual award value given Bharatmala's phased corridor expansion, while railways is accelerating fastest as Dedicated Freight Corridors and Regional Rapid Transit Systems multiply steel and concrete procurement volumes. Cement and steel together constitute the bulk material cost stack, with margin pools concentrating in specialized geotechnical and structural steel fabrication sub-contracting where supply bottlenecks persist.
BIS mandates govern material quality certification for construction inputs, while the CEA coordinates power and utility clearances for electrified rail corridors, and state-level Public Works Departments enforce geometric design standards per IRC guidelines that shape contractor qualification thresholds and project bundling strategies. The Ministry of Housing and Urban Affairs Metro Rail Policy mandates minimum private participation ratios that restructure risk allocation in urban transit concessions. Stakeholders must monitor how NHAI's asset monetization pipeline and state-level hybrid annuity model refinements reshape contractor cash flow cycles and bidding discipline.
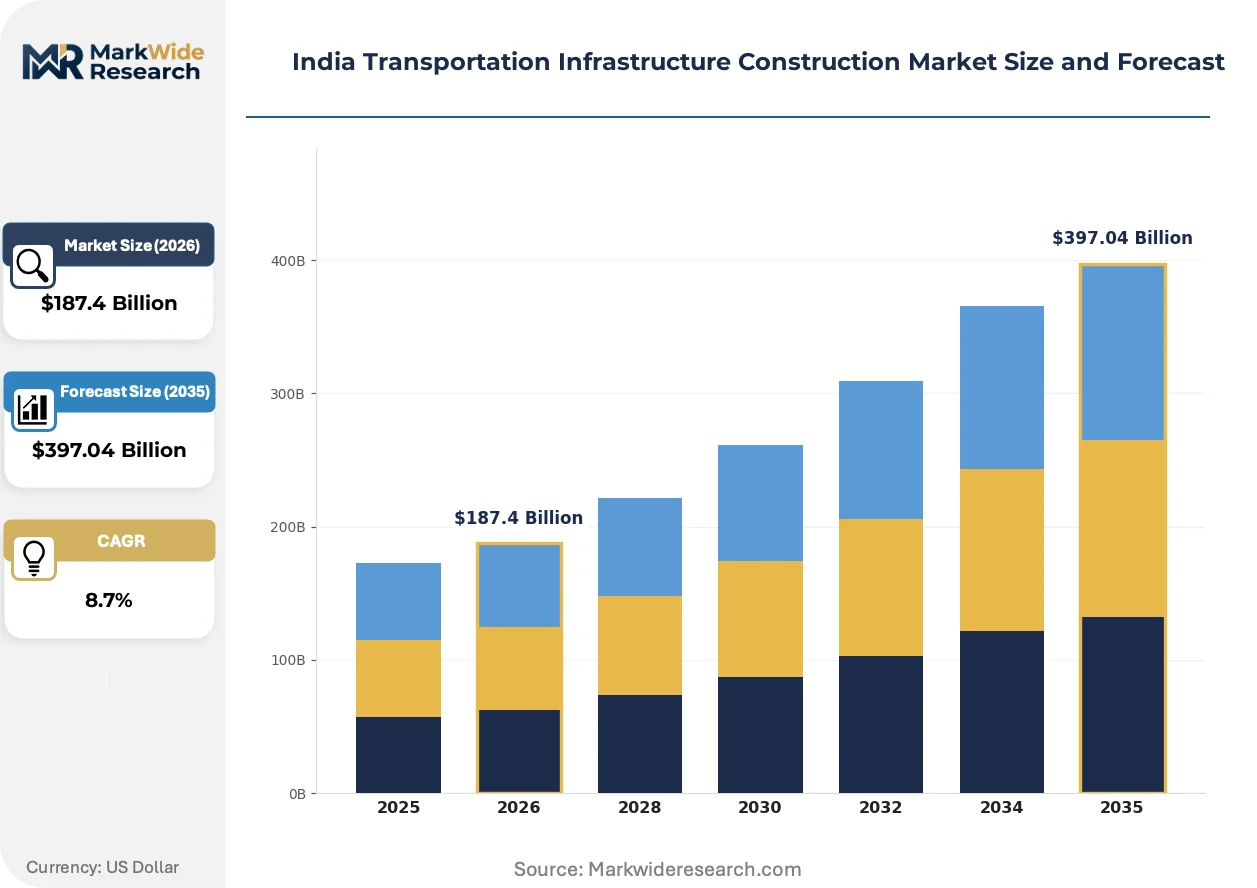
Market Dynamics
Bharatmala Pariyojana's expressway corridor acceleration is compressing project award cycles and forcing contractors to restructure bidding consortiums around land acquisition risk pools. State-level hybrid annuity refinements are redistributing payment timelines, squeezing working capital buffers for mid-tier EPC firms.
Growth Catalysts
- Dedicated Freight Corridors:Indian Railways' steel-intensive freight network expansion is pulling cement and structural fabrication volumes into eastern and western corridor segments.
- CEA Utility Clearances:Streamlined power connectivity approvals for electrified rail corridors are collapsing commissioning delays on Regional Rapid Transit Systems.
- Maharashtra Cluster Concentration:Mumbai-Ahmedabad High-Speed Rail and Navi Mumbai International Airport are generating bundled contract opportunities for integrated civil-electrical-mechanical vendors.
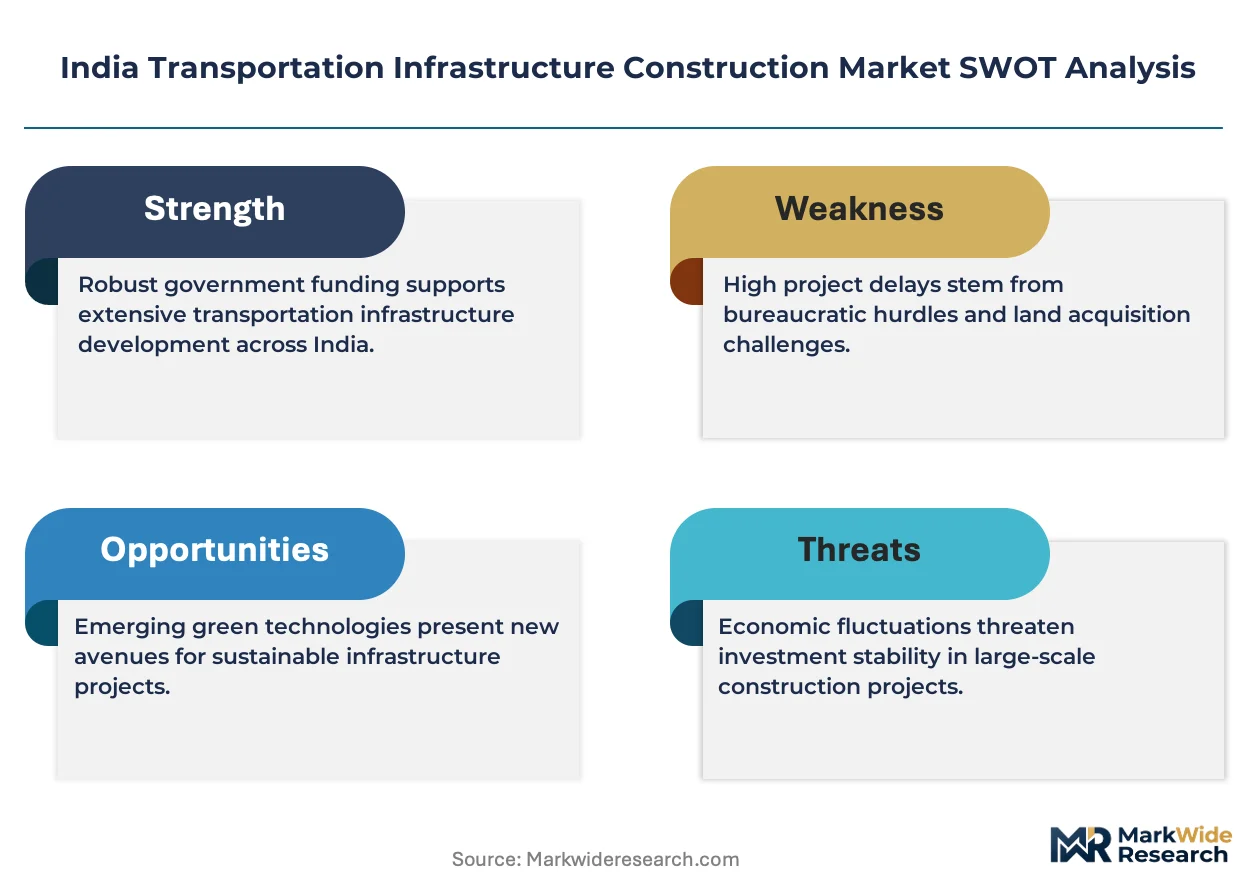
Market Restraints
- Cement-Steel Cost Stack Volatility:Bulk material input fluctuations compress margin pools for contractors locked into fixed-price EPC terms.
- Specialized Geotechnical Labor Scarcity:Tunneling and marine foundation expertise concentrates in Mumbai-Pune and Chennai corridors, creating bottleneck premiums.
- BIS Certification Friction:Material quality verification protocols for M60-grade concrete and polymer-modified asphalt extend procurement lead times.
Strategic Opportunities
- Last-Mile Metro Connectivity:State governments in Karnataka and Telangana are expanding capital allocations for feeder bus-integrated station precincts.
- PLI Scheme Tailwinds:Domestic manufacturing incentives for construction equipment and rolling stock components are reshaping supplier qualification criteria.
- Greenfield Airport Privatization:Brownfield expansion at secondary cities is opening design-build-operate concessions with extended concession periods.
Industry Challenges
- Bridge Superstructure Engineering Talent Gap:Segmental construction and cable-stayed design expertise remains concentrated among legacy public sector consultancy pools.
- IRC Geometric Standard Compliance:State Public Works Departments enforce varying interpretation of design guidelines, fragmenting contractor pre-qualification thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Transportation Infrastructure Construction Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Roadways, Railways, Airports, Seaports Material Used: Cement, Steel, Asphalt, Aggregate Investment Source: Public Sector, Private Sector, PPP, International Funding Construction Method: Traditional, Modular, Prefabrication, In-situ |
| Companies Covered | GMR Group, Shapoorji Pallonji and Company, Larsen & Toubro, NKC Projects Private Limited, NCC Limited, Tata Projects, Hindustan Construction Company, AFCONS Infrastructure, Reliance Infrastructure, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Transportation Infrastructure Construction Market Shifts & Advancements
Digital twin deployment and prefabricated structural systems are compressing traditional civil construction timelines. Material science advances and policy mandates are forcing recalibration of procurement and execution protocols across highway, rail, and aviation verticals.
Building Information Modeling integrated with drone-based topographic surveying is decomposing traditional survey-to-design handoff sequences. NHAI and state highway authorities are mandating BIM deliverables for expressway packages above threshold contract values. This convergence is collapsing preliminary engineering duration and compressing contractor mobilization windows.
Ministry of Housing and Urban Affairs Metro Rail Policy mandates are tightening private participation ratios and restructuring risk allocation in urban transit concessions. Minimum equity lock-in requirements and ridership guarantee frameworks are shifting financial closure complexity onto concessionaire consortia. Maharashtra and Karnataka urban development authorities are adapting concession templates to absorb these revised terms.
Asset monetization through InvIT structures is displacing traditional annuity-based contractor payment cycles. NHAI's toll-operate-transfer pipeline is attracting institutional capital into operational highway portfolios, freeing fiscal space for greenfield awards. This capital rotation is most visible in Gujarat and Rajasthan corridor segments where operational asset density supports scale pooling.
India Transportation Infrastructure Construction Market Segmentation
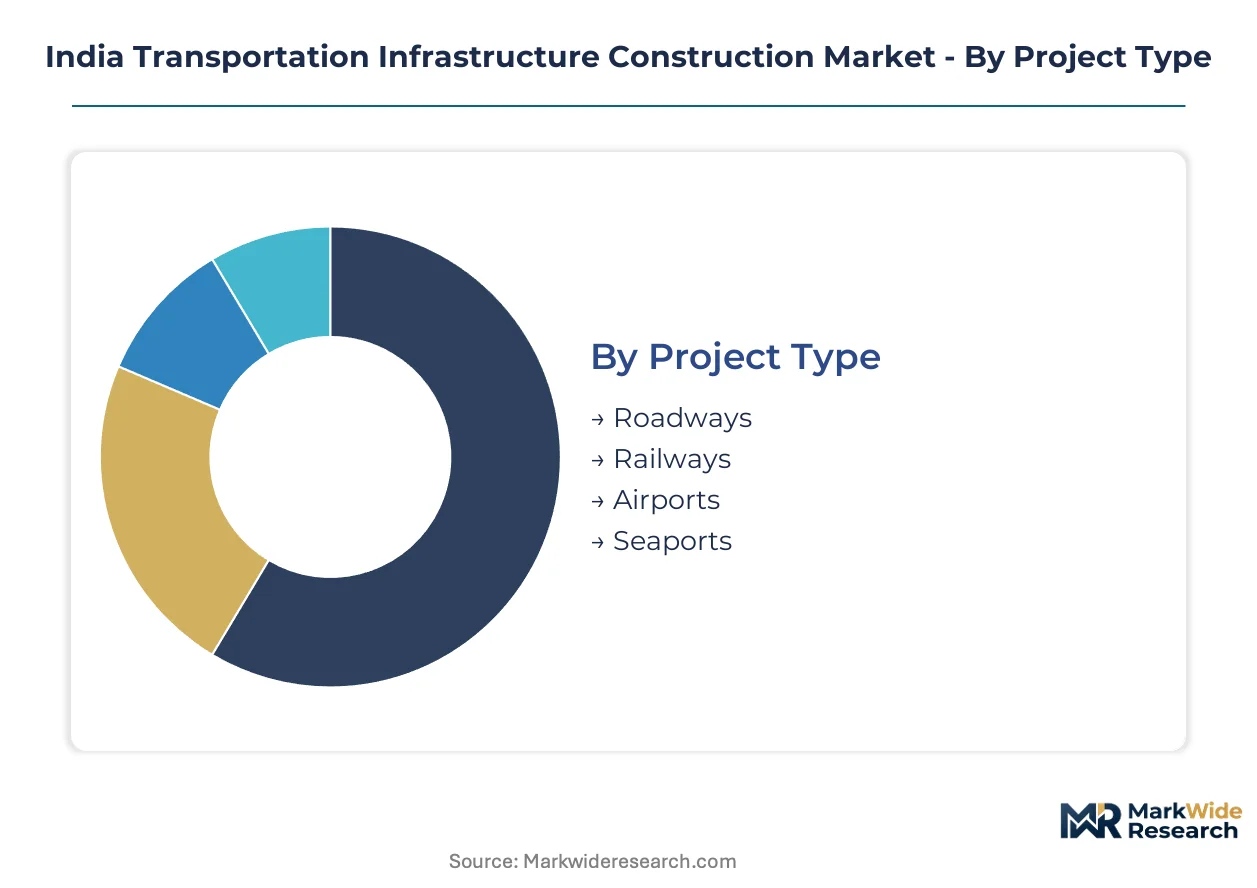
Segmentation in India's transportation infrastructure construction reveals how capital allocation, material procurement, and execution methodologies diverge across project archetypes. Understanding these fault lines exposes where contractor capabilities, financing structures, and regulatory compliance requirements cluster.
Project Type:
Margin pools concentrate in integrated multimodal developments where civil, electrical, and mechanical scopes bundle into single contract vehicles.
- Roadways:Expressway and highway construction consumes polymer-modified asphalt and M40-grade concrete for bridge superstructures under Bharatmala Pariyojana. Demand clusters in Gujarat and Rajasthan where NHAI's asset monetization pipeline accelerates greenfield awards through InvIT capital rotation.
- Railways:Steel-intensive corridor development spans Dedicated Freight Corridors and Regional Rapid Transit Systems with electrified traction infrastructure. Maharashtra and Karnataka urban development authorities absorb Ministry of Housing and Urban Affairs mandates for private participation ratios and ridership guarantees.
- Airports:Greenfield aviation facilities and brownfield expansions at secondary cities operate under design-build-operate concessions with extended concession periods.
- Seaports:Marine and coastal infrastructure modernization drives demand for deep foundation expertise and sea-link construction capabilities.
The dominant share belongs to Roadways, while Railways is expanding most quickly as steel and concrete procurement volumes multiply across eastern and western corridor segments.
Material Used:
Cost tier stratification separates bulk commodity inputs from specialized formulations where BIS certification friction extends procurement lead times.
- Cement:M60-grade concrete formulations for bridge superstructures and tunnel linings face quality verification bottlenecks under BIS protocols. Demand concentrates in Mumbai-Pune and Chennai corridors where specialized geotechnical labor scarcity creates bottleneck premiums.
- Steel:Structural fabrication conforming to BIS IS 2062 supplies elevated transit corridors and freight rail infrastructure. Maharashtra's Mumbai-Ahmedabad High-Speed Rail and Navi Mumbai International Airport generate bundled contract opportunities for integrated vendors.
- Asphalt:Polymer-modified binders for flexible pavements serve expressway packages above threshold contract values where NHAI mandates BIM deliverables.
- Aggregate:Crushed stone and sand inputs support sub-base and base course layers across highway and airport runway construction.
Cement commands the dominant share given Bharatmala's phased corridor expansion, while Steel is climbing the fastest as freight network electrification intensifies.
Investment Source:
Customer type determines risk allocation structures and payment timeline compression that reshape contractor cash flow cycles.
- Public Sector:Central government allocations through NHAI and Indian Railways fund Bharatmala and Dedicated Freight Corridor development with traditional annuity-based disbursements.
- Private Sector:Domestic manufacturing incentives under PLI schemes reshape supplier qualification criteria for construction equipment and rolling stock components.
- PPP:Hybrid annuity model refinements redistribute payment timelines, squeezing working capital buffers for mid-tier EPC firms locked into fixed-price terms.
- International Funding:Multilateral development finance supports high-speed rail and metro rail networks with extended concession periods and equity lock-in requirements.
Public Sector retains the dominant share, while PPP is gaining share fastest as state governments restructure concession templates to absorb revised risk allocation terms.
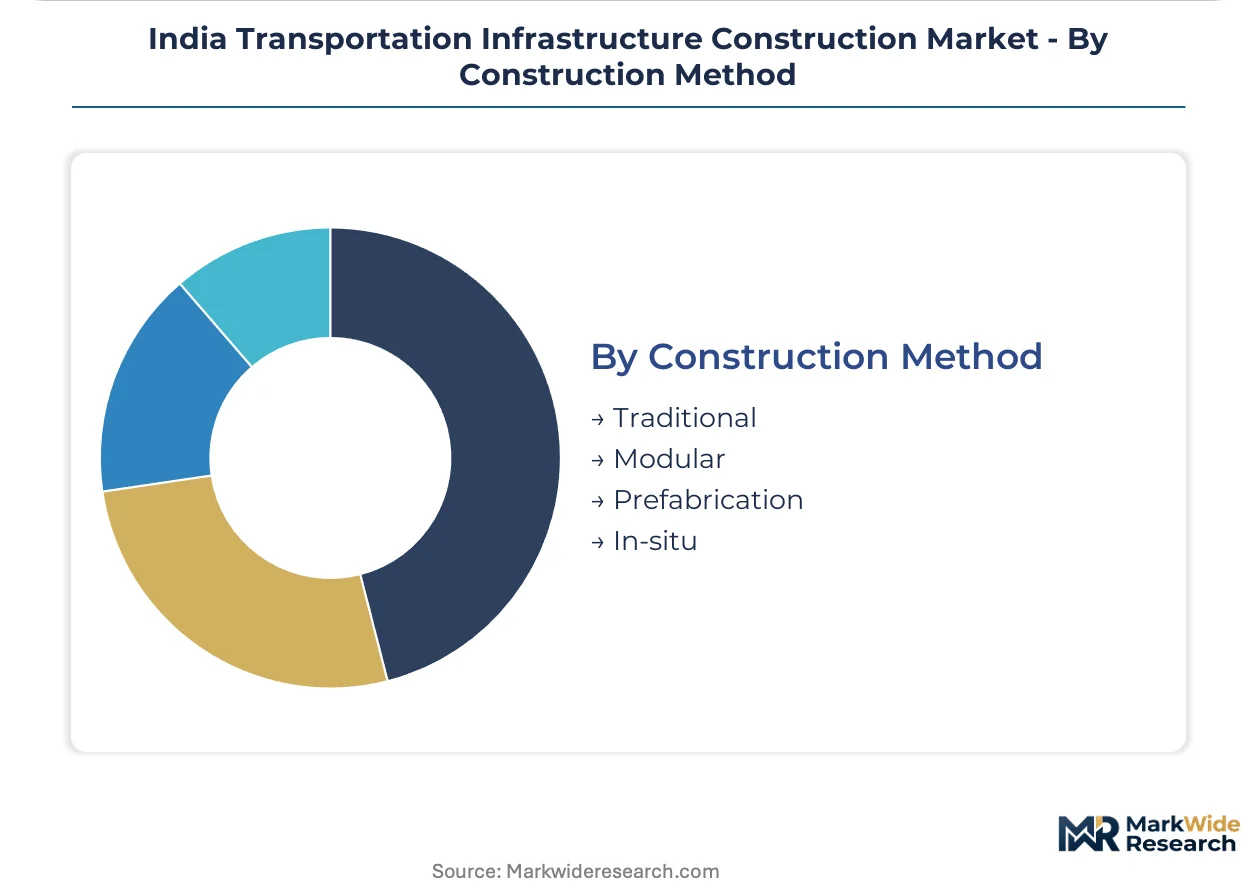
Construction Method:
Maturity gradients separate legacy execution protocols from digital-integrated approaches where drone-based surveying collapses preliminary engineering duration.
- Traditional:Cast-in-place concrete and incremental launching methods persist in state Public Works Department contracts where IRC geometric standard interpretation varies.
- Modular:Prefabricated bridge elements and standardized superstructure components compress mobilization windows for expressway packages.
- Prefabrication:Factory-controlled structural systems reduce site labor dependency and accelerate elevated corridor assembly timelines.
- In-situ:Tunnel boring machine deployment and segmental construction remain concentrated among legacy public sector consultancy pools with scarce technical talent.
Traditional methods hold the dominant share, while Prefabrication is accelerating fastest as BIM-integrated procurement protocols mandate digital deliverables.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CEA utility clearance protocols anchor Maharashtra's dominance in electrified rail corridor development. State-level hybrid annuity refinements redistribute payment timelines across sub-national markets.
Maharashtra
Mumbai-Ahmedabad High-Speed Rail and Navi Mumbai International Airport generate bundled contract opportunities for integrated civil-electrical-mechanical vendors. The Ministry of Housing and Urban Affairs Metro Rail Policy mandates minimum private participation ratios that restructure risk allocation in Mumbai and Pune urban transit concessions. Mumbai-Pune corridor concentration creates bottleneck premiums for specialized geotechnical and tunneling labor pools.
Gujarat
Operational highway asset density supports scale pooling through NHAI's toll-operate-transfer pipeline under InvIT structures. Bharatmala Pariyojana expressway packages accelerate greenfield awards where polymer-modified asphalt demand concentrates. Ahmedabad-Surat industrial belt absorbs cement and steel procurement volumes for corridor expansion.
Karnataka
Bengaluru Metro Phase extensions and Regional Rapid Transit Systems pull structural steel conforming to BIS IS 2062 into southern corridor segments. State government capital allocations expand for feeder bus-integrated station precincts under last-mile connectivity mandates. Bengaluru urban development authority adapts concession templates to absorb revised private participation terms.
Tamil Nadu
Chennai metro rail network expansion and port modernization drive demand for marine foundation expertise and sea-link construction capabilities. BIS certification friction for M60-grade concrete extends procurement lead times for bridge superstructure contracts. Chennai coastal corridor concentration mirrors specialized labor scarcity patterns visible in Mumbai-Pune belt.
Telangana
Hyderabad metro rail extensions and greenfield airport brownfield expansions open design-build-operate concessions with extended concession periods. PLI scheme tailwinds reshape supplier qualification criteria for construction equipment procurement. Hyderabad urban agglomeration represents emerging demand concentration outside traditional western corridor dominance.
India Transportation Infrastructure Construction Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated control over complex EPC contracts for elevated corridors and underground metro systems. Mid-tier firms cluster around discrete material supply and sub-contracting scopes where BIS certification bottlenecks persist. Two strategic archetypes dominate: vertically integrated conglomerates with captive cement and steel sourcing, and specialized geotechnical contractors with tunnel boring machine deployment expertise. Competitive moves concentrate on hybrid annuity model bidding consortium restructuring and asset monetization partnership formation with institutional capital pools.
Among India-based integrated infrastructure developers, Larsen & Toubro and Tata Projects exemplify the conglomerate archetype with design-procurement-commissioning capabilities spanning greenfield airport and rail verticals. AFCONS Infrastructure occupies a specialist position representing marine and coastal infrastructure expertise concentrated in port modernization and sea-link construction. GMR Group anchors the airport concessionaire vector with extended concession period structures at secondary city brownfield expansions. These three firms sit within distinct capability tiers rather than direct overlap, reflecting market segmentation by project complexity and financing structure.
| Leading Market Players |
|---|
| GMR Group |
| Shapoorji Pallonji and Company |
| Larsen & Toubro |
| NKC Projects Private Limited |
| NCC Limited |
| Tata Projects |
| Hindustan Construction Company |
| AFCONS Infrastructure |
| Reliance Infrastructure |
| Others |
Supply & Pricing Matrix
Ninety-day cement inventory cycles at Maharashtra batching plants concentrate procurement leverage among integrated conglomerates with captive clinker sourcing, compressing margin pools for spot-market-dependent mid-tier contractors locked into fixed-price EPC terms. This lead-time asymmetry between bulk commodity inputs and specialized geotechnical sub-contracting creates divergent pricing power across the material cost stack.
Pricing Analysis
Mumbai-Pune corridor contractors command 15-20% premia over Gujarat highway developers for equivalent M60-grade concrete specifications, reflecting specialized labor scarcity and BIS certification friction in western Maharashtra. Project-based long-term offtake contracts dominate, with price differentiation anchored in cement grade certification and structural steel fabrication complexity. Cost compression in standard-grade asphalt intensifies as NHAI's InvIT capital rotation accelerates greenfield awards, squeezing working capital buffers. Tier-1 EPC firms with backward-integrated material sourcing exhibit lowest price sensitivity; mid-tier bidders on hybrid annuity terms face acute margin pressure.
Supply Chain Analysis
Forty-five day polymer-modified binder lead times from Gujarat refineries tether expressway procurement schedules to coastal petrochemical corridor capacity. Supply draws from India, China, and South Korea for structural steel conforming to BIS IS 2062, with cement clinker sourcing concentrated in Rajasthan and Madhya Pradesh limestone belts. Single-source vulnerability persists in tunnel boring machine spares and specialized geotechnical instrumentation. Distribution runs through state-level Public Works Department tendering platforms and NHAI's centralized e-procurement portal.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Operations and maintenance service contracts for electrified rail corridors and airport concessions are expanding faster than civil construction hardware, creating recurring-revenue attach opportunities that reshape contractor valuation multiples. This service-layer acceleration justifies capability investments in predictive asset management and digital twin deployment.
For Market Incumbents: Fortify captive cement and steel sourcing through Rajasthan clinker belt capacity additions, insulating margin pools from bulk material volatility. Deepen tunnel boring machine deployment expertise through Chennai and Mumbai-Pune labor pool consolidation, defending against emerging geotechnical specialists. Prioritize BIS certification pre-positioning for M60-grade concrete formulations to compress procurement lead times.
For New Entrants and Emerging Players: Differentiate on drone-integrated BIM deliverables for expressway packages above NHAI threshold values, where digital competency gaps persist among legacy contractors. Target Telangana and Karnataka feeder bus-integrated station precincts, the most penetrable last-mile connectivity segment. Pursue design-build-operate concession partnerships with state urban development authorities as the primary go-to-market angle.
For Investors and Strategic Acquirers: Carve-out targets emerge from public sector consultancy pools with concentrated segmental construction and cable-stayed design expertise, stranded by hybrid annuity model refinements. Long-term viability centers on contractors with demonstrated InvIT partnership formation and operational highway asset management capabilities. Monitor NHAI's toll-operate-transfer pipeline velocity as the inflection signal for greenfield award acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Clinker Sourcing | Rajasthan limestone belt capacity secures margin insulation against cement price volatility. |
| BIM-Integrated Drone Surveying Deployment | NHAI-mandated deliverables collapse preliminary engineering duration for expressway bids. |
| Tunnel Boring Machine Fleet Expansion | Mumbai-Pune and Chennai corridor concentration addresses specialized geotechnical labor scarcity. |
| InvIT Partnership Formation | Gujarat and Rajasthan operational asset pooling attracts institutional capital rotation. |
| Operations and Maintenance Service Layer Buildout | Electrified rail corridor concessions generate recurring revenue beyond construction completion. |
Research Methodology
Initial hypotheses were tested against primary input from NHAI project directors, state Public Works Department engineers, EPC contractor procurement heads, and cement batching plant operations managers, and refined through secondary validation against Indian Railways annual reports, BIS certification databases, and state urban development authority concession documents. Bottom-up project pipeline aggregation triangulated with top-down central government budget allocation analysis.
Variance decomposition across project type, material grade tier, construction methodology, and state-level regulatory framework shaped the analytical framework over the projection horizon. CAGRs derived from award value trajectory modeling and execution timeline compression factors, with cement-steel cost stack volatility and hybrid annuity payment timeline refinements as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained Bharatmala corridor acceleration and CEA utility clearance streamlining would require recalibration. Forecasts reflect documented assumptions regarding land acquisition protocol efficiency and state-level fiscal capacity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Steel Utility Poles Market
Infrastructure Construction
Transmission and Distribution Infrastructure Market
Infrastructure Construction
Global Port Infrastructure Market
Infrastructure Construction
Mexico Data Center Construction Market
Infrastructure Construction
Docks Market
Infrastructure Construction
Qatar Infrastructure Sector Market
Infrastructure Construction
Taiwan Data Center Construction Market
Infrastructure Construction
Pipeline Construction Market
Infrastructure Construction
Italy Transportation Infrastructure Construction Market
Infrastructure Construction
North America Pipeline Maintenance Market
Infrastructure Construction
Oil and Gas Pipeline Fabrication and Construction Market
Infrastructure Construction
United States Transportation Infrastructure Construction Market
Infrastructure Construction
Oman Transportation Infrastructure Construction Market
Infrastructure Construction
Middle East Pipeline Construction Market
Infrastructure Construction
Brazil Data Center Construction Market
Infrastructure Construction
India Transportation Infrastructure Market