
 South America Anchors and Grouts Market | 2026-2036
South America Anchors and Grouts Market Size, Share, and Industry Trends Forecast 2026-2036
South America Anchors and Grouts Market Analytics
Technical support and application engineering services is rebalancing how anchor and grout solutions are sold in South America, shifting transactions from commodity hardware to performance-guaranteed systems. Sika AG leverages its certified applicator networks to lock in specification control on major infrastructure bids. MAPEI SpA anchors its position through localized manufacturing in Brazil that reduces import dependency and shortens lead times. BASF SE differentiates via R&D intensity in epoxy-modified grout formulations tailored to seismic zones.
Anchors and grouts encompass mechanical fastening devices and cementitious or resin-based bonding materials engineered to specified compressive strengths, typically ranging from 50 to 100 MPa for structural grouts, designed to transfer loads between structural elements and substrates in civil and industrial applications. The primary commercial purpose centers on ensuring structural integrity in concrete repair, new construction, and rock stabilization where dynamic or static loads exceed substrate capacity. Chemical anchors command margin pools due to specification-driven procurement in seismic-rated projects across the Andean region. Mechanical anchors retain volume leadership in standard construction applications where cost sensitivity dominates contractor selection. Grouting systems represent the fastest-growing category as tunneling and mining activity intensifies in Chile, Peru, and Colombia.
ABNT, the Brazilian national standards body, mandates compliance with NBR 15575 for structural performance, directly shaping product certification requirements and market access conditions for imported systems. ANVISA regulates chemical components in resin grouts, while Chile's Ministerio de Obras Públicas enforces specific anchoring standards for public infrastructure that favor technically validated suppliers. Peru's SENCICO technical norms similarly constrain unproven entrants on state-funded mining and hydroelectric projects. Stakeholders must monitor evolving national content requirements and local certification timelines as procurement rules tighten across the region's largest public works programs.
Market Dynamics
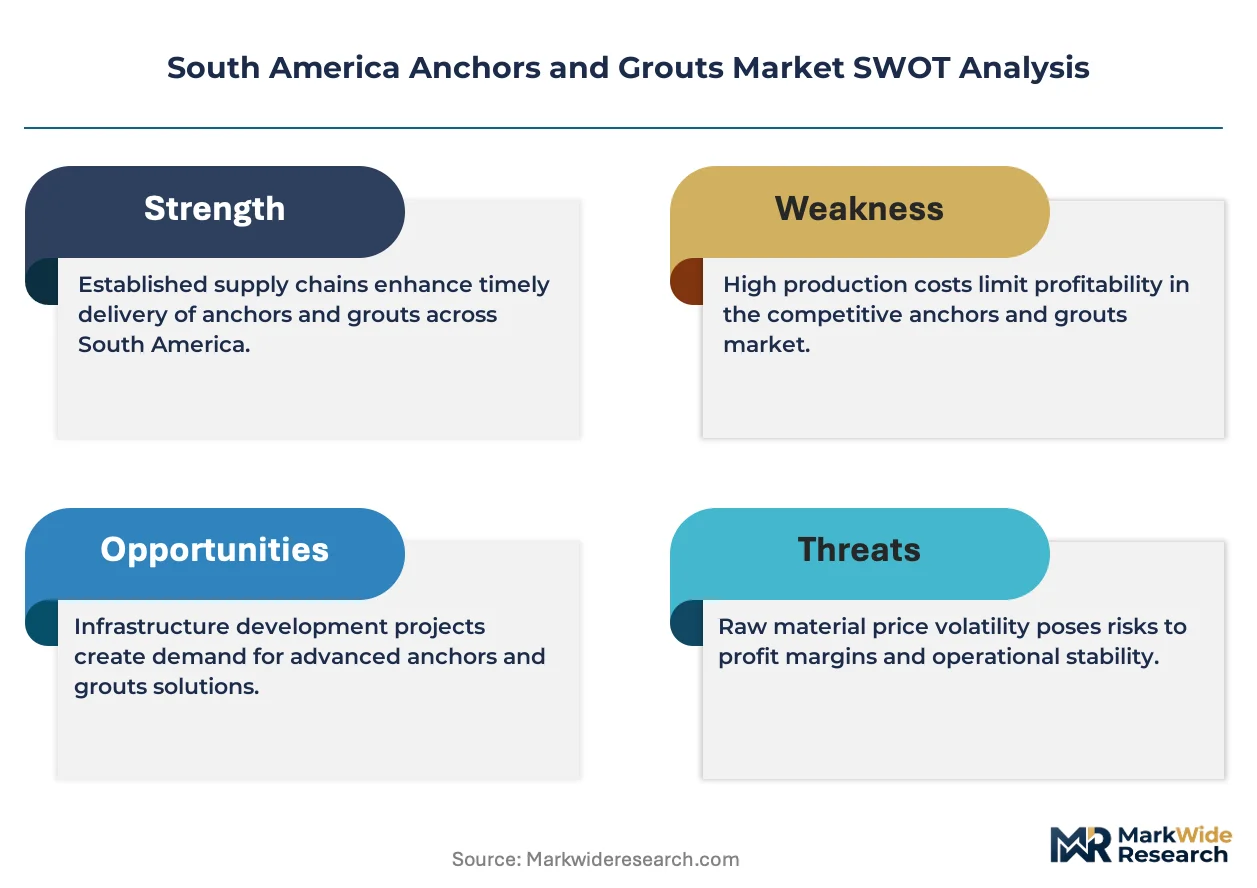
Resin-based anchoring systems are displacing mechanical fasteners in South American underground mining as operators face deeper extraction depths and seismic loading requirements that exceed traditional capacity.
Growth Catalysts
- ABNT NBR 15575 structural mandates:Brazil's updated performance standards for residential and commercial buildings are forcing specification upgrades to high-strength cementitious grouts.
- Chilean copper extraction depths:Underground operations below 1,000 meters require resin anchors rated for dynamic rockburst conditions.
- Colombian hydroelectric expansion:Tunneling activity for run-of-river projects is generating specification-grade demand for injection grouting systems.
Market Restraints
- Import dependency for epoxy formulations:Specialty hardeners and modifiers concentrate in European and Asian supply bases, exposing buyers to currency volatility and extended lead times.
- Specialized applicator certification gaps:Proper installation of chemical anchors requires trained technicians, and qualified labor pools remain thin outside São Paulo and Santiago.
- Cement price volatility:Structural grouts depend on Portland cement and supplementary cementitious materials subject to energy-linked cost swings.
Strategic Opportunities
- Peruvian mining corridor infrastructure:State-funded projects under SENCICO norms favor technically validated suppliers with local testing capabilities.
- Seismic-rated retrofit demand:ABNT's evolving standards for existing building reinforcement create specification pathways for epoxy-modified systems.
- Digital specification platforms:Engineering firms are migrating anchor selection to BIM-integrated tools that lock in approved products early in design cycles.
Industry Challenges
- ANVISA chemical registration timelines:Resin grout formulations face extended approval cycles for new hardener chemistries, delaying product launches by 18-24 months.
- Field testing infrastructure scarcity:Validated pull-test equipment and certified laboratories concentrate in Brazil, complicating quality assurance for Andean projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Anchors and Grouts Market |
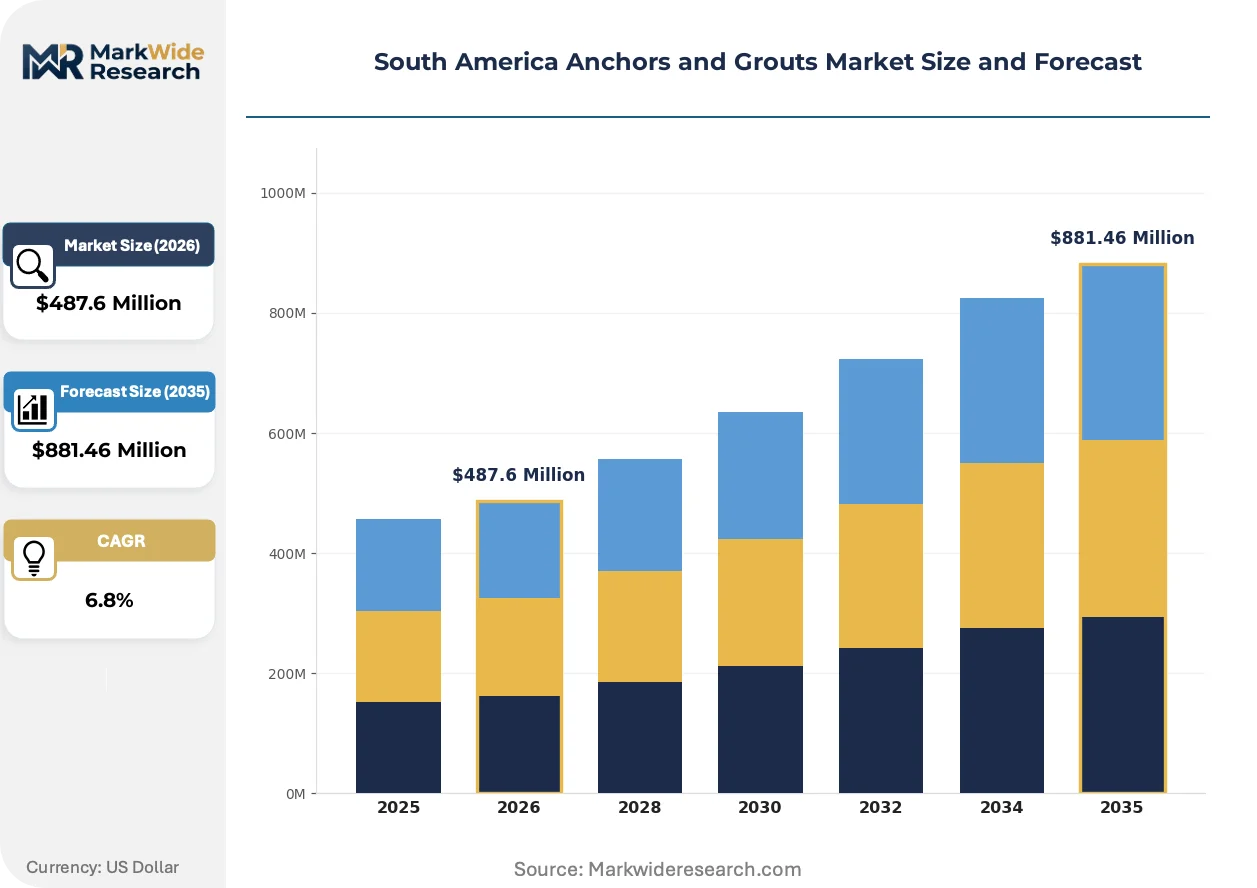
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Anchors, Chemical Anchors, Grouting Systems, Resin Grouts Application: Construction, Infrastructure, Mining, Marine End User: Contractors, Engineers, Equipment Manufacturers, Government Agencies Distribution Channel: Online Retail, Distributors, Direct Sales, Wholesalers |
| Companies Covered | Sika AG, MAPEI SpA, BASF SE, Hilti Corporation, Bostik, MBCC Group, Fosroc International Limited, GCP Applied Technologies, Five Star Products Inc, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Anchors and Grouts Market Evolving Landscape
Specification control is migrating upstream from contractors to engineering consultancies and asset owners who embed performance guarantees into procurement terms. Three forces are compressing traditional sales models.
Hybrid resin-cement systems are expanding into high-load infrastructure applications by combining the rapid strength gain of epoxies with the cost position of cementitious grouts. Chilean mining contractors are specifying these materials for production-critical roof bolting where downtime costs exceed material premiums. The technology is expanding into specification territories previously reserved for pure epoxy systems.
ABNT's phased implementation of NBR 15575 performance tiers is tightening allowable deformation limits for structural connections. Manufacturers must now submit third-party test data for full assembly configurations rather than component ratings. High-rise residential projects in São Paulo and Belo Horizonte are driving the fastest compliance upgrades.
Asset owners are unbundling material supply from installation labor and demanding separate warranties for each. Mining companies in Peru and Chile now require applicator certification records as contract conditions. This pattern concentrates volume with suppliers who maintain trained contractor networks rather than those selling through distribution alone.
South America Anchors and Grouts Market Segmentation
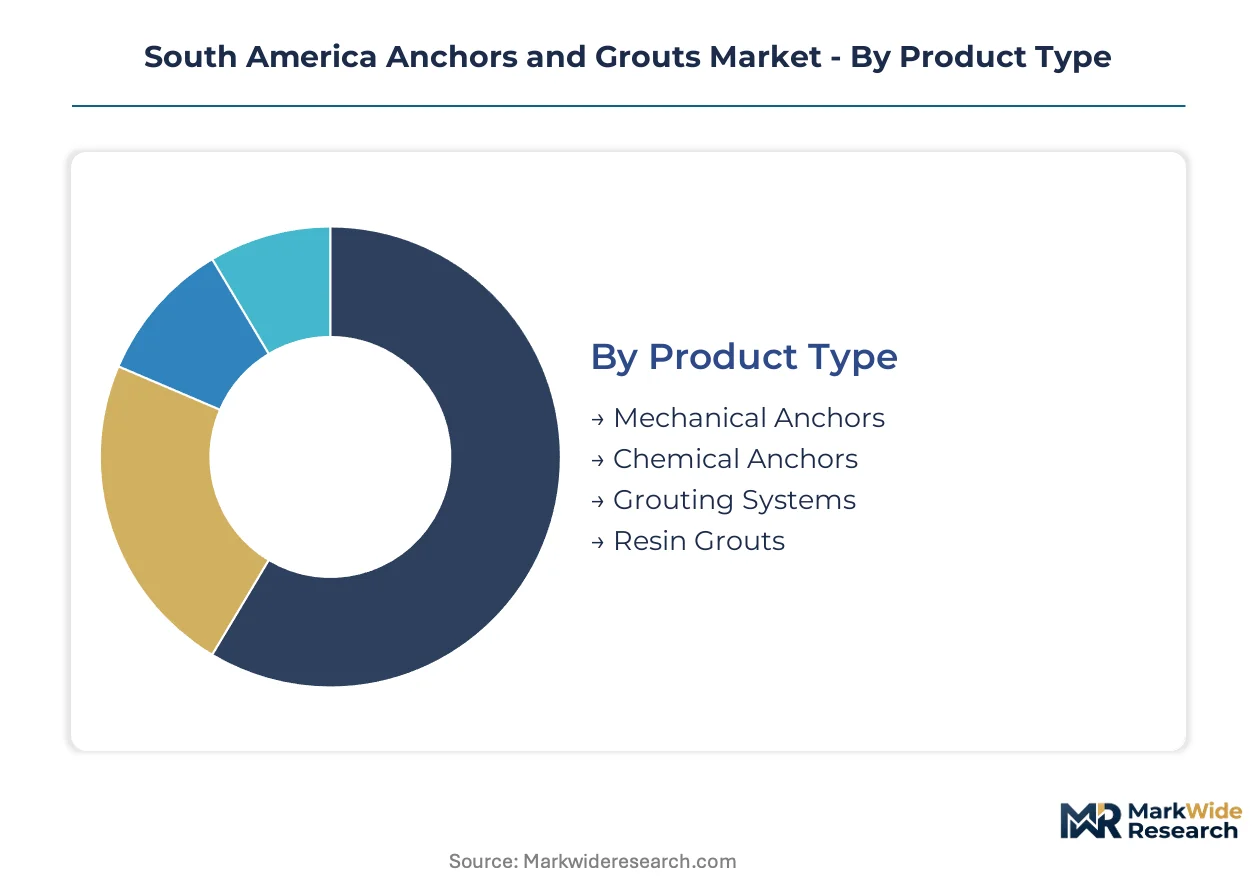
Anchor and grout procurement in South America diverges sharply across buyer types, with mining operators prioritizing seismic-rated resin systems while residential contractors chase cost-optimized mechanical fasteners. Specification control flows differently through each channel, reshaping how suppliers configure product portfolios and service capabilities.
Product Type:
Buyers segment first by load-bearing mechanism and substrate compatibility, then filter for installation speed and seismic certification requirements.
- Mechanical Anchors:Expansion and undercut designs relying on friction and mechanical interlock with concrete or masonry substrates. Brazilian residential contractors in São Paulo's high-rise corridor specify these for standard curtain wall connections where ABNT NBR 15575 does not mandate chemical bonding.
- Chemical Anchors:Epoxy, vinylester, or hybrid resin cartridges bonded into drilled holes for dynamic load transfer. Chilean copper mines below 1,000 meters depth specify these exclusively for rockburst-rated roof support, accepting 40-60% material cost premiums for verified pull-out performance.
- Grouting Systems:Cementitious and epoxy-based materials for structural void filling and precision equipment mounting.
- Resin Grouts:Rapid-curing formulations for production-critical applications where downtime costs dominate material economics.
Mechanical anchors lead on scale; chemical anchors lead on momentum.
Application:
End-use context dictates specification stringency, with mining and infrastructure enforcing third-party validation that construction segments often bypass.
- Construction:Commercial and residential building applications spanning structural connections, façade anchoring, and precast element erection. ABNT's phased NBR 15575 implementation is tightening deformation limits for high-rise residential projects in Belo Horizonte and São Paulo.
- Infrastructure:Bridges, tunnels, and transportation facilities requiring seismic-rated performance guarantees. Colombian run-of-river hydroelectric tunneling is generating specification-grade demand for injection grouting systems with documented flow characteristics.
- Mining:Underground and open-pit extraction operations requiring rock stabilization and equipment anchoring.
- Marine:Port facilities and offshore structures exposed to chloride corrosion and cyclic loading.
Infrastructure commands specification premiums; mining drives volume concentration.
End User:
Technical sophistication and warranty exposure separate procurement behaviors across buyer categories.
- Contractors:Installation firms balancing material cost against labor productivity and callback risk. Southeastern Brazil's industrial corridor contractors increasingly demand certified applicator networks from suppliers to transfer liability.
- Engineers:Design consultancies embedding performance specifications into BIM models before contractor involvement. Chilean and Peruvian engineering firms now lock anchor selections into digital specification platforms early in design cycles.
- Equipment Manufacturers:OEMs requiring precision grouting for machinery installation and alignment.
- Government Agencies:Public works directors enforcing SENCICO norms in Peru and Ministerio de Obras Públicas standards in Chile, favoring technically validated suppliers with local testing capabilities.
Contractors move the most volume; government agencies set the strictest barriers.
Distribution Channel:
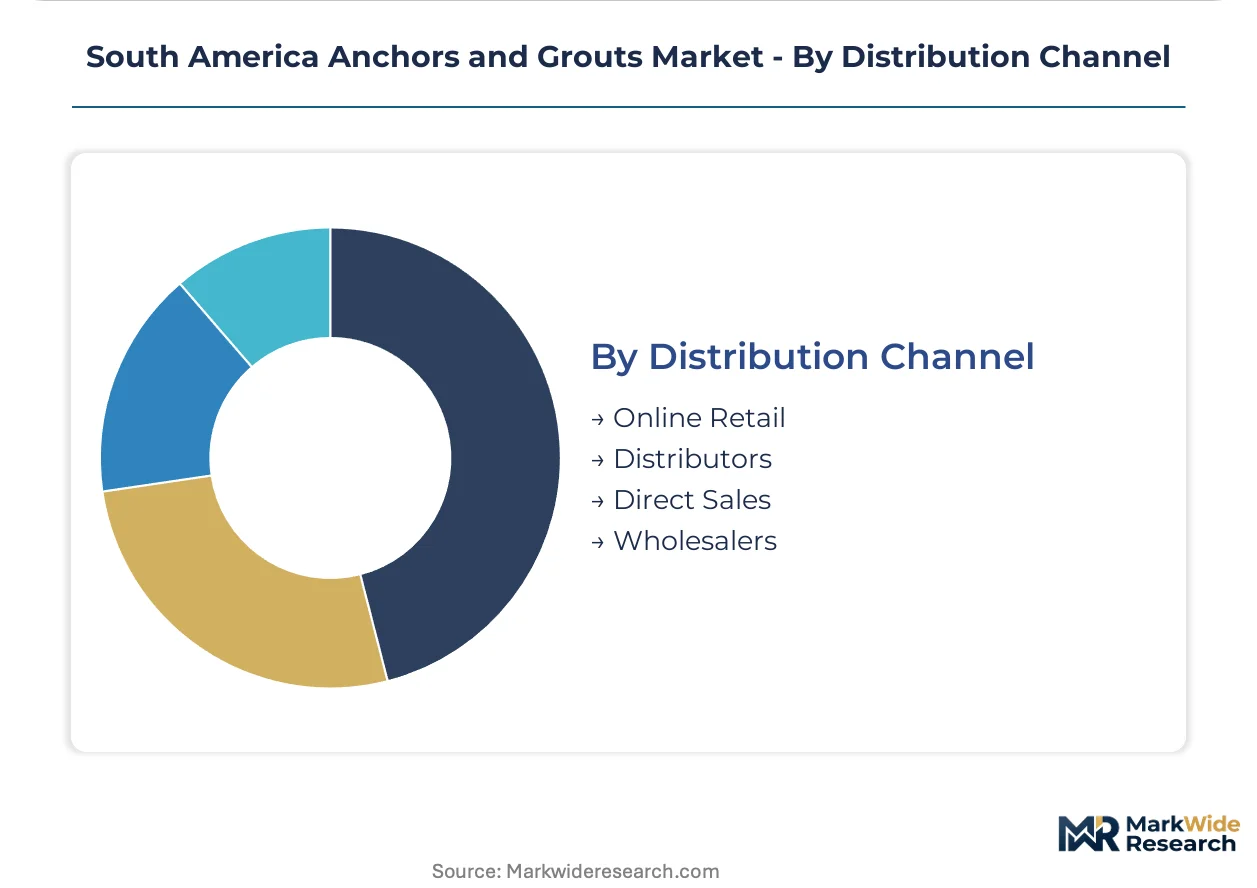
Channel choice reflects order size urgency, technical support requirements, and specification complexity.
- Direct Sales:Manufacturer-led specification and project management for complex mining and infrastructure bids. Sika AG and MAPEI SpA deploy technical engineers to lock in large-scale anchor and grout packages before competitive tendering.
- Distributors:Regional stockists serving contractors with standard mechanical anchors and cementitious grouts. Brazilian distributors in Minas Gerais maintain inventory positions to capture spot demand from industrial maintenance cycles.
- Online Retail:E-commerce platforms for standardized hardware and small-quantity resin cartridges.
- Wholesalers:Bulk intermediaries moving commodity-grade cementitious grouts to price-sensitive construction segments.
Direct sales capture specification value; distributors handle transaction velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands the largest installed base of anchors and grouts consumption, yet Chile and Peru generate the fastest specification-grade demand through mining-driven procurement.
Brazil
ABNT NBR 15575 structural mandates are forcing upgrades to high-strength cementitious grouts across residential and commercial construction. ANVISA regulates chemical components in resin formulations, extending approval timelines for new products. The southeastern industrial corridor spanning São Paulo and Minas Gerais concentrates demand from high-rise residential projects and industrial maintenance cycles.
Chile
Copper extraction depths below 1,000 meters require resin anchors rated for dynamic rockburst conditions in underground operations. The Ministerio de Obras Públicas enforces specific anchoring standards for public infrastructure that favor technically validated suppliers. Santiago hosts the region's densest concentration of certified applicator networks and pull-test laboratories.
Peru
State-funded mining and hydroelectric projects under SENCICO technical norms constrain unproven entrants and favor suppliers with local testing capabilities. The central government is tightening national content requirements for procurement on major public works. The mining corridor infrastructure generates specification-grade demand for injection grouting systems with documented performance data.
Colombia
Run-of-river hydroelectric tunneling activity is driving procurement of specification-grade injection grouting systems. The national infrastructure agency is aligning procurement rules with seismic performance requirements for Andean terrain. Bogotá-based engineering consultancies are migrating anchor selection to BIM-integrated specification platforms.
South America Anchors and Grouts Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with specification-controlled mining and infrastructure bids concentrating around technically validated suppliers while standard construction flows through distribution-heavy channels. The market structure tilts toward consolidation at the premium tier where certification barriers and applicator network requirements filter out commodity entrants. Three archetypes dominate: European-headquartered specialty chemical groups with certified installer ecosystems, regional manufacturing subsidiaries of global building materials conglomerates, and niche applicator-service firms that bundle installation with material supply. Competitive moves center on backward integration into local manufacturing to reduce import dependency and on digital specification platform partnerships that lock product selections early in design cycles.
Within the European-headquartered specialty tier, Sika AG and MAPEI SpA exemplify the certified-applicator model that transfers liability and secures recurring specification control. BASF SE anchors the R&D-intensive archetype through formulation capabilities in seismic-modified systems. These three occupy positions where technical validation and local testing infrastructure outweigh price competition in procurement decisions.
| Leading Market Players |
|---|
| Sika AG |
| MAPEI SpA |
| BASF SE |
| Hilti Corporation |
| Bostik |
| MBCC Group |
| Fosroc International Limited |
| GCP Applied Technologies |
| Five Star Products Inc |
| Others |
Value Network & Pricing Analysis
Epoxy resin hardener imports from European and Asian supply bases cascade through three distinct pricing tiers in South America, with currency volatility amplifying cost differentials between specification-grade mining procurement and standard construction spot purchases. Brazilian contractors in São Paulo's industrial corridor absorb the steepest markups when exchange rate movements coincide with cement price swings, forcing selective trade-offs between resin system performance and project budget adherence.
Pricing Analysis
Capacity additions in Brazil's southeastern industrial corridor are reshaping price floors for cementitious grouts as localized manufacturing reduces import dependency. Three-tier pricing structure across premium, standard, and economy levels separates seismic-certified resin systems from commodity mechanical anchors, with certification grade and volume scale as the primary differentiation drivers. Pricing pressure stems from ANVISA's extended chemical registration timelines, which delay product launches and compress margins for new formulations. Mining operators in Chile and Peru exhibit the least price sensitivity, accepting material cost premiums for verified pull-out performance, while residential contractors in Brazil's high-rise segment drive the most aggressive cost negotiations.
Supply Chain Analysis
Single-source vulnerability sits with specialty epoxy hardener suppliers concentrated in Germany, Switzerland, and Japan, exposing South American formulators to extended lead times and currency-linked cost spikes. Raw material dependencies center on bisphenol-A epoxies, vinylester resins, and Portland cement clinker sourced from China, the United States, and domestic Brazilian kilns. Tariff exposure runs through Mercosur's variable external tariff schedules for chemical intermediates, creating procurement timing advantages for bonded warehouse inventory. Distribution runs through certified applicator networks for specification-grade projects, while commodity-grade mechanical anchors flow through regional distributors in Minas Gerais and São Paulo states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America Anchors and Grouts Market functions as a geographic-arbitrage play where Brazilian manufacturing cost advantages under ABNT certification frameworks contrast with Andean mining premiums tied to SENCICO and Ministerio de Obras Públicas validation requirements.
For Market Incumbents: Acquire certified applicator networks to lock in specification control before competitive tendering on Chilean copper mine expansions and Colombian hydroelectric tunneling projects. Defensive consolidation demands backward integration into local resin formulation capacity in Brazil to neutralize import dependency and ANVISA registration delays, while channel control investments in BIM-integrated specification platforms capture engineer-driven product selection upstream from contractor involvement. For New Entrants and Emerging Players: Hybrid resin-cement system technology offers a technology-first wedge into the production-critical roof bolting segment where Chilean mining contractors prioritize downtime cost reduction over material premiums. White-space targets concentrate in Peruvian mining corridor infrastructure under SENCICO norms, where local testing capabilities filter out unproven suppliers, and in Colombian run-of-river hydroelectric injection grouting where documented flow characteristics command specification premiums. A go-to-market angle anchored in digital specification platform partnerships with Bogotá-based engineering consultancies locks product selections early in design cycles before incumbent technical sales teams engage. For Investors and Strategic Acquirers: Consolidation pressure builds where applicator certification gaps and ANVISA registration barriers strand sub-scale formulators without backward integration into local manufacturing. Long-term viability over a multi-year window favors acquisition targets possessing captive Brazilian production assets and established pull-test laboratory relationships in Santiago or São Paulo. The signal to watch is ABNT's phased NBR 15575 implementation timeline, which accelerates compliance-driven specification upgrades and expands addressable market for high-performance grout systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Local Resin Manufacturing | Captive production in Brazil neutralizes ANVISA registration delays and currency volatility for epoxy hardener inputs. |
| Certified Applicator Network Expansion | Trained technician pools in Santiago and São Paulo transfer liability and secure recurring specification control on mining bids. |
| BIM-Integrated Specification Platform Partnership | Engineering consultancy alliances in Bogotá and Belo Horizonte lock product selections before competitive tendering begins. |
| Seismic-Modified Formulation R&D Investment | Epoxy systems tailored to Andean rockburst conditions command 40-60% material cost premiums in Chilean underground operations. |
| Local Testing Capability Buildout | Pull-test laboratories in Peru satisfy SENCICO norms and filter unproven entrants from state-funded mining procurement. |
Research Methodology
Bottom-up construction and mining sector modeling reconciled against top-down chemical formulation and import tracking forms the analytical core of this study. Primary interviews with plant engineers at Brazilian precast concrete facilities, procurement leads at Chilean copper mining operations, technical directors at resin formulators, distribution channel partners in Minas Gerais, and certified applicator network managers in Santiago were combined with secondary validation from ABNT certification databases, ANVISA chemical registration filings, Chilean Ministerio de Obras Públicas infrastructure procurement records, Peruvian SENCICO technical norm documentation, and customs trade data for epoxy resin and hardener imports. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of anchor and grout consumption patterns across the analysis window established baseline growth trajectories for each modeled segment. The forecast framework incorporates product type differentiation between mechanical anchors, chemical anchors, and grouting systems; application splits across construction, infrastructure, and mining end-uses; and regional production hub dynamics spanning Brazil, Chile, Peru, and Colombia. CAGRs were derived from regression analysis of specification-grade procurement intensity correlated with mining extraction depth trends and ABNT compliance upgrade cycles.
The model holds under stable currency regimes and continued enforcement of SENCICO and Ministerio de Obras Públicas technical norms; deviation in regulatory timelines, cement price volatility, or applicator certification capacity would shift volume trajectories. Forecasts reflect assumptions about mining investment continuity and residential construction permit flows without claiming precision on timing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Construction
Concrete and Cement Dissolver Market
Specialty Construction
Indonesia Waterproofing Solutions Market
Specialty Construction
Shotcrete Accelerators Market
Specialty Construction
Temporary Fencing Panels Market
Specialty Construction
India Anchors and Grouts Market
Specialty Construction
Roller Shutter Market
Specialty Construction
Fire Hydrants Market
Specialty Construction
Portable Walls Market
Specialty Construction
Welded Metal Bellows Market
Specialty Construction
Slab Repair Products Market
Specialty Construction
Asia-Pacific Anchors and Grouts Market
Specialty Construction
Asia-Pacific Waterproofing Solutions Market
Specialty Construction
Global Fencing Market
Specialty Construction
ASEAN Waterproofing Market
Specialty Construction
Expandable Shelter Market
Specialty Construction
Composite Repair Market