
 Vietnam Data Center Construction Market | 2026-2036
Vietnam Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Data Center Construction Market Insights
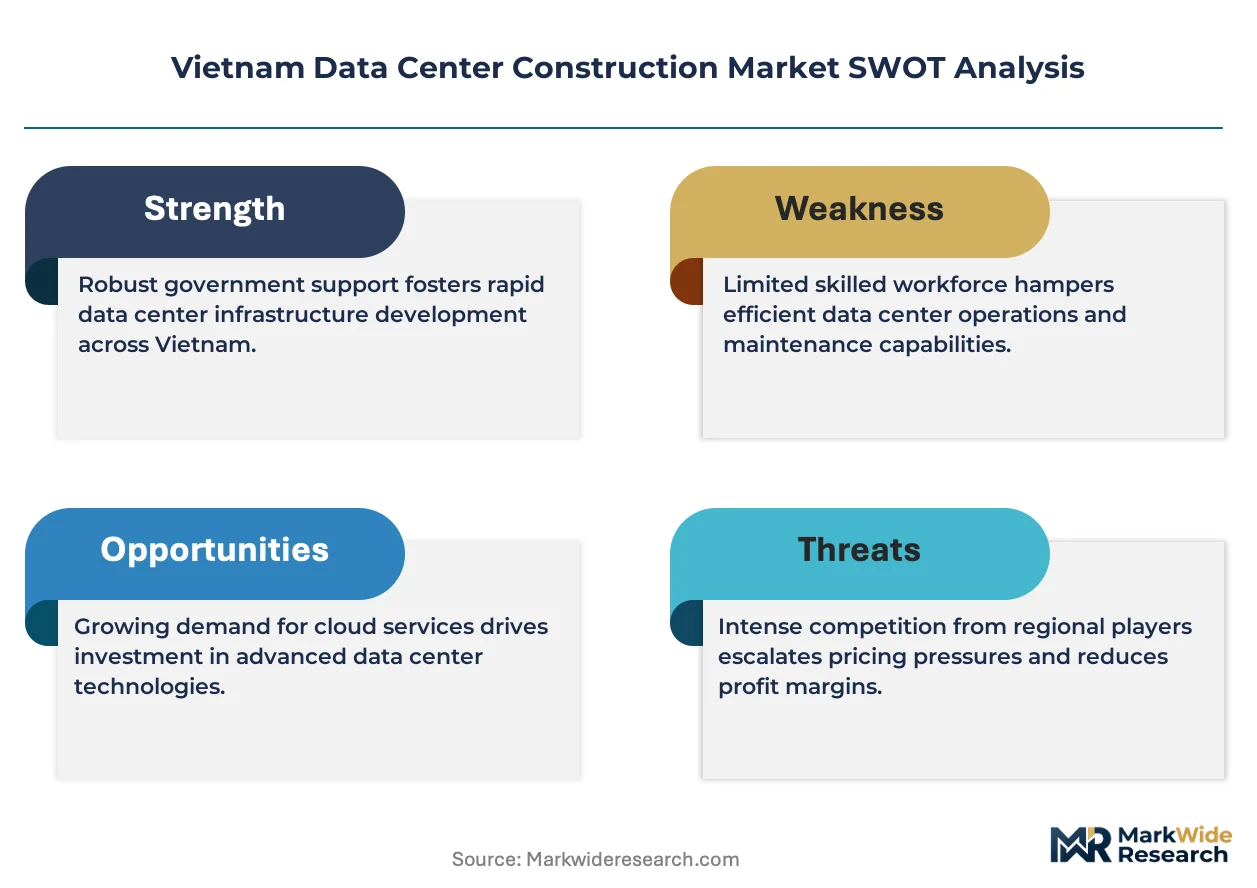
The Vietnam data center construction market is restructuring around a sharp split between hyperscale campuses built for international cloud operators and smaller enterprise facilities serving domestic corporates. Viettel IDC leverages its military-affiliated land access to anchor greenfield developments near Hanoi. FPT Telecom competes through integrated telecom-to-data-center service bundles. Coteccons Construction Joint Stock Company dominates the EPC contractor tier with proven delivery of Tier III-certified facilities.
Vietnam data center construction encompasses the civil engineering, mechanical and electrical installation, and commissioning of facilities designed to house IT infrastructure with specified power densities, cooling redundancy, and uptime tiers. Primary commercial purpose is to provide sovereign compute capacity for enterprises and cloud operators subject to Vietnamese data residency requirements. Hyperscale facilities capture the dominant share of capital deployment as foreign cloud providers commit to local presence. Colocation construction is accelerating fastest among segments as mid-market enterprises outsource facility ownership. Edge data center construction remains nascent but attracts pilot investment from telecom operators seeking low-latency nodes.
Vietnam's Ministry of Information and Communications enforces data localization through the Cybersecurity Law, mandating domestic storage of personal and sensitive data. The Ministry of Construction issues building codes specific to fire suppression and structural load for data center facilities. BIS-equivalent electrical safety standards and Tier certification from Uptime Institute shape procurement specifications and vendor qualification. Stakeholders must monitor regulatory clarity on cross-border data transfer permissions and renewable energy procurement rules as these will determine facility location economics and power architecture decisions.
Market Dynamics
Vietnam's data center construction market is bifurcating around the Cybersecurity Law's data localization mandates, which force foreign cloud providers to build sovereign facilities while domestic enterprises accelerate colocation adoption to comply without owning assets.
Growth Catalysts
- Cybersecurity Law localization mandates:Foreign cloud operators must store Vietnamese personal data domestically, triggering greenfield hyperscale investments across Ho Chi Minh City industrial zones.
- Fintech platform expansion:Digital payment and lending platforms require low-latency infrastructure, driving demand for Tier III-certified facilities with redundant power architectures.
- Liquid cooling adoption:High-density GPU clusters for AI training are displacing traditional air-cooled designs, forcing mechanical engineering upgrades in new builds.
Market Restraints
- Copper and aluminum price volatility:Busbar and cable costs constitute substantial electrical infrastructure spend, with commodity swings compressing EPC margins on fixed-price contracts.
- Limited domestic switchgear manufacturing:Vietnam lacks indigenous producers of medium-voltage breakers and transformers, creating import dependency on Chinese and South Korean suppliers.
- Grid interconnection delays:EVN's substation upgrade timelines often lag facility construction schedules, stranding completed shells awaiting power commissioning.
Strategic Opportunities
- Da Nang corridor development:Central Vietnam's underpenetrated geography offers submarine cable landing proximity with lower land costs than southern industrial zones.
- Renewable energy procurement rules:Draft regulations enabling direct power purchase agreements with solar and wind developers would reshape site selection economics toward renewable-rich provinces.
- Edge node convergence with 5G:Telecom operators are piloting micro data centers at cellular base stations, creating distributed infrastructure demand outside traditional hyperscale clusters.
Industry Challenges
- Tier III certification timelines:Uptime Institute's design and facility certification process extends project delivery schedules, creating revenue recognition delays for developers.
- Specialized MEP engineering scarcity:Vietnam's construction workforce lacks depth in precision cooling and electrical redundancy design, forcing reliance on foreign specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Data Center Construction Market |
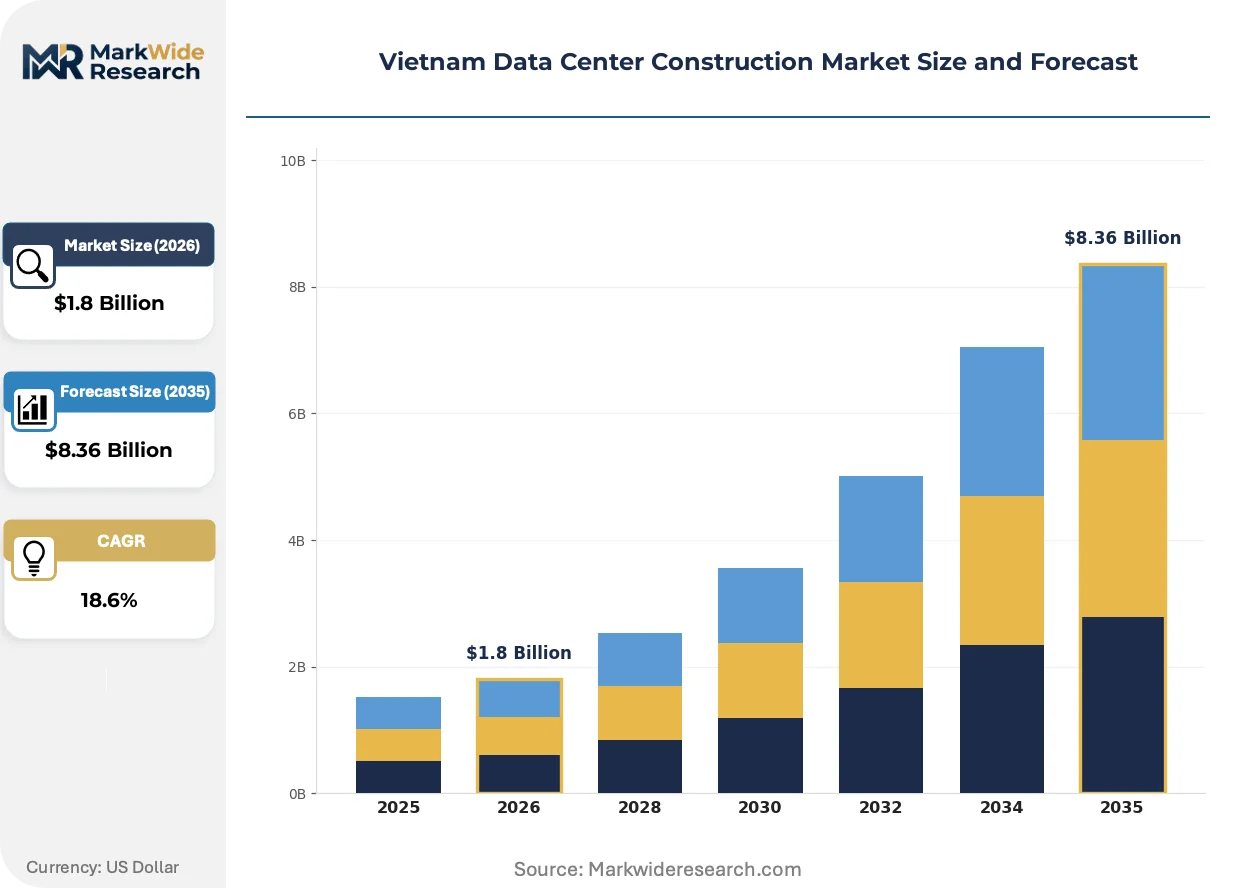
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Hyperscale, Enterprise, Colocation, Edge Construction Type: New Build, Retrofit, Expansion, Renovation Power Source: Grid, Renewable, Diesel Generator, Hybrid Cooling System: Air-Cooled, Liquid-Cooled, Immersion, Chilled Water |
| Companies Covered | Viettel IDC, VNPT, FPT Telecom, CMC Telecom, NTT GDC Vietnam, ST Telemedia GDC Vietnam, Keppel DC Vietnam, Coteccons Construction Joint Stock Company, Turner Construction Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Data Center Construction Market Trends and Innovations
Mechanical and electrical systems are converging around thermal efficiency and grid flexibility, with modular construction methods compressing deployment timelines for hyperscale campuses.
Immersion cooling is electrifying high-density deployment economics in Vietnamese facilities. The technology submerges servers in dielectric fluid, eliminating air handling infrastructure. Hyperscale operators are piloting two-phase immersion systems for AI training clusters. This thermal architecture is compressing power usage effectiveness ratios below 1.15, enabling rack densities previously impractical in tropical climates.
Vietnam's Ministry of Information and Communications is tightening enforcement of the Cybersecurity Law's data classification requirements. The regulation mandates distinct storage architectures for personal, important, and national security data tiers. Domestic banks and healthcare providers are most affected, redesigning facility segmentation to achieve multi-zone compliance within single campuses.
Enterprise buyers are consolidating vendor relationships around integrated design-build-operate contracts. Mid-market firms previously procured civil construction, MEP installation, and facility management separately. Colocation developers now capture full lifecycle value by bundling these services, with this model dominating procurement in Hanoi and Ho Chi Minh City metropolitan areas.
Vietnam Data Center Construction Market Segmentation
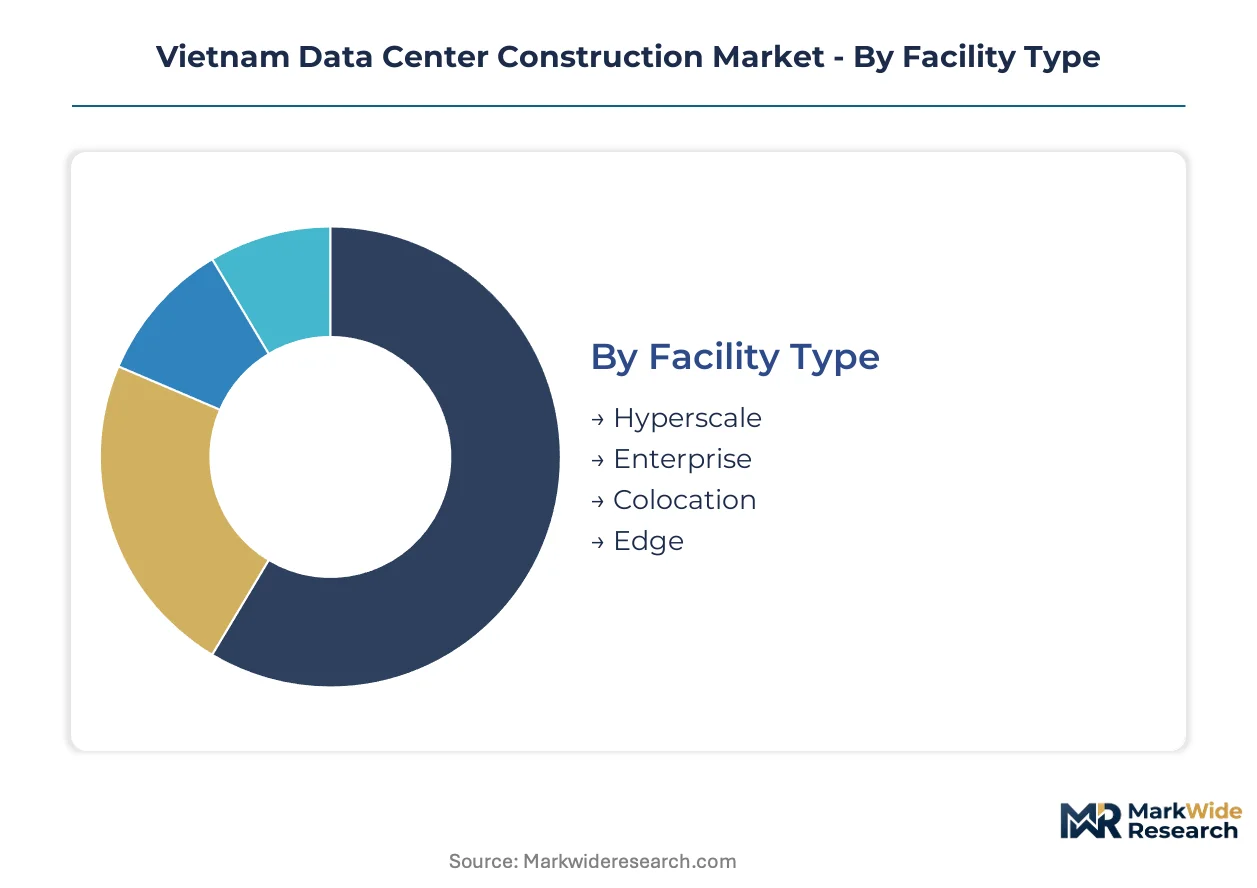
Facility architecture, construction methodology, power architecture, and thermal management each create distinct procurement patterns and vendor qualification requirements across Vietnamese data center projects. Segmentation reveals where capital concentrates and which technical specifications dominate competitive positioning.
Facility Type:
Upgrade cycles and capacity expansion timelines diverge sharply across facility scales, with hyperscale campuses operating on 3-5 year refresh schedules while enterprise facilities stretch replacement intervals to 7-10 years.
- Hyperscale:Massive single-tenant campuses exceeding 10MW designed for cloud service providers and international platforms. Demand clusters in Ho Chi Minh City industrial zones as foreign operators comply with data localization mandates under the Cybersecurity Law.
- Colocation:Multi-tenant facilities where enterprises lease rack space rather than owning infrastructure. Vietnamese banks and fintech platforms are accelerating adoption to satisfy regulatory requirements without capital-intensive builds.
- Enterprise:Dedicated facilities constructed for single corporate owners, typically 1-5MW capacity. State-owned enterprises and military-affiliated organizations favor this model for sensitive data architectures.
- Edge:Distributed micro-facilities under 500kW positioned for ultra-low latency applications. Viettel and FPT Telecom are piloting base station-integrated nodes for 5G and IoT workloads.
Volume placements concentrate in Hyperscale; the faster expansion belongs to Colocation.
Construction Type:
Cost tiering separates greenfield developments from retrofit engagements, with new builds commanding premium engineering margins while renovation work competes on speed and minimal operational disruption.
- New Build:Ground-up construction on greenfield or brownfield sites with full design flexibility. Hyperscale operators exclusively pursue this route to achieve Tier III certification and custom power density specifications.
- Expansion:Modular capacity additions to operational facilities, typically adding 2-5MW halls. Colocation providers favor this approach to capture demand surges without full campus redevelopment.
- Retrofit:Conversion of existing industrial or commercial buildings into data center specifications. Lower land costs in peripheral Hanoi zones attract this construction mode for mid-market facilities.
- Renovation:Upgrade of legacy data center infrastructure without structural modification. Enterprise owners deploy this option to extend facility lifespans while awaiting regulatory clarity on cross-border data transfer permissions.
Capital deployment concentrates in New Build; the steepest expansion trajectory belongs to Expansion.
Power Source:
Customer type and uptime requirements determine power architecture selection, with financial services and healthcare mandating redundant configurations that manufacturing and logistics clients rarely require.
- Grid:Primary reliance on EVN's national transmission network with substation interconnection. Ho Chi Minh City facilities face commissioning delays as grid upgrade timelines lag construction schedules.
- Hybrid:Grid interconnection supplemented by on-site generation and battery storage. This architecture is gaining preference among Tier III-certified facilities seeking operational flexibility during EVN maintenance windows.
- Diesel Generator:Emergency backup systems mandated for Tier III and Tier IV uptime certification. Vietnamese environmental regulations are tightening emissions standards for these installations.
- Renewable:Direct procurement from solar or wind developers under draft power purchase agreement frameworks. Site selection economics would shift toward renewable-rich provinces if regulations finalize.
Current deployments concentrate in Grid-dominant Hybrid configurations; regulatory finalization would accelerate Renewable adoption fastest.
Cooling System:
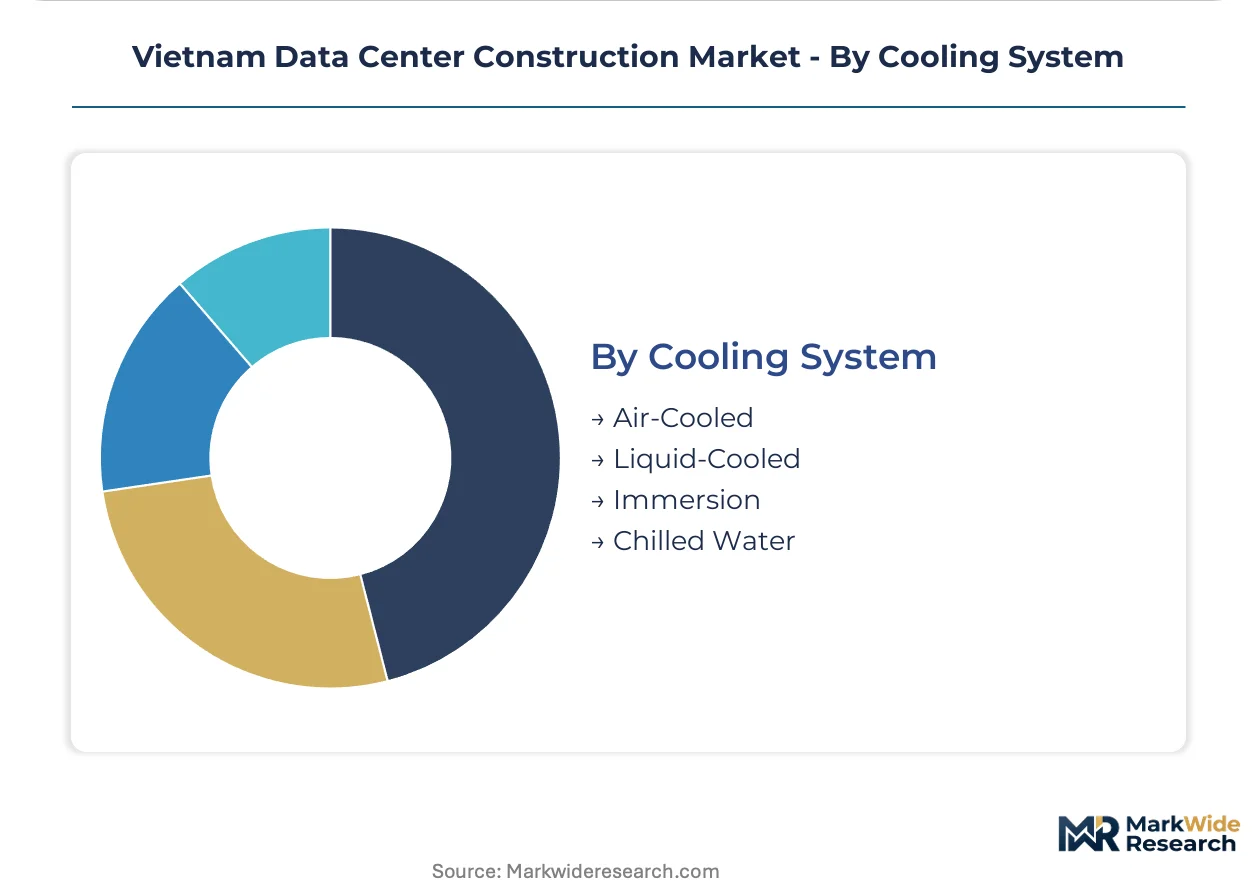
Technology maturity and supply concentration shape procurement patterns, with established air-cooled designs dominating volume while emerging thermal architectures capture high-density niche applications.
- Liquid-Cooled:Direct-to-chip or rear-door heat exchanger systems for racks exceeding 30kW density. AI training clusters are forcing adoption of this technology in new hyperscale halls.
- Immersion:Dielectric fluid submersion eliminating air handling infrastructure entirely. Foreign cloud operators are piloting two-phase systems to achieve power usage effectiveness below 1.15 in tropical conditions.
- Air-Cooled:Traditional computer room air handler and precision air conditioning units. This technology retains dominance in enterprise and colocation facilities with moderate density requirements.
- Chilled Water:Centralized plant cooling with cooling towers and heat rejection equipment. Older facilities in Hanoi employ this architecture, though water scarcity concerns are limiting new adoption.
Installed base concentrates in Air-Cooled; Immersion is climbing the fastest among emerging thermal architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ho Chi Minh City and its surrounding industrial zones anchor Vietnam's data center construction activity, with hyperscale campuses clustering near Tan Thuan Export Processing Zone and Cat Lai Port corridor. Foreign cloud operators target these southern hubs for submarine cable landing proximity and established power infrastructure. Northern Vietnam's Hanoi corridor offers military-affiliated land access and lower cooling costs during winter months.
Ho Chi Minh City Metropolitan Area
Hyperscale demand from international cloud providers and fintech platforms concentrates in Thu Duc City and District 9 industrial parks. The Ministry of Information and Communications enforces Cybersecurity Law data localization mandates that force foreign operators to build sovereign facilities. Tan Thuan Export Processing Zone hosts multiple Tier III-certified campuses under active construction.
Hanoi and Red River Delta
State-owned enterprises and military-affiliated organizations drive enterprise facility demand across Gia Lam and Long Bien districts. Viettel IDC leverages privileged land access from military holdings to anchor greenfield developments. The northern corridor attracts operators seeking lower land costs and reduced tropical cooling loads during winter months.
Binh Duong Province
Industrial zone expansion creates brownfield conversion opportunities for mid-market colocation facilities. Vietnam-Singapore Industrial Park and VSIP II offer pre-cleared land titles with simplified permitting. Foreign EPC contractors favor these zones for established utility corridors and construction labor pools.
Da Nang and Central Coast
Submarine cable landing stations at Da Nang create latency advantages for edge computing nodes serving central Vietnam. The underpenetrated geography offers land cost arbitrage against southern industrial zones. Telecom operators pilot micro data center deployments at cellular base stations for 5G workload distribution.
Dong Nai Province
Long Thanh District and Bien Hoa City industrial zones absorb overflow demand from saturated Ho Chi Minh City corridors. Grid interconnection capacity constraints limit near-term development despite available land banks. Provincial authorities compete for data center investment through tax incentive packages.
Vietnam Data Center Construction Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and power density specifications, with Tier III-certified facility developers capturing engineering premiums while retrofit contractors compete on speed. The market structures around three strategic archetypes: military-affiliated domestic operators with privileged land access, integrated telecom-to-data-center service bundlers, and foreign-invested hyperscale specialists. Competitive moves concentrate on EPC contractor consolidation and renewable energy procurement partnerships.
Within the domestic operator tier, Viettel IDC exemplifies military-affiliated land access advantages, while FPT Telecom occupies a position as an integrated service bundler spanning telecom infrastructure through facility operations. Coteccons Construction Joint Stock Company anchors the EPC contractor segment with proven Tier III delivery capability. These three entities represent distinct competitive positioning vectors: sovereign land control, vertical service integration, and specialized construction execution.
| Leading Market Players |
|---|
| Viettel IDC |
| VNPT |
| FPT Telecom |
| CMC Telecom |
| NTT GDC Vietnam |
| ST Telemedia GDC Vietnam |
| Keppel DC Vietnam |
| Coteccons Construction Joint Stock Company |
| Turner Construction Company |
| Others |
Pricing and Supply Chain Analysis
Copper and aluminum price volatility on the London Metal Exchange cascades through Vietnam's data center construction supply chain, compressing EPC margins on fixed-price contracts and forcing tiered pricing structures that separate Tier III-certified hyperscale builds from uncertified mid-market facilities.
Pricing Analysis
Uptime Institute certification tier anchors value-based pricing across Vietnamese data center construction, with Tier III-certified facilities commanding engineering premiums that reflect guaranteed uptime outcomes. Price differentiation separates foreign cloud operators seeking sovereign capacity from domestic enterprises pursuing colocation outsourcing. Cost compression in the mid-market tier is intensifying because retrofit contractors compete on speed rather than certification depth. State-owned enterprises exhibit the lowest price sensitivity due to sovereign data requirements, while fintech platforms balance latency demands against capital constraints.
Supply Chain Analysis
Regional distribution centers in Singapore and Hong Kong feed mechanical and electrical components into Vietnam's project sites, creating hub-and-spoke patterns that extend lead times for critical switchgear. Supply concentration rests on Chinese and South Korean producers of medium-voltage breakers and transformers, with Vietnamese EPCs lacking indigenous manufacturing alternatives. Copper busbar and precision cooling equipment draw from these concentrated sources, exposing projects to single-source vulnerability during EVN grid interconnection delays. Distribution runs through bonded warehouse facilities at Cat Lai Port before final-mile deployment to Ho Chi Minh City industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's data center construction market sits in a technology-transition phase, with immersion cooling displacing traditional air-cooled architectures in high-density hyperscale halls.
For Market Incumbents: Hedge against margin erosion in the commodity retrofit tier by securing captive supply agreements for copper and aluminum feedstock. Coteccons and established EPC contractors should deepen backward integration into precision cooling engineering talent pools to defend against foreign specialist dependency as liquid-cooled AI clusters proliferate. For New Entrants and Emerging Players: The Cybersecurity Law in Vietnam opens a window for specialized compliance-focused facility designers serving domestic banks and healthcare providers redesigning for multi-zone data classification. Da Nang's underpenetrated corridor offers the most penetrable geography, with submarine cable proximity and lower land costs than saturated southern zones. A go-to-market angle anchored in integrated design-build-operate contracts captures full lifecycle value from mid-market enterprises. For Investors and Strategic Acquirers: The window for entry favors EPC contractors with proven Tier III delivery capability and established relationships with Viettel IDC or FPT Telecom. Long-term viability hinges on positioning for renewable energy procurement rule finalization, which would reshape site selection economics toward solar-rich provinces. The signal to watch is draft direct power purchase agreement regulations advancing through the Ministry of Industry and Trade.| Strategic Initiative | Industry Significance |
|---|---|
| Tier III Certification Investment | Uptime Institute certification enables premium pricing from foreign cloud operators under Cybersecurity Law mandates. |
| Backward Integration into MEP Engineering | In-house precision cooling design capabilities reduce reliance on scarce foreign specialists and compress project timelines. |
| Renewable Energy Procurement Partnership | Direct power purchase agreements with solar developers would shift facility economics toward renewable-rich provinces. |
| Da Nang Corridor Expansion | Submarine cable landing proximity and land cost arbitrage create latency advantages for edge computing nodes. |
| Integrated Design-Build-Operate Bundling | Full lifecycle contracts capture recurring revenue from mid-market enterprises outsourcing facility ownership. |
Research Methodology
Multi-period observation of EVN grid interconnection timelines, copper price indices, and Tier III certification completion rates anchored the trend analysis, supplemented by interviews with EPC project directors, data center facility managers at Viettel IDC and FPT Telecom, Ministry of Information and Communications regulatory officers, and precision cooling equipment procurement leads. Secondary validation drew from Vietnam customs import records for electrical switchgear, Uptime Institute certification databases, EVN transmission expansion disclosures, and Cybersecurity Law implementation circulars. Bottom-up project pipeline tracking triangulated against top-down capital expenditure estimates from disclosed hyperscale operator commitments.
Segment-weighting across facility type, construction methodology, power architecture, and cooling system dimensions shaped the analytical framework over the projection horizon. CAGRs derived from capacity addition schedules, power density evolution curves, and regulatory enforcement intensity trajectories. Modeling incorporated AI training cluster deployment rates as a demand-side input and immersion cooling technology cost curves as a supply-side variable.
The model assumes a particular technology adoption path; alternative pathways for liquid cooling penetration would alter the outlook if tropical climate engineering constraints prove more persistent than anticipated. Forecasts reflect documented assumptions around EVN grid upgrade pacing and Cybersecurity Law enforcement consistency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Europe Transportation Infrastructure Construction Market
Infrastructure Construction
APAC Data Center Construction Market
Infrastructure Construction
Global Rail Infrastructure Market
Infrastructure Construction
Thailand Data Center Construction Market
Infrastructure Construction
Denmark Data Center Construction Market
Infrastructure Construction
India Transportation Infrastructure Construction Market
Infrastructure Construction
Transportation Infrastructure Construction Market
Infrastructure Construction
New Zealand Data Center Construction Market
Infrastructure Construction
South America Data Center Construction Market
Infrastructure Construction
Infrastructure Sector in Asia Pacific Market
Infrastructure Construction
Poland Transportation Infrastructure Construction Market
Infrastructure Construction
South Korea Transportation Infrastructure Construction Market
Infrastructure Construction
Qatar Transportation Infrastructure Construction Market
Infrastructure Construction
Bahrain Construction Market
Infrastructure Construction
Pipeline Construction Market
Infrastructure Construction
India Transportation Infrastructure Market