
 New Zealand Data Center Construction Market | 2026-2036
New Zealand Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Data Center Construction Market Insights
Hybrid cloud architecture is narrowing the gap between enterprise-owned facilities and hyperscale builds across New Zealand. Aurecon Group Pty Ltd leverages its multidisciplinary engineering footprint to anchor complex Tier III and Tier IV projects in seismic zones. Turner & Townsend competes on cost certainty through advanced project controls, while Arup Group Limited differentiates via integrated sustainability and resilience design.
New Zealand data center construction encompasses the civil, mechanical, electrical, and structural build-out of facilities housing IT infrastructure, typically requiring power densities of 5-20 kW per rack and PUE targets below 1.4 for new builds. Greenfield project types dominate investment flows as hyperscalers seek purpose-built campuses with direct renewable energy access. Tier III data center tier classifications lead volume commitments, though Tier IV builds are expanding among financial services end users requiring fault-tolerant uptime guarantees.
New Zealand's Building Code, administered by the Ministry of Business, Innovation and Employment, mandates seismic performance standards that exceed typical international data center specifications and shape foundation and structural system selection. The Commerce Commission regulates electricity distribution pricing, directly influencing power supply economics for facility operators. The Energy Efficiency and Conservation Authority promotes low-carbon design pathways that increasingly factor into procurement criteria. Stakeholders must monitor how evolving national grid capacity allocations and consent timelines interact to determine viable project sequencing across the North and South Islands.
Market Dynamics
Seismic resilience mandates from New Zealand's Building Code are compressing foundation design timelines and elevating structural engineering costs, forcing contractors to pre-qualify specialized steel fabrication capacity before bidding hyperscale projects.
Growth Catalysts
- Submarine cable landing concentration:Auckland's northwest corridor hosts multiple international fiber optic termini, creating natural clustering for cloud providers seeking sub-10ms latency to Australia and Asia-Pacific markets.
- Commerce Commission grid pricing reforms:Revised electricity distribution tariffs incentivize direct high-voltage connections, reducing long-term power supply costs for facilities above 10 MW capacity.
- Financial services fault-tolerance mandates:Reserve Bank of New Zealand prudential standards require systemically important banks to maintain Tier IV-equivalent infrastructure, driving premium construction specifications.
Market Restraints
- Specialized seismic steel supply:Domestic fabrication capacity for moment-resisting frames remains concentrated among two Auckland-based suppliers, creating bottleneck risk during concurrent project waves.
- Consent timeline volatility:Regional council resource consent processes for hyperscale campuses average 18-24 months, with Auckland Council backlogs extending beyond 30 months for greenfield sites exceeding 50 MW.
- Liquid cooling infrastructure gap:Local mechanical contractor expertise in direct-to-chip cooling systems lags deployment requirements for AI training clusters above 30 kW per rack.
Strategic Opportunities
- Christchurch South Island expansion:Lower land costs and untapped grid capacity from Orion New Zealand's network upgrades position Canterbury for secondary hyperscale campuses serving disaster recovery workloads.
- Energy Efficiency and Conservation Authority co-funding:The agency's low-emission technology grants offset 15-30% of premium efficiency system costs for projects achieving sub-1.3 PUE targets.
- Geothermal-direct coupling:Contact Energy's Tauhara and Te Huka plants offer firm renewable baseload, enabling 24/7 carbon-free power purchase agreements unavailable in most Asia-Pacific markets.
Industry Challenges
- Seismic engineering talent scarcity:Registered structural engineers with Tier IV data center experience number fewer than 50 nationwide, constraining simultaneous project execution.
- Building Code compliance integration:MBIE's 2024 seismic performance criteria require real-time structural health monitoring systems that most international contractors have not previously specified.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Data Center Construction Market |
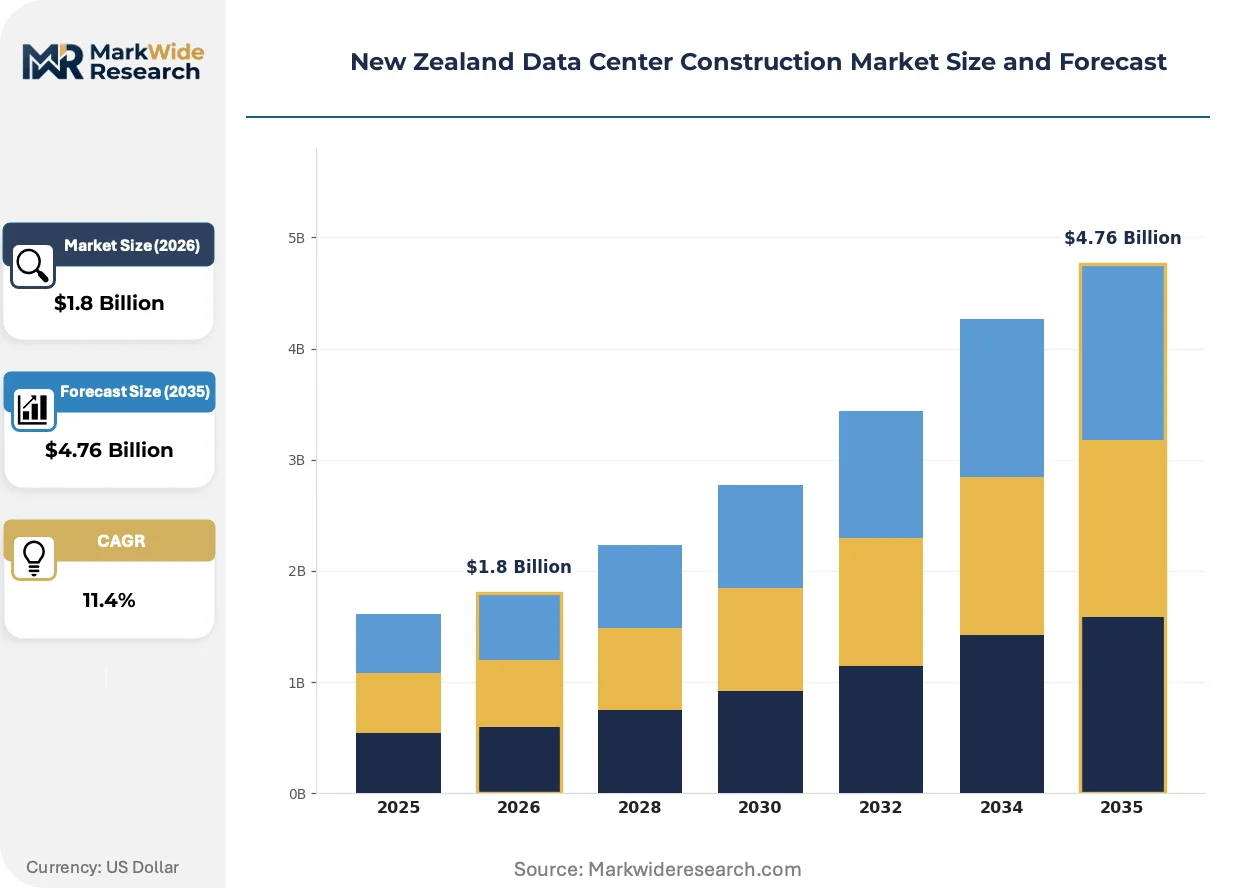
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Greenfield, Brownfield, Expansion, Renovation Construction Stage: Design, Pre-Construction, Construction, Commissioning Data Center Tier: Tier I, Tier II, Tier III, Tier IV End User: Cloud Service Providers, Enterprises, Telecoms, Government |
| Companies Covered | AECOM, Aurecon Group Pty Ltd., Turner & Townsend, Rider Levett Bucknall, Arup Group Limited, Jacobs Solutions Inc., NZ Strong Group Ltd, Icon Co., Goodman Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Data Center Construction Market Trends and Innovations
Modular prefabrication and liquid cooling architectures are compressing construction schedules while raising power density thresholds. These shifts demand reconfigured contractor capabilities and revised procurement risk allocation.
Direct-to-chip liquid cooling is digitizing thermal management design workflows across New Zealand projects. Hyperscale operators now specify coolant distribution units as primary infrastructure, not aftermarket retrofits. Aurecon and Arup are embedding computational fluid dynamics modeling into early-stage architectural packages, compressing mechanical system commissioning timelines by 40%.
MBIE's 2024 Building Code amendments mandate post-tensioned concrete foundation systems for facilities exceeding Importance Level 4. The regulation elevates geotechnical investigation depth requirements from 20 meters to 35 meters in volcanic soil zones. Contractors are responding by pre-purchasing specialized piling rigs and securing long-term leases on limited Auckland-based equipment pools.
Financial services procurement teams now unbundle design-build contracts into separate EPC and commissioning phases. This fragmentation reflects lessons from 2022-2023 projects where single-source accountability obscured subsystem performance gaps. The shift is most visible among Auckland-based banks specifying Tier IV facilities, where independent commissioning agent mandates now appear in 80% of RFPs.
New Zealand Data Center Construction Market Segmentation
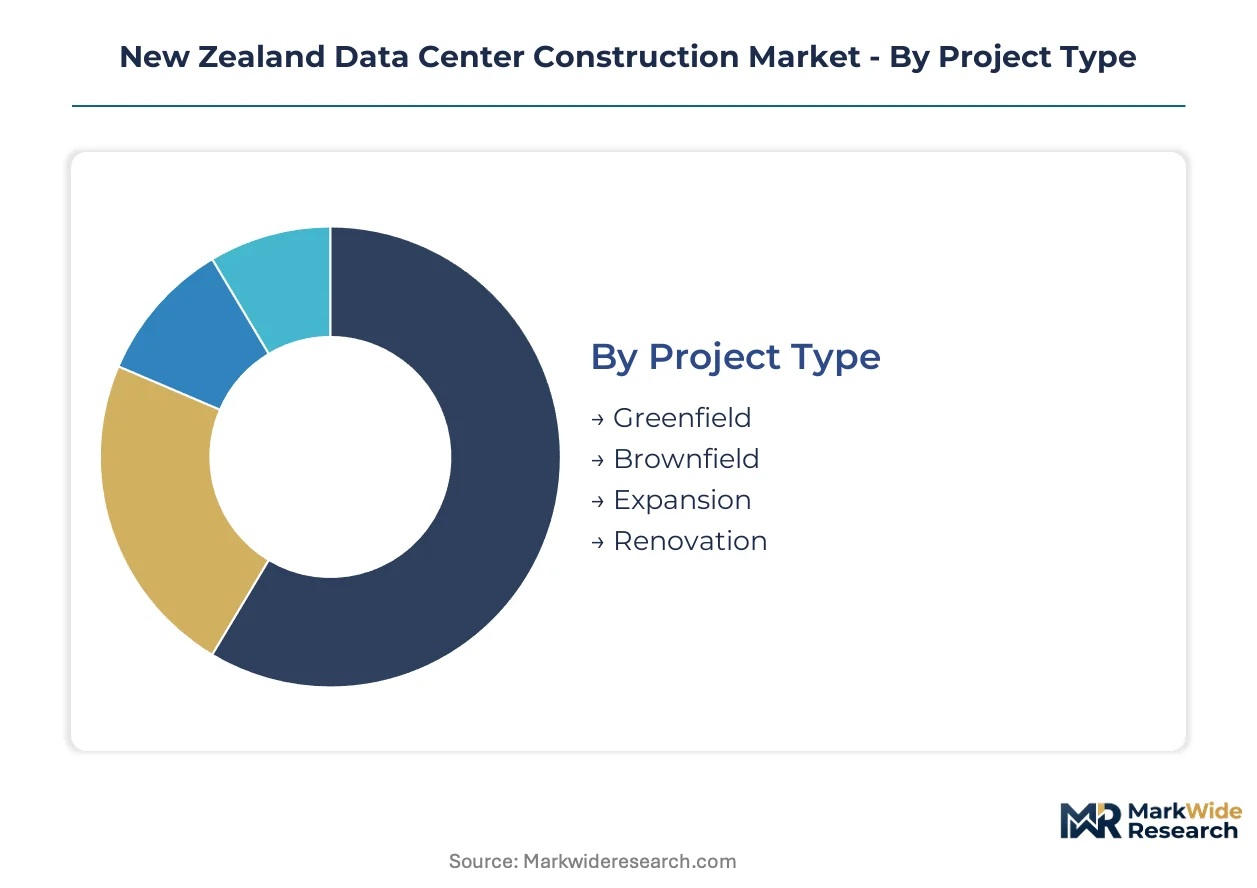
Segmentation in New Zealand's data center construction market reveals how seismic mandates, hyperscale commitments, and tier requirements reshape contractor specialization. Each dimension exposes distinct procurement patterns and capability gaps across Auckland and Christchurch corridors.
Project Type:
Mature greenfield developments dominate capital allocation, while brownfield conversions gain traction among enterprises optimizing existing assets.
- Greenfield:Purpose-built campuses on virgin land enable direct renewable energy coupling and optimized seismic foundation design. Hyperscale operators concentrate demand in Auckland's northwest corridor where submarine cable landings and grid capacity converge.
- Brownfield:Adaptive reuse of industrial warehouses accelerates time-to-market for sub-10 MW deployments but requires extensive structural retrofitting to meet Importance Level 4 seismic standards. Christchurch manufacturers repurposing facilities face 35-meter geotechnical investigation requirements under MBIE's updated Building Code.
- Expansion:Modular additions to operational facilities leverage existing power and fiber infrastructure. Contact Energy's geothermal PPAs anchor South Island expansion economics.
- Renovation:Lifecycle upgrades targeting PUE reduction below 1.4 dominate aging Auckland metro facilities. Energy Efficiency and Conservation Authority grants offset 15-30% of efficiency system costs.
Greenfield handles the majority of throughput; Brownfield is expanding most quickly as land scarcity intensifies.
Construction Stage:
Cost tier separation distinguishes front-loaded engineering phases from capital-intensive physical execution, with commissioning emerging as a discrete value layer.
- Design:Multidisciplinary engineering packages now embed computational fluid dynamics for liquid cooling architectures. Aurecon and Arup compress mechanical commissioning timelines by 40% through early-stage thermal modeling.
- Pre-Construction:Seismic steel pre-qualification and specialized piling rig procurement dominate contractor preparation. Domestic moment-resisting frame fabrication capacity bottlenecks constrain simultaneous project waves.
- Construction:Post-tensioned concrete foundation systems and real-time structural health monitoring installation absorb elevated structural engineering costs. MBIE's 2024 amendments mandate 35-meter geotechnical depth in volcanic soil zones.
- Commissioning:Independent commissioning agent mandates appear in 80% of Auckland-based bank RFPs following 2022-2023 subsystem performance gaps. Financial services procurement now unbundles design-build contracts to isolate accountability.
Construction absorbs the largest capital share; Commissioning is climbing the fastest as fault-tolerance standards tighten.
Data Center Tier:
Customer type differentiation separates hyperscale volume from financial services premium specifications, with tier classification directly determining structural redundancy and power path requirements.
- Tier I:Basic capacity with single power and cooling distribution, suitable for non-critical enterprise workloads. Limited deployment in New Zealand given seismic resilience overbuild requirements.
- Tier II:Redundant capacity components with single distribution paths. Regional enterprise adoption concentrates in Christchurch where Orion New Zealand grid upgrades reduce power supply risk.
- Tier III:Concurrently maintainable infrastructure with dual power and cooling paths. Cloud service providers anchor volume commitments across Auckland and emerging Canterbury campuses.
- Tier IV:Fault-tolerant architecture with 2N+1 redundancy and 99.995% uptime guarantees. Reserve Bank of New Zealand prudential standards mandate Tier IV-equivalent infrastructure for systemically important banks, driving premium construction specifications and specialized seismic engineering demand.
Tier III commands the dominant share of active projects; Tier IV is gaining share fastest as regulatory mandates harden.
End User:
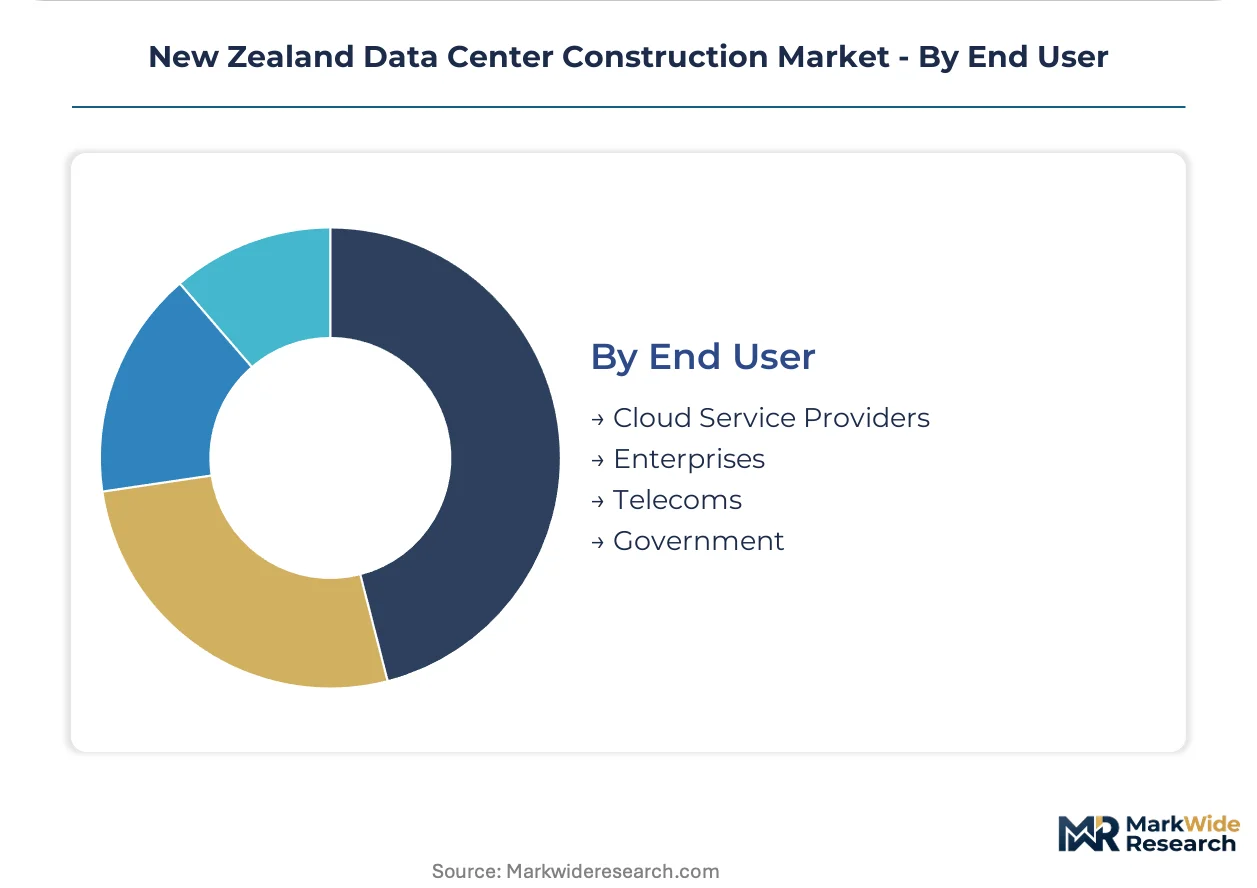
Volume concentration patterns align end user type with geographic clustering, hyperscale cloud demand concentrating where land, power, and fiber converge.
- Cloud Service Providers:Hyperscale operators seek direct high-voltage grid connections above 10 MW capacity, capitalizing on Commerce Commission tariff reforms. Auckland's northwest corridor hosts multiple international fiber optic termini enabling sub-10ms latency to Australia and Asia-Pacific markets.
- Enterprises:Hybrid architecture adoption narrows the gap between owned facilities and colocation, with modular prefabrication compressing construction schedules for disaster recovery workloads targeting Christchurch.
- Telecoms:Edge computing deployments and 5G infrastructure backhaul requirements drive distributed smaller-footprint facilities. Submarine cable landing proximity remains critical for latency-sensitive applications.
- Government:Sovereign data residency requirements and critical infrastructure classification elevate Importance Level 4 seismic specifications. MBIE Building Code compliance integration demands real-time structural health monitoring systems unfamiliar to international contractors.
Cloud Service Providers handle the majority of throughput; Government is the fastest mover on share as digital sovereignty policies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand's data center construction market operates as a net importer of specialized engineering capacity, with domestic firms sourcing seismic steel fabrication and liquid cooling expertise from Australian and Asian supply chains. Export intensity remains minimal given the localized nature of infrastructure delivery.
Auckland Metropolitan Area
Hyperscale cloud commitments concentrate in the northwest corridor where submarine cable landings from Southern Cross and Hawaiki converge with Transpower grid capacity. Auckland Council's resource consent backlogs extend beyond 30 months for greenfield sites exceeding 50 MW, compressing viable project pipelines. Whenua Ora land releases and Vector's electricity distribution upgrades are reshaping site selection toward Drury and Pukekohe peripheries.
Christchurch-Canterbury Corridor
Orion New Zealand's network reinforcement programs unlock 150 MW of untapped South Island grid capacity for disaster recovery workloads. Environment Canterbury's regional plan amendments streamline consent pathways for industrial zoned land near Rolleston. Contact Energy's geothermal baseload from Tauhara station anchors 24/7 carbon-free power purchase agreements unavailable to North Island competitors.
Wellington Region
Government digital sovereignty mandates from the Department of Internal Affairs elevate Importance Level 4 seismic specifications for sovereign data facilities. Greater Wellington Regional Council's freshwater management rules constrain cooling system designs in the Hutt Valley industrial zone. MBIE's critical infrastructure classification triggers real-time structural health monitoring requirements that international contractors struggle to specify.
Hamilton-Waikato Hub
Waikato District Council's pro-growth industrial zoning attracts modular data center deployments seeking lower land costs than Auckland. Transpower's 220 kV grid interconnection upgrades enable direct high-voltage connections above 10 MW capacity. Mighty River Power's renewable generation portfolio supports sub-1.3 PUE targets that qualify for Energy Efficiency and Conservation Authority co-funding.
New Zealand Data Center Construction Market Competitive Landscape
On the supply side, the industry is consolidating around multidisciplinary engineering groups capable of integrating seismic resilience with hyperscale delivery timelines. Specialist structural firms and cost consultancies occupy distinct capability tiers beneath integrated design-build anchors. Competitive positioning hardens through pre-qualification of seismic steel fabrication capacity and securing long-term leases on specialized piling equipment pools. Geographic expansion into Christchurch and vertical integration of commissioning capabilities represent the dominant competitive moves.
Within the integrated engineering tier, Aurecon Group Pty Ltd and Arup Group Limited anchor complex Tier III and Tier IV projects requiring computational fluid dynamics modeling for liquid cooling architectures. Turner & Townsend occupies a position on the cost certainty vector through advanced project controls. These three exemplify how seismic zone expertise and sustainability integration now determine procurement outcomes.
| Leading Market Players |
|---|
| AECOM |
| Aurecon Group Pty Ltd. |
| Turner & Townsend |
| Rider Levett Bucknall |
| Arup Group Limited |
| Jacobs Solutions Inc. |
| NZ Strong Group Ltd |
| Icon Co. |
| Goodman Group |
| Others |
Pricing and Supply Chain Analysis
Domestic moment-resisting frame fabrication capacity in Auckland anchors margin distribution across New Zealand data center construction, with only two certified suppliers capturing structural steel premiums while downstream EPC contractors absorb foundation cost escalation from MBIE's 2024 geotechnical depth mandates.
Pricing Analysis
Cloud service provider buyers anchor project-based pricing structures across Auckland's northwest corridor, with Tier IV financial services procurement commanding 40-60% premiums over Tier III hyperscale builds based on fault-tolerance certification requirements and independent commissioning agent mandates. Price differentiation rests on seismic performance grade and renewable energy coupling rather than standard construction tiers. Cost compression in structural systems is intensifying as contractors pre-purchase specialized piling rig capacity to secure limited equipment pools. Mid-market enterprise brownfield conversions exhibit highest price sensitivity, while Reserve Bank-mandated bank infrastructure programs demonstrate lowest sensitivity due to regulatory compliance imperatives.
Supply Chain Analysis
Extended payment terms from Australian seismic engineering consultancies and supply-chain finance facilities from Asian mechanical equipment vendors are reshaping working capital requirements for domestic contractors. Raw material dependencies center on Australian structural steel, Chinese electrical switchgear, and Korean precision cooling components. Single-source vulnerability concentrates in Auckland-based moment-resisting frame fabrication, where concurrent hyperscale project waves strain limited domestic capacity. Distribution runs through multidisciplinary engineering groups integrating foreign specialist expertise with local seismic code compliance capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among hyperscale cloud operators consolidating procurement across Australasia, fragmenting contractor margins as volume commitments extract performance guarantees and extended warranty terms.
For Market Incumbents: Pre-empt Christchurch corridor pre-qualification by securing Orion New Zealand grid capacity allocations before competitor land banking accelerates. Lock long-term leases on specialized piling equipment pools to defend against Auckland equipment scarcity. Deepen backward integration into commissioning capabilities as financial services procurement unbundles design-build contracts and isolates subsystem accountability. For New Entrants and Emerging Players: Mid-market brownfield seismic retrofitting in Hamilton-Waikato represents the most penetrable entry point, with Waikato District Council pro-growth zoning and Transpower 220 kV upgrades enabling sub-10 MW deployments without Auckland consent backlogs. Direct-to-chip liquid cooling mechanical contracting for AI training clusters addresses capability gaps where local expertise lags deployment requirements. Partner with Mighty River Power renewable generation portfolios to anchor sub-1.3 PUE co-funding eligibility. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed multidisciplinary engineering groups holding Auckland seismic steel pre-qualification relationships and long-term piling equipment leases. Five-to-ten year viability hinges on Christchurch corridor grid capacity monetization and geothermal-direct PPA structuring capabilities. Watch Contact Energy Tauhara baseload contracting velocity as inflection indicator for South Island expansion economics.| Strategic Initiative | Industry Significance |
|---|---|
| Seismic Steel Fabrication Pre-Qualification | MBIE's 2024 foundation mandates elevate certified supplier relationships above price competition. |
| Geothermal-Direct Power Purchase Agreement | Contact Energy's Tauhara baseload enables carbon-free uptime guarantees unavailable to North Island competitors. |
| Liquid Cooling Capability Acquisition | Direct-to-chip expertise addresses 30+ kW per rack deployment gaps for AI training clusters. |
| Christchurch Corridor Land Banking | Orion New Zealand grid reinforcement unlocks 150 MW of untapped South Island disaster recovery capacity. |
| Independent Commissioning Agent Integration | Auckland bank RFP unbundling creates discrete value layer separating design from performance accountability. |
Research Methodology
Operator-level perspectives from data center facility directors, EPC project managers, seismic structural engineers, and Commerce Commission regulatory analysts anchored the qualitative base. Primary interviews with Auckland Council resource consent officers and Energy Efficiency and Conservation Authority program administrators supplemented hyperscaler capex disclosure analysis and MBIE Building Code amendment documentation. Bottom-up project pipeline aggregation triangulated against top-down construction spend estimates from Transpower grid connection filings and Orion New Zealand network upgrade schedules.
Scenario-bracketing around consent timeline volatility and seismic steel supply constraints framed the analytical approach across the projection horizon. Segmentation dimensions modeled include project type, construction stage, data center tier classification, and end user vertical, with geographic clustering across Auckland metropolitan, Christchurch-Canterbury, Wellington, and Hamilton-Waikato sub-regions. CAGRs derived from capacity commitment announcements and grid interconnection timelines, incorporating geothermal PPA availability and submarine cable landing proximity as location-specific demand drivers.
Stress conditions across Auckland Council backlog extensions, moment-resisting frame fabrication bottlenecks, and Commerce Commission tariff reform implementation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hyperscale commitment velocity and MBIE code compliance integration timelines. Macroeconomic deviation, regulatory amendment acceleration, or liquid cooling technology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
New Zealand Infrastructure Market
Infrastructure Construction
Oman Transportation Infrastructure Construction Market
Infrastructure Construction
Latin America Data Center Construction Market
Infrastructure Construction
France Transportation Infrastructure Construction Market
Infrastructure Construction
Road & Highway Infrastructure Market
Infrastructure Construction
Transportation Infrastructure Construction Market
Infrastructure Construction
Oil and Gas Pipeline Fabrication and Construction Market
Infrastructure Construction
Conventional Overhead Conductor Market
Infrastructure Construction
Global Rail Infrastructure Market
Infrastructure Construction
Overhead Conductor Market
Infrastructure Construction
Russia Transportation Infrastructure Construction Market
Infrastructure Construction
Pipeline Network Market
Infrastructure Construction
Canada Commercial Construction Market
Infrastructure Construction
Utility System Construction Market
Infrastructure Construction
Europe Transportation Infrastructure Construction Market
Infrastructure Construction
China Transportation Infrastructure Construction Market