
 Thailand Data Center Construction Market | 2026-2036
Thailand Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Data Center Construction Market Insights
Tier-III and Tier-IV certification standards is reorganizing procurement priorities across Thailand's data center pipeline. Syntec Construction PCL leverages its local civil engineering scale to dominate ground-up builds in Bangkok's peripheral zones. Thai Kajima Co., Ltd anchors its competitive stance through precision cooling integration and seismic-resistant structural design. Aurecon Group Pty Ltd differentiates via end-to-end project management spanning feasibility through commissioning.
Data center construction encompasses the specialized engineering, structural build-out, and systems integration required to create facilities housing servers, storage, and networking equipment with guaranteed uptime, typically achieving power usage effectiveness ratios below 1.5 and maintaining N+1 redundancy on critical infrastructure. The primary purpose is delivering controlled environments that ensure continuous digital service availability for enterprise and consumer applications. Modular technology deployment is accelerating fastest as operators seek phased capital deployment, while traditional build-outs retain margin concentration in legacy banking and government segments. Design services command premium pricing when bundled with sustainability consulting, reflecting client demands for LEED and TIA-942 compliance.
Thailand's Ministry of Digital Economy and Society enforces data localization requirements under the Personal Data Protection Act, compelling foreign operators to construct domestic facilities rather than rely on regional hubs. The National Telecommunications Commission regulates cross-border connectivity standards, directly influencing facility location decisions near submarine cable landing stations. Stakeholders must monitor evolving Board of Investment incentive structures and power tariff negotiations with the Provincial Electricity Authority as these will determine project economics for multi-hundred-megawatt campuses.
Market Dynamics
Hyperscale cloud operators are compressing build timelines in Thailand's data center pipeline, forcing Tier-III and Tier-IV certification requirements into standard procurement specifications and rewiring contractor selection criteria around integrated engineering capabilities rather than siloed civil construction.
Growth Catalysts
- Data Center and Cloud First Policy:Thailand's Ministry of Digital Economy and Society mandates domestic cloud infrastructure, compelling foreign operators to construct local facilities rather than serve from Singapore or Hong Kong hubs.
- Eastern Economic Corridor concentration:Land availability and pre-zoned industrial estates in Chonburi and Rayong provinces accelerate permitting timelines and reduce site preparation costs for multi-megawatt campuses.
- Submarine cable landing proximity:Facilities near Laem Chabang and Songkhla cable stations gain latency advantages for financial services and gaming workloads requiring sub-30 millisecond connectivity to ASEAN markets.
Market Restraints
- Provincial Electricity Authority tariff uncertainty:Negotiations for industrial power rates remain unresolved for campuses exceeding 100 megawatts, freezing final investment decisions on three planned hyperscale builds.
- Seismic engineering requirements:Thailand's location on the Sunda Megathrust fault zone mandates specialized structural designs that add 12-18% to concrete and steel costs versus standard commercial construction.
- Liquid cooling supply concentration:Precision cooling equipment for tropical climates sources primarily from German and Japanese manufacturers, exposing projects to 14-16 week lead times and currency fluctuation risk.
Strategic Opportunities
- Chiang Mai secondary market:Cooler upland temperatures and lower land costs create viable alternatives to Bangkok-Chonburi corridor saturation for disaster recovery and archive storage workloads.
- Board of Investment tax holidays:Eight-year corporate income tax exemptions for data center investments exceeding 1 billion baht improve project IRRs for foreign capital deployment.
- AI training cluster specialization:Convergence of GPU-intensive compute demand with Thailand's renewable energy commitments positions the country for carbon-neutral AI infrastructure marketing to European cloud customers.
Industry Challenges
- TIA-942 certification timeline:Third-party validation for Tier-III facilities requires 8-12 months of continuous operational testing, delaying revenue recognition and complicating construction-to-operations handoffs.
- Specialized MEP workforce scarcity:Thailand produces fewer than 200 certified data center mechanical-electrical-plumbing engineers annually, forcing contractors to import Vietnamese and Filipino supervision at premium cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Data Center Construction Market |
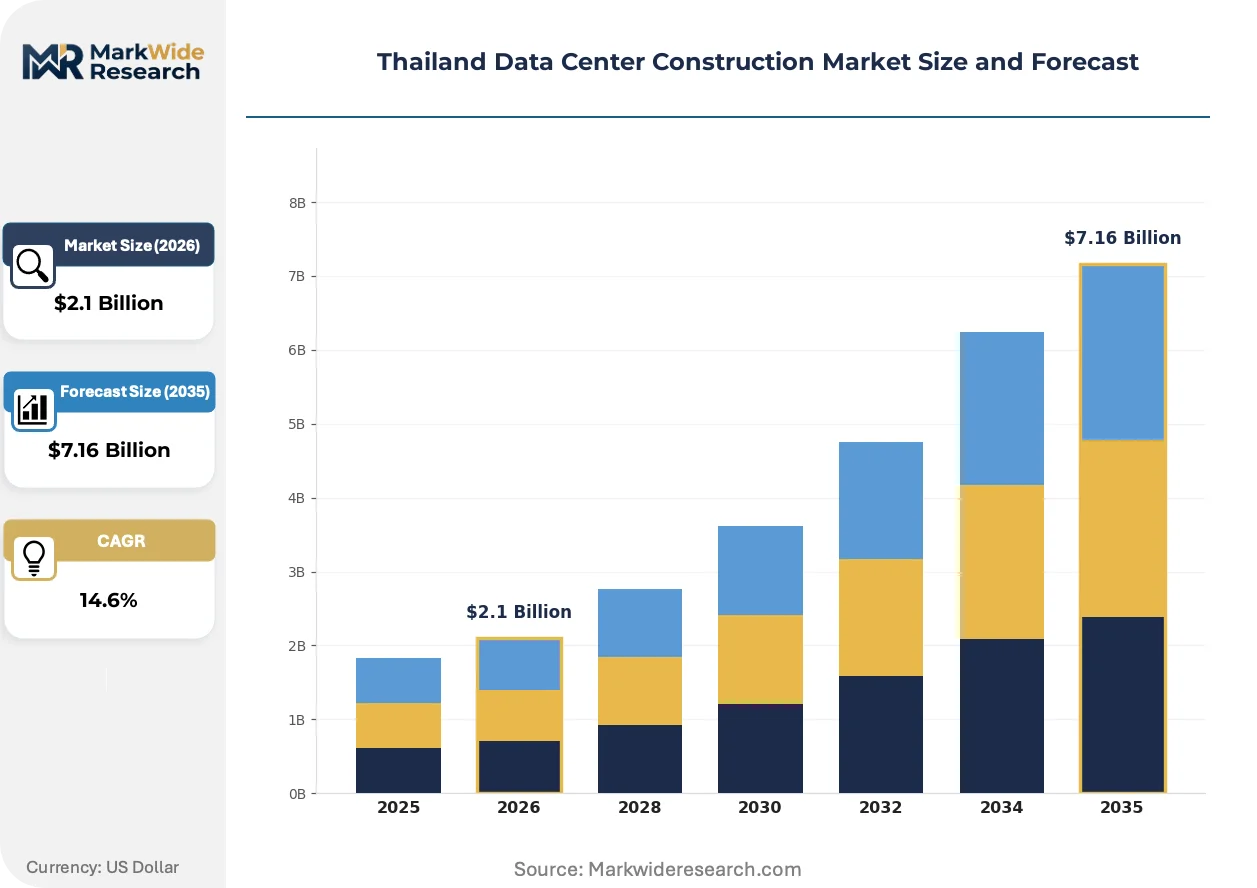
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.16 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Construction, Management, Consulting Technology: Hybrid, Cloud, Traditional, Modular End User: Telecommunications, IT Service Providers, Enterprises, Government Application: Data Storage, Disaster Recovery, Web Hosting, Virtualization |
| Companies Covered | Syntec Construction PCL, AECOM (Thailand) Ltd, Thai Kajima Co., Ltd, Thai Obayashi Corp. Ltd, PPS Group PCL, Aurecon Group Pty Ltd, Arup, Meinhardt Group, Architects 49, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Data Center Construction Market Trends and Innovations
Modular prefabrication is compressing Thailand's data center delivery schedules while rewiring the traditional general contractor-subcontractor hierarchy around integrated module suppliers with captive manufacturing capacity.
Immersion cooling systems using dielectric fluids are displacing air-cooled architectures in new Bangkok metropolitan builds. Banking and cryptocurrency mining operators are specifying these systems for density targets above 50 kilowatts per rack. The technology is displacing conventional CRAC-based designs from premium segment procurement, forcing mechanical contractors to retrain installation crews or cede work to specialized fluid systems integrators.
Thailand's Personal Data Protection Act enforcement through the Ministry of Digital Economy and Society is hardening data localization requirements. Operators must demonstrate domestic storage for citizen personal data, eliminating hybrid cloud architectures that relied on regional redundancy. Financial services and healthcare verticals are responding by contracting dedicated facility builds rather than colocation leases, shifting procurement toward design-build-operate contracts with 15-20 year terms.
Enterprise buyers are unbundling commissioning and warranty services from construction contracts, creating separate procurement streams for independent commissioning agents. This fragmentation is disrupting traditional contractor revenue models that bundled testing and handoff services at margin. The pattern is most visible in state enterprise and banking segments, where procurement committees now mandate third-party Uptime Institute witness testing as a payment milestone independent of construction completion certificates.
Thailand Data Center Construction Market Segmentation
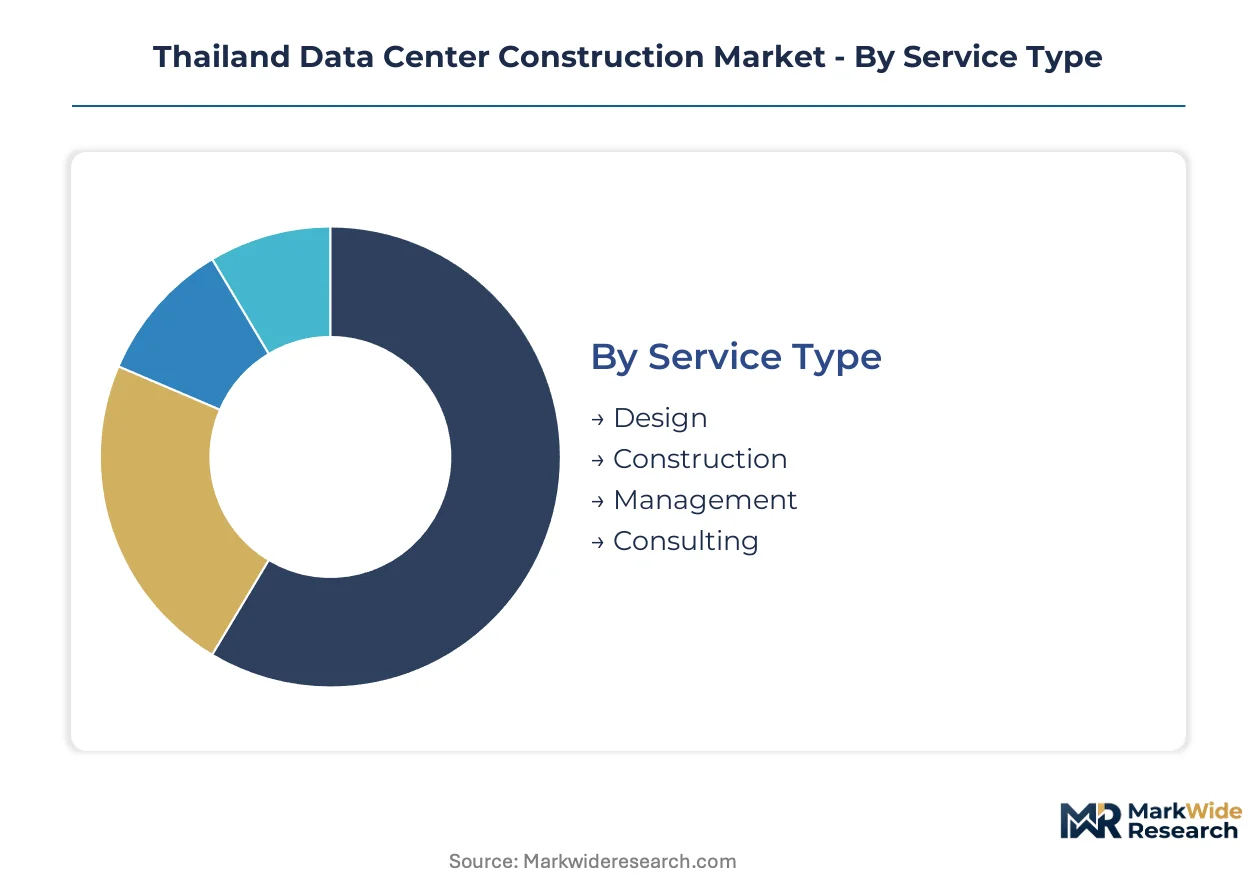
Thailand's data center construction market fragments across four dimensions that determine procurement channel selection and margin capture. Service type and technology choices dictate whether contracts flow through integrated engineering firms or specialized subcontractors, while end-user and application segments shape facility specifications from power density to certification tiers.
Service Type:
Channel flow splits between bundled design-build contracts favored by hyperscale operators and unbundled procurement patterns among state enterprises and banking clients.
- Design:Architectural and engineering specifications for Tier-III and Tier-IV facilities command premium pricing when bundled with sustainability consulting for LEED and TIA-942 compliance. Demand concentrates among foreign cloud operators entering Thailand under the Data Center and Cloud First Policy, where domestic design partners accelerate regulatory approvals.
- Construction:Ground-up civil works with seismic-resistant structural systems dominate the Eastern Economic Corridor, where Syntec Construction PCL leverages local scale for multi-megawatt campus builds. The segment captures the largest contract values but faces margin pressure from compressed timelines demanded by hyperscale clients.
- Management:End-to-end project oversight spanning feasibility through commissioning differentiates Aurecon Group's positioning in Bangkok's peripheral zones. This segment gains share as operators separate construction completion from independent Uptime Institute witness testing milestones.
- Consulting:Regulatory navigation and Board of Investment incentive structuring for foreign capital deployment. Thai Kajima anchors this segment through precision cooling integration advisory and seismic engineering specialization.
By volume, Construction leads. By growth pace, Management services are expanding most quickly.
Technology:
Facility architecture choices determine supply chain sourcing patterns, with modular systems rewiring traditional contractor-subcontractor relationships around integrated module suppliers.
- Hybrid:Blended on-premise and cloud infrastructure configurations that balance latency requirements with cost optimization. Financial services and healthcare verticals in Bangkok metropolitan area drive specification as data localization mandates harden under the Personal Data Protection Act.
- Cloud:Hyperscale-optimized builds with power densities exceeding 50 kilowatts per rack and liquid cooling readiness. This architecture dominates new capacity in Chonburi and Rayong provinces where submarine cable proximity delivers sub-30 millisecond ASEAN connectivity.
- Traditional:Air-cooled facilities with N+1 redundancy targeting legacy banking and government segments with lower density requirements. Procurement concentrates through established general contractors with proven relationships with the Provincial Electricity Authority.
- Modular:Prefabricated power and cooling modules enabling phased capital deployment. The technology is gaining share fastest among operators seeking to compress delivery schedules while mitigating tariff uncertainty risk for campuses exceeding 100 megawatts.
By installed base, Traditional architecture dominates. By new contract flow, Modular deployment is climbing the fastest.
End User:
Customer type determines facility ownership structure, with telecommunications and IT service providers favoring design-build-operate contracts while enterprises shift from colocation toward dedicated builds.
- Telecommunications:Carrier-neutral facilities with cross-connect density and submarine cable landing station proximity. Demand clusters near Laem Chabang and Songkhla where National Telecommunications Commission connectivity standards influence site selection.
- IT Service Providers:Multi-tenant builds with flexible power provisioning and rapid deployment capability. This segment is gaining share fastest as regional cloud operators establish Thailand presence to serve ASEAN enterprise workloads.
- Enterprises:Single-tenant facilities with customized security and compliance architectures. Banking and cryptocurrency mining operators in Bangkok are specifying immersion cooling systems for density targets above 50 kilowatts per rack.
- Government:State enterprise procurement with mandatory third-party commissioning and extended warranty terms. Projects concentrate in the Eastern Economic Corridor where Board of Investment tax holidays improve project economics.
By contract value, Telecommunications leads. By specification intensity, Enterprise builds are advancing the fastest.
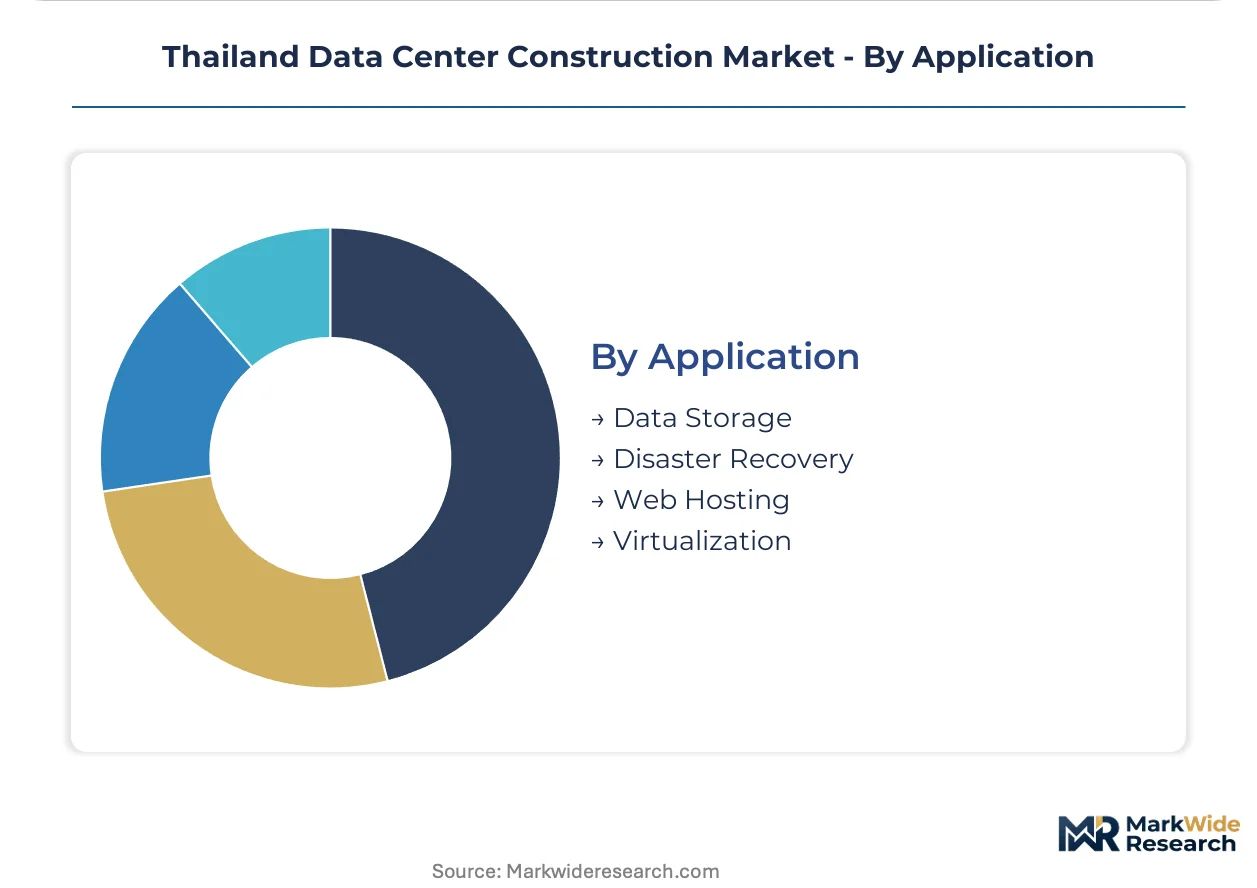
Application:
Workload purpose shapes redundancy requirements and geographic distribution, with disaster recovery applications driving secondary market development outside the Bangkok-Chonburi corridor.
- Data Storage:Archive and cold storage facilities with relaxed latency requirements enabling Chiang Mai secondary market development. Cooler upland temperatures reduce cooling energy consumption for long-retention workloads.
- Disaster Recovery:Geographically separated backup sites with synchronous replication capability. This application is expanding fastest as data localization mandates eliminate hybrid cloud architectures that relied on regional redundancy.
- Web Hosting:Edge-optimized facilities with content delivery network integration. Demand concentrates in Bangkok metropolitan area where consumer internet traffic density justifies proximity to population centers.
- Virtualization:Compute-intensive builds supporting enterprise workload consolidation. GPU cluster specialization for AI training is emerging as a distinct sub-segment tied to Thailand's renewable energy commitments and carbon-neutral infrastructure marketing.
By facility count, Data Storage leads. By growth trajectory, Disaster Recovery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's data center construction capacity clusters in the Eastern Economic Corridor and Bangkok periphery, where land availability and submarine cable proximity attract hyperscale investment. Provincial power negotiations and seismic engineering requirements create location-specific cost premiums that reshape sub-regional competitiveness.
Bangkok Metropolitan Region
Immersion cooling deployments for cryptocurrency mining and banking workloads drive specification intensity in Samut Prakan and Pathum Thani provinces. The Ministry of Digital Economy and Society enforces Personal Data Protection Act data localization requirements that compel domestic facility construction. Latency-sensitive financial services clusters concentrate in Lat Krabang and Bang Na districts near fiber interconnection points.
Eastern Economic Corridor
Chonburi and Rayong provinces host multi-hundred-megawatt campuses targeting cloud operators seeking ASEAN connectivity under 30 milliseconds. Board of Investment eight-year tax holidays for investments exceeding one billion baht improve project IRRs for foreign capital. Laem Chabang submarine cable landing station proximity creates competitive advantage for carrier-neutral facilities serving regional gaming and fintech workloads.
Chiang Mai and Northern Uplands
Cooler temperatures and lower land costs position the secondary market for disaster recovery and archive storage applications. The Provincial Electricity Authority offers more favorable industrial tariff negotiations for sub-100-megawatt facilities outside Bangkok-Chonburi corridor saturation. Data center operators are contracting dedicated builds in Hang Dong and San Sai districts to serve backup replication mandates eliminating hybrid cloud regional redundancy.
Songkhla and Southern Seaboard
Submarine cable landing infrastructure near Hat Yai creates latency advantages for connectivity to Indonesian and Malaysian markets. National Telecommunications Commission cross-border standards influence facility siting decisions for telecommunications carriers. State enterprise procurement concentrates in this corridor where Board of Investment incentives apply to government-critical infrastructure.
Thailand Data Center Construction Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Thailand's data center construction pipeline. The market structure splits between integrated engineering firms bundling design-through-commissioning services and specialized contractors capturing margin in seismic-resistant structural systems. Three archetypes dominate: local civil engineering specialists with Provincial Electricity Authority relationships, Japanese-Thai joint ventures with precision cooling integration capabilities, and Australian project management firms with Uptime Institute certification expertise. Competitive moves center on modular manufacturing partnerships and independent commissioning agent alliances that unbundle traditional construction-to-operations handoffs.
Within the local engineering tier, Syntec Construction PCL anchors ground-up civil works capacity in Bangkok's peripheral zones. Thai Kajima Co., Ltd exemplifies the Japanese-Thai joint venture archetype through seismic engineering and cooling systems specialization. Aurecon Group Pty Ltd occupies the integrated project management position spanning feasibility through commissioning. These three companies represent distinct competitive vectors—scale-driven local execution, technology-integrated structural design, and end-to-end oversight—that collectively define procurement channel segmentation for Tier-III and Tier-IV certification requirements.
| Leading Market Players |
|---|
| Syntec Construction PCL |
| AECOM (Thailand) Ltd |
| Thai Kajima Co., Ltd |
| Thai Obayashi Corp. Ltd |
| PPS Group PCL |
| Aurecon Group Pty Ltd |
| Arup |
| Meinhardt Group |
| Architects 49 |
| Others |
Pricing and Supply Chain Analysis
Immersion cooling dielectric fluids are displacing conventional air-cooled architectures in Bangkok metropolitan builds, simultaneously shifting procurement geography toward German and Japanese precision equipment suppliers and compressing contractor margins through specialized fluid systems integrator premiums. This substitution dynamic rewires traditional mechanical-electrical-plumbing bidding structures around captive cooling module manufacturers with tropical climate engineering expertise.
Pricing Analysis
The Personal Data Protection Act dictates the pricing tier structure across Thailand's data center construction pipeline. Three-tier pricing stratifies across Tier-IV certification premiums, Tier-III standard builds, and uncertified economy-grade government facilities. Price differentiation hinges on Uptime Institute certification level and bundled commissioning services. Pricing pressure stems from hyperscale operators compressing build timelines and unbundling warranty services from construction contracts. State enterprise procurement committees demonstrate highest price sensitivity through mandatory third-party witness testing milestones, while foreign cloud operators entering under the Data Center and Cloud First Policy show lowest sensitivity to secure domestic design partners.
Supply Chain Analysis
Fourteen-to-sixteen week lead times for precision cooling equipment expose projects to currency fluctuation risk and construction scheduling uncertainty. German and Japanese manufacturers anchor supply for tropical-grade liquid cooling systems, while Thai and Vietnamese contractors provide seismic-resistant structural steel and concrete. Raw material dependencies center on specialized dielectric fluids, seismic-grade rebar, and high-efficiency transformers. Single-source vulnerability concentrates in precision cooling equipment where tropical climate specifications limit qualified suppliers. Distribution runs through integrated engineering firms bundling design-through-commissioning services rather than fragmented general contractor-subcontractor hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's data center construction market represents an early-cycle expansion story justified by the Data Center and Cloud First Policy mandating domestic cloud infrastructure buildout, compelling foreign operators to construct local facilities rather than serve from regional hubs.
For Market Incumbents: Secure long-term power purchase agreements with the Provincial Electricity Authority before tariff negotiations resolve for campuses exceeding 100 megawatts, locking in project economics against rate uncertainty. Deepen captive relationships with German and Japanese precision cooling suppliers to mitigate lead time risk and currency exposure threatening margin compression. Invest in TIA-942 certification expertise to capture premium pricing from banking and healthcare verticals responding to data localization mandates.
For New Entrants and Emerging Players: Lead with modular prefabrication capabilities targeting the Eastern Economic Corridor, where phased capital deployment appeals to operators seeking tariff risk mitigation. Target Chiang Mai's secondary market for disaster recovery and archive storage workloads, exploiting cooler upland temperatures and favorable Provincial Electricity Authority negotiations for sub-100-megawatt facilities. Position through Board of Investment tax holiday structuring advisory to differentiate from established civil engineering incumbents.
For Investors and Strategic Acquirers: The market sits at an infrastructure buildout phase that favors integrated engineering firms with Uptime Institute certification expertise and modular manufacturing partnerships. Long-term viability centers on five-to-ten-year data localization enforcement durability and renewable energy commitment credibility for carbon-neutral AI infrastructure marketing. Acquisition targets should demonstrate seismic engineering specialization and captive precision cooling supply relationships. The signal to watch is Provincial Electricity Authority industrial tariff resolution for hyperscale campuses, which would unlock frozen final investment decisions and accelerate contract flow.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Manufacturing Partnership | Compresses delivery schedules while rewiring contractor-subcontractor hierarchies around integrated module suppliers. |
| Seismic Engineering Certification Investment | Captures premium pricing for Tier-III and Tier-IV facilities in Sunda Megathrust fault zone construction. |
| Independent Commissioning Agent Alliance | Aligns with state enterprise procurement mandates separating construction completion from Uptime Institute witness testing. |
| Liquid Cooling Systems Integration | Addresses banking and cryptocurrency mining density targets exceeding 50 kilowatts per rack in Bangkok builds. |
| Board of Investment Incentive Structuring | Improves project IRRs for foreign capital deployment through eight-year corporate income tax exemptions. |
Research Methodology
The analysis maps design services, construction, management, and consulting segments, each validated through primary interviews with data center developers, EPC contractors, Ministry of Digital Economy and Society officials, and Provincial Electricity Authority planning officers. Secondary validation draws from Board of Investment filings, National Telecommunications Commission connectivity standards, Uptime Institute certification databases, and Eastern Economic Corridor development authority records. Bottom-up project pipeline enumeration triangulates against top-down market sizing derived from hyperscaler capex disclosures and construction contract value aggregation.
Consistency checks validate volume and value outputs against external benchmarks including power capacity installation tracking, submarine cable landing station proximity premiums, and regional ASEAN data center development comparisons. Segmentation dimensions modeled span service type, technology architecture, end user category, and application workload across the projection horizon. CAGRs derive from fitted growth curves incorporating policy enforcement timelines, power infrastructure development pacing, and foreign direct investment flow patterns specific to data center asset class deployment.
The analysis sits within stated boundaries; outcomes outside sustained Data Center and Cloud First Policy enforcement, resolved Provincial Electricity Authority tariff negotiations, or stable seismic engineering cost structures would require recalibration. Forecasts reflect documented assumptions regarding hyperscale operator entry timing and data localization compliance trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Transmission and Distribution Infrastructure Market
Infrastructure Construction
APAC Data Center Construction Market
Infrastructure Construction
Overhead Conductor Market
Infrastructure Construction
Australia Transportation Infrastructure Construction Market
Infrastructure Construction
China Infrastructure Market
Infrastructure Construction
Steel Utility Poles Market
Infrastructure Construction
North America Transportation Infrastructure Construction Market
Infrastructure Construction
Aerial Cable Car Equipment Market
Infrastructure Construction
Global Manhole Covers Market
Infrastructure Construction
Mexico Data Center Construction Market
Infrastructure Construction
Ship Port Infrastructure Market
Infrastructure Construction
Vietnam Data Center Construction Market
Infrastructure Construction
New Zealand Data Center Construction Market
Infrastructure Construction
Gas Pipeline Infrastructure Market
Infrastructure Construction
Conventional Overhead Conductor Market
Infrastructure Construction
Netherlands Transportation Infrastructure Construction Market